

Robot Controller, Integrator and Software Market Size, Share, and Industry Trends Forecast 2026-2036
Robot Controller, Integrator and Software Market Insights
ISO 10218-1 safety certification tiers for collaborative robot controllers is bifurcating the competitive landscape into premium-validated and basic-compliance supply pools. ABB leverages its captive servo motor production to anchor controller margins across European automotive lines. FANUC sustains dominance in high-speed CNC-robot synchronization through proprietary fieldbus architectures. Siemens competes on open-platform programming environments that attract mid-tier integrators seeking vendor flexibility.
Robot controllers, integrators and software comprise the command, coordination and programming layer that governs industrial robot motion, logic sequencing and human-machine interaction, typically integrating real-time operating systems with cycle times below one millisecond and multi-axis interpolation algorithms for path precision within 0.1 millimeters. This layer serves to translate production workflows into executable machine instructions while enabling remote diagnostics, safety interlocking and production data logging for manufacturing execution systems. Motion controllers lead hardware value capture due to their embedded servo-drive complexity and thermal management requirements, while simulation software represents the fastest-expanding software category as virtual commissioning reduces physical prototype downtime for integrators. Turnkey integration services command superior margins in aerospace engineering and food processing, where hygienic design certifications and traceability protocols demand specialized application engineering.
FDA 21 CFR Part 820 quality system regulations govern medical device manufacturing robots in the United States, compelling controller vendors to validate software revision control and failure mode documentation. The EU Machinery Directive 2006/42/EC and CE marking requirements enforce functional safety validation for controllers deployed across European electronics manufacturing and packaging lines. China's SAMR administers compulsory GB standards for industrial robot electromagnetic compatibility and safety stop performance. Stakeholders must monitor evolving cybersecurity mandates for connected factory architectures, as controller network vulnerabilities increasingly trigger procurement specification changes and insurance liability calculations.
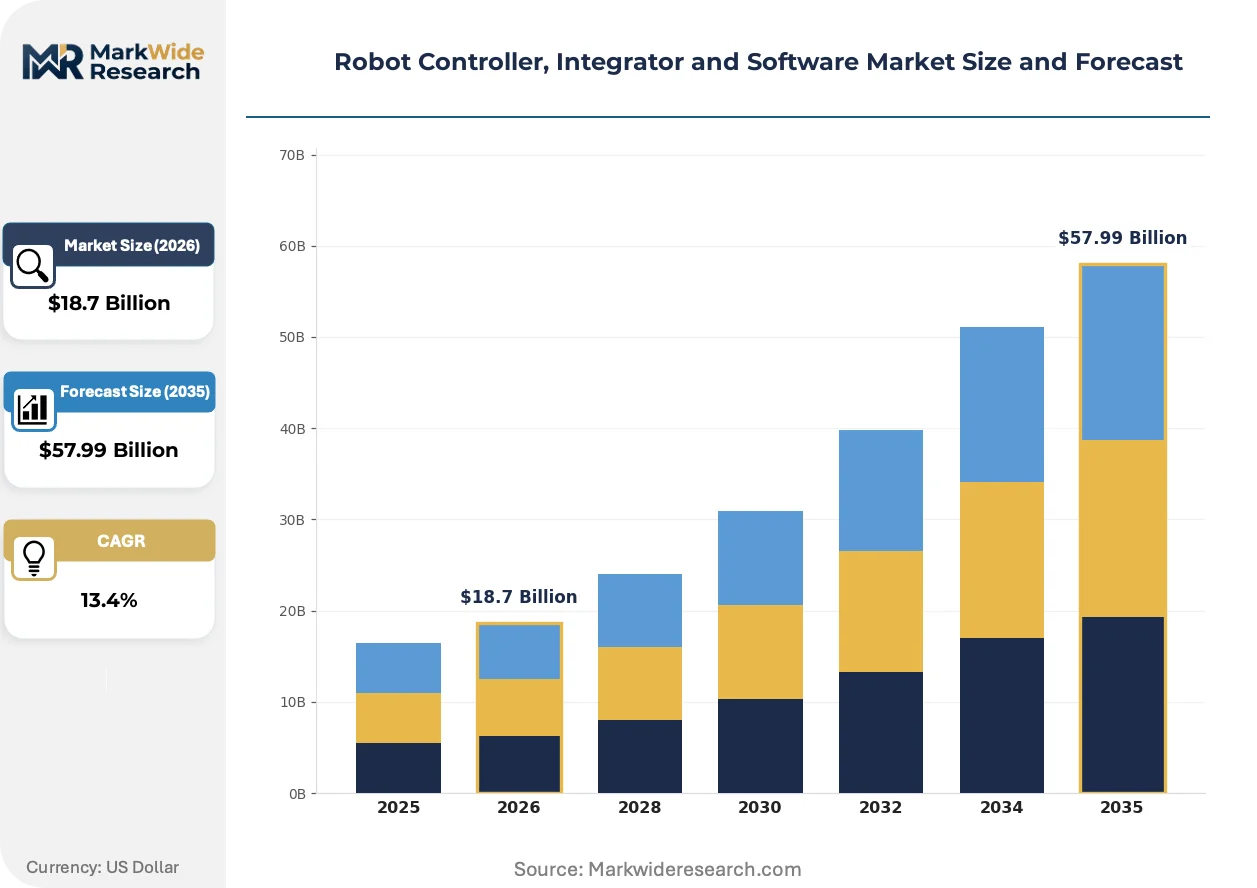
Market Dynamics
ISO 10218-1 safety certification tiers for collaborative robot controllers is bifurcating the competitive landscape into premium-validated and basic-compliance supply pools, forcing integrators to recalibrate procurement specifications across automotive and electronics manufacturing lines.
Growth Catalysts
- Electric vehicle battery assembly automation:German and Japanese automotive manufacturers are expanding robot controller deployments for high-precision cell stacking and module welding operations.
- China's MIIT dual carbon goals:Updated GB standards for industrial automation are accelerating domestic controller replacement cycles in heavy manufacturing corridors.
- Semiconductor fabrication demand:South Korea's Pyeongtaek-Yongin cleanroom cluster is concentrating procurement for specialized robot software contracts among precision integrators.
Market Restraints
- Silicon carbide power module cost volatility:Advanced servo-drive components face input price instability that compresses controller hardware margins.
- Fieldbus architecture lock-in:Proprietary communication protocols from dominant Japanese suppliers create switching friction for European automotive lines.
- Cybersecurity liability exposure:Connected factory architectures expose controller networks to insurance premium escalation and procurement specification tightening.
Strategic Opportunities
- India's PLI scheme for manufacturing:Domestic electronics and automotive contract manufacturers present untapped demand for mid-tier integration services.
- Digital twin convergence:Virtual commissioning software is merging with real-time controller diagnostics to reduce physical prototype downtime.
- FDA 21 CFR Part 820 medical device validation:Specialized compliance engineering for surgical robot controllers commands premium service margins in North American healthcare manufacturing.
Industry Challenges
- Safety-certified programming talent scarcity:Integrators face recruitment bottlenecks for engineers qualified in ISO 10218-1 collaborative robot risk assessment.
- Legacy CNC synchronization complexity:Retrofitting open-platform controllers into existing FANUC-dominated machining cells requires custom gateway development.
- CE marking timeline compression:EU Machinery Directive functional safety validation is extending project delivery schedules for electronics packaging integrators.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robot Controller, Integrator and Software Market Trends and Innovations
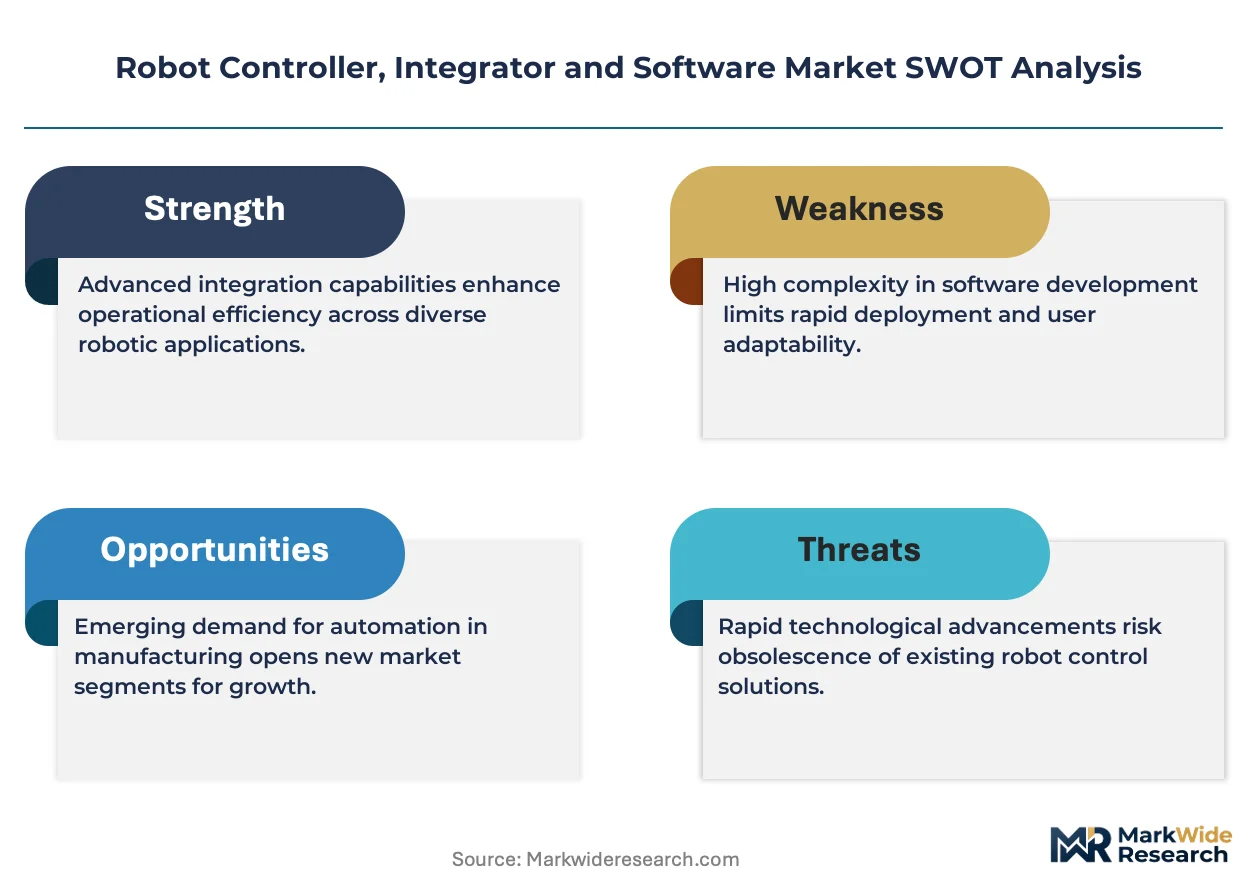
Real-time operating systems with sub-millisecond cycle times are becoming the baseline specification, while simulation software and edge-native diagnostics are displacing traditional commissioning workflows across automotive and semiconductor manufacturing.
Deterministic Ethernet is bifurcating motion control architectures between hard real-time deterministic networks for precision assembly and soft real-time variants for material handling. German automotive battery lines are adopting Time-Sensitive Networking for multi-axis synchronization. This technology is bifurcating integrator capabilities into deterministic-network specialists versus conventional fieldbus implementers.
The EU Machinery Directive 2006/42/EC is mandating functional safety validation for controllers deployed in collaborative applications. Electronics manufacturers in France and Italy are restructuring procurement specifications to require SIL-rated safety modules. Packaging line integrators are responding by embedding certified safety PLCs into standard controller offerings.
Virtual commissioning contracts are displacing physical prototype-based project pricing among mid-tier system integrators. Aerospace engineering firms in Germany and Japan are unbundling simulation services from hardware supply agreements. This shift is most visible in cleanroom semiconductor fabrication where digital twin validation reduces particle contamination risks during physical startup.
Robot Controller, Integrator and Software Market Segmentation
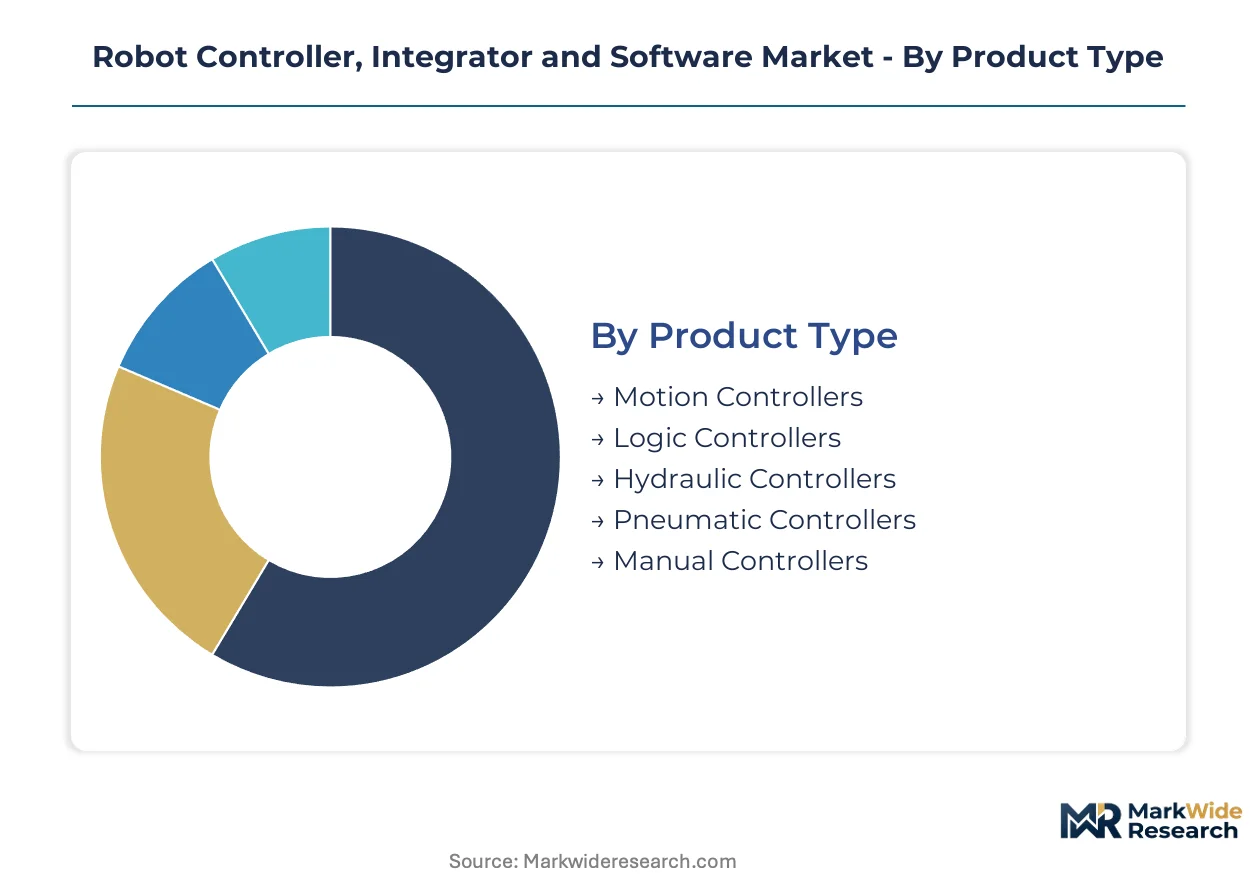
Robot controller segmentation reveals distinct margin architectures across hardware, services, and software layers. Motion controllers capture hardware value through embedded servo complexity, while simulation software and turnkey integration command premium pricing in specialized end-use environments.
Product Type:
Margin pools concentrate in precision motion architectures where thermal management and multi-axis interpolation justify hardware premiums.
- Motion Controllers:Embedded servo-drive systems with sub-millisecond cycle times and multi-axis interpolation algorithms deliver path precision within 0.1 millimeters. Demand concentrates in German and Japanese automotive battery assembly lines where high-precision cell stacking operations require deterministic motion architectures.
- Logic Controllers:Programmable automation controllers sequence discrete I/O and safety interlocking for manufacturing execution system integration. South Korea's Pyeongtaek-Yongin semiconductor fabrication corridor drives procurement for cleanroom-compatible logic sequencing platforms.
- Hydraulic Controllers:High-force actuation systems for heavy payload material handling in foundry and forging operations.
- Pneumatic Controllers:Cost-effective positioning systems for light-assembly pick-and-place applications in high-volume consumer electronics.
- Manual Controllers:Teach-pendant and jog-mode interfaces for robot programming and maintenance override functions.
The dominant share belongs to Motion Controllers, while Logic Controllers are closing the gap fastest.
Integration Service:
Service pricing stratifies sharply between commodity retrofit work and certified turnkey deployments in regulated environments.
- Turnkey Integration:End-to-end system design, installation, and commissioning with warranty-backed performance guarantees. Aerospace engineering firms in Germany and Japan unbundle these services from hardware supply agreements to capture specialized application engineering margins.
- Custom Application Development:Bespoke robot programming and process optimization for unique production workflows. FDA 21 CFR Part 820 medical device validation requirements in the United States command premium service margins for surgical robot controller compliance engineering.
- System Retrofit:Legacy equipment modernization with open-platform controller migration and fieldbus gateway development.
- Technical Consulting:Feasibility studies, safety risk assessments, and ISO 10218-1 collaborative robot certification support.
Turnkey Integration holds the dominant share, with Custom Application Development expanding most quickly in regulated manufacturing segments.
Software Solution:
Revenue velocity varies dramatically between visualization commodities and simulation platforms that displace physical commissioning.
- Simulation Software:Virtual commissioning environments with digital twin convergence for offline robot programming and cycle time optimization. Cleanroom semiconductor fabrication in South Korea leverages these tools to reduce particle contamination risks during physical startup.
- Programming Software:Open-platform environments attracting mid-tier integrators seeking vendor flexibility versus proprietary fieldbus lock-in.
- Visualization Tools:Human-machine interface dashboards for real-time production monitoring and alarm management.
- Maintenance Software:Predictive diagnostics and remote monitoring platforms for controller network health and servo-drive performance tracking.
- Security Software:Cybersecurity modules addressing connected factory liability exposure and insurance premium escalation.
Simulation Software claims the dominant share, while Security Software is gaining share fastest amid tightening procurement specifications.
End User:
End-use concentration maps directly to certification complexity and hygienic design requirements that sustain integration premiums.
- Electronics Manufacturing:High-speed surface-mount assembly and precision component placement with CE marking functional safety validation. France and Italy restructure procurement specifications to require SIL-rated safety modules for collaborative applications.
- Food Processing:Hygienic design certifications and traceability protocols demand specialized stainless-steel robot configurations with IP69K washdown ratings.
- Aerospace Engineering:Large-part machining and composite layup operations with unbundled simulation service contracts.
- Textile Production:Continuous material handling and quality inspection systems for fabric cutting and sewing automation.
- Packaging Firms:High-speed case packing and palletizing with extended EU Machinery Directive validation timelines compressing project delivery schedules.
Electronics Manufacturing retains the dominant share, though Food Processing is climbing the fastest as hygienic automation standards proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. South Korean semiconductor fabricators prioritize deterministic network performance over cost, while Indian contract manufacturers weigh mid-tier controller pricing heavily against integration service bundles.
Germany
Automotive battery assembly lines in Stuttgart and Munich drive demand for high-precision motion controllers with sub-millisecond cycle times. The EU Machinery Directive 2006/42/EC enforces SIL-rated safety module requirements for collaborative robot deployments. Bavarian aerospace engineering firms unbundle simulation services from hardware supply agreements to capture specialized application margins.
China
MIIT dual carbon goals accelerate domestic controller replacement cycles in heavy manufacturing corridors. Updated GB standards administered by SAMR mandate electromagnetic compatibility and safety stop performance for industrial robots. Yangtze River Delta electronics manufacturers restructure procurement specifications to favor certified safety PLCs in collaborative applications.
South Korea
Pyeongtaek-Yongin semiconductor fabrication corridors concentrate procurement for cleanroom-compatible robot software contracts. MFDS medical device regulations shape validation requirements for surgical robot controllers in healthcare manufacturing. Seoul Capital Area integrators compete for precision motion architecture contracts where particle contamination risks demand virtual commissioning workflows.
United States
FDA 21 CFR Part 820 quality system regulations govern medical device manufacturing robots, compelling software revision control and failure mode documentation. Automotive battery assembly in Michigan and Ohio expands controller deployments for cell stacking operations. Greater Boston aerospace engineering firms adopt digital twin convergence to reduce physical prototype downtime.
Japan
METI industrial policy supports high-speed CNC-robot synchronization through proprietary fieldbus architectures. JIS standards anchor functional safety validation for electronics manufacturing and packaging lines. Nagoya automotive corridors and Osaka precision machinery clusters sustain demand for deterministic motion control systems with multi-axis interpolation capabilities.
Robot Controller, Integrator and Software Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the controller ecosystem. The market structures around three tiers: premium-validated suppliers with captive servo production, mid-tier open-platform vendors, and regional integration specialists. European automotive lines favor deterministic network specialists, while Asian electronics manufacturers accept proprietary fieldbus lock-in for synchronization performance. Competitive moves concentrate on backward integration into servo-drive manufacturing and geographic expansion through local integration partnerships.
Among Switzerland-based and Germany-based industrial automation groups, ABB and Siemens occupy positions on opposite ends of the platform spectrum. ABB anchors premium-tier supply through in-house servo motor production, while Siemens exemplifies open-platform strategy attracting mid-tier integrators. Japanese machinery specialists FANUC and Yaskawa Electric sit within the proprietary architecture tier, their fieldbus dominance creating switching friction for automotive lines seeking vendor flexibility. These three archetypes represent the structural fault lines shaping procurement specifications across battery assembly and semiconductor fabrication corridors.
| Leading Market Players |
|---|
| ABB |
| FANUC |
| Yaskawa Electric |
| KUKA |
| Mitsubishi Electric |
| Omron |
| KEYENCE |
| Siemens |
| Rockwell Automation |
| Others |
Pricing and Supply Chain Analysis
Project-based integration contracts with multi-year service attachments lock in supply access for German automotive battery lines while anchoring price visibility against silicon carbide power module volatility. This structure concentrates procurement leverage among turnkey integrators serving FDA-regulated medical device manufacturers and CE-marked electronics packaging firms.
Pricing Analysis
ISO 10218-1 safety certification tiers dictate the pricing tier structure across collaborative robot controllers, separating SIL-rated premium modules from basic-compliance alternatives. Three-tier pricing stratifies across certified safety PLCs, standard logic controllers, and economy pneumatic systems, with customization depth and after-sales service bundling as primary differentiation drivers. Cost compression in mid-tier hardware is intensifying because Japanese proprietary fieldbus architectures limit vendor switching. European automotive OEMs exhibit lowest price sensitivity, prioritizing deterministic network performance, while Indian contract manufacturers under PLI scheme incentives weigh controller pricing heavily against integration service bundles.
Supply Chain Analysis
Taiwan semiconductor foundry capacity for advanced servo-drive ASICs underwrites controller hardware availability for precision motion architectures. Manufacturing concentrates in Japan, Germany, and China, with raw material dependencies spanning silicon carbide substrates, rare-earth permanent magnets, and high-grade copper windings. Single-source vulnerability runs through Japanese fieldbus protocol suppliers serving FANUC-dominated machining cells. Distribution runs through authorized system integrator networks with captive service attach contracts, bypassing direct OEM procurement in regulated end-uses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Simulation software and virtual commissioning services are expanding faster than hardware as aerospace engineering firms unbundle digital validation from controller supply agreements. This service-attach layer commands recurring revenue streams that outpace motion controller unit economics.
For Market Incumbents: Consolidate backward integration into servo-drive manufacturing to defend margin architecture against silicon carbide cost volatility. Capture ISO 10218-1 certification talent pools in South Korea and Germany to maintain premium-tier positioning against mid-tier open-platform vendors. Deepen channel control through exclusive integration partnerships in India's PLI-subsidized manufacturing corridors. For New Entrants and Emerging Players: Anchor in India's electronics contract manufacturing clusters where mid-tier controller demand outpaces established integration capacity. Target FDA 21 CFR Part 820 compliance engineering services as the most penetrable white-space segment, with surgical robot validation expertise as the differentiated go-to-market angle. Leverage open-platform programming environments to attract integrators seeking escape from Japanese fieldbus lock-in. For Investors and Strategic Acquirers: Capital is best deployed toward simulation software specialists with digital twin capabilities converging into real-time diagnostics, positioned for sustained viability across the analysis window. Watch for inflection signals in semiconductor fabrication virtual commissioning adoption rates as particle contamination risk management drives procurement specification changes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo-Drive Manufacturing | Captures margin pool from silicon carbide power modules in German automotive battery lines. |
| ISO 10218-1 Safety Certification Investment | Unlocks premium pricing tiers for collaborative robot controllers in EU electronics manufacturing. |
| Virtual Commissioning Platform Launch | Reduces physical prototype downtime for South Korean semiconductor fabricators in Pyeongtaek. |
| India PLI Corridor Integration Partnership | Establishes local service capacity for mid-tier controller demand in electronics contract manufacturing. |
| FDA 21 CFR Part 820 Compliance Engineering Service | Commands premium margins for surgical robot validation in North American healthcare manufacturing. |
Research Methodology
Cross-validation between primary interviews with robot controller procurement managers, system integrator technical leads, and semiconductor fabrication engineers anchors the qualitative findings against secondary validation. Plant engineers at German automotive battery lines, FDA quality affairs directors at medical device manufacturers, and aftermarket service heads at Japanese machinery specialists provided operational demand perspectives. Secondary sources include SEC filings from listed automation vendors, MIIT GB standard updates, EU Machinery Directive implementation guidance, and customs trade data for servo-drive component flows. Bottom-up unit economics and top-down sectoral demand triangulate volume estimates.
Sensitivity analysis across deployment scale, certification tier, and regional regulatory cluster tests forecast robustness over the projection horizon. Segmentation dimensions modeled include controller hardware type, integration service depth, software solution category, and end-use industry vertical with regional production cluster overlays. CAGRs derive from regression against industrial automation capex cycles and electric vehicle battery capacity expansion trajectories. Forecast inputs incorporate MIIT dual carbon policy implementation pace and FDA medical device manufacturing inspection priority shifts.
Underlying assumptions cover sustained electric vehicle battery assembly automation demand and stable silicon carbide supply availability, with deviation risk concentrated in cybersecurity liability recalibration and fieldbus architecture standardization delays. Practitioners should keep alternative scenarios live as China's SAMR enforcement intensity and EU Machinery Directive timeline compression evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.