
 Global Molecular Robotics Market | 2026-2036
Global Molecular Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Molecular Robotics Market Foresight
Pharmaceutical R&D is recalibrating procurement priorities toward programmable molecular systems for targeted drug delivery. Thermo Fisher Scientific leverages its reagent-to-instrument ecosystem to anchor contract research workflows. Danaher Corporation sustains multi-brand instrumentation density across high-throughput screening labs.
Molecular robotics encompasses engineered nanoscale devices constructed from DNA, protein, or synthetic molecular components, typically operating at sub-100 nanometer scales with programmable conformational states for cargo transport or chemical manipulation. DNA origami systems dominate current fabrication due to predictable base-pairing geometries, while enzyme-driven architectures capture expanding interest for energy-autonomous operation. Hybrid systems concentrate margin pools where multi-modal functionality commands premium positioning in molecular diagnostics workflows.
FDA biocompatibility standards for implantable nanodevices shape product development timelines for US market entry, while EMA's evolving ATMP classification framework determines reimbursement pathways for cell-interfacing molecular robots in Europe. ISO nanotechnology terminology standards provide foundational interoperability for cross-border preclinical data exchange. Stakeholders must monitor regulatory divergence between adaptive pathway frameworks and traditional PMA requirements when prioritizing geographic launch sequencing.
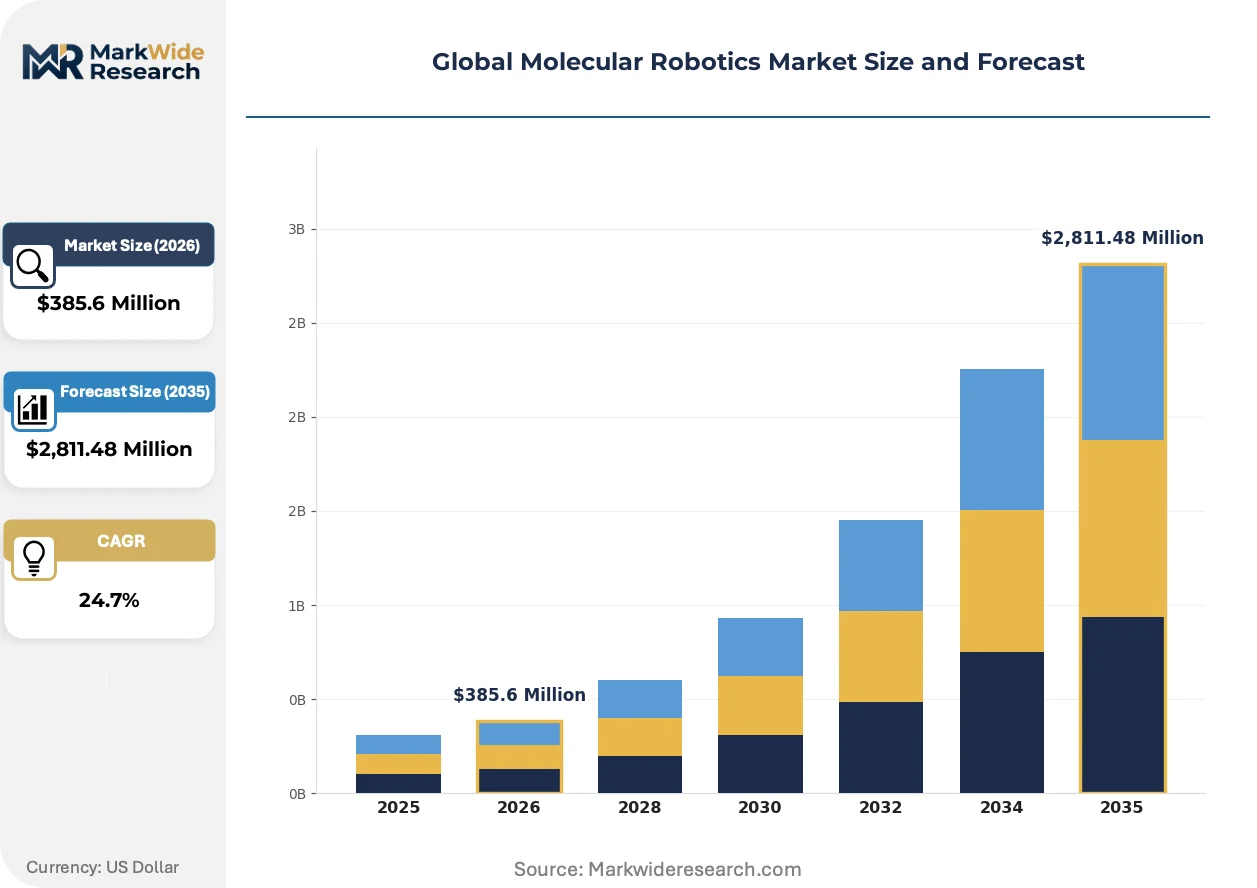
Market Dynamics
DNA origami fabrication is rewriting cost structures for programmable nanoscale devices, compressing prototyping cycles from months to weeks while pharmaceutical R&D departments recalibrate procurement priorities toward precision therapeutics.
Growth Catalysts
- EMA ATMP Classification:The evolving framework in Europe creates reimbursement clarity for cell-interfacing molecular robots, accelerating clinical translation timelines for implantable therapeutic devices.
- Enzyme-Driven Architectures:Energy-autonomous operation eliminates external power requirements, opening deployment scenarios in inaccessible physiological environments for targeted cargo transport.
- Baden-Württemberg Cluster:Fraunhofer institutes anchor translational research density, concentrating vendor-proximity advantages for contract manufacturing scale-up.
Market Restraints
- Purified Nucleotide Costs:Synthetic DNA oligomer input prices fluctuate with phosphoramidite chemical feedstock volatility, squeezing margin structures for high-complexity origami designs.
- FDA Biocompatibility Timelines:Implantable nanodevice PMA pathways extend development-to-market intervals, freezing capital in preclinical validation phases.
- Protein-Based Substitutes:Engineered viral capsids compete for intracellular delivery applications with simpler manufacturing workflows and established regulatory precedents.
Strategic Opportunities
- Japan's Regenerative Medicine Sandbox:PMDA conditional approval pathways for novel therapeutic modalities reduce time-to-revenue for first-in-class molecular robotic interventions.
- ISO Nanotechnology Terminology:Standardized preclinical data formats unlock cross-border trial pooling, reducing redundant safety studies for multi-jurisdictional filings.
- Hybrid Multi-Modal Systems:Convergence of DNA origami scaffolds with enzyme actuators commands premium positioning in molecular diagnostics workflows requiring simultaneous sensing and manipulation.
Industry Challenges
- Specialized Fabrication Talent:Cross-disciplinary expertise spanning structural DNA nanotechnology and microfluidic integration remains scarce, inflating compensation premiums for R&D team assembly.
- Legacy LIMS Integration:Molecular robotics data formats conflict with existing pharmaceutical laboratory information management systems, requiring custom middleware development for workflow incorporation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Molecular Robotics Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $2,811.48 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DNA Robots, Protein Robots, RNA Robots, Synthetic Molecular Machines, Hybrid Systems Technology: Self-Assembly, DNA Origami, Molecular Motors, Nanoparticle-based, Enzyme-driven Application: Targeted Drug Delivery, Biosensing, Molecular Diagnostics, Environmental Monitoring, Chemical Synthesis End User: Pharmaceutical R&D, Biotechnology Firms, Academic Institutions, Contract Research Organizations |
| Companies Covered | Bruker Corporation, Danaher Corporation, Thermo Fisher Scientific Inc., PerkinElmer Inc., Qiagen N.V., Ginkgo Bioworks, Zymergen Inc., Imina Technologies SA, JEOL Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Molecular Robotics Market Shifts & Advancements
Programmable matter architectures are compressing the boundary between materials science and therapeutics, forcing simultaneous advances in fabrication fidelity and regulatory science.
Dynamic DNA nanotechnology is rewriting the functional repertoire of molecular machines. Strand displacement circuits enable real-time conformational switching in response to biomolecular cues. Oncology R&D groups at major pharmaceutical firms are embedding these systems into preclinical screening workflows. The technology is rewriting expectations for in vitro model fidelity, displacing static nanoparticle controls with responsive, logic-gated alternatives.
REACH chemical registration requirements in Europe are tightening disclosure obligations for synthetic DNA constructs used in consumer-facing applications. Industrial consequence includes mandatory safety dossier compilation for oligonucleotide components above tonnage thresholds. Diagnostic assay manufacturers are responding by segregating EU-bound product lines from research-grade materials to contain compliance costs.
Pharmaceutical procurement departments are consolidating vendor relationships around full-stack reagent-to-instrument ecosystems. Single-source contracting displaces multi-vendor assembly of molecular robotics components. This concentration is most visible in Germany's Baden-Württemberg corridor, where translational research clusters negotiate enterprise pricing for integrated fabrication and analytics platforms.
Global Molecular Robotics Market Segmentation
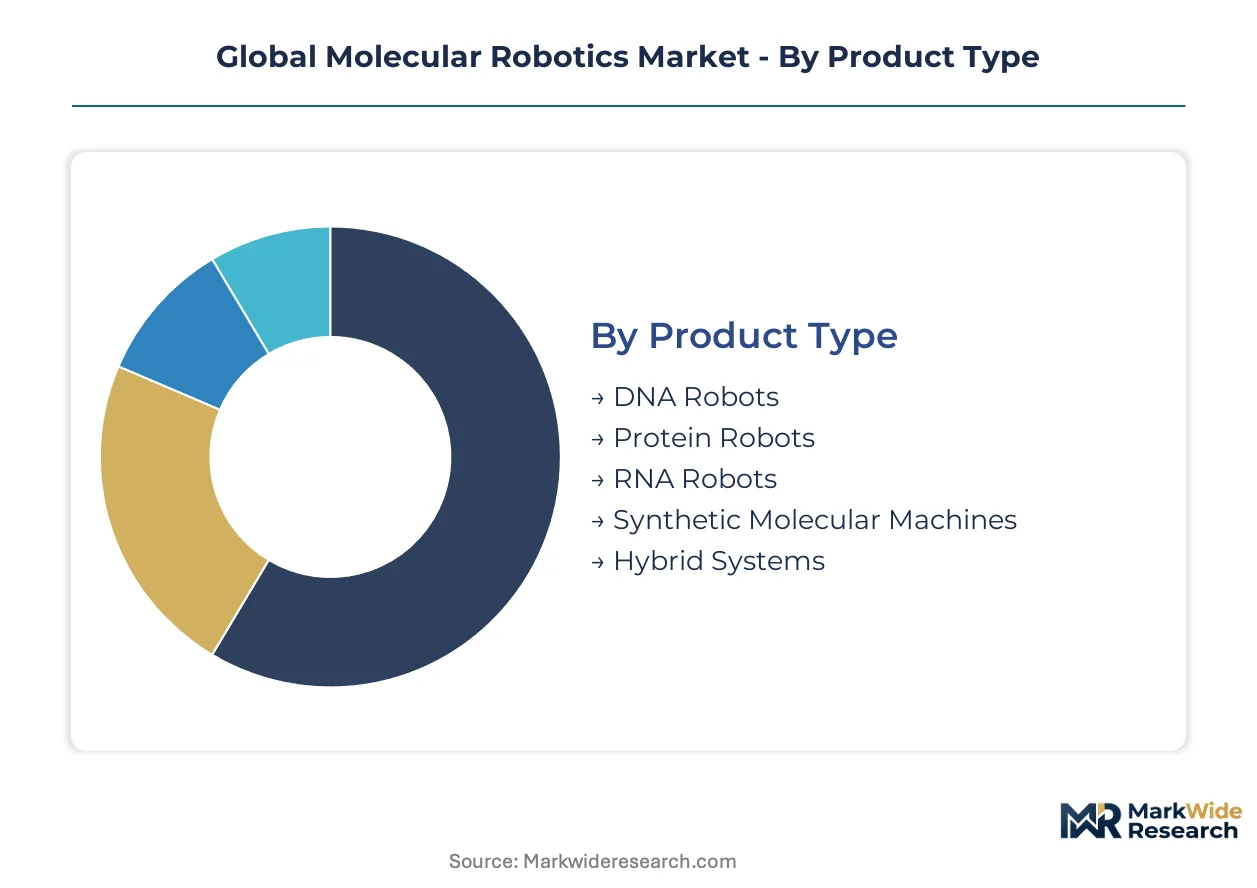
Segmentation in molecular robotics reveals distinct capability-performance tradeoffs across fabrication platforms. Technology choices lock in regulatory pathways and manufacturing scalability, while application focus determines reimbursement potential and competitive moat depth.
Product Type:
Upgrade cycles in molecular robotics accelerate as pharmaceutical R&D departments replace first-generation static nanoparticles with programmable, logic-gated alternatives. Procurement teams now evaluate total cost of ownership across fabrication fidelity, regulatory validation burden, and integration complexity.
- DNA Robots:Engineered nanostructures exploit predictable Watson-Crick base pairing to achieve sub-5 nanometer positional precision in cargo placement. Thermo Fisher Scientific's integrated reagent-instrument ecosystems dominate contract research procurement in Germany's Baden-Württemberg corridor, where Fraunhofer institutes validate clinical translation protocols.
- Hybrid Systems:Multi-modal architectures combine DNA origami scaffolds with protein or synthetic components to enable simultaneous sensing, computation, and actuation. These systems command premium positioning in molecular diagnostics workflows at Danaher Corporation's high-throughput screening installations, where dual-functionality reduces assay step count.
- Protein Robots:Engineered viral capsids and motor proteins leverage evolved intracellular trafficking mechanisms for delivery applications.
- RNA Robots:Ribozyme-based architectures enable catalytic activity with reduced immunogenicity profiles compared to DNA counterparts.
- Synthetic Molecular Machines:Non-biological molecular components including rotaxanes and catenanes provide abiotic stability in harsh chemical environments.
DNA Robots sits at the top of the volume ranking, with Hybrid Systems climbing the fastest.
Technology:
Cost tier stratification separates research-grade fabrication from clinical-ready manufacturing, with GMP-compatible workflows carrying 3-4x overhead premiums. Technology selection dictates capital equipment requirements and cleanroom classification thresholds.
- DNA Origami:Scaffolded DNA folding techniques achieve complex three-dimensional geometries through thermal annealing of long single-stranded templates with short staple oligonucleotides. REACH chemical registration requirements in Europe mandate safety dossier compilation for synthetic DNA constructs above tonnage thresholds, pushing diagnostic manufacturers to segregate EU-bound product lines.
- Enzyme-driven:Biological motor proteins including kinesin and myosin convert chemical energy into mechanical work without external power infrastructure. Energy-autonomous operation opens deployment scenarios in inaccessible physiological environments for targeted cargo transport, particularly in oncology applications where FDA biocompatibility timelines extend development intervals.
- Self-Assembly:Spontaneous organization of molecular components through non-covalent interactions enables parallel fabrication at scale.
- Molecular Motors:Synthetic rotary and linear motors achieve directional motion through controlled energy landscapes.
- Nanoparticle-based:Inorganic cores with molecular surface functionalization bridge electronic and biological signal domains.
DNA Origami captures the dominant revenue share, while Enzyme-driven approaches gain share fastest in therapeutic applications.
Application:
Application concentration follows reimbursement pathway maturity, with diagnostic applications achieving faster regulatory clearance than therapeutic interventions. Volume distribution reflects the gap between technical feasibility and commercial validation.
- Targeted Drug Delivery:Molecular robots navigate physiological barriers to release therapeutic payloads at disease-specific biomarker signatures. EMA's evolving ATMP classification framework determines reimbursement pathways for cell-interfacing molecular robots in Europe, accelerating clinical translation timelines for implantable therapeutic devices.
- Molecular Diagnostics:Programmable sensing platforms detect nucleic acid and protein analytes with single-molecule sensitivity. Japan's PMDA conditional approval pathways for novel therapeutic modalities reduce time-to-revenue for first-in-class molecular robotic interventions, concentrating vendor investment in Tokyo-Osaka research corridors.
- Biosensing:Real-time molecular detection systems interface with electronic readout infrastructure for continuous monitoring.
- Environmental Monitoring:Field-deployable molecular sensors detect contaminants in water and soil matrices.
- Chemical Synthesis:Molecular machines enable stereoselective catalysis with atomic precision in reaction control.
Targeted Drug Delivery leads absolute volume, with Molecular Diagnostics expanding most quickly due to faster regulatory cycles.
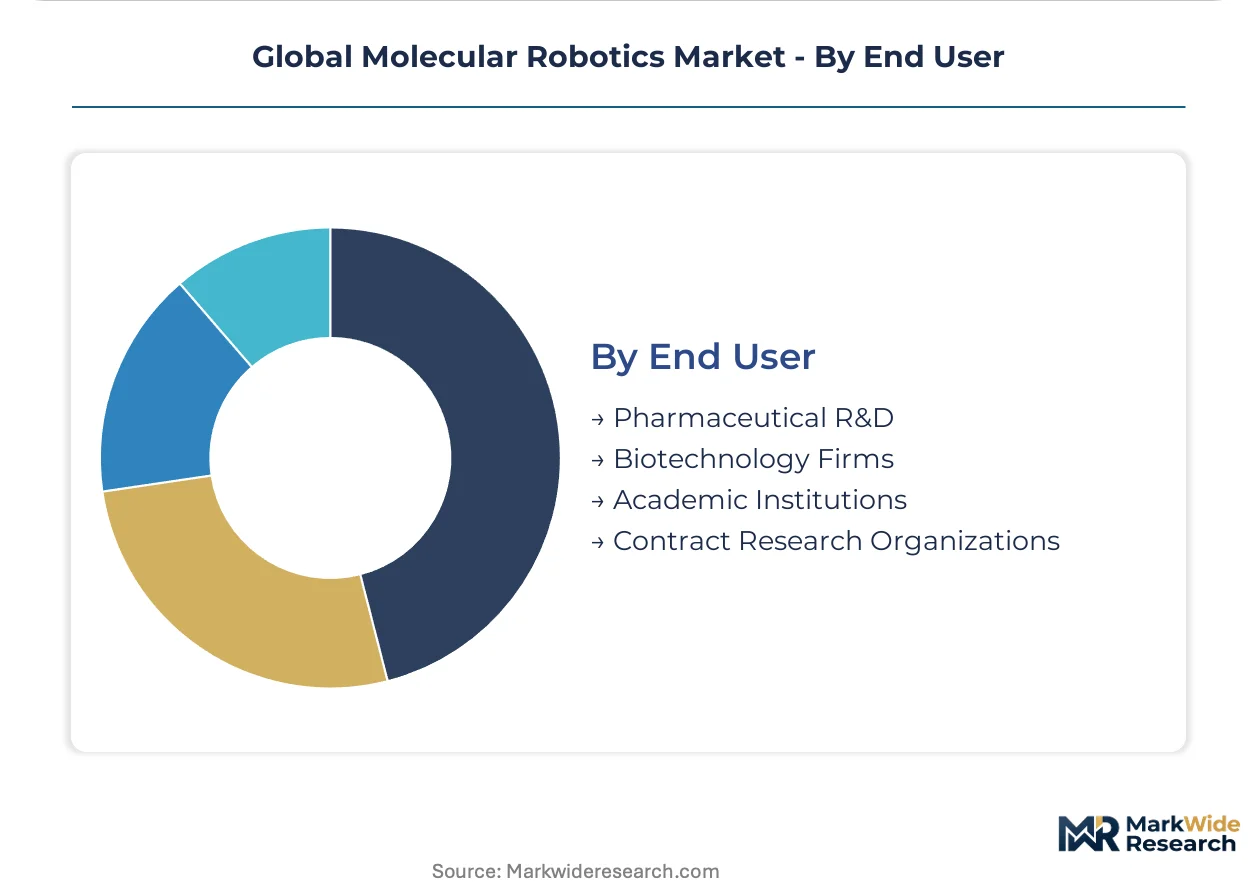
End User:
Customer type determines procurement sophistication, with pharmaceutical R&D departments consolidating around full-stack ecosystems while academic users prioritize modularity and publication flexibility. Contract research organizations occupy intermediate positions with standardized validation requirements.
- Pharmaceutical R&D:Integrated drug discovery divisions demand validated, scalable platforms with regulatory documentation packages. ISO nanotechnology terminology standards provide foundational interoperability for cross-border preclinical data exchange, reducing redundant safety studies for multi-jurisdictional filings at major pharma headquarters in the US, Switzerland, and Japan.
- Biotechnology Firms:Venture-backed developers prioritize rapid prototyping cycles and technology licensing flexibility for platform expansion. Specialized fabrication talent scarcity spanning structural DNA nanotechnology and microfluidic integration inflates compensation premiums for R&D team assembly in Boston and San Francisco clusters.
- Academic Institutions:Research laboratories prioritize publication-grade reproducibility and open-source design accessibility.
- Contract Research Organizations:Service providers standardize on instrumentation platforms that minimize client-specific customization overhead.
Pharmaceutical R&D dominates procurement value, with Biotechnology Firms showing the steepest expansion trajectory as platform companies advance toward clinical milestones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping molecular robotics manufacturing geography, with fabrication capacity migrating toward jurisdictions offering streamlined biocompatibility pathways and concentrated translational research infrastructure.
United States
FDA biocompatibility timelines for implantable nanodevices extend development-to-market intervals, freezing capital in preclinical validation phases. The IRA's advanced manufacturing tax credits incentivize domestic production of precision therapeutic platforms. Greater Boston anchors specialized fabrication talent pools spanning structural DNA nanotechnology and microfluidic integration.
Germany
EU MDR framework tightening biocompatibility requirements for implantable molecular devices concentrates vendor-proximity advantages in translational clusters. REACH chemical registration mandates safety dossier compilation for synthetic DNA constructs above tonnage thresholds. Baden-Württemberg's Fraunhofer institutes validate clinical translation protocols for enterprise pricing negotiations.
Japan
PMDA conditional approval pathways for novel therapeutic modalities reduce time-to-revenue for first-in-class molecular robotic interventions. METI funding for regenerative medicine sandboxes accelerates vendor investment in Tokyo-Osaka research corridors. Kanto region biotechnology firms prioritize rapid prototyping cycles for platform expansion toward clinical milestones.
Switzerland
Swissmedic's adaptive licensing frameworks attract platform companies seeking regulatory efficiency for cell-interfacing molecular robots. Federal technology transfer programs bridge academic structural DNA nanotechnology with industrial microfluidic integration. Basel's pharmaceutical headquarters consolidate vendor relationships around full-stack reagent-to-instrument ecosystems.
United Kingdom
Post-Brexit divergence from EU MDR creates parallel compliance obligations for implantable nanodevice manufacturers serving European markets. UK Research and Innovation funding concentrates specialized fabrication expertise in Cambridge-Oxford-London triangle. London-based contract research organizations standardize on instrumentation platforms minimizing client-specific customization overhead.
Global Molecular Robotics Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical R&D procurement consolidating around integrated ecosystems while academic users prioritize modularity. The vendor base concentrates among multi-brand instrumentation conglomerates, precision fabrication specialists, and synthetic biology platform developers. Three archetypes dominate: full-stack reagent-to-instrument providers, DNA origami fabrication specialists, and enzyme-driven architecture innovators. Competitive moves center on strategic partnerships for regulatory validation bundling and backward integration into phosphoramidite chemical feedstocks.
Among diversified instrumentation conglomerates, Danaher Corporation and Thermo Fisher Scientific occupy positions anchoring high-throughput screening lab density. Bruker Corporation exemplifies the precision analytics tier where multi-modal functionality commands premium positioning. These three entities represent distinct competitive vectors: ecosystem integration, fabrication scale, and analytical instrumentation specialization respectively.
| Leading Market Players |
|---|
| Bruker Corporation |
| Danaher Corporation |
| Thermo Fisher Scientific Inc. |
| PerkinElmer Inc. |
| Qiagen N.V. |
| Ginkgo Bioworks |
| Zymergen Inc. |
| Imina Technologies SA |
| JEOL Ltd. |
| Others |
Supply & Pricing Matrix
Captive backward integration into phosphoramidite chemical feedstocks anchors pricing power for DNA origami fabricators, while contract manufacturers without upstream control face margin compression from synthetic nucleotide cost volatility. Pharmaceutical R&D procurement teams leverage this supply asymmetry to extract volume discounts from full-stack ecosystem providers in Germany's Baden-Württemberg corridor.
Pricing Analysis
Distributor margins in molecular robotics equipment compress the final price by 15-25 points before reaching end-user laboratories. Three-tier pricing structure across premium, standard, and economy levels separates GMP-validated clinical-grade systems from research-grade fabrication kits. Cost compression in the economy tier is intensifying because REACH chemical registration mandates are pushing diagnostic manufacturers to segregate EU-bound product lines. Academic institutions exhibit the highest price sensitivity, while pharmaceutical R&D departments prioritize regulatory documentation packages over unit cost.
Supply Chain Analysis
Dual-sourcing requirements for phosphoramidite reagents are now standard among DNA origami fabricators seeking to mitigate single-source vulnerability. Manufacturing concentration rests on Germany, the United States, and Japan, where Fraunhofer institutes, Greater Boston talent pools, and Tokyo-Osaka research corridors anchor production. Synthetic DNA oligomer inputs draw from chemical feedstock suppliers in China and South Korea. Distribution runs through specialized life sciences distributors with cold-chain capabilities for temperature-sensitive reagents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in molecular robotics hinges on enzyme-driven architecture adoption, which eliminates costly external power infrastructure and commands premium positioning in therapeutic applications.
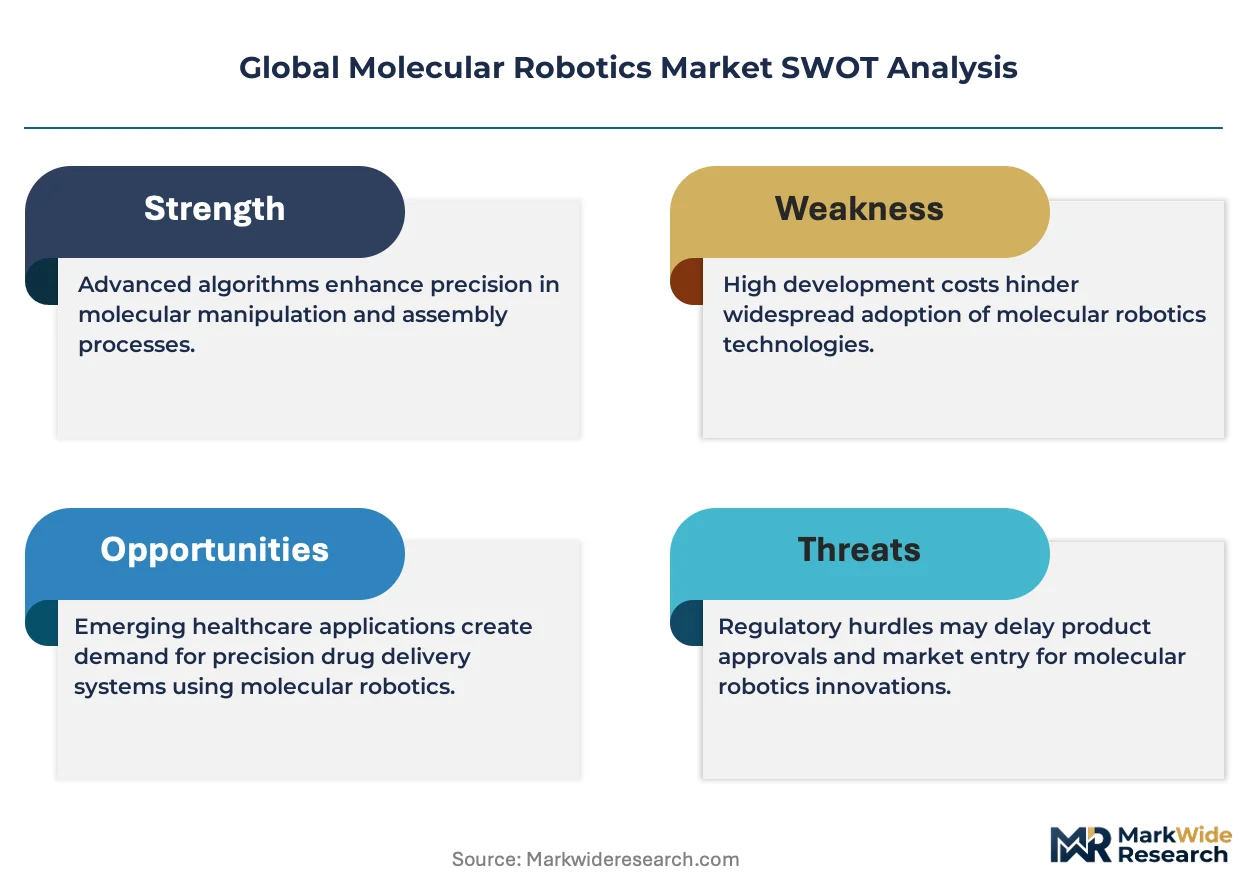
For Market Incumbents: Extend regulatory validation bundling across EMA ATMP and FDA biocompatibility pathways to lock in pharmaceutical procurement contracts. Backward integration into staple oligonucleotide synthesis protects margin structures from phosphoramidite price volatility. Incumbents must counter protein-based viral capsid substitutes by emphasizing programmable conformational states that static nanoparticles cannot replicate. For New Entrants and Emerging Players: Begin with Japan's PMDA conditional approval sandbox, where reduced time-to-revenue for first-in-class interventions creates white-space opportunity. Molecular diagnostics workflows offer faster regulatory cycles than therapeutic applications, enabling revenue generation while clinical translation timelines extend. A licensing-first go-to-market model with established CROs minimizes capital requirements for GMP facility investment. For Investors and Strategic Acquirers: Roll-up economics work for precision fabrication specialists because specialized talent scarcity spanning structural DNA nanotechnology and microfluidic integration inflates acquisition premiums for standalone teams. Platform companies advancing toward clinical milestones in the 5-10 year window offer the strongest viability framing. Watch for EMA ATMP classification clarity as the inflection signal triggering consolidation in cell-interfacing molecular robotics.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | EMA ATMP classification clarity accelerates reimbursement for implantable therapeutic devices in Europe. |
| Backward Integration | Captive phosphoramidite production insulates DNA origami fabricators from synthetic nucleotide cost volatility. |
| Strategic Partnership | Fraunhofer institute collaborations validate clinical translation protocols for Baden-Württemberg vendors. |
| Product Launch | Hybrid multi-modal systems combining DNA scaffolds with enzyme actuators command premium diagnostics positioning. |
| Geographic Expansion | Tokyo-Osaka corridor investment leverages PMDA conditional approval pathways for faster revenue generation. |
Research Methodology
Multiple input streams — primary interviews with drug development executives and regulatory affairs leads, secondary validation through FDA filings and EMA submissions, and bottom-up triangulation against ClinicalTrials.gov records — were reconciled to construct segment-level demand estimates. Conversations with formulary directors and hospital procurement managers informed reimbursement pathway assessments. Top-down cross-checks against SEC 10-K disclosures from diversified instrumentation conglomerates anchored aggregate market sizing.
Historical trend extrapolation was cross-referenced against expert panel inputs to derive expansion rates across the projection horizon. Segmentation modeling incorporated product type, technology platform, application focus, and end-user procurement sophistication as core dimensions. Enzyme-driven architecture adoption curves and DNA origami fabrication cost trajectories served as industry-specific forecast inputs, with CAGRs synthesized from diffusion modeling and capital deployment patterns.
Several conditions sit outside the modeled scope, including unforeseen regulatory divergence between EU MDR and post-Brexit UK frameworks, and breakthrough advances in protein-based substitutes displacing DNA origami. Forecasts reflect documented assumptions about biocompatibility validation timelines and phosphoramidite feedstock stability. Deviation in FDA PMA pathway duration or EMA ATMP classification timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Waste Sorting Robots Market
Robotics and Automation
South Korea Cloud Robotics Market
Robotics and Automation
Global Rescue Robot Market
Robotics and Automation
Commercial Security Robots Market
Robotics and Automation
North America AUV and ROV Market
Robotics and Automation
Autonomous Security Robots Market
Robotics and Automation
Self-Driving Floor Scrubbers Market
Robotics and Automation
Vision Guided Robotics Market
Robotics and Automation
Robotics End of Arm Tooling Market
Robotics and Automation
Robotics in Shipbuilding Market
Robotics and Automation
Robotics Actuators Market
Robotics and Automation
Retail Robotics Market
Robotics and Automation
Firefighting Robots Market
Robotics and Automation
Smart Personal Assistance Devices Market
Robotics and Automation
North America Automated Liquid Handling Market
Robotics and Automation
Automated Liquid Handling Technologies Market