
 Self-Driving Floor Scrubbers Market | 2026-2036
Self-Driving Floor Scrubbers Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Driving Floor Scrubbers Market Insights
The gap between vision-based and LiDAR-dependent navigation architectures is narrowing as sensor fusion costs decline and edge computing performance improves. Alfred Kärcher SE & Co. KG leverages its European manufacturing footprint to sustain premium positioning in industrial-grade autonomous scrubbers. Brain Corp anchors the North American market through its AI software platform licensed to multiple equipment OEMs. Gaussian Robotics specializes in compact form factors designed for Asia-Pacific retail environments.
Self-driving floor scrubbers are electromechanical cleaning systems integrating autonomous navigation, water recovery, and brush agitation mechanisms to execute floor sanitation cycles without human operators. These machines typically operate at 0.5–1.2 meters per second, carry 50–150 liter solution tanks, and rely on SLAM-based mapping for dynamic obstacle avoidance in cluttered commercial spaces. Robotic scrubbers dominate current revenue as established logistics operators validate return-on-investment through labor displacement metrics. AI-powered floor cleaners represent the fastest-expanding category, with computer vision and machine learning segments capturing disproportionate R&D allocation as vendors differentiate through predictive maintenance and anomaly detection capabilities.
FCC equipment authorization governs wireless telemetry modules embedded in fleet-managed units, while OSHA General Industry Standards influence machine guarding and emergency stop requirements for human-robot collaboration zones. The EU AI Act and CE machinery directives are reshaping product liability frameworks for autonomous equipment deployed in European public spaces. Stakeholders must monitor evolving insurance underwriting criteria for autonomous cleaning fleets, as risk transfer mechanisms remain unsettled across commercial property and general liability policies.
Market Dynamics
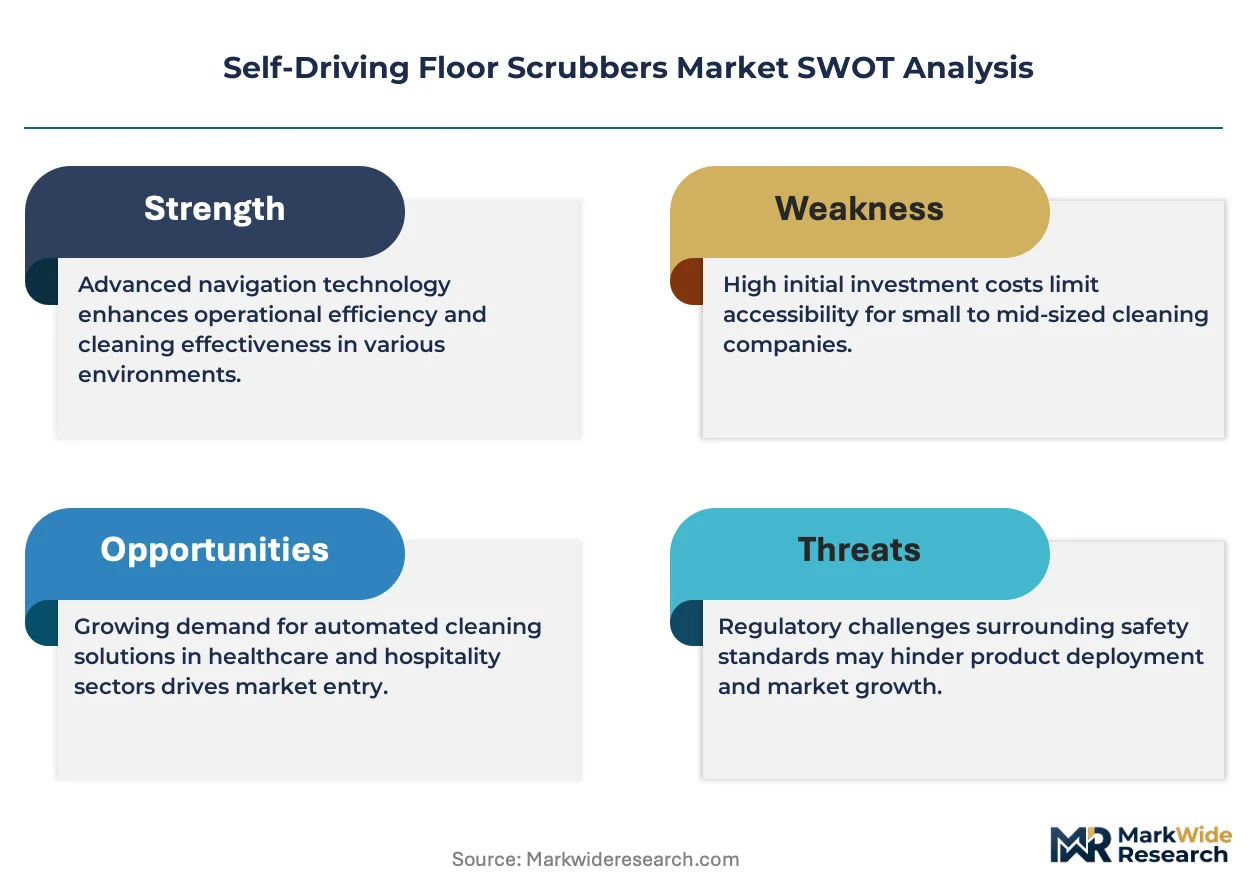
OSHA workplace safety mandates and evolving AI navigation standards are accelerating machine certification requirements for autonomous cleaning equipment, compressing vendor development timelines and reshaping competitive positioning around compliance capabilities.
Growth Catalysts
- Healthcare infection control mandates:Hospital-acquired infection risk reduction protocols are expanding autonomous cleaning fleet procurement in acute care facilities and long-term care institutions.
- FCC equipment authorization frameworks:Standardized wireless telemetry module certification is streamlining fleet-managed unit deployment across multi-site retail and logistics operators.
- Edge computing performance gains:Sensor fusion cost declines are narrowing the capability gap between vision-based and LiDAR-dependent navigation architectures.
Market Restraints
- LiDAR sensor supply concentration:Dependence on specialized optical component manufacturers in East Asia creates input cost volatility and procurement lead time uncertainty.
- EU AI Act liability exposure:Autonomous equipment deployed in European public spaces faces unsettled product liability frameworks and insurance underwriting criteria.
- Manual cleaning labor substitution economics:Low-wage janitorial service markets in emerging economies limit robotic scrubber return-on-investment validation.
Strategic Opportunities
- India retail modernization:Organized retail expansion and shopping mall development create first-mover positioning for compact autonomous scrubber vendors.
- CE machinery directive harmonization:Unified European safety standards reduce certification fragmentation and enable cross-border fleet standardization.
- Predictive maintenance convergence:Integration of machine learning anomaly detection with brush agitation mechanism monitoring enables outcome-based service contracting.
Industry Challenges
- SLAM algorithm talent scarcity:Recruitment of robotics software engineers with simultaneous localization and mapping expertise outpaces supply in key development clusters.
- Human-robot collaboration zone certification:OSHA General Industry Standards compliance for emergency stop and machine guarding systems extends deployment timelines.
- Legacy building infrastructure retrofit costs:Older commercial facilities lack elevator and doorway clearances compatible with autonomous scrubber form factors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Driving Floor Scrubbers Market |
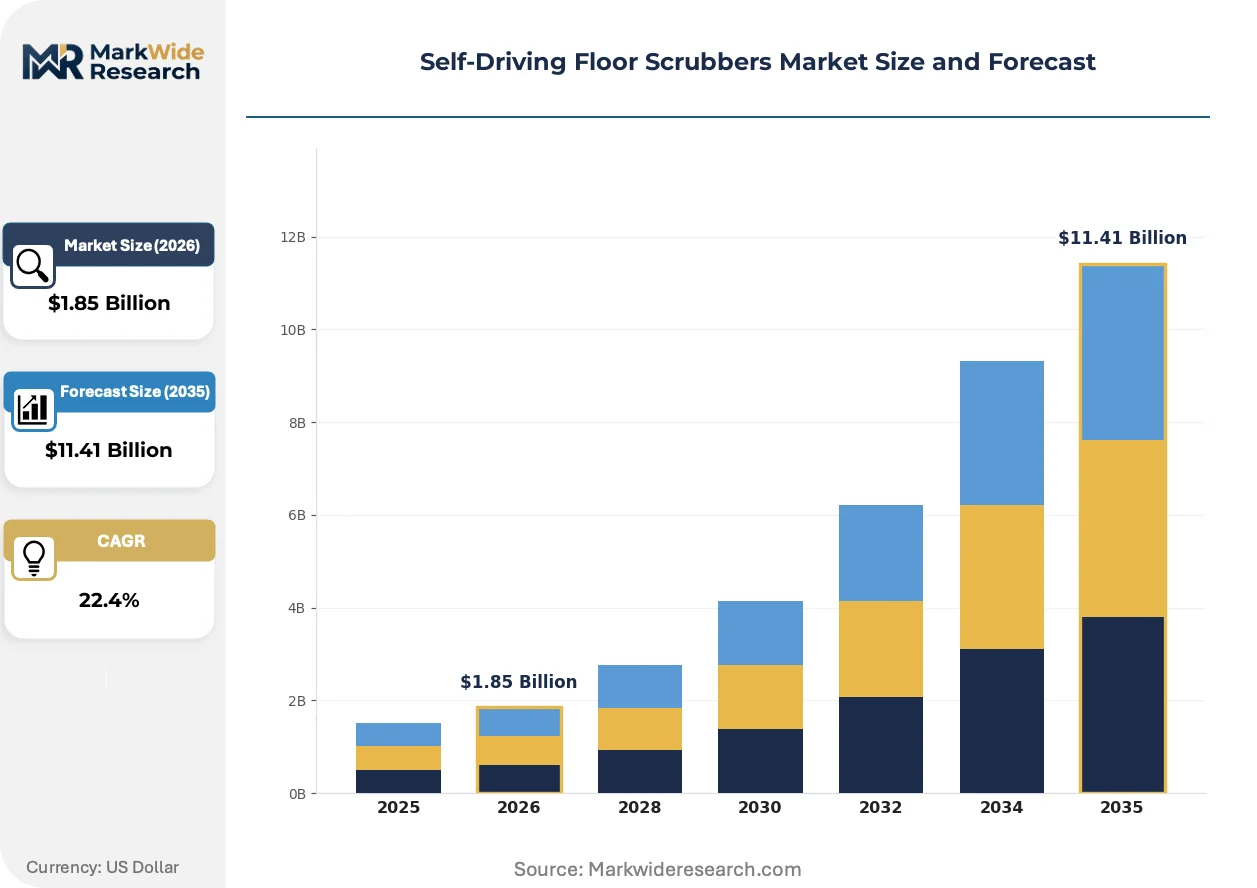
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $11.41 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Scrubbers, Autonomous Scrubbing Machines, AI-Powered Floor Cleaners, Smart Cleaning Solutions End User: Warehouses, Airports, Shopping Malls, Healthcare Facilities Technology: LiDAR Navigation, Computer Vision, Machine Learning, RFID Integration Deployment: On-Premises, Cloud-Based, Hybrid Models, Remote Monitoring |
| Companies Covered | iRobot Corporation, Alfred Kärcher SE & Co. KG, Nilfisk Group, Avidbots Corp., Brain Corp, Gaussian Robotics, VIGGO, Ecovacs Robotics, Tennant Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Driving Floor Scrubbers Market Trends and Innovations
Navigation architecture decisions, regulatory compliance frameworks, and procurement model evolution are the three forces actively restructuring how autonomous floor cleaning equipment reaches end-users and generates returns.
Sensor fusion technology is migrating from premium industrial-grade units to mid-market retail configurations. Grocery chains and big-box retailers are adopting hybrid vision-LiDAR systems at accelerating pace. This technology diffusion is compressing price-performance thresholds and eroding single-sensor competitive moats.
The EU AI Act risk classification system is reshaping conformity assessment procedures for autonomous cleaning equipment. High-risk system designations trigger third-party auditing requirements and technical documentation burdens. European facility management contractors are prioritizing CE-marked units with embedded explainability features to preempt liability exposure.
Equipment-as-a-service contracting is displacing capital purchase models among multi-site logistics operators. Third-party fleet management platforms are capturing maintenance and software update revenue streams. This shift concentrates most visibly in United States distribution center networks where labor arbitrage calculations dominate procurement committees.
Self-Driving Floor Scrubbers Market Segmentation
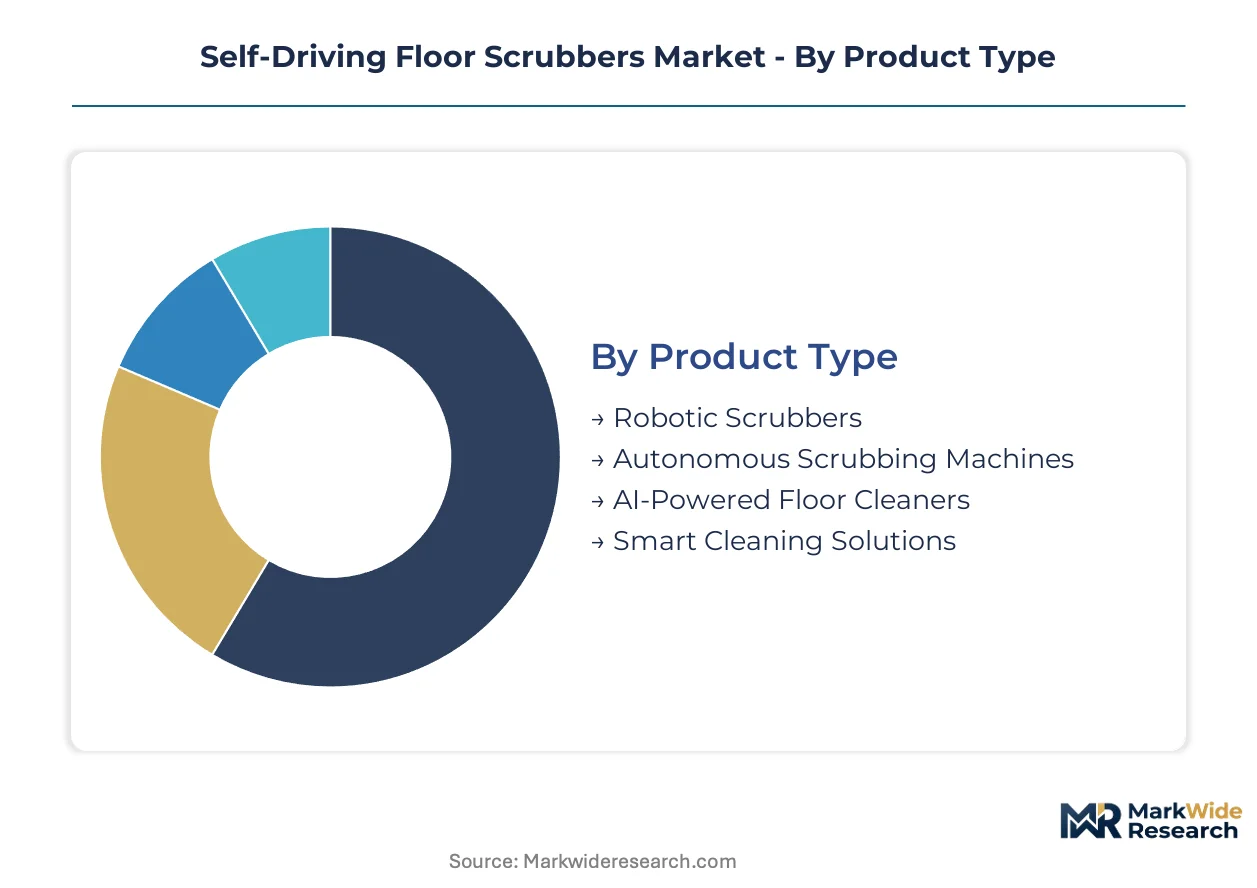
Segmentation in autonomous floor cleaning equipment reveals how procurement priorities diverge across facility types and operational models. Cycle time variations between product categories and deployment architectures directly shape vendor R&D allocation and service revenue structures.
Product Type:
Robotic scrubbers turn over fastest in fleet replacement cycles, while AI-powered configurations refresh slowest due to embedded software licensing terms.
- Robotic Scrubbers:Electromechanical platforms with fixed-path programming and basic obstacle detection dominate current installed base in United States logistics networks. Demand concentrates among third-party facility management contractors seeking labor arbitrage in distribution centers, constrained by limited interoperability with legacy building management systems.
- AI-Powered Floor Cleaners:Computer vision-enabled units with predictive maintenance capabilities capture disproportionate R&D investment from North American software licensors. Procurement is accelerating among healthcare facilities in California and Texas pursuing infection control certification.
- Autonomous Scrubbing Machines:Industrial-grade platforms with SLAM-based navigation serve European manufacturing plants requiring CE machinery directive compliance.
- Smart Cleaning Solutions:Integrated hardware-software bundles with fleet analytics target multi-site retail operators in Germany and France.
Robotic scrubbers anchor the volume base while AI-powered floor cleaners gain share at the steepest rate.
End User:
Cost tier stratification separates capital-intensive warehouse deployments from budget-constrained healthcare procurement.
- Warehouses:Large-format distribution centers in Ohio and Pennsylvania validate return-on-investment through direct labor displacement metrics. OSHA General Industry Standards compliance for human-robot collaboration zones extends deployment timelines in these facilities.
- Healthcare Facilities:Acute care hospitals in Illinois and Florida prioritize autonomous scrubbers with EPA-registered disinfectant compatibility and audit trail documentation. Joint Commission accreditation requirements drive specification rigor.
- Airports:High-traffic terminal operators in Atlanta and Dallas-Fort Worth demand 24/7 operational capability with minimal downtime.
- Shopping Malls:Mixed-use retail complexes in Arizona and Nevada favor compact form factors for escalator and corridor navigation.
Warehouses anchor the volume base while healthcare facilities gain share at the steepest rate.
Technology:
Supply concentration in East Asian optical component manufacturing creates input cost volatility across navigation architectures.
- LiDAR Navigation:Laser-based spatial mapping systems deliver centimeter-level accuracy for dynamic obstacle avoidance in cluttered retail environments. Procurement concentrates among European facility operators seeking EU AI Act conformity assessment compliance.
- Computer Vision:Camera-based perception systems with edge processing enable lower unit economics for mid-market grocery chains. FCC equipment authorization for embedded wireless telemetry modules streamlines fleet deployment across United States multi-site operators.
- Machine Learning:Algorithmic anomaly detection for brush wear and solution flow optimization supports outcome-based service contracting.
- RFID Integration:Proximity-based location tracking enables zone-restricted operation in secured healthcare and aviation facilities.
LiDAR navigation anchors the volume base while computer vision gains share at the steepest rate.
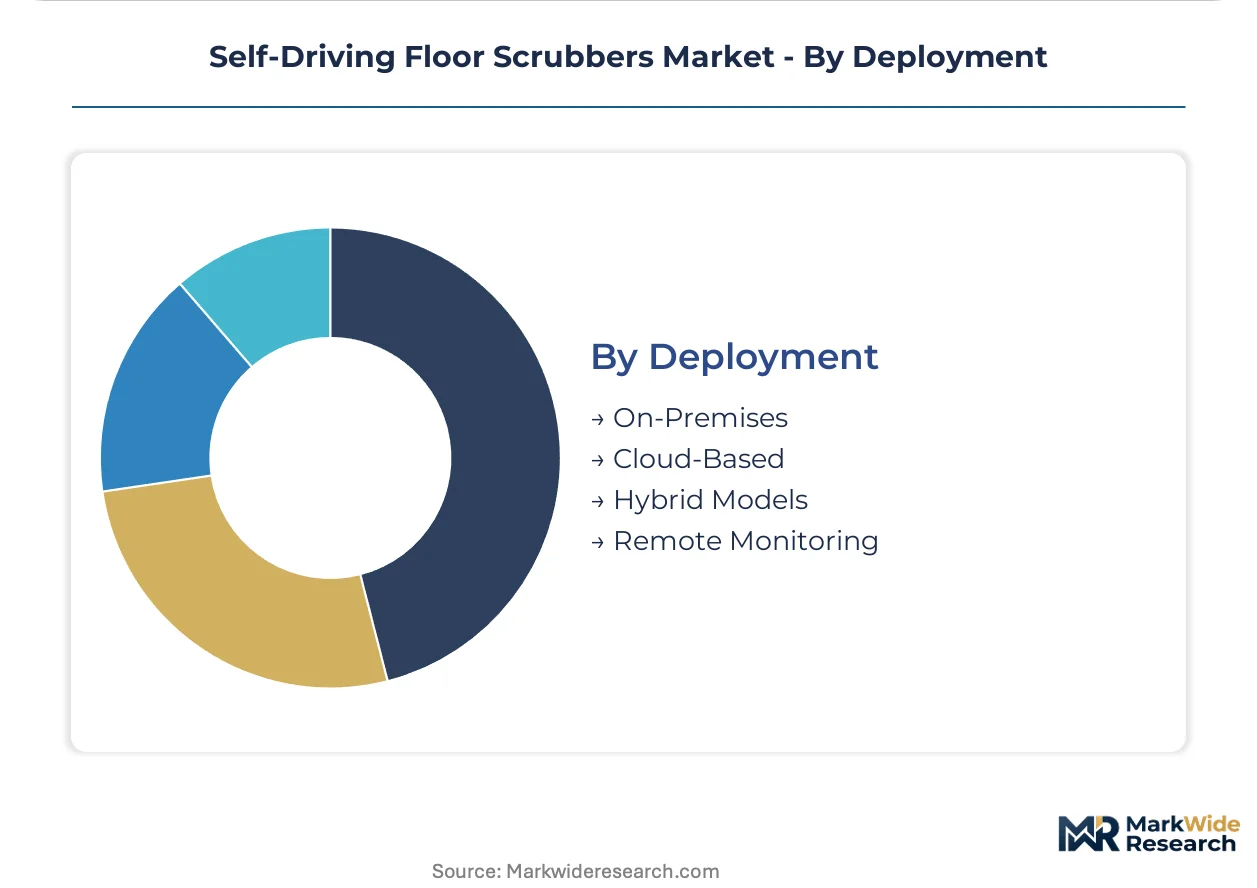
Deployment:
Customer type segmentation separates capital-purchasing facility owners from operational-expense-focused managed service providers.
- On-Premises:Local server-based fleet management with air-gapped security protocols serves defense contractors and critical infrastructure operators in Virginia and Maryland. NIST cybersecurity framework compliance drives architecture selection.
- Cloud-Based:Centralized software-as-a-service platforms with over-the-air update capability capture recurring revenue from United States retail chains with 50-plus locations. Data sovereignty concerns limit European adoption.
- Hybrid Models:Split processing between edge units and cloud analytics balances latency requirements with computational intensity.
- Remote Monitoring:Third-party operations centers in Texas and Arizona handle exception management and predictive intervention.
On-premises deployment anchors the volume base while cloud-based models gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export autonomous scrubber platforms to United States distribution networks, while Chinese component suppliers feed sensor modules into European assembly lines. Trade corridors between East Asian optical component clusters and North American OEMs define input cost structures.
United States
Ohio and Pennsylvania warehouse operators validate fleet deployment through labor displacement metrics. OSHA General Industry Standards mandate emergency stop systems and machine guarding for human-robot collaboration zones. Dallas-Fort Worth airport terminals demand 24/7 operational capability with minimal downtime.
Germany
CE machinery directive compliance drives specification rigor among industrial facility operators. The EU AI Act risk classification system triggers third-party auditing requirements for high-risk autonomous equipment. Bavarian manufacturing plants prioritize SLAM-based navigation platforms with embedded explainability features.
China
Shanghai and Shenzhen retail complexes favor compact form factors for escalator navigation in mixed-use developments. GB standards and MIIT regulations govern wireless telemetry module certification for fleet-managed units. Yangtze River Delta component suppliers concentrate LiDAR optical manufacturing capacity.
Japan
Tokyo healthcare facilities pursue infection control certification through autonomous cleaning protocols. METI industrial standards influence predictive maintenance algorithm validation requirements. Kansai region logistics operators test hybrid vision-LiDAR systems in constrained retail environments.
India
Maharashtra shopping mall developers create first-mover positioning for compact autonomous scrubber vendors. BIS certification requirements streamline equipment import procedures for organized retail expansion. Karnataka technology corridors attract SLAM algorithm engineering talent for localization development.
Self-Driving Floor Scrubbers Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base separates into software licensors, equipment OEMs, and integrated hardware-software providers. Three archetypes dominate: AI platform licensors, industrial-grade fabricators, and compact-form-factor specialists. Competitive moves concentrate on technology licensing partnerships and geographic manufacturing footprint expansion.
Within the AI platform tier, Brain Corp and Gaussian Robotics exemplify divergent geographic anchoring strategies. Alfred Kärcher SE & Co. KG occupies a position among European industrial-grade fabricators with manufacturing concentration in Germany. iRobot Corporation represents North American consumer-robotics lineage applied to commercial sanitation applications.
| Leading Market Players |
|---|
| iRobot Corporation |
| Alfred Kärcher SE & Co. KG |
| Nilfisk Group |
| Avidbots Corp. |
| Brain Corp |
| Gaussian Robotics |
| VIGGO |
| Ecovacs Robotics |
| Tennant Company |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Yangtze River Delta LiDAR optical manufacturing is compressing component pricing while forcing suppliers toward long-term equipment-as-a-service contracts with North American OEMs. This utilization dynamic rewards vendors with captive fleet-management platforms and squeezes pure hardware manufacturers into margin-deteriorating spot market exposure.
Pricing Analysis
Cost-plus contracts with semiconductor price indexation dominate procurement between East Asian sensor suppliers and European equipment fabricators. Three-tier pricing structure across premium CE-marked industrial units, standard FCC-authorized retail configurations, and economy-grade fixed-path scrubbers separates certification-grade buyers from price-sensitive facility management contractors. Pricing pressure stems from sensor fusion cost declines eroding single-sensor competitive moats. Third-party logistics operators exhibit highest price sensitivity due to labor arbitrage-driven procurement committees, while healthcare facilities demonstrate lowest sensitivity given Joint Commission accreditation requirements.
Supply Chain Analysis
Export control restrictions on advanced optical components limit flows from specialized East Asian manufacturers to European assembly lines. Supply concentrates in China for LiDAR optical modules, Germany for precision brush agitation mechanisms, and the United States for edge computing chipsets. Raw material dependencies span rare-earth optical substrates, high-torque electric motor assemblies, and EPA-registered disinfectant formulations. Single-source vulnerability in Yangtze River Delta component manufacturing creates procurement lead time uncertainty. Distribution runs through third-party fleet management platforms capturing recurring software update and predictive maintenance revenue.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where predictive maintenance and fleet analytics subscriptions expand faster than hardware unit sales. Vendors capturing software licensing revenue streams achieve superior lifetime value economics compared to capital-equipment pure-plays.
For Market Incumbents: Insulate core positioning through backward integration into LiDAR optical component manufacturing and captive development of SLAM algorithm talent pools in Karnataka technology corridors. Emerging AI software licensors threaten premium positioning through platform licensing to multiple equipment OEMs. Certification investment in EU AI Act conformity assessment procedures represents the critical defensive lever against liability exposure.
For New Entrants and Emerging Players: Maharashtra shopping mall development creates first-mover positioning for compact form factor vendors with BIS certification readiness. White-space targets include India organized retail expansion and European mid-market grocery chains adopting hybrid vision-LiDAR systems. Equipment-as-a-service contracting with embedded fleet analytics offers the most penetrable go-to-market angle against capital-purchase incumbents.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among AI platform licensors with embedded software licensing terms spanning multi-year fleet deployment cycles. Long-term viability favors vendors with vertical integration into sensor manufacturing and established third-party fleet management relationships. The signal to watch is OSHA General Industry Standards harmonization accelerating machine certification requirements and consolidating vendor positioning around compliance capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Platform Integration | Hybrid vision-LiDAR configurations compress price-performance thresholds for mid-market retail adoption. |
| CE Machinery Directive Certification | EU AI Act conformity assessment unlocks cross-border fleet standardization in European public spaces. |
| Equipment-as-a-Service Launch | Recurring revenue models displace capital purchases among multi-site United States logistics operators. |
| Predictive Maintenance Development | Machine learning anomaly detection enables outcome-based contracting with healthcare infection control mandates. |
| Geographic Manufacturing Footprint | European fabrication anchors premium industrial-grade positioning against Asian compact-form-factor competition. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and equipment certification databases. Interviews with facility management contractors, hospital procurement committees, OEM engineering directors, and aftermarket service heads inform demand-side validation. Secondary sources include FCC equipment authorization records, OSHA General Industry Standards documentation, EU AI Act technical specifications, and CE machinery directive conformity assessment procedures. Bottom-up unit deployment tracking and top-down fleet revenue analysis provide triangulation across the analysis window.
Forecast inputs span product type segmentation across robotic scrubbers and AI-powered configurations, technology architecture differentiation between LiDAR and computer vision systems, and deployment model variation from on-premises to cloud-based fleet management. End-user segmentation incorporates warehouse labor displacement economics, healthcare infection control certification requirements, and retail space constraints. CAGRs derive from installed base replacement cycles, sensor cost decline trajectories, and regulatory compliance timeline acceleration. Edge computing performance gains and FCC equipment authorization streamlining represent key industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by AI platform licensors or unexpected OSHA mandate acceleration would shift outcomes. Material shifts in LiDAR sensor supply concentration, EU AI Act liability framework evolution, or equipment-as-a-service contracting penetration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
India Cloud Robotics Market
Robotics and Automation
Rehabilitation Robot Gloves Market
Robotics and Automation
Service Robotics Market
Robotics and Automation
LAMEA Waste Sorting Robots Market
Robotics and Automation
Global Machine Vision and Vision Guided Robotics Market
Robotics and Automation
North America Automated Liquid Handling Market
Robotics and Automation
Mobile Robotics Software Market
Robotics and Automation
Africa Agricultural Robots and Mechatronics Market
Robotics and Automation
South America Agricultural Robots and Mechatronics Market
Robotics and Automation
Asia-Pacific Robotics Technology Market
Robotics and Automation
Nanorobots in Healthcare Market
Robotics and Automation
Japan Articulated Robot Market
Robotics and Automation
Robotic Coffee Bars Market
Robotics and Automation
Autonomous Mobile Manipulator Robots (AMMR) Market
Robotics and Automation
Construction Robotics Market
Robotics and Automation
Inspection Robots Market