
 Global Exoskeleton Market | 2026-2036
Global Exoskeleton Market Size, Share, and Industry Trends Forecast 2026-2036
Global Exoskeleton Market Analysis
Modular exoskeleton platforms that separate the drive unit from the limb attachments is expanding buyer choice across healthcare and industrial segments. Ekso Bionics leverages a rehabilitation-focused product architecture that dominates North American hospital networks. Ottobock sustains its position through orthotics heritage and channel control in European prosthetics markets. CYBERDYNE Inc. anchors its competitive stance with a regulatory-first approach to powered medical devices in Japan.
Exoskeletons are wearable robotic structures that combine electromechanical actuators, sensor arrays, and control algorithms to augment, restore, or enhance human locomotion and load-bearing capacity. These systems typically incorporate torque-limiting joints, inertial measurement units, and force-sensitive resistors to enable real-time gait adaptation for rehabilitation or occupational safety. Active exoskeletons with powered hip and knee drives capture the dominant share of clinical revenue, while soft exosuit variants represent the fastest-expanding segment for logistics and construction applications. Passive systems occupy a mature niche in spinal support, where margin pools concentrate on durable medical equipment reimbursement pathways.
The FDA regulates exoskeletons as Class II medical devices under 510(k) or de novo pathways, while the EU Medical Device Regulation mandates notified body conformity assessment for CE marking in Europe. ISO 13485 quality management and IEC 60601 electrical safety standards shape design verification protocols and market access timelines across jurisdictions. Stakeholders must monitor reimbursement coding decisions by national health technology assessment bodies, as these determinations will dictate which exoskeleton categories achieve sustainable volume deployment in clinical settings.
Market Dynamics
Powered hip-knee actuation systems are compressing rehabilitation timelines and forcing reimbursement authorities to recalibrate episode-based payment models for neurorecovery.
Growth Catalysts
- FDA Breakthrough Device Designation:Expedited clinical trial pathways in the United States accelerate powered gait systems from bench to bedside.
- ISO 13485 Certification Momentum:Quality management standardization reduces design verification cycles and opens hospital procurement channels across Germany and Japan.
- Spinal Cord Injury Prevalence:Trauma centers in South Korea are expanding dedicated neurorehabilitation wards with integrated exoskeleton protocols.
Market Restraints
- Actuator Cost Concentration:Rare-earth magnet supply from Chinese processors creates input price volatility for torque-dense motor assemblies.
- Battery Energy Density Limits:Lithium-ion cell chemistry constraints restrict continuous ambulation duration below clinical session thresholds.
- EU MDR Conformity Burden:Notified body capacity bottlenecks extend CE marking timelines for novel wearable robotics.
Strategic Opportunities
- Soft Exosuit Logistics Penetration:Warehouse operators in the United States are piloting textile-based lifting assistance for order fulfillment roles.
- Construction Load-Bearing Applications:Japanese contractors are testing passive spinal support systems for aging skilled trades workforces.
- India PLI Medical Device Incentive:Production-linked subsidy schemes attract component manufacturing for cost-optimized rehabilitation platforms.
Industry Challenges
- Biomechanical Calibration Talent Scarcity:Shortage of gait analysts capable of tuning sensor thresholds to individual patient kinematics.
- IEC 60601 Electrical Safety Certification:Isolation testing for wearable power electronics extends pre-market validation schedules.
- Legacy EMR Integration Complexity:Proprietary data formats from established hospital information systems obstruct real-time therapy outcome capture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Exoskeleton Market |
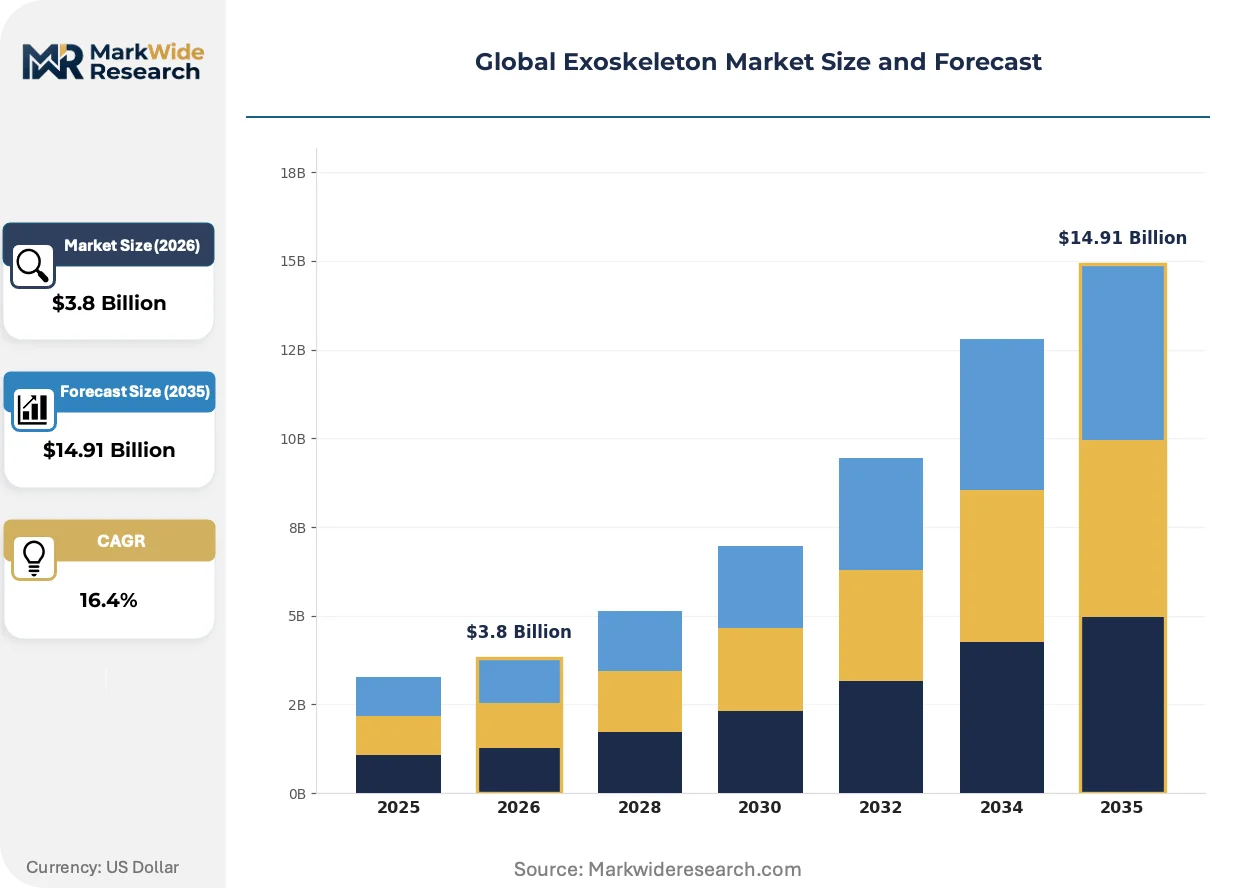
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active, Passive, Soft, Rigid End User: Healthcare, Industrial, Military, Sports Technology: Wearable, Robotics, Sensors, Control Systems Application: Rehabilitation, Mobility Assistance, Load Carrying, Exertion Reduction |
| Companies Covered | Ekso Bionics, Ottobock, ReWalk Robotics, CYBERDYNE Inc., Lockheed Martin Corporation, Rex Bionics Plc., Hocoma, DIH Medical, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Exoskeleton Market Emerging Trajectories
Real-time kinematic sensing is compressing the gap between assistive torque delivery and patient-initiated movement intention, reshaping how clinicians prescribe robotic gait training.
Machine learning-driven gait prediction is converging with powered exoskeleton control architectures. Rehabilitation hospitals in Germany are deploying adaptive torque modulation that anticipates hemiparetic stride initiation. This convergence is compressing the therapist-to-patient ratio required for safe ambulation sessions.
Japan's PMDA has established a dedicated review pathway for wearable medical robots with autonomous balance correction. Manufacturers must demonstrate fall-prevention algorithm reliability through standardized perturbation testing. European competitors are adapting submission dossiers to mirror these evidentiary requirements.
Hospital procurement committees are unbundling device acquisition from maintenance contracts and therapist training packages. North American health systems now source hardware through capital equipment budgets while negotiating software updates and clinical education separately. This bifurcation is most pronounced in academic medical centers with established biomedical engineering departments.
Global Exoskeleton Market Segmentation
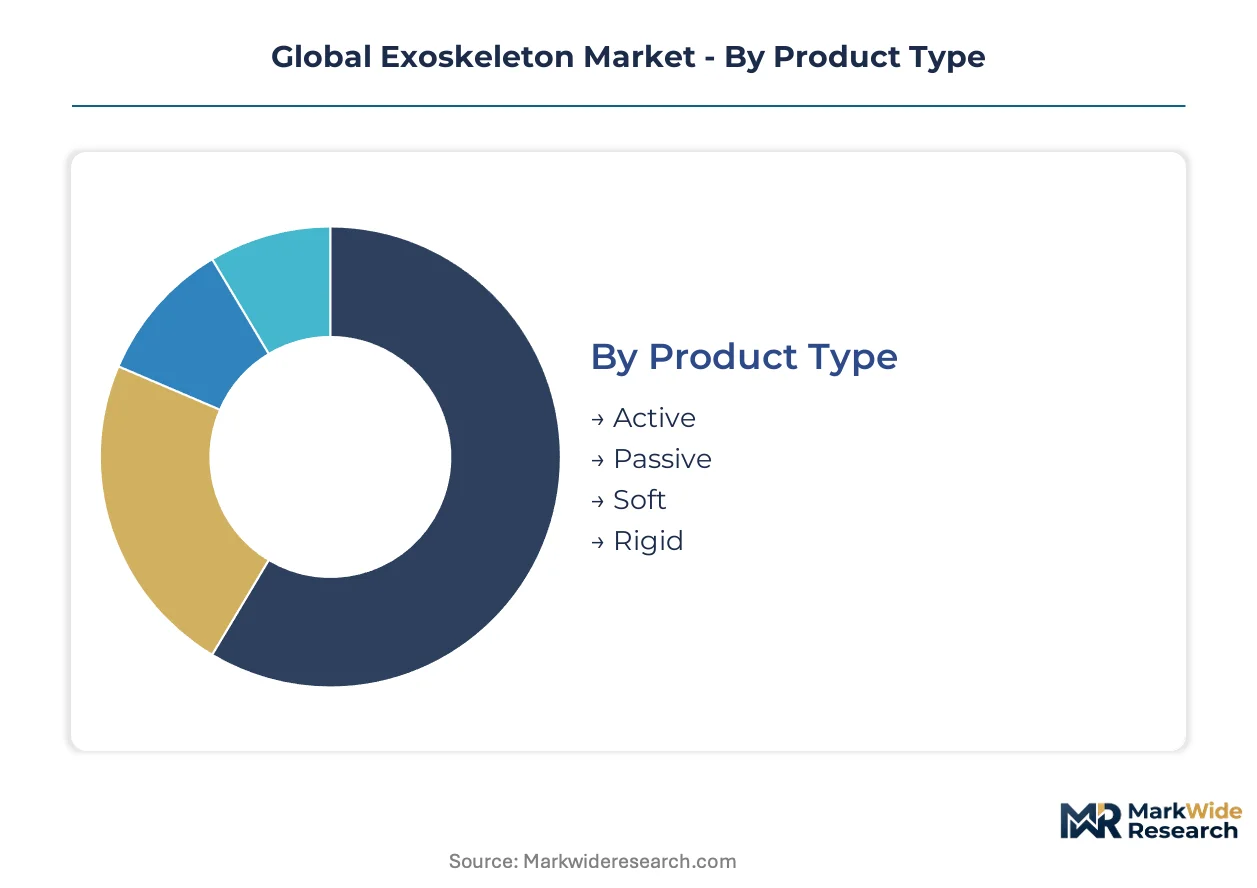
Segmentation in the exoskeleton market reveals how power delivery mechanisms, user environments, and control architectures create distinct procurement channels and reimbursement pathways. Understanding these divisions exposes where hardware margins concentrate versus where software and service revenue accumulates.
Product Type:
Power delivery architecture determines unit economics, battery dependency, and maintenance cadence across deployment scenarios.
- Active:Electromechanical actuators with powered hip and knee joints deliver torque-augmented gait assistance for spinal cord injury rehabilitation. Demand clusters in United States trauma centers and German university hospitals where FDA breakthrough and EU MDR pathways have cleared reimbursement.
- Passive:Spring-loaded and gravity-compensating frames redistribute load without external power, serving construction sites in Japan and logistics hubs in South Korea where battery logistics complicate shift-based operations.
- Soft:Textile-based exosuits employ cable-driven actuation and elastic elements to reduce muscle fatigue during repetitive lifting. Warehouse operators in the United States are piloting these systems for aging workforces in e-commerce fulfillment.
- Rigid:Structural frames with mechanical linkages provide postural support for industrial assembly lines, favored in Chinese manufacturing zones where durability outweighs flexibility requirements.
Active systems lead on scale in clinical revenue; soft variants lead on momentum in logistics trials.
End User:
Procurement authority and budget source vary sharply across institutional buyers, dictating sales cycle length and contract structure.
- Healthcare:Hospital rehabilitation departments and outpatient neurorecovery clinics purchase through capital equipment budgets with bundled training contracts. Japanese long-term care insurers now reimburse rental models for home-based stroke recovery.
- Industrial:Manufacturing and logistics employers acquire through occupational safety budgets, amortizing costs against workers' compensation reductions. German automotive plants are standardizing passive lumbar support for assembly stations.
- Military:Defense procurement offices fund load-carriage systems for infantry and logistics units, with South Korea's DAPA accelerating field trials for mountainous terrain operations.
- Sports:Elite athletic training facilities and rehabilitation clinics for professional teams represent a nascent segment with direct-to-institution sales models.
Healthcare dominates installed base; industrial buyers are expanding fastest as safety ROI documentation matures.
Technology:
Control and sensing layers determine responsiveness, calibration complexity, and integration with legacy hospital information systems.
- Wearable:Garment-integrated form factors prioritize comfort and donning speed for all-day industrial use, with Chinese manufacturers optimizing for cost-sensitive healthcare access programs.
- Robotics:Articulated limb mechanisms with position and force feedback enable autonomous balance correction, requiring PMDA-style perturbation testing for Japanese market entry.
- Sensors:Inertial measurement units, surface electromyography, and force-sensitive resistors capture kinematic and intent data, with German clinics demanding ISO 13485-compliant calibration protocols.
- Control Systems:Machine learning gait prediction and adaptive torque modulation software layers are unbundling from hardware in North American academic medical center procurement.
Robotics anchors premium pricing; control systems are gaining share fastest as software separates from device sales.
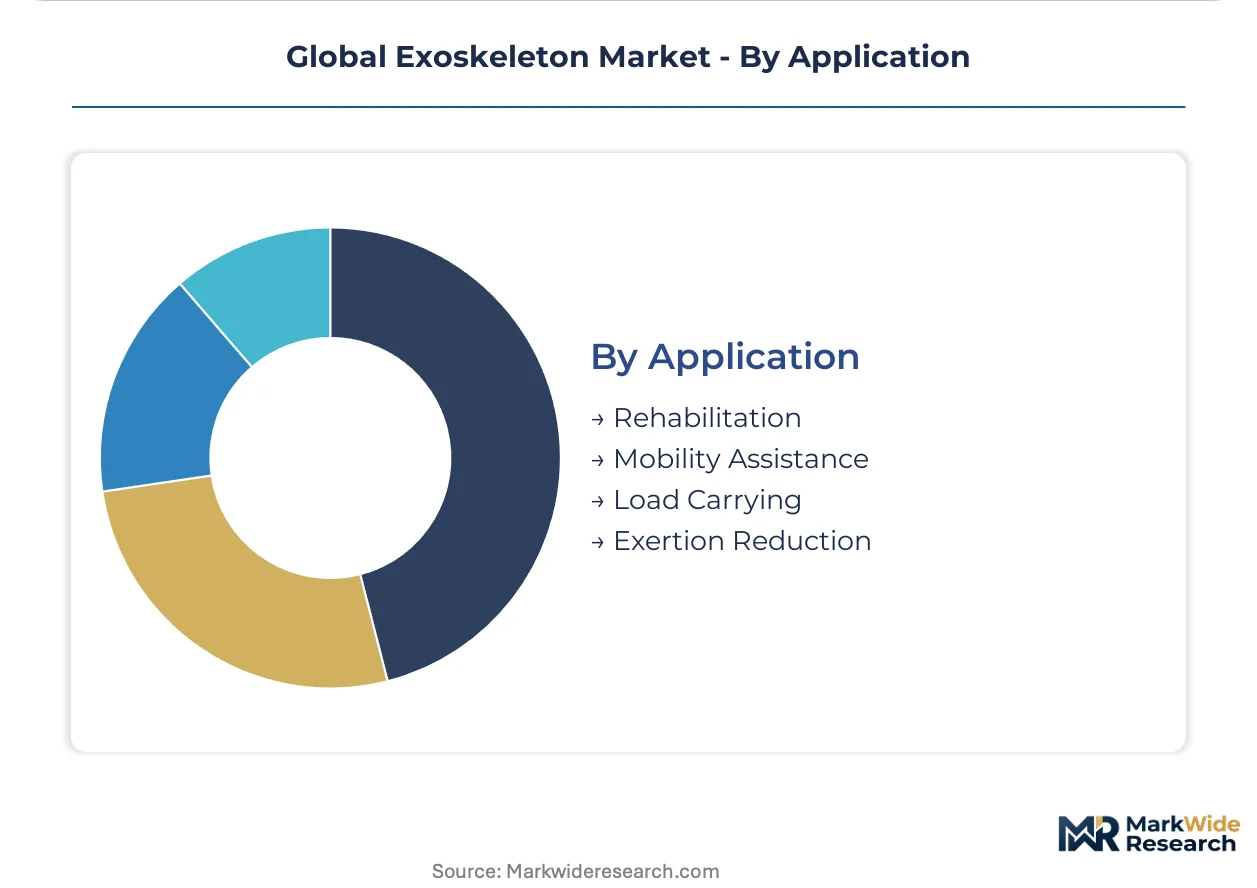
Application:
Clinical outcome metrics and reimbursement coding tie directly to intended use case, shaping regulatory submission strategies.
- Rehabilitation:Neuroplasticity-driven gait training for stroke and spinal cord injury patients, reimbursed through episode-based payment models in United States Medicare Advantage plans.
- Mobility Assistance:Daily ambulation support for degenerative conditions, with Japanese municipal governments subsidizing home rental programs for elderly residents.
- Load Carrying:Weight distribution for military rucksacks and construction materials, tested by Japanese contractors for aging skilled trades demographics.
- Exertion Reduction:Muscle fatigue mitigation for repetitive material handling, piloted by United States e-commerce operators in high-turnover fulfillment roles.
Rehabilitation commands highest unit prices; exertion reduction is climbing fastest as logistics employers quantify retention savings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The exoskeleton industry traces its commercial origins to Japanese robotics laboratories and German rehabilitation engineering centers, with early powered gait systems emerging from university hospital partnerships in the 2000s before spreading to trauma centers across North America and East Asia.
United States
FDA breakthrough device designations accelerate clinical trial timelines for powered gait systems, compressing bench-to-bedside development cycles. Medicare Advantage plans in multiple states now reimburse episode-based neurorehabilitation protocols. Academic medical centers in Boston and Pittsburgh unbundle hardware procurement from software licensing and therapist training contracts.
Germany
University hospitals in Heidelberg and Berlin scale procurement of powered hip-knee systems for stroke rehabilitation wards. ISO 13485 certification requirements shape design verification protocols for European market entry. The KBA and notified bodies under EU MDR extend CE marking timelines, creating compliance bottlenecks for novel wearable robotics.
Japan
PMDA-established review pathways for autonomous balance correction accelerate regulatory clearance for fall-prevention algorithms. Municipal governments subsidize home rental programs for elderly stroke recovery patients in Osaka and Nagoya. CYBERDYNE Inc. anchors competitive positioning through regulatory-first submission strategies.
South Korea
DAPA accelerates field trials for load-carriage systems in mountainous terrain operations. Trauma centers in Seoul expand dedicated neurorehabilitation wards with integrated exoskeleton protocols. MFDS alignment with international electrical safety standards streamlines pre-market validation for domestic manufacturers.
China
NMPA medical device classification pathways accommodate powered rehabilitation robotics under Class II and III review tracks. Manufacturing zones in Shenzhen and Suzhou optimize rigid-frame industrial exoskeletons for durability-focused assembly line applications. MIIT standards development for wearable robotics shapes domestic procurement specifications.
Global Exoskeleton Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification intensity and reimbursement access dimensions. The vendor base clusters around three strategic archetypes: rehabilitation-focused platform developers, industrial safety equipment diversifiers, and defense contractors adapting load-carriage systems. Dominant competitive moves include strategic partnerships with hospital procurement networks and technology licensing for soft exosuit textile integration.
Within the rehabilitation-focused tier, Ekso Bionics and ReWalk Robotics exemplify platform developers pursuing FDA-cleared clinical pathways. Ottobock GmbH occupies a position bridging European orthotics heritage with powered device integration. CYBERDYNE Inc. anchors the regulatory-first archetype through PMDA-aligned submission strategies. Lockheed Martin Corporation represents defense-sector adaptation of load-bearing exoskeleton architectures for military logistics applications.
| Leading Market Players |
|---|
| Ekso Bionics |
| Ottobock |
| ReWalk Robotics |
| CYBERDYNE Inc. |
| Lockheed Martin Corporation |
| Rex Bionics Plc. |
| Hocoma |
| DIH Medical |
| Panasonic Corporation |
| Others |
Supply Flow & Price Mechanics
Captive integration into rare-earth magnet processing anchors both cost position and pricing power for powered exoskeleton manufacturers. Chinese processors control torque-dense motor assembly inputs, while FDA-cleared systems in the United States command premium positioning through breakthrough device designation pathways.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared rehabilitation platforms from CE-marked clinical systems and unbranded industrial passive frames. Price differentiation rests on certification grade and after-sales service bundling, with ISO 13485 compliance commanding substantial uplifts. Cost compression in economy-tier passive systems is intensifying because Chinese manufacturers are scaling rigid-frame production for construction applications. Hospital procurement committees in Germany exhibit lowest price sensitivity, while warehouse operators in the United States prioritize per-unit acquisition cost over service contracts.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and South Korea feed hospital procurement networks through hub-and-spoke patterns calibrated to capital equipment budget cycles. Manufacturing concentrates in China for actuators and structural components, Germany for precision drive assemblies, and Japan for sensor integration. Raw material dependencies include neodymium-iron-boron magnets, lithium-ion cells, and high-torque servo motors. Single-source vulnerability in rare-earth processing creates exposure to export restriction shocks. Distribution runs through authorized medical device distributors with ISO 13485-certified service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Exoskeleton Market reads as a late-cycle quality story. Rehabilitation demand is shifting toward autonomous balance correction and predictive gait modulation specifications that favor certified platform developers.
For Market Incumbents: Extend software unbundling strategies to capture recurring revenue from academic medical centers in Boston and Pittsburgh. Fortify actuator supply through backward integration into magnet sourcing or long-term offtake agreements with Chinese processors. The threat of soft exosuit substitutes in logistics applications demands preemptive certification investment in textile-drive architectures. For New Entrants and Emerging Players: Municipal home rental programs in Japanese prefectures represent an underserved buyer archetype with subsidized procurement pathways. Target construction safety managers in aging Japanese skilled trades demographics with passive spinal support systems. Partner with occupational health clinics for direct-to-employer pilot programs bypassing traditional hospital sales cycles. For Investors and Strategic Acquirers: Roll-up economics work for control-system software specialists because hospital procurement committees are separating hardware from algorithm licensing. Platform-rollup viability extends across the medium-term horizon for vendors with PMDA-aligned fall-prevention validation. Target acquisition archetypes include gait prediction algorithm developers and ISO 13485-certified calibration service providers. The signal to watch is reimbursement coding decisions by Medicare Advantage plans in additional states.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Expedited clinical trial timelines compress bench-to-bedside development for powered gait systems in United States trauma centers. |
| PMDA Autonomous Balance Review | Dedicated regulatory pathway in Japan accelerates market entry for fall-prevention algorithm reliability demonstrations. |
| ISO 13485 Certification Investment | Quality management standardization opens hospital procurement channels across German university hospital networks. |
| Software Unbundling Strategy | Separate hardware acquisition from control system licensing captures recurring revenue in North American academic medical centers. |
| Soft Exosuit Textile Partnership | Collaboration with apparel manufacturers enables logistics penetration for warehouse operator fatigue reduction programs. |
Methodological Framework
Bottom-up rehabilitation ward deployment modeling reconciled against top-down actuator manufacturing tracking forms the analytical core of this study. Primary interviews with hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and occupational health safety officers combined with secondary validation from FDA 510(k) filings, PMDA approval databases, hospital procurement records, and ISO 13485 certification registries. Triangulation across stakeholder inputs and regulatory documentation ensured cross-verification of volume assumptions.
Input-output matrix framing connects unit-level exoskeleton procurement to national health technology assessment reimbursement decisions. Segmentation dimensions modeled include power delivery architecture, end-user procurement authority, control system technology, and intended clinical application across the projection horizon. CAGRs were derived from installed base growth trajectories and replacement cycle analysis. Forecast inputs incorporate battery energy density evolution timelines and rare-earth magnet price volatility assumptions.
Inputs from regulatory filing databases and hospital procurement systems were available through the study window; gaps in real-time therapy outcome capture from legacy EMR integration introduce uncertainty bands around clinical adoption velocity. Forecasts reflect documented assumptions regarding reimbursement expansion timelines and certification pathway durations. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Global Robot Teach Pendant Market
Robotics and Automation
Underwater Robot Market
Robotics and Automation
SLAM Robots Market
Robotics and Automation
Top Robotics Market
Robotics and Automation
Latin America Warehouse Robotics Market
Robotics and Automation
Medical Service Robots Market
Robotics and Automation
Medical Robotics Market
Robotics and Automation
Robotic Waste Sorting System Market
Robotics and Automation
Global Rescue Robot Market
Robotics and Automation
Cleanroom Robots in Healthcare Market
Robotics and Automation
Global Adaptive Robotics Market
Robotics and Automation
GCC AUV Market
Robotics and Automation
North America Data Center Robotics Market
Robotics and Automation
Security and Law Enforcement Robot Market
Robotics and Automation
Robotics for NDT Market
Robotics and Automation
Autonomous Drilling Robots Market