
 Underwater Jetpack Market | 2026-2036
Underwater Jetpack Market Size, Share, and Industry Trends Forecast 2026-2036
Underwater Jetpack Market Analytics
Florida's marine technology corridor is rewriting competitive dynamics for underwater propulsion hardware. CudaJet leverages its coastal engineering base to dominate recreational channel distribution. Zapata Racing sustains technology leadership through sustained R&D in jet propulsion architectures. Sublue anchors Asian market presence with manufacturing scale across Shenzhen and Zhuhai facilities.
An underwater jetpack is a wearable thrust device utilizing sealed electric motors or hydraulic pumps to generate vectored water propulsion, typically operating at depths up to 40 meters with battery durations of 30–120 minutes depending on power configuration. The equipment serves commercial divers, military trainees, and recreational users requiring hands-free mobility in submerged environments. Propulsion systems capture the dominant margin pool due to sealed motor complexity and thermal management requirements. Electric drive technology leads unit shipments while hybrid configurations attract professional diver segments demanding extended runtime. Water sports applications show the fastest end-use expansion as resort operators integrate guided jetpack experiences into premium activity portfolios.
Maritime safety regulators in the United States, European Union, and China enforce diver-equipment standards that shape battery enclosure specifications and depth-rating certifications. The U.S. Coast Guard and EU's CE marking framework impose electromagnetic compatibility and pressure-testing protocols that extend product development cycles. China's GB standards and MIIT directives govern lithium-ion transport and underwater electronics export compliance. Stakeholders must monitor evolving battery chemistry regulations and depth-certification reciprocity agreements across target deployment jurisdictions.
Market Dynamics
Maritime battery safety mandates from the U.S. Coast Guard and EU's CE marking framework are compressing product development timelines while forcing sealed motor and thermal management redesigns across all manufacturer tiers.
Growth Catalysts
- Luxury marine tourism expansion:Resort operators in the Maldives and Caribbean are integrating guided underwater jetpack experiences into premium activity portfolios, creating dedicated procurement channels for electric-drive units.
- REACH and RoHS compliance convergence:EU chemical and electronics regulations are standardizing battery enclosure materials and pressure-testing protocols, reducing certification fragmentation for export-oriented manufacturers.
- Sealed electric motor advancement:Improvements in submersible motor efficiency and thermal dissipation are extending operational depths and runtimes, opening military training and commercial diver segments.
Market Restraints
- Lithium-ion cell cost volatility:Battery chemistry price swings constrain margin stability for electric-drive manufacturers dependent on imported cell supplies.
- Pressure-testing facility concentration:Depth-rating certification capacity clusters in Germany and China, creating bottlenecks for new product validation.
- Hydraulic system substitution:Professional diver segments retain preference for hydraulic propulsion in extended-runtime applications, limiting electric unit penetration.
Strategic Opportunities
- Southeast Asian coastal resort zones:Underpenetrated demand in Thailand, Vietnam, and Indonesia offers first-mover positioning for experience-based rental fleet deployment.
- EU Green Deal maritime decarbonization incentives:Subsidies for zero-emission marine equipment accelerate electric-drive adoption in European commercial diving operations.
- AI-assisted buoyancy control convergence:Integration of machine learning with vectored thrust systems enables autonomous depth maintenance, attracting technical training institutes.
Industry Challenges
- Subsea electronics technician scarcity:Specialized skills for sealed motor repair and pressure-hull maintenance outpace vocational training program output.
- CE marking reciprocity delays:Divergent depth-certification standards between EU member states and third-country recognition agreements extend market entry timelines.
- Battery thermal runaway containment:Maritime regulator demands for fail-safe enclosure designs drive R&D capex intensity without immediate volume offset.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Underwater Jetpack Market |
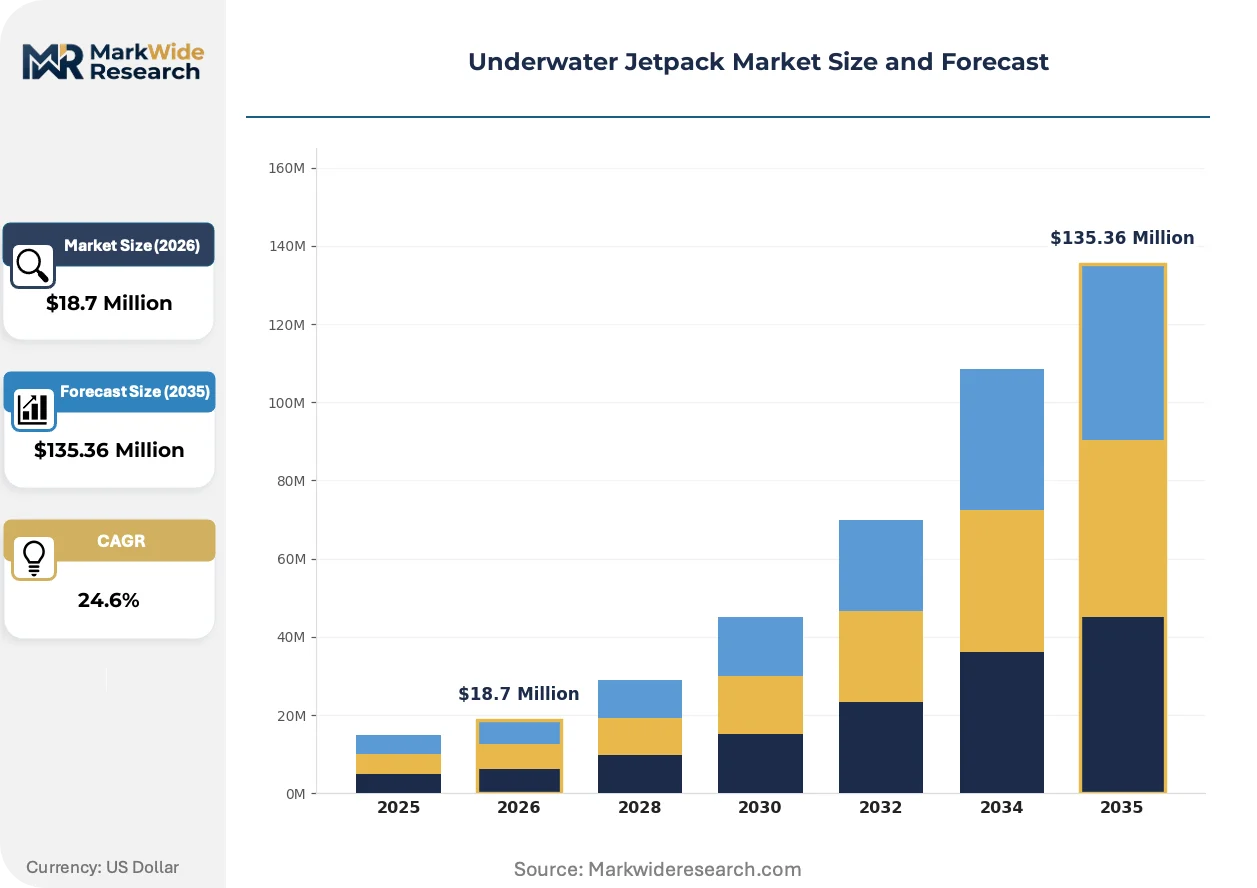
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $135.36 Million |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Propulsion Systems, Safety Gear, Control Mechanisms, Power Supplies End User: Recreational Users, Professional Divers, Emergency Services, Military Technology: Electric Drive, Hydraulic, Hybrid, Jet Propulsion Application: Water Sports, Underwater Exploration, Rescue Operations, Military Training |
| Companies Covered | CudaJet, Jetpack Aviation, Zapata Racing, SUEX, Seabob, Yamaha Motor Co., Ltd., X-Jetpacks, Gravity Industries, Sublue, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Underwater Jetpack Market Evolving Landscape
Digital integration across propulsion control systems and predictive maintenance platforms is redefining product architecture, while regulatory pressure on battery safety and resort-driven experience commercialization reshape competitive requirements.
Closed-loop motor control with integrated pressure sensors is digitizing thrust vectoring precision for depth-hold and obstacle-avoidance functions. Military training centers and technical diving institutes are adopting these systems at accelerated procurement cycles. The technology is digitizing operational safety margins while compressing instructor-to-trainee ratios in certification programs.
China's GB standards and MIIT directives on lithium-ion transport and underwater electronics exports are tightening cell packaging and electromagnetic compatibility requirements. Manufacturers must redesign battery management systems to satisfy dual compliance with Chinese export rules and destination-market maritime safety codes. Asian production facilities face the steepest adaptation costs as these rules phase in.
Resort operators are unbundling equipment ownership from experience delivery, preferring lease-to-operate models with embedded maintenance and certification refresh. Traditional distributor channels lose volume to direct manufacturer partnerships with marine tourism conglomerates. Thailand's integrated resort developments demonstrate this shift most visibly, with procurement decisions consolidating under hospitality procurement divisions rather than marine equipment specialists.
Underwater Jetpack Market Segmentation
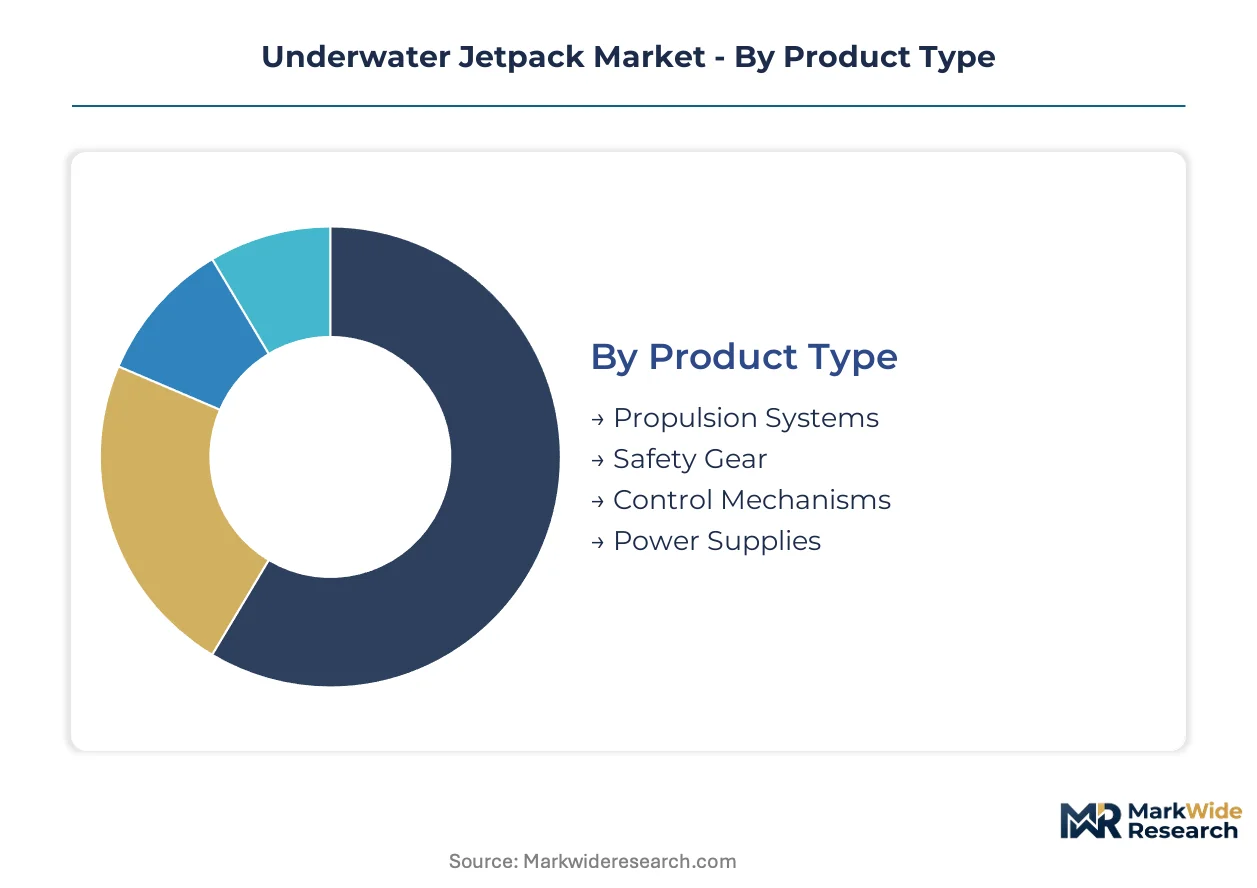
Segmentation reveals divergent procurement rhythms across the underwater jetpack market. Product refresh cycles, certification burdens, and end-use intensity create stark differences in replacement velocity and margin capture.
Product Type:
Propulsion systems turn over slowest due to sealed motor longevity, while safety gear cycles fastest from wear-and-tear exposure and regulatory recertification mandates.
- Propulsion Systems:Sealed electric motors and hydraulic pump assemblies constitute the core thrust generation hardware. Demand concentrates in professional diver and military training segments where depth ratings and thermal management specifications command premium positioning. The Maldives and Caribbean resort operators prioritize electric-drive units for guest experience consistency.
- Safety Gear:Buoyancy compensators, harness systems, and emergency ascent devices require frequent replacement from saltwater degradation. Southeast Asian coastal resorts drive volume through rapid fleet turnover in high-utilization rental operations.
- Control Mechanisms:Handheld or body-mounted throttle interfaces with pressure-rated electronic housings.
- Power Supplies:Battery packs and fuel cells with maritime-certified enclosures.
Propulsion systems anchor the volume base while safety gear gains share at the steepest rate.
End User:
Cost tiers separate hobbyist price sensitivity from institutional procurement discipline and mission-critical reliability premiums.
- Recreational Users:Individual purchasers and resort guests seeking guided underwater mobility experiences. Demand clusters in Thailand's integrated resort developments where hospitality procurement divisions consolidate fleet acquisition decisions.
- Professional Divers:Commercial operators requiring extended runtime and certified depth performance. EU Green Deal maritime decarbonization subsidies accelerate electric-drive adoption in European commercial diving operations.
- Emergency Services:First responder units deploying rapid underwater search and recovery capabilities.
- Military:Defense training centers procuring closed-loop motor control systems for depth-hold and obstacle-avoidance instruction.
Recreational users anchor the volume base while professional divers gain share at the steepest rate.
Technology:
Application requirements dictate technology selection, with runtime demands and depth specifications driving divergent adoption patterns.
- Electric Drive:Battery-powered sealed motors dominating unit shipments across recreational and commercial segments. China's GB standards and MIIT directives on lithium-ion transport force battery management system redesigns for export compliance.
- Hydraulic:Pump-driven systems retaining preference in professional extended-runtime applications where battery thermal constraints limit electric alternatives.
- Hybrid:Combined electric-hydraulic configurations for mission-flexible military training deployments.
- Jet Propulsion:Impeller-based thrust architectures from sustained R&D investment in vectored water propulsion.
Electric drive anchors the volume base while hybrid configurations gain share at the steepest rate.
Application:
Customer type and utilization intensity separate experience-based rental models from operational deployment in structured environments.
- Water Sports:Resort-integrated guided experiences and individual recreational activity. Thailand, Vietnam, and Indonesia coastal zones offer first-mover positioning for experience-based rental fleet deployment.
- Underwater Exploration:Scientific and recreational depth exploration requiring autonomous buoyancy maintenance. Technical diving institutes adopt AI-assisted depth control systems at accelerated procurement cycles.
- Rescue Operations:Emergency response deployment for submerged casualty extraction.
- Military Training:Structured diver certification programs compressing instructor-to-trainee ratios through digitized safety margins.
Water sports anchors the volume base while military training gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The U.S. Coast Guard's battery safety mandates anchor North American demand, while EU decarbonization subsidies and Asian manufacturing scale reshape procurement geography across three continents.
United States
Florida's marine technology corridor drives recreational channel procurement, with Miami-Dade and Broward County operators consolidating fleet acquisition under hospitality procurement divisions. The U.S. Coast Guard enforces electromagnetic compatibility and pressure-testing protocols that extend product development cycles for sealed motor redesigns. Tampa-St. Petersburg anchors Gulf Coast distribution, where coastal engineering bases support maintenance and certification refresh services.
Germany
Professional diver segments in the North Sea and Baltic coastal zones prioritize extended-runtime hydraulic configurations for commercial operations. REACH and RoHS compliance convergence standardizes battery enclosure materials, reducing certification fragmentation for export-oriented manufacturers. Pressure-testing facility concentration in Hamburg and Bremen creates validation bottlenecks that favor established suppliers with existing certification relationships.
China
Shenzhen and Zhuhai manufacturing facilities capture electric-drive unit production scale, serving Southeast Asian resort procurement channels. GB standards and MIIT directives on lithium-ion transport force battery management system redesigns for dual compliance with export rules and destination-market maritime safety codes. Yangtze River Delta production clusters face steepest adaptation costs as phased regulatory requirements tighten cell packaging specifications.
Thailand
Integrated resort developments in Phuket and Krabi demonstrate unbundled equipment ownership models, with lease-to-operate structures embedding maintenance and certification refresh. Underpenetrated coastal zones in Vietnam and Indonesia offer first-mover positioning for experience-based rental fleet deployment. Bangkok-based hospitality procurement divisions consolidate volume decisions previously fragmented across marine equipment specialists.
Maldives
Luxury marine tourism operators prioritize electric-drive units for guided guest experience consistency across atoll resort clusters. Resort-driven experience commercialization reshapes competitive requirements, with direct manufacturer partnerships displacing traditional distributor channels. Malé-based logistics hubs coordinate Indian Ocean fleet deployment and rapid replacement part availability.
Underwater Jetpack Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another, producing a bifurcated structure where sealed motor engineering expertise separates premium positioning from volume manufacturing. The vendor base organizes around coastal engineering proximity, Asian production scale, and sustained R&D investment in jet propulsion architectures. Three archetypes dominate: Florida-based recreational channel specialists, Chinese manufacturing-scale operators, and European professional-grade equipment fabricators. Competitive moves concentrate on direct resort partnership formation and battery thermal management R&D capex acceleration.
Within the coastal engineering tier, CudaJet leverages Florida infrastructure for recreational distribution dominance. Zapata Racing exemplifies sustained technology leadership investment in vectored thrust architectures. Sublue anchors Asian market presence through Shenzhen and Zhuhai manufacturing scale. These three occupy positions across the capability-scale spectrum, representing geographic specialization rather than direct segment overlap.
| Leading Market Players |
|---|
| CudaJet |
| Jetpack Aviation |
| Zapata Racing |
| SUEX |
| Seabob |
| Yamaha Motor Co., Ltd. |
| X-Jetpacks |
| Gravity Industries |
| Sublue |
| Others |
Value Network & Pricing Analysis
Overcapacity in Shenzhen and Zhuhai manufacturing clusters compresses supplier margins while forcing Florida-based distributors to absorb freight premiums for sealed motor assemblies, tightening pricing discipline across both production and procurement tiers.
Pricing Analysis
Geographic price spreads between Chinese-manufactured electric-drive units and European-certified hydraulic systems exceed three-to-one ratios, with certification grade and battery thermal management specifications driving differentiation. Three-tier pricing structure across premium CE-marked, standard export-grade, and economy resort-rental levels separates procurement channels. Pricing pressure stems from lithium-ion cell cost volatility imported from Yangtze River Delta suppliers. Recreational resort operators exhibit highest price sensitivity, while military training centers prioritize performance premiums over unit economics.
Supply Chain Analysis
Tariff exposure between China and United States trade corridors dominates supply chain risk profiles for battery management system components and sealed motor housings. Manufacturing concentrates in China, Germany, and Florida, with raw material dependencies on rare-earth magnets, pressure-rated aluminum alloys, and maritime-certified lithium-ion cells. Single-source vulnerability in Hamburg and Bremen pressure-testing facilities creates validation bottlenecks for depth-rating certifications. Distribution runs through direct manufacturer partnerships with hospitality procurement divisions, displacing traditional marine equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market faces substitution defense against surface-based hydroflight equipment and autonomous underwater vehicles, requiring incumbents to deepen experience-based differentiation and runtime performance advantages.
For Market Incumbents: Insulate proprietary sealed motor architectures through captive thermal management R&D and exclusive resort partnership lockups. Accelerate certification refresh services to raise switching costs for lease-to-operate fleet operators. Hydraulic system substitution in professional diver segments demands electric-drive runtime extension to defend share. For New Entrants and Emerging Players: Vietnam's coastal resort zones offer first-mover positioning for experience-based rental fleet deployment with minimal incumbent saturation. Target integrated hospitality procurement divisions in Indonesia's developing atoll destinations with lease-to-operate structures embedding maintenance and Malé-based logistics support. White-space capture favors direct manufacturer partnerships over distributor channel fragmentation. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among coastal engineering specialists with captive certification refresh services and resort fleet management contracts. Long-term viability across the projection horizon favors acquisition targets with dual compliance capabilities for China's GB standards and EU CE marking frameworks. Battery thermal runaway containment R&D capex intensity serves as inflection indicator for sustainable margin structures.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Resort Partnership Formation | Consolidates procurement decisions under hospitality divisions, bypassing marine equipment distributors in Thailand and Maldives clusters. |
| Battery Thermal Management R&D Acceleration | Addresses U.S. Coast Guard and EU maritime safety mandates while extending electric-drive runtime for professional diver penetration. |
| Pressure-Testing Facility Investment | Reduces Hamburg and Bremen validation bottlenecks, compressing product development cycles for new depth-rated sealed motor designs. |
| Lease-to-Operate Model Expansion | Captures recurring revenue streams through embedded maintenance and certification refresh services in Southeast Asian coastal zones. |
| Dual Compliance System Architecture | Enables simultaneous satisfaction of China's MIIT lithium-ion directives and destination-market maritime safety codes for export flexibility. |
Research Methodology
Desk research of maritime safety regulatory filings, customs trade databases, and resort operator procurement disclosures preceded structured interviews with sealed motor engineering directors, hospitality procurement managers, and commercial diving equipment specialists. Primary fieldwork with Florida marine technology corridor operators and Shenzhen manufacturing facility managers combined with secondary validation against EU CE marking framework documentation and U.S. Coast Guard enforcement bulletins. Bottom-up unit shipment estimates triangulated against top-down tourism expenditure models across the analysis window.
Fixed assumptions held battery chemistry cost trajectories and maritime regulatory reciprocity timelines constant while varying resort fleet penetration rates and military training procurement cycles across segmentation dimensions of propulsion technology, end-user category, and geographic deployment cluster. CAGRs derived from logistic diffusion curves fitted to early-adopter resort operator data and professional diver replacement velocity patterns. Industry-specific inputs included pressure-testing facility capacity utilization and lithium-ion cell import dependency ratios.
Practitioners should monitor battery thermal runaway incident reports and CE marking reciprocity negotiation progress for early signals of forecast revision triggers. Forecasts reflect documented assumptions regarding sealed motor efficiency improvement curves and resort tourism recovery trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Global Robotic Process Automation in Healthcare Market
Robotics and Automation
Robot for Public Service Market
Robotics and Automation
Case and Box Handling Robots Market
Robotics and Automation
Global Mobile Robots Market
Robotics and Automation
Global Robotics Parking System Market
Robotics and Automation
Data Center Robotics Market
Robotics and Automation
Global Adaptive Robotics Market
Robotics and Automation
Painting Robot Market
Robotics and Automation
Household Robots Market
Robotics and Automation
Healthcare Mobile Robots Market
Robotics and Automation
Wearable Robotic Exoskeleton Market
Robotics and Automation
Global Medical Robotic Systems Market
Robotics and Automation
Mobile Cobots Market
Robotics and Automation
Pipetting Robots Market
Robotics and Automation
Robotic Process Automation (RPA) Market
Robotics and Automation
Mobile Robotics Market