
 Ethylene-Vinyl Acetate [EVA] Infusion Bags Market | 2026-2036
Ethylene-Vinyl Acetate [EVA] Infusion Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Ethylene-Vinyl Acetate [EVA] Infusion Bags Market Foresight
Buyer concentration across hospital procurement groups is expanding as integrated delivery networks consolidate purchasing power across multi-facility systems. Baxter International leverages its global manufacturing footprint to sustain supply agreements with these consolidated buyers. Fresenius Kabi anchors its position through specialized parenteral nutrition portfolios that lock in multi-year hospital contracts. B. Braun Melsungen AG competes on sterilization technology leadership, differentiating its EVA bag systems through closed-system transfer device compatibility.
Ethylene-vinyl acetate infusion bags are flexible polymer containers manufactured with vinyl acetate content typically ranging from 9% to 40%, extruded into multi-layer films that combine pliability with chemical inertness for sterile fluid storage and intravenous delivery. Multi-chamber bags command premium positioning by enabling admixture separation until point-of-use activation, a feature critical for unstable nutritional and chemotherapy formulations. Single-chamber bags dominate volume throughput in fluid resuscitation and standard electrolyte replacement, where cost efficiency and supply security outweigh advanced functionality requirements.
The FDA enforces container closure integrity standards under 21 CFR 211 while the EU MDR mandates clinical evidence for polymer migration profiles in extended-contact medical devices, directly shaping R&D allocation and compliance timelines for manufacturers. ISO 15747 sets international benchmarks for plastic containers for intravenous injections, creating a baseline that national regulators reference or exceed. Stakeholders must monitor evolving pharmacopeial extractables testing protocols and position their material qualification pipelines to preempt rather than react to tightened polymer purity thresholds.
Market Dynamics
Consolidated hospital procurement networks are compressing vendor margins while demanding container closure integrity documentation that exceeds current pharmacopeial standards, forcing manufacturers to accelerate material qualification timelines and sterilization validation investments.
Growth Catalysts
- Ambulatory infusion therapy expansion:Germany, the United States, and Japan are extending reimbursement coverage for home-based parenteral nutrition and chemotherapy administration, directly expanding addressable demand for portable EVA bag systems.
- EU MDR migration profile requirements:The regulation's clinical evidence mandates for polymer leachables are elevating entry barriers for non-compliant suppliers, creating protected market space for qualified incumbents with pre-submitted technical files.
- Multi-chamber activation technology:Point-of-use mixing systems for unstable oncology and nutritional formulations command premium positioning and lock in multi-year supply agreements with specialized compounding pharmacies.
Market Restraints
- Ethylene and vinyl acetate monomer volatility:Feedstock price swings compress margin predictability for film extruders operating on fixed-price hospital contracts with annual renegotiation windows.
- South Korean and Chinese film supplier concentration:Dependence on a narrow base of Asian polymer converters creates single-source vulnerability for European and North American bag assemblers.
- Glass and cyclic olefin copolymer substitution:Premium parenteral applications with extreme thermal cycling requirements continue specifying non-polymer containers despite EVA's flexibility advantages.
Strategic Opportunities
- India's hospital infrastructure buildout:The country's PLI scheme for medical devices and expanding tertiary care network create first-mover positioning for EVA bag suppliers establishing local sterilization partnerships.
- Closed-system transfer device convergence:Integration with automated compounding workflows and robotic filling lines opens new specification channels in oncology pharmacy automation.
- Japan's aging-in-place policy framework:METI-directed home care subsidies for infusion therapy are accelerating demand for lightweight, disposable containers with extended hang-time stability.
Industry Challenges
- Extractables testing protocol complexity:Evolving USP and EP compendial methods for polymer characterization extend new product qualification timelines by 18-24 months.
- Gamma sterilization capacity constraints:Cobalt-60 source availability and facility certification backlogs bottleneck scale-up for multi-chamber bag launches.
- Legacy enterprise resource planning integration:Hospital IDN procurement platforms demand real-time lot traceability data that legacy manufacturing execution systems cannot natively transmit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethylene-Vinyl Acetate [EVA] Infusion Bags Market |
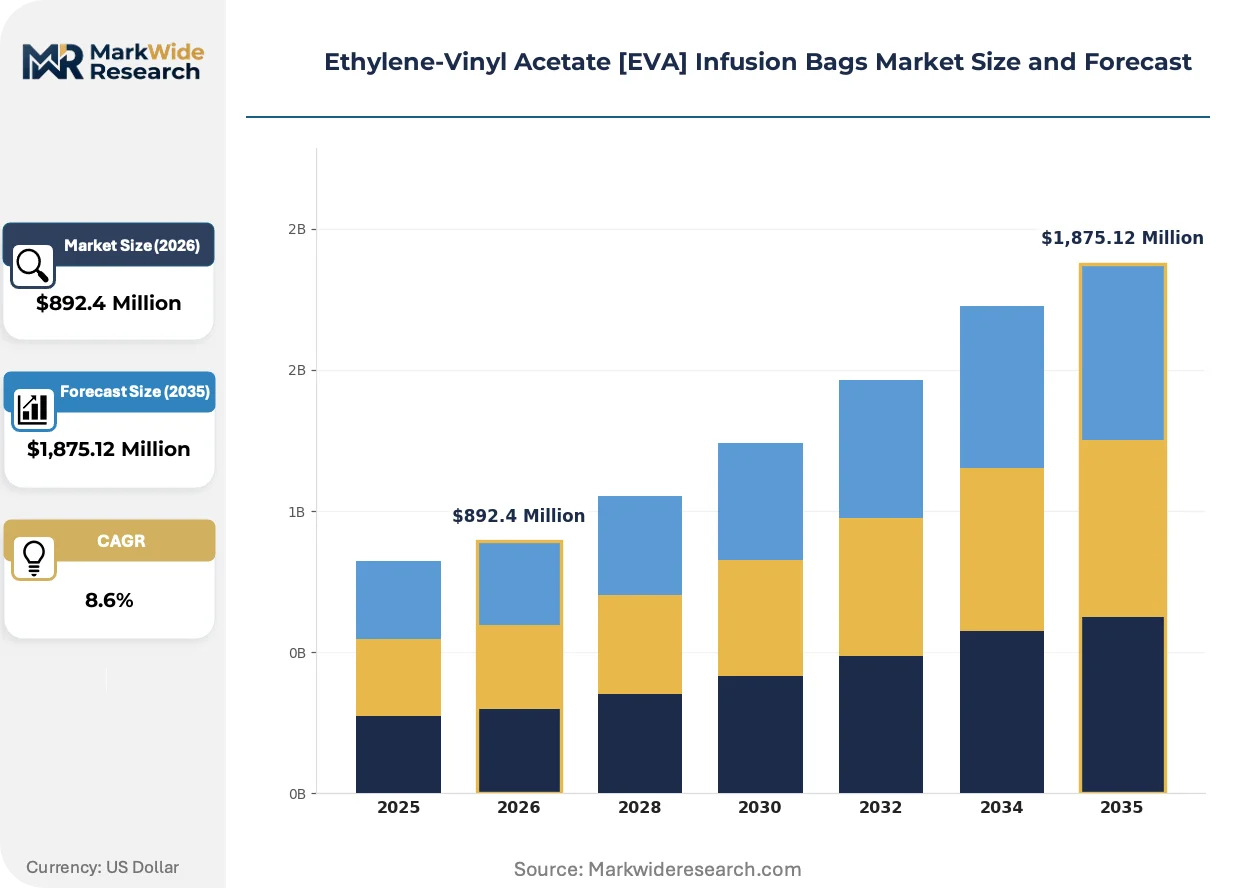
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $1,875.12 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Chamber Bags, Multi-Chamber Bags, Custom-Shaped Bags, Pediatric Bags Application: Fluid Delivery, Nutritional Support, Chemotherapy, Blood Transfusion End User: Hospitals, Clinics, Home Care, Ambulatory Surgery Centers Packaging Type: Sterile Packaging, Non-Sterile Packaging, Bulk Packaging, Individual Packaging |
| Companies Covered | Baxter International, Inc., ICU Medical, Inc., Fresenius Kabi AG, B. Braun Melsungen AG, Technoflex, The Metrix Company, McKesson Medical-Surgical, Inc., AdvaCare Pharma, Valmed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethylene-Vinyl Acetate [EVA] Infusion Bags Market Shifts & Advancements
Material science advances and regulatory data requirements are converging to reshape product architecture, with multi-layer film engineering and digital traceability systems emerging as the primary vectors of competitive differentiation.
Co-extruded barrier films incorporating ethylene-vinyl alcohol interlayers are integrating oxygen and moisture ingress protection that extends admixture stability from 7 to 30 days. Oncology compounding centers in Germany and the United States are adopting these systems fastest, replacing single-layer EVA for high-value biologic infusions. The technology is integrating cold-chain distribution networks previously reserved for glass vial formats, compressing the historical polymer-versus-glass performance gap.
REACH Annex XVII restrictions on phthalate plasticizers and the EU MDR's emphasis on substance migration documentation are compelling reformulation of legacy EVA compounds. Manufacturers with pre-2021 technical files face retrospective testing obligations that consume 15-20% of R&D budgets. Pediatric and neonatal nutrition segments are most affected, driving accelerated substitution of alternative plasticizers with toxicological profiles acceptable to ECHA.
Hospital procurement groups are consolidating supplier panels and mandating consolidated invoicing across multi-facility systems. Integrated delivery networks in the United States now specify direct-to-warehouse distribution with vendor-managed inventory, displacing traditional distributor intermediaries. This concentration is most visible in the Southeast and Midwest IDN clusters, where three-to-five-year sole-source agreements are replacing annual competitive bidding cycles.
Ethylene-Vinyl Acetate [EVA] Infusion Bags Market Segmentation
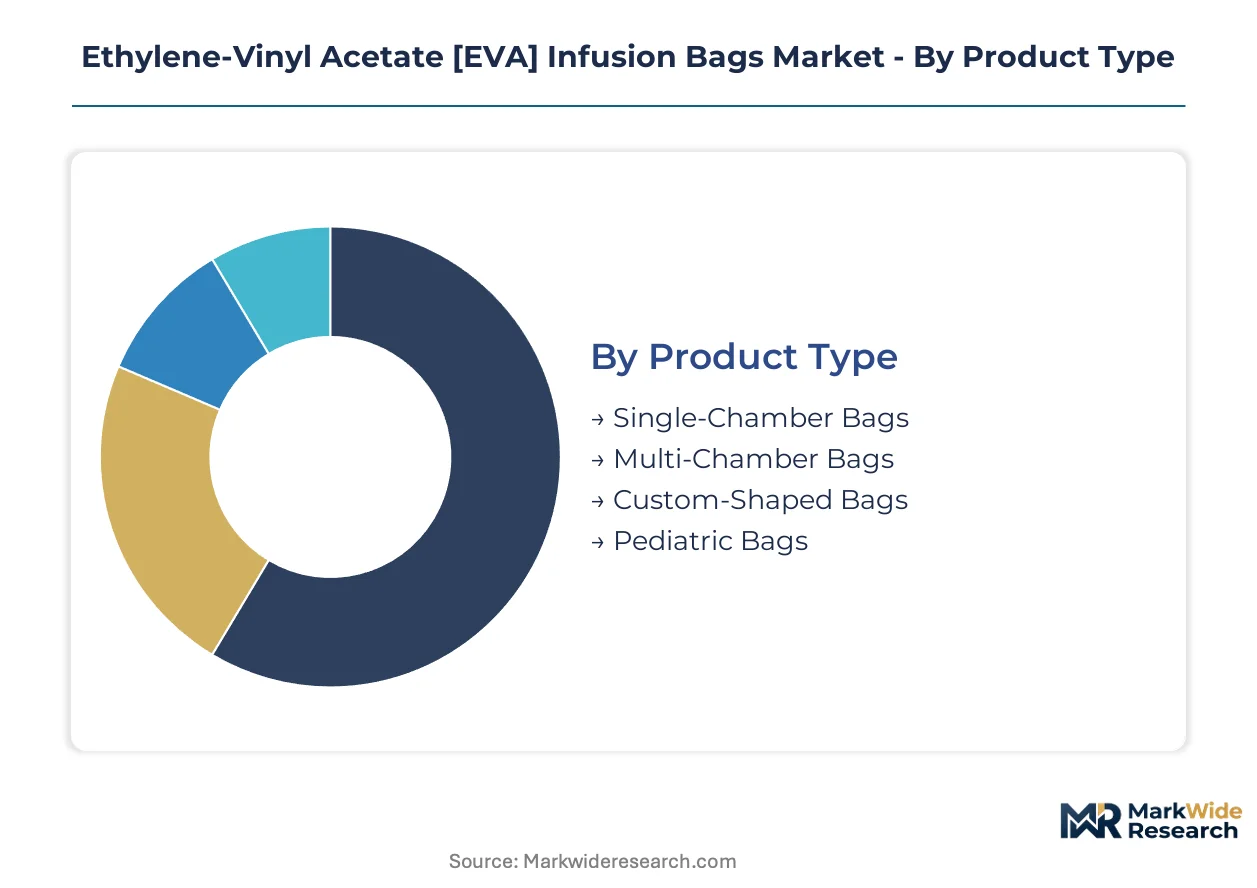
Segmentation in the EVA infusion bag market directly shapes regulatory qualification burdens and sterilization validation costs. Manufacturers must align product architectures with specific end-use requirements, as chemotherapy and parenteral nutrition applications trigger distinct migration testing protocols under FDA and EMA guidelines.
Product Type:
FDA 21 CFR 211 container closure integrity standards and EU MDR polymer migration documentation requirements apply differentially across chamber configurations, with multi-chamber systems demanding extended extractables validation timelines.
- Single-Chamber Bags:Standard unibody construction dominates fluid resuscitation and electrolyte replacement protocols across German and US hospital systems. Demand concentrates in emergency medicine departments where cost efficiency and supply security override advanced functionality requirements, though gamma sterilization capacity constraints periodically disrupt scale-up.
- Multi-Chamber Bags:Separated compartments enable point-of-use admixture activation for unstable nutritional and oncology formulations. German compounding pharmacies and US oncology centers are adopting these systems fastest, locking in multi-year supply agreements despite premium positioning and 18-24 month qualification timelines.
- Custom-Shaped Bags:Specialized geometries for robotic filling lines and automated compounding workflows.
- Pediatric Bags:Reduced-volume formats subject to REACH Annex XVII phthalate restrictions and retrospective ECHA toxicological reviews.
Single-chamber bags sit at the top of the volume ranking, with multi-chamber bags climbing the fastest.
Application:
Cost tier differentiation separates commodity fluid delivery from premium oncology and biologic infusion segments, with reimbursement codes directly influencing specification intensity.
- Fluid Delivery:Volume workhorse applications including crystalloid resuscitation and hydration therapy. US integrated delivery networks and Japanese tertiary hospitals drive procurement consolidation here, squeezing margins through multi-facility sole-source agreements.
- Nutritional Support:Parenteral nutrition formulations requiring oxygen-barrier protection and extended hang-time stability. METI-directed home care subsidies in Japan and expanded German ambulatory reimbursement are accelerating portable system demand.
- Chemotherapy:Closed-system transfer device compatibility and cytotoxic handling protocols command specification premiums.
- Blood Transfusion:Specialized compatibility testing for erythrocyte and platelet storage.
Fluid delivery captures the largest revenue base, while nutritional support gains share fastest on home infusion expansion.
End User:
Customer type determines distribution channel configuration and inventory management requirements, with hospital IDNs imposing vendor-managed inventory systems that displace traditional distributor intermediaries.
- Hospitals:Consolidated procurement networks across US Southeast and Midwest IDN clusters now mandate direct-to-warehouse distribution with real-time lot traceability. Three-to-five-year sole-source agreements are replacing annual competitive bidding cycles, compressing vendor panels to qualified incumbents with pre-submitted FDA technical files.
- Home Care:Lightweight disposable containers with extended stability are expanding fastest in Germany, the United States, and Japan as ambulatory reimbursement frameworks mature. India's PLI scheme for medical devices is creating first-mover positioning for suppliers establishing local sterilization partnerships.
- Clinics:Mid-volume purchasers with standardized formulary requirements.
- Ambulatory Surgery Centers:Same-day discharge protocols driving demand for pre-mixed, ready-to-hang systems.
Hospitals anchor procurement volume, with home care expanding most quickly on aging-in-place policy frameworks.
Packaging Type:
Supply concentration in gamma sterilization infrastructure shapes packaging configuration availability, with cobalt-60 source bottlenecks limiting sterile format scale-up.
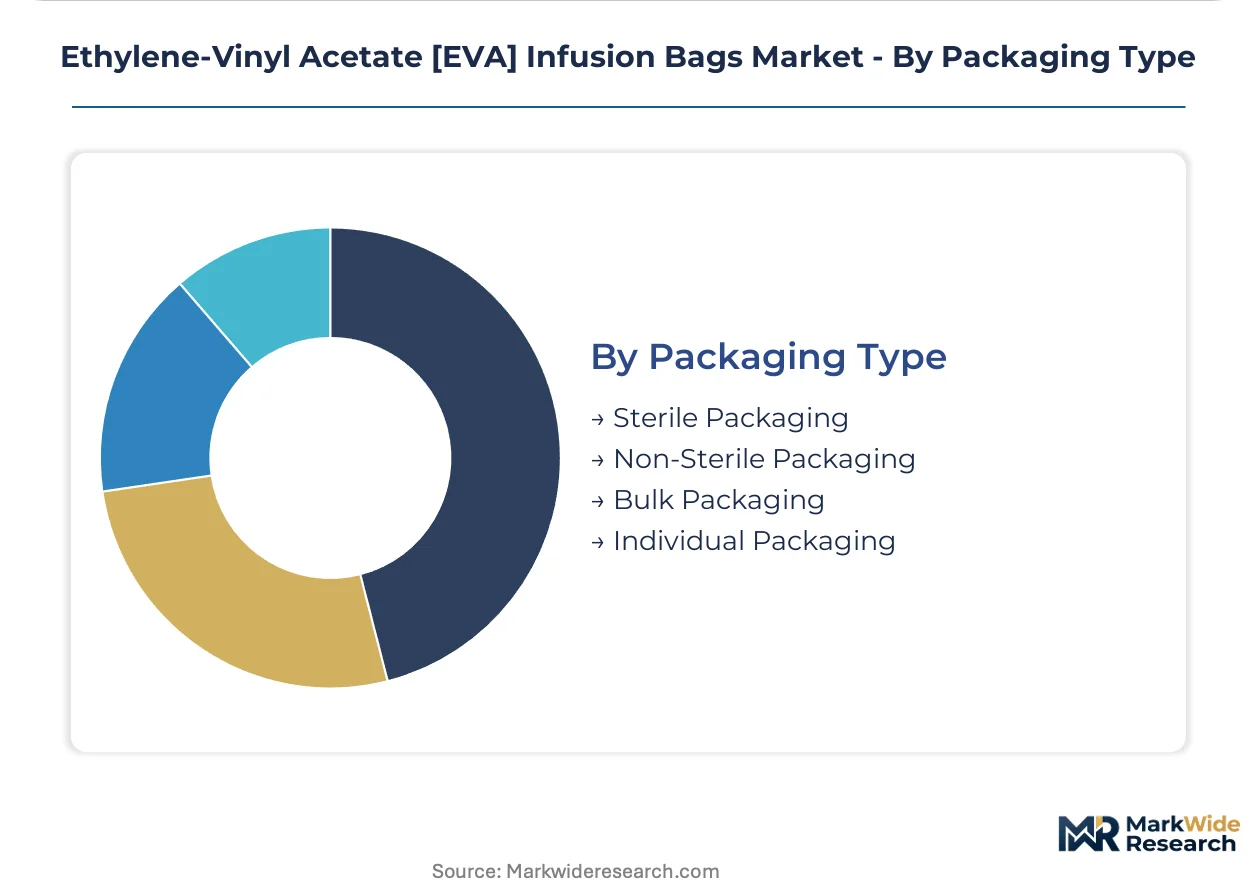
- Sterile Packaging:Terminal sterilization with cobalt-60 gamma irradiation or ethylene oxide for immediate clinical use. Capacity constraints at certified facilities are extending lead times for multi-chamber bag launches, favoring manufacturers with captive sterilization assets.
- Non-Sterile Packaging:Bulk formats for in-hospital compounding centers with internal sterilization capabilities. Cost-sensitive purchasers in India's expanding tertiary network are adopting these systems to bypass premium sterile finished goods pricing.
- Bulk Packaging:Multi-unit configurations for high-throughput automated filling lines.
- Individual Packaging:Unit-of-use formats for home infusion and ambulatory settings requiring portability.
Sterile packaging leads by revenue contribution, with non-sterile packaging gaining traction fastest in emerging market infrastructure buildouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's ambulatory reimbursement expansion contrasts with Japan's aging-in-place subsidy frameworks, yet both drive portable EVA bag demand through distinct policy mechanisms. The United States anchors procurement consolidation through integrated delivery networks, while India's infrastructure buildout creates emergent volume opportunities. Hospital procurement centralization and home care policy differentiation distinguish mature from developing market trajectories.
United States
Integrated delivery networks across the Southeast and Midwest now mandate vendor-managed inventory with direct-to-warehouse distribution, compressing supplier panels to qualified incumbents. FDA 21 CFR 211 container closure integrity standards exceed pharmacopeial baselines, forcing manufacturers to accelerate material qualification timelines. Three-to-five-year sole-source agreements in Texas and Florida IDN clusters are displacing annual competitive bidding cycles entirely.
Germany
Extended reimbursement coverage for home-based parenteral nutrition and chemotherapy administration expands addressable demand for portable systems. EU MDR polymer migration documentation requirements elevate entry barriers, creating protected market space for pre-qualified suppliers. Compounding pharmacies in Bavaria and North Rhine-Westphalia are adopting multi-chamber activation technology fastest, locking in multi-year supply agreements despite premium positioning.
Japan
METI-directed home care subsidies for infusion therapy accelerate demand for lightweight disposable containers with extended hang-time stability. PMDA clinical evidence requirements for extended-contact medical devices shape R&D allocation timelines for polymer-based containers. The Kanto region around Tokyo and the Kansai cluster surrounding Osaka concentrate procurement volume for aging-in-place program supplies.
India
The PLI scheme for medical devices and expanding tertiary care network create first-mover positioning for suppliers establishing local sterilization partnerships. CDSCO import substitution policies favor domestic manufacturing capacity for polymer-based medical containers. Maharashtra and Karnataka's hospital infrastructure buildout drives adoption of non-sterile bulk formats to bypass premium finished goods pricing.
China
NMPA tightening of biocompatibility standards for polymer-based medical containers extends new product qualification timelines. The country's national pharmaceutical regulator mandates clinical evidence for migration profiles that mirror EU MDR stringency. Yangtze River Delta medical device clusters are integrating captive film extrusion capacity to reduce dependence on South Korean polymer converters.
Ethylene-Vinyl Acetate [EVA] Infusion Bags Market Competitive Landscape
North American producers anchor one tier; European specialists hold differentiated positioning through sterilization technology leadership and parenteral nutrition portfolios. Market structure concentrates around three-to-five qualified incumbents with pre-submitted FDA and EMA technical files, while mid-scale fabricators compete on cost for non-sterile bulk formats. Strategic archetypes include diversified medical device conglomerates, specialized infusion therapy pure-plays, and regional contract manufacturers. Dominant competitive moves encompass captive sterilization asset acquisition and multi-year hospital contract lock-ins.
Among diversified medical device conglomerates, Baxter International, Fresenius Kabi AG, and B. Braun Melsungen AG occupy positions that exemplify distinct competitive vectors. Baxter represents the global manufacturing footprint archetype, sustaining supply agreements across consolidated procurement networks. Fresenius Kabi exemplifies specialized parenteral nutrition portfolio anchoring. B. Braun Melsungen AG sits within the sterilization technology leadership tier, differentiating through closed-system transfer device compatibility.
| Leading Market Players |
|---|
| Baxter International, Inc. |
| ICU Medical, Inc. |
| Fresenius Kabi AG |
| B. Braun Melsungen AG |
| Technoflex |
| The Metrix Company |
| McKesson Medical-Surgical, Inc. |
| AdvaCare Pharma |
| Valmed |
| Others |
Supply & Pricing Matrix
Multi-chamber certification tiers create a bifurcation between gamma-sterilized premium formats and non-sterile bulk configurations, with this divergence manifesting in both pricing power and supply chain geography. FDA and EU MDR compliance timelines lock qualified incumbents into premium positioning while India's PLI scheme and China's NMPA localization mandates reshape sourcing patterns for cost-sensitive tiers.
Pricing Analysis
Capacity additions in South Korea and China are reshaping price floors for film extrusion inputs, compressing margins for European and North American bag assemblers locked into fixed-price hospital contracts. Three-tier pricing structure across premium, standard, and economy levels separates gamma-sterilized multi-chamber systems from single-chamber formats and non-sterile bulk packaging. Pricing pressure stems from ethylene and vinyl acetate monomer volatility, with integrated delivery networks in the United States exhibiting highest price sensitivity and German compounding pharmacies least sensitive due to reimbursement premiums for closed-system compatibility.
Supply Chain Analysis
India's PLI scheme and China's NMPA biocompatibility mandates are reshaping sourcing toward domestic-content-qualified suppliers. South Korea, China, and Germany concentrate film extrusion and gamma sterilization infrastructure. Raw material dependencies center on ethylene feedstock, vinyl acetate monomer, and cobalt-60 irradiation capacity. Single-source vulnerability runs through South Korean polymer converters serving European assemblers. Distribution runs through direct-to-warehouse vendor-managed inventory systems mandated by United States integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where reimbursement expansion for home-based parenteral nutrition and chemotherapy administration shifts demand toward premium multi-chamber specifications with extended stability profiles.
For Market Incumbents: Extend sterilization technology leadership through captive gamma irradiation asset acquisition in Germany and the United States, locking in capacity ahead of cobalt-60 source bottlenecks. Deepen backward integration into ethylene-vinyl acetate film extrusion to defend margin position against South Korean and Chinese feedstock price volatility. Prioritize EU MDR technical file maintenance to preserve protected market space from retrospective migration testing obligations.
For New Entrants and Emerging Players: Capture India's hospital infrastructure buildout by establishing local sterilization partnerships under the PLI scheme for medical devices, bypassing premium finished goods pricing with non-sterile bulk formats. Target Maharashtra and Karnataka tertiary care networks as the most penetrable geography. Lead with cost-positioned single-chamber bags for fluid resuscitation protocols where supply security overrides advanced functionality requirements.
For Investors and Strategic Acquirers: Consolidation pressure builds where gamma sterilization capacity constraints and EU MDR compliance timelines create stranded asset risk for mid-scale fabricators without pre-submitted technical files. Long-term viability favors specialized infusion therapy pure-plays with parenteral nutrition portfolio anchoring and closed-system transfer device compatibility. Target acquisition archetype: regional contract manufacturers with captive sterilization assets in underserved emerging markets. Signal to watch: CDSCO import substitution policy enforcement accelerating domestic manufacturing mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| Gamma Sterilization Capacity Expansion | Captive cobalt-60 infrastructure locks in multi-chamber bag launch timelines ahead of competitor bottlenecks. |
| EU MDR Technical File Pre-Submission | Pre-qualified migration documentation creates protected market space from retrospective testing obligations. |
| Closed-System Transfer Device Integration | Oncology pharmacy automation compatibility commands specification premiums in German and United States compounding centers. |
| India PLI Scheme Localization | Domestic sterilization partnerships bypass import duties and accelerate tertiary care network penetration. |
| Multi-Layer Barrier Film Development | Ethylene-vinyl alcohol interlayers extend admixture stability from 7 to 30 days for high-value biologic infusions. |
Research Methodology
Bottom-up hospital and home care demand modeling reconciled against top-down film extrusion and sterilization capacity tracking forms the analytical core. Primary interviews with hospital procurement managers, GPO contracts directors, biomedical engineers, compounding pharmacy operators, and regulatory affairs leads at polymer converters were validated against FDA 510(k) filings, EMA device registrations, CDSCO import data, and ISO 15747 certification records. Triangulation across stakeholder inputs and secondary source verification ensures segmentation integrity.
Input-output matrices map ethylene-vinyl acetate resin throughput to finished bag production across single-chamber, multi-chamber, and pediatric formats. Modeled dimensions span chamber configuration, application type, end-user setting, and packaging sterilization status. CAGRs were derived from elasticity-adjusted demand projections across the analysis window, incorporating reimbursement policy trajectories in Germany, the United States, and Japan alongside METI-directed home care subsidy frameworks.
Feedstock price volatility, gamma sterilization capacity bottlenecks, and regulatory timeline extensions are the dominant revision risks. Forecasts reflect assumptions on polymer migration testing protocol stability and cobalt-60 source availability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices Packaging
Surgical Instruments Packaging Market
Medical Devices Packaging
Healthcare Packaging Market
Medical Devices Packaging
Middle East and Africa Parenteral Packaging Market
Medical Devices Packaging
Sterile and Antiviral Packaging Market
Medical Devices Packaging
Bio-Medical Packaging Market
Medical Devices Packaging
Global Medical Devices Packaging Market
Medical Devices Packaging
North America Medical Devices Packaging Market
Medical Devices Packaging
Syringe Trays Market
Medical Devices Packaging
Medical Devices Secondary Packaging Market
Medical Devices Packaging
Europe Parenteral Packaging Market
Medical Devices Packaging
US Home Care Packaging Market
Medical Devices Packaging
Multi-Med Adherence Packaging Market
Medical Devices Packaging
Sterile Packaging Market
Medical Devices Packaging
Europe Medical Devices Packaging Market
Medical Devices Packaging
Global First Aid Kit Packaging Market
Medical Devices Packaging
Middle East and Africa Medical Devices Packaging Market