
 Sterile and Antiviral Packaging Market | 2026-2036
Sterile and Antiviral Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Sterile and Antiviral Packaging Market Outlook
Pharmaceutical cold chain logistics is realigning demand toward multilayer barrier formats with validated antiviral properties. Amcor plc leverages its global film manufacturing footprint to supply high-barrier laminates for temperature-sensitive biologics. West Pharmaceutical Services, Inc. specializes in elastomeric closure systems that sustain seal integrity under extreme distribution stress. DuPont de Nemours, Inc. dominates fluoropolymer and Tyvek substrate supply for sterile breathable packaging applications.
Sterile and antiviral packaging encompasses engineered barrier systems designed to maintain microbiological integrity while neutralizing viral surface contamination, typically incorporating active agents such as copper ions, silver nanoparticles, or quaternary ammonium compounds within polymer matrices or coating layers. These systems undergo gamma irradiation or ethylene oxide sterilization cycles and must demonstrate log-reduction performance against enveloped and non-enveloped viruses per ISO 21702 and ASTM E1053 protocols. Plastic resins and laminated films lead material value capture due to their processability and compatibility with active additive integration, while biodegradable substrates represent the fastest-expanding segment as European Union regulatory pressure and corporate sustainability mandates reshape procurement specifications. Among applications, pharmaceutical primary packaging commands the deepest margin pool because of validation costs and switching barriers, whereas medical device packaging competes on scale through standardized tray and pouch formats.
The FDA enforces 21 CFR Part 211 compliance for pharmaceutical packaging materials, while the EU MDR requires notified body review of sterile barrier system validation for Class IIa and higher devices. ISO 11607 and ISO 15378 standards shape global design controls, though REACH restrictions on certain antimicrobial chemistries force European manufacturers toward alternative active systems. Stakeholders must monitor evolving regulatory divergence between FDA and EMA antiviral claim substantiation pathways to avoid dual-validation cost escalation.
Market Dynamics
Pharmaceutical cold chain logistics is forcing material selection toward multilayer barrier systems with validated antiviral properties, as temperature excursions and surface contamination risks compound in biologics distribution.
Growth Catalysts
- EU MDR sterile barrier mandates:Class IIa and higher medical devices now require notified body validation of packaging systems, creating certified demand for pre-validated formats.
- Biologics cold chain expansion:mRNA vaccines and cell therapies require barrier-enhanced formats that sustain integrity across cryogenic to ambient temperature ranges.
- Copper ion integration:Active antiviral polymer matrices demonstrate log-reduction performance against enveloped viruses per ISO 21702, opening pharmaceutical primary packaging applications.
Market Restraints
- Fluoropolymer supply concentration:Tyvek and fluorinated substrate production centers on limited North American and European manufacturing assets, creating single-source vulnerability.
- REACH antimicrobial restrictions:ECHA limitations on quaternary ammonium compounds and certain silver formulations force European manufacturers toward alternative active systems with unproven validation histories.
- Gamma irradiation capacity:Sterilization service providers concentrate in Germany and the United States, creating logistics bottlenecks for Asia-Pacific converters.
Strategic Opportunities
- Biodegradable substrate penetration:European Union corporate sustainability mandates and CSRD reporting requirements reshape procurement specifications toward compostable barrier materials.
- Indian pharmaceutical export growth:CDSCO-aligned manufacturers serving regulated markets require ISO 15378-certified packaging systems, creating demand for validated local supply.
- Active coating convergence:Combination of copper-ion surface treatments with high-barrier laminates enables dual-function formats for temperature-sensitive antiviral applications.
Industry Challenges
- Dual-validation cost escalation:Divergent FDA and EMA antiviral claim substantiation pathways force manufacturers to maintain separate testing protocols and documentation systems.
- ISO 11607 implementation timelines:Design control and sterile barrier system validation requirements extend product development cycles for novel material formats.
- Active additive migration testing:Demonstrating stability and non-leaching properties of copper ions and silver nanoparticles across accelerated aging protocols demands specialized analytical capability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sterile and Antiviral Packaging Market |
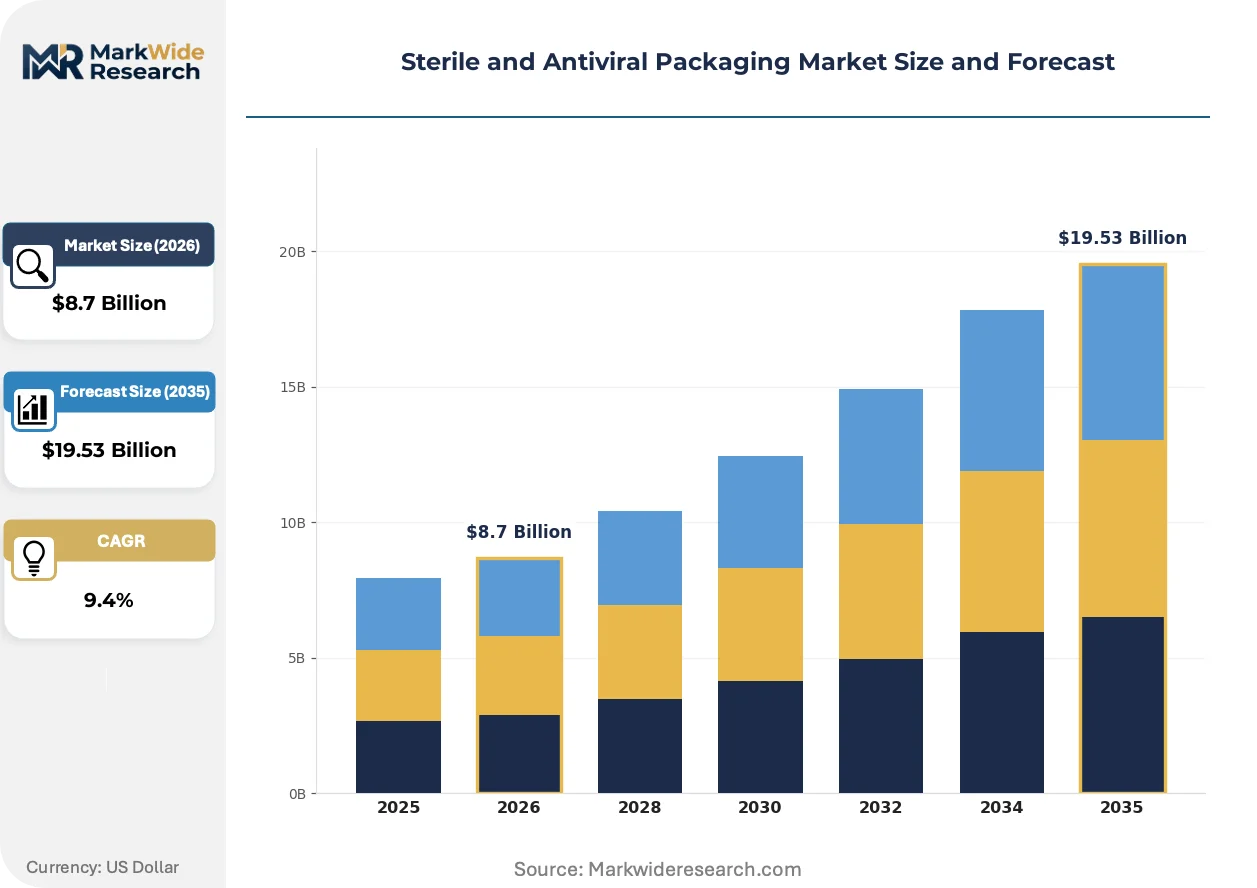
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blister Packs, Pouches, Trays, Labels Material: Plastic, Paper, Aluminum, Biodegradable Application: Pharmaceuticals, Medical Devices, Food Packaging, Laboratory Supplies End User: Hospitals, Pharmaceutical Companies, Research Labs, Biotechnology Firms |
| Companies Covered | Amcor plc, DuPont de Nemours, Inc., West Pharmaceutical Services, Inc., Berry Global Group, Inc., Sonoco Products Company, Wipak Group, BillerudKorsnas AB, Placon Corporation, Gerresheimer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sterile and Antiviral Packaging Market Strategic Shifts
Material science convergence with regulatory validation protocols is compressing development cycles while expanding the functional envelope of sterile barrier systems beyond passive protection.
Copper-ion polymer matrices is consolidating as the dominant active antiviral technology for pharmaceutical primary packaging. Parenteral drug manufacturers are adopting these formats for vial and syringe containment at accelerated qualification timelines. The technology is consolidating supplier relationships around converters with integrated additive compounding and gamma sterilization capabilities.
REACH restrictions on legacy antimicrobial chemistries are forcing European manufacturers toward alternative active systems. ECHA regulatory pressure is eliminating quaternary ammonium compounds from certain polymer applications, redirecting R&D investment toward copper and zinc-based alternatives. German medical device packaging suppliers are responding with accelerated migration testing protocols to substantiate new active formulations.
Hospital and pharmacy procurement is consolidating around pre-validated sterile barrier formats with documented antiviral performance. Group purchasing organizations are displacing custom specification development with catalog selection from qualified supplier lists. This behavioral shift concentrates most visibly in United States health system networks seeking to reduce incoming inspection and qualification burden.
Sterile and Antiviral Packaging Market Segmentation
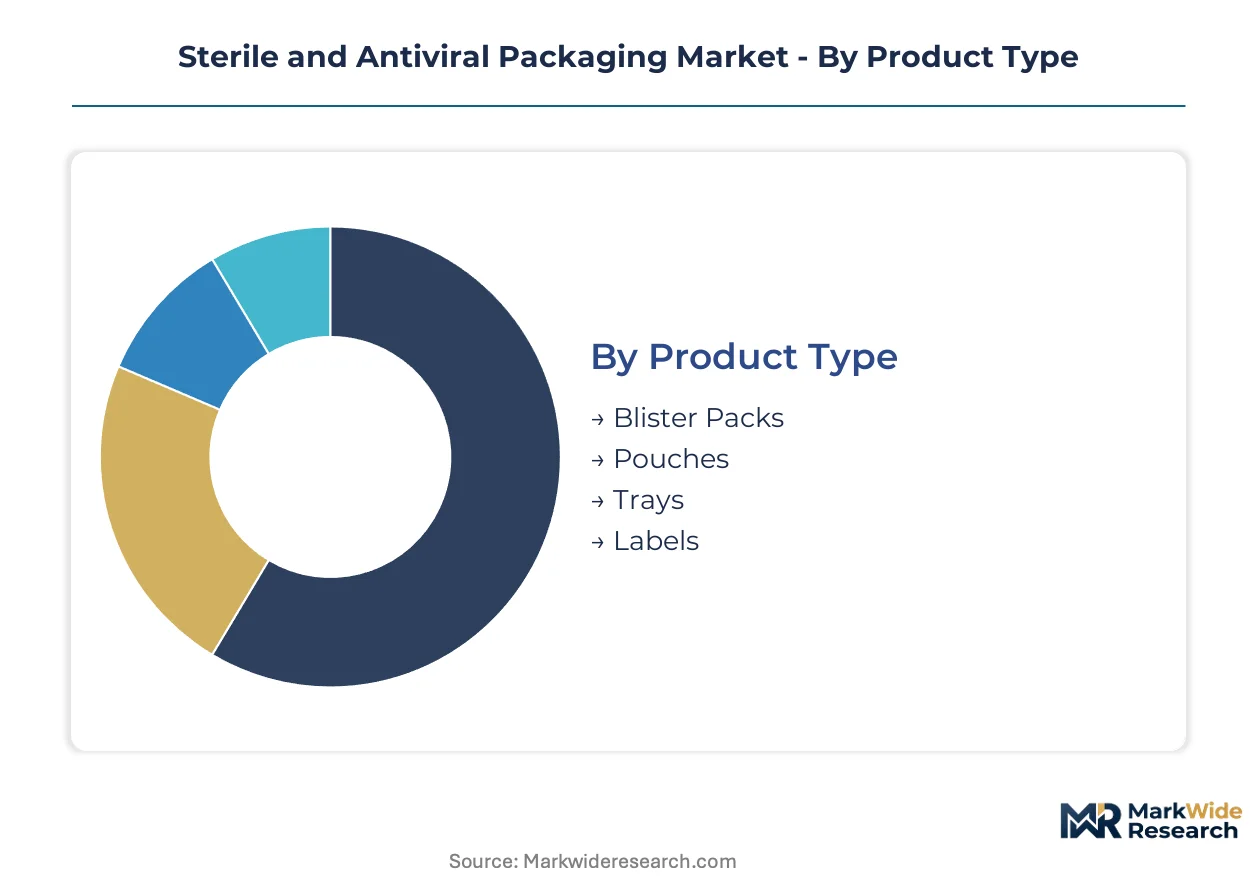
Segmentation in sterile and antiviral packaging reveals how validation costs, material compatibility, and regulatory scope concentrate margin capture across distinct product configurations. Understanding these divisions exposes where procurement budgets flow and where supplier switching costs create defensive positions.
Product Type:
Volume applications favor standardized formats with established sterilization protocols, while premium capture concentrates in customizable systems with integrated active antiviral layers.
- Blister Packs:Thermoformed plastic cavities sealed with foil or film lidding dominate oral solid dose containment. Pharmaceutical manufacturers in Germany's medical device corridor specify these for unit-dose compliance with EU MDR traceability mandates.
- Pouches:Flexible multilayer laminates accommodate irregular device geometries and varying sterilization methods. Demand clusters around gamma-irradiated formats for single-use surgical instruments where Tyvek breathable panels maintain sterility assurance levels.
- Trays:Rigid thermoformed platforms organize complex instrument sets for sterilization and presentation. Standardized dimensions suit high-volume medical device kitting with minimal customization overhead.
- Labels:Adhesive-backed indicators and barrier seals complete sterile barrier systems. Integration of copper-ion surface treatments expands functional claims beyond identification into active contamination control.
Mature deployment sits with blister packs. Newer deployment is concentrated in active-coated labels.
Material:
Material selection balances barrier performance, sterilization compatibility, and regulatory acceptance of active chemistries across pharmaceutical and medical device end-uses.
- Plastic:Polypropylene, polyethylene terephthalate, and cyclic olefin copolymers provide processability for thermoforming and film extrusion. Multilayer coextrusions with ethylene vinyl alcohol interlayers dominate high-barrier pharmaceutical applications where moisture and oxygen exclusion preserves biologic stability.
- Paper:Medical-grade kraft and surgical wrap papers serve breathable sterilization packaging for ethylene oxide and steam processes. REACH restrictions on fluorinated coatings redirect European converters toward uncoated alternatives with validated microbial barrier properties.
- Aluminum:Foil laminates deliver absolute moisture, light, and gas barriers for moisture-sensitive pharmaceuticals. Cold-form blister applications in parenteral drug packaging exploit metal formability for deep-draw cavity geometries.
- Biodegradable:Polylactic acid and polyhydroxyalkanoate substrates address EU corporate sustainability reporting mandates. Compostable barrier materials are climbing the fastest as CSRD-aligned procurement specifications reshape European hospital purchasing criteria.
Established supply relationships favor plastic and aluminum. Sustainability-driven substitution is accelerating fastest in biodegradable formats.
Application:
Application scope determines validation burden, with pharmaceutical primary packaging commanding the deepest compliance investment and longest qualification timelines.
- Pharmaceuticals:Primary packaging for sterile drug products requires ISO 15378 certification and drug master file documentation. Vial containment, prefillable syringes, and combination product formats absorb the majority of antiviral barrier development expenditure.
- Medical Devices:Sterile barrier systems for implantable and surgical instruments compete on scale through standardized tray and pouch configurations. EU MDR Class IIa and higher classifications mandate notified body review of packaging validation.
- Food Packaging:Antimicrobial food contact materials face EFSA safety assessments for active substance migration. Copper-based systems demonstrate compliance for extended shelf-life meat and dairy applications.
- Laboratory Supplies:Cell culture vessels, pipette tips, and diagnostic consumables require sterile presentation with minimal extractables. Gamma-irradiated plasticware supports biotechnology workflow contamination control.
Regulatory intensity peaks in pharmaceuticals. Volume expansion is steepest in laboratory supplies serving cell therapy manufacturing scale-up.
End User:
End-user procurement sophistication varies from centralized group purchasing organization negotiations to decentralized research laboratory specification.
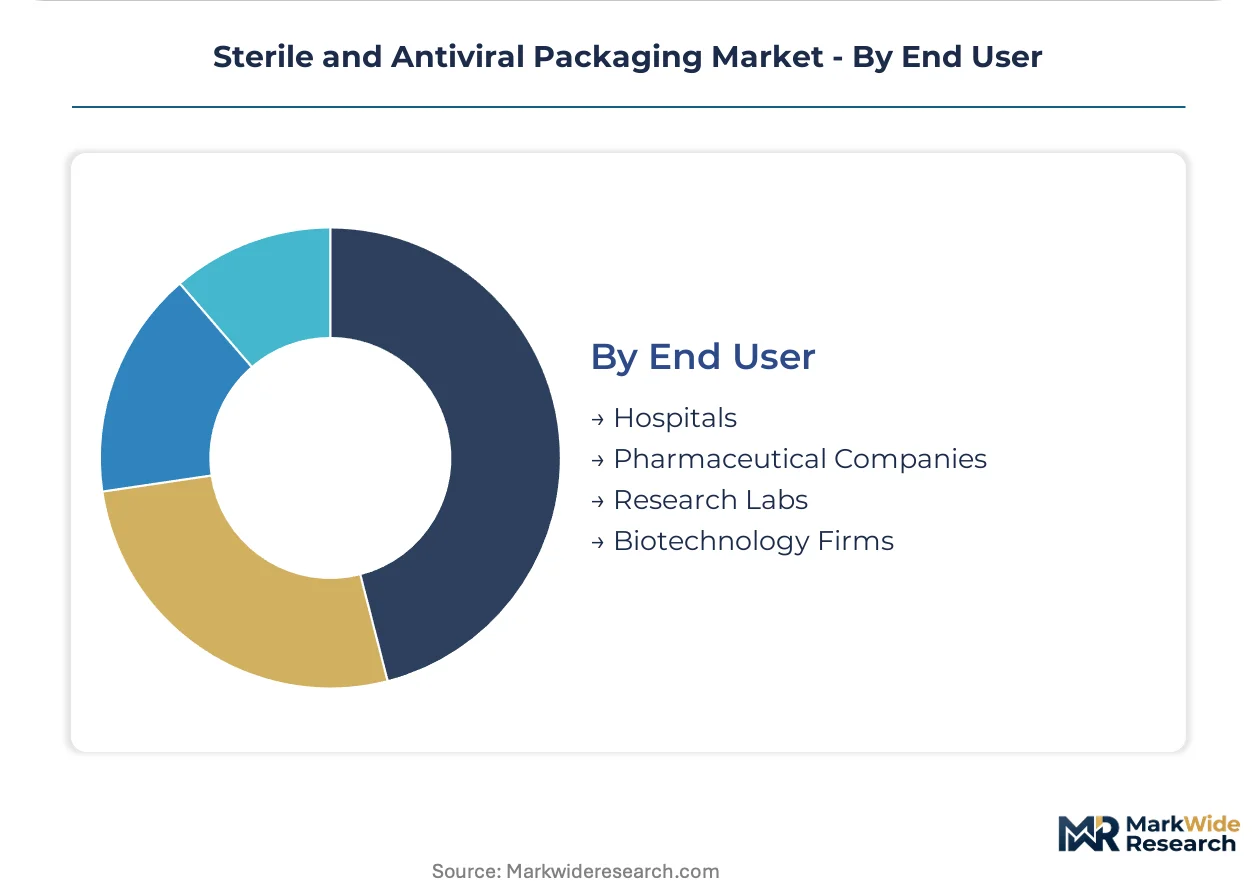
- Hospitals:Health system networks consolidate purchasing through qualified supplier lists that displace incoming inspection with pre-validated sterile barrier acceptance. United States GPO contracts favor catalog selection over custom development.
- Pharmaceutical Companies:Integrated drug manufacturers control packaging specification as part of regulatory submission strategy. Internal quality organizations mandate supplier audit programs that lock in converter relationships across product lifecycles.
- Research Labs:Academic and government laboratories prioritize cost and availability over validation documentation. Standardized sterile consumables from distributor catalogs minimize procurement friction for grant-funded operations.
- Biotechnology Firms:Cell therapy and gene therapy developers require cryogenic-compatible barrier systems for cryopreserved starting materials and finished products. Emerging CDMO relationships transfer packaging specification risk to manufacturing partners.
Procurement consolidation is most advanced in hospital networks. Specification control remains tightest among pharmaceutical companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's medical device corridor operates as the primary tax-incentive zone concentrating sterile packaging validation capacity, with specialized economic zones in Bavaria and Baden-Württemberg drawing gamma irradiation infrastructure and notified body presence.
United States
FDA 21 CFR Part 211 compliance mandates drive pharmaceutical packaging procurement toward pre-validated sterile barrier systems. The IRA's domestic manufacturing incentives accelerate converter capacity expansion in the Southeast and Midwest. Greater Boston's biotech cluster demands cryogenic-compatible formats for cell therapy cold chain logistics.
Germany
EU MDR Class IIa sterile barrier validation requirements concentrate notified body review capacity in Stuttgart and Munich. REACH restrictions on quaternary ammonium compounds redirect antimicrobial R&D toward copper-ion alternatives. The Tübingen-Reutlingen medical technology cluster houses integrated film extrusion and gamma sterilization assets.
India
CDSCO-aligned pharmaceutical exporters serving regulated markets require ISO 15378-certified packaging systems. The PLI scheme for medical devices attracts sterile barrier converters to Gujarat and Maharashtra. Hyderabad's vaccine manufacturing hub drives demand for validated cold-chain pouch formats.
China
NMPA medical device registration reforms elevate sterile barrier documentation requirements for Class II and III devices. Dual carbon goals accelerate biodegradable substrate pilot programs in the Yangtze River Delta. Suzhou's medical device industrial park concentrates multilayer film lamination capacity.
Switzerland
Swissmedic pharmaceutical packaging material approvals maintain stringent drug master file documentation standards. Basel's pharmaceutical headquarters economy sources high-barrier primary containment from validated regional suppliers. The country's precision manufacturing heritage supports specialized elastomeric closure system production.
Sterile and Antiviral Packaging Market Competitive Environment
Top-tier vendors anchor global film and substrate supply, while mid-tier converters compete on regional validation speed and customization responsiveness. The market structure consolidates around materials science conglomerates with captive polymer production, specialty pharmaceutical packaging pure-plays, and diversified industrial packaging groups with medical-grade certifications. Strategic moves concentrate on backward integration into active additive compounding and sterilization service acquisition to compress qualification timelines.
Within the materials science tier, DuPont de Nemours, Inc. and Amcor plc occupy positions exemplifying fluoropolymer substrate and multilayer laminate supply respectively. West Pharmaceutical Services, Inc. represents the pharmaceutical pure-play archetype focused on elastomeric closure systems. These three entities anchor distinct competitive vectors—substrate technology, flexible packaging scale, and drug-device integration—while mid-tier specialists compete on regional regulatory alignment and accelerated validation services.
| Leading Market Players |
|---|
| Amcor plc |
| DuPont de Nemours, Inc. |
| West Pharmaceutical Services, Inc. |
| Berry Global Group, Inc. |
| Sonoco Products Company |
| Wipak Group |
| BillerudKorsnas AB |
| Placon Corporation |
| Gerresheimer AG |
| Others |
Value Chain & Pricing Dynamics
Copper-ion additive costs cascade through polymer compounding, film extrusion, and gamma sterilization stages before crystallizing into three-tier pricing structures across premium, standard, and economy levels. Pharmaceutical manufacturers absorbing these input premiums for ISO 15378-certified formats pass heightened procurement specifications to group purchasing organizations consolidating hospital network demand.
Pricing Analysis
Lead-time-driven pricing angles dominate sterile barrier procurement, with premium capture for validated formats delivering under eight-week qualification timelines against discounted spot inventory from converters with excess gamma irradiation capacity. Price differentiation hinges on ISO 11607 certification tier and geographic delivery cost from German or North American sterilization hubs. Pricing pressure stems from REACH-compliant copper-ion formulation migration testing extending validation cycles. Research laboratories exhibit highest price sensitivity, while integrated pharmaceutical manufacturers prioritize qualification speed over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale pharmaceutical demand, while distributor networks serve mid-tier medical device manufacturers requiring standardized tray and pouch formats. Geographic supply concentration centers on Germany, the United States, and China for multilayer film lamination and fluoropolymer substrate production. Raw material dependencies draw from ethylene vinyl alcohol resin, Tyvek breathable membranes, and copper-ion masterbatch additives. Single-source vulnerability in gamma irradiation capacity creates structural risk. Distribution runs through qualified supplier lists maintained by hospital group purchasing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around validated sterile barrier capabilities, with dual-validation cost escalation for FDA and EMA pathways forcing subscale converters toward acquisition or exit.
For Market Incumbents: Anticipate margin compression from emerging Asian converters achieving ISO 15378 certification by securing backward integration into copper-ion masterbatch compounding and captive gamma sterilization assets in Germany's medical device corridor. Defensive positioning demands pre-validated format libraries that compress customer qualification timelines below competitor benchmarks. For New Entrants and Emerging Players: Capture white-space opportunity in biodegradable sterile barriers serving EU corporate sustainability reporting mandates, where established suppliers lag compostable validation timelines. Indian pharmaceutical export growth to regulated markets offers penetrable entry, with CDSCO-aligned manufacturers requiring local ISO 15378-certified supply. Go-to-market execution should anchor on accelerated migration testing protocols substantiating alternative active formulations. For Investors and Strategic Acquirers: Copper-ion polymer matrix adoption by parenteral drug manufacturers is the leading indicator that active antiviral packaging is transitioning from premium niche to standard-of-care expectation. Long-term viability favors converters with integrated additive compounding and sterilization service capabilities. Acquisition targets should display gamma irradiation infrastructure and notified body relationships. Monitor ECHA regulatory bulletins for antimicrobial chemistry restrictions as early signals of formulation obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Active Additive Compounding | Captive copper-ion masterbatch production compresses qualification timelines for pharmaceutical customers. |
| Gamma Sterilization Service Acquisition | Integrated sterilization assets eliminate logistics bottlenecks and single-source vulnerability in Germany. |
| Biodegradable Substrate Validation Investment | Compostable barrier certification addresses EU CSRD procurement mandates reshaping hospital purchasing. |
| Dual-Regulatory Validation Capability Buildout | Parallel FDA and EMA testing protocols defend margin position against dual-validation cost escalation. |
| Regional Converter Capacity Expansion | Indian PLI scheme-aligned manufacturing captures CDSCO-certified demand from pharmaceutical exporters. |
Study Parameters
Regulatory filings with FDA and EMA, ISO standard documentation, and trade customs data formed the secondary backbone, cross-referenced against primary interviews with sterile barrier system validation managers, gamma sterilization service operators, pharmaceutical packaging procurement directors, and notified body technical assessors. Bottom-up and top-down triangulation reconciled converter capacity data with end-user demand signals across pharmaceutical, medical device, and biotechnology segments.
Bottom-up modeling anchored volume estimates in sterilization cycle throughput and active additive incorporation rates, while top-down analysis tested aggregate market scale against pharmaceutical cold chain logistics expansion trends. Segmentation dimensions spanned product format, material chemistry, application regulatory intensity, and end-user procurement sophistication. CAGRs derived from regression analysis of historical validation timeline compression and sustainability-driven material substitution elasticities.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA antimicrobial restriction scope and gamma irradiation capacity expansion timing. Forecasts reflect documented assumptions on regulatory alignment between FDA and EMA antiviral claim pathways. Practitioners should monitor REACH restriction bulletins, CDSCO export certification trends, and hospital GPO contract consolidation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices Packaging
Sterile Wraps Market
Medical Devices Packaging
Medical Tray Sealers Market
Medical Devices Packaging
Medical Processing Seals (MPS) Market
Medical Devices Packaging
Global Medical Devices Packaging Market
Medical Devices Packaging
Plastic Healthcare Packaging Market
Medical Devices Packaging
US Home Care Packaging Market
Medical Devices Packaging
Medical-Grade Foil Market
Medical Devices Packaging
Europe Parenteral Packaging Market
Medical Devices Packaging
Ophthalmic Packaging Market
Medical Devices Packaging
Asia Pacific Blood Glucose Test Strip Packaging Market
Medical Devices Packaging
Medical Containers Market
Medical Devices Packaging
Healthcare Packaging Market
Medical Devices Packaging
Global First Aid Kit Packaging Market
Medical Devices Packaging
Syringe Trays Market
Medical Devices Packaging
Surgical Instruments Packaging Market
Medical Devices Packaging
North America Parenteral Packaging Market