
 Europe Parenteral Packaging Market | 2026-2036
Europe Parenteral Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Parenteral Packaging Market Foresight
EU MDR Annex I technical documentation is redrawing competitive boundaries for sterile container suppliers. Gerresheimer AG leverages its glass conversion expertise to dominate high-barrier vial production across German and French biopharma corridors. SCHOTT AG sustains technology leadership in borosilicate glass formulations for mRNA cold-chain requirements. West Pharmaceutical Services, Inc. anchors its position through integrated elastomer and delivery system platforms that span multiple European manufacturing sites.
Europe Parenteral Packaging encompasses sterile primary containers, closure systems, and administration devices engineered to maintain drug product integrity from manufacture through patient administration, typically involving materials with extractables and leachables profiles below pharmacopeial thresholds. Glass vials and prefillable syringes constitute the largest product segments, with biologics applications commanding premium positioning due to protein stability and silicone sensitivity requirements. Plastic and polymer alternatives represent the fastest-expanding material category as cyclic olefin polymers displace traditional formats in sensitive biologic formulations.
EMA quality guidelines, EU MDR conformity assessment procedures, and EudraLex Volume 4 Annex 1 sterile manufacturing standards collectively dictate validation protocols and barrier system performance criteria across the region. These frameworks compel manufacturers to demonstrate container closure integrity and particulate control at intensified statistical rigor. Stakeholders must monitor evolving pharmacopeial harmonization between EP, USP, and JP standards to anticipate specification shifts that will determine qualification timelines and capital allocation priorities.
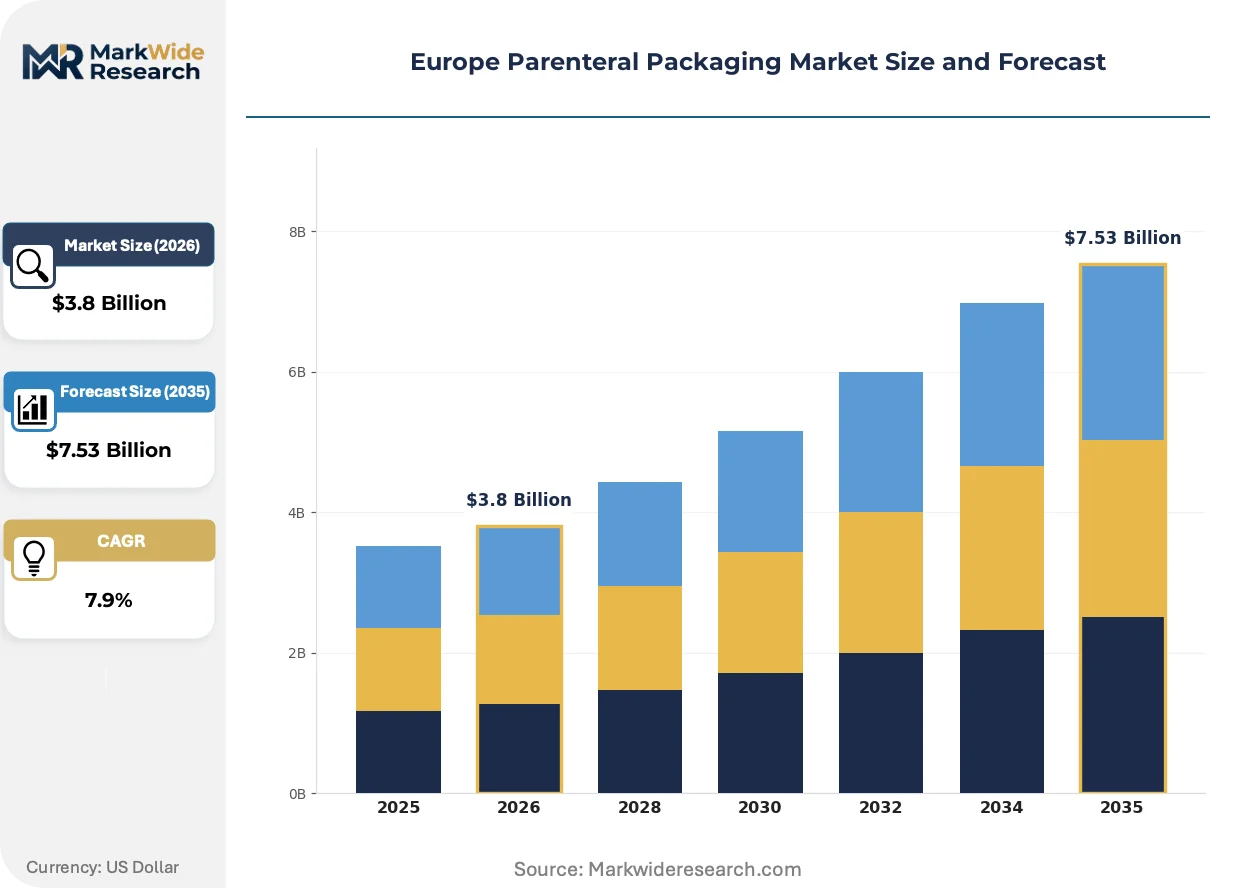
Market Dynamics
EU MDR Annex I container closure integrity requirements are compressing qualification timelines and forcing sterile packaging manufacturers to revalidate legacy product lines at unprecedented statistical rigor.
Growth Catalysts
- Biologics manufacturing expansion:Contract development organizations across Germany and France are scaling sterile injectable capacity for monoclonal antibodies and mRNA therapeutics, driving demand for high-barrier primary containers.
- EudraLex Volume 4 Annex 1 revision:The updated sterile manufacturing standard mandates barrier isolation technology and continuous particulate monitoring, compelling facility upgrades across European fill-finish operations.
- Cyclic olefin polymer adoption:Biopharma formulators are specifying COP vials and syringes for protein-sensitive biologics, creating material substitution momentum in France and Switzerland.
Market Restraints
- Specialty glass supply concentration:Borosilicate tubing production clusters in Germany and limited qualified alternative suppliers create input vulnerability for vial and prefillable syringe manufacturers.
- Extractables and leachables validation burden:EMA quality guidelines require extensive analytical characterization for each drug-container combination, extending development timelines by 12-18 months for novel formats.
- Silicone oil sensitivity constraints:Protein aggregation risks in prefilled syringes limit plunger coating options and complicate elastomer selection for high-value biologics.
Strategic Opportunities
- Poland and Czech Republic manufacturing expansion:Lower-cost sterile fill-finish capacity is attracting CMO investment, creating localized packaging demand outside traditional German and Swiss hubs.
- Integrated delivery system platforms:Combination product regulations are incentivizing suppliers to develop autoinjector and safety syringe systems that lock in primary container specifications.
- EU Green Deal packaging sustainability mandates:Circular economy requirements for medical plastics are opening competitive space for recyclable and bio-based polymer alternatives to traditional formats.
Industry Challenges
- Container closure integrity test method harmonization:Discrepancies between EMA, FDA, and PMDA acceptance criteria for probabilistic leak detection force redundant validation studies for multi-region product launches.
- Specialized elastomer formulation expertise scarcity:The intersection of polymer science, pharmaceutical regulatory knowledge, and extractables chemistry concentrates in a limited workforce pool across European manufacturing corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Parenteral Packaging Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.53 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Syringes, Vials, Ampoules, Cartridges Material: Glass, Plastic, Rubber, Metal Application: Injectable Medications, Vaccines, Blood Products, Biologics End User: Hospitals, Clinics, Pharmacies, Contract Manufacturers |
| Companies Covered | West Pharmaceutical Services, Inc., AptarGroup, Inc., Amcor plc, SGD Pharma, Catalent, Inc., Gerresheimer AG, Stevanato Group, Becton, Dickinson and Company, SCHOTT AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Parenteral Packaging Market Shifts & Advancements
Cold-chain infrastructure demands and protein stability requirements are accelerating material science investment across European sterile packaging value chains. Three converging developments are restructuring competitive positioning.
Ready-to-use (RTU) container systems are decomposing traditional component supply relationships. Biopharma manufacturers in Germany and Switzerland are specifying nested, pre-sterilized vials and syringes that eliminate in-house washing and depyrogenation. This shift compresses capital requirements for fill-finish operations while locking buyers into integrated supplier ecosystems.
EMA's tightened expectations for visible and subvisible particulate control are forcing container manufacturers to implement 100% automated inspection protocols. The industrial consequence is a capital equipment arms race among European glass and polymer converters. High-value biologics applications are absorbing these compliance costs fastest, with German CMOs leading adoption of laser-based particle detection systems.
Buyer consolidation among contract development organizations is concentrating procurement leverage in fewer hands. Large European CDMOs are unbundling after-sales technical support and demanding predictive analytics for supply continuity. This pattern is most visible in the Frankfurt-Heidelberg corridor, where sterile injectable production clusters around three major manufacturing networks.
Europe Parenteral Packaging Market Segmentation
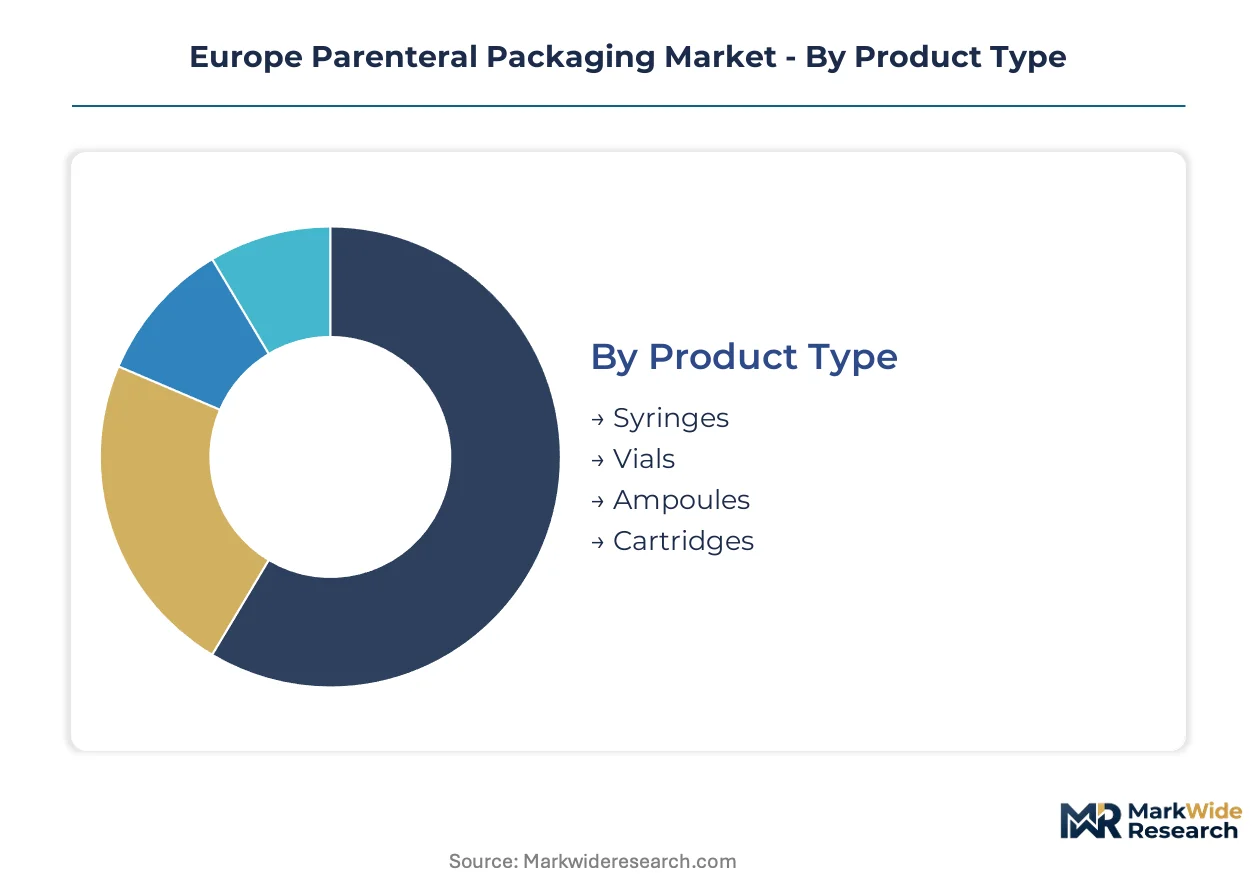
Europe Parenteral Packaging segmentation reflects divergent regulatory burdens and supply chain configurations across material classes and end-use applications. Each category carries distinct qualification timelines and geographic demand patterns that shape procurement strategies.
Product Type:
German and Swiss fill-finish corridors drive syringe and vial demand for export to North American and Asian markets, while ampoules serve predominantly domestic European generics manufacturers. Cartridge formats concentrate in French and Danish insulin production clusters.
- Syringes:Prefillable glass and polymer syringes incorporate staked-needle or Luer-lock configurations with elastomer plunger systems. Demand clusters around Heidelberg and Frankfurt CMOs manufacturing mRNA and monoclonal antibody products for EMA-regulated export markets. Silicone oil sensitivity in protein formulations is driving specification divergence between standard and reduced-residue plunger coatings.
- Vials:Borosilicate and aluminosilicate glass vials in 2R-50R ISO formats constitute the workhorse container for lyophilized and liquid parenterals. German glass converters supply French and Italian biopharma facilities under EudraLex Volume 4 Annex 1 sterile manufacturing mandates. Cyclic olefin polymer vials are gaining traction in Swiss protein stability applications.
- Ampoules:Type I borosilicate ampoules serve cost-sensitive generic injectable markets across Southern Europe.
- Cartridges:Pen-injector compatible 1.5ml and 3ml glass cartridges concentrate in Danish and French diabetes therapy manufacturing.
Vials hold the largest share; momentum sits with syringes.
Material:
Glass retains dominance in high-value biologics despite polymer substitution pressure, while rubber closure formulations face extractables scrutiny under EMA quality guidelines. Metal components serve specialized safety-device applications.
- Glass:Borosilicate tubing from German suppliers feeds vial and syringe conversion across European manufacturing corridors. Surface hydrolytic resistance and visible particulate control dominate qualification protocols. French and Italian facilities specify premium cosmetic-grade glass for high-visibility biologics packaging.
- Plastic:Cyclic olefin polymers and copolymers displace glass in protein-sensitive formulations requiring reduced silicone contact. Swiss and German formulators specify COP for prefilled syringes in cold-chain mRNA applications. Breakage reduction and design flexibility accelerate adoption in automated fill-finish lines.
- Rubber:Bromobutyl and chlorobutyl elastomer formulations provide gas-barrier closure systems. EMA extractables validation requirements extend development timelines for novel coating technologies.
- Metal:Aluminum crimp seals and needle shields serve autoinjector and safety-syringe combination products.
Glass commands the value premium; plastic is climbing the fastest.
Application:
Biologics applications absorb disproportionate packaging innovation investment, while vaccine demand fluctuates with public procurement cycles. Blood products maintain steady glass-dependent demand across European transfusion networks.
- Biologics:Monoclonal antibodies, recombinant proteins, and cell therapies require container systems with subvisible particulate control below USP 788 thresholds. German CMOs specify nested RTU vials and syringes to minimize contamination risk. Protein aggregation sensitivity drives material selection toward low-extractable polymers and specialized elastomer formulations.
- Injectable Medications:Small-molecule parenterals span generic antibiotics to complex liposomal formulations. Cost pressure in European hospital procurement favors standardized glass vial formats.
- Vaccines:Multidose vials and single-dose prefilled syringes serve EMA and national immunization programs. Adjuvant compatibility constrains material selection.
- Blood Products:Plasma-derived therapies and coagulation factors require validated container closure integrity for extended shelf life.
Injectable medications hold the largest share; biologics show the steepest expansion trajectory.
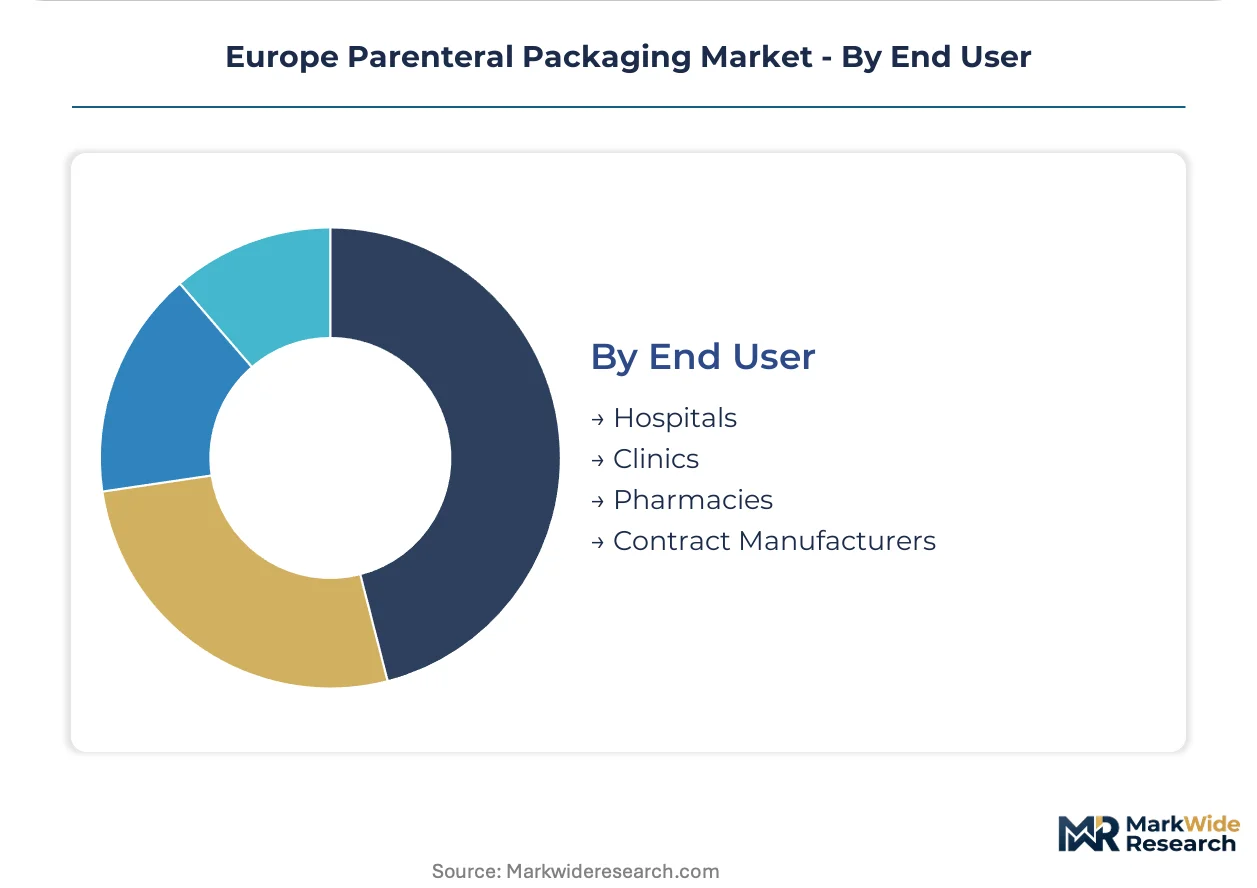
End User:
Contract manufacturers concentrate procurement leverage through multi-site standardization, while hospital pharmacy compounding drives demand for flexible container formats. Retail pharmacy channels expand with self-administration therapies.
- Contract Manufacturers:CDMOs across Germany, France, and Switzerland specify integrated supplier platforms spanning primary containers, closure systems, and device components. Frankfurt-Heidelberg corridor facilities demand predictive supply analytics and dual-source qualification for high-value biologics campaigns.
- Hospitals:Central pharmacy operations and oncology compounding units require break-resistant containers and needle-safety systems. German hospital procurement consortia negotiate volume contracts for standardized vial formats.
- Clinics:Outpatient infusion centers favor prefilled syringes for workflow efficiency.
- Pharmacies:Retail channels expand with patient self-injection therapies requiring patient-centric device design.
Contract manufacturers hold the largest share; pharmacies are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU MDR Annex I container closure integrity requirements are redrawing procurement patterns across European biopharma corridors. National implementation timelines and sterile manufacturing infrastructure investments are creating divergent growth trajectories among member states.
Germany
Frankfurt-Heidelberg sterile injectable clusters absorb the majority of high-barrier vial and prefillable syringe demand. EudraLex Volume 4 Annex 1 mandates accelerate barrier isolation technology adoption across Hesse and Baden-Württemberg fill-finish facilities. German glass converters supply borosilicate tubing to domestic CMOs while exporting precision-molded components to French and Italian biopharma networks.
Switzerland
Basel and Zurich biologics formulators specify cyclic olefin polymer alternatives for protein-sensitive mRNA applications. Swissmedic quality guidelines enforce extractables validation protocols that exceed baseline EMA requirements. The Basel-Lucerne corridor concentrates specialty elastomer formulation expertise for plunger systems in cold-chain biologics.
France
Paris-Saclay and Lyon biotech clusters drive demand for nested ready-to-use container systems. ANSM pharmacovigilance standards tighten visible particulate thresholds for high-value monoclonal antibody packaging. French CDMOs in the Île-de-France region are qualifying dual-source glass suppliers to mitigate German supply concentration risk.
Italy
Lombardy and Emilia-Romagna generic injectable manufacturers favor cost-optimized Type I borosilicate ampoules for hospital procurement contracts. AIFA pricing pressure on standard parenterals limits packaging specification upgrades outside Milan-Turin biologics corridors. Italian converters are expanding polymer vial capacity to serve Swiss and German protein formulation outsourcing.
Poland
Warsaw and Krakow sterile fill-finish investments attract CMOs seeking lower-cost European capacity. EU cohesion fund infrastructure grants support barrier technology upgrades at emerging manufacturing sites. Polish facilities are qualifying as secondary supply sources for German biopharma networks requiring geographic diversification.
Europe Parenteral Packaging Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and regulatory capability dimensions. The vendor base stratifies between integrated platform providers and component-focused converters. Three archetypes dominate: glass conversion specialists with tubing-to-vial vertical control, integrated delivery system architects spanning elastomers to devices, and polymer innovators displacing traditional formats. Competitive moves concentrate on capacity expansion in German corridors and technology licensing for COP formulations.
Within the integrated platform tier, West Pharmaceutical Services, Inc. and AptarGroup, Inc. exemplify the delivery system convergence strategy. SCHOTT AG and Gerresheimer AG occupy positions as glass conversion anchors with German heritage. Stevanato Group represents the private specialist archetype with Italian roots.
| Leading Market Players |
|---|
| West Pharmaceutical Services, Inc. |
| AptarGroup, Inc. |
| Amcor plc |
| SGD Pharma |
| Catalent, Inc. |
| Gerresheimer AG |
| Stevanato Group |
| Becton, Dickinson and Company |
| SCHOTT AG |
| Others |
Supply & Pricing Matrix
EMA quality guidelines and EU MDR Annex I conformity assessment simultaneously gate supplier qualification and stratify price tiers across European sterile packaging procurement. Buyers absorbing EudraLex Volume 4 Annex 1 sterile manufacturing mandates face dual cost pressure: validation expenses for container closure integrity testing and premium pricing for pre-qualified RTU formats.
Pricing Analysis
Certification level under EMA and EU MDR frameworks creates the primary spread between premium qualified suppliers and unvalidated alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects extractables validation depth, with biologics-grade glass and COP formats commanding substantial premiums over generic ampoules. Cost compression in standard vial tiers is intensifying because Italian and Polish converters are expanding capacity with automated inspection equipment. Hospital procurement consortia exhibit highest price sensitivity, while Frankfurt-Heidelberg CMOs prioritize supply continuity over unit cost.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg container terminals feed into landed pricing for Asian-sourced polymer resins and specialty elastomers. German borosilicate tubing production, Italian glass conversion, and Swiss COP formulation expertise anchor European supply. Raw material dependencies include borosilicate glass tubing, bromobutyl elastomer formulations, and cyclic olefin polymer resin. Single-source vulnerability concentrates in German specialty glass tubing. Distribution runs through integrated supplier platforms serving multi-site CDMO networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive supply analytics and technical support subscriptions are expanding faster than primary container hardware sales, creating recurring revenue attach opportunities for packaging suppliers. Service-layer penetration now determines procurement stickiness in consolidated CDMO accounts.
For Market Incumbents: Consolidate through backward integration into borosilicate tubing production or captive elastomer formulation capability to defend against polymer substitution threats. Lock in Frankfurt-Heidelberg corridor accounts with integrated RTU platforms spanning nested vials, closure systems, and predictive inventory management. Certification investment in EU MDR Annex I technical documentation creates switching costs for biologics manufacturers.
For New Entrants and Emerging Players: Lead with recyclable COP alternatives targeting EU Green Deal compliance requirements in French and Swiss sustainability-focused formulators. Poland and Czech Republic sterile fill-finish expansion offers the most penetrable geography outside German supply concentration. Partner with emerging CDMOs in Warsaw-Krakow corridors to establish qualification track records before scaling to Western European biopharma networks.
For Investors and Strategic Acquirers: EU MDR Annex I implementation timeline reshapes the acquisition landscape by compressing qualification windows for unvalidated suppliers. Five-to-ten year viability favors integrated platform providers with elastomer-to-device architectures over component-focused converters. Target acquisition archetype: specialty elastomer formulators with extractables chemistry expertise and existing EMA master file documentation. Signal to monitor: ANSM and Swissmedic visible particulate threshold tightening that would accelerate automated inspection equipment replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| RTU Container Platform Expansion | Nested, pre-sterilized formats eliminate CMO washing capital and lock in supplier ecosystems across German corridors. |
| Elastomer Formulation Acquisition | Specialized plunger coatings for silicone-sensitive biologics concentrate expertise in Basel-Lucerne and Frankfurt-Heidelberg zones. |
| COP Manufacturing Scale-Up | Cyclic olefin polymer capacity addresses protein stability requirements in Swiss mRNA cold-chain applications. |
| Barrier Isolation Technology Partnership | EudraLex Volume 4 Annex 1 compliance mandates drive fill-finish facility upgrades across Hesse and Baden-Württemberg. |
| Polish Secondary Supply Qualification | Warsaw-Krakow facilities diversify geographic risk for German biopharma networks under procurement consolidation pressure. |
Research Methodology
Cross-validation between regulatory filing analysis and supply chain stakeholder interviews anchors the qualitative findings in documented compliance patterns. Primary fieldwork encompassed regulatory affairs directors at EMA-notified bodies, procurement leads at Frankfurt-Heidelberg CDMOs, sterile manufacturing engineers, and elastomer formulation specialists. Secondary sources included EMA quality guideline documentation, EU MDR Annex I technical standards, EudraLex Volume 4 Annex 1 revision drafts, and customs data for borosilicate glass and polymer resin trade flows. Bottom-up capacity modeling and top-down demand estimation triangulate market sizing across material and application segments.
Sensitivity analysis around EMA extractables validation timeline assumptions and EU MDR implementation pace informs scenario boundaries. Segmentation dimensions encompass product type, material class, application, and end-user archetype, with additional modeling for regional regulatory cluster effects. CAGRs derive from normalized historical growth patterns adjusted for EudraLex Volume 4 Annex 1 capital expenditure cycles and biologics manufacturing expansion trajectories. Forecast inputs include CDMO capacity announcements, barrier technology adoption curves, and polymer substitution elasticity estimates.
The analysis sits within stated boundaries; outcomes outside sustained EMA enforcement intensity or accelerated COP adoption would require recalibration. Forecasts reflect assumptions regarding EU MDR Annex I conformity assessment timelines, EudraLex Volume 4 Annex 1 sterile manufacturing upgrade completion rates, and biologics pipeline advancement through European CMO networks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices Packaging
Multi-Med Adherence Packaging Market
Medical Devices Packaging
US Home Care Packaging Market
Medical Devices Packaging
Europe Medical Devices Packaging Market
Medical Devices Packaging
Bio-Medical Packaging Market
Medical Devices Packaging
Medical-Grade Foil Market
Medical Devices Packaging
Medical Diagnostic Packaging Market
Medical Devices Packaging
Medical Devices Secondary Packaging Market
Medical Devices Packaging
Sterile Wraps Market
Medical Devices Packaging
Medical Implants Sterile Packaging Market
Medical Devices Packaging
Plastic Healthcare Packaging Market
Medical Devices Packaging
North America Parenteral Packaging Market
Medical Devices Packaging
Sterile Packaging Market
Medical Devices Packaging
Molded Pulp Clinical Packaging Market
Medical Devices Packaging
Medical Tray Sealers Market
Medical Devices Packaging
Sterile and Antiviral Packaging Market
Medical Devices Packaging
Global First Aid Kit Packaging Market