
 Medical Tray Sealers Market | 2026-2036
Medical Tray Sealers Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Tray Sealers Market Outlook
Modular packaging configurations that separate sealing heads from vacuum-forming stations is realigning how hospitals evaluate capital equipment. Multivac leverages its integrated thermoforming-sealing platforms to anchor high-throughput surgical supply operations. Nelipak Healthcare specializes in medical-grade polymer compatibility, extending its position in tray-sealing consumables alongside capital equipment. Atlas Vac Machine competes through custom-engineered vacuum-seal validation systems for central sterile processing departments.
Medical tray sealers are electromechanical devices that apply controlled heat, pressure, and dwell time to bond lidding material to pre-formed trays, typically achieving seal strengths of 1.5-3.0 N/15mm and maintaining sterile barrier integrity per ISO 11607 requirements. Their primary purpose is to create validated, peelable seals for terminally sterilized medical devices and surgical kits. Fully automatic sealers dominate installed capacity in large hospital systems where throughput exceeds 200 trays per hour, while hybrid sealers represent the fastest-expanding category as mid-size laboratories seek flexible batch processing without dedicated operator stations. Heat sealing technology occupies the largest technology share due to its maturity and lower validation burden, though ultrasonic sealing is gaining traction in temperature-sensitive biologics packaging where thermal degradation risk constrains process windows.
FDA enforcement of 21 CFR Part 820 quality system regulations and EU MDR requirements for sterile barrier validation are elevating the compliance threshold for seal process qualification. ISO 11607 and EN 868-5 standards dictate seal strength, peel characteristics, and microbial barrier performance, effectively filtering manual sealer suppliers from regulated medical device packaging. Stakeholders must monitor evolving FDA guidance on packaging process validation and EU notified body interpretation of MDR Annex I general safety requirements to anticipate capital refresh cycles and qualification cost structures.
Market Dynamics
EU MDR documentation requirements for sterile barrier validation are compressing the installed base of manual sealers and forcing capital upgrades toward automated, validated systems with full process traceability.
Growth Catalysts
- FDA 21 CFR Part 820 enforcement:Quality system regulations mandate documented seal process qualification, pushing hospitals toward equipment with built-in validation protocols.
- Surgical volume recovery:North American and European hospitals are expanding central sterile processing capacity to address procedure backlogs.
- Ultrasonic sealing technology:Temperature-sensitive biologics packaging is accelerating adoption of non-thermal sealing methods for heat-labile pharmaceutical products.
Market Restraints
- Stainless steel and aluminum input volatility:Precision sealing head fabrication depends on machined metal components subject to commodity price swings.
- German and Swiss control system concentration:PLC and HMI modules for validated sealers source heavily from Central European automation suppliers, creating single-region dependency.
- ISO 11607-2 validation burden:Process qualification requirements for seal strength and peel characteristics extend equipment commissioning timelines.
Strategic Opportunities
- Chinese hospital system modernization:Tier-3 city medical centers are building surgical instrument reprocessing infrastructure with validated packaging lines.
- Point-of-care sterilization expansion:Ambulatory surgery centers require compact, hybrid sealers for same-day procedure kits.
- EU Green Deal packaging mandates:Recyclable lidding material compatibility requirements favor sealers with adjustable temperature and pressure profiles.
Industry Challenges
- Validation engineering talent scarcity:ISO 11607 and FDA process qualification expertise concentrates among specialized consultants, extending project timelines.
- Legacy equipment integration:Automated sealers must interface with existing hospital inventory management and track-and-trace systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Tray Sealers Market |
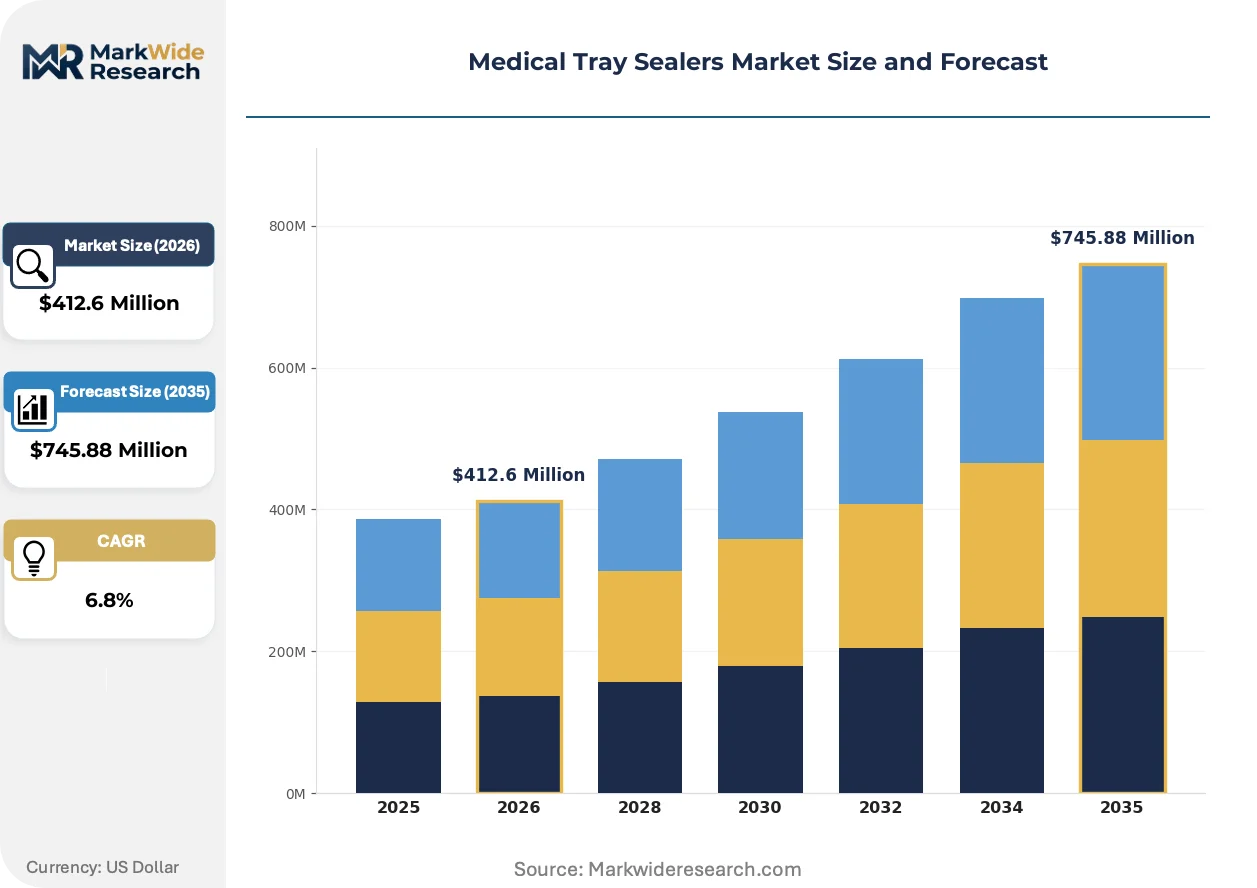
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Semi-Automatic Sealers, Fully Automatic Sealers, Manual Sealers, Hybrid Sealers Material: Plastic, Aluminum, Composite, Paper, Others End User: Hospitals, Laboratories, Clinics, Research Institutions Technology: Heat Sealing, Ultrasonic Sealing, Laser Sealing, Cold Sealing |
| Companies Covered | Multivac, Nelipak Healthcare, Atlas Vac Machine, SencorpWhite, Accu-Seal, Apex Packaging Corporation, Belco Packaging Systems, ULMA Packaging, Cama Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Tray Sealers Market Strategic Shifts
Equipment architecture is fragmenting from monolithic platforms toward modular configurations that separate sealing, vacuum-forming, and printing stations, enabling hospitals to phase capital deployment.
Ultrasonic sealing is electrifying sterile barrier formation for temperature-sensitive biologics by eliminating thermal degradation risk. Cell and gene therapy manufacturers are adopting this technology rapidly. The shift is compressing the addressable market for conventional heat-sealing equipment in advanced therapeutic packaging.
EU MDR Annex I general safety requirements are elevating sterile barrier documentation standards. Notified body interpretation is forcing manufacturers to demonstrate seal integrity across accelerated aging protocols. Class III device packaging operations in Germany and Ireland are responding by retrofitting automatic sealers with real-time seal strength monitoring.
Consolidated procurement through group purchasing organizations is concentrating buying power among US hospital systems. Independent facilities are losing negotiating leverage for capital equipment. The Midwest and Southeast regions show the most pronounced GPO concentration effects on sealer vendor selection criteria.
Medical Tray Sealers Market Segmentation
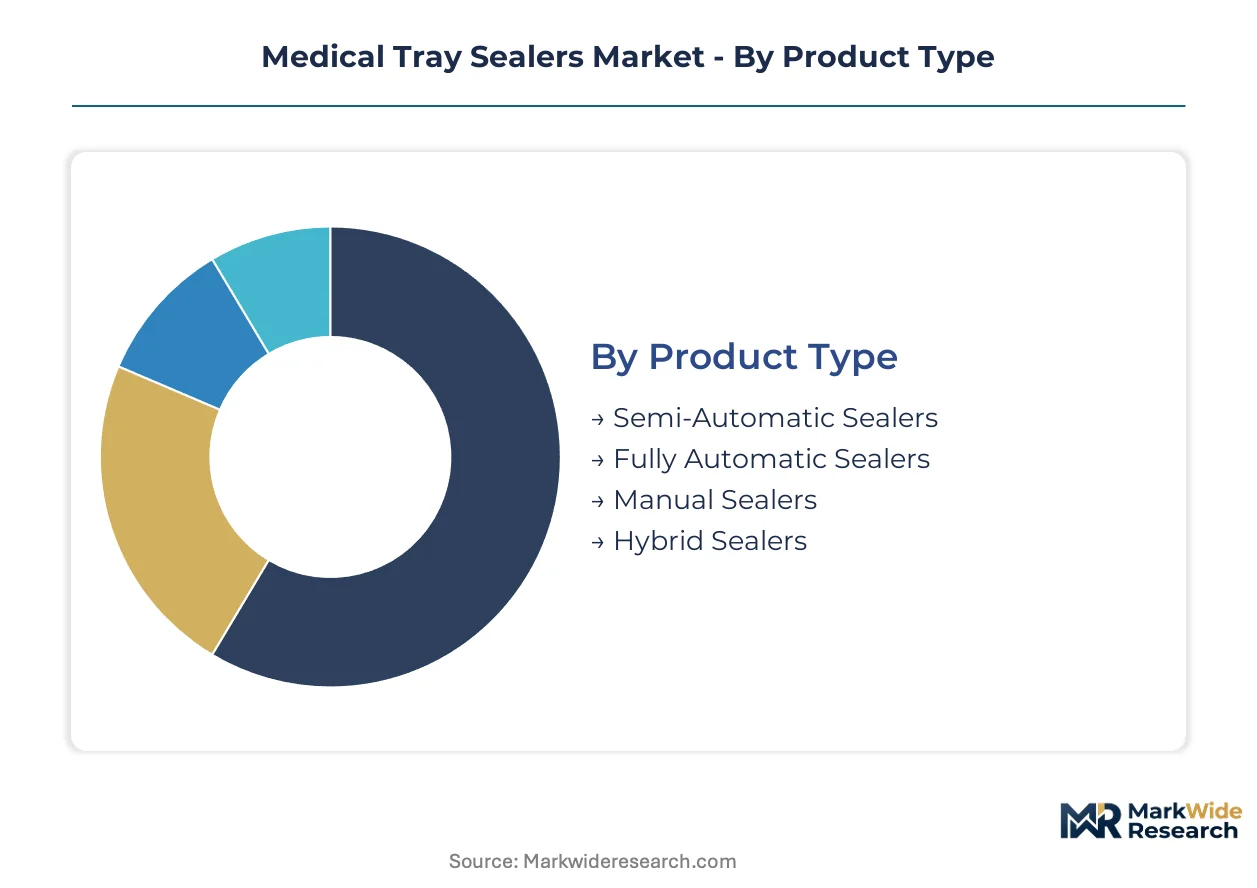
Medical tray sealer segmentation reveals how capital deployment priorities diverge between high-throughput hospital systems and smaller facilities with intermittent sterilization needs. Equipment architecture, material compatibility, and validation burden vary sharply across these divisions.
Product Type:
Standalone sealers dominate independent sterile processing departments, while integrated packaging lines embed sealing modules within automated reprocessing workflows.
- Fully Automatic Sealers:These systems execute tray loading, seal cycle execution, and documentation without operator intervention, achieving throughputs exceeding 200 trays hourly. Demand concentrates in United States hospital systems where FDA 21 CFR Part 820 enforcement mandates full process traceability for surgical kit packaging.
- Hybrid Sealers:Configurable platforms switch between manual loading and automated cycle execution based on batch size. Mid-size laboratories in Germany are adopting these units to avoid dedicated operator stations during off-peak hours while retaining flexibility for variable workload periods.
- Semi-Automatic Sealers:Require operator tray placement but automate seal parameter control; common in ambulatory surgery centers with moderate sterilization volumes.
- Manual Sealers:Hand-operated units with minimal validation documentation; regulatory pressure from EU MDR is compressing this segment's installed base.
Volume placements concentrate in fully automatic sealers; the faster expansion belongs to hybrid configurations.
Material:
Material selection tracks sterilization method compatibility and regulatory acceptance for specific device classifications.
- Plastic:Medical-grade polymers including PETG and HIPS dominate tray fabrication for ethylene oxide and gamma sterilization applications. Chinese hospital system modernization is accelerating demand for plastic-compatible sealers as tier-3 cities build surgical instrument reprocessing infrastructure.
- Composite:Multi-layer structures combining polymer barriers with breathable membranes address moisture-sensitive device packaging. Cell and gene therapy manufacturers in Ireland are specifying composite tray sealers for temperature-sensitive biologics where barrier integrity across accelerated aging protocols is mandatory.
- Aluminum:Rigid metal trays for steam sterilization with exceptional durability; concentrated in orthopedic instrument kits.
- Paper:Limited to lightweight single-use instruments; declining share as polymer barriers advance.
- Others:Bioabsorbable and coated specialty substrates for niche applications.
Plastic maintains the largest installed base; composite materials are climbing the fastest as advanced therapeutic packaging expands.
End User:
Facility scale determines throughput requirements and capital budget allocation for validation-capable equipment.
- Hospitals:Central sterile processing departments with 24-hour operation cycles and multi-specialty surgical volume. United States health systems are expanding capacity to address procedure backlogs, driving demand for high-throughput validated sealers with inventory management integration.
- Laboratories:Research and diagnostic facilities with batch-oriented processing needs. Point-of-care sterilization expansion in ambulatory settings is creating demand for compact footprint sealers with simplified qualification protocols.
- Clinics:Limited-volume outpatient facilities; price-sensitive segment with basic heat sealing predominance.
- Research Institutions:Academic medical centers with diverse protocol requirements; hybrid sealer adoption is highest here.
Hospital procurement dominates capital placements; research institutions are gaining share fastest as cell therapy manufacturing scales.
Technology:
Sealing mechanism selection balances thermal exposure limits against validation complexity and seal strength requirements.
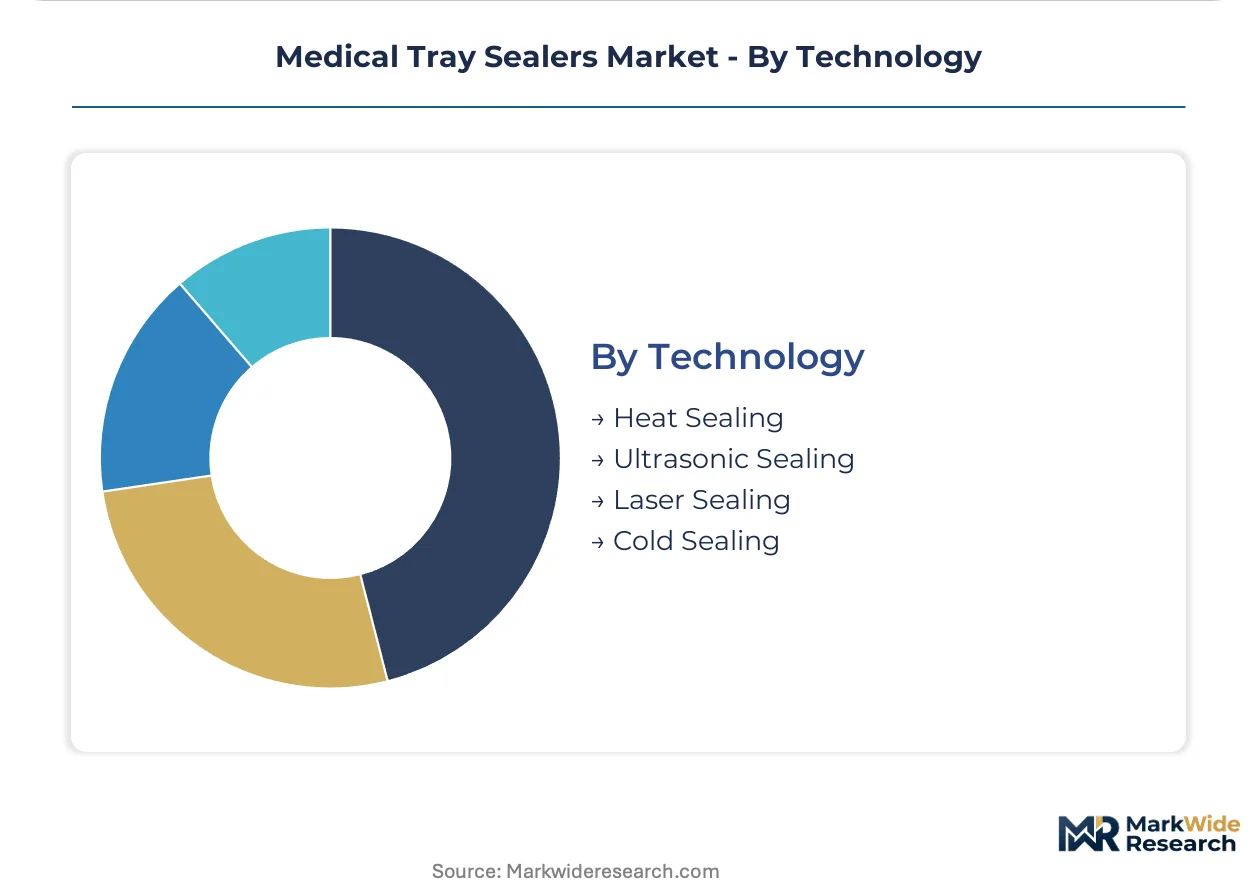
- Heat Sealing:Mature technology applying controlled temperature and pressure to bond lidding films; occupies the largest technology share due to lower validation burden and extensive ISO 11607 qualification history. German Class III device packaging operations are retrofitting heat sealers with real-time seal strength monitoring to satisfy notified body interpretation of EU MDR Annex I requirements.
- Ultrasonic Sealing:Non-thermal bonding through high-frequency mechanical vibration eliminates thermal degradation risk. Temperature-sensitive biologics packaging is accelerating adoption in pharmaceutical manufacturing where heat-labile products constrain process windows.
- Laser Sealing:Precision energy delivery for micro-device packaging; limited penetration due to capital intensity.
- Cold Sealing:Pressure-activated adhesive bonding for heat-sensitive materials; niche applications in diagnostic kit assembly.
Heat sealing retains dominant volume; ultrasonic technology is expanding most quickly as biologics packaging requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free-trade zones in Shanghai and Shenzhen concentrate medical device packaging equipment imports, creating distribution hubs that serve tier-3 hospital construction across China's interior provinces.
United States
Group purchasing organizations consolidate procurement for over 6,000 hospitals, concentrating vendor selection power among Midwest and Southeast health systems. FDA 21 CFR Part 820 enforcement mandates documented seal process qualification, accelerating replacement of manual sealers with validated automatic systems. Minneapolis and Boston clusters host central sterile processing equipment distributors serving the Great Lakes and Northeast surgical corridors.
Germany
Class III device manufacturers in Baden-Württemberg and Bavaria retrofit heat sealers with real-time monitoring to satisfy EU MDR Annex I sterile barrier documentation requirements. EU notified body interpretation of accelerated aging protocols forces capital upgrades in Frankfurt-Rhine-Main medical technology manufacturing. Stuttgart precision engineering suppliers fabricate PLC-controlled sealing heads for validated packaging lines.
China
Tier-3 city medical centers in Sichuan and Henan provinces build surgical instrument reprocessing infrastructure with imported validated packaging lines. NMPA medical device registration rules align with ISO 11607 standards, filtering domestic sealer suppliers without process qualification capabilities. Yangtze River Delta free-trade zones in Shanghai and Jiangsu concentrate equipment import and technical service operations.
Ireland
Cell and gene therapy manufacturers in Dublin and Cork specify composite tray sealers for temperature-sensitive biologics packaging. EMA centralized procedure requirements for advanced therapy medicinal products mandate barrier integrity across accelerated aging studies. Shannon Free Zone logistics infrastructure supports just-in-time delivery of lidding materials to pharmaceutical packaging operations.
Japan
Aging surgical infrastructure in Kanto and Kansai regions drives replacement demand for compact hybrid sealers with simplified qualification protocols. PMDA quality management system inspections emphasize process validation documentation for sterile barrier formation. Osaka precision machinery suppliers integrate sealing modules with hospital inventory management systems for orthopedic instrument kit operations.
Medical Tray Sealers Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across three distinct capability tiers. Large-scale packaging equipment manufacturers leverage integrated thermoforming-sealing platforms to anchor high-throughput hospital supply contracts. Mid-tier specialists compete through custom-engineered validation systems for central sterile processing departments. Consolidated procurement through group purchasing organizations concentrates buying power among United States health systems, compressing price negotiation leverage for independent facilities.
Among European-headquartered diversified manufacturers, Multivac and ULMA Packaging occupy positions representing integrated platform specialists with thermoforming-sealing capabilities. Nelipak Healthcare exemplifies the medical-grade polymer compatibility archetype, extending positioning across both capital equipment and consumables segments. Atlas Vac Machine represents the custom-engineered validation systems tier, serving central sterile processing departments with specialized vacuum-seal equipment.
| Leading Market Players |
|---|
| Multivac |
| Nelipak Healthcare |
| Atlas Vac Machine |
| SencorpWhite |
| Accu-Seal |
| Apex Packaging Corporation |
| Belco Packaging Systems |
| ULMA Packaging |
| Cama Group |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up specialists in medical packaging equipment have consolidated fragmented regional distributors across the United States and Germany, concentrating pricing power among three platform owners while compressing margin buffers for independent service providers and smaller OEMs competing on validation engineering.
Pricing Analysis
Margin tightening in standard-grade heat sealers reflects stainless steel and aluminum input volatility, with precision sealing head fabrication costs fluctuating alongside commodity markets. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated automatic systems with full process traceability from basic semi-automatic units and legacy manual equipment. Ambulatory surgery centers exhibit highest price sensitivity, prioritizing compact footprint over validation documentation, while Class III device manufacturers in Germany and Ireland absorb premium pricing for real-time seal strength monitoring to satisfy EU MDR Annex I requirements.
Supply Chain Analysis
Domestic-content mandates in China's tier-3 hospital construction programs are reshaping sourcing patterns for PLC and HMI modules, pressuring foreign equipment vendors to localize control system assembly in Jiangsu and Zhejiang provinces. Supply chain configuration draws heavily from German and Swiss automation suppliers for validated sealing heads, Japanese precision machinery for compact hybrid units, and Chinese fabrication for standard-grade components. Single-region dependency on Central European control systems creates vulnerability to export licensing delays. Distribution runs through Shanghai and Shenzhen free-trade zone hubs serving interior hospital construction, with technical service operations concentrated in Yangtze River Delta clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Validation engineering talent scarcity props pricing for qualified equipment, as ISO 11607 expertise concentrates among specialized consultants and extends commissioning timelines for automated sealers.
For Market Incumbents: Anticipate ultrasonic sealing technology displacement in temperature-sensitive biologics packaging by retrofitting heat-sealing platforms with modular upgrade paths and real-time monitoring capabilities. Consolidate position through backward integration into medical-grade polymer consumables, mirroring Nelipak Healthcare's dual-equipment-consumables model, while defending hospital system contracts against emerging Chinese vendors with localized validation support. For New Entrants and Emerging Players: Group purchasing organization channel partners offer the most viable entry vector for mid-scale hybrid sealers targeting Midwest and Southeast United States health systems seeking flexible batch processing. White-space concentrates in point-of-care sterilization expansion at ambulatory surgery centers requiring simplified qualification protocols, and in Chinese tier-3 city medical centers building first-generation reprocessing infrastructure with imported validated packaging lines. For Investors and Strategic Acquirers: Distressed-cycle entries favor custom-engineered validation system specialists in Germany and the United States with established FDA 510(k) predicate histories and EU notified body relationships. Long-term viability hinges on software companion development for inventory management integration and predictive maintenance. Watch EU Green Deal packaging mandates as the inflection signal for recyclable lidding material compatibility requirements favoring adjustable-parameter equipment architectures.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission Pathway | 510(k) predicate strategies accelerate hospital system procurement cycles in United States markets. |
| CE Marking Pathway | Notified body relationships under EU MDR compress validation timelines for Class III device packaging. |
| Hospital System Partnership | GPO contract penetration secures multi-year equipment refresh cycles across integrated delivery networks. |
| Software Companion Development | Inventory management integration addresses legacy equipment interoperability challenges in sterile processing departments. |
| Reimbursement Strategy | Procedure volume recovery documentation supports capital expenditure justification for central sterile processing expansion. |
Study Parameters
Document review covered FDA 510(k) filings, EU MDR technical documentation, ISO 11607 guidance interpretations, and hospital procurement database records, complemented by interviews with central sterile processing directors, biomedical engineers, GPO contracts managers, and validation engineering consultants. Secondary sources included SEC filings from diversified packaging equipment manufacturers, NMPA registration databases for Chinese market entrants, and trade customs data for equipment import flows. Bottom-up equipment placement estimates triangulated against top-down surgical procedure volume projections.
Cross-referencing historical installation patterns against expert panel input on capital refresh cycles shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, material compatibility, end-user facility scale, and sealing technology type, with regional regulatory clusters capturing FDA, EU MDR, NMPA, and PMDA compliance pathways. CAGRs derived from surgical volume recovery trajectories, sterile processing capacity expansion plans, and equipment replacement rates for legacy manual sealers.
Caveats apply where EU notified body interpretation shifts, Chinese domestic-content mandate enforcement intensity, or ultrasonic sealing technology cost curves could materially shift the outlook for conventional heat-sealing equipment demand. Forecasts reflect assumptions regarding surgical backlog resolution, commodity input stability, and validation engineering labor availability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices Packaging
Surgical Instruments Packaging Market
Medical Devices Packaging
Middle East and Africa Parenteral Packaging Market
Medical Devices Packaging
Medical-Grade Foil Market
Medical Devices Packaging
Syringe Trays Market
Medical Devices Packaging
US Home Care Packaging Market
Medical Devices Packaging
Global Medical Packaging Market
Medical Devices Packaging
Asia-Pacific Parenteral Packaging Market
Medical Devices Packaging
Middle East and Africa Medical Devices Packaging Market
Medical Devices Packaging
Multi-Med Adherence Packaging Market
Medical Devices Packaging
Medical Implants Sterile Packaging Market
Medical Devices Packaging
Asia-Pacific Medical Devices Packaging Market
Medical Devices Packaging
Bio-Medical Packaging Market
Medical Devices Packaging
Medical Containers Market
Medical Devices Packaging
Medical Processing Seals (MPS) Market
Medical Devices Packaging
North America Parenteral Packaging Market
Medical Devices Packaging
Ethylene-Vinyl Acetate [EVA] Infusion Bags Market