
 United States Aesthetic Devices Market | 2026-2036
United States Aesthetic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
United States Aesthetic Devices Market Analytics
Silicone is decoupling from facial implant portfolios as hyaluronic acid formulations capture margin in injectable suites. AbbVie (Allergan Aesthetics) leverages its Juvederm manufacturing scale to dominate dermal filler supply chains. Cynosure anchors its position through specialized laser platforms for skin resurfacing. Alma Lasers competes across multiple energy modalities with integrated cooling systems.
United States aesthetic devices comprise electromechanical and energy-delivery systems engineered to modify soft tissue through thermal, mechanical, or pharmacological action, typically operating at wavelengths between 532 nm and 10,600 nm with pulse durations calibrated to target chromophores or collagen structures. These systems serve commercial purposes in elective cosmetic procedures, reconstructive applications, and dermatological treatments performed in clinical settings. Laser devices command the largest installed base due to decade-long reimbursement familiarity and versatile platform configurations. Radiofrequency devices represent the fastest-expanding category as fractional delivery systems penetrate medical spa channels. Injectables retain the densest margin pools despite capital-light deployment models.
FDA premarket notification requirements under 21 CFR 878 shape device commercialization timelines for laser and radiofrequency systems, while OSHA workplace safety standards govern clinic operator certification and facility compliance. The Federal Trade Commission monitors advertising claims for energy-based devices, creating enforcement risk for unsubstantiated efficacy statements. Stakeholders must monitor evolving FDA guidance on software-as-medical-device classifications for AI-enhanced imaging platforms.
Market Dynamics
FDA premarket notification pathways for energy-based aesthetic systems have tightened substantially, extending commercialization timelines and forcing manufacturers to front-load clinical validation investments before 510(k) submissions.
Growth Catalysts
- Medical spa channel expansion:Standalone aesthetic clinics in Texas and Florida are doubling device footprints as patient volumes surge beyond dermatology office capacity.
- Hyaluronic acid formulation advances:Cross-linked injectable suites are capturing facial implant volumes previously served by silicone-based permanent solutions.
- OSHA operator certification mandates:Standardized laser safety training requirements are professionalizing clinic workforces and reducing liability exposure for energy-based procedure adoption.
Market Restraints
- Capital intensity of fractional RF platforms:Medical spas face equipment financing hurdles as advanced radiofrequency systems require six-figure capital commitments with extended payback periods.
- Input concentration in laser crystal supply:Nd:YAG and erbium-doped gain media production concentrates among limited specialty optical suppliers, creating vulnerability for domestic device assembly.
- Technical limitation in melanin-safe wavelengths:Existing 755 nm alexandrite and 1,064 nm Nd:YAG platforms struggle to deliver consistent outcomes across Fitzpatrick skin types IV-VI without epidermal injury risk.
Strategic Opportunities
- Underpenetrated Midwest corridors:Ohio and Illinois medical spa density lags California and Florida by substantial margins, presenting whitespace for device placement expansion.
- AI-enhanced imaging convergence:Machine learning algorithms paired with multispectral cameras are enabling pre-treatment simulation capabilities that reduce consultation friction and improve conversion rates.
- Telemedicine-integrated consultation models:Remote aesthetic assessment platforms are opening suburban and rural patient funnels previously inaccessible to urban clinic networks.
Industry Challenges
- Laser safety officer talent scarcity:OSHA-compliant certification programs produce insufficient qualified technicians to match medical spa expansion velocity, creating hiring bottlenecks.
- Software-as-medical-device classification uncertainty:FDA guidance evolution on AI-enhanced treatment planning algorithms is creating compliance timeline ambiguity for platform developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Aesthetic Devices Market |
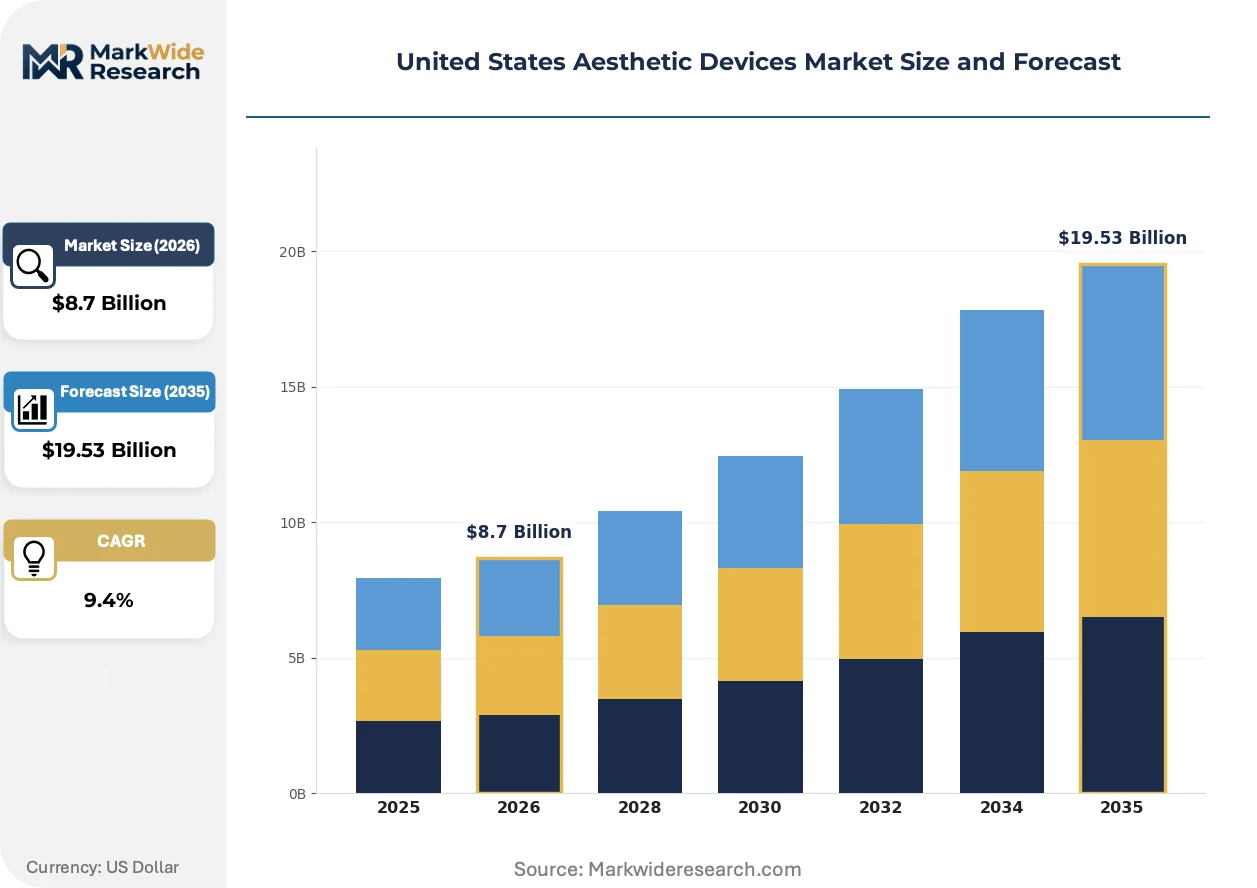
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectables, Laser Devices, Radiofrequency Devices, Microneedling Devices End User: Dermatology Clinics, Plastic Surgery Centers, Medical Spas, Cosmetics Retailers Technology: Non-Invasive Technology, Minimally Invasive Technology, Advanced Imaging Technology, Energy-Based Technology Application: Skin Rejuvenation, Body Contouring, Hair Removal, Acne Treatment |
| Companies Covered | AbbVie (Allergan Aesthetics), Cynosure, Lumenis, Bausch Health, Alma Lasers, Candela Medical, Cutera, InMode, Merz Aesthetics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Aesthetic Devices Market Evolving Landscape
Radiofrequency fractional delivery systems are compressing treatment intervals and broadening addressable patient populations, while software-enabled platforms are redefining device differentiation beyond raw hardware specifications.
Picosecond-domain laser technology is expanding into tattoo removal and benign pigmented lesion applications through pulse duration compression that minimizes thermal diffusion. Dermatology clinics in California are adopting these platforms at accelerated replacement cycles compared to nanosecond legacy systems. The structural consequence is expanding into melanin-rich skin type safety profiles that previously excluded significant patient demographics from laser procedures.
FDA 510(k) premarket notification requirements under 21 CFR 878 are intensifying clinical data expectations for energy-based systems with software-controlled dose modulation. Device manufacturers now face extended validation timelines and expanded predicate device comparison burdens. Laser and radiofrequency segments are responding through earlier-stage physician advisory board engagement to preempt regulatory review objections.
Subscription-based device access models are displacing outright capital purchases among independent medical spa operators facing cash flow constraints. Equipment financing entities and manufacturer captive finance arms are capturing channel margin previously held by traditional distributors. This shift concentrates most visibly in Florida and Texas where franchise clinic networks prioritize balance sheet flexibility over ownership.
United States Aesthetic Devices Market Segmentation
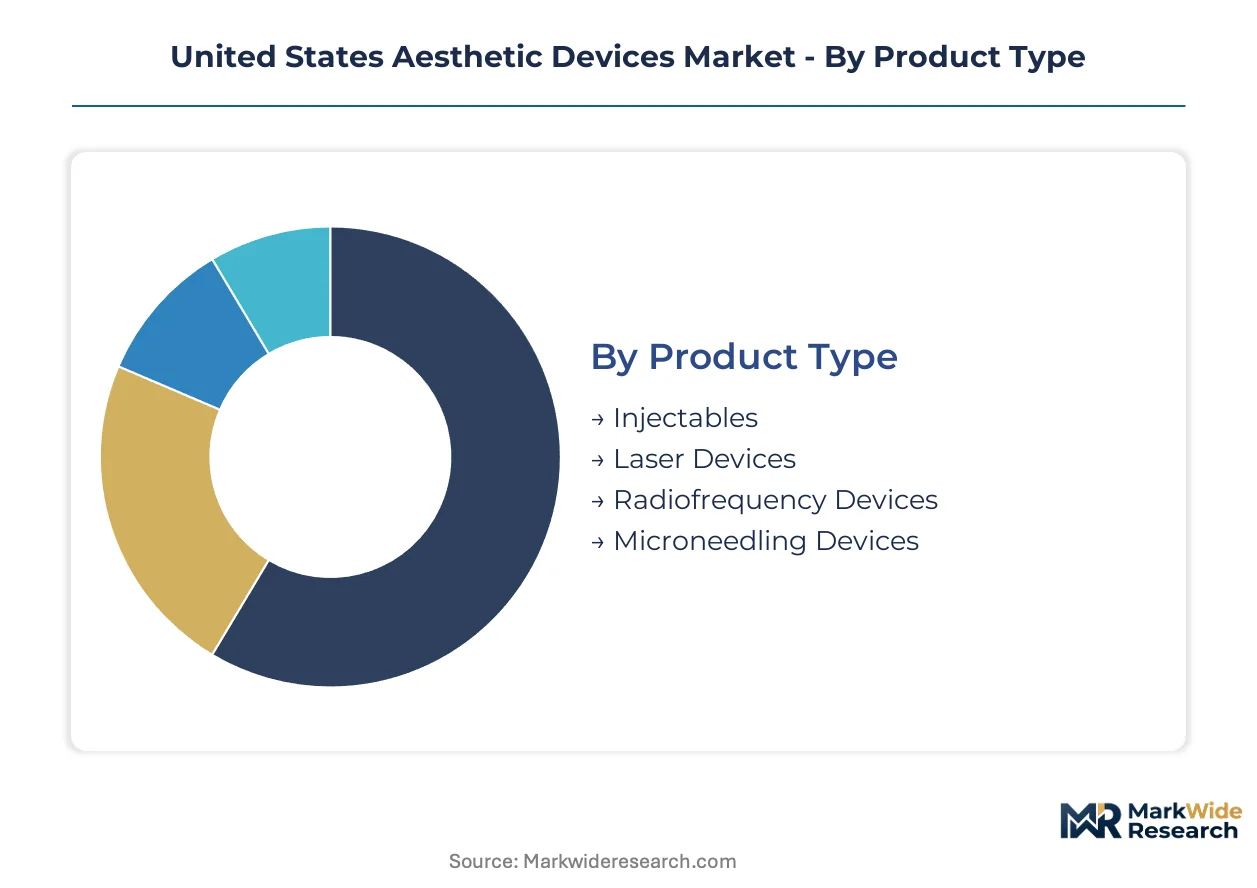
Device segmentation in the United States aesthetic market reveals divergent capital requirements, regulatory pathways, and margin structures across product categories. Understanding these distinctions enables precise resource allocation for manufacturers and clinic operators navigating procurement decisions.
Product Type:
Laser devices demand the heaviest upfront capital commitment, with installed platforms requiring six-figure investments and specialized facility infrastructure. Injectables operate at the opposite extreme, generating dense margin pools through minimal capital deployment.
- Laser Devices:Energy-delivery systems operating between 532 nm and 10,600 nm wavelengths target chromophores through thermal action. California dermatology clinics are accelerating replacement cycles for picosecond-domain platforms that expand safe treatment to Fitzpatrick skin types IV-VI.
- Radiofrequency Devices:Fractional delivery systems penetrate tissue through resistive heating without optical wavelength dependence. Texas and Florida medical spas are doubling device footprints as patient volumes surge beyond traditional clinic capacity, though six-figure financing requirements constrain independent operators.
- Injectables:Hyaluronic acid formulations dominate facial volume applications with minimal facility investment.
- Microneedling Devices:Mechanical penetration systems serve entry-level aesthetic channels with lower regulatory barriers.
Most installed capacity flows through laser devices. Expansion is steepest in radiofrequency devices.
End User:
Customer type segmentation tracks divergent procurement sophistication, with hospital-affiliated centers demanding comprehensive service contracts while independent spas prioritize financing flexibility.
- Dermatology Clinics:Physician-supervised facilities anchor laser device demand through established reimbursement familiarity and clinical validation requirements. These settings concentrate in California, Texas, and Florida where medical spa density already exceeds national averages.
- Medical Spas:Standalone aesthetic clinics are professionalizing rapidly under OSHA laser safety officer mandates, though talent scarcity creates hiring bottlenecks that constrain expansion velocity in Ohio and Illinois corridors.
- Plastic Surgery Centers:Hospital-affiliated and independent surgical facilities integrate energy-based systems into combined procedure protocols.
- Cosmetics Retailers:Non-clinical channels face FDA jurisdiction boundaries that limit device category access.
Dermatology clinics retain the densest installed base. Medical spas are climbing the fastest.
Technology:
Technology segmentation distinguishes regulatory classification intensity, with software-enabled platforms facing evolving FDA guidance on artificial intelligence integration.
- Energy-Based Technology:Laser and radiofrequency systems dominate commercial revenue through thermal tissue modification. FDA 510(k) premarket notification requirements under 21 CFR 878 are intensifying clinical data expectations for dose modulation capabilities.
- Non-Invasive Technology:Surface-level treatment modalities address patient preference for zero-downtime procedures. Demand concentrates in suburban expansion corridors where consultation friction reduction drives conversion optimization.
- Minimally Invasive Technology:Penetrating delivery systems balance efficacy with recovery considerations.
- Advanced Imaging Technology:Multispectral cameras paired with machine learning algorithms enable pre-treatment simulation capabilities.
Energy-based platforms command the largest revenue share. Advanced imaging is gaining share fastest.
Application:
Application segmentation correlates with demographic addressability, with body contouring expanding patient populations beyond traditional facial aesthetic consumers.
- Skin Rejuvenation:Collagen remodeling procedures through laser resurfacing and radiofrequency tightening represent the most mature application category. Picosecond-domain technology is compressing treatment intervals while improving safety profiles across diverse skin types.
- Hair Removal:Laser-based permanent reduction retains high procedure volume despite wavelength limitations for melanin-rich skin. Technical constraints at 755 nm alexandrite and 1,064 nm Nd:YAG platforms create unmet demand in underserved demographics.
- Body Contouring:Non-invasive fat reduction and skin tightening applications.
- Acne Treatment:Energy-based and pharmacological interventions for active disease and scarring.
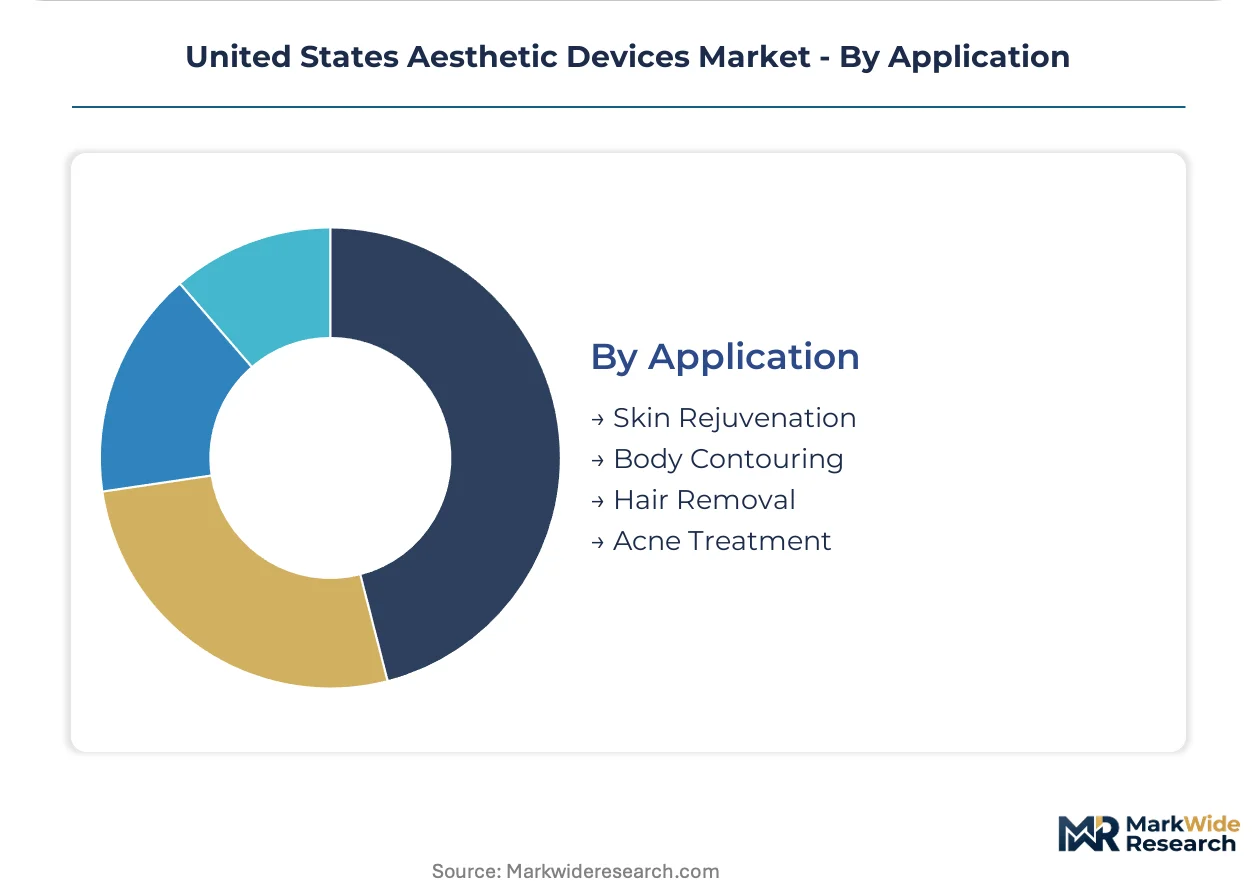
Skin rejuvenation procedures generate the highest treatment volume. Body contouring shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's medical corridor anchors United States aesthetic device demand through concentrated dermatology clinic networks and elevated medical spa density. The state's regulatory environment under FDA and OSHA frameworks shapes national compliance benchmarks. Geographic expansion patterns reveal substantial whitespace in secondary metropolitan clusters.
California
Los Angeles and San Francisco Bay Area medical spas drive picosecond laser platform adoption at accelerated replacement cycles. FDA 510(k) premarket notification requirements under 21 CFR 878 intensify clinical validation burdens for energy-based systems seeking clearance. Beverly Hills and Newport Beach dermatology clusters concentrate fractional radiofrequency device placements as patient volumes exceed traditional clinic capacity.
Texas
Dallas-Fort Worth and Houston standalone aesthetic clinics are doubling device footprints as suburban patient demand surges beyond dermatology office capacity. OSHA laser safety officer certification mandates professionalize clinic workforces while creating hiring bottlenecks that constrain expansion velocity. Austin medical spa networks prioritize subscription-based device access models over capital purchases to preserve balance sheet flexibility.
Florida
Miami and Tampa Bay franchise clinic networks dominate injectable suite deployments while expanding into energy-based modalities. FTC advertising claim enforcement creates compliance risk for unsubstantiated efficacy statements in competitive coastal markets. Orlando medical spa corridors show the steepest radiofrequency device placement growth as financing entities capture channel margin through captive lease structures.
Illinois
Chicago metropolitan medical spa density lags California and Florida by substantial margins, presenting whitespace for device placement expansion. Illinois Department of Public Health facility licensing requirements parallel federal OSHA standards for laser operator certification. Suburban Cook County and DuPage County clinic networks are adopting telemedicine-integrated consultation models to access previously unreachable patient funnels.
New York
Manhattan and Long Island dermatology clinics retain dense installed bases of legacy nanosecond laser platforms awaiting replacement cycles. New York State Department of Health oversight of office-based surgery facilities adds regulatory layering to energy-based procedure adoption. Buffalo and Rochester medical spa channels remain underpenetrated relative to coastal demand concentrations, creating distribution expansion opportunities.
United States Aesthetic Devices Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers expand across energy modalities and injectable formulations. The vendor base concentrates among integrated aesthetics conglomerates and specialized laser platform developers. Three strategic archetypes define competitive positioning: pharmaceutical-backed device distributors, pure-play energy technology specialists, and hybrid injectable-device portfolio managers. M&A activity and technology licensing agreements represent the primary competitive moves as firms seek predicate device portfolios for accelerated FDA pathways.
Within the pharmaceutical-backed tier, AbbVie through its Allergan Aesthetics unit and Bausch Health exemplify scale-driven distribution architectures that leverage manufacturing volume for supply chain control. Among specialized energy platform developers, Cynosure, Lumenis, and Alma Lasers occupy positions defined by wavelength specialization and integrated cooling system differentiation. These entities represent contrasting strategic postures: conglomerate-backed players prioritize injectable-device bundling, while independent specialists concentrate on fractional delivery innovation and software-enabled treatment planning capabilities.
| Leading Market Players |
|---|
| AbbVie (Allergan Aesthetics) |
| Cynosure |
| Lumenis |
| Bausch Health |
| Alma Lasers |
| Candela Medical |
| Cutera |
| InMode |
| Merz Aesthetics |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between FDA-cleared energy systems and non-cleared aesthetic devices manifests in divergent pricing architectures and procurement channel configurations. Premium laser and radiofrequency platforms command six-figure capital commitments through specialized distributor networks, while entry-level microneedling systems flow through direct-to-clinic arrangements with compressed margin structures.
Pricing Analysis
Input-cost pass-through from Nd:YAG and erbium-doped laser crystal suppliers concentrates pricing power among specialty optical manufacturers. Three-tier pricing structure across premium, standard, and economy levels tracks FDA clearance status, cooling system integration depth, and software-enabled treatment planning capabilities. Pricing pressure stems from subscription-based device access models displacing outright purchases among independent medical spa operators. Medical spa franchise networks exhibit highest price sensitivity due to cash flow constraints, while hospital-affiliated plastic surgery centers demonstrate lowest sensitivity given captive financing access.
Supply Chain Analysis
FDA 510(k) premarket notification requirements under 21 CFR 878 gate component qualification timelines for laser and radiofrequency system assemblers. Nd:YAG and erbium-doped gain media production concentrates in Germany, Japan, and the United States, creating geographic dependency for critical optical inputs. Domestic device assembly draws from specialty crystal suppliers, integrated cooling module manufacturers, and software control system developers. Single-source vulnerability in laser crystal supply creates disruption risk for fractional platform production. Distribution runs through manufacturer-direct sales forces serving dermatology clinics, with independent distributors capturing medical spa channel margin in Texas and Florida.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
United States aesthetic device procurement patterns reward geographic arbitrage between OSHA-compliant coastal corridors and underpenetrated Midwest markets where regulatory compliance costs lag California and Florida by substantial margins.
For Market Incumbents: Hedge against software-as-medical-device classification uncertainty by accelerating FDA pre-submission engagement for AI-enhanced treatment planning algorithms. Deepen backward integration into laser crystal supply through captive sourcing agreements with German and Japanese optical manufacturers. Channel control investments in subscription-based financing arms capture margin displacement from traditional distributors. For New Entrants and Emerging Players: Launch via telemedicine-integrated consultation platforms targeting suburban Chicago and upstate New York corridors where medical spa density lags coastal benchmarks. White-space concentration in Ohio and Illinois standalone aesthetic clinics presents lowest competitive intensity for fractional radiofrequency device placement. Go-to-market execution should prioritize OSHA laser safety officer certification bundling to preempt hiring bottlenecks. For Investors and Strategic Acquirers: Asymmetric upside sits with hybrid injectable-device portfolio managers positioned for cross-selling synergies. Long-term viability hinges on predicate device accumulation for accelerated FDA 510(k) pathways. Acquisition target archetype: specialized energy platform developers with picosecond-domain intellectual property and established physician advisory board relationships. Signal to watch is FDA guidance finalization on AI-enhanced imaging classifications.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Premarket Submission | Accelerates commercialization timelines for energy-based systems with established predicate comparisons. |
| Physician Advisory Board Engagement | Preempts regulatory review objections through early-stage clinical validation protocol design. |
| Subscription-Based Device Financing | Captures medical spa channel margin previously held by independent equipment distributors. |
| Laser Safety Officer Certification Program | Addresses OSHA talent scarcity constraining clinic expansion velocity in underpenetrated corridors. |
| AI-Enhanced Imaging Platform Development | Enables pre-treatment simulation capabilities that reduce consultation friction and improve conversion. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement captured perspectives from dermatology clinic operators, medical spa franchise development executives, biomedical engineers at device manufacturers, GPO contracts managers, and OSHA laser safety officers. Secondary validation drew from FDA 510(k) premarket notification filings, CMS procedure volume databases, state medical board licensing records, and medical spa facility registration data. Bottom-up installed base modeling and top-down revenue triangulation converged on segment-level estimates.
Segment-weighting approaches distributed total market value across laser devices, radiofrequency systems, injectables, and microneedling platforms, with further subdivision by end-user category and technology intensity. CAGRs were derived from procedure volume growth trajectories, replacement cycle compression patterns, and channel expansion rates across the projection horizon. Industry-specific forecast inputs included medical spa density differentials by metropolitan statistical area and FDA clearance pipeline status for software-enabled platforms.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated FDA software-as-medical-device reclassification or sustained laser crystal supply disruption. Projections reflect documented assumptions regarding OSHA enforcement consistency and medical spa financing availability. A model refresh is warranted upon material change in FDA guidance timelines for AI-enhanced treatment planning algorithms.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Syringe Pumps Market
Medical Devices
China Artificial Organs and Bionic Implants Market
Medical Devices
Global Trauma Fixation Devices Market
Medical Devices
Dialysis Catheters Market
Medical Devices
South Africa Digital X-Ray Devices Market
Medical Devices
Wireless Portable Medical Devices Market
Medical Devices
Artificial Eye Market
Medical Devices
Manual Wheelchair Market
Medical Devices
Automated Insulin Delivery Device Market
Medical Devices
Minimally Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Indonesia Devices Market
Medical Devices
Spinal Trauma Devices Market
Medical Devices
Tracheostomy Tubes Market
Medical Devices
Urinary Incontinence Devices Market
Medical Devices
Americas Wearable Medical Device Market
Medical Devices
Global Limb Prosthetics Market