
 Mechanical Performance Tuning Components Market | 2026-2036
Mechanical Performance Tuning Components Market Size, Share, and Industry Trends Forecast 2026-2036
Mechanical Performance Tuning Components Market Outlook
Carbon fiber is hardening its position as the preferred reinforcement in high-performance intake manifolds and turbocharger housings, displacing heavier aluminum castings across premium tuning tiers. Robert Bosch GmbH leverages its injection-molding expertise to supply composite intake plenums for European racing programs. Brembo S.p.A. anchors its aftermarket dominance through forged aluminum brake caliper architectures that withstand sustained thermal cycling on track days.
Mechanical performance tuning components comprise engineered subsystems—exhaust systems, forced-induction hardware, engine management modules, and intake pathways—that modify factory powertrain output, thermal efficiency, or acoustic signature beyond original equipment specifications. These assemblies typically operate at elevated combustion pressures, often exceeding 2.0 bar absolute in turbocharged configurations, and serve both competitive motorsport and consumer street-performance applications. Turbochargers command the largest value share among component types due to their dual role in OEM downsizing strategies and aftermarket power augmentation, while ECU tuners represent the fastest-expanding category as flash-based calibration tools democratize engine remapping. Stainless steel retains volume leadership in exhaust fabrication for its oxidation resistance, though titanium and Inconel alloys capture margin pools in professional racing exhausts where weight reduction justifies material premiums.
The EPA enforces emissions compliance for aftermarket catalytic converters and exhaust modifications under Clean Air Act Title II, compelling suppliers to certify hardware for OBD-II compatibility and tailpipe pollutant thresholds. California Air Resources Board executive orders create a de facto national benchmark, as tuners seeking statewide legality must submit components for laboratory emissions validation. NHTSA's Federal Motor Vehicle Safety Standards further govern structural integrity of suspension and braking modifications, limiting geometry alterations that compromise crashworthiness. Stakeholders must monitor evolving state-level preemption debates and electrification carve-outs that could redefine compliance boundaries for internal-combustion tuning hardware.
Market Dynamics
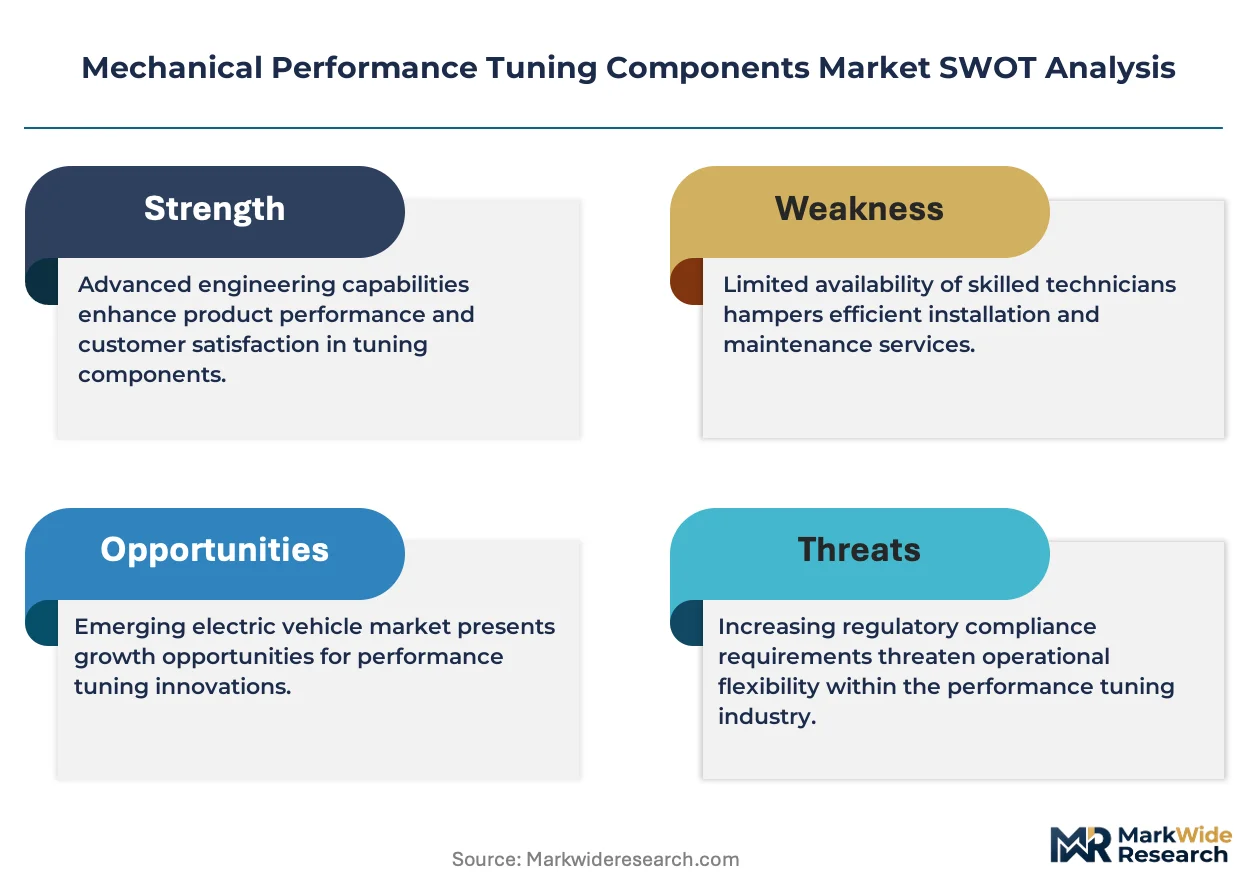
Stringent emissions enforcement is compressing the addressable market for internal-combustion tuning hardware while simultaneously concentrating supplier investment toward compliant component architectures that satisfy dual-use motorsport and limited street-legality requirements.
Growth Catalysts
- EPA Title II certification pathways:Aftermarket catalytic converters achieving OBD-II compatibility unlock California Air Resources Board executive orders, creating a de facto national compliance standard that expands legal installation bases.
- Track-day participation:Closed-circuit motorsport programs in Germany, Japan, and the United States generate sustained demand for non-street-legal exhaust and forced-induction configurations exempt from tailpipe regulations.
- Carbon fiber reinforcement:Composite intake plenums and turbocharger housings reduce rotational mass and thermal lag, enabling power density gains that justify premium pricing tiers in amateur racing segments.
Market Restraints
- Titanium and Inconel input costs:Professional racing exhaust fabrication depends on aerospace-grade alloy supply chains concentrated in specialty foundries, exposing margins to volatile nickel and vanadium spot markets.
- KBA type-approval protocols:Germany's Federal Motor Transport Authority mandates extensive durability testing for modified powertrain components, extending product development cycles and raising barrier-to-entry capital requirements.
- Electrification substitution:Battery-electric powertrains eliminate the addressable hardware base for traditional tuning components, compressing long-term demand visibility for piston-engine aftermarket suppliers.
Strategic Opportunities
- Software-defined calibration tools:Flash-based ECU remapping platforms enable recurring revenue models through over-the-air updates, shifting value capture from hardware sales toward subscription maintenance.
- Hydrogen combustion retrofits:Emerging H2-ICE conversion kits for existing performance engines create a transitional hardware category bridging fossil-fuel tuning expertise with zero-emission powertrain architectures.
- Direct-to-consumer channel expansion:Specialized e-commerce platforms bypass traditional distributor markups in Australia and Canada, capturing margin expansion while accelerating technical support response times.
Industry Challenges
- Calibration engineering talent scarcity:The intersection of combustion physics, embedded systems, and emissions chemistry requires specialized skill sets concentrated among aging OEM powertrain veterans.
- Homologation timeline compression:Accelerating regulatory revision cycles in the European Union force suppliers to maintain parallel certification tracks, fragmenting R&D resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mechanical Performance Tuning Components Market |
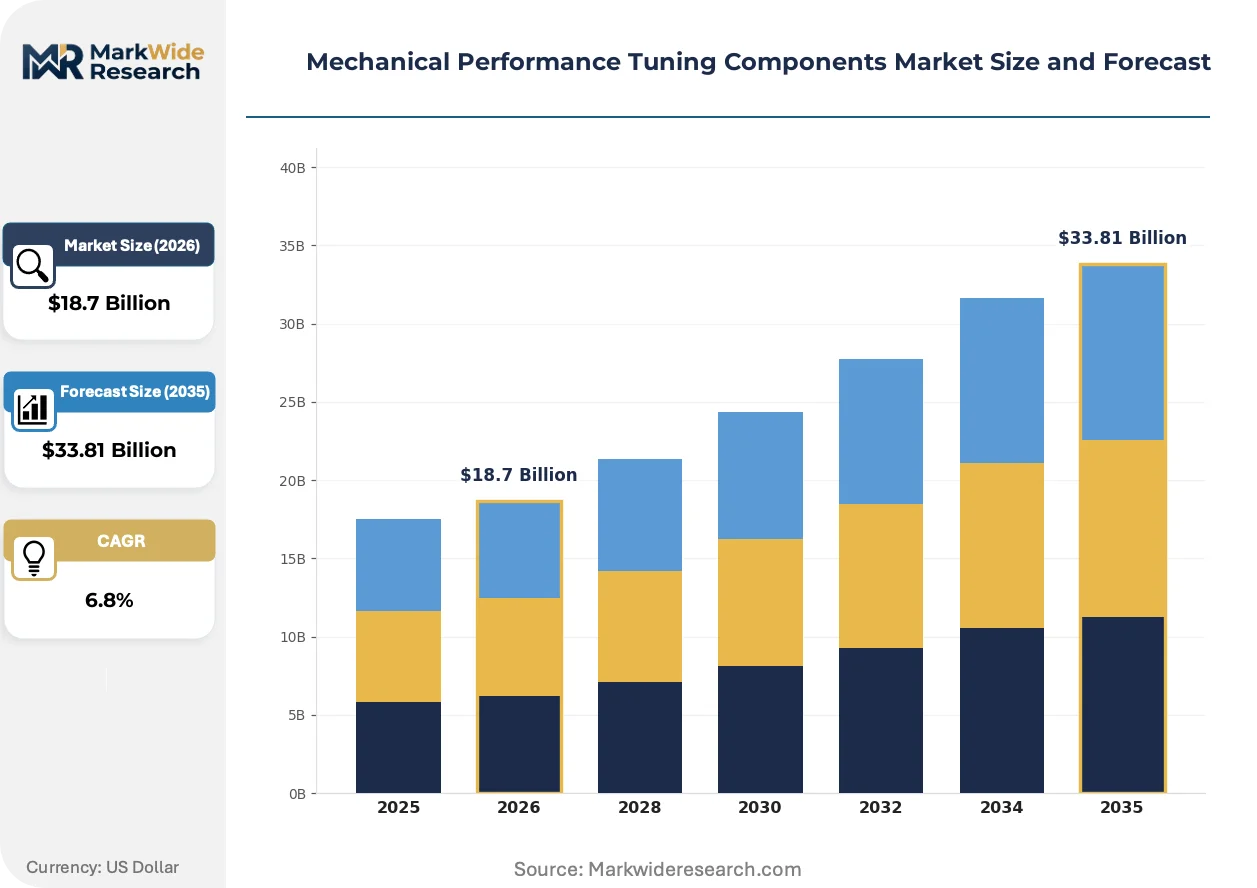
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Exhaust Systems, Cold Air Intakes, Turbochargers, ECU Tuners Material: Aluminum, Stainless Steel, Composite, Plastic Application: Automotive Racing, Street Performance, Off-Roading, Marine End User: OEMs, Aftermarket Tuners, Auto Enthusiasts, Commercial Fleets |
| Companies Covered | Robert Bosch GmbH, ZF Friedrichshafen AG, Continental AG, BorgWarner, Brembo S.p.A., Holley Performance Products Inc., Magna International, Valeo, DENSO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mechanical Performance Tuning Components Market Strategic Shifts
Active thermal management and additive manufacturing are converging to redefine component performance boundaries, while regulatory bifurcation between street and track applications forces suppliers to architect dual-purpose product lines.
Additive-manufactured titanium exhaust manifolds with conformal cooling channels are consolidating production workflows for low-volume racing hardware. Porsche Motorsport and Ferrari Corse Clienti programs now specify electron-beam-melted titanium collectors that withstand exhaust gas temperatures exceeding 1050°C while reducing wall thickness by 40 percent versus traditional fabrication. This process consolidation compresses lead times from twelve weeks to under four for prototype batches.
The European Union's F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in charge-air cooling systems, compelling suppliers to validate CO2-based secondary loops or ambient air-to-liquid heat exchangers. Tier-1 thermal management specialists are retooling test benches to accommodate transcritical R-744 pressures above 100 bar. Motorsport applications in Belgium and Italy face accelerated compliance deadlines that predate consumer automotive requirements.
Collector car restoration shops are unbundling turnkey engine rebuilds into component-level sourcing decisions, creating spot-market volatility for period-correct carburetors and mechanical ignition distributors. This procurement fragmentation concentrates price discovery on specialized auction platforms rather than traditional jobber networks. The phenomenon is most pronounced in Southern California and England's Home Counties, where vintage Porsche and Jaguar specialists maintain captive inventories of NLA hardware.
Mechanical Performance Tuning Components Market Segmentation
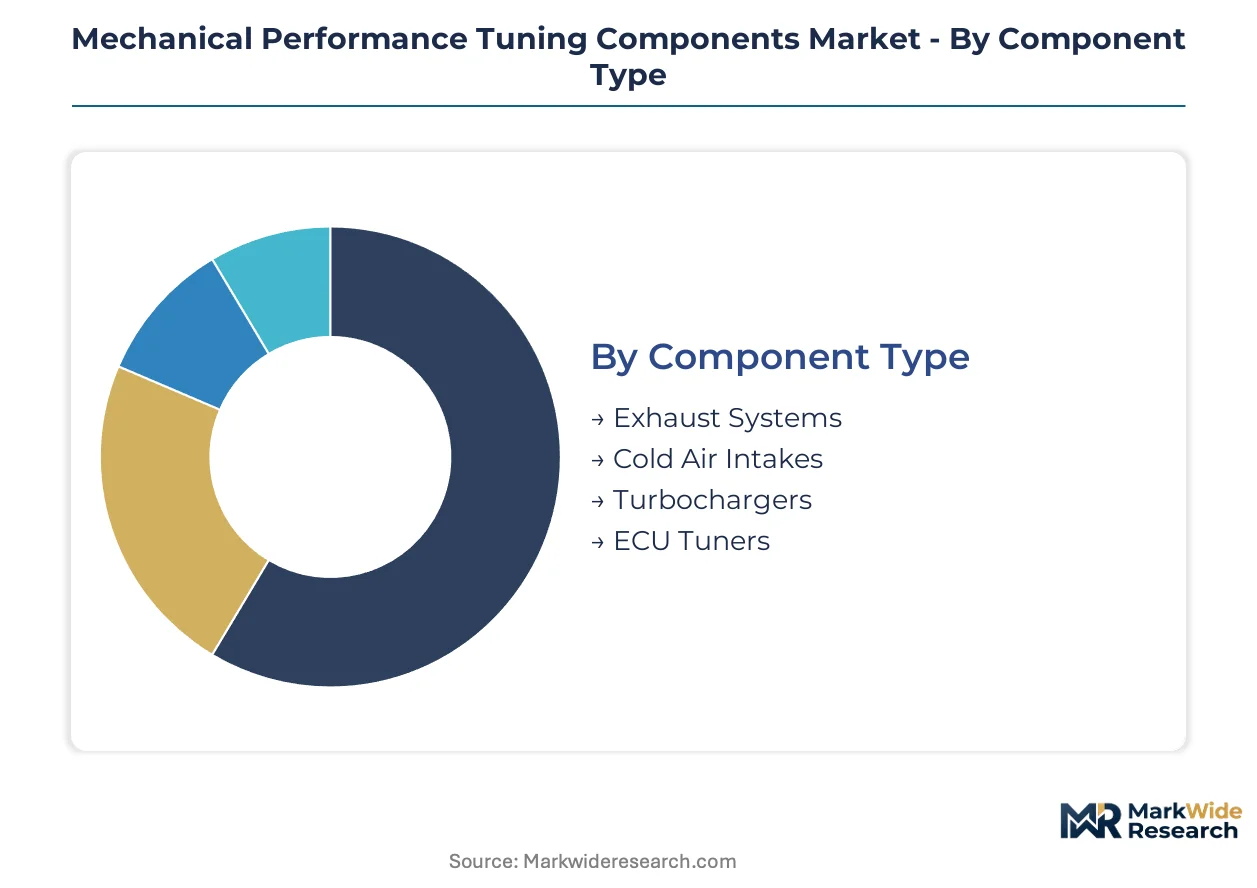
Component categorization in this market reveals distinct integration architectures. Some segments function as bolt-on replacements requiring minimal calibration, while others demand deep powertrain integration and software co-development. Understanding these integration depths clarifies procurement patterns and margin distribution across supplier tiers.
Component Type:
Standalone hardware dominates volume tiers, whereas embedded electronic systems command premium positioning through recurring calibration revenues.
- Exhaust Systems:Fabricated assemblies of mandrel-bent tubing, catalytic substrates, and acoustic attenuators that modify backpressure profiles and sound signatures. Aftermarket tuners in Germany source stainless steel and titanium configurations to satisfy KBA type-approval protocols for street-legal modifications. EPA Title II certification requirements compress supplier margins while creating compliance barriers for unvalidated imports.
- Turbochargers:Forced-induction compressors and turbine wheels that elevate manifold pressures beyond naturally aspirated baselines. Demand concentrates in amateur racing circuits across Japan and the United States where power density gains justify thermal management investments. Dual-ball-bearing cartridges and variable-geometry nozzle rings differentiate premium tiers from journal-bearing commodity units.
- Cold Air Intakes:Filter housings and induction tubing that reduce inlet air temperatures below engine-bay ambient levels.
- ECU Tuners:Flash-based calibration interfaces that rewrite fuel, ignition, and boost control maps.
Exhaust systems lead volumes today; ECU tuners are gaining share fastest.
Material:
Cost stratification across material tiers reflects thermal performance requirements and aerospace alloy availability rather than simple commodity substitution.
- Stainless Steel:Austenitic and ferritic grades that provide oxidation resistance at exhaust gas temperatures below 900°C. Volume production of cat-back and axle-back systems for street-performance applications depends on Chinese and Indian mill supply. Raw material volatility in nickel markets squeezes fabricator margins during contract renegotiation cycles.
- Composite:Carbon fiber and glass-reinforced polymers that reduce mass in intake plenums and engine covers. Porsche Motorsport programs in Germany specify woven prepregs with high-temperature epoxy matrices for under-hood thermal cycling. Robert Bosch GmbH injection-molds composite intake runners that displace aluminum castings in European racing supply chains.
- Aluminum:Cast and wrought alloys for intercooler end tanks and intake manifolds.
- Plastic:Glass-filled nylons and PPS compounds for non-structural ducting and resonators.
Stainless steel dominates unit economics; composite materials are climbing the fastest.
Application:
Regulatory bifurcation between closed-circuit and public-road usage forces suppliers to maintain parallel product architectures with divergent homologation investments.
- Automotive Racing:Closed-circuit configurations exempt from tailpipe emissions standards. Track-day programs at Nürburgring and Fuji Speedway sustain demand for non-compliant exhaust and open-element intake systems. Sustained thermal cycling at full load requires Inconel and titanium alloys that withstand exhaust gas temperatures exceeding 1000°C.
- Street Performance:Road-legal modifications subject to EPA, CARB, and KBA emissions validation. California Air Resources Board executive orders create a de facto national compliance benchmark for US suppliers. Catalytic converter substrate selection and OBD-II compatibility dominate engineering resource allocation.
- Off-Roading:Dust filtration and impact resistance priorities for desert and rock-crawling disciplines.
- Marine:Corrosion-resistant architectures for saltwater operating environments.
Street performance anchors revenue today; automotive racing shows the steepest expansion trajectory.
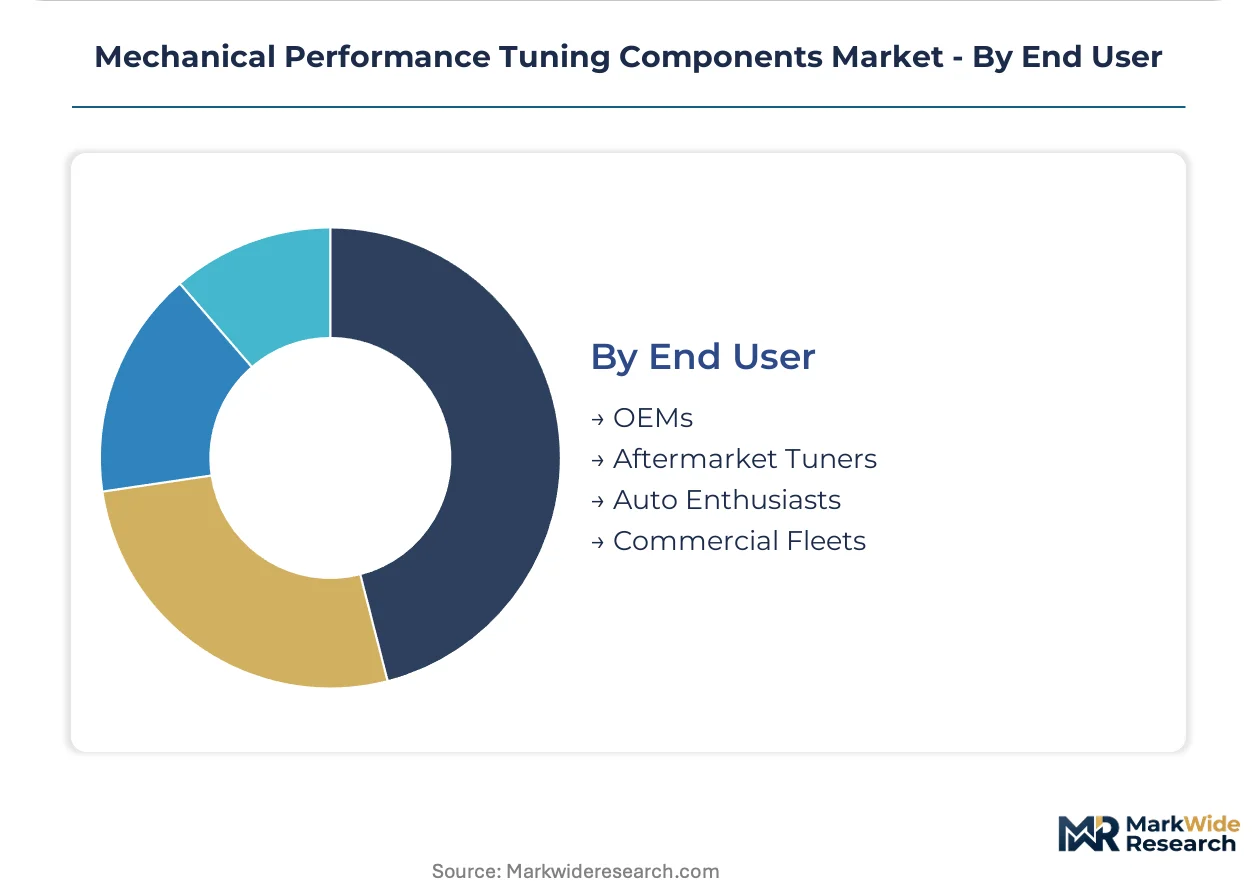
End User:
Procurement authority fragmentation across end-user categories determines pricing power and technical support intensity requirements.
- Aftermarket Tuners:Specialized installers and retail distributors serving enthusiast consumer segments. Direct-to-consumer e-commerce platforms in Australia and Canada bypass traditional jobber markups while accelerating technical support response times. Warranty liability and calibration validation responsibilities concentrate with the installation entity rather than component manufacturer.
- Auto Enthusiasts:Individual consumers purchasing components for self-installation or enthusiast shop fitting. Southern California and England's Home Counties host dense clusters of vintage Porsche and Jaguar specialists maintaining captive inventories of NLA hardware. Collector car restoration fragmentation concentrates price discovery on specialized auction platforms.
- OEMs:Original equipment manufacturers integrating performance variants into factory production.
- Commercial Fleets:Vehicle operators seeking durability or fuel efficiency modifications.
Aftermarket tuners command volume leadership today; auto enthusiasts are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Nürburgring Nordschleife industrial corridor anchors aftermarket tuning demand through Germany's dense concentration of motorsport engineering shops and type-approval testing facilities. Regulatory fragmentation across EPA, CARB, and KBA jurisdictions forces suppliers to maintain parallel certification tracks. Track-day participation in Japan, the United States, and Germany sustains demand for non-compliant hardware exempt from street emissions standards.
United States
Southern California hosts the densest cluster of vintage Porsche and Jaguar restoration specialists maintaining captive inventories of period-correct carburetors and mechanical ignition distributors. EPA Title II certification requirements under the Clean Air Act compress supplier margins while creating compliance barriers for unvalidated exhaust imports. The California Air Resources Board executive order system creates a de facto national benchmark that expands legal installation bases for compliant catalytic converters.
Germany
The KBA enforces extensive durability testing protocols for modified powertrain components, extending product development cycles and raising capital requirements for market entry. Stuttgart and Munich anchor OEM-adjacent tuning ecosystems where Robert Bosch GmbH supplies composite intake plenums for European racing programs. Track-day programs at Nürburgring sustain demand for non-street-legal exhaust configurations exempt from tailpipe regulations.
Japan
Fuji Speedway and Tsukuba Circuit generate sustained demand for forced-induction hardware and open-element intake systems in amateur racing circuits. METI oversees industrial standards for automotive components while maintaining carve-outs for competition-use equipment. Osaka-based fabricators specialize in titanium exhaust manifolds for domestic time-attack competitions where thermal cycling demands exceed street-legal material specifications.
United Kingdom
England's Home Counties concentrate collector car restoration shops unbundling turnkey engine rebuilds into component-level sourcing decisions. The Driver and Vehicle Standards Agency enforces emissions compliance for road-legal modifications while permitting track-only configurations under Motorsport UK exemptions. Silverstone's industrial periphery hosts low-volume specialists additive-manufacturing titanium exhaust collectors for prototype racing batches.
Australia
Direct-to-consumer e-commerce platforms bypass traditional distributor markups while accelerating technical support response times for enthusiast segments. The Australian Design Rules framework governs vehicle modifications with state-level enforcement variations that create compliance complexity. Melbourne and Sydney anchor aftermarket tuner clusters serving domestic muscle car restoration and Japanese import performance segments.
Mechanical Performance Tuning Components Market Competitive Environment
Portfolio diversification dominates the current landscape as suppliers architect dual-purpose product lines spanning street-legal and track-only applications. The vendor base concentrates around three strategic archetypes: diversified automotive conglomerates leveraging injection-molding and forging expertise, specialized braking and thermal management firms, and dedicated aftermarket performance brands. M&A activity and technology licensing agreements represent the primary competitive vectors as scale advantages compound in emissions certification and additive manufacturing capabilities.
Among diversified conglomerates, Robert Bosch GmbH and Continental AG occupy positions exemplifying the injection-molding and powertrain electronics archetype, while Brembo S.p.A. anchors the specialized braking systems tier. ZF Friedrichshafen AG sits within the scale-driven supplier group. These entities represent contrasting strategic postures: conglomerates pursuing backward integration into composite materials and calibration software, versus specialists defending margin positions through forged aluminum architectures and thermal cycling expertise.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| ZF Friedrichshafen AG |
| Continental AG |
| BorgWarner |
| Brembo S.p.A. |
| Holley Performance Products Inc. |
| Magna International |
| Valeo |
| DENSO Corporation |
| Others |
Value Chain & Pricing Dynamics
London Metal Exchange nickel futures volatility cascades through exhaust system fabricator pricing tiers, compressing margins on stainless steel cat-back configurations while amplifying premium capture for titanium and Inconel racing exhausts where aerospace-grade alloy premiums pass directly to amateur racing buyers in Germany and Japan.
Pricing Analysis
Input-cost pass-through from specialty alloy spot markets stratifies pricing across three certification tiers. CARB-executive-order-compliant catalytic converters command substantial premiums over non-certified alternatives due to EPA Title II validation investments, while KBA type-approval protocols in Germany add further homologation cost layers. Price erosion runs through commodity stainless steel axle-back systems as Chinese mill oversupply intensifies competition. Aftermarket tuners exhibit highest price sensitivity on volume exhaust hardware; collector car restoration specialists show lowest sensitivity on period-correct NLA components.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and German precision forging houses supplying dual-ball-bearing turbocharger cartridges, where aerospace-qualified heat treatment capacity concentrates among aging specialty foundries. Raw material flows draw from Chinese nickel refining, Indian stainless steel rolling, and US titanium sponge production. Tariff exposure on Inconel feedstock from specialty alloy distributors amplifies cost volatility for professional racing exhaust fabricators. Distribution runs through specialized e-commerce platforms in Australia and Canada alongside traditional jobber networks serving Southern California and England's Home Counties.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where enthusiast procurement shifts toward EPA-certified and KBA-homologated premium tiers, rewarding suppliers with parallel street-legal and track-only product architectures.
For Market Incumbents: Anticipate electrification substitution by accelerating hydrogen combustion retrofit R&D and securing calibration engineering talent from aging OEM powertrain veterans. Backward integration into composite injection-molding capacity defends margin positions against emerging Asian suppliers. Certification investment in CARB executive orders creates compliance moats that fragment competitor addressable markets. For New Entrants and Emerging Players: Launch via direct-to-consumer e-commerce channels targeting Australian and Canadian enthusiast segments where traditional distributor markups remain penetrable. White-space concentrates in software-defined ECU calibration platforms enabling recurring subscription revenues, and in additive-manufactured titanium exhaust collectors for low-volume racing prototype batches where lead time compression commands premium positioning. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized thermal management firms possessing F-Gas Regulation-compliant R-744 test bench infrastructure ahead of EU phase-down deadlines. Long-term viability hinges on transitional hydrogen combustion hardware bridging fossil-fuel expertise with zero-emission architectures. Watch EPA electrification carve-out negotiations as the critical inflection signal for internal-combustion tuning hardware demand visibility.| Strategic Initiative | Industry Significance |
|---|---|
| EPA Title II Certification Investment | CARB executive orders unlock de facto national addressable markets for compliant catalytic converters. |
| Backward Integration into Composite Manufacturing | Robert Bosch GmbH's injection-molding expertise anchors racing program supply relationships. |
| Software-Defined Calibration Platform Launch | Flash-based ECU remapping shifts value capture from hardware sales toward recurring subscription maintenance. |
| Additive Manufacturing Capability Buildout | Electron-beam-melted titanium collectors reduce prototype lead times from twelve weeks to under four. |
| Hydrogen Combustion Retrofit Development | H2-ICE conversion kits bridge existing performance engine architectures with zero-emission powertrain transitions. |
Study Parameters
Coverage spans Germany, the United States, Japan, the United Kingdom, and Australia, with primary inputs from each market's aftermarket tuner procurement directors, OEM platform engineers, EPA and KBA regulatory affairs specialists, and collector car restoration shop owners. Secondary validation drew from EPA Title II certification databases, CARB executive order filings, KBA type-approval registries, and specialized auction platform transaction records. Bottom-up component demand modeling triangulated against top-down powertrain modification expenditure estimates.
Granularity-level modeling disaggregated volume and value across component type, material grade, application regulatory status, and end-user procurement authority throughout the projection horizon. Segmentation dimensions included exhaust system architecture, forced-induction hardware specification, calibration interface deployment model, and regional certification cluster. CAGRs derived from trend extrapolation of track-day participation rates, emissions enforcement intensity indices, and composite material substitution curves in European racing supply chains.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated electrification substitution or EPA regulatory preemption shifts. Forecasts reflect documented assumptions regarding KBA protocol stability and F-Gas Regulation phase-down timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Windshield Washer System Market
Automotive Parts
Singapore Automotive Engine Oils Market
Automotive Parts
Global Automotive Gas Charged Shock Absorbers Market
Automotive Parts
Europe Automotive Parts Zinc Die Casting Market
Automotive Parts
Global EV Speed Reducer Market
Automotive Parts
South Africa Automotive Lubricants Market
Automotive Parts
Global Automotive Muffler Tip Market
Automotive Parts
Engine Oil Market
Automotive Parts
Automotive Hinges Market
Automotive Parts
Garage Body Shop Equipment Market
Automotive Parts
United States Automotive Parts Die Casting Market
Automotive Parts
Automotive Parts Die Casting Market
Automotive Parts
Oil Catch Cans Market
Automotive Parts
Automotive Brake Wheel Cylinder Market
Automotive Parts
Global Automotive Selective Catalytic Reduction System Market
Automotive Parts
Automotive Weatherstrips Market