
 Global Automotive Gas Charged Shock Absorbers Market | 2026-2036
Global Automotive Gas Charged Shock Absorbers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Gas Charged Shock Absorbers Market Analysis
Software-defined ride calibration is realigning how shock absorbers get specified and monetized. ZF Friedrichshafen AG leverages its chassis electronics portfolio to bundle adaptive damping with over-the-air update capability. Tenneco Inc sustains aftermarket channel control through private-label and branded replacement programs across North American service chains. KYB Corporation anchors its position in Asian OEM supply through manufacturing scale in Thailand and Japan.
Automotive gas charged shock absorbers are hydraulic dampers pressurized with nitrogen gas to prevent cavitation and maintain consistent damping force across temperature extremes; they isolate sprung mass from road disturbances to preserve tire contact and vehicle stability. Twin tube designs occupy the volume-intensive economy and mid-range passenger segments where cost sensitivity dominates OEM procurement. Mono tube configurations lead performance-oriented applications and premium electric vehicles where thermal capacity and precise damping modulation command margin premiums. Electromagnetic and active technologies represent the fastest-growing technology tier as automakers integrate semi-autonomous chassis systems.
NHTSA enforces FMVSS 121 durability benchmarks that shape absorber fatigue-life requirements for commercial vehicles sold in the United States. ECE R14 and ECE R29 frameworks in Europe govern occupant protection and cab structural integrity, indirectly mandating suspension performance standards for truck and bus platforms. China's GB/T automotive suspension standards and MIIT new-energy vehicle technical rules compound compliance complexity for suppliers serving multiple geographies. Stakeholders must monitor how software-defined vehicle architectures rewrite procurement specifications for chassis hardware.
Market Dynamics
Software-defined vehicle architectures are compressing specification cycles for chassis hardware as automakers bundle adaptive damping with over-the-air calibration capability.
Growth Catalysts
- FMVSS 121 brake standard updates:NHTSA durability benchmarks for commercial vehicles in the United States indirectly mandate enhanced suspension component fatigue life, expanding replacement demand for gas charged absorbers in heavy-duty fleets.
- Electric vehicle thermal management requirements:Premium EV platforms favor mono tube configurations for their superior heat dissipation capacity, pulling specification upgrades across OEM procurement.
- Stuttgart-Munich manufacturing corridor concentration:Germany's commercial vehicle production cluster sustains steady absorber demand from Mercedes-Benz, MAN, and Scania assembly operations.
Market Restraints
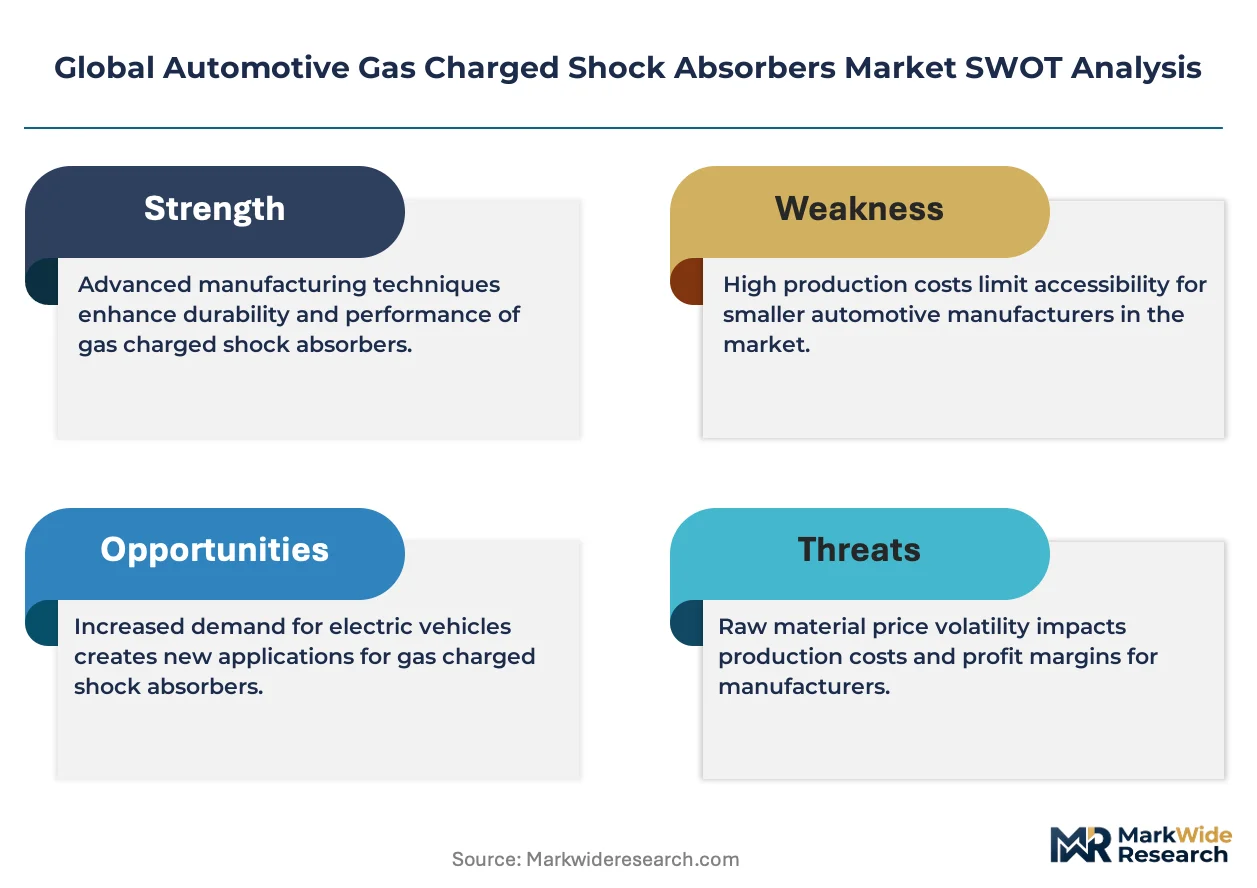
- Steel and nitrogen gas input volatility:Twin tube absorber margins compress when raw material costs spike, forcing OEMs to extend procurement payment terms.
- Thailand-Japan supply concentration:KYB Corporation and regional Tier 2 suppliers control Asian OEM volume, creating geographic single-source vulnerability for European and North American automakers.
- Electromagnetic active suspension substitution:Semi-autonomous chassis systems with real-time damping adjustment threaten conventional gas charged hardware in premium segments above $50,000 vehicle price points.
Strategic Opportunities
- India commercial vehicle fleet modernization:BIS automotive suspension standards and PLI scheme incentives for local manufacturing create entry points for absorber suppliers establishing domestic production.
- Over-the-air calibration bundling:Chassis electronics integration allows suppliers to monetize damping software updates as recurring revenue streams alongside hardware sales.
- China NEV technical compliance complexity:MIIT new-energy vehicle rules compound certification requirements, favoring suppliers with established GB/T standard expertise and local testing partnerships.
Industry Challenges
- Software-hardware integration skill scarcity:Traditional damper engineering teams lack embedded systems and control algorithm expertise required for adaptive suspension development.
- Multi-jurisdiction certification timelines:Simultaneous NHTSA, ECE R14, and GB/T validation extends product launch cycles by 8-14 months for global platform suppliers.
- Legacy fleet aftermarket fragmentation:Independent service chains in North America resist standardized diagnostic protocols for gas charged absorber replacement, complicating warranty claim processing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Gas Charged Shock Absorbers Market |
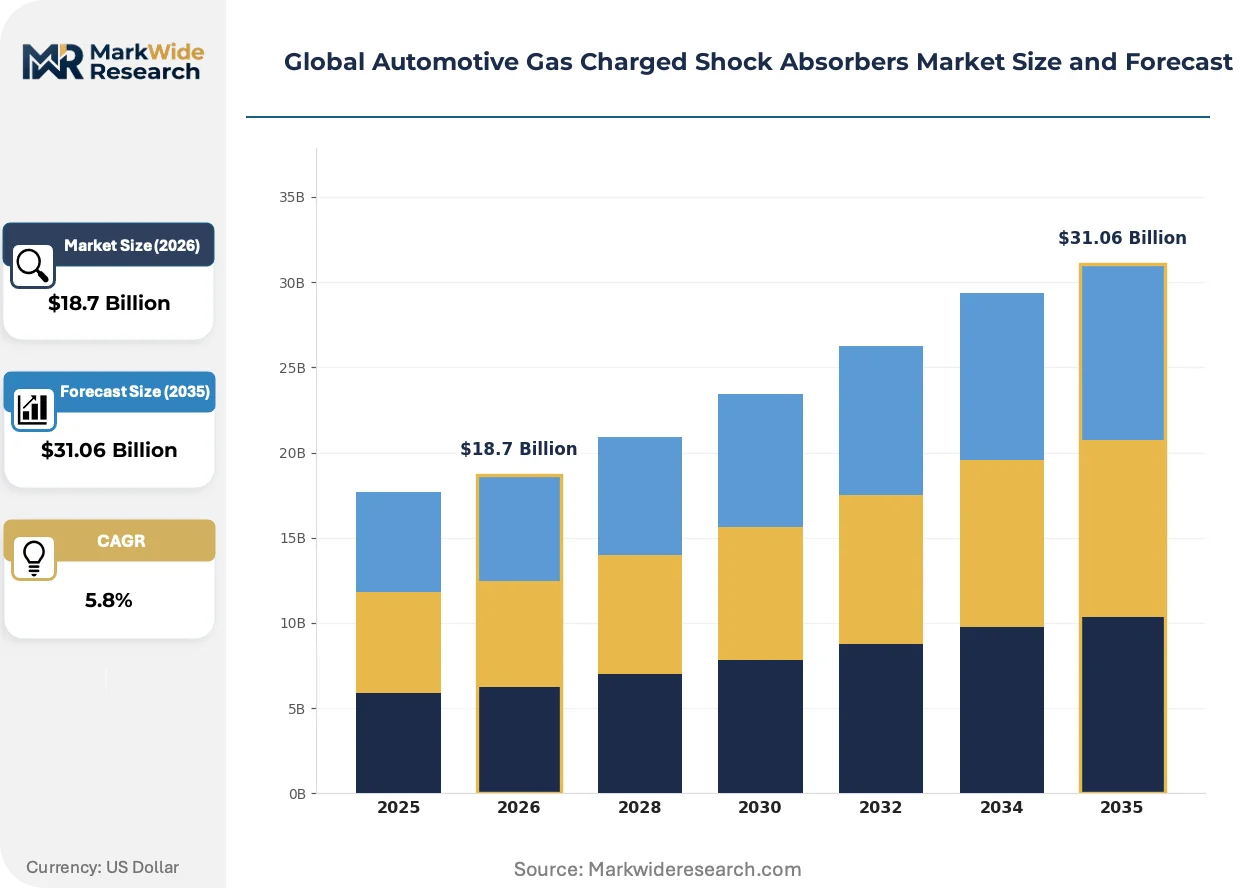
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Twin Tube, Mono Tube, Adjustable, Custom Technology: Hydraulic, Pneumatic, Electromagnetic, Active End User: OEMs, Aftermarket, Fleet Services, Racing Teams Installation Type: Original Equipment, Retrofit, DIY Kits, Professional |
| Companies Covered | ZF Friedrichshafen AG, Tenneco Inc, KYB Corporation, Hitachi Astemo, Ltd, Samvardhana Motherson Group, Showa Corporation, ITT Inc, Thyssenkrupp AG, Meritor, Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Gas Charged Shock Absorbers Market Emerging Trajectories
Active damping algorithms and predictive suspension control are converging to redefine how shock absorbers generate value beyond mechanical isolation.
Magnetorheological fluid technology is absorbing road input variations through real-time viscosity modulation controlled by electromagnetic fields. High-performance EV manufacturers including Porsche and Ferrari-specified suppliers deploy these systems for sub-10-millisecond response times. The technology is absorbing margin from conventional gas charged hardware in vehicles above $80,000 MSRP.
REACH chemical substance restrictions and the EU Green Deal carbon border adjustment mechanism are tightening material traceability requirements for suspension component suppliers. European absorber manufacturers must document virgin steel sourcing and nitrogen gas production emissions intensity. Germany-based suppliers face the steepest compliance cost escalation as KBA type-approval audits expand to cover supply chain carbon accounting.
Fleet operators in North America are unbundling after-sales service contracts from OEM vehicle purchases, creating direct procurement relationships with absorber specialists. Large trucking conglomerates negotiate multi-year damping replacement schedules independent of dealer networks. This pattern concentrates most visibly in long-haul freight corridors connecting California ports to Midwest distribution hubs.
Global Automotive Gas Charged Shock Absorbers Market Segmentation
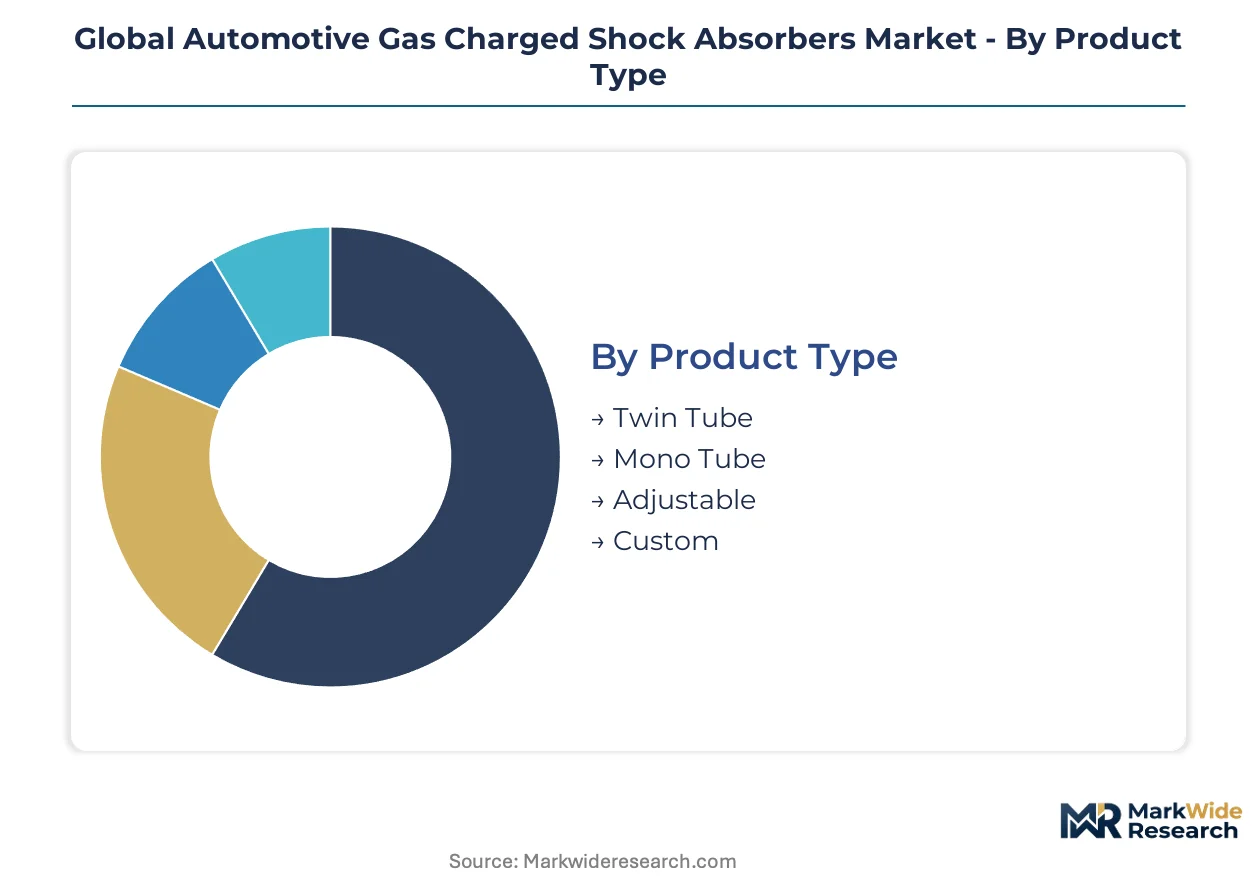
Segmentation in automotive gas charged shock absorbers reveals how capital deployment, technical complexity, and procurement channel control shape competitive returns. Suppliers must align production scale with the diverging durability and calibration requirements across passenger, commercial, and performance vehicle categories.
Product Type:
Capital intensity varies sharply across product architectures, with mono tube manufacturing demanding precision machining investments that twin tube lines avoid.
- Twin Tube:Concentric cylinder construction with inner working tube and outer reserve tube separates compression and rebound valving. Volume demand concentrates in economy and mid-range passenger vehicles produced in high-volume assembly plants across Germany, China, and the United States where procurement teams prioritize unit cost over thermal performance.
- Mono Tube:Single high-pressure cylinder with floating piston separating oil and nitrogen gas delivers superior heat dissipation and damping consistency. Premium EV platforms from Stuttgart-based manufacturers specify these configurations for thermal management under sustained high-load driving, pulling specification upgrades across OEM procurement tiers.
- Adjustable:Variable orifice or external reservoir designs permit manual damping modification for off-road and towing applications.
- Custom:Bespoke valving and stroke lengths serve motorsport and specialized commercial vehicle retrofitters.
Twin Tube absorbs the bulk of installed capacity; Mono Tube is expanding most quickly.
Technology:
Technology tiering separates commodity hydraulic hardware from electronically controlled systems that command software-enabled recurring revenue.
- Hydraulic:Conventional oil-based damping with nitrogen gas charge preventing cavitation maintains dominant share in replacement markets and developing economy vehicle production.
- Pneumatic:Air-spring integration with gas charged damping supports commercial vehicle height adjustment and load-leveling requirements in European long-haul freight specifications.
- Electromagnetic:Magnetorheological fluid systems with real-time viscosity modulation deliver sub-10-millisecond response times. Porsche and Ferrari-specified suppliers deploy these in vehicles above $80,000 MSRP, absorbing margin from conventional hardware.
- Active:Sensor-fed predictive control with over-the-air calibration capability represents the steepest expansion trajectory as automakers integrate semi-autonomous chassis systems.
Hydraulic technology retains the largest installed base; Active systems are climbing the fastest.
End User:
End user channel structure determines pricing power, with fleet direct procurement eroding traditional aftermarket margin capture.
- OEMs:Original equipment supply contracts with Mercedes-Benz, MAN, and Scania assembly operations in Germany's Stuttgart-Munich corridor sustain steady absorber demand with multi-year volume commitments.
- Aftermarket:Independent service chains and parts distributors serve vehicle owners outside warranty periods, though standardized diagnostic protocol resistance complicates warranty claim processing in North American markets.
- Fleet Services:Large trucking conglomerates negotiate multi-year damping replacement schedules independent of dealer networks, concentrating in California-to-Midwest freight corridors.
- Racing Teams:Motorsport specialists demand rapid-turn custom valving with telemetry integration for circuit-specific setup optimization.
OEMs absorb the bulk of installed capacity; Fleet Services is expanding most quickly.
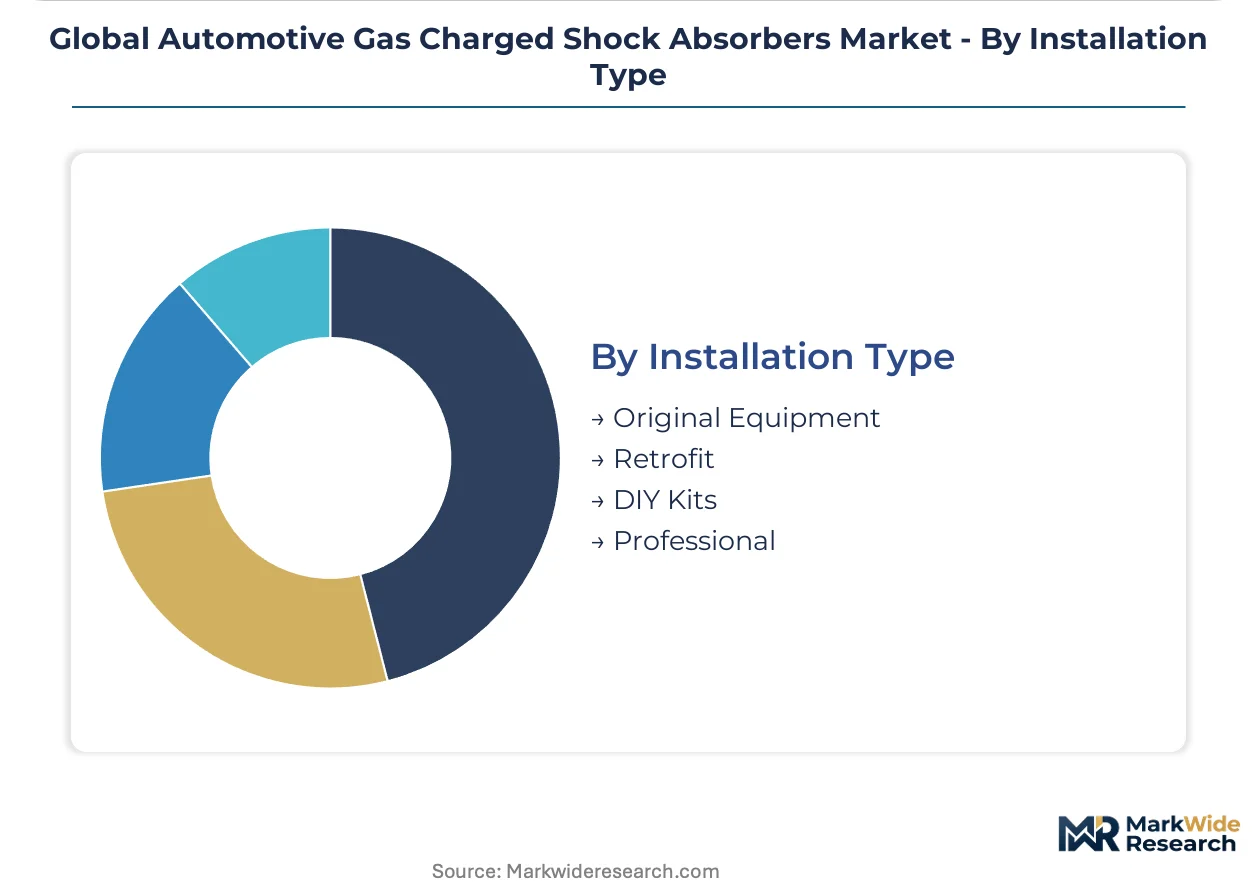
Installation Type:
Installation channel configuration shapes service revenue attachment and brand loyalty retention across vehicle lifecycle stages.
- Original Equipment:Factory-installed absorbers specified at vehicle design phase carry warranty integration and platform validation requirements that lock in supplier relationships.
- Retrofit:Suspension upgrade packages for commercial vehicle life extension and performance enhancement support mid-life revenue capture.
- DIY Kits:Consumer-direct packaged replacements with installation instructions serve independent vehicle owners in North American and European markets.
- Professional:Dealer and certified repair facility installation maintains diagnostic protocol compliance and warranty continuity for complex adaptive systems.
Original Equipment absorbs the bulk of installed capacity; Professional installation is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Germany, Japan, and China, while consumption pulls strongest from the United States and European commercial vehicle corridors. This geographic split shapes supplier location decisions and regulatory compliance strategies across the value chain.
United States
Heavy-duty fleet operators in California-to-Midwest freight corridors drive replacement demand through unbundled service contracts independent of dealer networks. NHTSA FMVSS 121 brake standard updates indirectly mandate enhanced suspension durability, expanding absorber procurement cycles. Detroit and Chicago manufacturing clusters anchor domestic commercial vehicle assembly operations.
Germany
Mercedes-Benz, MAN, and Scania assembly operations in the Stuttgart-Munich corridor sustain steady OEM absorber demand with multi-year volume commitments. KBA type-approval audits now cover supply chain carbon accounting under EU Green Deal implementation. Baden-Württemberg suppliers face steepest compliance cost escalation from REACH chemical restrictions.
Japan
KYB Corporation and Showa Corporation anchor Asian OEM supply through manufacturing scale in Kanto and Kansai industrial zones. METI industrial standards shape domestic procurement specifications for chassis components. Tokyo-Osaka logistics networks concentrate distribution for Southeast Asian export markets.
China
MIIT new-energy vehicle technical rules compound certification complexity for absorber suppliers serving domestic EV platforms. Yangtze River Delta manufacturing clusters house GB/T standard testing partnerships essential for market access. Shanghai-based procurement teams prioritize suppliers with established local validation capabilities.
India
BIS automotive suspension standards and PLI scheme incentives for local manufacturing create entry points for absorber specialists establishing domestic production. Maharashtra and Tamil Nadu commercial vehicle assembly plants pull component sourcing toward South Asian supply bases. Pune-Chennai industrial corridors concentrate fleet modernization programs.
Global Automotive Gas Charged Shock Absorbers Market Vendor Landscape
Top-tier vendors anchor OEM supply relationships, while mid-tier specialists capture aftermarket and fleet service channels. The vendor base stratifies across three tiers: integrated chassis electronics providers, standalone damper manufacturers, and regional aftermarket distributors. Two strategic archetypes dominate: technology bundlers integrating software-defined calibration, and scale operators controlling manufacturing cost positions. Competitive moves concentrate on backward integration into precision machining and strategic partnerships for electromagnetic active suspension development.
Among Germany-based integrated suppliers, ZF Friedrichshafen AG and Thyssenkrupp AG occupy positions exemplifying the chassis electronics bundling archetype. Tenneco Inc represents North American aftermarket channel control through branded and private-label replacement programs. KYB Corporation anchors the Asian manufacturing scale archetype, with Japanese and Thai production facilities supporting regional OEM volume. These three entities illustrate how geographic origin and corporate structure shape competitive positioning without determining specific strategic outcomes.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| Tenneco Inc |
| KYB Corporation |
| Hitachi Astemo, Ltd |
| Samvardhana Motherson Group |
| Showa Corporation |
| ITT Inc |
| Thyssenkrupp AG |
| Meritor, Inc |
| Others |
Supply Flow & Price Mechanics
Mono tube precision machining migration toward high-pressure cylinder production is simultaneously elevating capital barriers and consolidating supplier tiers around German and Japanese manufacturing clusters. This technical transition rewards absorber specialists with captive forging and nitrogen gas charging capabilities while squeezing twin tube assemblers dependent on commodity steel sourcing.
Pricing Analysis
Margin tightening in twin tube segments reflects steel and nitrogen gas input volatility that OEM procurement teams offset through extended payment term demands. Three-tier pricing structure across premium, standard, and economy levels separates electromagnetic active systems above $80,000 vehicle MSRP from mono tube configurations in premium EVs and twin tube hardware in volume passenger production. Fleet direct procurement in North American long-haul corridors intensifies price transparency, while adaptive damping software bundling insulates integrated chassis electronics providers from commodity cost exposure.
Supply Chain Analysis
Precision machining workforce scarcity in Baden-Württemberg and Kanto industrial zones constrains mono tube capacity expansion despite specification pull from Stuttgart-based EV platforms. Supply concentrates in Germany, Japan, and Thailand, with KYB Corporation and Showa Corporation anchoring Asian OEM volume through Kanto and Kansai production networks. Raw material dependencies center on virgin steel sourcing, nitrogen gas production, and magnetorheological fluid compounds. Single-source vulnerability from Thailand-Japan geographic concentration threatens European and North American automaker supply security. Distribution runs through OEM direct contracts, aftermarket service chains, and fleet procurement relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where EU Green Deal carbon border adjustment mechanisms and KBA supply chain carbon accounting audits erect regulatory moats favoring incumbent suppliers with established documentation systems.
For Market Incumbents: Lock in backward integration into precision machining and nitrogen gas charging infrastructure to defend mono tube margin positions against electromagnetic active suspension substitution in premium segments. Prioritize software-defined calibration capability investments that enable over-the-air damping update monetization as recurring revenue streams alongside hardware sales. For New Entrants and Emerging Players: Enter via India's commercial vehicle fleet modernization wave, where BIS automotive suspension standards and PLI scheme incentives create accessible entry points for absorber specialists establishing Maharashtra or Tamil Nadu production. Target fleet services direct procurement relationships in California-to-Midwest freight corridors where unbundled service contracts bypass entrenched OEM aftermarket channels. For Investors and Strategic Acquirers: Exit pathways concentrate in chassis electronics bundling acquisitions by Tier 1 automotive suppliers seeking adaptive damping algorithm capabilities. Long-term viability hinges on software-hardware integration expertise rather than commodity damper manufacturing scale. Monitor electromagnetic active suspension penetration rates above $50,000 vehicle price points as the critical inflection signal for conventional gas charged hardware displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Machining | Captive high-pressure cylinder production locks in mono tube margin premiums against steel cost volatility. |
| Software-Defined Calibration Capability | Over-the-air damping updates enable recurring revenue streams alongside hardware sales for ZF and Tenneco. |
| India Manufacturing Footprint Establishment | BIS compliance and PLI incentives position entrants for commercial vehicle fleet modernization procurement. |
| Electromagnetic Active Suspension Partnership | Magnetorheological fluid alliances with Porsche-specified suppliers defend premium segment positioning. |
| Fleet Direct Procurement Channel | Unbundled service contracts in California-to-Midwest corridors bypass dealer network margin capture. |
Methodological Framework
Vehicle production databases, IHS Markit registration data, and SEC filings from listed Tier 1 suppliers formed the secondary backbone, cross-referenced with primary interviews involving OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and dealership operations managers. Bottom-up and top-down triangulation validated segment sizing across product architectures and technology tiers.
Bottom-up modeling built volume estimates from named country production clusters and content-per-vehicle assumptions, while top-down approaches anchored aggregate market sizing to macro vehicle assembly forecasts across the analysis window. Segmentation dimensions spanned product type, technology tier, end user channel, and regional production cluster. CAGRs derived from regression analysis against historical replacement cycles and specification upgrade trajectories, with EV thermal management requirements and NHTSA durability benchmarks as key forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under electromagnetic active suspension substitution acceleration or prolonged steel and nitrogen gas cost volatility. Forecasts reflect assumptions around regulatory compliance timelines and fleet procurement pattern persistence. Material deviation in MIIT NEV rule enforcement intensity or EU carbon border adjustment implementation pace warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
France Automotive Parts Aluminium Die Casting Market
Automotive Parts
Automotive Rear Spoiler Market
Automotive Parts
Automotive Oil Pressure Switch Market
Automotive Parts
Bumper Beam Market
Automotive Parts
Electromagnetic Clutch System Market
Automotive Parts
High Level Brake Lamp Market
Automotive Parts
Global Rubber Transmission Belts Market
Automotive Parts
Windshield Repair Kit Market
Automotive Parts
Motorcycle Battery Chargers Market
Automotive Parts
Brake Fluids Market
Automotive Parts
Automotive Lifts Market
Automotive Parts
Morocco Passenger Vehicles Lubricants Market
Automotive Parts
Colombia Commercial Vehicles Lubricants Market
Automotive Parts
Automotive Fuel Nozzle Market
Automotive Parts
Cabin Air Filter Housing Replacement Parts Market
Automotive Parts
Middle East Passenger Vehicles Lubricants Market