
 Singapore Automotive Engine Oils Market | 2026-2036
Singapore Automotive Engine Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Automotive Engine Oils Market Analytics
Fleet operator consolidation is repositioning procurement power toward large commercial vehicle workshops and ride-hailing fleet managers in Singapore. ExxonMobil Corporation leverages its integrated refining and lubricant blending capabilities to secure supply contracts with these concentrated buyers. AP Oil anchors its position through specialized manufacturing scale at its Jurong Island facility, while ENEOS Corporation differentiates via advanced additive technology leadership for tropical climate formulations.
Singapore automotive engine oils are formulated lubricants comprising base oils and additive packages designed to reduce friction, dissipate heat, and protect internal combustion engine components under operating temperatures typically ranging from 40°C to 150°C. Synthetic formulations command premium positioning due to extended drain intervals and superior oxidation stability demanded by Singapore's stop-and-go urban driving conditions. SAE 5W-30 grade occupies the volume core across passenger vehicle service bays, while SAE 0W-20 is gaining fastest in hybrid and downsized turbocharged engines where fuel economy regulations intensify. The distributor channel sustains dominant flow for commercial workshops, though online platforms are fragmenting retail access for DIY motorcycle owners.
Singapore's National Environment Agency enforces lubricant waste management protocols under the Environmental Public Health Act, while the Land Transport Authority mandates periodic vehicle inspections that validate proper engine oil maintenance. These frameworks elevate demand for certified, traceable products and compress informal re-refined oil circulation. Stakeholders must monitor how the Carbon Pricing Act's escalating levy structure reshapes fleet operator preferences toward lower-viscosity, fuel-efficient formulations.
Market Dynamics
Singapore's tightening Carbon Pricing Act levy structure is forcing fleet operators to abandon mineral-based lubricants in favor of synthetic formulations that deliver measurable fuel economy gains during mandatory emissions audits.
Growth Catalysts
- Carbon Pricing Act Escalation:The Land Transport Authority's progressive levy tiers create direct financial incentives for commercial fleets to specify lower-viscosity synthetic grades that reduce tailpipe emissions during inspection cycles.
- Hybrid Powertrain Proliferation:Stop-start urban driving patterns across Singapore's dense road network accelerate oil degradation, shortening drain intervals and expanding volume demand for premium oxidation-resistant formulations.
- Jurong-Tuas Workshop Clustering:Industrial zone concentration of commercial vehicle service bays enables bulk procurement efficiencies and just-in-time inventory systems that favor established lubricant distributors with dedicated logistics capabilities.
Market Restraints
- Base Oil Import Dependency:Singapore lacks domestic Group III/IV base oil production, exposing blenders to freight cost volatility and currency fluctuation risks on shipments from South Korea and Middle Eastern suppliers.
- Re-refined Oil Informal Circulation:Unlicensed collectors operating outside Environmental Public Health Act protocols compress pricing for certified products by distributing untreated waste oil to price-sensitive independent workshops.
- Extended Drain Interval Technology:Advanced synthetic formulations capable of 15,000-kilometer service cycles structurally reduce per-vehicle oil consumption volume despite premium unit pricing.
Strategic Opportunities
- Electric Vehicle Fluid Adjacencies:Battery thermal management and e-axle lubrication requirements create formulation white space as Singapore's taxi and ride-hailing fleets electrify under Land Transport Authority mandates.
- Digital Platform Integration:B2B procurement portals connecting Jurong industrial workshops directly to blenders disintermediate traditional distributor markups and capture transaction data for predictive inventory positioning.
- Waste Oil Re-refining Infrastructure:National Environment Agency licensing frameworks favor investment in closed-loop collection and reprocessing facilities that convert used lubricants into certified base stocks for domestic blending.
Industry Challenges
- Additive Package Sourcing Complexity:Tropical climate formulations requiring enhanced detergency and dispersant chemistry face extended lead times from European and Japanese specialty chemical suppliers.
- Technician Certification Gaps:Commercial workshops struggle to retain staff trained in viscosity grade matching for downsized turbocharged engines, resulting in warranty claims and customer disputes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Automotive Engine Oils Market |
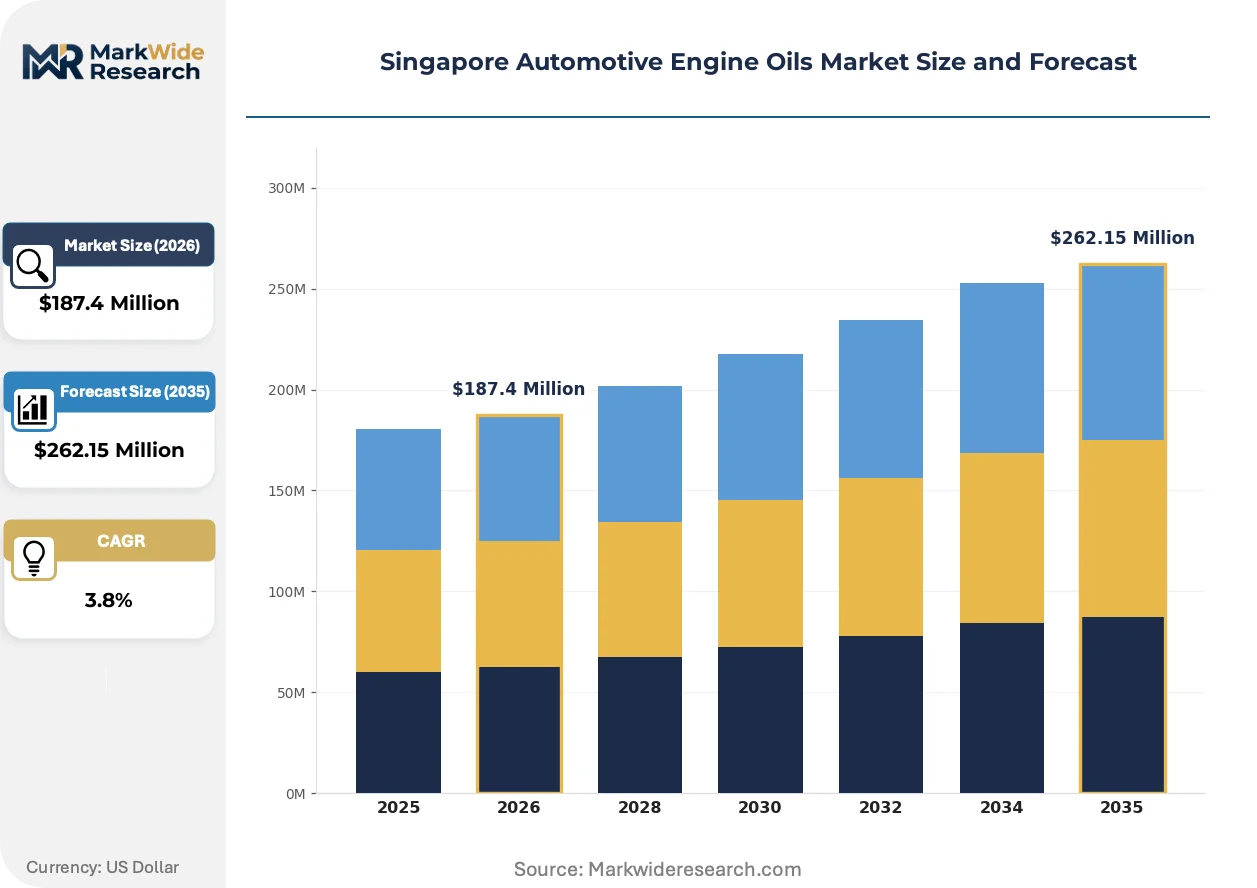
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $262.15 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic, Conventional, High Mileage, Diesel Grade: SAE 0W-20, SAE 5W-30, SAE 10W-40, SAE 15W-50 End User: Passenger Vehicles, Commercial Vehicles, Motorcycles, Small Engines Distribution Channel: Retail Stores, Online, Distributors, Service Stations |
| Companies Covered | BP Plc (Castrol), Chevron Corporation, ExxonMobil Corporation, Royal Dutch Shell Plc, TotalEnergies, AP Oil, ENEOS Corporation, Idemitsu Kosan Co. Ltd, Motul, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Automotive Engine Oils Market Evolving Landscape
Formulation chemistry and distribution architecture are undergoing parallel transformation as Singapore's regulatory environment hardens and fleet procurement centralizes. Three developments dominate the current cycle.
Polyalkylene glycol (PAG) synthetic base stocks are expanding into hybrid vehicle transmission and axle applications where conventional mineral oils fail under electrical field exposure and thermal cycling stress. Fleet maintenance managers at ride-hailing operators are specifying PAG-based products for their Toyota and Honda hybrid fleets despite 40% unit cost premiums. This technology is expanding into service bay recommendation protocols as original equipment manufacturers validate compatibility with legacy seal materials.
Singapore's National Environment Agency has enacted lubricant waste manifest requirements under Environmental Public Health Act amendments that mandate cradle-to-grave tracking of every liter sold. Blenders must now integrate QR-code traceability systems linking retail packaging to collection facility receipts. Small independent distributors lacking IT infrastructure face compliance cost burdens that accelerate market share consolidation toward integrated suppliers with proprietary logistics platforms.
Workshop procurement managers are consolidating supplier relationships from fragmented multi-brand sourcing to single-source framework agreements with volume-based rebate structures. Tuas-based heavy commercial vehicle fleets now negotiate annual contracts covering engine oils, greases, and hydraulic fluids rather than spot purchasing. This concentration is most visible among construction logistics operators serving the Port of Singapore Authority terminals, where procurement directors prioritize invoice consolidation over brand loyalty.
Singapore Automotive Engine Oils Market Segmentation
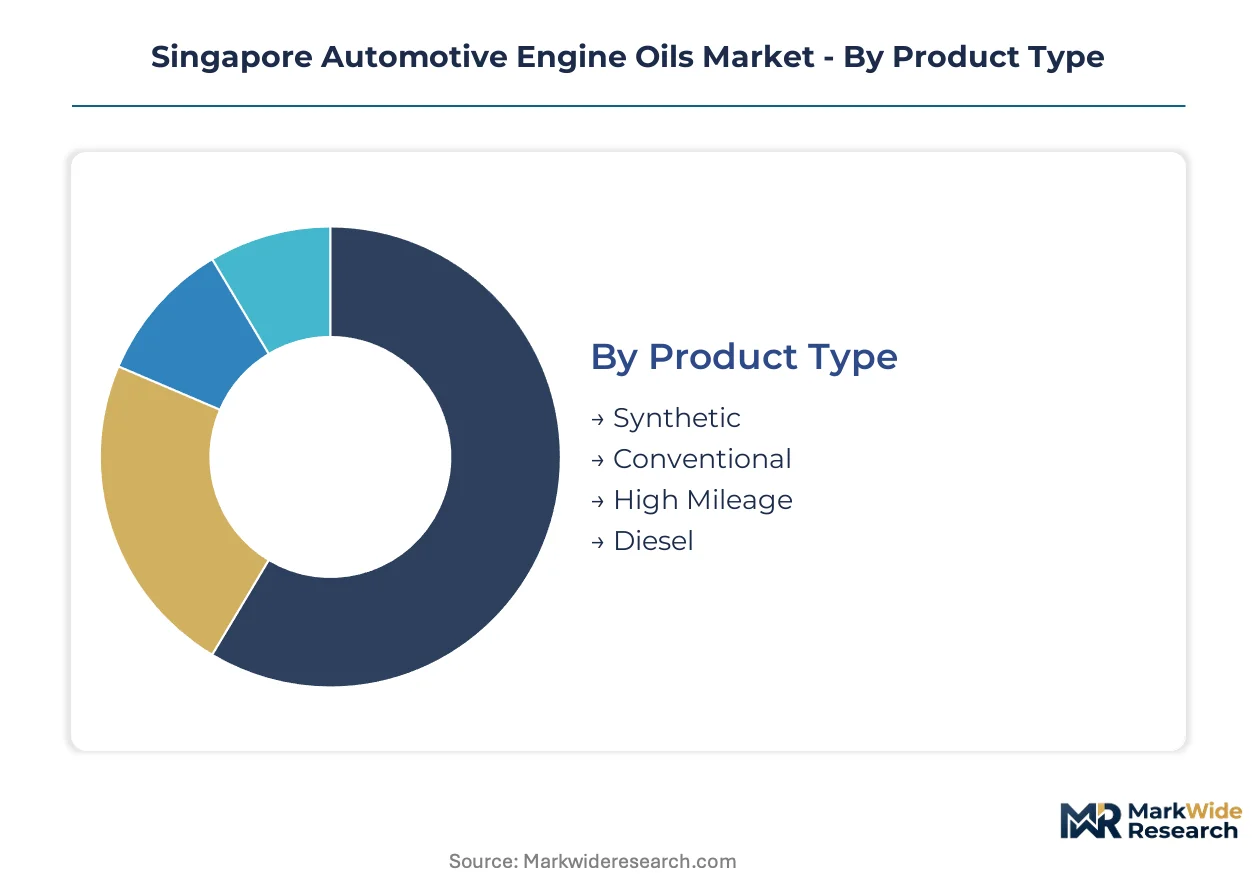
Singapore's automotive engine oils market fragments across formulation chemistry, viscosity specifications, vehicle applications, and procurement channels. Each segmentation axis reveals distinct margin structures and competitive intensity patterns that shape blender strategy and distributor economics.
Product Type:
Customization intensity varies sharply across this category, from commodity mineral formulations to proprietary synthetic blends requiring additive package engineering.
- Synthetic:Group III and Group IV base stocks blended with detergent-dispersant packages deliver extended drain intervals and thermal stability. Fleet operators in Jurong industrial zones specify these grades to meet Land Transport Authority emission audit thresholds under the Carbon Pricing Act.
- Conventional:Mineral base oils dominate price-sensitive independent workshops serving aging vehicle populations. Demand concentrates in motorcycle service bays where drain intervals remain short and cost pressure from informal re-refined oil circulation compresses margins.
- High Mileage:Seal conditioners and anti-wear additives target vehicles exceeding 100,000 kilometers. Niche positioning among private vehicle owners in residential estates seeking to extend engine life without full synthetic cost.
- Diesel:Higher Total Base Number formulations neutralize sulfuric acid from heavy fuel combustion. Commercial vehicle workshops across Tuas prioritize these grades for port logistics trucks and construction equipment.
Most installed capacity flows through Synthetic. Expansion is steepest in High Mileage as vehicle parc ages.
Grade:
Cost tier stratification separates premium low-viscosity synthetics from standard multi-grade mineral oils serving budget segments.
- SAE 0W-20:Ultra-low viscosity synthetic formulations reduce cold-start friction and improve fuel economy metrics. Hybrid vehicle fleets operated by ride-hailing platforms specify this grade to optimize urban cycle efficiency under Land Transport Authority fuel economy mandates.
- SAE 5W-30:The volume core balancing cold-flow protection and high-temperature film strength. Passenger vehicle service bays across Singapore's heartland districts stock this grade as their default recommendation for Japanese and Korean nameplates.
- SAE 10W-40:Higher viscosity mineral and semi-synthetic blends serve older European and domestic Asian vehicles with looser engine tolerances. Demand clusters in independent workshops serving vehicle populations beyond warranty coverage.
- SAE 15W-50:Heavy-duty protection for high-performance and tropical climate applications. Motorcycle enthusiasts and classic car collectors in specialist segments accept the fuel economy trade-off for enhanced film strength.
Volume concentration sits with SAE 5W-30. Climbing the fastest is SAE 0W-20 as hybrid powertrain penetration accelerates.
End User:
Customer type determines procurement scale, from individual retail transactions to consolidated fleet framework agreements.
- Passenger Vehicles:Private car owners and family fleets drive premium synthetic adoption through authorized dealer networks and quick-lube chains. Urban stop-start driving patterns shorten effective drain intervals despite extended service claims.
- Commercial Vehicles:Fleet managers at logistics and construction operators negotiate annual volume contracts covering multiple lubricant categories. Bulk procurement power concentrates in Tuas and Jurong industrial corridors serving Port of Singapore Authority terminals.
- Motorcycles:High-revving small-displacement engines demand frequent oil changes, creating steady volume. DIY maintenance culture among delivery riders and enthusiasts fragments purchasing across retail auto parts stores and online platforms.
- Small Engines:Lawn equipment, generators, and marine outboards require specialized two-stroke and four-stroke formulations. Niche demand from landscaping contractors and recreational boaters at marinas along the Singapore Strait.
Revenue scale peaks with Commercial Vehicles. Share expansion is strongest in Motorcycles as gig economy delivery fleets multiply.
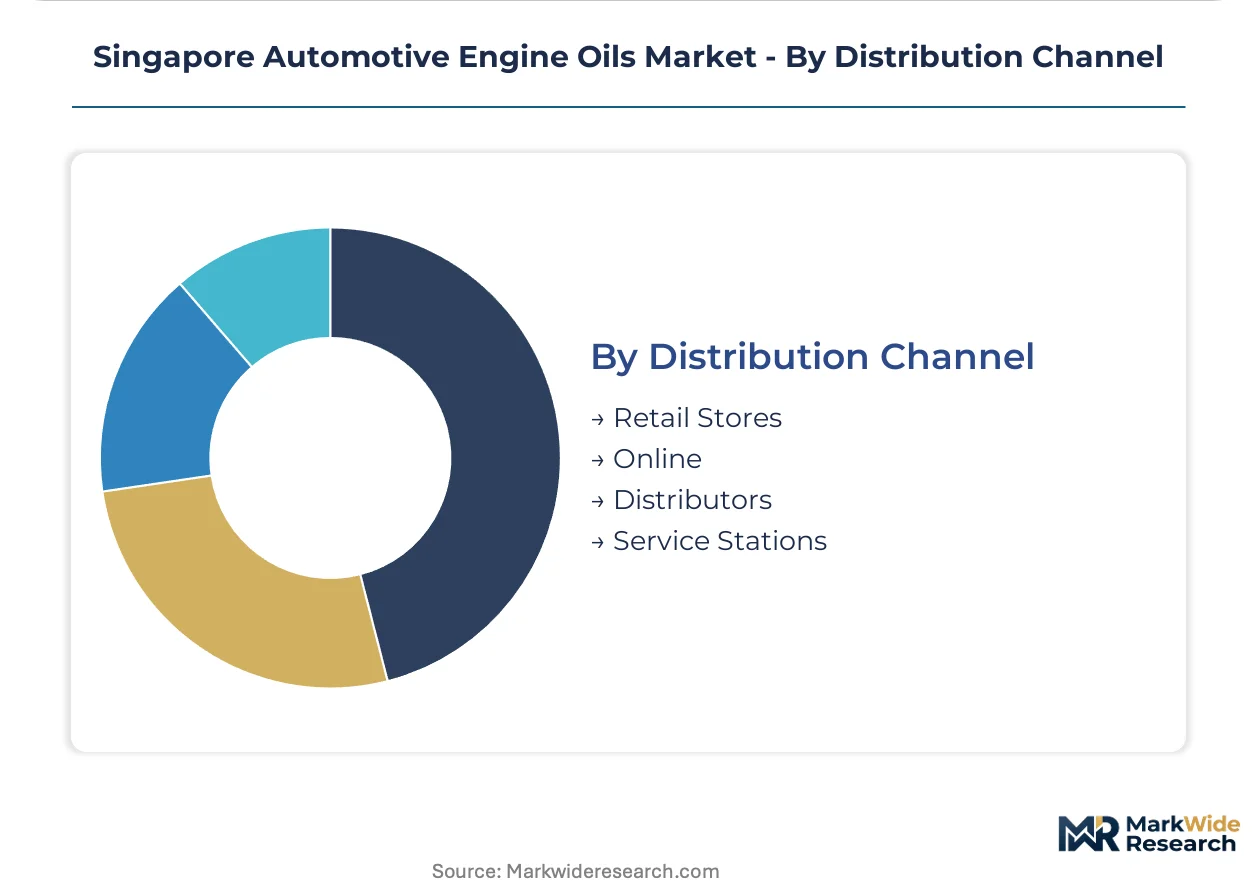
Distribution Channel:
Supply concentration versus fragmentation shapes margin capture and brand control across this final segmentation axis.
- Retail Stores:Hypermarkets and specialty auto parts outlets serve DIY consumers and small independent workshops. Shelf space competition favors established brands with marketing support and promotional funding.
- Online:E-commerce platforms and direct-to-consumer portals fragment price transparency and enable private label penetration. Motorcycle owners and enthusiast segments increasingly bypass traditional distributor markups for bulk purchases.
- Distributors:Authorized lubricant distributors maintain dedicated logistics capabilities for just-in-time delivery to commercial workshops. Jurong and Tuas industrial clustering enables efficient route density and inventory positioning.
- Service Stations:Integrated oil change bays at fuel retail sites capture convenience-driven passenger vehicle owners. Quick-service positioning competes on speed rather than technical consultation.
Volume flows predominantly through Distributors. Digital channel expansion is accelerating fastest as procurement managers seek price transparency and rebate consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysia's automotive lubricant consumption exceeds Singapore's by volume, yet Singapore commands higher per-liter value through premium synthetic penetration and stringent regulatory enforcement that eliminates informal re-refined oil circulation.
Central Region
Vehicle density peaks in Singapore's urban core where ride-hailing fleets and private passenger vehicles create concentrated demand for low-viscosity synthetics. The Land Transport Authority enforces periodic vehicle inspections under the Carbon Pricing Act that validate proper engine oil maintenance. Fleet operators in the Central Business District negotiate bulk procurement contracts with dedicated logistics providers.
West Region
Jurong Island hosts AP Oil's specialized manufacturing facility alongside petroleum refining complexes that supply base stocks to domestic blenders. The National Environment Agency enforces lubricant waste management protocols under the Environmental Public Health Act across this industrial corridor. Commercial vehicle workshops cluster near port logistics terminals serving the Port of Singapore Authority.
North Region
Residential estates with aging vehicle populations sustain demand for high-mileage formulations and conventional mineral oils. Independent workshops compete on price against quick-lube chains. The Land Transport Authority's vehicle inspection stations in Woodlands and Yishun compress margins for non-compliant operators.
East Region
Changi logistics hubs and airport-related commercial fleets specify premium synthetic grades to minimize downtime. The Carbon Pricing Act's escalating levy structure forces fleet managers toward fuel-efficient formulations. Service bay concentration around Tampines industrial zones enables just-in-time inventory systems.
Singapore Automotive Engine Oils Market Competitive Landscape
North American and European energy majors anchor the premium synthetic tier; Japanese and Singaporean specialists hold differentiated positions in tropical climate formulations and regional distribution logistics. Market structure concentrates around integrated petroleum companies with captive base oil supply and dedicated blending assets. Three archetypes dominate: global supermajors leveraging refining integration, Asia-Pacific specialists exploiting climate-specific formulation expertise, and regional distributors capturing procurement consolidation among fleet operators. Competitive dynamics center on framework contract negotiations with large fleet accounts and compliance infrastructure investments for waste oil traceability mandates.
Within the integrated supermajor tier, ExxonMobil Corporation and Royal Dutch Shell Plc exemplify the refining-to-retail model that secures supply contracts with concentrated commercial buyers. AP Oil and ENEOS Corporation occupy positions as Asia-Pacific specialists where tropical formulation knowledge and proximity to industrial zone logistics create defensive moats. These four entities represent the competitive poles around which procurement managers structure their supplier relationships.
| Leading Market Players |
|---|
| BP Plc (Castrol) |
| Chevron Corporation |
| ExxonMobil Corporation |
| Royal Dutch Shell Plc |
| TotalEnergies |
| AP Oil |
| ENEOS Corporation |
| Idemitsu Kosan Co. Ltd |
| Motul |
| Others |
Value Network & Pricing Analysis
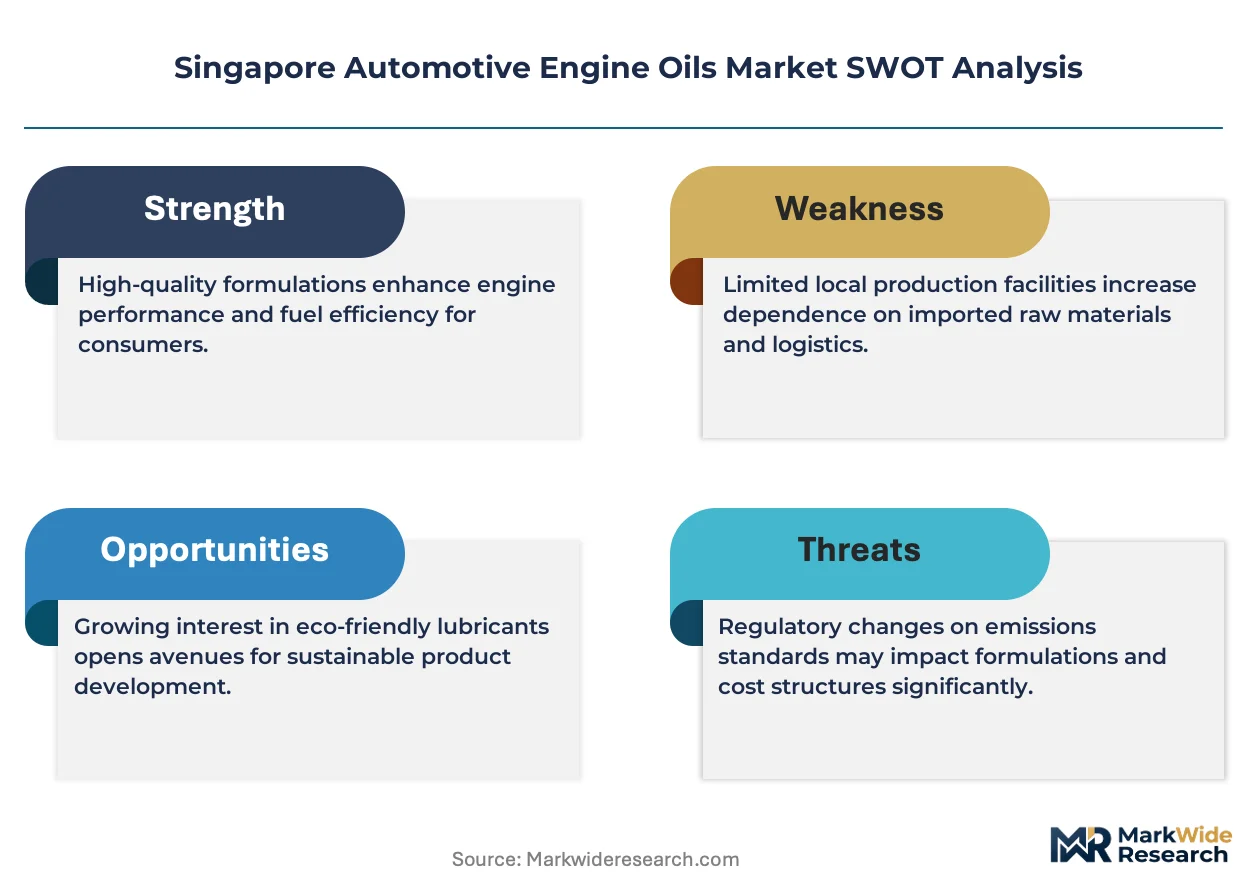
Captive refining and lubricant blending integration at Jurong Island anchors supply positioning and pricing power for Singapore's dominant blenders. This upstream control over base oil feedstock insulates integrated operators from freight volatility while enabling premium synthetic grade positioning that commands sustained margin capture against import-dependent competitors.
Pricing Analysis
Capacity additions in South Korea and Middle Eastern Group III base oil facilities are reshaping price floors for synthetic formulations entering Singapore. Three-tier pricing structure across premium synthetic, semi-synthetic, and mineral economy levels stratifies by certification grade under Land Transport Authority emission audit requirements and volume scale from fleet framework contracts. Cost compression in the mineral tier is intensifying because informal re-refined oil circulation erodes certified product margins. Independent motorcycle workshops exhibit highest price sensitivity; integrated fleet procurement directors at Tuas port logistics operators prioritize invoice consolidation over unit cost.
Supply Chain Analysis
Group III and Group IV base oil supply rests on South Korean, Middle Eastern, and Japanese specialty chemical producers. Singapore blenders draw from these sources for high-purity feedstocks while sourcing detergent-dispersant additive packages from European and Japanese compounders. Single-source vulnerability concentrates in tropical climate additive chemistry where extended lead times from specialty suppliers create formulation bottlenecks. Distribution runs through authorized lubricant distributors with dedicated logistics capabilities for just-in-time delivery to Jurong and Tuas industrial workshop clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Singapore's automotive engine oils market functions as a stable compounder where regulatory ratchet effects under the Carbon Pricing Act generate persistent synthetic grade upgrade cycles. Fleet procurement centralization and waste oil traceability mandates create durable competitive moats for compliant integrated suppliers.
For Market Incumbents: Extend framework contract coverage from engine oils into greases, hydraulic fluids, and emerging battery thermal management fluids to capture procurement consolidation at ride-hailing and port logistics fleets. Deepen captive base oil supply through backward integration into re-refining infrastructure licensed under National Environment Agency protocols, insulating margin position against import cost volatility from Korean and Middle Eastern suppliers.
For New Entrants and Emerging Players: Digital B2B procurement platforms connecting Jurong industrial workshops directly to blenders offer a technology-first wedge that disintermediates traditional distributor markups and captures transaction data for predictive inventory positioning. Target the fragmented independent motorcycle service bay segment where DIY maintenance culture and online price transparency have eroded incumbent brand loyalty, deploying bulk e-commerce fulfillment with QR-code traceability compliance as the go-to-market angle.
For Investors and Strategic Acquirers: Roll-up economics work for regional distributors with proprietary logistics platforms because National Environment Agency waste manifest requirements are accelerating compliance cost burdens that marginalize small independent operators lacking IT infrastructure. The five-to-ten year viability thesis centers on procurement consolidation toward integrated suppliers capable of cradle-to-grave traceability. Acquisition targets should display dense route networks in Tuas and Jurong industrial corridors with established fleet relationships. Watch Land Transport Authority electrification mandates for taxi and ride-hailing fleets as the inflection signal for battery thermal management fluid formulation capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Re-refining | Captive supply of certified base stocks under Environmental Public Health Act licensing reduces import dependency. |
| Digital Platform Integration | B2B procurement portals disintermediate distributor markups and enable predictive inventory positioning at Jurong workshops. |
| Electric Vehicle Fluid Adjacencies | Battery thermal management and e-axle lubrication address Land Transport Authority electrification mandates for taxi fleets. |
| Framework Contract Expansion | Annual volume agreements covering multiple lubricant categories capture procurement consolidation at Tuas port logistics operators. |
| QR-Code Traceability Compliance | Cradle-to-grave tracking systems satisfy National Environment Agency waste manifest amendments and accelerate market share consolidation. |
Research Methodology
Coverage spans Singapore's Central, West, North, and East regions, with primary inputs from each. The analysis combines structured interviews with fleet procurement managers at ride-hailing and port logistics operators, commercial vehicle workshop owners across Jurong and Tuas industrial zones, lubricant distributor operations heads, and National Environment Agency compliance officers. Secondary validation draws from Land Transport Authority vehicle inspection statistics, Environmental Public Health Act regulatory filings, customs import data for base oil shipments, and Singapore Petroleum Company industry reports. Bottom-up volume modeling triangulates against top-down market sizing from refining capacity and parc vehicle data.
Rate-of-change decomposition separates volume effects from value migration across the projection horizon. The analytical framework models segmentation across formulation chemistry, viscosity grade, vehicle application, and procurement channel dimensions, with additional granularity for regulatory compliance tier. CAGRs derive from regression analysis of historical synthetic penetration rates against Carbon Pricing Act levy escalation schedules. Industry-specific forecast inputs include hybrid powertrain adoption curves from Land Transport Authority fleet electrification targets and drain interval extension trends from original equipment manufacturer service recommendations.
The model holds under stable regulatory enforcement of waste oil traceability and continued Carbon Pricing Act escalation; deviation in electrification pace or informal re-refined oil crackdown intensity would shift volume and value trajectories. Forecasts reflect documented assumptions about fleet procurement consolidation and synthetic grade substitution elasticity. A small set of named triggers warrants ongoing watch: Land Transport Authority electrification mandates, National Environment Agency re-refining licensing decisions, and South Korean base oil export policy shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Proportioning Valves Market
Automotive Parts
Mexico Automotive Parts Zinc Die Casting Market
Automotive Parts
Engine Oil Market
Automotive Parts
Poland Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Crankcase Additives Market
Automotive Parts
Morocco Automotive Engine Oils Market
Automotive Parts
Automotive AHSS Market
Automotive Parts
India Automotive Coolant Market
Automotive Parts
Automotive Electric Parking Brakes Market
Automotive Parts
Automotive Brake Shims Market
Automotive Parts
Bearing Steel Balls for New Energy Vehicles Market
Automotive Parts
Automotive Trim Part Market
Automotive Parts
Heavy Duty Clutches Market
Automotive Parts
Uae Passenger Vehicles Lubricants Market
Automotive Parts
Off-Road Hoses Market
Automotive Parts
Japan Automotive Parts Zinc Die Casting Market