
 Meat Extract Market | 2026-2036
Meat Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Meat Extract Market Analysis
EU REACH chemical registration and safety evaluation rules are recalibrating the cost-of-entry calculus for meat extract processors operating across European markets. Givaudan leverages its flavor science infrastructure to sustain premium positioning in savory taste solutions. Essentia Protein Solutions anchors its competitive stance through specialized protein extraction capabilities for food and pharmaceutical applications. JBS S.A. competes by controlling integrated livestock-to-extract supply chains across multiple protein categories.
Meat extract comprises concentrated soluble substances derived from animal tissues through controlled hydrolysis, yielding products with elevated free amino acid and peptide content typically standardized to specific nitrogen levels for industrial use. Beef extract dominates volume flows into culture media and broth manufacturing, while powder forms command wider distribution reach due to extended shelf stability and reduced logistics complexity. Chicken extract occupies growing share in culinary and foodservice channels as clean-label flavor demand intensifies among restaurant operators and packaged food developers.
FDA food safety standards in the United States and EFSA hygiene regulations in Europe shape pathogen control protocols and labeling requirements that directly determine facility certification and cross-border market access. Japan's Ministry of Health, Labour and Welfare maintains distinct specifications for meat-derived food additives that influence export qualification procedures for international suppliers. Stakeholders must monitor divergence between regional allergen declaration rules and emerging biotechnology-based alternative protein regulations that could redefine competitive boundaries for traditional extract sources.
Market Dynamics
EU REACH chemical registration requirements are recalibrating capital allocation for meat extract processors, forcing facility upgrades that favor larger-scale operators with compliance infrastructure already in place.
Growth Catalysts
- Clean-label broth demand:Food manufacturers are expanding meat extract use in savory flavor bases as restaurant operators and packaged food developers seek recognizable ingredient lists.
- F-Gas Regulation tightening:European processors investing in low-emission thermal processing equipment gain operational continuity as older facilities face phase-out deadlines.
- Culture media standardization:Biotechnology laboratories are specifying beef extract nitrogen content more precisely, creating specification-driven procurement relationships with qualified suppliers.
Market Restraints
- Livestock input volatility:Cattle and poultry supply fluctuations in Brazil and Australia transmit directly to extract raw material costs, compressing processor margins during herd contraction cycles.
- Allergen declaration fragmentation:Divergent labeling requirements between FDA standards in the United States and EFSA protocols in Europe force dual-format packaging investments.
- Plant protein substitution:Fermentation-derived savory flavor alternatives are capturing share in foodservice applications where taste precision requirements allow formulation flexibility.
Strategic Opportunities
- Pharmaceutical-grade extraction:Specialized protein isolation for cell culture media commands premium positioning as biologics manufacturing expands in Singapore and Switzerland.
- Direct-to-manufacturer e-procurement:Digital platforms are collapsing traditional distributor layers, allowing extract processors to capture margin previously allocated to intermediaries.
- Carbon accounting alignment:EU Green Deal sustainability reporting requirements favor suppliers with verified supply chain emissions data, creating first-mover advantage for integrated livestock-to-extract operators.
Industry Challenges
- Cross-functional compliance expertise:Facilities must simultaneously manage food safety auditors, chemical safety assessors, and pharmaceutical GMP inspectors, stretching quality assurance staffing.
- Legacy equipment retrofitting:Older hydrolysis vessels require expensive automation upgrades to meet real-time process monitoring mandates without production interruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meat Extract Market |
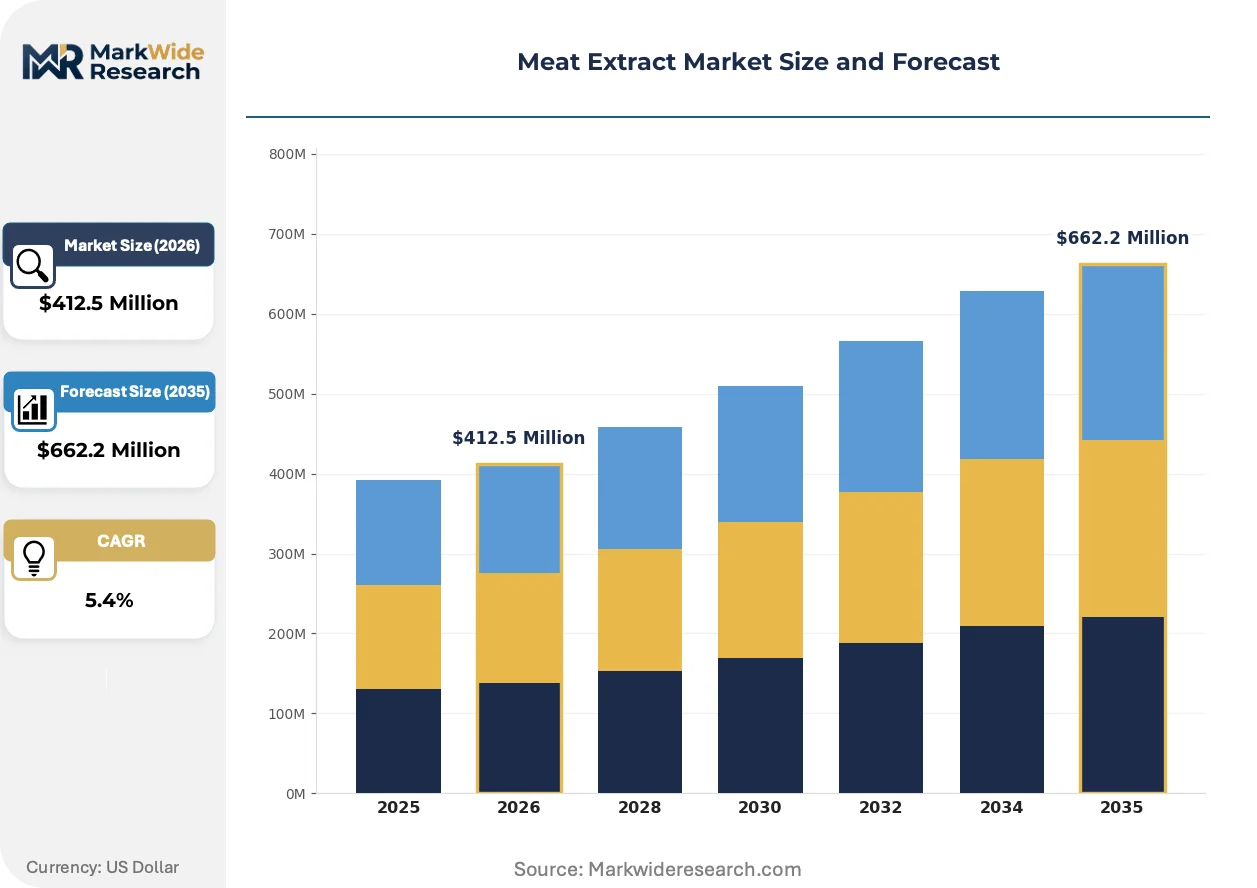
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $662.2 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef Extract, Chicken Extract, Pork Extract, Fish Extract Form: Paste, Powder, Liquid, Granules Packaging Type: Bottles, Pouches, Jars, Tins End User: Food Industry, Culinary Professionals, Home Cooks, Restaurants |
| Companies Covered | Givaudan, Nikken Foods, Essentia Protein Solutions, IDF, Carnad A/S, Haco Holding AG, BRF S.A., JBS S.A., Titan Biotech Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meat Extract Market Emerging Trajectories
Processing technology convergence with digital quality control systems is compressing batch-to-batch variation, enabling meat extract suppliers to serve pharmaceutical and food applications from shared production lines.
Enzymatic hydrolysis optimization is integrating machine learning-driven parameter adjustment into continuous processing systems. Pharmaceutical contract manufacturers are adopting these platforms fastest, with three-year equipment refresh cycles replacing decade-long capital intervals. This integration is enabling nitrogen standardization precision that satisfies both food-grade and cell-culture specifications from identical raw material inputs.
REACH authorization procedures for processing chemicals are extending substance approval timelines, forcing European extract processors to qualify alternative hydrolysis catalysts. Industrial consequence includes reformulation costs and temporary capacity constraints. Germany-based facilities are responding by accelerating in-house enzymatic process development to reduce dependency on external chemical registrations.
Specification-driven procurement contracts are replacing spot-market purchasing for high-volume food manufacturers. Long-term agreements with embedded quality auditing rights are displacing traditional distributor relationships. This pattern is most visible in United Kingdom foodservice supply chains, where consolidated buying groups now mandate supplier process documentation as a contract precondition.
Meat Extract Market Segmentation
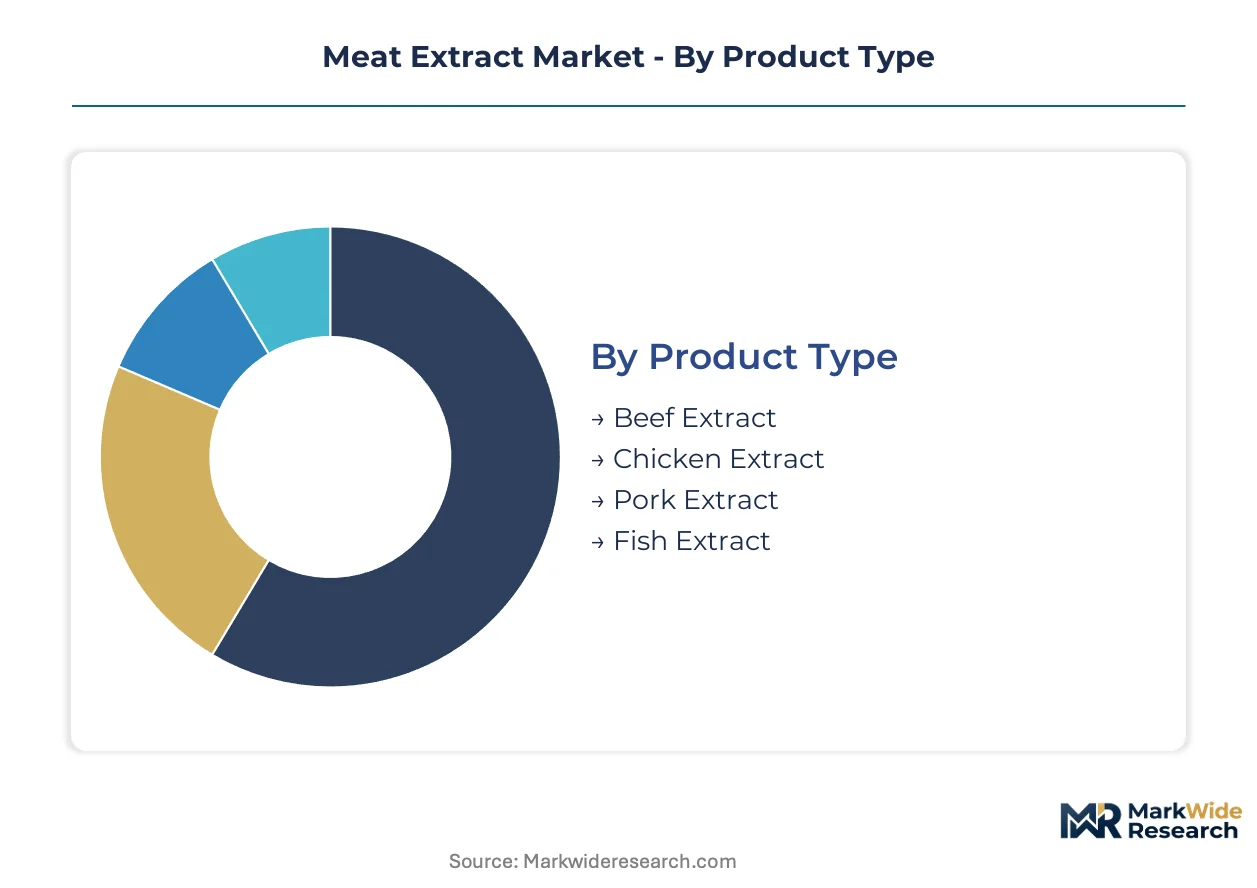
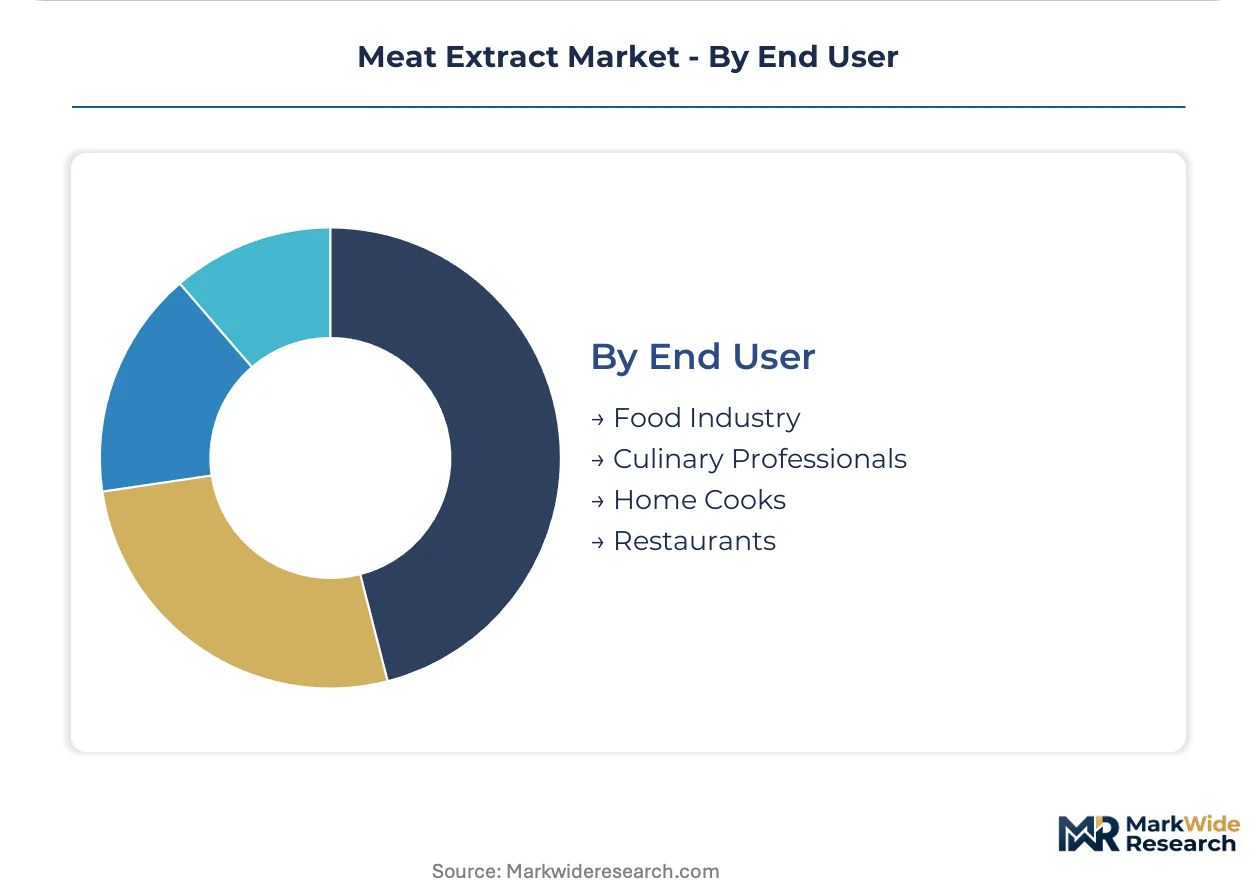
Meat extract segmentation reflects divergent technical requirements across pharmaceutical, foodservice, and retail channels. Specification precision, shelf stability, and handling convenience drive purchasing decisions differently in each vertical.
Product Type:
Extraction chemistry and amino acid profiles distinguish competitive positioning across source materials.
- Beef Extract:Hydrolyzed bovine tissue yields elevated free amino nitrogen standardized for cell culture media and diagnostic broth manufacturing. Biotechnology laboratories in Germany and Switzerland specify nitrogen content tolerances within narrow bands, locking procurement relationships with qualified suppliers.
- Chicken Extract:Lower molecular weight peptides deliver cleaner flavor profiles for culinary applications. Restaurant operators in France and the United Kingdom specify chicken extract for clean-label savory bases as allergen-conscious menu development accelerates.
- Pork Extract:Intermediate peptide distribution suits processed meat flavor enhancement and regional sauce formulations.
- Fish Extract:Distinct umami compounds serve seafood broth applications and specialized Asian culinary formulations.
Beef extract leads on scale; chicken extract leads on momentum.
Form:
Moisture content and dissolution kinetics determine logistics economics and application suitability.
- Powder:Spray-dried concentrates achieve 24-month shelf stability with reduced cold-chain dependency. Industrial food manufacturers in the United Kingdom favor powder for bulk savory seasoning production where extended storage and rail freight economics matter.
- Paste:Higher moisture retention preserves volatile flavor compounds for premium culinary applications. French gastronomy suppliers specify paste for chef-directed formulations where aromatic intensity justifies refrigerated distribution.
- Liquid:Immediate solubility serves high-throughput foodservice operations and automated dispensing systems.
- Granules:Controlled particle size reduces dusting during industrial handling while maintaining rapid hydration.
Powder commands volume leadership; paste captures margin premiums.
Packaging Type:
Barrier properties and dispensing ergonomics align with end-user operational requirements.
- Pouches:Flexible multilayer films reduce shipping cube and enable portion-controlled dispensing. Restaurant chains in Germany specify pouches for back-of-house efficiency where storage density and waste minimization drive procurement.
- Bottles:Rigid containment suits retail shelf presentation and controlled pour applications for home cooks.
- Jars:Wide-mouth access accommodates spoon-based portioning in professional culinary environments.
- Tins:Metal barrier protection serves extended ambient storage for institutional foodservice inventory.
Pouches expand most quickly; tins retain institutional loyalty.
End User:
Specification stringency and volume scale separate commercial from consumer demand patterns.
- Food Industry:Manufacturers of packaged soups, sauces, and ready meals require batch-to-batch consistency and documentation for supplier audits. Processed food producers in France negotiate long-term contracts with embedded quality verification rights.
- Restaurants:Independent and chain operators prioritize flavor intensity and kitchen workflow efficiency over documentation depth.
- Culinary Professionals:Chef-driven purchasing emphasizes provenance labeling and artisanal processing narratives for menu storytelling.
- Home Cooks:Retail-packaged formats with recipe guidance and resealability dominate supermarket channel placement.
Food industry leads on volume; restaurants lead on specification flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized hydrolysis technicians and food safety auditors concentrate in Germany, Switzerland, and the United Kingdom, anchoring European meat extract processing expertise and compliance infrastructure.
Germany
Biotechnology laboratories in Munich and Heidelberg specify precise nitrogen tolerances for beef extract procurement, locking qualified suppliers into long-term contracts. ECHA REACH authorization procedures extend chemical approval timelines, forcing reformulation investments at processing facilities. Bavaria-based manufacturers accelerate in-house enzymatic development to reduce dependency on external catalyst registrations.
Switzerland
Pharmaceutical contract manufacturers in Basel and Geneva adopt three-year equipment refresh cycles for cell culture media production. Swissmedic maintains distinct specifications for meat-derived additives that shape export qualification procedures for international suppliers. The Basel-Land industrial cluster concentrates precision extraction capacity serving biologics manufacturing expansion.
United Kingdom
Consolidated foodservice buying groups mandate supplier process documentation as contract preconditions, displacing traditional distributor relationships. EFSA hygiene regulations determine facility certification requirements for cross-border market access into continental Europe. Greater London anchors specification-driven procurement for packaged soup and ready meal manufacturers.
France
Restaurant operators in Paris and Lyon specify chicken extract for clean-label savory bases as allergen-conscious menu development accelerates. ANSM maintains oversight of pharmaceutical-grade extraction facilities serving cell culture applications. The Auvergne-Rhône-Alpes region concentrates culinary extract production for chef-directed formulations.
Japan
Food manufacturers in Tokyo and Osaka expand meat extract use in clean-label broths as consumer preference shifts toward recognizable ingredient lists. The Ministry of Health, Labour and Welfare maintains distinct specifications for meat-derived food additives that influence import qualification procedures. The Kanto industrial corridor anchors umami compound research for specialized Asian culinary formulations.
Meat Extract Market Vendor Landscape
The competitive structure tilts toward integrated livestock-to-extract operators with captive raw material supply. Processing capability concentrates among mid-scale specialists with enzymatic hydrolysis expertise and pharmaceutical-grade certification. Three archetypes dominate: integrated protein conglomerates controlling upstream livestock supply, flavor science specialists leveraging taste modulation infrastructure, and pharmaceutical-grade extraction contractors serving cell culture media. Capacity expansion and strategic partnerships represent the dominant competitive vectors as facilities retrofit for REACH-compliant catalyst systems.
Among integrated protein conglomerates, JBS S.A. and BRF S.A. exemplify the livestock-backward archetype with captive supply chains across multiple protein categories. Givaudan occupies a position within the flavor science tier, leveraging sensory research infrastructure for savory taste solutions. Essentia Protein Solutions anchors the specialized extraction segment, representing pharmaceutical-grade capability for food and cell culture applications.
| Leading Market Players |
|---|
| Givaudan |
| Nikken Foods |
| Essentia Protein Solutions |
| IDF |
| Carnad A/S |
| Haco Holding AG |
| BRF S.A. |
| JBS S.A. |
| Titan Biotech Ltd. |
| Others |
Supply Flow & Price Mechanics
Livestock procurement costs in Brazil and Australia transmit directly through three pricing tiers for meat extract buyers, with pharmaceutical-grade nitrogen-standardized product commanding premium positioning over foodservice paste formats.
Pricing Analysis
Bundle-unbundle splits separate technical support and certification documentation from base product pricing. Three-tier pricing structure across pharmaceutical-grade, food-industry standard, and economy foodservice levels reflects nitrogen precision tolerances and REACH compliance documentation depth. Cost compression in economy tiers is intensifying because fermentation-derived savory alternatives capture share in flexible formulation applications. Quick-service restaurant chains exhibit highest price sensitivity; biotechnology laboratories in Basel and Heidelberg show lowest sensitivity due to specification lock-in with qualified suppliers.
Supply Chain Analysis
Dual-sourcing requirements from consolidated United Kingdom foodservice buying groups and German biotechnology laboratories mandate multi-supplier qualification for critical nitrogen-standardized beef extract. Supply concentrates in Brazil, Australia, and Germany for livestock inputs and precision extraction capability. Raw material flows draw from cattle and poultry processing by-products, enzymatic catalyst inventories, and multilayer flexible packaging films. Single-source vulnerability concentrates in REACH-registered hydrolysis catalyst supply. Distribution runs through direct-to-manufacturer e-procurement platforms and specialized chemical distributors serving pharmaceutical contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory value as EU REACH authorization timelines extend and F-Gas Regulation phase-out deadlines force thermal processing equipment replacement, locking compliant processors into premium procurement relationships.
For Market Incumbents: Extend certification depth into pharmaceutical-grade extraction to defend against fermentation-derived savory alternatives capturing foodservice share. Invest in captive livestock supply integration in Brazil to buffer margin compression during herd contraction cycles. Accelerate in-house enzymatic process development to reduce dependency on external REACH-registered catalyst suppliers facing extended approval timelines.
For New Entrants and Emerging Players: The price-point gap between pharmaceutical-grade nitrogen-standardized extract and economy foodservice paste creates entry space for mid-tier certified food-industry product. Target French and United Kingdom restaurant operator procurement where clean-label savory base demand outpaces qualified supplier capacity. Pursue direct-to-manufacturer e-procurement platform partnerships to bypass entrenched distributor relationships.
For Investors and Strategic Acquirers: Consolidation pressure builds where REACH compliance infrastructure and pharmaceutical-grade certification concentrate among mid-scale specialists with limited succession planning. Five-to-ten year viability favors integrated livestock-to-extract operators with verified supply chain emissions data aligned to EU Green Deal sustainability reporting. Monitor divergence between regional allergen declaration rules as signal for dual-format packaging investment requirements that favor scaled processors.
| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade Certification Investment | Qualifies processors for Basel and Geneva biologics manufacturing expansion with nitrogen precision tolerances. |
| Backward Integration into Livestock Supply | Captures margin compression buffer during Brazil and Australia herd contraction cycles. |
| In-House Enzymatic Process Development | Reduces dependency on ECHA REACH-registered catalysts facing extended authorization timelines. |
| Direct-to-Manufacturer E-Procurement Platform | Collapses distributor layers to capture margin previously allocated to intermediaries in United Kingdom foodservice. |
| Carbon Accounting Verification Program | Aligns with EU Green Deal sustainability reporting to create first-mover advantage for integrated operators. |
Methodological Framework
Multiple input streams — structured interviews with extraction facility quality assurance directors, procurement leads at German biotechnology laboratories, and United Kingdom foodservice buying group managers; secondary validation against ECHA REACH substance registration databases, EU F-Gas Regulation implementation timelines, and customs trade flow records; plus bottom-up capacity modeling reconciled with top-down demand estimation from cell culture media and packaged food manufacturing — were triangulated to construct market estimates.
Historical volume trajectories were cross-referenced against panel input from plant managers and regulatory affairs specialists to project growth across the analysis window. Segmentation dimensions modeled include source material type, form factor moisture content, end-user specification stringency, and regional regulatory cluster. CAGRs were derived from slope analysis of normalized growth curves calibrated to equipment refresh cycle timing and procurement contract duration patterns in pharmaceutical and food manufacturing channels.
The model assumes a particular technology adoption path; alternative pathways for machine learning-driven enzymatic hydrolysis parameter optimization would alter the outlook for batch-to-batch variation compression and shared production line viability. Deviation in EU REACH authorization timelines for processing chemicals or F-Gas Regulation enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
North America Cheese Powder Market
Ingredients
Asia-Pacific Fats and Oil Market
Ingredients
Global Dairy Protein Ingredients Market
Ingredients
Rose Extract Market
Ingredients
Mannan-Oligosaccharide (MOS) Market
Ingredients
Gluten-Free Flour Market
Ingredients
North America Brewing Enzymes Market
Ingredients
Cocoa Bean Extract Market
Ingredients
Black Cumin Seed Oil Market
Ingredients
Corn Gluten Meal Market
Ingredients
Asia-Pacific Plant Protein Ingredients Market
Ingredients
Liquid Malt Extract Products Market
Ingredients
All Purpose Flour Market
Ingredients
Plant-Based API Market
Ingredients
Horehound Extract Market
Ingredients
Ground-Nut Oil Market