
 Winter Melon Peel Extract Market | 2026-2036
Winter Melon Peel Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Winter Melon Peel Extract Market Insights
Direct procurement between Chinese extract manufacturers and Western nutraceutical finished-goods makers is reshaping traditional broker-mediated supply chains. Xi'an Le Sen Bio-Technology leverages its GMP-certified facility to sustain long-term supply agreements with North American dietary supplement brands. Shaanxi Jintai Biological Engineering anchors its competitive position through backward integration into winter melon cultivation across Shaanxi Province. Indena S.p.A. differentiates by applying pharmaceutical-grade purification standards historically developed for Italian botanical extracts.
Winter melon peel extract comprises triterpenoids, flavonoids, and polysaccharides recovered from the outer pericarp through aqueous or ethanol extraction, typically standardized to 10-20% total saponins for commercial use. The extract functions primarily as a functional ingredient in antioxidant and anti-inflammatory formulations across nutraceutical and cosmeceutical applications. Powder formats dominate current volume due to superior stability in bulk ingredient logistics and compatibility with capsule and tablet manufacturing lines. Liquid extracts capture expanding demand from beverage manufacturers seeking clean-label botanical fortification without reconstitution steps. Nutraceutical applications lead value generation, though cosmetic brands increasingly specify peel-derived materials for claims around skin barrier protection and melanin inhibition.
China's NMPA enforces GB standards for botanical extract heavy metal and pesticide residue limits, while the US FDA exercises DSHEA authority over New Dietary Ingredient notifications for novel extract presentations entering American commerce. REACH registration obligations in Europe constrain small-volume exporters from establishing direct B2B relationships with EU-based cosmetic and pharmaceutical formulators. Stakeholders must monitor evolving pharmacopeial monograph developments and regional clean-label certification schemes to anticipate which purity benchmarks will become non-negotiable for market access.
Market Dynamics
China's NMPA tightened botanical extract purity standards in 2024, forcing suppliers to upgrade chromatographic testing protocols and reshaping competitive positioning around certification capabilities rather than raw volume capacity.
Growth Catalysts
- Cosmeceutical antioxidant demand:South Korean cosmetic brands are accelerating procurement of peel-derived triterpenoids for melanin-inhibition formulations, creating pull-through for standardized extract grades.
- Clean-label beverage fortification:Liquid extract formats are capturing demand from beverage manufacturers seeking botanical fortification without reconstitution steps, expanding addressable applications beyond capsules.
- REACH registration compliance:European cosmetic formulators are qualifying new suppliers who have completed full substance registration, opening direct B2B channels previously blocked by regulatory barriers.
Market Restraints
- Input cost volatility:Winter melon cultivation cycles in Shaanxi Province face climate sensitivity, creating raw material availability constraints for non-integrated processors.
- Heavy metal testing burden:China's GB standards for pesticide residue limits require expensive chromatographic infrastructure, elevating fixed costs for small-batch toll manufacturers.
- Synthetic antioxidant substitution:Butylated hydroxytoluene and ascorbic acid derivatives compete on cost in mass-market nutraceutical applications, pressuring natural extract pricing.
Strategic Opportunities
- Southeast Asian distribution expansion:Zhejiang Province toll manufacturers are capturing export orders to Vietnamese and Thai nutraceutical distributors, building regional brand recognition.
- Pharmaceutical-grade purification convergence:Supercritical CO2 extraction is hybridizing with traditional aqueous methods to enable USP-grade monograph development for prescription adjuvant applications.
- Dual carbon policy alignment:China's MEE carbon intensity targets are incentivizing solvent recovery systems that reduce ethanol waste, qualifying suppliers for preferential state procurement.
Industry Challenges
- Analytical chemistry talent scarcity:HPLC method development and validation expertise is concentrated among senior technicians in Xi'an and Hangzhou, constraining facility expansion timelines.
- DSHEA notification complexity:US FDA New Dietary Ingredient submissions for novel saponin standardizations require 90-180 day review cycles, delaying revenue recognition for innovative extract presentations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Winter Melon Peel Extract Market |
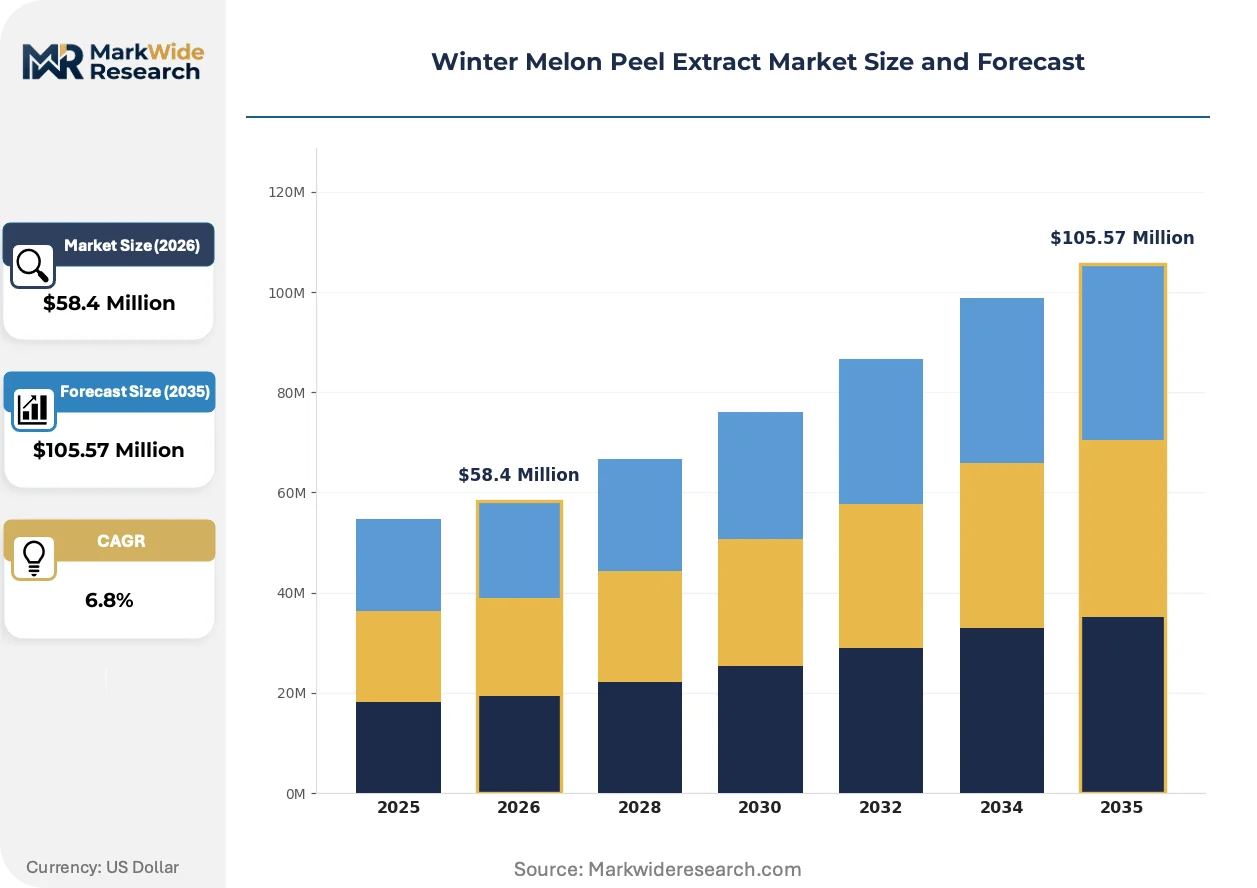
| Market Size in 2026 | $58.4 Million |
| Market Size in 2035 | $105.57 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Capsule, Extract Application: Nutraceuticals, Pharmaceuticals, Cosmetics, Food & Beverages Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers End User: Health-conscious Consumers, Herbal Product Manufacturers, Cosmetic Brands, Food Manufacturers |
| Companies Covered | Herbalife Nutrition Ltd., NutraBlend Foods, Naturex S.A., Ginkgo BioWorks, Xi'an Le Sen Bio-Technology, Shaanxi Jintai Biological Engineering, Hunan Nutramax, Chengdu Wagott, Indena S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Winter Melon Peel Extract Market Trends and Innovations
Extraction technology convergence and regulatory differentiation are compressing the viable supplier base while creating premium tiers around certification depth and application-specific standardization.
Supercritical fluid extraction is hybridizing with conventional ethanol-based recovery to preserve heat-sensitive flavonoid profiles while achieving pharmaceutical-grade purity thresholds. North American dietary supplement brands are qualifying these dual-process materials for inflammation-support claims. The technology is compressing margins for single-method processors who cannot meet dual-specification contracts.
China's NMPA 2024 botanical extract purity enforcement is disqualifying legacy suppliers lacking in-house chromatography capabilities. Industrial consequence includes accelerated consolidation among Zhejiang and Shaanxi processors. Cosmetic ingredient divisions within these regions are responding by investing in ICP-MS heavy metal screening to maintain export eligibility.
Direct manufacturer-to-formulator relationships are displacing traditional broker-mediated procurement in North American nutraceutical supply chains. Long-term supply agreements now specify lot-level COA transparency and audit rights previously mediated by trading intermediaries. This pattern is most visible in California and Utah-based dietary supplement manufacturing clusters.
Winter Melon Peel Extract Market Segmentation
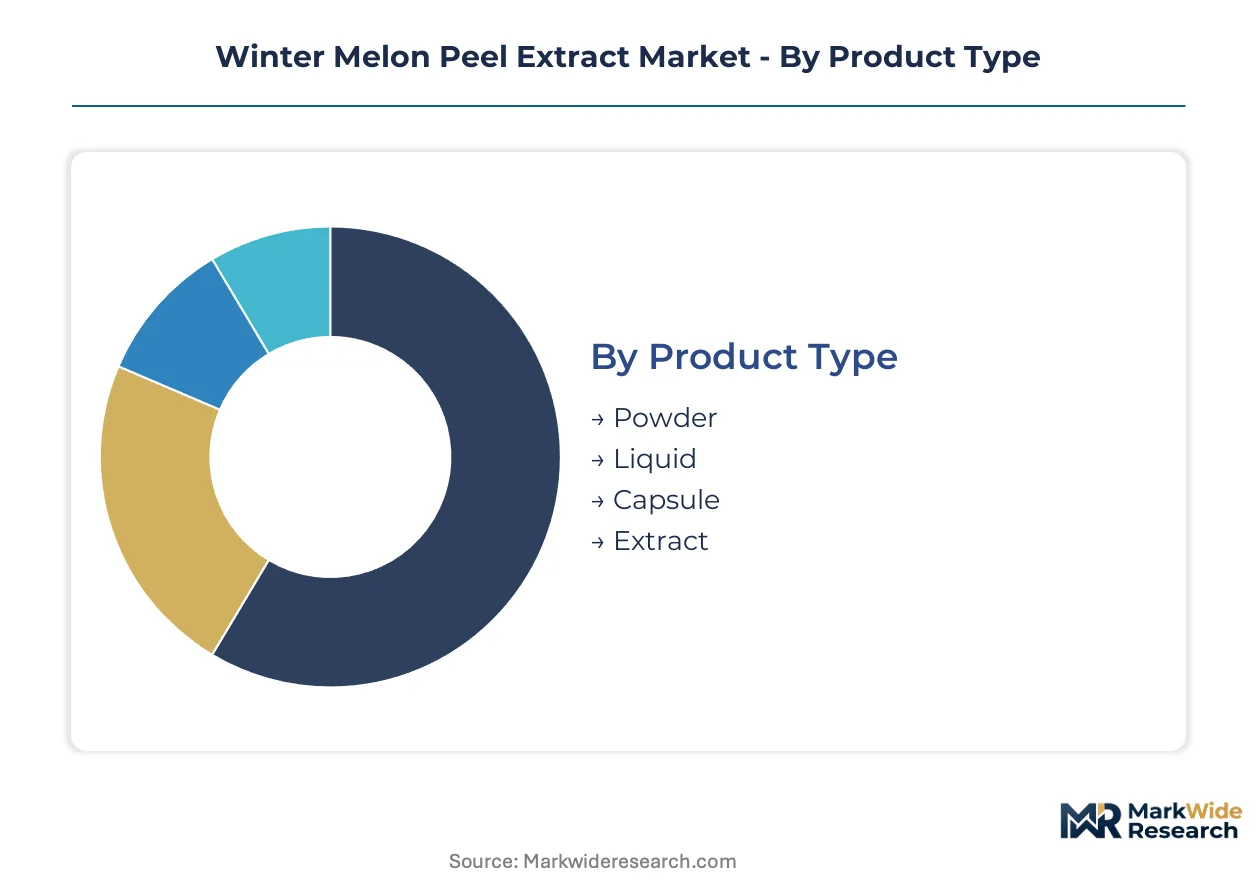
Winter melon peel extract suppliers configure production lines around format stability and customer technical service requirements. Segment boundaries reflect divergent purity specifications and formulation support intensity across nutraceutical and cosmetic value chains.
Product Type:
After-sales service intensity peaks with liquid extract formats requiring shelf-life monitoring and reconstitution guidance, while powder formats demand minimal technical intervention beyond COA documentation.
- Powder:Spray-dried or freeze-dried particulate standardized to 10-20% total saponins dominates bulk ingredient logistics. Zhejiang Province toll manufacturers supply capsule and tablet producers in Vietnam and Thailand where humidity-stable formats reduce packaging complexity. Powder commands the largest volume position.
- Liquid:Aqueous or hydroalcoholic solutions preserve heat-sensitive flavonoid profiles for beverage fortification applications. South Korean cosmetic formulators specify liquid grades for direct incorporation into melanin-inhibition serums without reconstitution steps. Momentum sits with liquid as clean-label beverage brands accelerate procurement.
- Capsule:Pre-encapsulated single-ingredient or blended formulations target finished-goods brands lacking in-house tableting capacity.
- Extract:Crude or semi-purified preparations serve regional traditional medicine practitioners and compounding pharmacies.
Powder holds the largest share; momentum sits with liquid.
Application:
Cost tier stratification separates pharmaceutical-grade purification investments from commodity nutraceutical specifications.
- Nutraceuticals:Dietary supplement applications drive value concentration through inflammation-support and antioxidant positioning. North American brands qualify suppliers via DSHEA New Dietary Ingredient notifications for novel saponin standardizations. Nutraceuticals anchor current revenue generation.
- Cosmetics:Skin barrier protection and melanin-inhibition claims accelerate procurement from South Korean brands seeking peel-derived triterpenoids. REACH-registered European formulators are qualifying direct B2B channels previously blocked by regulatory complexity. Cosmetics is expanding most quickly.
- Pharmaceuticals:Prescription adjuvant applications require USP-grade monograph development through supercritical CO2 hybrid extraction.
- Food & Beverages:Clean-label botanical fortification in functional beverages and wellness shots captures emerging demand.
Nutraceuticals dominate absolute value; cosmetics shows the steepest expansion trajectory.
Distribution Channel:
Volume concentration favors wholesaler-mediated procurement for bulk ingredient flows, while margin capture shifts toward direct manufacturer relationships.
- Online Retail:Direct-to-consumer finished goods and small-batch ingredient sourcing for artisan formulators.
- Supermarkets:Mass-market shelf presence for pre-formulated capsule and liquid wellness products.
- Specialty Stores:Premium positioning through natural product retailers and apothecary channels.
- Wholesalers:Broker-mediated and increasingly direct procurement between Chinese extract manufacturers and Western finished-goods makers. Xi'an and Hangzhou clusters serve North American dietary supplement manufacturing bases in California and Utah through long-term supply agreements specifying lot-level COA transparency.
Wholesalers transact the highest volume; direct procurement is gaining share fastest.
End User:
Customer type determines specification depth, with cosmetic brands demanding the most intensive analytical documentation.
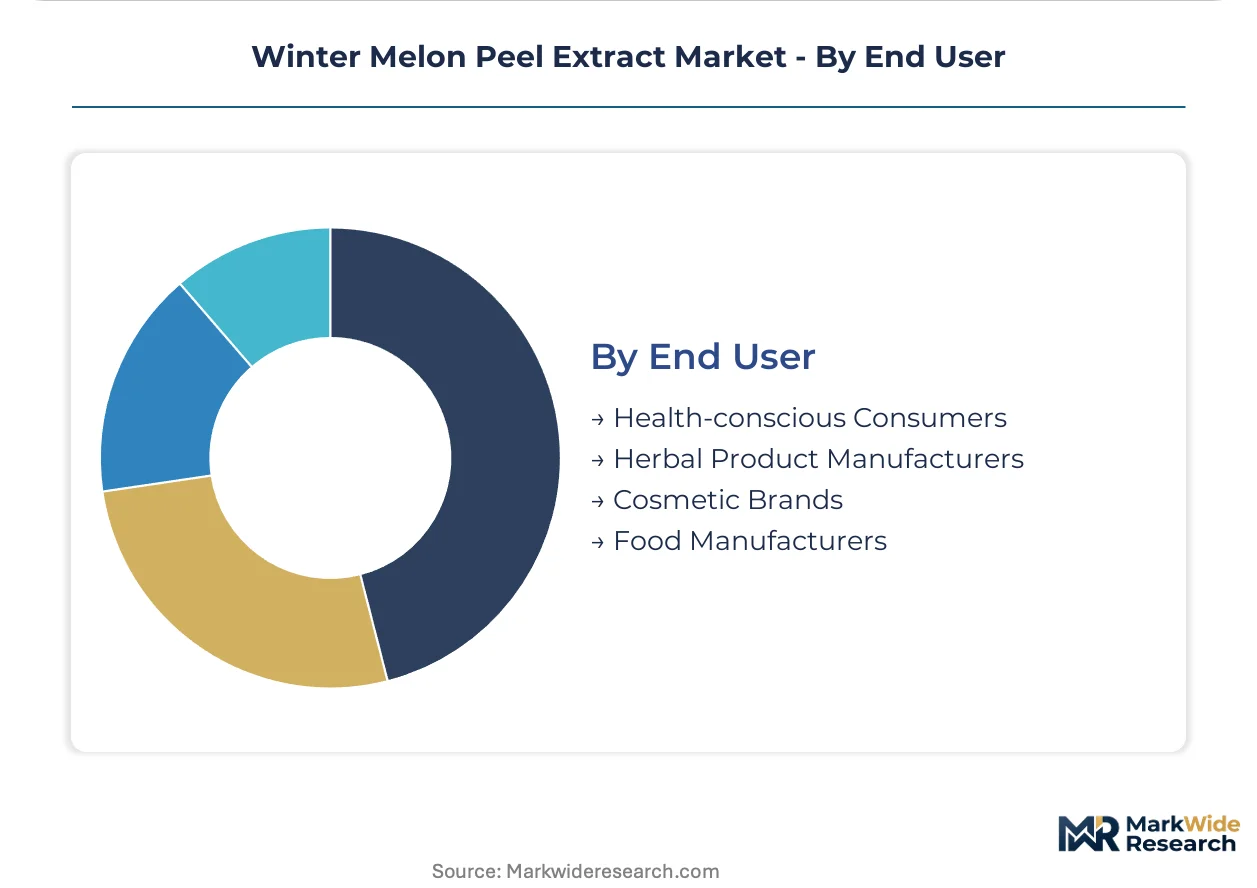
- Health-conscious Consumers:Terminal demand for finished capsules, liquids, and functional beverages through retail channels.
- Herbal Product Manufacturers:Traditional medicine compounders sourcing crude extracts for regional distribution.
- Cosmetic Brands:South Korean and European formulators specify ICP-MS heavy metal screening and chromatographic purity certificates to satisfy NMPA and REACH compliance. Cosmetic procurement requires the most intensive supplier qualification protocols.
- Food Manufacturers:Beverage producers seeking clean-label fortification without synthetic antioxidant alternatives.
Cosmetic brands command premium pricing tiers; food manufacturers represent the fastest-emerging demand pool.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dual carbon policy and South Korea's K-beauty export incentives are redirecting procurement flows toward certified extract suppliers. Regulatory tightening across multiple jurisdictions is compressing the viable supplier base while opening premium channels for compliant producers.
China
NMPA's 2024 GB standard enforcement for botanical heavy metal limits is disqualifying legacy processors lacking ICP-MS capabilities. The Ministry of Ecology and Environment carbon intensity targets incentivize solvent recovery investments in ethanol-based extraction. Shaanxi Province cultivation clusters and Zhejiang toll manufacturing bases are consolidating under integrated processors who control both raw material sourcing and chromatographic testing infrastructure.
South Korea
MFDS cosmetic ingredient safety guidelines and K-beauty export promotion programs accelerate demand for melanin-inhibition actives. Seoul-based cosmetic brands specify peel-derived triterpenoids with documented antioxidant profiles for brightening serum formulations. Gyeonggi-do biotech clusters are qualifying Chinese suppliers through direct audit programs that bypass traditional distributor layers.
United States
FDA DSHEA New Dietary Ingredient notification requirements for novel saponin standardizations create 90-180 day regulatory lead times. California and Utah dietary supplement manufacturing clusters are executing long-term supply agreements with GMP-certified Chinese extractors specifying lot-level COA transparency. EPA solvent discharge regulations elevate compliance costs for US-based toll processors competing against imported finished extracts.
Italy
EMA botanical drug development guidelines and REACH registration obligations constrain small-volume extractors from EU market access. Lombardy-based pharmaceutical ingredient specialists apply USP-grade purification protocols historically developed for Italian botanical monographs. Milan cosmetic formulators are qualifying winter melon peel materials through pharmaceutical-grade supplier audits that exceed standard cosmetic ingredient requirements.
Vietnam
Ministry of Health functional food registration pathways and ASEAN harmonization initiatives expand distribution opportunities for standardized extracts. Ho Chi Minh City nutraceutical distributors are sourcing powder formats from Zhejiang Province toll manufacturers for capsule and tablet re-export throughout Southeast Asia. Da Nang logistics corridors reduce transit times for humidity-sensitive botanical materials entering regional markets.
Winter Melon Peel Extract Market Competitive Landscape
On the supply side, the industry is consolidating around certification depth rather than raw volume capacity, with NMPA compliance and REACH registration serving as the primary sorting mechanisms. Three archetypes dominate: integrated cultivator-processors controlling Shaanxi Province farmland, Zhejiang-based toll manufacturers serving export markets, and European pharmaceutical-grade specialists applying monograph-grade purification. Competitive moves center on backward integration into winter melon cultivation and supercritical CO2 extraction technology licensing to access dual-process contracts.
Within the integrated cultivation tier, Shaanxi Jintai Biological Engineering anchors Chinese supply through upstream control over provincial farmland. Xi'an Le Sen Bio-Technology occupies the GMP-certified export channel position, while Indena S.p.A. exemplifies the European pharmaceutical-grade archetype applying Italian botanical purification standards. These three represent the certification-depth segmentation that now determines market access rather than scale alone.
| Leading Market Players |
|---|
| Herbalife Nutrition Ltd. |
| NutraBlend Foods |
| Naturex S.A. |
| Ginkgo BioWorks |
| Xi'an Le Sen Bio-Technology |
| Shaanxi Jintai Biological Engineering |
| Hunan Nutramax |
| Chengdu Wagott |
| Indena S.p.A. |
| Others |
Pricing and Supply Chain Analysis
Shaanxi Province cultivation clusters anchor upstream supply through captive winter melon farmland, concentrating margin capture among integrated processors who command pharmaceutical-grade pricing premiums while toll manufacturers in Zhejiang compete on volume throughput for Southeast Asian nutraceutical distributors.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, cosmetic-grade, and commodity nutraceutical levels stratifies extract values based on chromatographic purity certification and ICP-MS heavy metal documentation. Price differentiation hinges on NMPA GB standard compliance and REACH registration completion, with cosmetic brands in Seoul and Milan paying premiums for audit-transparent supply chains. Cost compression in commodity powder grades is intensifying because synthetic antioxidant substitutes pressure natural extract positioning. Small-batch toll manufacturers exhibit highest price sensitivity, while GMP-certified direct exporters to North American dietary supplement brands maintain pricing power through long-term offtake agreements.
Supply Chain Analysis
China's NMPA 2024 botanical extract purity enforcement functions as a de facto export control regime, restricting flows from legacy processors lacking in-house chromatography capabilities and consolidating viable supply among certified Shaanxi and Zhejiang facilities. Geographic supply concentration centers on China, with secondary processing nodes in Vietnam and Thailand serving regional Southeast Asian distribution. Raw material dependencies draw from winter melon cultivation cycles, ethanol solvent supply, and supercritical CO2 extraction equipment. Single-source vulnerability permeates the analytical chemistry talent pool concentrated in Xi'an and Hangzhou. Distribution runs through direct manufacturer-to-formulator channels displacing traditional broker mediation, particularly for California and Utah dietary supplement manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across certification tiers and application-specific standardization creates niche entry points, as South Korean K-beauty export incentives and European REACH registration requirements splinter demand into distinct supplier qualification tracks.
For Market Incumbents: Insulate market position through backward integration into Shaanxi Province farmland to secure climate-sensitive raw material supply against cultivation volatility, while investing in supercritical CO2 hybrid extraction technology to access pharmaceutical-grade monograph development contracts that synthetic antioxidant substitutes cannot penetrate. For New Entrants and Emerging Players: Vietnamese and Thai nutraceutical distributors present underpenetrated channels where Zhejiang toll manufacturers currently dominate powder format supply, offering white-space entry through liquid extract formats for clean-label beverage fortification applications. Target direct B2B relationships with Ho Chi Minh City distributors by leveraging ASEAN harmonization initiatives to bypass legacy broker layers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Zhejiang toll manufacturers facing NMPA compliance cost burdens, presenting consolidation opportunities for platforms with chromatography infrastructure. Long-term viability over a multi-year horizon hinges on dual carbon policy alignment and carbon intensity reduction credentials. The signal to watch is NMPA pharmacopeial monograph development timelines that would elevate prescription adjuvant applications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Shaanxi Jintai's provincial farmland control secures raw material supply against climate volatility. |
| Supercritical CO2 Technology Licensing | Hybrid extraction methods enable USP-grade purity thresholds for prescription adjuvant contracts. |
| REACH Registration Completion | Full substance registration opens direct B2B channels with Milan and Seoul cosmetic formulators. |
| Solvent Recovery System Investment | Ethanol waste reduction qualifies suppliers for China's MEE preferential state procurement programs. |
| Direct Manufacturer Qualification Programs | Lot-level COA transparency agreements displace broker mediation in California supplement clusters. |
Research Methodology
A spread of perspectives from extraction plant managers, cosmetic formulator procurement leads, nutraceutical brand regulatory affairs directors, and Southeast Asian distribution channel partners converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews across Shaanxi and Zhejiang processing clusters with secondary validation through NMPA GB standard documentation, MFDS cosmetic ingredient safety guidelines, FDA DSHEA New Dietary Ingredient notification records, and REACH registration databases. Bottom-up volume triangulation from toll manufacturer capacity assessments and top-down demand validation from finished-goods brand procurement forecasts were cross-referenced to establish analytical coherence.
Demand-supply-balance framing anchored the forecast framework, modeling segment trajectories across powder and liquid formats, nutraceutical and cosmetic applications, and wholesaler versus direct procurement channels throughout the projection horizon. CAGRs were derived from regression analysis of historical price-volume relationships and forward-looking capacity expansion announcements. Industry-specific inputs included winter melon cultivation yield sensitivity to Shaanxi Province precipitation patterns and supercritical CO2 equipment installation timelines among leading processors.
Practitioners should monitor NMPA pharmacopeial monograph developments, MFDS brightening serum formulation trend shifts, and REACH substance evaluation timeline accelerations for early signals of forecast revision triggers. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and cultivation climate stability. Material shifts in China's dual carbon policy stringency or South Korean K-beauty export incentive structures would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Modified Lecithin Market
Flavorings and Food Additives
Yeast Based Savory Flavors Market
Flavorings and Food Additives
Valencene Market
Flavorings and Food Additives
Oil Soluble Flavors Market
Flavorings and Food Additives
Chicory Extract Market
Flavorings and Food Additives
Natural Food Colors Market
Flavorings and Food Additives
Sour Cream Powder Market
Flavorings and Food Additives
De Oiled Lecithin Market
Flavorings and Food Additives
France Food Colorants Market
Flavorings and Food Additives
Blueberry Extract Market
Flavorings and Food Additives
Jujube Extracts Market
Flavorings and Food Additives
Lemon Essential Oil Market
Flavorings and Food Additives
Mouth Freshener Market
Flavorings and Food Additives
Chokeberry Extract Market
Flavorings and Food Additives
Rose Water Market
Flavorings and Food Additives
Flavored Butter and Oils Market