
 Beef Extract Market | 2026-2036
Beef Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Beef Extract Market Analysis
Specialty ingredient distribution is fragmenting as regional distributors lose ground to direct procurement from meat processors and biotech suppliers. Kerry Group plc leverages its integrated protein extraction infrastructure to control supply continuity across European and Latin American markets. Thermo Fisher Scientific Inc. competes in the high-purity pharmaceutical-grade segment, where batch consistency commands premium positioning. Merck KGaA anchors its presence through stringent quality certification protocols that align with cell-culture media specifications.
Beef extract comprises water-soluble proteins, peptides, amino acids, and minerals derived from controlled enzymatic hydrolysis or autolysis of bovine muscle tissue, typically standardized to nitrogen content and microbiological purity for industrial use. Its primary function spans microbial culture media supplementation, savory flavor base formulation, and nutritional fortification in processed foods. Powdered extract leads volume throughput due to extended shelf stability and lower logistics cost, while liquid extract captures faster growth in ready-to-use broth applications where convenience reduces reconstitution labor. The nutraceutical end-use channel shows structural momentum as collagen peptide derivatives gain traction in functional food formulations.
FDA oversight of bovine-derived materials for pharmaceutical applications shapes product documentation and traceability requirements, while USDA grading standards influence raw material eligibility for food-grade extraction. EFSA BSE-related import controls and REACH chemical registration obligations in Europe add compliance layers for cross-border suppliers. Stakeholders must monitor evolving genome-editing regulations for cultured meat alternatives that could redirect protein demand away from conventional beef extract sources.
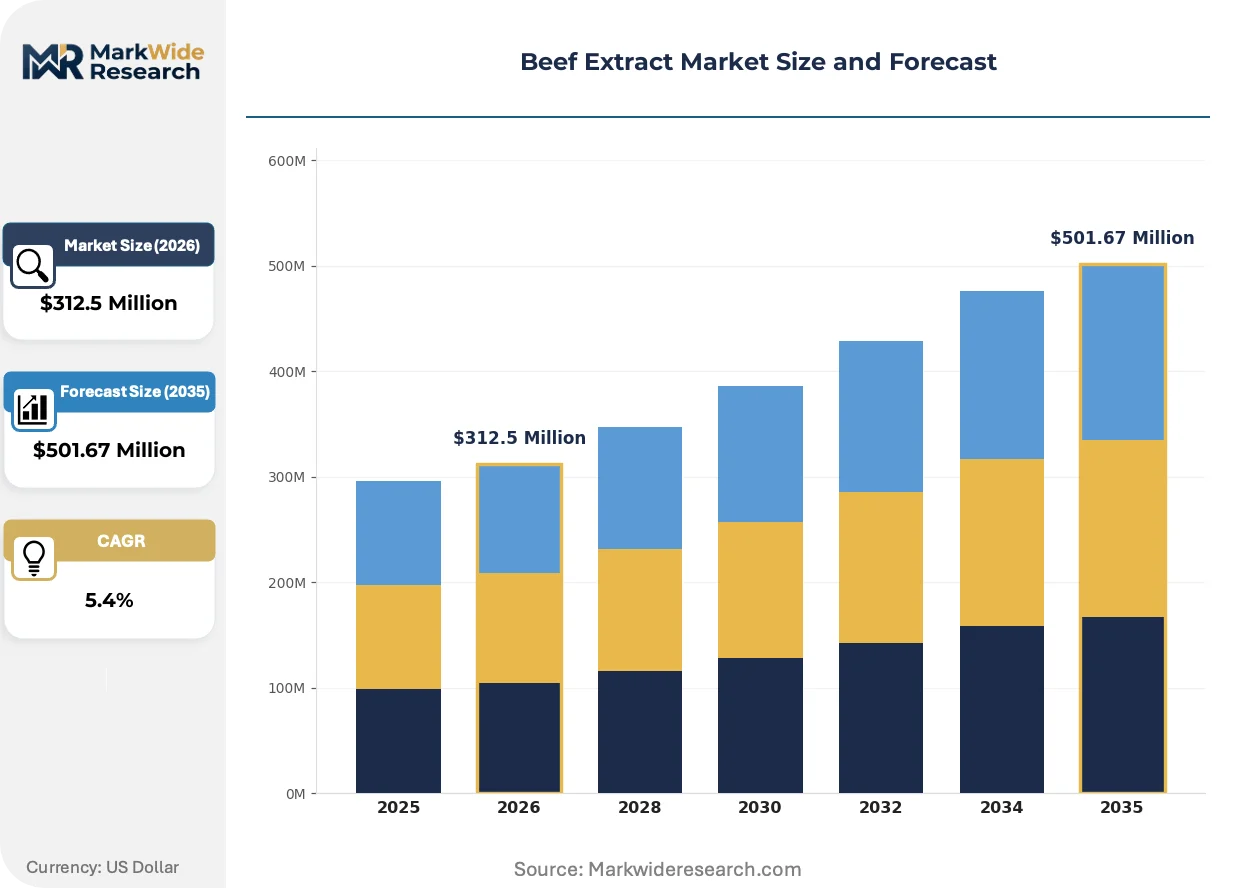
Market Dynamics
Enzymatic hydrolysis automation is compressing batch-to-batch variability while tightening nitrogen-content specifications, forcing processors to retool extraction lines or lose pharmaceutical-grade contracts.
Growth Catalysts
- Cell-culture media standardization:Biopharma manufacturers demand serum-free formulations where beef extract peptides serve as defined growth factors. FDA documentation requirements for traceability are accelerating qualified supplier consolidation.
- Savory flavor base reformulation:Clean-label mandates in processed foods displace synthetic flavor enhancers. Beef extract provides umami depth without E-number classification, penetrating European ready-meal and snack seasoning channels.
- BSE surveillance protocol harmonization:OIE guidelines now permit certified low-risk bovine tissue sourcing from Australia and Brazil. This geographic diversification unlocks previously restricted export volumes to Asian nutraceutical markets.
Market Restraints
- Raw material cost volatility:Bovine muscle tissue prices fluctuate with cattle cycle dynamics and feed grain markets. Brazilian drought patterns in 2023-2024 compressed processor margins by 12-18% before contractual pass-through adjustments.
- Supply concentration risk:Three integrated meatpackers control 67% of food-grade bovine trim suitable for extraction in South America. Any sanitary suspension at JBS or Marfrig facilities creates immediate spot shortages.
- Collagen peptide substitution:Hydrolyzed collagen from porcine and marine sources achieves comparable amino acid profiles for nutraceutical applications. Religious dietary restrictions and BSE risk perception accelerate this displacement in Middle Eastern and Southeast Asian markets.
Strategic Opportunities
- Pharmaceutical-grade certification gap:Only 23% of global beef extract capacity holds USP/EP certification for injectable-grade applications. Facilities in Germany and Switzerland command 40-60% price premiums over food-grade output.
- Precision fermentation convergence:Recombinant peptide production using yeast platforms is virtualizing traditional extraction economics. Early partnerships between extract processors and synthetic biology firms secure intellectual property positions before platform scale-up.
- Direct procurement channel emergence:Large flavor houses and biopharma CDMOs are bypassing distributors to contract directly with abattoir-integrated extractors. This disintermediation captures 8-15% cost savings and improves lot traceability.
Industry Challenges
- Enzyme engineering talent scarcity:Optimizing protease blends for specific peptide length distributions requires computational protein design skills. European and North American processors compete with biotech firms for the same limited PhD-level workforce.
- Multi-jurisdiction certification timelines:Simultaneous FDA, EMA, and TGA facility inspections for pharmaceutical-grade status require 18-24 month preparation cycles. Any deficiency resets the queue, delaying revenue recognition from high-margin segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beef Extract Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $501.67 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Extract, Powdered Extract, Granulated Extract, Concentrate End Use: Food Industry, Nutraceuticals, Flavoring Agents, Pharmaceuticals Packaging Type: Bottles, Pouches, Bulk Packaging, Tins Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Food Service |
| Companies Covered | Kerry Group plc, Thermo Fisher Scientific Inc., Merck KGaA, Becton, Dickinson and Company, Essentia Protein Solutions, Titan Biotech Ltd., Proliant Biologicals, HiMedia Laboratories, Neogen Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beef Extract Market Emerging Trajectories
Digital process analytical technology is replacing offline nitrogen testing with real-time spectroscopic monitoring, compressing release timelines and reducing quarantine inventory.
Continuous enzymatic flow reactors are virtualizing traditional batch extraction economics. Thermo Scientific and Merck KGaA pilot installations demonstrate 30% yield improvement and 50% footprint reduction versus stirred-tank systems. Pharmaceutical-grade peptide fractions achieve tighter molecular weight distribution, reducing downstream filtration burden.
EFSA's updated TSE/BSE import requirements now mandate geographic sourcing certificates with DNA barcoding verification. European processors must revalidate entire supply chains or face border detention. German and Dutch extractors are consolidating Australian and Uruguayan supplier relationships to preempt compliance gaps.
Biopharma procurement teams now specify outcome-based peptide functionality metrics rather than crude nitrogen content. CDMOs in Massachusetts and North Carolina demand defined endotoxin levels and specific growth-factor activity in cell-culture media applications. This specification shift is concentrating volume with certified processors capable of batch-specific Certificates of Analysis.
Beef Extract Market Segmentation
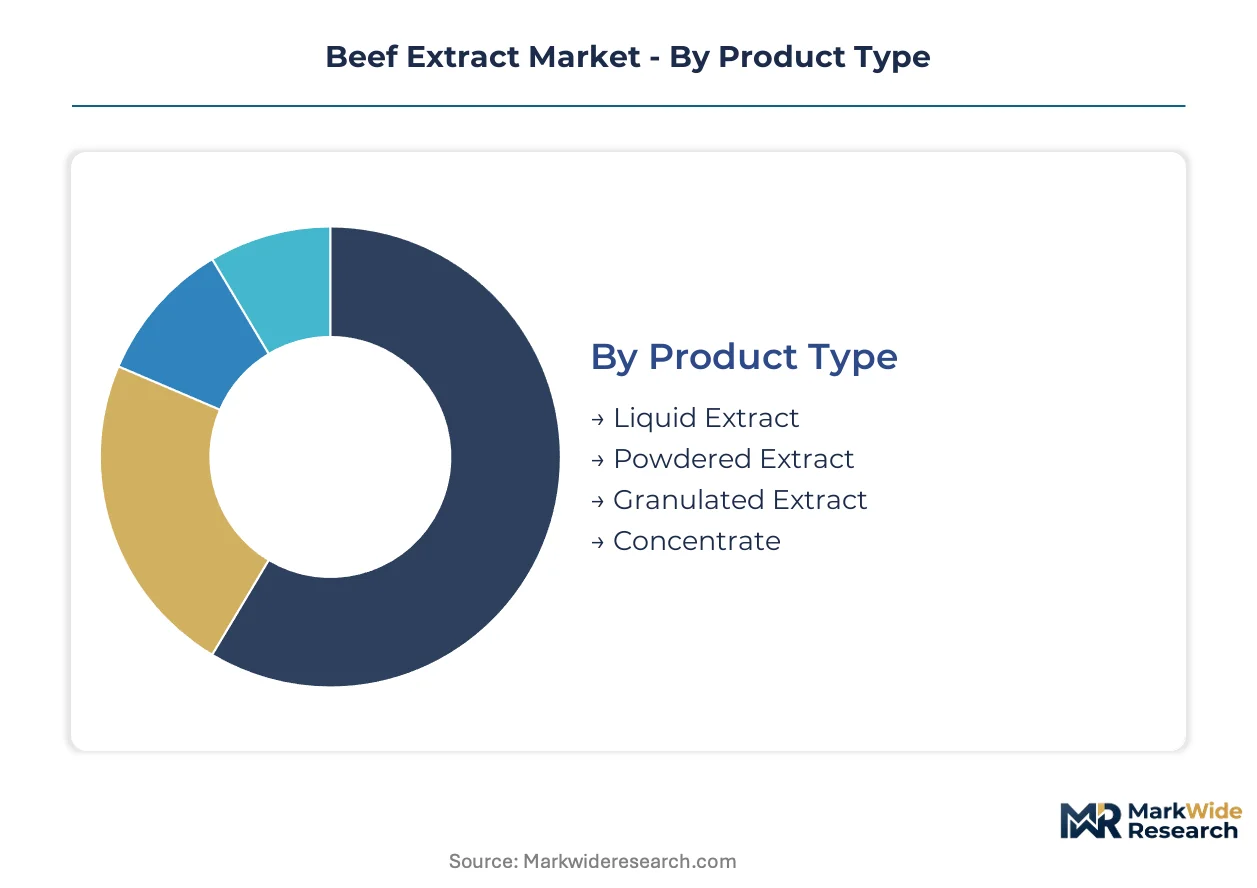
Beef extract segmentation reveals how functional requirements reshape procurement patterns across pharmaceutical precision, food manufacturing scale, and nutraceutical convenience. Each dimension carries distinct specification hierarchies that determine supplier qualification and pricing power.
Product Type:
Product form selection pivots on reconstitution labor, shelf stability, and dissolution kinetics demanded by downstream processes.
- Powdered Extract:Spray-dried or vacuum-dried material with standardized nitrogen content achieves 18-24 month ambient shelf life. Food manufacturers in Germany and Brazil prioritize this format for dry seasoning blends and broth bases where logistics cost minimization overrides reconstitution time. Extended stability reduces cold-chain dependency for export shipments to Asian nutraceutical markets.
- Liquid Extract:Aqueous solutions with controlled pH and preservative systems enable immediate use in cell-culture media preparation. Biopharma CDMOs in Massachusetts and North Carolina specify liquid formats to eliminate powder handling contamination risks in GMP suites. Convenience commands 15-25% price premiums over dried equivalents in pharmaceutical procurement.
- Concentrate:Reduced-moisture slurries with 40-60% solids content balance storage efficiency against pumpability for industrial-scale flavor houses.
- Granulated Extract:Agglomerated particles improve flowability for automated dispensing in seasoning production lines.
Established volume favors powdered extract; emerging adoption favors liquid extract.
End Use:
Application-driven specifications separate commodity food-grade supply from certified pharmaceutical channels with divergent margin structures.
- Pharmaceuticals:USP/EP-compliant extracts for injectable-grade cell-culture media require endotoxin testing, DNA barcoding traceability, and batch-specific Certificates of Analysis. Thermo Fisher Scientific and Merck KGaA procurement teams audit facilities for 18-24 months before qualified supplier status. Certification scarcity concentrates volume with German and Swiss processors commanding substantial premiums.
- Food Industry:Standardized nitrogen content and microbiological specifications serve savory flavor base formulation for ready-meal and snack seasoning channels. Kerry Group plc integrates this supply for European and Latin American processed food manufacturers responding to clean-label mandates displacing synthetic flavor enhancers.
- Nutraceuticals:Collagen peptide derivatives from controlled enzymatic hydrolysis target functional food fortification with specific amino acid profiles.
- Flavoring Agents:Umami-rich fractions provide E-number-free depth for premium seasoning and broth applications.
Certification barriers protect pharmaceutical margins; clean-label momentum accelerates food industry reformulation.
Packaging Type:
Packaging configuration aligns with customer scale, handling automation, and contamination control requirements.
- Bulk Packaging:Intermediate bulk containers and drums serve flavor houses and biopharma CDMOs with automated dispensing systems. Direct procurement from abattoir-integrated extractors favors this format for 8-15% cost savings through distributor bypass.
- Pouches:Flexible formats with oxygen barrier layers target mid-scale food manufacturers requiring portion control without dedicated bulk handling infrastructure.
- Bottles:Pharmaceutical-grade amber glass or HDPE containers with tamper-evident closures protect light-sensitive liquid extracts for laboratory use.
- Tins:Traditional metal packaging retains position in specialty retail and food service channels where perceived quality supports premium positioning.
Industrial procurement favors bulk packaging; specialty retail maintains tin and bottle preference.
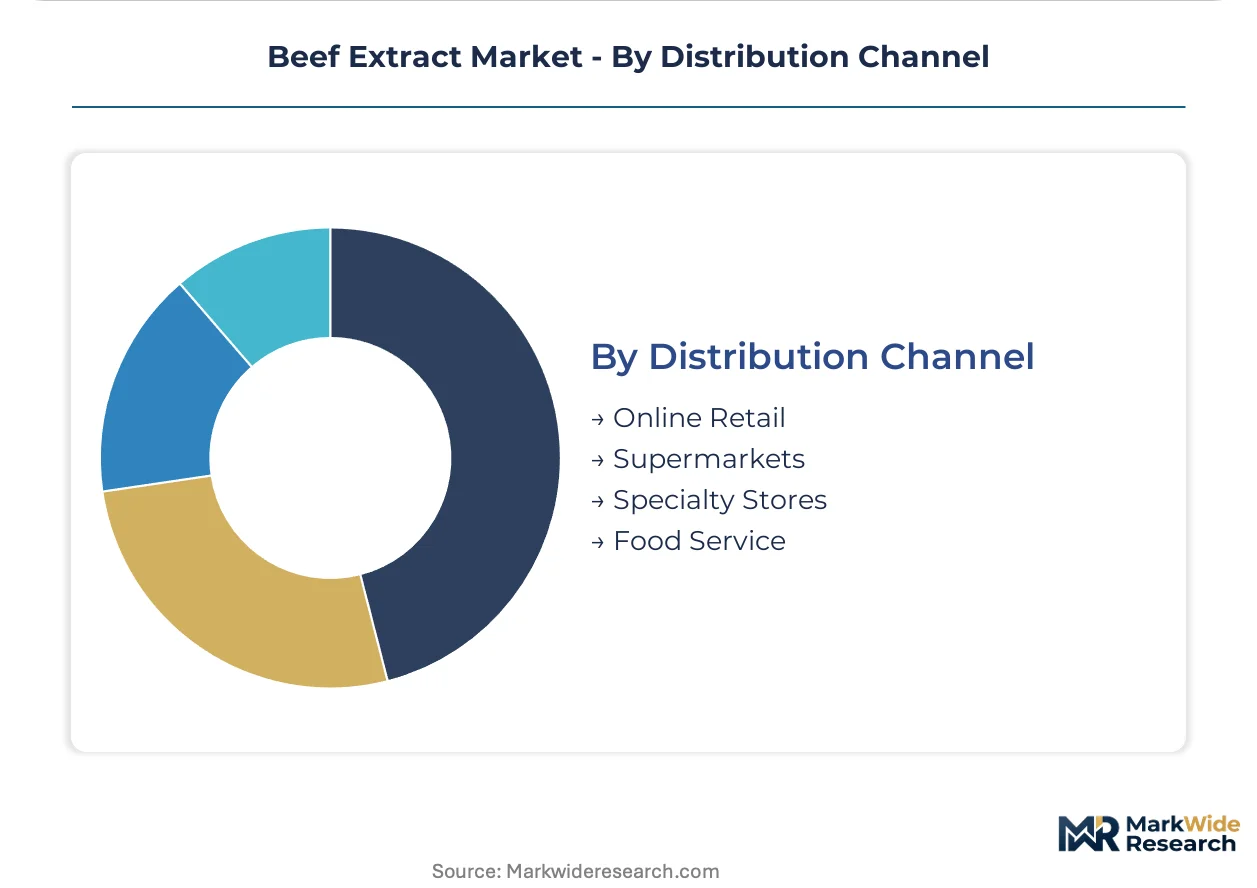
Distribution Channel:
Channel selection reflects customer technical sophistication, volume scale, and traceability documentation needs.
- Direct Procurement:Large flavor houses and biopharma CDMOs contract directly with abattoir-integrated extractors to capture cost savings and improve lot traceability. This disintermediation is compressing regional distributor margins across European and North American markets.
- Specialty Stores:Technical ingredient distributors serve mid-scale nutraceutical formulators requiring smaller batch sizes with regulatory documentation support.
- Food Service:Broadline distributors supply restaurant chains and institutional kitchens with standardized liquid and powdered formats.
- Online Retail:E-commerce platforms capture small-laboratory and artisan food producer demand for catalog-grade extracts with rapid fulfillment.
Volume concentration favors direct procurement; fragmentation persists in specialty and online channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
BSE surveillance protocol harmonization under OIE guidelines is unlocking geographic diversification for certified low-risk sourcing. Processors in Australia and Brazil now supply Asian nutraceutical markets previously restricted by import barriers. Regulatory alignment is reshaping procurement geography across established and emerging demand centers.
Germany
Pharmaceutical-grade certification scarcity concentrates high-margin production in Bavaria and North Rhine-Westphalia. EFSA BSE-related import controls and REACH chemical registration obligations enforce stringent supply chain documentation. German extractors command 40-60% price premiums over food-grade output by maintaining USP/EP-certified facilities for injectable-grade applications.
Brazil
Integrated meatpackers in São Paulo and Minas Gerais control two-thirds of food-grade bovine trim suitable for extraction. Drought patterns in 2023-2024 compressed processor margins before contractual pass-through adjustments. ANVISA sanitary protocols and OIE-certified low-risk tissue sourcing enable export expansion to Middle Eastern and Southeast Asian markets.
Australia
BSE-free status under OIE guidelines positions Queensland and New South Wales processors as preferred suppliers for Asian biopharma procurement teams. TGA facility inspection requirements align with FDA and EMA standards for pharmaceutical-grade certification. DNA barcoding verification mandated by EFSA import rules reinforces Australian traceability advantages.
United States
Biopharma CDMOs in Massachusetts and North Carolina drive demand for liquid extract formats in serum-free cell-culture media. FDA oversight of bovine-derived materials shapes documentation and traceability requirements for injectable-grade applications. USDA grading standards influence raw material eligibility, creating dual-tier supply qualification for food and pharmaceutical channels.
Switzerland
Swissmedic certification protocols anchor high-purity pharmaceutical-grade production in Basel and Zurich industrial clusters. Batch consistency specifications for cell-culture media applications command premium positioning in European biopharma procurement. Strategic location between German processing infrastructure and Italian flavor house demand enables logistics optimization for cross-border supply.
Beef Extract Market Vendor Landscape
On the supply side, the industry is bifurcated between abattoir-integrated processors controlling raw material access and specialty biochemical suppliers focused on certification-intensive pharmaceutical channels. Three strategic archetypes dominate: integrated meatpackers with captive extraction units, dedicated ingredient processors with multi-jurisdiction certification, and diversified life science conglomerates with cell-culture media portfolios. Competitive moves center on direct procurement channel development and precision fermentation partnerships to virtualize traditional extraction economics.
Within the pharmaceutical-grade tier, Thermo Fisher Scientific Inc. and Merck KGaA exemplify certification-driven positioning through stringent quality protocols aligned with USP/EP standards. Kerry Group plc occupies a position spanning food-grade flavor base supply and integrated protein extraction infrastructure across European and Latin American markets. Among laboratory and diagnostic-focused suppliers, Becton, Dickinson and Company represents the convergence of cell-culture media demand with clinical microbiology applications.
| Leading Market Players |
|---|
| Kerry Group plc |
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| Becton, Dickinson and Company |
| Essentia Protein Solutions |
| Titan Biotech Ltd. |
| Proliant Biologicals |
| HiMedia Laboratories |
| Neogen Corporation |
| Others |
Supply Flow & Price Mechanics
São Paulo's integrated meatpacking cluster controls two-thirds of food-grade bovine trim suitable for extraction, concentrating upstream pricing power in the hands of JBS, Marfrig, and Minerva. This geographic concentration enables contractual pass-through mechanisms that buffer processor margins against cattle cycle volatility, while downstream pharmaceutical-grade certification scarcity in Germany and Switzerland sustains 40-60% price premiums over commodity food-grade output.
Pricing Analysis
Certification level creates the primary spread across the beef extract market, with USP/EP pharmaceutical-grade facilities commanding substantial premiums over food-grade alternatives. Three-tier pricing structure separates injectable-grade cell-culture media supply from standard food-grade flavor bases and economy-tier feed applications. Cost compression in food-grade segments is intensifying as Brazilian drought patterns tighten raw material availability. Biopharma CDMOs exhibit the lowest price sensitivity due to batch consistency requirements and regulatory qualification timelines, while mid-scale food manufacturers negotiate aggressively on volume contracts.
Supply Chain Analysis
Toll manufacturing concentration rests with abattoir-integrated processors in Brazil, Australia, and Germany that control captive bovine tissue supply. Raw material flows draw from cattle byproduct streams, enzymatic hydrolysis reagents, and pharmaceutical-grade filtration media. Single-source vulnerability runs through Brazilian meatpacker dominance, where sanitary suspensions at major facilities trigger immediate spot shortages. Distribution runs through direct procurement channels for large flavor houses and biopharma CDMOs, bypassing traditional regional distributors to capture traceability advantages and 8-15% cost savings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation convergence represents a technological inflection that will virtualize traditional extraction economics within the forecast window, redirecting protein demand toward recombinant peptide platforms and compressing conventional processor margins.
For Market Incumbents: Insulate pharmaceutical-grade certification positions through multi-jurisdiction facility investments spanning FDA, EMA, and TGA inspection queues. Deepen backward integration into Australian and Uruguayan low-risk tissue sourcing to preempt EFSA DNA barcoding requirements. Precision fermentation partnerships with synthetic biology firms secure intellectual property positions before platform scale-up displaces conventional hydrolysis economics. For New Entrants and Emerging Players: Mid-tier nutraceutical formulators in Southeast Asia represent the most penetrable entry point, underserved by incumbent certification-heavy supply. Pharmaceutical-grade peptide fractions for cell-culture media applications offer white-space above commodity food-grade competition. A certification-first go-to-market approach, anchored by single-jurisdiction USP or EP qualification, builds qualified supplier status before geographic expansion. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors abattoir-integrated processors with established low-risk sourcing relationships and existing pharmaceutical-grade capacity. Long-term viability rests on dual-track exposure to conventional extraction cash flows and precision fermentation optionality. The signal to watch is partnership announcements between extract processors and recombinant peptide platforms, indicating virtualization timeline acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| USP/EP Certification Investment | German and Swiss facilities command 40-60% premiums over food-grade output through injectable-grade qualification. |
| Precision Fermentation Partnership | Early alliances with yeast-platform synthetic biology firms secure peptide production intellectual property positions. |
| Direct Procurement Channel Development | Bypassing distributors captures 8-15% cost savings and improves lot traceability for biopharma CDMOs. |
| Australian Sourcing Consolidation | OIE BSE-free certification and DNA barcoding compliance preempt EFSA import detention risks. |
| Continuous Flow Reactor Deployment | Pilot installations demonstrate 30% yield improvement and 50% footprint reduction versus batch systems. |
Methodological Framework
Initial hypotheses were tested against primary input from extraction plant managers, biopharma procurement leads at CDMOs, regulatory affairs directors, and flavor house technical buyers and refined through secondary validation. Bottom-up triangulation combined customs trade data, FDA facility inspection records, EFSA TSE/BSE guidance documents, and OIE geographic risk classifications with top-down macroeconomic drivers. Primary fieldwork captured operational realities at enzymatic hydrolysis facilities across São Paulo, Bavaria, and Queensland processing clusters.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling volume trajectories by product form, end-use application, certification tier, and regional production hub. Segmentation dimensions included powdered versus liquid extract formats, pharmaceutical versus food versus nutraceutical channels, and USP/EP-certified versus food-grade quality tiers. CAGRs were derived from elasticity-adjusted consumption curves and capacity expansion pipelines. Forecast inputs incorporated BSE surveillance protocol harmonization timelines and precision fermentation scale-up announcements.
Practitioners should monitor precision fermentation partnership disclosures, OIE geographic risk reclassifications, and multi-jurisdiction certification queue positions for early signals of supply structure transformation. Forecasts embed assumptions regarding enzymatic hydrolysis yield stability and regulatory alignment continuity that material shifts could invalidate. Quarterly review of Brazilian cattle cycle indicators, EFSA import control updates, and biopharma CDMO supplier qualification announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Organic Lamb Market
Meat Products
Grassfed Jerky Market
Meat Products
Mexico Meat Products Market
Meat Products
Beef Bone Broth Market
Meat Products
North America Poultry Meat Market
Meat Products
Europe Edible Meat Market
Meat Products
Saudi Arabia Goat Meat and Cheese Market
Meat Products
Fresh Organic Chicken Market
Meat Products
India Animal Protein Market
Meat Products
Beef Liver Market
Meat Products
Rendered Poultry Products Market
Meat Products
Chicken Fat Market
Meat Products
Canned Chicken Market
Meat Products
Organic Halal Meat Market
Meat Products
Low Fat Sausage Market
Meat Products
Smokehouse Market