
 Horehound Extract Market | 2026-2036
Horehound Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Horehound Extract Market Analytics
Pharmaceutical-grade extract specifications are redrawing competitive boundaries in horehound processing. Monterey Bay Spice Company leverages direct relationships with Mediterranean growers to sustain consistent marrubiin content in its raw material pipeline. Mountain Rose Herbs anchors its position through certified organic extraction protocols that differentiate supply to dietary supplement bottlers. Herb Pharm competes on alcohol-free glycerite formats that occupy shelf space in natural product retail channels.
Horehound extract is a concentrated preparation derived from Marrubium vulgare aerial parts, typically standardized to marrubiin content between 0.5% and 2.0% through ethanol or glycerin maceration processes, and functions primarily as an expectorant and bitter digestive stimulant in commercial formulations. Liquid extract formats dominate pharmaceutical compounding due to dosage precision and faster bioavailability, while dried leaf and powder segments serve tea manufacturers and encapsulation houses with lower processing overhead. Respiratory health applications lead volume demand, though cough suppressant formulations in over-the-counter herbal syrups are registering the fastest trajectory as consumers shift from synthetic dextromethorphan alternatives.
The European Medicines Agency's Committee on Herbal Medicinal Products governs monograph compliance for horehound therapeutics, while the U.S. Food and Drug Administration exercises oversight through dietary supplement Current Good Manufacturing Practice regulations that mandate identity testing and contamination screening for botanical imports. Compliance with these frameworks shapes batch release protocols, certificate-of-analysis requirements, and supplier qualification burdens that determine which extract houses can service regulated channels versus commodity botanical traders. Stakeholders must monitor evolving pharmacovigilance reporting obligations and monograph updates that could restrict or expand permitted health claims across key jurisdictions.
Market Dynamics
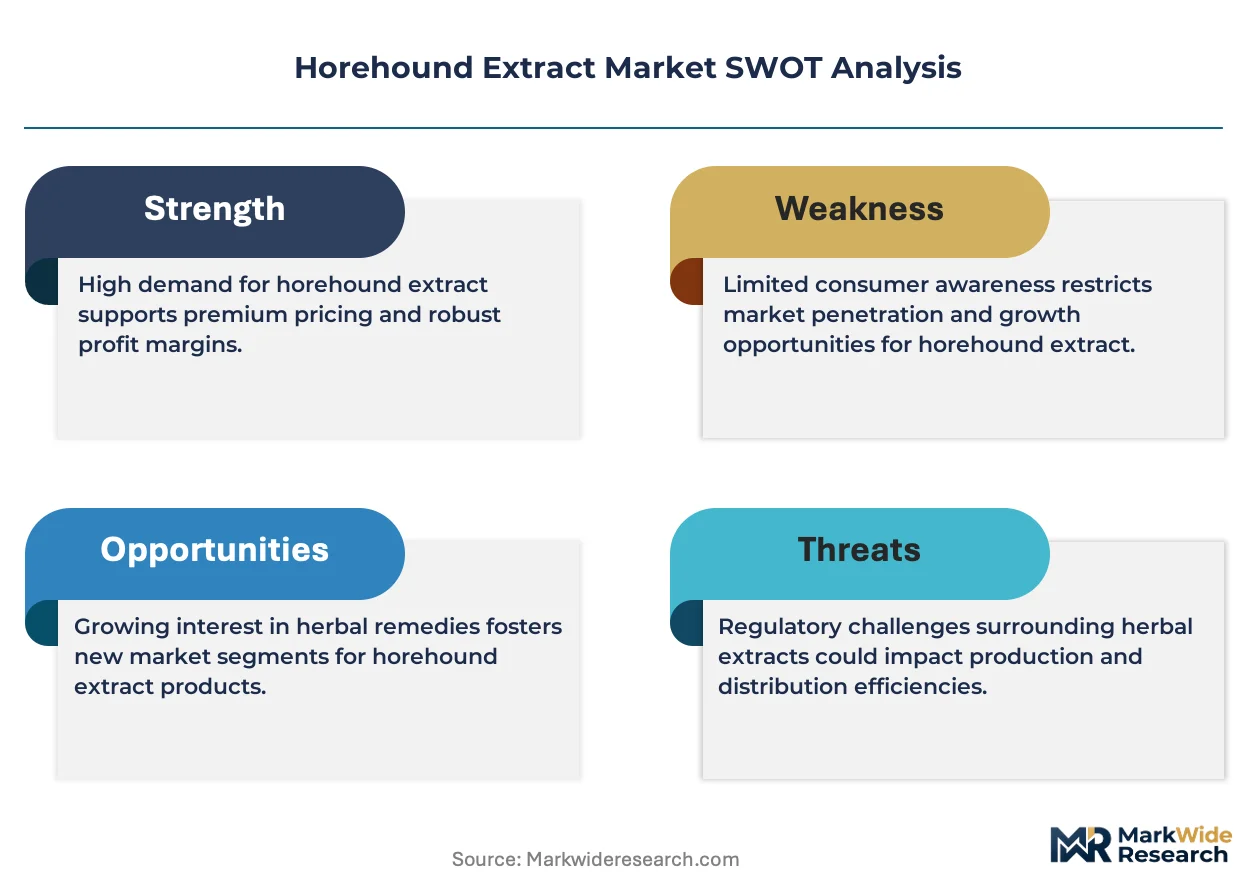
The EU Herbal Medicines Directive is consolidating extract supply chains by mandating Traditional Herbal Registration for all horehound therapeutics sold through pharmacy channels, forcing smaller processors to either upgrade analytical capabilities or exit regulated markets entirely.
Growth Catalysts
- Traditional Herbal Registration pathway:Germany's BfArM and Austria's BASG are fast-tracking approvals for standardized marrubiin extracts, reducing time-to-market for compliant suppliers by streamlining pharmacovigilance documentation requirements.
- Respiratory formulation demand:Cough suppressant manufacturers are substituting synthetic dextromethorphan with horehound glycerites, creating pull-through for alcohol-free extract formats in pediatric and dry-syrup applications.
- Central European phytotherapy loyalty:Pharmacist-recommended herbal preparations in Bavaria, Baden-Württemberg, and Vienna sustain premium pricing for certified organic extracts versus commodity botanical grades.
Market Restraints
- Wild-harvested raw material volatility:Marrubiin content fluctuates 0.3% to 2.5% across Mediterranean wild collections, forcing processors to maintain expensive buffer inventories or absorb batch rejection costs.
- EMA monograph compliance burden:Certificate-of-analysis requirements for heavy metals, aflatoxins, and pesticide residues add 12-18% to quality control overhead for extract houses serving pharmaceutical channels.
- Synthetic expectorant substitution:Guai-fenesin and acetylcysteine formulations retain formulary preference in acute care settings, limiting horehound penetration in hospital discharge prescriptions.
Strategic Opportunities
- Digestive bitters positioning:Functional beverage formulators in Austria and Switzerland are incorporating horehound tinctures into aperitif-style non-alcoholic spirits, opening shelf-space outside traditional pharmacy channels.
- EU Green Deal botanical incentives:CAP subsidies for medicinal herb cultivation in Romania and Bulgaria are expanding contract farming acreage, reducing dependency on unpredictable wild harvests.
- Direct-to-practitioner distribution:Herbalist and naturopath networks in Germany are bypassing wholesale distributors through cooperative buying platforms, compressing margin extraction by intermediaries.
Industry Challenges
- Analytical chemist scarcity:HPLC quantification of marrubiin and related diterpenes requires specialized phytochemical expertise that extract houses in Central Europe struggle to recruit at competitive salaries.
- Legacy equipment retrofit costs:Transitioning from conventional maceration to ultrasonic-assisted extraction demands capital outlays of €400,000-€800,000 per production line, straining mid-tier processors.
- Cross-border batch release friction:Mutual recognition agreements between Germany's BfArM and Switzerland's Swissmedic remain incomplete, forcing duplicate stability testing for extracts sold in both markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Horehound Extract Market |
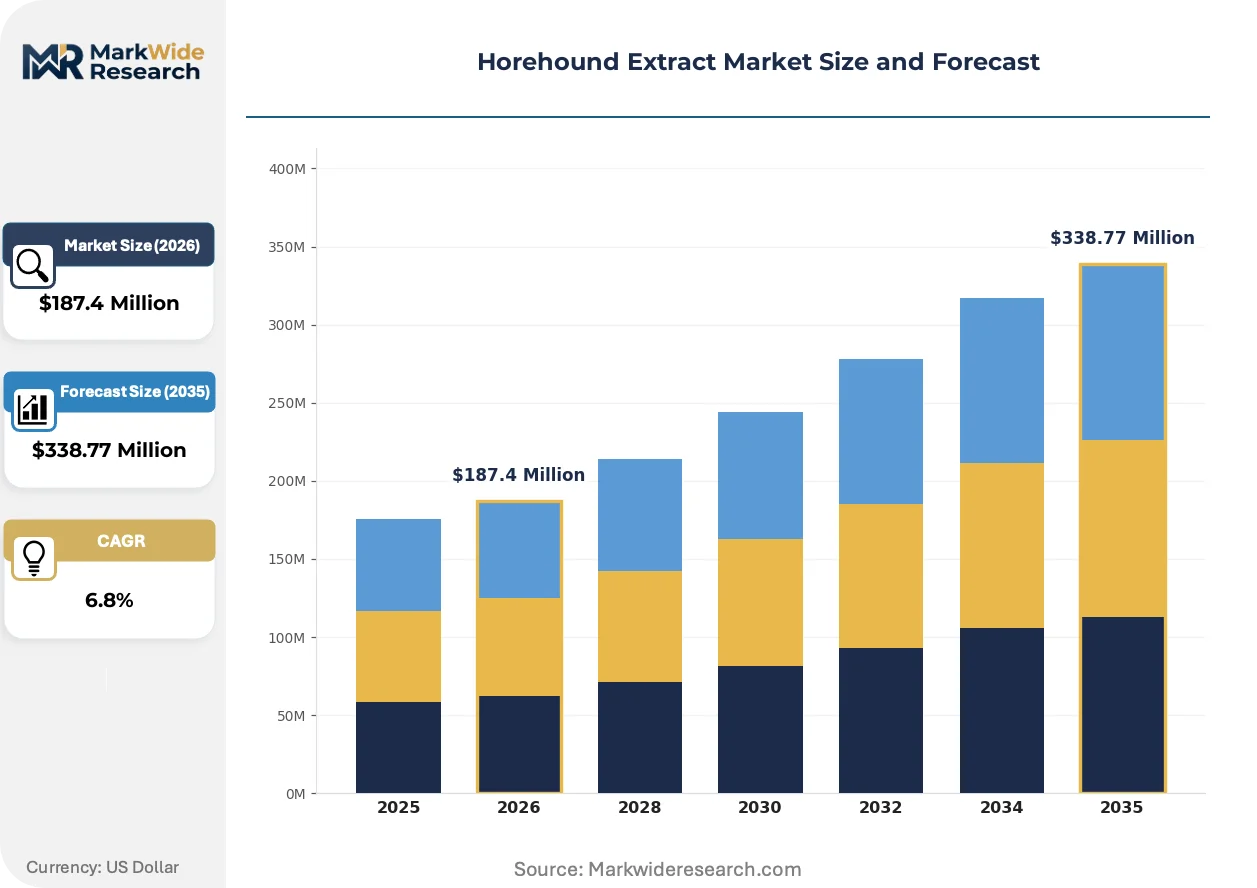
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Extract, Dried Leaf, Powder, Tincture End User: Pharmaceuticals, Dietary Supplements, Cosmetics, Food & Beverage Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Health Food Stores Application: Respiratory Health, Digestive Aid, Cough Suppressant, Flavoring Agent |
| Companies Covered | Monterey Bay Spice Company, Mountain Rose Herbs, Red Moon Herbs, Herb Pharm, The Great American Spice Co., Bickford Flavors, Ricola AG, Nutraceutical International Corporation, Swanson Health Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Horehound Extract Market Evolving Landscape
Extraction technology and regulatory data integrity requirements are compressing the competitive set, favoring processors with capital reserves to deploy advanced analytics and automated batch documentation systems.
Ultrasonic-assisted extraction is decomposing the traditional six-week ethanol maceration cycle into 48-hour processing windows while preserving heat-sensitive marrubiin isomers. German dietary supplement contract manufacturers are adopting these systems to meet just-in-time replenishment demands from pharmacy chains. The technology is decomposing the historical advantage of large inventory-holding traders by enabling small-batch freshness claims.
EMA's revised pharmacovigilance guidelines for herbal medicinal products are mandating real-time adverse event reporting through the EudraVigilance portal. Extract houses must now maintain dedicated regulatory affairs staff capable of MedDRA coding and periodic safety update report preparation. German and Austrian suppliers serving prescription channels are absorbing these compliance costs while commodity traders retreat to food-grade applications with lighter oversight.
Pharmacist counseling is displacing self-selection in respiratory remedy purchases across Bavarian and Viennese pharmacy networks. Consumers now request specific marrubiin-standardized products by name rather than browsing generic cough syrup shelves. This behavioral shift concentrates volume with registered traditional herbal medicinal products, squeezing unregistered food-supplement formats from professional recommendation workflows.
Horehound Extract Market Segmentation
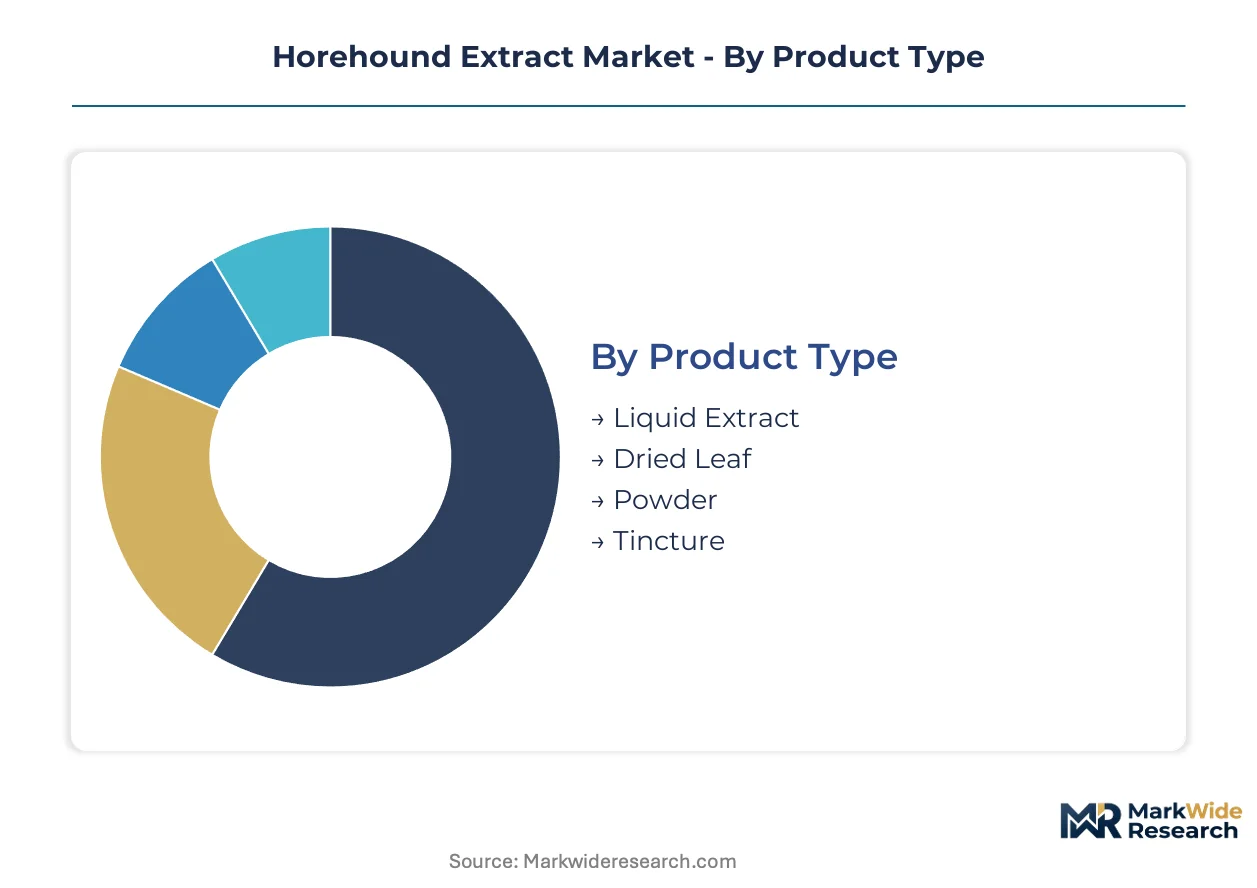
Segmentation in horehound extract markets reveals how marrubiin standardization requirements and regulatory pathways fragment commercial opportunity across product formats and distribution channels. Manufacturers configure extraction protocols and certification levels differently depending on whether supply targets pharmacy compounding, dietary supplement bottling, or functional beverage formulation.
Product Type:
Liquid extract formats command premium margin pools due to pharmaceutical compounding demand for precise marrubiin dosing and faster bioavailability profiles in respiratory therapeutics.
- Liquid Extract:Standardized ethanol or glycerin macerates containing 0.5% to 2.0% marrubiin serve prescription cough syrups and pediatric formulations. Demand concentrates in German and Austrian pharmacy channels where Traditional Herbal Registration compliance enables pharmacist recommendation.
- Dried Leaf:Unprocessed aerial parts retain volatile oils and bitter principles for tea manufacturers seeking lower processing overhead. Volume demand clusters in Central European direct-to-consumer herbal retail where consumers self-select for digestive applications.
- Powder:Spray-dried or milled preparations facilitate encapsulation by dietary supplement houses requiring flowable, uniform particle size for high-speed tableting operations.
- Tincture:Alcohol-based preparations with extended shelf stability occupy natural product retail positioning between pharmaceutical extracts and food-grade botanicals.
Liquid extract holds installed capacity. Tincture is rotating up the share rankings.
End User:
Pharmaceutical buyers absorb the steepest compliance costs but lock in multi-year contracts, while dietary supplement formulators trade specification flexibility for faster inventory turns.
- Pharmaceuticals:EMA monograph compliance and batch release documentation for respiratory therapeutics require dedicated regulatory affairs staff and HPLC verification of marrubiin content. German BfArM oversight shapes supplier qualification protocols.
- Dietary Supplements:FDA Current Good Manufacturing Practice regulations govern identity testing and contamination screening for botanical imports serving US encapsulation houses and tincture bottlers.
- Cosmetics:Bitter principle extracts for dermocosmetic bitter tonics occupy niche positioning in French and Swiss premium skincare channels.
- Food & Beverage:Flavoring applications in non-alcoholic aperitif-style spirits bypass pharmaceutical registration requirements but face food-grade additive scrutiny.
Pharmaceuticals dominate contract value. Dietary supplements are expanding most quickly.
Distribution Channel:
Channel selection determines margin capture versus volume scale, with pharmacy-direct distribution preserving premium pricing and online retail compressing intermediation layers.
- Online Retail:Direct-to-practitioner platforms and cooperative buying networks enable German herbalists and naturopaths to bypass wholesale distributors. Austrian practitioners increasingly source through specialized botanical e-procurement portals.
- Specialty Stores:Independent herbal apothecaries in Bavaria and Vienna sustain face-to-face consultation models that drive premium extract selection over commodity grades.
- Supermarkets:Mass-market tea and supplement placement requires food-grade certification and simplified labeling that excludes marrubiin content claims.
- Health Food Stores:Natural product retail chains in German-speaking markets allocate shelf space to alcohol-free glycerite formats targeting pediatric and dry-syrup applications.
Specialty stores maintain pricing power. Online retail is climbing the fastest.
Application:
Respiratory positioning commands formulation investment due to pharmacist recommendation workflows, while digestive applications access alternative channel structures with lighter regulatory burden.
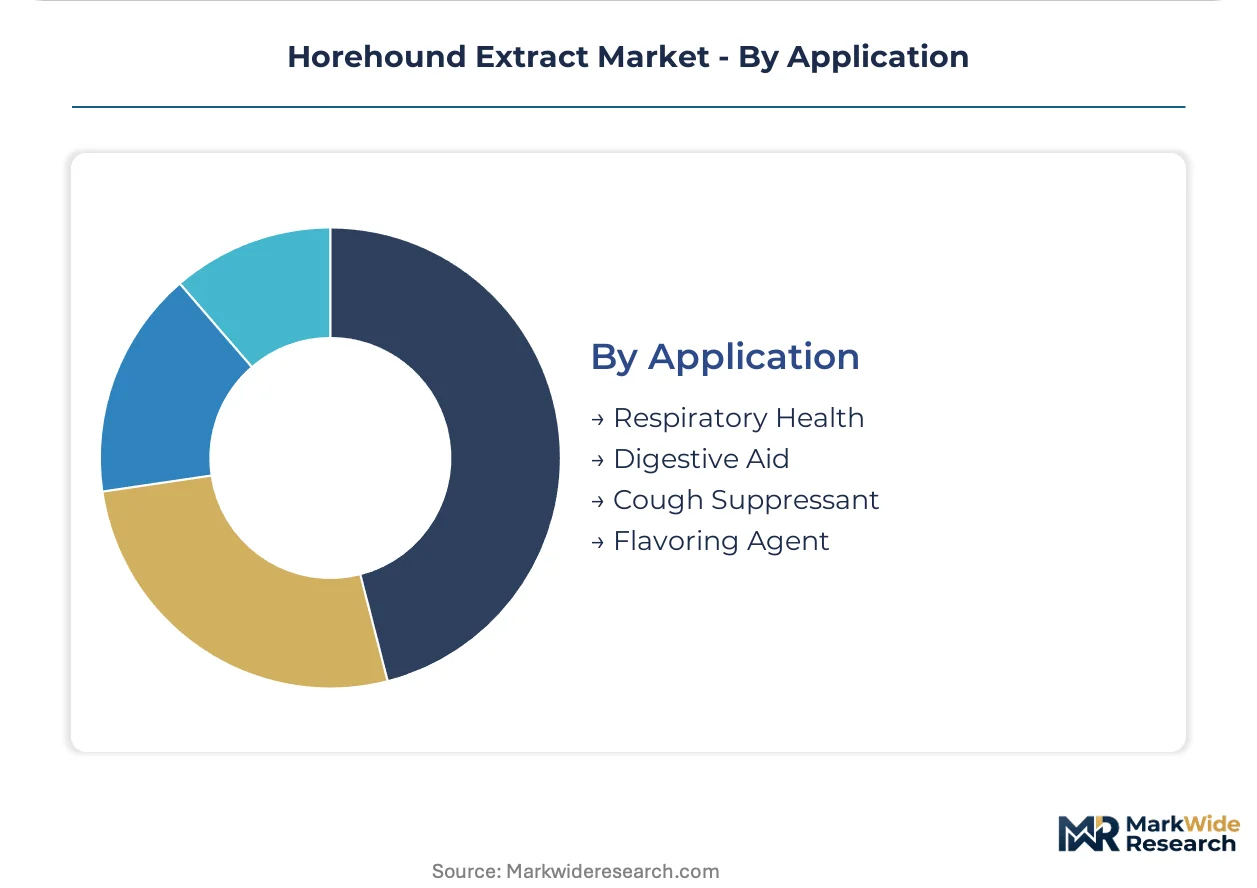
- Respiratory Health:Expectorant formulations in over-the-counter herbal syrups register steep expansion as consumers substitute synthetic dextromethorphan alternatives. German pharmacy networks drive volume through counseling-based selection.
- Digestive Aid:Bitter stimulant applications in functional beverages and aperitif-style non-alcoholic spirits open Austrian and Swiss shelf-space outside traditional pharmacy channels. Formulators leverage lighter food-grade oversight.
- Cough Suppressant:Pediatric glycerite formats specifically target alcohol-free positioning for dry-syrup applications in Central European markets.
- Flavoring Agent:Bitter principle incorporation into craft beverage and confectionery applications serves niche demand with minimal therapeutic claim exposure.
Respiratory health anchors installed demand. Digestive aid is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Austria currently dominate horehound extract trade flows, with import dependency on Mediterranean wild harvests creating supply vulnerability during adverse growing seasons. Export-oriented processors in these markets capture value through Traditional Herbal Registration compliance, while downstream formulation houses in Switzerland and France absorb premium extracts for pharmacy distribution.
Germany
Pharmacy chains in Bavaria and Baden-Württemberg drive pharmacist-recommended horehound syrup volumes through counseling-based selection workflows. The Federal Institute for Drugs and Medical Devices enforces Traditional Herbal Registration requirements that filter out non-compliant suppliers from pharmacy channels. Contract extract processors in the Black Forest region upgrade analytical capabilities to meet EMA monograph compliance for respiratory therapeutics.
Austria
Functional beverage formulators in Vienna incorporate horehound tinctures into aperitif-style non-alcoholic spirits, accessing shelf-space outside traditional pharmacy structures. The Austrian Medicines and Medical Devices Agency coordinates with Germany's BfArM on mutual recognition for batch release documentation. Herbalist cooperatives in Lower Austria operate direct-to-practitioner procurement platforms that bypass wholesale distribution layers.
Switzerland
Swissmedic oversight creates parallel stability testing requirements for extracts crossing the German-Swiss border, adding regulatory friction for multi-market suppliers. Premium dermocosmetic bitter tonics in Geneva and Zurich skincare channels absorb small-batch certified organic extracts. Cross-border pharmacy networks in Basel and Schaffhausen concentrate volume for pediatric glycerite formulations.
France
ANSM pharmacovigilance reporting obligations shape adverse event documentation standards for horehound therapeutics sold through French pharmacy networks. Tea manufacturers in Provence source dried leaf grades for direct-to-consumer herbal retail with lower processing overhead. The country's national pharmaceutical regulator maintains strict aflatoxin and heavy metal thresholds that exceed baseline EU requirements.
United States
FDA Current Good Manufacturing Practice regulations govern identity testing and contamination screening for botanical imports serving dietary supplement encapsulation houses. Natural product retail chains in the Pacific Northwest allocate shelf space to alcohol-free glycerite formats targeting pediatric applications. Domestic contract manufacturers face supplier qualification burdens that determine access to regulated channels versus commodity botanical trading.
Horehound Extract Market Competitive Landscape
Concentration sits with specialized botanical extract houses and vertically integrated herb suppliers that control raw material provenance through direct grower relationships. The competitive set fragments across three tiers: registered traditional herbal medicinal product suppliers serving European pharmacy channels, certified organic processors capturing premium dietary supplement contracts, and commodity traders supplying food-grade applications with lighter oversight. Strategic moves center on ultrasonic-assisted extraction technology licensing and backward integration into contract farming arrangements that reduce wild-harvest dependency.
Within the premium organic tier, Mountain Rose Herbs exemplifies certified organic extraction protocol differentiation, while Herb Pharm occupies a position anchored in alcohol-free glycerite formats for natural product retail. Monterey Bay Spice Company represents Mediterranean sourcing archetypes through direct grower relationships that sustain consistent marrubiin content. These three anchors illustrate how supply chain configuration and format specialization stratify competitive positioning across pharmacy, supplement, and food-grade market layers.
| Leading Market Players |
|---|
| Monterey Bay Spice Company |
| Mountain Rose Herbs |
| Red Moon Herbs |
| Herb Pharm |
| The Great American Spice Co. |
| Bickford Flavors |
| Ricola AG |
| Nutraceutical International Corporation |
| Swanson Health Products |
| Others |
Value Network & Pricing Analysis
Batch-scale economies at ultrasonic extraction facilities in southern Germany compress unit costs for marrubiin-standardized outputs while simultaneously elevating price floors for smaller processors lacking capital reserves to retrofit legacy maceration lines. This scale asymmetry concentrates pharmaceutical-grade supply among three to four extract houses capable of EMA-compliant batch release, reinforcing premium capture at the top tier and margin erosion for commodity traders serving food-grade channels.
Pricing Analysis
Pharmaceutical buyers anchor a contract-based long-term offtake structure that locks in multi-year pricing for Traditional Herbal Registration-compliant extracts. Price differentiation rests on certification grade—EMA monograph compliance versus food-grade additive status—and volume scale, with pharmacy-direct procurement commanding substantial premiums over wholesale distributor channels. Cost compression in the commodity tier is intensifying because CAP-subsidized cultivation in Romania and Bulgaria is expanding certified organic raw material availability. Dietary supplement bottlers exhibit the highest price sensitivity, trading specification flexibility for faster inventory turns, while respiratory syrup manufacturers under BfArM oversight absorb compliance premiums without volume elasticity.
Supply Chain Analysis
Mediterranean wild harvest volatility through Moroccan and Spanish collection networks underwrites persistent marrubiin content inconsistency that ripples downstream into processor inventory management. Geographic supply concentrates in Morocco, Spain, and Bulgaria, with contract farming expansion in the latter reducing dependency on unpredictable wild collections. Raw material sourcing draws from wild-harvested aerial parts, certified organic cultivation plots, and CAP-subsidized Romanian acreage. Single-source vulnerability persists for processors lacking backward integration into grower relationships. Distribution runs through pharmacy-direct channels for registered therapeutics, wholesale distributors for dietary supplement houses, and cooperative buying platforms for German herbalist networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among German pharmacy chains and Austrian functional beverage formulators, compressing margin extraction by intermediate distributors and forcing extract houses to choose between volume scale and premium positioning.
For Market Incumbents: Shield pharmacy channel relationships through dedicated regulatory affairs staffing capable of EudraVigilance adverse event reporting and periodic safety update preparation. Prioritize ultrasonic-assisted extraction licensing to decompose the six-week maceration cycle into 48-hour windows, enabling just-in-time replenishment that smaller competitors cannot match. The threat of synthetic expectorant substitution in acute care settings demands defensive positioning through pediatric glycerite formats where alcohol-free claims resist chemical alternatives. For New Entrants and Emerging Players: Lead with digestive bitters positioning in Austrian and Swiss functional beverage channels, where food-grade oversight bypasses Traditional Herbal Registration barriers that block pharmacy market access. The most penetrable white-space sits in non-alcoholic aperitif-style spirits incorporating horehound tinctures, a segment where pharmacist recommendation workflows do not gate consumer trial. Pursue direct-to-practitioner distribution through cooperative buying platforms that German herbalist networks increasingly favor over wholesale intermediaries. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among extract houses with multi-year pharmaceutical contracts under BfArM oversight, where batch release documentation requirements create switching costs that sustain renewal rates. Long-term viability hinges on backward integration into contract farming arrangements that reduce wild-harvest dependency and stabilize marrubiin content variance. Acquisition targets should demonstrate existing EMA monograph compliance infrastructure rather than retrofit requirements. The signal to watch is CAP subsidy allocation shifts in Romania and Bulgaria, which could accelerate cultivation acreage expansion and compress raw material premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Ultrasonic Extraction Technology Licensing | German contract manufacturers deploy 48-hour processing windows to meet pharmacy chain just-in-time demands. |
| Backward Integration into Contract Farming | CAP-subsidized Romanian cultivation reduces marrubiin content volatility that plagues Mediterranean wild harvests. |
| Traditional Herbal Registration Compliance Investment | BfArM-fast-tracked approvals enable pharmacist recommendation workflows that food-grade competitors cannot access. |
| Direct-to-Practitioner Distribution Platform | Herbalist cooperatives in Lower Austria bypass wholesale margin extraction through specialized e-procurement portals. |
| Pediatric Glycerite Format Development | Alcohol-free positioning targets dry-syrup applications where synthetic dextromethorphan substitution is accelerating. |
Research Methodology
A standing panel of extraction technology specialists, regulatory affairs directors at German extract houses, Austrian functional beverage formulators, and pharmacy chain procurement managers provided ongoing calibration across the research cycle. Primary interviews with these stakeholders were combined with secondary validation from EMA monograph databases, BfArM Traditional Herbal Registration filings, EU CAP subsidy allocation records, and customs trade data for Marrubium vulgare raw material imports. Bottom-up volume modeling across liquid extract, dried leaf, powder, and tincture formats was triangulated against top-down value estimates derived from pharmacy channel pricing intelligence.
Consistency checks against external benchmarks validated that modeled CAGRs aligned with observed contract renewal rates and capacity expansion announcements across the projection horizon. The analytical framework segmented demand by product type, end user, distribution channel, and application, with additional granularity for marrubiin standardization tiers and certification levels. Forecast inputs incorporated CAP subsidy trajectory assumptions, EMA pharmacovigilance guideline evolution, and ultrasonic extraction adoption curves among Central European processors.
Forecasts assume regulatory continuity in EMA monograph requirements and BfArM oversight protocols; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as CAP subsidy allocations and wild-harvest seasonal variability evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Asia-Pacific Brewing Enzymes Market
Ingredients
Casein Market
Ingredients
Asia-Pacific Potato Protein Market
Ingredients
Ice Cream Bases Market
Ingredients
Canada Whey Protein Ingredients Market
Ingredients
Meat Tenderizer Powder Market
Ingredients
Aroma Ingredients Market
Ingredients
Africa Fats and Oil Market
Ingredients
Sugar Beet Pectin Market
Ingredients
Global Autolyzed Yeast Extract Market
Ingredients
Vegetable Glycerin Market
Ingredients
Wheat Germ Oil Market
Ingredients
Halal and Kosher Empty Capsules Market
Ingredients
Europe Vanilla Beans and Extract Market
Ingredients
Middle-East and Africa Vegetable Oil Market
Ingredients
Dry Molasses Products Market