
 Gluten-Free Flour Market | 2026-2036
Gluten-Free Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Gluten-Free Flour Market Analytics
The gap between premium artisan-grade gluten-free flour and commodity bulk supply is repositioning how manufacturers allocate milling capacity and brand investment. General Mills, Inc. dominates mainstream retail shelf space with scaled production of rice and tapioca blends. Bob's Red Mill Natural Foods differentiates through stone-ground heritage processes and transparent sourcing narratives. King Arthur Baking Company, Inc. anchors the premium tier with certified gluten-free facilities and dedicated R&D for baking performance.
Gluten-free flour consists of milled grains, legumes, nuts, or starches processed to eliminate wheat, barley, and rye proteins, typically achieving less than 20 parts per million gluten content to meet clinical safety thresholds for celiac patients. Its primary purpose is to replicate the viscoelastic properties of gluten in baked goods and prepared foods through alternative protein structures and hydrocolloid additives. Almond flour occupies the highest margin tier due to keto and paleo diet alignment, while rice flour sustains volume leadership through cost efficiency and neutral flavor profiles in food manufacturing. Tapioca flour represents the fastest-growing starch segment as clean-label formulations replace modified wheat starches in snack and convenience applications.
The FDA enforces gluten-free labeling standards below 20 ppm, compelling manufacturers to implement segregated supply chains and third-party certification. EFSA and national regulators across the European Union enforce comparable thresholds through the Food Information to Consumers Regulation, creating compliance complexity for exporters. Codex Alimentarius guidelines from WHO provide the harmonized reference standard that most national frameworks adopt or exceed. Stakeholders must monitor evolving threshold debates and emerging rapid-detection technologies that could tighten specifications beyond current analytical limits.
Market Dynamics
The FDA's 20 ppm gluten threshold and parallel EFSA standards are forcing millers to rebuild supply chains around segregated handling infrastructure and third-party certification protocols.
Growth Catalysts
- Celiac Diagnosis Rates:Clinical screening expansion in the United States and European Union creates a patient population requiring certified gluten-free ingredients for daily consumption.
- Clean-Label Reformulation:Snack manufacturers are replacing modified wheat starches with tapioca and potato flours to meet retailer ingredient blacklists.
- Keto and Paleo Diet Alignment:Almond and coconut flours command premium positioning as low-carbohydrate alternatives attract health-conscious households through direct-to-consumer channels.
Market Restraints
- Input Cost Volatility:Almond flour margins compress during California drought cycles that constrain nut supply and spike raw material pricing.
- Supply Concentration Risk:Rice flour production clusters in Southeast Asian milling centers, exposing buyers to monsoon disruption and export restriction volatility.
- Technical Limitation:No single flour replicates gluten's viscoelasticity, forcing formulators to use expensive hydrocolloid blends and multi-flour systems.
Strategic Opportunities
- Underpenetrated Foodservice:Commercial bakeries in Germany and France lag retail in gluten-free SKU penetration, creating white space for pre-mix suppliers.
- Regulatory Tailwind:Australia's TGA is tightening gluten-free pharmaceutical standards, opening demand for certified excipient-grade starches.
- Technology Convergence:Near-infrared spectroscopy and blockchain traceability are combining to enable real-time gluten contamination detection at mill intake points.
Industry Challenges
- Certification Timeline Compression:BRC and GFSI audits require 12-18 month facility validation cycles that delay new entrant market entry.
- Skill Gap in Formulation Chemistry:Industrial bakeries lack staff trained in hydrocolloid hydration kinetics and protein network substitution science.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gluten-Free Flour Market |
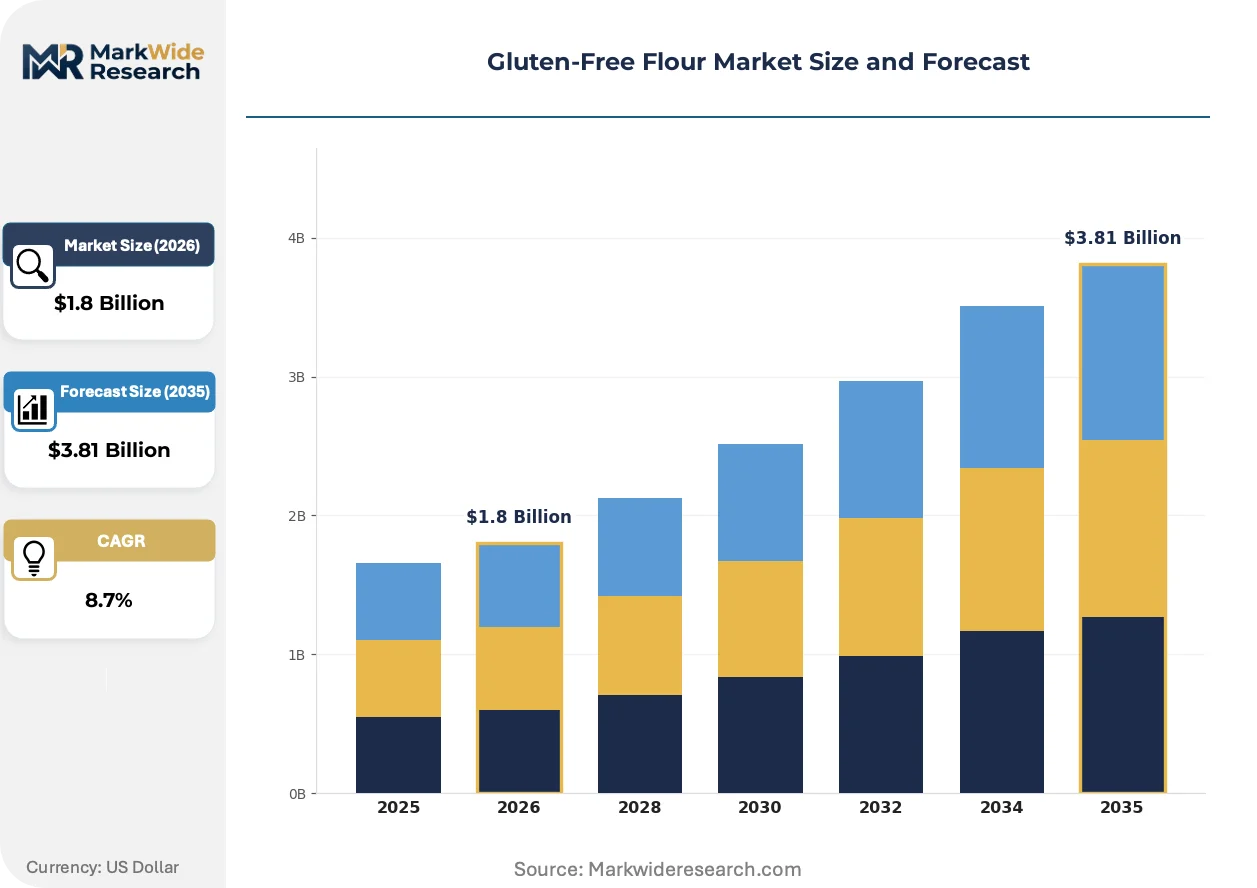
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Almond Flour, Coconut Flour, Rice Flour, Tapioca Flour End User: Households, Restaurants, Bakeries, Food Manufacturers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale Application: Baking, Cooking, Snacks, Meal Replacement |
| Companies Covered | General Mills, Inc., Cargill, Incorporated, Archer Daniels Midland Company, SunOpta, The Scoular Company, AGRANA Beteiligungs-AG, Associated British Foods plc, Bob’s Red Mill Natural Foods, King Arthur Baking Company, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gluten-Free Flour Market Evolving Landscape
Processing technology and supply chain transparency tools are reshaping how gluten-free flour achieves functional parity with wheat while meeting stricter contamination protocols.
High-pressure processing is integrating into oat flour production to enzymatically reduce cross-contact risks without thermal degradation of lipid fractions. European breakfast cereal manufacturers are adopting these systems to secure gluten-free claims on porridge and muesli lines. The technology is integrating previously separate decontamination and milling stages, compressing capital requirements for new facility builds.
REACH authorization requirements for processing aids are forcing European millers to substitute synthetic emulsifiers with native protein isolates from chickpea and fava bean streams. ECHA's 2024 updated guidance on food contact substances triggered reformulation audits across German and Dutch milling operations. Premium flour brands are responding by marketing "process-aid-free" positioning to differentiate from commodity suppliers.
Buyers in United States specialty retail are consolidating purchases around vertically integrated brands that control farming through packaging. Independent natural grocers are displacing distributor middlemen with direct mill relationships that offer lot-level traceability. This concentration is most visible in Pacific Northwest co-op networks where consumer-members demand origin documentation for every ingredient.
Gluten-Free Flour Market Segmentation
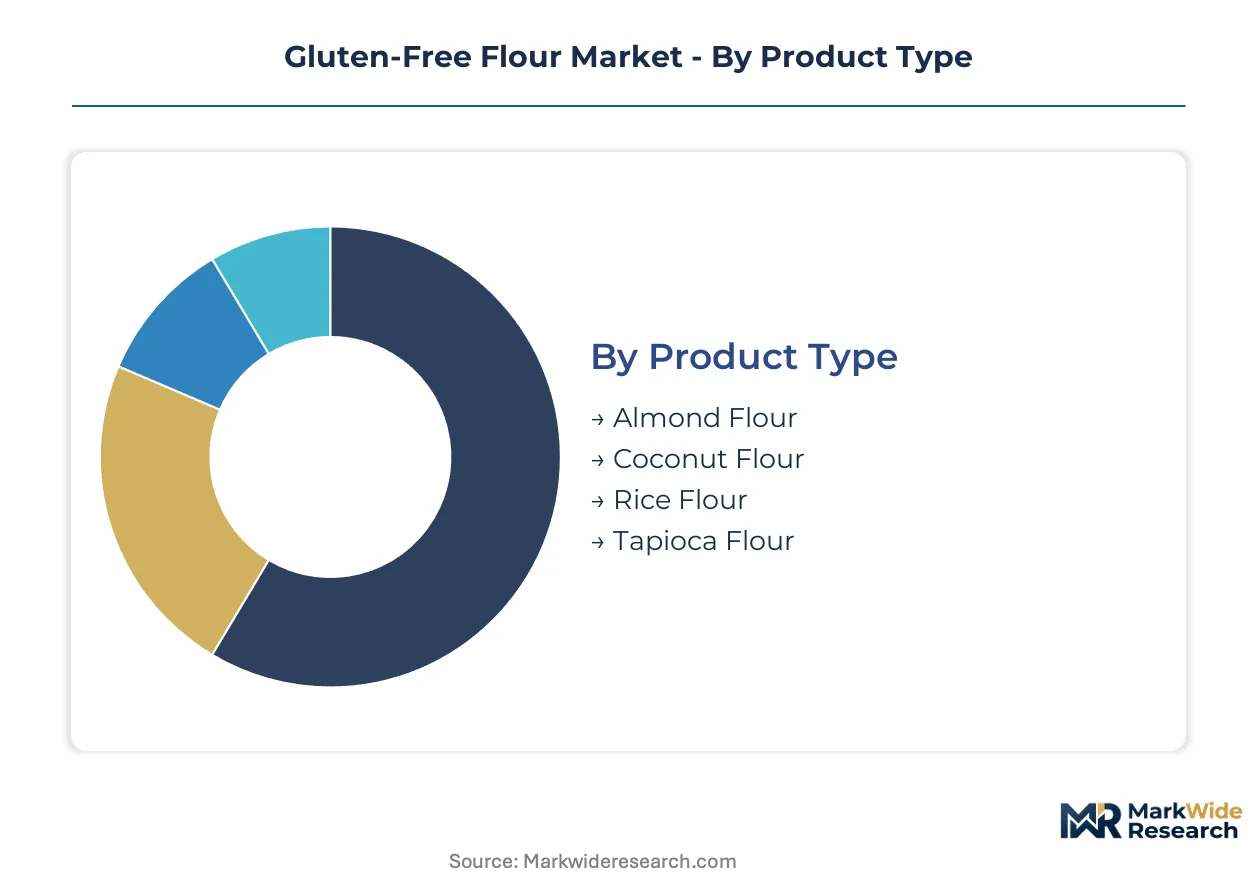
Gluten-free flour segmentation reveals divergent margin profiles across ingredient types and distribution channels. Manufacturers allocate milling capacity based on whether segments serve clinical necessity or discretionary wellness positioning.
Product Type:
Volume leadership concentrates in commodity starches while premium margins accrue to nut-based alternatives with functional density advantages.
- Almond Flour:Finely ground blanched almonds deliver high protein and fat content that mimics wheat flour's moisture retention in baked goods. Keto and paleo diet adherents in United States coastal metro areas purchase through direct-to-consumer subscription channels, compressing retail markup capture.
- Rice Flour:Milled white or brown rice provides neutral flavor and cost-efficient bulk for commercial baking applications. Southeast Asian milling clusters supply food manufacturers in Germany and France seeking clean-label starch bases for cracker and extruded snack production.
- Coconut Flour:Dehydrated coconut meat yields high-fiber, low-carbohydrate baking properties requiring recipe modification due to hygroscopic density.
- Tapioca Flour:Cassava root starch delivers exceptional binding and crisping functionality for clean-label reformulations displacing modified wheat starches.
Mature deployment sits with Rice Flour. Newer deployment is concentrated in Tapioca Flour.
End User:
Procurement sophistication varies sharply between clinical-diagnosis-driven consumption and commercial formulation requirements.
- Food Manufacturers:Industrial bakeries and CPG companies purchase bulk-certified flour under long-term supply agreements with third-party audit requirements. FDA's 20 ppm threshold compliance necessitates segregated handling infrastructure that elevates supplier qualification timelines.
- Bakeries:Commercial artisan and franchise operations require consistent performance across humidity and altitude variations, driving demand for pre-blended flour systems with hydrocolloid additives.
- Households:Diagnosed celiac patients and wellness-oriented consumers buy branded retail packages with certification marks from GFCO or NSF.
- Restaurants:Foodservice operators source through broadline distributors with limited SKU depth, creating white space for pre-portioned baking mixes.
Certified supply relationships dominate Food Manufacturers. Direct-to-consumer experimentation is expanding fastest among Households.
Distribution Channel:
Channel selection determines traceability depth and margin capture available to flour brands.
- Specialty Stores:Independent natural grocers and co-op networks demand lot-level origin documentation and transparent processing narratives. Pacific Northwest consumer-members in United States markets increasingly require farm-to-package traceability that displaces distributor intermediaries.
- Online Retail:Direct-to-consumer platforms enable subscription models and educational content that builds formulation confidence among novice gluten-free bakers.
- Supermarkets:Mass retail placement requires slotting fee investments and scaled production capacity that favors rice and tapioca blend suppliers.
- Wholesale:Foodservice and industrial distributors handle bulk shipments with reduced certification documentation compared to retail channels.
Established volume flows through Wholesale. Traceability innovation is reshaping Specialty Stores.
Application:
Functional requirements dictate flour selection based on structural demands and moisture management needs.
- Baking:Bread, pastry, and cake applications require multi-flour blends with xanthan gum or psyllium husk to replicate gluten's viscoelastic network. King Arthur Baking Company and Bob's Red Mill dominate this segment with proprietary blend formulations.
- Snacks:Extruded crackers, chips, and puffed products utilize tapioca and rice flour for expansion and crisping properties without allergen labeling triggers.
- Cooking:Sauce thickening and coating applications favor neutral-flavor starches with minimal protein interference.
- Meal Replacement:Protein-fortified shakes and bars incorporate almond and coconut flour for macronutrient density and shelf stability.
Technical complexity peaks in Baking. Clean-label reformulation is driving steepest expansion in Snacks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Portland anchors North American gluten-free flour innovation through vertically integrated mill networks that connect Willamette Valley farming cooperatives directly to Pacific Northwest specialty retail channels.
United States
FDA's 20 ppm labeling threshold drives certified facility investment across the country. California almond growers supply high-margin nut flour to keto-aligned direct-to-consumer brands. Minneapolis-St. Paul hosts scaled rice and tapioca blending operations serving mainstream retail distribution.
Germany
EFSA's Food Information to Consumers Regulation enforces strict gluten thresholds for imported flour. REACH authorization pressures millers in North Rhine-Westphalia to eliminate synthetic processing aids. Bavarian artisan bakeries lag in gluten-free SKU penetration, creating white space for pre-mix suppliers.
France
ANSM oversees pharmaceutical-grade starch standards tightening excipient requirements. Parisian commercial bakeries show slower gluten-free adoption than retail channels. Auvergne-Rhône-Alpes clusters clean-label snack manufacturing driving tapioca flour demand.
Australia
TGA's tightening gluten-free pharmaceutical standards open certified excipient-grade starch demand. Melbourne and Sydney specialty grocers enforce farm-to-package traceability requirements. Queensland cassava processing expands tapioca flour export capacity.
United Kingdom
FSA enforces labeling parity with EU standards post-Brexit. London's foodservice distributors carry limited gluten-free flour SKU depth. Midlands industrial baking corridor sources rice flour under long-term supply agreements with third-party audit requirements.
Gluten-Free Flour Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and sourcing transparency dimensions. The vendor base stratifies between scaled agricultural conglomerates with segregated handling infrastructure and heritage millers with stone-ground positioning. Three archetypes dominate: diversified grain traders with global sourcing networks, specialty millers with certified gluten-free facilities, and vertically integrated nut processors controlling California almond supply. Competitive moves concentrate on backward integration into farming operations and technology licensing for real-time contamination detection.
Among diversified agricultural conglomerates, Cargill, Incorporated and Archer Daniels Midland Company exemplify scale-driven commodity supply archetypes with global grain trading infrastructure. King Arthur Baking Company, Inc. occupies premium-tier positioning through certified facility investment and dedicated gluten-free R&D capacity. These three anchors represent the structural tension between volume efficiency and certification premium capture that defines competitive dynamics.
| Leading Market Players |
|---|
| General Mills, Inc. |
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| SunOpta |
| The Scoular Company |
| AGRANA Beteiligungs-AG |
| Associated British Foods plc |
| Bob's Red Mill Natural Foods |
| King Arthur Baking Company, Inc. |
| Others |
Value Network & Pricing Analysis
California almond orchard irrigation costs cascade through premium flour tiers, compressing margins for keto-aligned brands while rice flour suppliers in Thailand and Vietnam absorb monsoon-driven volatility through long-term offtake contracts with industrial bakers.
Pricing Analysis
Baking performance yield anchors value-based pricing for gluten-free flour, with certified-facility premiums separating King Arthur Baking Company positioning from commodity rice blend suppliers. Certification grade and volume scale drive differentiation, with GFCO-certified products commanding sustained premiums over uncertified alternatives. Pricing pressure intensifies in almond flour segments as drought cycles constrain California nut supply and elevate raw material costs. Food manufacturers exhibit highest price sensitivity due to bulk procurement volumes, while direct-to-consumer households absorb premium positioning for heritage-processed stone-ground products.
Supply Chain Analysis
Cassava root supply rests on Thai and Vietnamese agricultural processing clusters, with Queensland in Australia expanding export milling capacity for tapioca starch. Rice flour production draws from Southeast Asian milling centers, almond flour from California Central Valley orchards, and coconut flour from Philippine and Indonesian copra processors. Single-source vulnerability concentrates in California almond supply during drought periods, exposing premium brands to input cost spikes. Distribution runs through vertically integrated mill networks in the Pacific Northwest and broadline foodservice distributors serving commercial bakery chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certification timeline compression functions as a consolidation mechanism, forcing sub-scale millers to exit as BRC and GFSI audit cycles demand capital reserves beyond regional player capacity.
For Market Incumbents: Anticipate hydrocolloid cost inflation by securing multi-year supply agreements with xanthan gum and psyllium husk processors ahead of food-grade pharmaceutical demand competition. Lock in segregated handling infrastructure expansion in Minneapolis-St. Paul and Portland corridors before real estate costs escalate, cementing capacity advantages that new entrants cannot replicate within 18-month qualification windows. For New Entrants and Emerging Players: Capture Bavarian and Parisian commercial bakery white space where gluten-free SKU penetration lags retail channels by developing pre-mix formulations with altitude-compensated hydrocolloid ratios. Foodservice distributors in Germany and France carry limited certified flour depth, creating entry points for millers offering pre-portioned baking systems with embedded technical support. For Investors and Strategic Acquirers: TGA's tightening gluten-free pharmaceutical standards is the leading indicator that excipient-grade starch demand will separate certified facility valuations from commodity milling assets within a five-to-ten year viability window. Target vertically integrated nut processors with captive California almond supply and existing pharmaceutical customer relationships. Watch for FDA threshold reduction debates as the signal that rapid-detection technology investments will become mandatory rather than discretionary.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Facility Investment | GFCO and BRC certifications unlock pharmaceutical excipient contracts under TGA standards. |
| Backward Integration into Farming | Willamette Valley cooperative partnerships secure lot-level traceability for Pacific Northwest retail networks. |
| Pre-Mix Formulation Development | Altitude-compensated hydrocolloid blends address Bavarian bakery technical skill gaps. |
| Real-Time Contamination Detection | Near-infrared spectroscopy deployment at mill intake points satisfies FDA audit trail requirements. |
| Direct-to-Consumer Channel Expansion | Subscription models bypass retail slotting fees and capture margin from keto-aligned coastal households. |
Research Methodology
Multi-period observation of celiac diagnosis rates, certified facility investment flows, and almond orchard water allocation patterns anchored the trend analysis, supplemented by interviews with milling operations directors, food manufacturer procurement leads, specialty retail category buyers, and hydrocolloid supplier technical sales managers. Secondary validation drew from FDA gluten-free labeling guidance updates, EFSA Food Information to Consumers Regulation amendments, USDA almond acreage reports, and customs trade data for rice and tapioca flour imports. Bottom-up segment sizing triangulated against top-down market value estimates derived from production capacity and average selling price assumptions.
Input-output matrices modeled flour demand across product type, end user sophistication, distribution channel depth, and application functional requirements over the projection horizon. CAGRs were derived from segment-level growth rate assumptions weighted by base-year value contribution. Forecast inputs incorporated almond yield volatility scenarios tied to California drought indices and rice export restriction probability models for Southeast Asian supply clusters.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA threshold tightening, ECHA processing aid authorization revisions, and blockchain traceability adoption rates across Pacific Northwest cooperative networks. A small set of named triggers—regulatory threshold reductions, drought severity in California Central Valley, and TGA pharmaceutical starch certification mandates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
North America Soy Protein Concentrate Market
Ingredients
Medium Chain Triglyceride (MCT) Oil Market
Ingredients
Punica Granatum (Pomegranate) Seed Oil Market
Ingredients
Omega 6 Market
Ingredients
Rose Extract Market
Ingredients
South America Fats and Oil Market
Ingredients
Global Fresh Compressed Yeast Market
Ingredients
South America Agar Market
Ingredients
Milk Mineral Concentrate Market
Ingredients
Liquid Egg Market
Ingredients
Vital Wheat Gluten Market
Ingredients
South Africa Sodium Reduction Ingredients Market
Ingredients
Plant Based Ingredients Market
Ingredients
Non-GMO Oil Market
Ingredients
Colombia Food Ingredients Market
Ingredients
North America Malt Ingredients Market