
 Plant-Based API Market | 2026-2036
Plant-Based API Market Size, Share, and Industry Trends Forecast 2026-2036
Plant-Based API Market Analytics
Pharmaceutical formulators is bifurcating between synthetic and botanical sourcing strategies as EMA purity standards tighten for oral dosage applications. Evonik Industries AG leverages its fermentation expertise to produce high-purity plant-derived excipients for regulated drug channels. Cargill, Incorporated anchors North American supply through its integrated soybean and corn processing infrastructure. Indena S.p.A. specializes in standardized botanical extracts with documented pharmacokinetic profiles for European pharmaceutical clients.
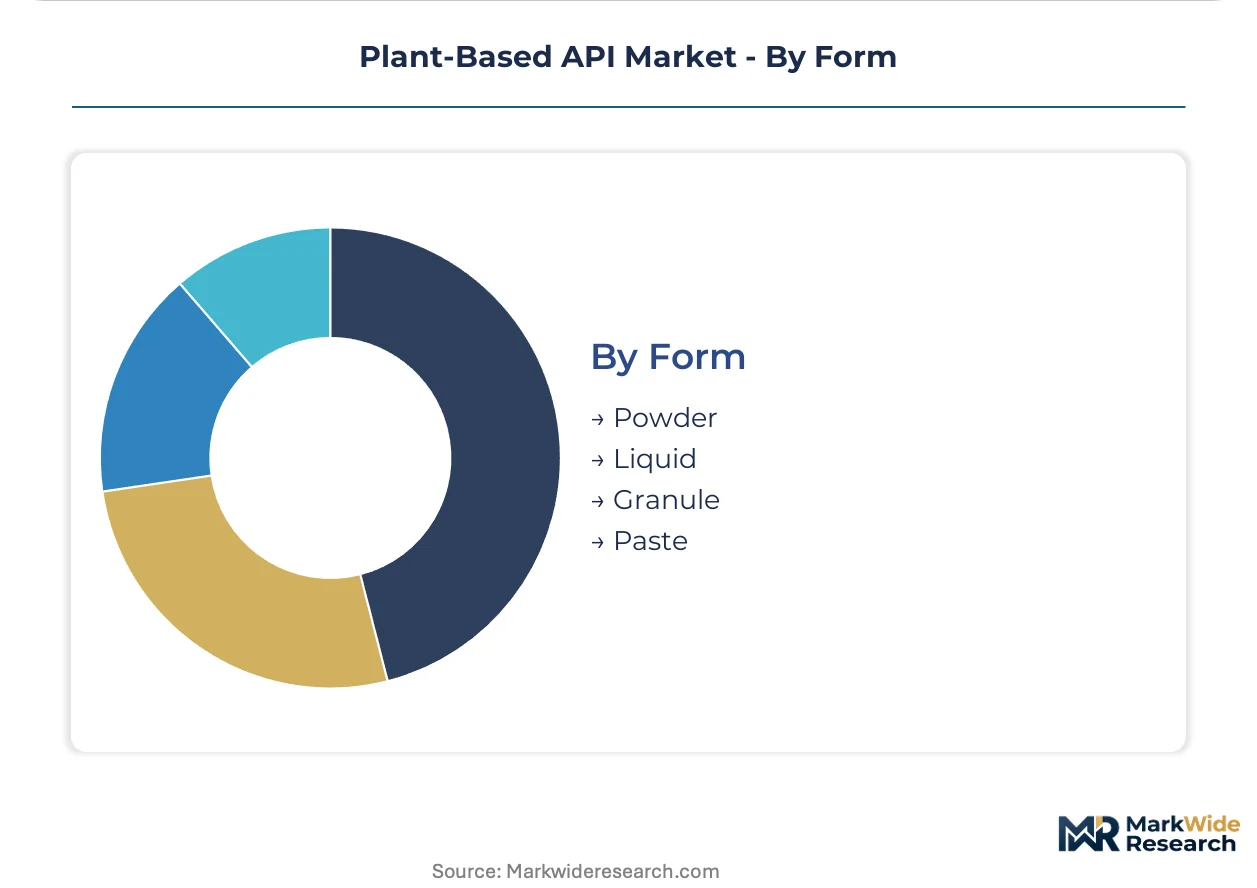
Plant-based APIs comprise biologically active compounds extracted, purified, and standardized from botanical sources for therapeutic use, typically requiring specified marker compound concentrations above 95 percent and validated chromatographic fingerprinting for batch consistency. Their primary commercial purpose centers on supplying active pharmaceutical ingredients and functional excipients for solid oral, topical, and parenteral dosage forms where synthetic chemistry faces regulatory or patient acceptance constraints. Proteins and emulsifiers lead current revenue pools due to their functional indispensability in formulation stability, while nutraceuticals and pharmaceuticals command the deepest margin pools as end-user segments because of stringent certification requirements and long-term supply contracts. Powder forms dominate manufacturing throughput for their shelf stability and precise dosing compatibility, though liquid extracts gain share in biopharmaceutical applications requiring rapid solubilization.
EMA guidelines, REACH chemical safety registrations, and FDA botanical drug development guidance collectively shape purity thresholds, extraction solvent restrictions, and clinical evidence requirements for market access across regulated jurisdictions. These frameworks elevate capital requirements for extraction facilities and analytical laboratories while disqualifying uncertified suppliers from pharmaceutical procurement lists. Stakeholders must monitor evolving pharmacopeial monograph revisions and region-specific sustainability disclosure mandates to preserve formulation partnerships and avoid supply chain disqualification.
Market Dynamics
EMA purity benchmarks are compressing supplier margins and forcing pharmaceutical formulators to consolidate procurement around certified botanical extractors with validated chromatographic capabilities.
Growth Catalysts
- REACH chemical safety registrations:European pharmaceutical manufacturers now require documented solvent residue profiles for all botanical APIs entering oral solid dosage channels, accelerating demand for compliant extraction partners.
- Biopharmaceutical solubilization requirements:Liquid plant-based extracts are capturing share in parenteral formulation development where synthetic excipients face patient immunogenicity constraints.
- German contract manufacturing clusters:Specialized phytochemical extraction facilities in Bavaria and Baden-Württemberg are scaling GMP-certified capacity to serve pan-European drug sponsors.
Market Restraints
- Agricultural input volatility:Soybean and corn feedstock prices fluctuate with commodity futures, compressing margin predictability for North American protein and emulsifier producers.
- Extraction solvent restrictions:ECHA guidelines on residual hexane and ethanol concentrations in botanical extracts have disqualified multiple South Asian suppliers from European pharmaceutical procurement lists.
- Synthetic chemistry substitution:Fermentation-derived excipients from microbial platforms are capturing formulation share in topical applications where botanical sourcing adds cost without therapeutic differentiation.
Strategic Opportunities
- Indian CDMO expansion:Contract development and manufacturing organizations in Hyderabad and Bangalore are building US FDA-inspected facilities to capture botanical API outsourcing from Western sponsors seeking cost arbitrage.
- CSRD sustainability disclosure mandates:European pharmaceutical buyers now require carbon footprint documentation across botanical supply chains, creating first-mover advantage for extraction houses with verified regenerative agriculture partnerships.
- Continuous processing convergence:Integration of supercritical CO2 extraction with in-line PAT analytics is enabling real-time batch release for time-sensitive biopharmaceutical clients.
Industry Challenges
- Pharmacopeial monograph lag:USP and EP revision cycles for novel botanical markers often trail clinical development timelines, forcing sponsors to pursue costly interim specification negotiations.
- Cross-border certification friction:Mutual recognition gaps between FDA botanical drug guidance and EMA herbal medicine frameworks extend regulatory approval timelines for multi-jurisdictional products.
- Analytical talent scarcity:Chromatographic fingerprinting and marker compound quantification require specialized phytochemical expertise that outpaces current university training output in key manufacturing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant-Based API Market |
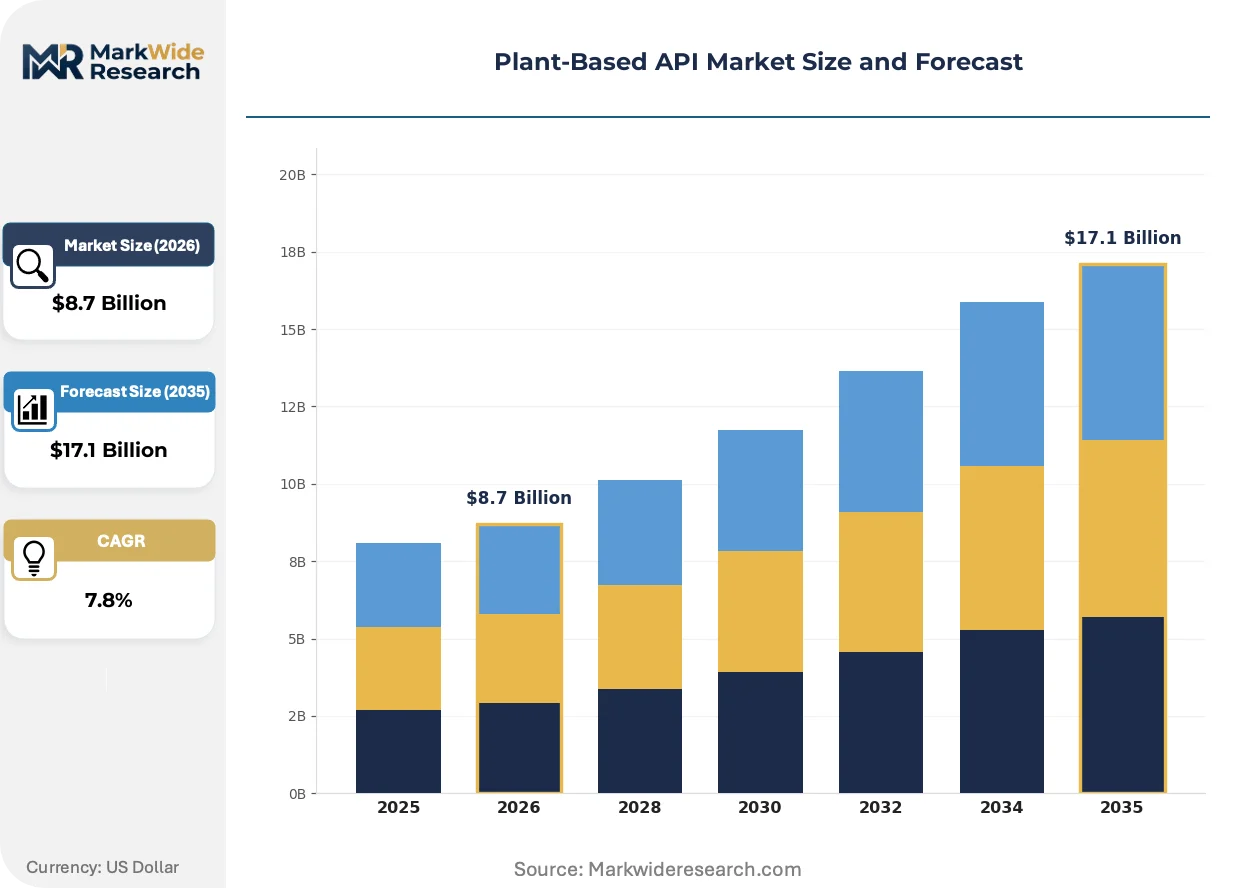
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proteins, Emulsifiers, Starches, Fibers Application: Beverages, Bakery, Snacks, Meat Alternatives End User: Food Industry, Cosmetics, Pharmaceuticals, Nutraceuticals Form: Powder, Liquid, Granule, Paste |
| Companies Covered | Roquette Freres SA, Evonik Industries AG, Cargill, Incorporated, BASF SE, Centroflora Group, Arboris, LLC, Alchem International Ltd., Indena S.p.A., Kothari Phytochemicals & Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant-Based API Market Evolving Landscape
Supercritical fluid extraction and precision fermentation are converging to redefine purity benchmarks and supply chain architecture for botanical-derived pharmaceutical inputs.
Supercritical CO2 extraction systems are supplanting conventional solvent-based methods in high-value alkaloid and terpene recovery. European pharmaceutical formulators are adopting these platforms for heat-sensitive compounds where thermal degradation risks batch failure. The technology is compressing downstream purification steps and enabling single-step isolation of marker compounds above 98 percent purity.
REACH Annex XVII updates are restricting residual solvent thresholds for botanical extracts entering drug channels. ECHA enforcement actions have triggered facility upgrades across Central European extraction houses, with capital deployment concentrating in Germany and Switzerland. Oral solid dosage manufacturers are responding by consolidating supplier panels around REACH-registered partners with dedicated analytical laboratories.
Long-term offtake agreements are displacing spot purchasing for critical botanical APIs. Multinational pharmaceutical sponsors in Germany and Switzerland are locking five-year supply contracts with extraction houses to secure batch-to-batch consistency for commercialized products. This shift is most visible in standardized ginkgo and milk thistle extracts where pharmacokinetic variability directly impacts clinical outcomes.
Plant-Based API Market Segmentation
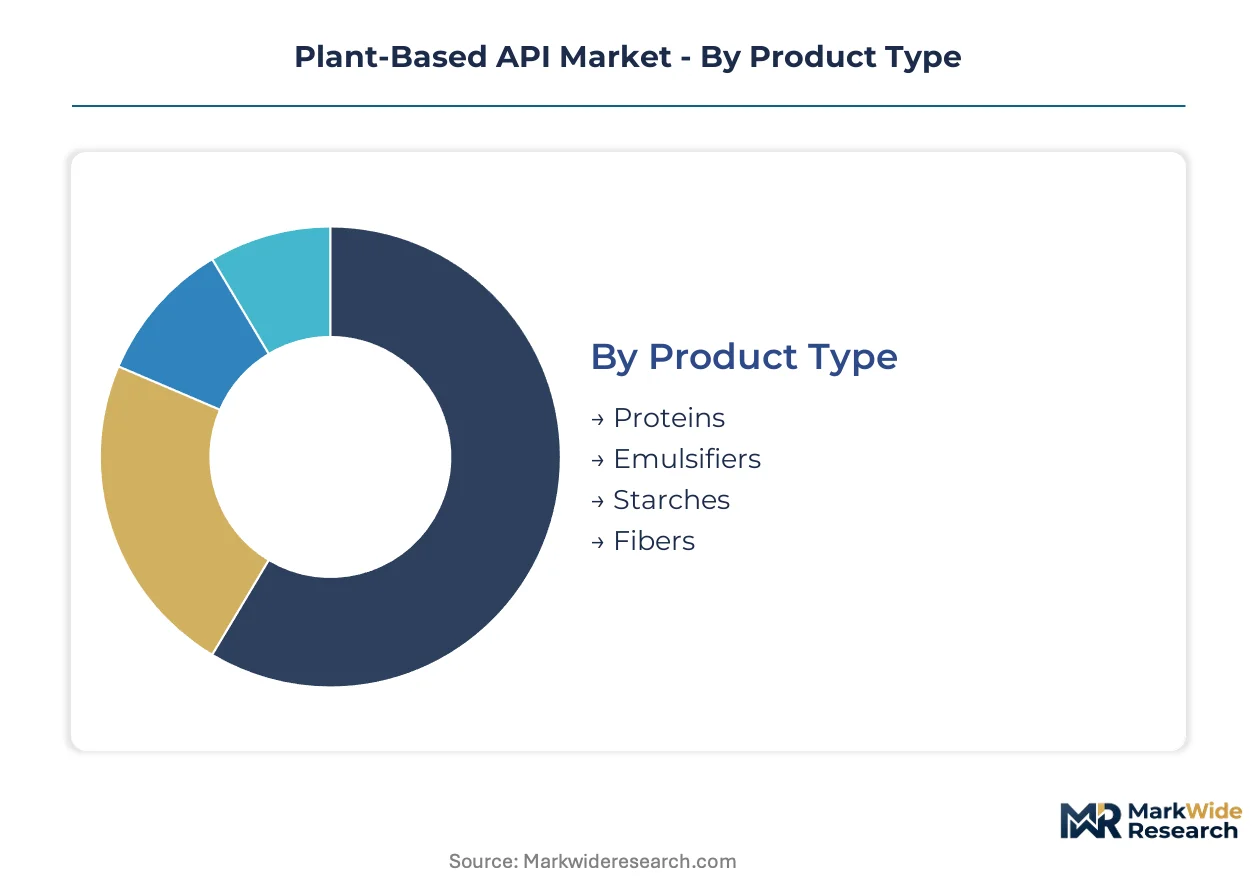
Plant-based API procurement patterns diverge sharply across product categories and end-use specifications. Pharmaceutical formulators demand validated chromatographic profiles that food and cosmetic buyers rarely require.
Product Type:
Domestic consumption dominates proteins and starches in North America and Europe, while emulsifiers and specialty fibers flow disproportionately to export markets serving Asian pharmaceutical manufacturers.
- Proteins:Soy and pea protein isolates serve as binding agents in oral solid dosage forms. German pharmaceutical contract manufacturers source these heavily from domestic oilseed processors to minimize REACH documentation burdens. Isolated soy proteins with specified PDI values above 90 percent anchor formulation stability for high-shear tablet compression.
- Emulsifiers:Lecithin and saponin-derived surfactants stabilize topical and parenteral formulations. Indian CDMOs in Hyderabad import these at scale for US FDA-inspected facilities serving Western drug sponsors seeking cost arbitrage on validated excipients.
- Starches:Maize and tapioca-derived native and modified starches function as disintegrants and binders.
- Fibers:Cellulose and hemicellulose fractions provide controlled-release matrix properties.
Proteins command the established base. The steepest expansion runs through emulsifiers.
Application:
Cost tier stratification separates beverage applications—where commodity pricing prevails—from meat alternatives and pharmaceuticals where certification premiums apply.
- Beverages:Plant protein fortification in ready-to-drink formats demands cold-water dispersibility and neutral flavor profiles. North American beverage manufacturers source pea protein isolates with specified NSI values above 85 percent to prevent sedimentation in extended shelf-life products.
- Meat Alternatives:Textured vegetable proteins and binding systems require thermoplastic extrusion compatibility. Dutch and German food technologists specify high-moisture extrudates with defined water-holding capacity above 3.0 g/g for whole-muscle analogs.
- Bakery:Egg replacement systems leverage emulsifier-starch synergies for crumb structure.
- Snacks:Protein enrichment in extruded formats emphasizes expansion ratio control.
Beverages anchor volume demand. Meat alternatives are climbing the fastest on reformulation mandates.
End User:
Customer type determines specification rigor, with pharmaceutical and nutraceutical buyers imposing pharmacopeial compliance that food and cosmetic segments rarely match.
- Pharmaceuticals:Botanical APIs for oral solid dosage require USP or EP monograph compliance with validated chromatographic fingerprinting. Swiss and German drug sponsors audit extraction houses for solvent residue documentation per ECHA Annex XVII thresholds.
- Nutraceuticals:Standardized extracts with specified marker compound concentrations command premium positioning. Italian and French supplement manufacturers source milk thistle and ginkgo extracts with documented pharmacokinetic profiles for health claim substantiation.
- Food Industry:Clean-label positioning drives demand for minimally processed plant proteins.
- Cosmetics:Emollient and surfactant applications prioritize sensory performance over clinical validation.
Food Industry represents the volume foundation. Pharmaceuticals shows the steepest margin expansion trajectory.
Form:
Supply concentration in powder processing reflects capital efficiency, while liquid extraction capabilities concentrate in specialized German and Swiss facilities serving parenteral formulation needs.
- Powder:Spray-dried and roller-dried formats dominate manufacturing throughput for shelf stability and precise dosing. Bavarian extraction houses supply GMP-certified powders with validated particle size distributions for direct compression tableting.
- Liquid:Aqueous and hydroalcoholic extracts enable rapid solubilization in biopharmaceutical applications. Swiss manufacturers of parenteral-grade liquid extracts maintain dedicated cleanroom suites for endotoxin-controlled production.
- Granule:Agglomerated formats improve flow properties for high-speed capsule filling.
- Paste:Semi-solid concentrates serve niche topical and cosmetic compounding.
Powder forms hold the installed capacity base. Liquid extracts are gaining share fastest in biopharmaceutical channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German extraction houses export standardized botanical APIs to Swiss and French pharmaceutical sponsors under REACH-registered supply agreements, while Indian contract manufacturers ship phytochemical isolates to US FDA-inspected formulation facilities.
Germany
Bavarian and Baden-Württemberg facilities scale GMP-certified phytochemical extraction for pan-European drug sponsors. EMA purity benchmarks and ECHA Annex XVII solvent restrictions compress supplier margins and disqualify uncertified competitors. Contract manufacturers in these regions consolidate procurement around validated chromatographic partners to preserve formulation partnerships.
Switzerland
Swiss drug sponsors source high-purity liquid extracts for parenteral applications where synthetic excipients face immunogenicity constraints. Swissmedic oversight aligns with EMA frameworks while maintaining distinct pharmacopeial requirements. Basel-area facilities specialize in endotoxin-controlled production for biopharmaceutical clients requiring rapid solubilization.
India
Hyderabad and Bangalore CDMOs build US FDA-inspected capacity to capture botanical API outsourcing from Western sponsors seeking cost arbitrage. CDSCO registration pathways and DGFT export incentives accelerate facility upgrades. These clusters now supply validated emulsifiers and protein isolates to North American oral solid dosage manufacturers.
United States
FDA botanical drug development guidance shapes clinical evidence requirements for plant-derived APIs entering drug channels. Midwestern oilseed processors supply soy and corn-derived excipients to domestic formulators. Greater Boston and New Jersey pharmaceutical clusters audit extraction houses for solvent residue documentation per FDA guidance thresholds.
Italy
Milan and Piedmont supplement manufacturers source milk thistle and ginkgo extracts with documented pharmacokinetic profiles for health claim substantiation. EFSA novel food assessments and EMA herbal medicine frameworks create dual regulatory exposure. Italian extraction houses specialize in standardized botanical markers for nutraceutical premium positioning.
Plant-Based API Market Competitive Landscape
Player mix skews toward diversified chemical conglomerates with fermentation expertise and specialized botanical extractors with pharmacopeial capabilities. Market structure concentrates around REACH-registered suppliers with validated analytical laboratories and GMP-certified manufacturing assets. Two strategic archetypes dominate: integrated agribusiness processors controlling upstream feedstock supply, and precision extraction houses delivering chromatographically standardized APIs. Competitive moves center on long-term offtake agreements locking batch-to-batch consistency and supercritical CO2 capacity expansion for heat-sensitive alkaloid recovery.
Within the integrated processor tier, Cargill, Incorporated and Roquette Freres SA exemplify upstream feedstock control through oilseed and starch processing infrastructure. Evonik Industries AG represents the fermentation-derived alternative path, leveraging microbial platforms to produce high-purity excipients. Among specialized extraction houses, Indena S.p.A. occupies a position anchored in standardized botanical extracts with documented pharmacokinetic profiles for European pharmaceutical validation requirements.
| Leading Market Players |
|---|
| Roquette Freres SA |
| Evonik Industries AG |
| Cargill, Incorporated |
| BASF SE |
| Centroflora Group |
| Arboris, LLC |
| Alchem International Ltd. |
| Indena S.p.A. |
| Kothari Phytochemicals & Industries Ltd. |
| Others |
Value Network & Pricing Analysis
EMA purity benchmarks and REACH Annex XVII registrations gate supply qualification while simultaneously stratifying price tiers across pharmaceutical-grade and nutraceutical-grade botanical extracts. German extraction houses with validated chromatographic capabilities command premium positioning against uncertified South Asian competitors disqualified from European procurement channels.
Pricing Analysis
Conventional solvent-based extraction, supercritical CO2 systems, and precision fermentation platforms occupy distinct price bands determined by purity thresholds and capital intensity. Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified pharmaceutical APIs from nutraceutical-grade extracts and commodity food ingredients. Price differentiation rests on REACH registration status and validated chromatographic fingerprinting. Cost compression in standard-grade extracts is intensifying as Indian CDMOs scale US FDA-inspected capacity. Nutraceutical manufacturers exhibit highest price sensitivity; Swiss parenteral formulators show lowest.
Supply Chain Analysis
Hexane and ethanol solvent availability through Rotterdam and Hamburg port infrastructure underwrites European extraction capacity. Raw material supply concentrates in Germany, India, and Switzerland for pharmaceutical-grade processing. Feedstock dependencies span Ukrainian sunflower, Indian soybean, and Chinese ginkgo leaf. Single-source vulnerability runs through German GMP-certified facilities for heat-sensitive alkaloid recovery. Distribution runs through long-term offtake agreements locking batch-to-batch consistency rather than spot purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat arena where EMA certification entrenchment creates switching costs that pharmaceutical formulators cannot easily circumvent. Network effects concentrate around extraction houses with validated pharmacokinetic documentation.
For Market Incumbents: Secure five-year supply contract extensions with Swiss and German drug sponsors before Indian CDMOs complete US FDA facility inspections. Invest in supercritical CO2 capacity expansion for heat-sensitive terpene recovery to defend against fermentation-derived substitutes capturing topical formulation share. Lock exclusive regenerative agriculture partnerships to preempt CSRD sustainability disclosure advantages.
For New Entrants and Emerging Players: Lead with US FDA-inspected facilities in Hyderabad or Bangalore targeting North American oral solid dosage manufacturers seeking cost arbitrage on validated emulsifiers. Capture white-space in parenteral-grade liquid extracts where Swiss supply constraints create entry windows. Position through documented pharmacokinetic profiles matching Indena's standardized extract positioning.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed German contract manufacturing organizations that scaled GMP capacity during prior botanical API outsourcing waves. Five-to-ten-year viability hinges on REACH-registered supplier consolidation continuing under ECHA enforcement pressure. Monitor EMA herbal medicine framework revisions as inflection signal for multi-jurisdictional product approval timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | Enables single-step isolation of marker compounds above 98 percent purity for EMA compliance. |
| REACH Registration Investment | Preserves European pharmaceutical procurement eligibility under ECHA Annex XVII solvent restrictions. |
| Regenerative Agriculture Partnership | Delivers verified carbon footprint documentation required by CSRD sustainability disclosure mandates. |
| Long-term Supply Agreement | Locks batch-to-batch consistency for commercialized ginkgo and milk thistle extract products. |
| US FDA Facility Inspection | Qualifies Indian CDMOs for Western sponsor outsourcing seeking cost arbitrage on validated excipients. |
Research Methodology
A spread of perspectives from extraction house technical directors, pharmaceutical regulatory affairs leads, contract manufacturing procurement managers, and nutraceutical formulation scientists converged on the working assumptions. Primary fieldwork combined with secondary validation through EMA submission databases, USP pharmacopeial monograph revisions, FDA botanical drug guidance filings, and CDSCO registration records. Bottom-up capacity assessments across Bavarian and Baden-Württemberg facilities triangulated against top-down demand estimates from European oral solid dosage manufacturers.
Segmentation dimensions modeled include product type tier, end-use application rigor, customer certification requirements, and regional regulatory cluster across the analysis window. CAGRs derive from facility capacity expansion announcements, long-term offtake contract disclosures, and feedstock price trajectory assumptions. Industry-specific inputs incorporate ECHA enforcement action timelines and pharmacopeial monograph revision cycles.
The analysis sits within stated boundaries; outcomes outside sustained EMA purity benchmark tightening or REACH Annex XVII solvent restriction enforcement would require recalibration. Forecasts reflect documented assumptions regarding German contract manufacturing cluster scaling and Indian CDMO facility upgrade completion. Practitioners should keep alternative scenarios live as EMA herbal medicine framework harmonization with FDA botanical drug guidance evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Vitex Agnus Castus Extract Market
Ingredients
Middle East and Africa Fruit and Vegetable Ingredients Market
Ingredients
Sodium Caseinate Market
Ingredients
Dry Brewing Ingredients Market
Ingredients
Spain Fermentation Ingredients Market
Ingredients
United States Avocado Oil Market
Ingredients
Grape Seed Extracts Market
Ingredients
Bangladesh Mustard Oil Market
Ingredients
North America Bioactive Ingredients Market
Ingredients
Global Personal Care Active Ingredients Market
Ingredients
Asia Pacific Vegetable Oil Market
Ingredients
Marine Ingredients Market
Ingredients
Cocoa Market
Ingredients
Fish Peptones Market
Ingredients
Marine Collagen Ingredients Market
Ingredients
Cosmetic Ingredients Market