
 Liquid Malt Extract Products Market | 2026-2036
Liquid Malt Extract Products Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Malt Extract Products Market Insights
Premium malt extract specification is rotating toward higher diastatic power and lower moisture thresholds as craft breweries and nutraceutical formulators demand cleaner label inputs. Muntons PLC leverages its UK malting heritage to sustain long-term supply contracts with European brewers. Boortmalt anchors global volume through its integrated barley-to-extract pipeline across multiple continents. Rahr Corporation differentiates via specialized roasting profiles that serve the North American craft segment.
Liquid malt extract is a concentrated syrup derived from germinated cereal grains, typically barley, produced through controlled mashing, wort separation, and vacuum evaporation to achieve solids content between 78% and 82%; its primary function is to provide fermentable sugars, color, and enzymatic activity across brewing, baking, and nutritional applications. Organic liquid malt commands margin premiums as clean-label procurement expands, while the brewery end user segment dominates volume offtake through direct bulk contracts. Nutraceutical applications represent the fastest-growing demand pool as protein-fortified beverages and malt-based dietary supplements gain shelf space.
FDA food safety standards and USDA organic certification govern product integrity and label claims in the United States, while REACH and EFSA frameworks in Europe regulate chemical inputs and novel food classifications for malt-derived ingredients. These compliance layers elevate capital requirements for new entrants and favor established processors with dedicated quality laboratories. Stakeholders must monitor evolving clean-label thresholds and carbon-accounting rules that will reshape supplier qualification criteria and contract structures.
Market Dynamics
Energy-efficiency mandates under the EU F-Gas Regulation are forcing malting facilities to retire conventional kiln systems and adopt modified vacuum evaporation technologies, restructuring capital allocation across the supply base.
Growth Catalysts
- EU Green Deal compliance:Malting operations in Germany and Belgium are retrofitting facilities to meet carbon-accounting thresholds, generating demand for process-optimized extract systems.
- Craft brewery procurement:Small-batch brewers across the United States and United Kingdom are contracting directly for premium liquid malt extract with specified diastatic power ranges.
- Nutraceutical formulation:Protein-fortified beverage manufacturers are integrating malt-derived substrates into clean-label dietary supplements.
Market Restraints
- Barley input volatility:Weather-driven supply fluctuations in Australia and Canada create margin compression for extract processors locked into annual contracts.
- Supply concentration:A limited number of integrated barley-to-extract pipelines control bulk volume, constraining negotiating leverage for independent craft buyers.
- Substitution pressure:Dried malt extract and enzymatic syrup alternatives compete on shelf stability and logistics efficiency.
Strategic Opportunities
- Organic certification expansion:USDA organic and EU organic label thresholds create margin premiums for processors investing in dedicated supply chains.
- Asia-Pacific craft emergence:Brewery incubation in South Korea and Japan presents underdeveloped demand for imported premium extract.
- Clean-label procurement mandates:Retailer qualification standards in France and Switzerland favor malt-derived ingredients over synthetic additives.
Industry Challenges
- Specialized malting expertise:Germination control and kiln operation skills are aging out of the workforce faster than training programs replenish talent pools.
- Multi-jurisdiction certification timelines:REACH registration, FDA food facility registration, and organic audit cycles extend product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Malt Extract Products Market |
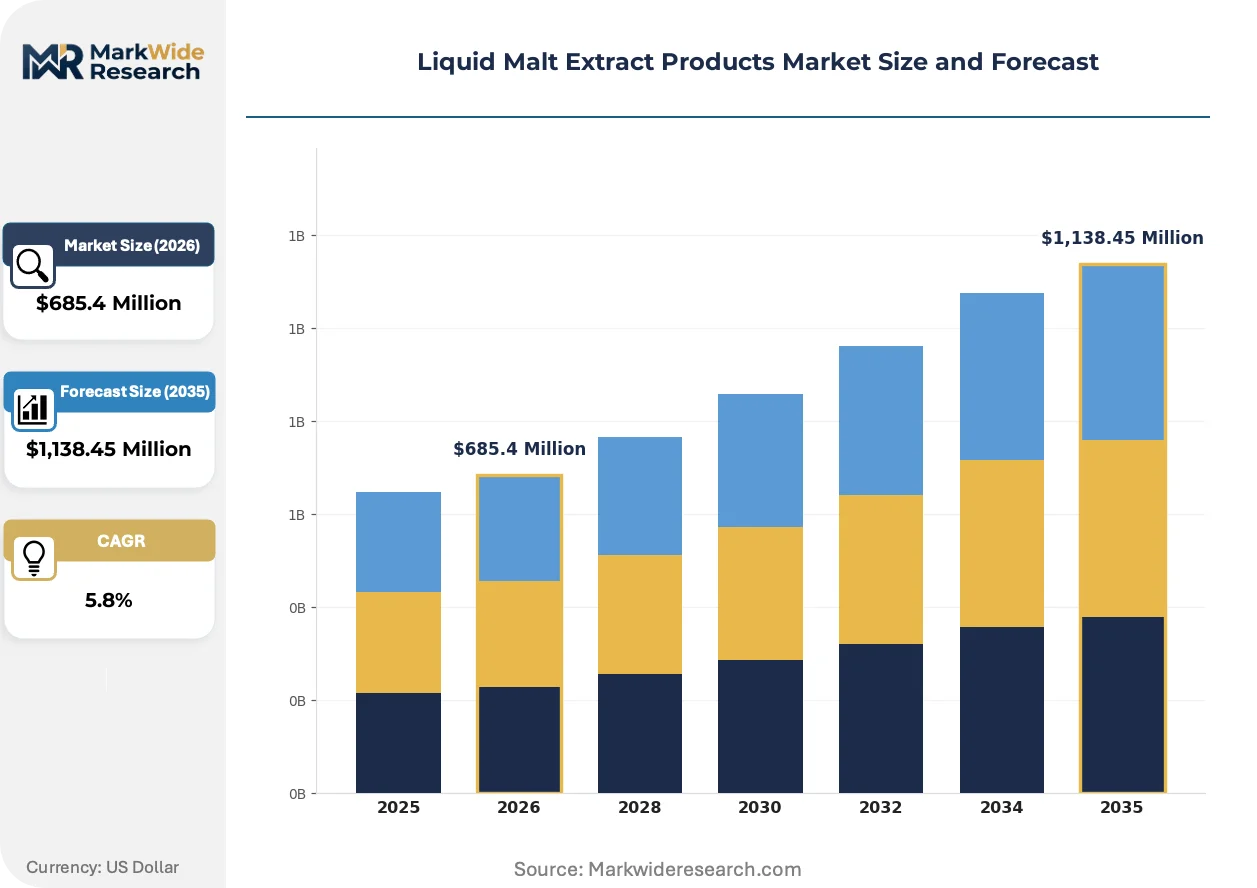
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Liquid Malt, Non-Organic Liquid Malt, Dry Malt Extract, Premium Malt Extract Application: Beverages, Bakery Products, Sauces, Dietary Supplements Distribution Channel: Online Stores, Supermarkets, Specialty Stores, Wholesale Distributors End User: Brewery, Food Industry, Nutraceuticals, Home Brewers |
| Companies Covered | Boortmalt, Malt Products Corporation, GrainCorp, Muntons PLC, Holland Malt, Malteurop, Group Soufflet, Viking Malt, Rahr Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Malt Extract Products Market Trends and Innovations
Processing technology and procurement specifications are diverging as end-users split between premium craft requirements and industrial-scale efficiency targets.
Modified vacuum evaporation systems with heat-recapture modules are bifurcating the installed base of malting facilities. Craft-oriented processors in Bavaria and Oregon are adopting low-temperature concentration to preserve enzymatic activity. Industrial-scale operators are compressing energy costs per unit through integrated heat exchangers.
The EU F-Gas Regulation is accelerating phase-out of hydrofluorocarbon-based refrigeration in malt storage and transport. Facility operators in the Netherlands and Denmark are retrofitting ammonia-based cooling systems. Compliance deadlines are compressing investment timelines for mid-cap malting groups.
Direct contracting between craft breweries and regional malting houses is displacing traditional distributor intermediaries. Brewery associations in Colorado and Yorkshire are negotiating collective purchasing agreements. This channel restructuring concentrates volume with processors demonstrating batch-traceability capabilities.
Liquid Malt Extract Products Market Segmentation
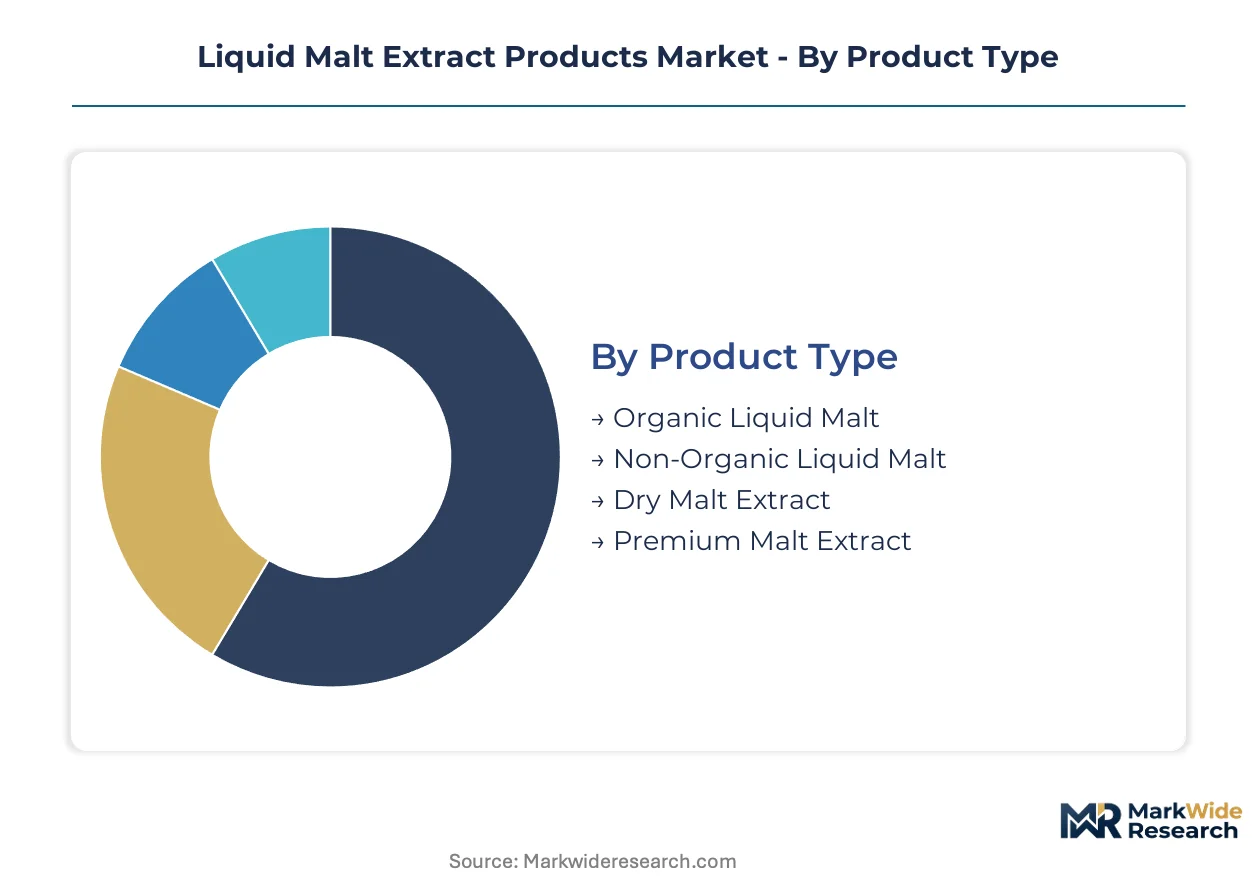
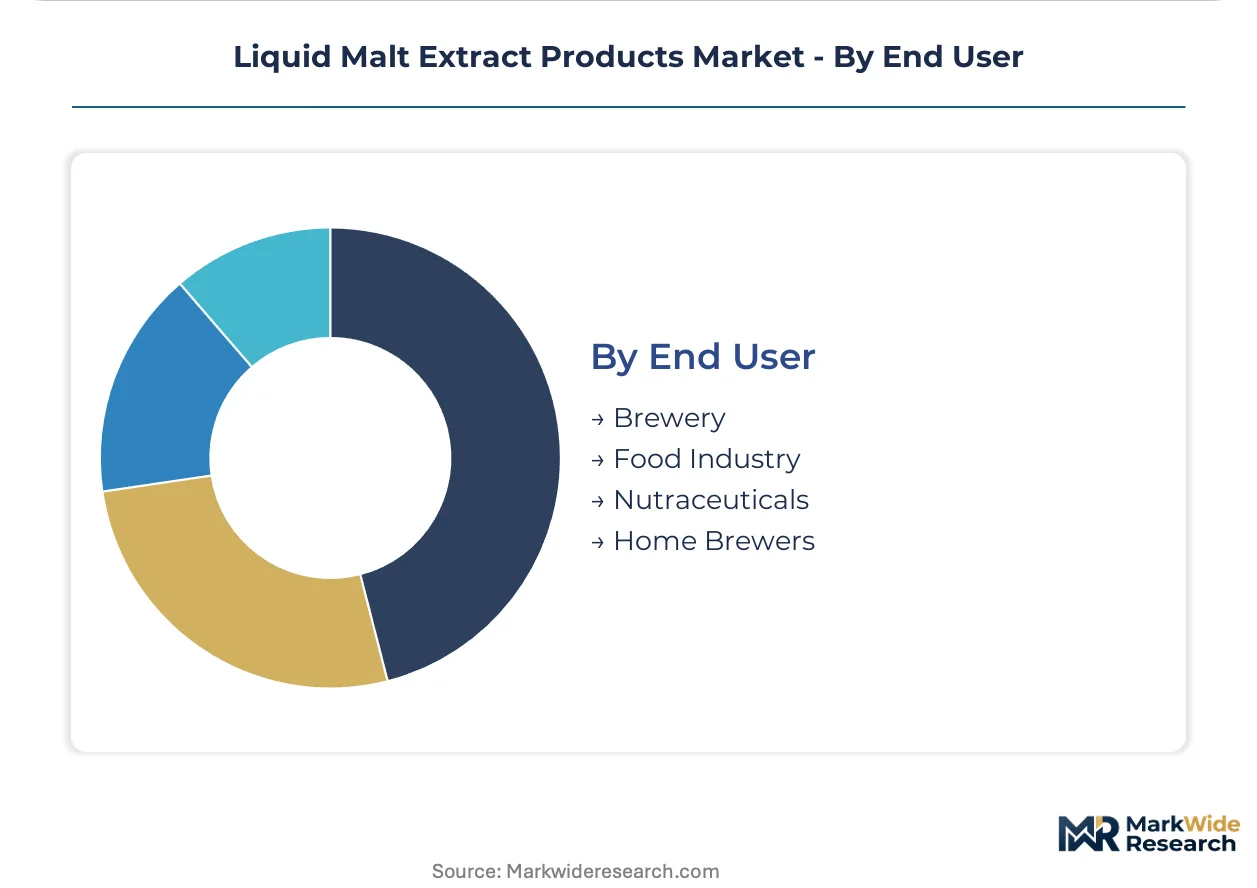
Liquid malt extract procurement patterns diverge sharply across end-use applications, with brewing operations demanding bulk enzymatic specifications while nutraceutical formulators prioritize organic certification thresholds. Channel structures further fragment as craft brewers disintermediate traditional distributors in favor of direct malting house contracts.
Product Type:
Dry malt extract poses the most acute substitution threat to liquid formats, leveraging superior shelf stability and reduced freight costs to capture logistics-sensitive buyers.
- Non-Organic Liquid Malt:Standard-grade syrup with 78-82% solids content serves high-volume brewing operations through annual bulk contracts. German and Belgian industrial breweries anchor demand here, though margin compression from barley price volatility constrains processor flexibility.
- Organic Liquid Malt:Certified organic syrup commands 15-25% price premiums as clean-label procurement expands across French and Swiss retail channels. USDA and EU organic audit cycles extend lead times, favoring established processors with dedicated laboratory infrastructure.
- Premium Malt Extract:Specified diastatic power ranges above 120°Lintner target craft brewery small-batch production in Colorado and Yorkshire.
- Dry Malt Extract:Spray-dried powder alternative eliminates refrigeration requirements and reduces transport costs for Asia-Pacific export markets.
Non-Organic Liquid Malt anchors the volume base while Organic Liquid Malt gains share at the steepest rate.
Application:
Cost tier stratification separates commodity brewing inputs from value-added nutraceutical formulations.
- Beverages:Fermentable sugar substrate for beer production represents the dominant consumption category. Craft brewery incubation in South Korea and Japan is expanding addressable demand for imported premium extract specifications.
- Dietary Supplements:Protein-fortified malt-based formulations are climbing the fastest as sports nutrition brands replace synthetic sweeteners with clean-label alternatives. EFSA novel food classifications govern ingredient approvals here.
- Bakery Products:Enzymatic activity enhancement for dough conditioning in artisan bread production.
- Sauces:Color and viscosity modification for barbecue and specialty sauce manufacturers.
Beverages retain the largest revenue footprint while Dietary Supplements demonstrate the most aggressive expansion trajectory.
Distribution Channel:
Volume concentration favors wholesale structures, though digital penetration is accelerating in fragmented buyer segments.
- Wholesale Distributors:Bulk tanker and intermediate bulk container logistics dominate brewery procurement, with Boortmalt and Muntons PLC maintaining direct supply relationships across multiple continents.
- Online Stores:E-commerce penetration is expanding most quickly among home brewers and small-scale food manufacturers seeking specialized roasting profiles without minimum order constraints.
- Specialty Stores:Regional brewing supply retailers serving craft segment equipment and ingredient bundling.
- Supermarkets:Limited retail shelf presence concentrated in European markets with home baking traditions.
Wholesale Distributors control the volume base while Online Stores capture the steepest share gains.
End User:
Customer type maturity separates established industrial buyers from emerging craft and nutraceutical demand pools.
- Brewery:Industrial-scale lager producers and craft ale manufacturers constitute the primary demand anchor, with German facilities retrofitting kilns to meet EU F-Gas Regulation compliance deadlines.
- Nutraceuticals:Protein-fortified beverage and dietary supplement manufacturers are expanding most aggressively, driven by FDA food safety standards and retailer clean-label mandates.
- Food Industry:Bakery and sauce manufacturers utilizing malt extract for enzymatic and color functions.
- Home Brewers:Small-volume hobbyist segment concentrated in United Kingdom and United States markets.
Brewery end users anchor the volume base while Nutraceuticals gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in liquid malt extract tilt toward surplus production in established malting belts and deficit absorption in emerging craft markets. Germany and Belgium sustain net export positions through integrated barley-to-extract infrastructure. Import dependency concentrates in Asia-Pacific craft incubation zones and North American specialty segments.
Germany
Bavarian craft brewery clusters and industrial lager producers drive premium extract procurement with specified diastatic power requirements. The EU F-Gas Regulation compels kiln retrofits across malting facilities in Lower Bavaria and Upper Palatinate. Munich and Bamberg anchor production gravity, with regional cooperatives negotiating collective purchasing agreements for small-batch brewers.
United States
Colorado and Pacific Northwest craft brewery incubation expands direct contracting for liquid malt extract with traceability documentation. FDA food facility registration and USDA organic certification govern cross-state distribution compliance. Denver and Portland metropolitan brewing corridors concentrate demand for specialized roasting profiles and enzymatic specifications.
Belgium
Traditional lambic and abbey brewing heritage sustains steady demand for heritage malt varieties with controlled fermentation characteristics. REACH chemical input registration affects imported barley treatment protocols at Antwerp and Ghent processing sites. Flemish malting houses along the Scheldt corridor invest in ammonia-based cooling retrofits ahead of EU refrigeration phase-out deadlines.
United Kingdom
Yorkshire and Scottish craft ale revival drives small-batch procurement of premium liquid malt extract with heritage barley provenance. Muntons PLC maintains long-term supply relationships across English and Welsh brewing operations. Burton-upon-Trent and Edinburgh clusters demonstrate batch-traceability capabilities through direct malting house partnerships.
Japan
South Korean and Japanese craft brewery emergence creates import demand for premium liquid malt extract specifications unavailable from domestic suppliers. METI industrial standards govern food additive classifications for malt-derived ingredients in functional beverages. Tokyo and Osaka distribution hubs consolidate refrigerated tanker logistics for temperature-sensitive syrup delivery.
Liquid Malt Extract Products Market Competitive Landscape
Concentration sits with integrated barley-to-extract processors controlling bulk volume through captive agricultural supply chains. The vendor base stratifies across three tiers: multinational malting groups with continental processing footprints, regional specialists serving craft segments through direct contracting, and commodity traders distributing standardized grades. Competitive positioning hinges on backward integration into barley origination, certification laboratory infrastructure, and kiln technology retrofit completion ahead of regulatory deadlines. M&A activity targets regional craft-focused malting houses, while capacity expansion concentrates in low-carbon process installations.
Within the integrated multinational tier, Boortmalt and Malteurop exemplify scale-driven archetypes with multi-continental processing footprints. Muntons PLC occupies a position representing UK heritage malting specialization with dedicated quality laboratory infrastructure. Rahr Corporation anchors the North American craft segment vector through specialized roasting profile capabilities. These three named entities collectively illustrate how competitive positioning fragments across geographic specialization, certification depth, and end-use segment focus rather than converging on uniform scale advantages.
| Leading Market Players |
|---|
| Boortmalt |
| Malt Products Corporation |
| GrainCorp |
| Muntons PLC |
| Holland Malt |
| Malteurop |
| Group Soufflet |
| Viking Malt |
| Rahr Corporation |
| Others |
Pricing and Supply Chain Analysis
EU organic certification and USDA organic label thresholds gate both supplier qualification and price differentiation simultaneously, as processors investing in dedicated laboratory infrastructure capture margin premiums while conventional grade suppliers face cost compression from barley volatility.
Pricing Analysis
Industrial brewery buyers anchor contract-based long-term offtake structures across the liquid malt extract market. Three-tier pricing structure across premium, standard, and economy levels separates organic-certified syrup from heritage varietal specifications and commodity-grade inputs. Cost compression in standard grades is intensifying because Australian and Canadian barley harvest volatility squeezes processor margins. Craft brewers demonstrate lowest price sensitivity, prioritizing diastatic power specifications and batch traceability over per-unit economics.
Supply Chain Analysis
Refrigerated tanker lead times for temperature-sensitive syrup delivery stretch distribution planning horizons across Asia-Pacific import corridors. Supply concentration rests on Germany, Belgium, and the United Kingdom as integrated barley-to-extract pipelines. Raw material dependencies center on Australian and Canadian malting barley, ammonia-based cooling equipment, and vacuum evaporation systems. Single-source vulnerability concentrates in germination control expertise aging out of the workforce faster than training replenishment. Distribution runs through wholesale tanker logistics with direct malting house contracting displacing traditional intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Craft brewery disintermediation and nutraceutical formulation emergence fragment demand into specialized niches, creating structural opportunities for differentiated positioning beyond commodity volume play.
For Market Incumbents: Compound backward integration into captive barley origination to defend against dried malt extract substitution pressure and lock in supply security. Accelerate ammonia-based cooling retrofits ahead of EU F-Gas Regulation phase-out deadlines to preserve facility licensing. Prioritize certification laboratory infrastructure investment to sustain organic and premium grade margin premiums as clean-label procurement expands. For New Entrants and Emerging Players: Anchor in South Korean and Japanese craft brewery incubation zones where domestic supply gaps force import dependency for premium extract specifications. Target protein-fortified beverage formulators seeking malt-derived substrates as synthetic sweetener replacements. Pursue direct contracting models with batch-traceability documentation to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: EU F-Gas Regulation compliance deadlines reshape the acquisition landscape toward processors with completed kiln retrofits and ammonia cooling installations. Five-to-ten year viability favors regional craft-focused malting houses with dedicated quality infrastructure over commodity-scale operators facing margin compression. Monitor clean-label procurement mandate expansion across French and Swiss retail channels as inflection signal for organic certification premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barley Origination | Captive supply from Australian and Canadian growing regions insulates processors from weather-driven input volatility. |
| Ammonia-Based Cooling Retrofit | EU F-Gas Regulation compliance preserves facility operating licenses ahead of hydrofluorocarbon phase-out deadlines. |
| Organic Certification Investment | USDA and EU organic audit capabilities unlock 15-25% price premiums in French and Swiss retail channels. |
| Direct Malting House Contracting | Bypassing distributor intermediaries concentrates volume with processors demonstrating batch-traceability capabilities. |
| Low-Temperature Concentration Technology | Preserved enzymatic activity meets craft brewery diastatic power specifications above 120°Lintner thresholds. |
Research Methodology
Operator-level perspectives from malting plant managers, craft brewery procurement leads, nutraceutical formulation scientists, and wholesale distribution channel heads anchored the qualitative base for this study. Primary fieldwork combined with secondary validation from customs and trade data, SEC filings of publicly traded processors, EU F-Gas Regulation implementation tracking, and organic certification registry databases. Bottom-up volume modeling across product grades and applications triangulated against top-down macroeconomic demand indicators.
Sensitivity analysis tested forecast robustness across barley price volatility scenarios, regulatory compliance cost trajectories, and substitution elasticity parameters over the projection horizon. Segmentation dimensions modeled include organic certification status, end-use application across beverages and dietary supplements, and distribution channel structure. CAGRs were derived from annualized growth rate calculations applied to base-year market sizing. Industry-specific inputs incorporated EU Green Deal carbon-accounting thresholds and craft brewery incubation rates in Asia-Pacific markets.
Material uncertainties — weather-driven barley harvest failures, regulatory deadline extensions, and workforce skill gap acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding clean-label procurement mandate expansion and kiln technology adoption curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Virginiamycin Market
Ingredients
Marine Hyaluronic Ingredients Market
Ingredients
Asparagus Extract Market
Ingredients
Soy Flour Market
Ingredients
Wheat Protein Concentrates Market
Ingredients
Hibiscus Extract Market
Ingredients
Amylase Market
Ingredients
Cheese Ingredients Market
Ingredients
Africa Soy Protein Ingredients Market
Ingredients
Macleaya Cordata Extract Market
Ingredients
Malted Wheat Flour Market
Ingredients
Italy Soy Protein Market
Ingredients
Malted Barley Flour Market
Ingredients
Hydrolyzed Egg Market
Ingredients
Campesterol Market
Ingredients
2'-Fucosyllactose (2'-FL) Market