
 Ground-Nut Oil Market | 2026-2036
Ground-Nut Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Ground-Nut Oil Market Insights
Project finance tied to African crushing facilities is tilting competitive dynamics toward capital-heavy operators with balance-sheet depth. Cargill leverages its origination networks across Senegal and Argentina to secure feedstock at scale. Wilmar International Limited anchors Southeast Asian refining capacity with integrated port-to-pantry logistics. Bunge Limited competes through backward integration into Brazilian peanut farming cooperatives.
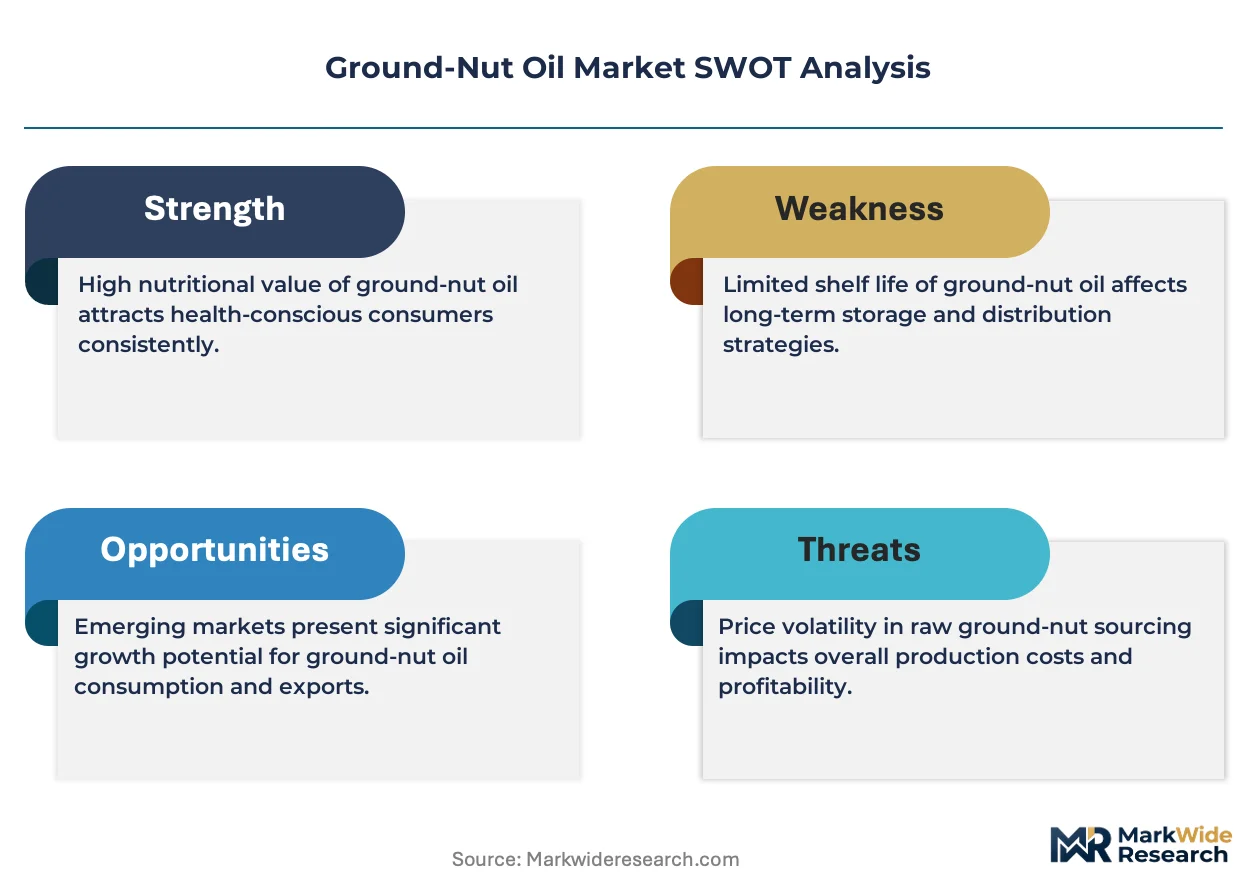
Ground-nut oil is an edible vegetable oil extracted from Arachis hypogaea seeds through mechanical pressing or solvent extraction, yielding a product with approximately 80% monounsaturated and polyunsaturated fatty acids and a smoke point ranging from 160°C for unrefined grades to 232°C for refined variants; its primary commercial purpose centers on frying, dressing, and industrial lubricant formulations. Refined oil dominates value pools in food manufacturing channels where oxidative stability commands premium positioning, while organic oil represents the fastest-expanding category as EU Green Deal farm-to-fork traceability requirements reshape procurement criteria. Culinary application sustains volume leadership across household and restaurant segments, though biofuels emerge as a structurally significant offtake avenue where policy mandates blend-rate floors.
FDA oversight of allergen labeling and GRAS status for refined peanut oil shapes US market access conditions, while EFSA maximum residue limits and REACH chemical safety protocols govern European import eligibility. India's FSSAI mandates edible oil fortification with vitamins A and D, directly altering product formulation requirements for domestic manufacturers. Stakeholders must monitor how EU deforestation regulation due diligence obligations cascade through West African supply chains.
Market Dynamics
India's FSSAI fortification mandates and China's GB standards for edible oil purity are compressing margins for non-compliant processors while rewarding integrated operators with laboratory and certification infrastructure. These dual regulatory pressures are accelerating consolidation around crushing clusters with captive testing facilities.
Growth Catalysts
- Cold-pressed extraction technology:Food manufacturers across Asia-Pacific are expanding sourcing of mechanically pressed oils for clean-label packaged goods, bypassing solvent-extracted alternatives that carry residual chemical concerns.
- EU Green Deal farm-to-fork traceability:Organic certification requirements are reshaping procurement criteria, with European buyers demanding blockchain-verified supply chain documentation from West African and South American origins.
- Biofuel blend-rate mandates:Policy floors for renewable fuel content in transportation sectors are opening structurally significant offtake channels for refined ground-nut oil as a feedstock alternative.
Market Restraints
- Argentine peso volatility:Currency instability in major feedstock origins compresses margin predictability for crushers without hedging infrastructure or dollar-denominated forward contracts.
- Solvent extraction bans in premium channels:EU organic certification bodies and US natural-foods retailers are systematically excluding hexane-extracted oils from premium shelf placements.
- Palm oil price arbitrage:Southeast Asian palm oil production cost advantages continue to displace ground-nut oil in price-sensitive frying applications across institutional foodservice.
Strategic Opportunities
- West African crushing facility expansion:Senegal and Mali offer underexploited origination potential where project finance availability favors capital-heavy operators with balance-sheet depth.
- Blockchain-integrated traceability platforms:Convergence of distributed ledger technology with satellite-based farm monitoring is enabling premium pricing for verified deforestation-free supply chains.
- Direct-to-restaurant distribution:Bypassing traditional wholesale channels through specialized bulk delivery to high-volume frying operations captures margin currently absorbed by intermediaries.
Industry Challenges
- Phytosanitary certification timelines:EU deforestation regulation due diligence obligations are extending pre-shipment documentation periods, straining working capital cycles for smaller traders.
- Refinery-scale capex requirements:Continuous deodorization and winterization equipment necessary for high-oleic variants demands capital commitments that exclude mid-scale entrants.
- Allergen segregation protocols:FDA GRAS status for refined peanut oil requires dedicated processing lines, complicating multi-oil facility economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ground-Nut Oil Market |
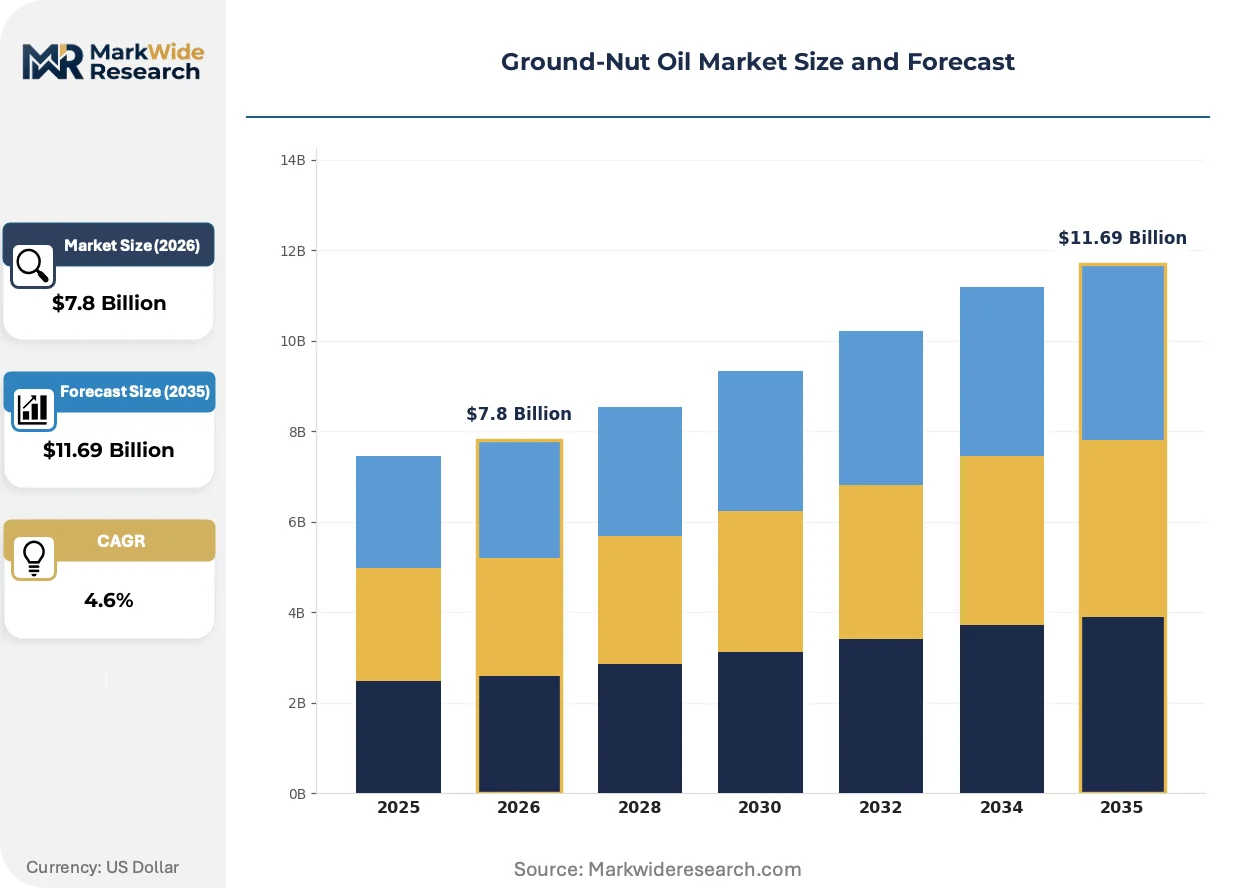
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $11.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Oil, Crude Oil, Blended Oil, Organic Oil Application: Culinary, Industrial, Cosmetics, Biofuels End User: Food Manufacturers, Restaurants, Households, Personal Care Companies Distribution Channel: Online Retail, Supermarkets, Direct Sales, Specialty Stores |
| Companies Covered | Cargill, Archer Daniels Midland Company, Wilmar International Limited, Bunge Limited, Olam International, COFCO Corporation, Gemini Edibles & Fats India Ltd, AAK AB, Marico Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ground-Nut Oil Market Trends and Innovations
Mechanical pressing and solvent recovery systems are undergoing rapid efficiency improvements while regulatory traceability requirements force digitization of supply chain documentation. These simultaneous pressures favor operators with capital reserves for equipment and compliance infrastructure.
Supercritical CO2 extraction systems are rendering obsolete traditional hexane-based solvent methods in premium oil segments. European organic food manufacturers and North American natural-foods retailers are adopting these systems at accelerating rates despite higher capital intensity. The technology is rendering obsolete smaller crushers dependent on legacy solvent infrastructure, compressing the supplier base toward integrated processors with multi-million-dollar equipment investments.
REACH chemical safety protocols and EFSA maximum residue limits are tightening import eligibility criteria for European markets. Industrial consequence includes mandatory third-party laboratory certification for every shipment batch, with rejection penalties for non-compliant lots. Refined oil categories bound for food manufacturing channels face the most stringent enforcement, driving consolidation toward exporters with captive laboratory facilities in Rotterdam and Hamburg port zones.
Buyer concentration among multinational food manufacturers is compressing procurement cycles and demanding outcome-based quality guarantees rather than commodity spot purchases. Large-scale restaurant chains and packaged-foods producers are replacing traditional broker relationships with direct mill partnerships backed by multi-year volume commitments. This pattern is most visible in Gujarat and Shandong provinces where crushing clusters align with port infrastructure and manufacturing demand density.
Ground-Nut Oil Market Segmentation
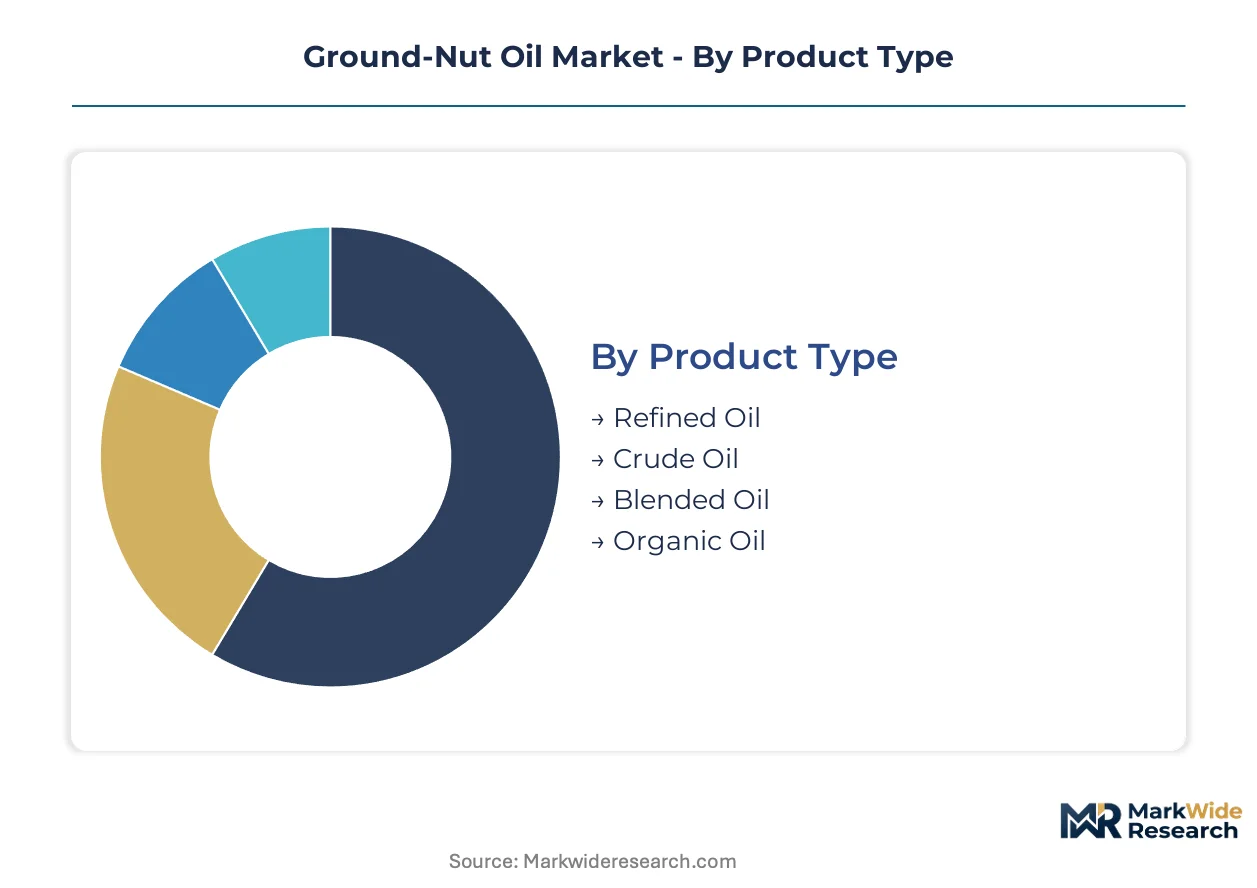
Ground-nut oil demand fragments across extraction grades, use intensities, and buyer procurement sophistication. Each segment carries distinct margin profiles and regulatory exposure that reshape competitive positioning.
Product Type:
Refined variants command food manufacturing channels where oxidative stability and extended fry-life justify premium positioning against commodity alternatives.
- Refined Oil:Deodorized and winterized grades achieve smoke points of 232°C, making them essential for high-temperature frying operations in quick-service restaurants and snack manufacturing. Gujarat and Shandong crushing clusters dominate supply, with FSSAI fortification mandates and China's GB standards compressing margins for non-compliant processors.
- Organic Oil:Cold-pressed extraction without chemical solvents satisfies EU Green Deal farm-to-fork traceability requirements. European buyers demand blockchain-verified documentation from West African origins, with Senegalese cooperatives capturing premium pricing for deforestation-free certification.
- Crude Oil:Unfiltered grades retain phospholipids and free fatty acids for industrial lubricant formulations and subsequent refinery feedstock.
- Blended Oil:Formulations combining ground-nut with palm or sunflower oils target price-sensitive household segments in South Asian markets.
The dominant share belongs to Refined Oil, while Organic Oil is closing the gap fastest.
Application:
Volume concentrates in frying and dressing uses, though policy-driven biofuel channels are restructuring offtake economics.
- Culinary:Household and restaurant frying, salad dressings, and traditional cooking across South Asia and West Africa. India's FSSAI vitamin A and D fortification mandates directly alter product formulation requirements for domestic manufacturers serving this segment.
- Biofuels:Refined high-oleic variants serve as renewable diesel feedstock where blend-rate mandates create structurally significant demand floors. Policy floors in transportation sectors are opening dedicated offtake channels separate from food-grade pricing volatility.
- Industrial:Lubricant formulations and metalworking fluids leverage ground-nut oil's viscosity stability and biodegradability.
- Cosmetics:Cold-pressed grades supply emollient bases for skincare formulations, with EFSA maximum residue limits governing European import eligibility.
Culinary applications retain volume leadership, though Biofuels demonstrate the steepest expansion trajectory.
End User:
Procurement sophistication divides buyers between specification-driven manufacturers and price-sensitive household purchasers.
- Food Manufacturers:Packaged snack and sauce producers demand outcome-based quality guarantees with multi-year volume commitments, bypassing traditional spot-market brokers. Direct mill partnerships in Gujarat and Shandong provinces are displacing intermediary relationships.
- Restaurants:High-volume frying operations seek bulk delivery contracts with specialized logistics, capturing margin currently absorbed by wholesale distributors.
- Households:Retail consumers in India, China, and Nigeria purchase smaller formats through supermarket and online channels, with palm oil price arbitrage displacing ground-nut oil in cost-sensitive segments.
- Personal Care Companies:Cosmetic formulators source cold-pressed organic grades for natural-product lines, with REACH chemical safety protocols mandating third-party laboratory certification for every European-bound shipment batch.
Food Manufacturers command the largest value pool, while Restaurants are gaining procurement sophistication fastest.
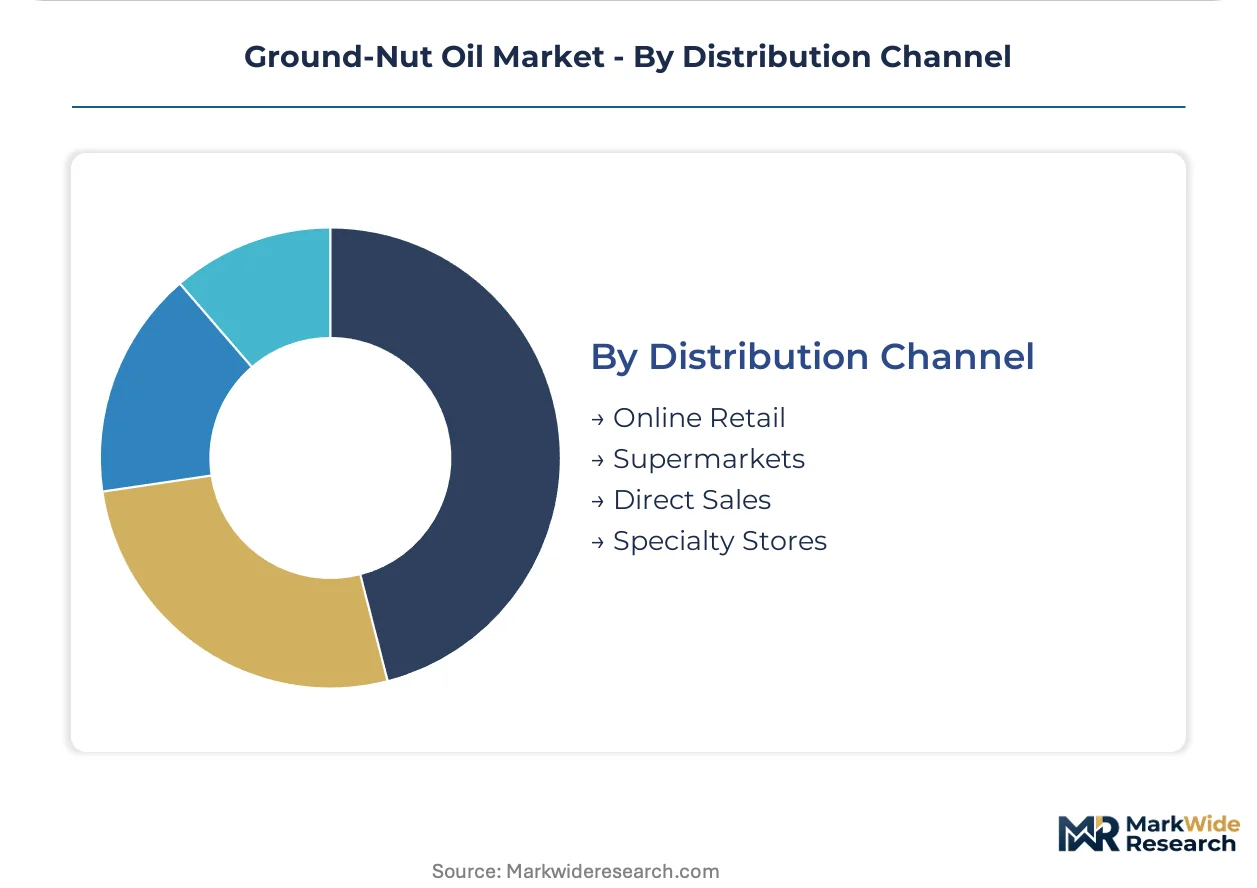
Distribution Channel:
Channel selection determines working capital intensity and traceability compliance burden.
- Direct Sales:Mill-to-manufacturer contracts eliminate intermediary margins and enable custom specification negotiation. This channel concentrates among integrated crushers with captive laboratory facilities in Rotterdam and Hamburg port zones.
- Supermarkets:Branded retail formats dominate household purchases in urban India and Chinese tier-one cities, with private-label expansion compressing branded margins.
- Online Retail:E-commerce platforms serve dispersed household demand and specialty organic buyers, with blockchain-integrated traceability platforms enabling premium pricing for verified supply chains.
- Specialty Stores:Natural-foods retailers and ethnic grocers cater to allergen-conscious and diaspora consumers, with FDA GRAS status for refined peanut oil shaping shelf-access conditions in US markets.
Direct Sales holds the dominant position, while Online Retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances vary sharply across origin markets, with crushing capacity expansion in West Africa reshaping Atlantic trade flows while Asian refiners absorb growing shares of South American feedstock. Currency volatility in Argentina and infrastructure bottlenecks in Senegal create divergent cost structures for international buyers.
India
Domestic consumption of ground-nut oil concentrates in Gujarat and Maharashtra where household frying traditions sustain volume demand. FSSAI mandates edible oil fortification with vitamins A and D, forcing reformulation across domestic manufacturers. Crushing clusters in Gujarat's Saurashtra region align with Mundra port infrastructure to serve both local refiners and export channels.
China
Shandong province anchors national refining capacity with integrated port-to-pantry logistics serving quick-service restaurant chains. GB standards for edible oil purity tighten quality benchmarks, compressing margins for non-compliant processors. Qingdao and Yantai crushing facilities capture economies of scale through continuous deodorization equipment investments.
United States
Food manufacturing demand centers on high-oleic variants for extended fry-life in snack production. FDA oversight of allergen labeling and GRAS status for refined peanut oil shapes market access conditions. Georgia and Alabama processing facilities serve southeastern peanut belt origins with dedicated allergen-segregation protocols.
Senegal
West African origination potential attracts project finance for crushing facility expansion near Dakar port zones. EU deforestation regulation due diligence obligations cascade through supply chains, demanding blockchain-verified documentation. Senegalese cooperatives capture premium pricing for organic certification meeting EU Green Deal farm-to-fork traceability requirements.
Brazil
Argentine peso volatility redirects some feedstock sourcing toward Brazilian peanut farming cooperatives in Minas Gerais. ANVISA pharmaceutical-grade oil standards open specialized export channels for refined variants. Crushing investments in São Paulo state leverage Santos port infrastructure for Atlantic basin distribution.
Ground-Nut Oil Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in origination and niche processing segments. The vendor base concentrates around capital-heavy operators with balance-sheet depth to finance African crushing facilities and European compliance infrastructure. Three archetypes dominate: integrated agribusiness conglomerates with multi-continent origination networks, regional refiners with captive port logistics, and organic-certified specialists serving premium European channels. Competitive moves center on backward integration into farming cooperatives and blockchain-integrated traceability platform deployment.
Within the integrated agribusiness tier, Cargill and Bunge Limited represent archetypes of feedstock security through origination network scale. Wilmar International Limited anchors Southeast Asian refining capacity with integrated logistics infrastructure. Among these, Cargill exemplifies the capital-heavy operator profile capable of project finance deployment across West African expansion opportunities.
| Leading Market Players |
|---|
| Cargill |
| Archer Daniels Midland Company |
| Wilmar International Limited |
| Bunge Limited |
| Olam International |
| COFCO Corporation |
| Gemini Edibles & Fats India Ltd |
| AAK AB |
| Marico Limited |
| Others |
Pricing and Supply Chain Analysis
Argentine peso volatility determines both pricing tier spreads and supply chain shape, forcing crushers without hedging infrastructure toward dollar-denominated forward contracts while compressing margin predictability across all grades. This currency instability feeds directly into three-tier pricing structure across premium, standard, and economy levels, with integrated operators capturing spread expansion through captive origination networks.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with food manufacturers demanding outcome-based quality guarantees backed by multi-year volume commitments. Price differentiation rests on certification level — EU organic and FSSAI fortification compliance — alongside volume scale. Cost compression in refined grades is intensifying because palm oil price arbitrage displaces ground-nut oil in price-sensitive institutional frying. Household purchasers in South Asian retail channels exhibit highest price sensitivity, while European organic buyers demonstrate lowest elasticity due to traceability requirements.
Supply Chain Analysis
Tariff exposure between Argentina and European Union markets dominates supply chain risk calculations for Atlantic basin crushers. Geographic supply concentrates in Argentina, Senegal, and India, with feedstock sourcing draws from Brazilian peanut farming cooperatives when peso instability peaks. Raw material dependencies center on high-oleic seed varieties, hexane solvent stocks for conventional extraction, and supercritical CO2 systems for premium grades. Distribution runs through integrated port-to-pantry logistics anchored in Rotterdam, Hamburg, and Shandong province crushing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ground-nut oil sits at an early-cycle expansion story where biofuel blend-rate mandates in transportation sectors create structurally significant offtake channels separate from food-grade volatility.
For Market Incumbents: Entrench feedstock security through backward integration into Senegalese and Brazilian farming cooperatives before project finance availability tightens. Deploy blockchain-integrated traceability platforms to capture EU Green Deal premium pricing. Expand crushing capacity in Gujarat and Shandong provinces where port infrastructure aligns with manufacturing demand density and FSSAI compliance infrastructure compresses non-compliant competitor margins. For New Entrants and Emerging Players: Mid-scale organic-certified crushing in West African origins represents the most penetrable entry point, with Senegalese cooperatives already capturing premium pricing for deforestation-free certification. Target direct-to-restaurant distribution channels bypassing wholesale intermediaries in high-volume frying operations. Pursue specialized bulk delivery contracts with outcome-based quality guarantees as the primary go-to-market angle. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors capital-heavy operators with balance-sheet depth to finance African crushing facilities and European compliance infrastructure. Long-term viability over the next decade hinges on origination network scale and captive laboratory certification capabilities. Watch EU deforestation regulation enforcement timelines as the critical inflection signal for working capital cycle compression among smaller traders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farming Cooperatives | Cargill and Bunge secure Argentine and Senegalese feedstock through origination network scale. |
| Blockchain-Integrated Traceability Platform Deployment | European buyers demand verified deforestation-free documentation from West African origins. |
| Supercritical CO2 Extraction Capacity Addition | Organic certification bodies exclude hexane-extracted oils from premium shelf placements. |
| Direct-to-Restaurant Distribution Channel Expansion | Specialized bulk delivery captures margin currently absorbed by wholesale intermediaries. |
| EU Compliance Infrastructure Investment | Rotterdam and Hamburg port zone laboratories enable mandatory third-party batch certification. |
Research Methodology
A standing panel of crushing facility operations managers, edible oil procurement leads at multinational food manufacturers, FSSAI compliance officers, and West African cooperative export coordinators provided ongoing calibration. Primary interviews combined with secondary validation from customs and trade data, FSSAI fortification mandate filings, EU deforestation regulation documentation, and SEC 10-K disclosures from listed agribusiness conglomerates. Bottom-up volume modeling across extraction grades and top-down macroeconomic anchoring were triangulated for convergence.
Scenario-bracketing framed analytical approach across the projection horizon, with segmentation dimensions spanning refined versus organic extraction grades, culinary versus biofuel application channels, and food manufacturer versus household end-user archetypes. CAGRs were derived from elasticity-adjusted demand curves incorporating policy-driven blend-rate mandates and palm oil substitution dynamics. Industry-specific inputs included FSSAI fortification compliance timelines and EU Green Deal traceability implementation phases.
Macroeconomic conditions sit as an overlay; deviation in Argentine peso volatility, West African port infrastructure investment cycles, or palm oil production cost trajectories would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and biofuel policy durability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Coconut Flour Market
Ingredients
Pepsin Market
Ingredients
Bran Market
Ingredients
North America Sodium Reduction Ingredients Market
Ingredients
Philippines Edible Oils & Fats Market
Ingredients
Arachidonic Acid Market
Ingredients
Arrowroot Starch Market
Ingredients
Cocoa Solids Market
Ingredients
Soy Lecithin Market
Ingredients
Cognitive Ingredients Market
Ingredients
United States Protein Market
Ingredients
South Africa Sodium Reduction Ingredients Market
Ingredients
Ben Oil Market
Ingredients
US Vegetable Oil Market
Ingredients
Botanical Extracts Market
Ingredients
Shortening Powder Market