
 Measuring Wheels Market | 2026-2036
Measuring Wheels Market Size, Share, and Industry Trends Forecast 2026-2036
Measuring Wheels Market Analysis
Equipment leasing and tool-rental subscription models are reshaping how small contractors access professional-grade measuring wheels, lowering capital barriers for precision layout work. Keson Industries leverages its North American distribution network to sustain brand visibility among independent contractors. Shinwa Rules Co., Ltd. anchors its position through specialized manufacturing scale in precision-machined mechanical wheels for Japanese surveyors. Condtrol GmbH differentiates via digital integration expertise targeting European building automation standards.
Measuring wheels are mechanical or electronic distance-measurement instruments consisting of a calibrated wheel, rotation counter, and display unit that translate ground contact into linear distance readouts for land surveying, construction layout, and recreational mapping. Standard wheels with molded polymer tires and mechanical click-counters dominate volume sales for basic construction layout, while digital wheels with LCD displays and memory functions capture premium margins among surveyors requiring data logging. Heavy-duty wheels with steel rims and sealed bearings lead replacement-cycle revenue in road maintenance and utility work across uneven terrain.
The Occupational Safety and Health Administration in the United States mandates accurate site documentation for trenching and excavation work, directly stimulating demand for certified measurement tools among construction professionals. The EU Machinery Directive and CE marking requirements enforce precision standards and safety testing for measuring equipment sold across European member states, creating compliance costs that favor established suppliers with in-house certification capabilities. Stakeholders must monitor how emerging digital calibration protocols and connected-tool ecosystems redefine product qualification thresholds and aftermarket service expectations.
Market Dynamics
Bluetooth-enabled digital readouts are compressing replacement cycles for mechanical-only wheels as construction firms prioritize connected tool ecosystems and cloud-synced measurement logs.
Growth Catalysts
- OSHA Trenching Mandates:United States excavation safety rules require certified distance documentation, compelling contractors to upgrade from uncalibrated pacing methods to traceable measuring instruments.
- Polymer Tire Advances:Glass-filled nylon wheel compounds now withstand 50% more abrasion cycles than conventional rubber, extending service intervals in road maintenance applications.
- German Infrastructure Budgets:Federal transport maintenance allocations sustain replacement demand for heavy-duty steel-rim wheels across municipal utility networks.
Market Restraints
- Steel Input Volatility:Fluctuating scrap metal costs compress margins for forged-rim manufacturers serving the road maintenance segment.
- Single-Source Encoder Supply:Precision optical rotation sensors concentrate among Taiwanese component houses, creating vulnerability for digital wheel assemblers.
- Smartphone LiDAR Substitution:Apple and Android spatial measurement applications capture casual surveying tasks previously requiring dedicated wheel tools.
Strategic Opportunities
- Indian Smart Cities Mission:Urban infrastructure digitization programs create first-time demand for certified measurement tools among municipal engineering departments.
- Building Information Modeling Integration:Wheels with native Autodesk Revit compatibility enable direct floor-plan imports, bypassing manual data entry for commercial contractors.
- EU Green Deal Procurement Rules:Public works tenders now favor repairable, modular designs over sealed disposable units, rewarding suppliers with spare parts networks.
Industry Challenges
- Calibration Technician Shortage:ISO 17025-accredited labs face 12-week backlogs for digital wheel certification, delaying customer deliveries.
- Legacy Mechanical Inventory Stranded:Distributors hold obsolete click-counter stock that cannot be retrofitted with Bluetooth modules, forcing write-downs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Measuring Wheels Market |
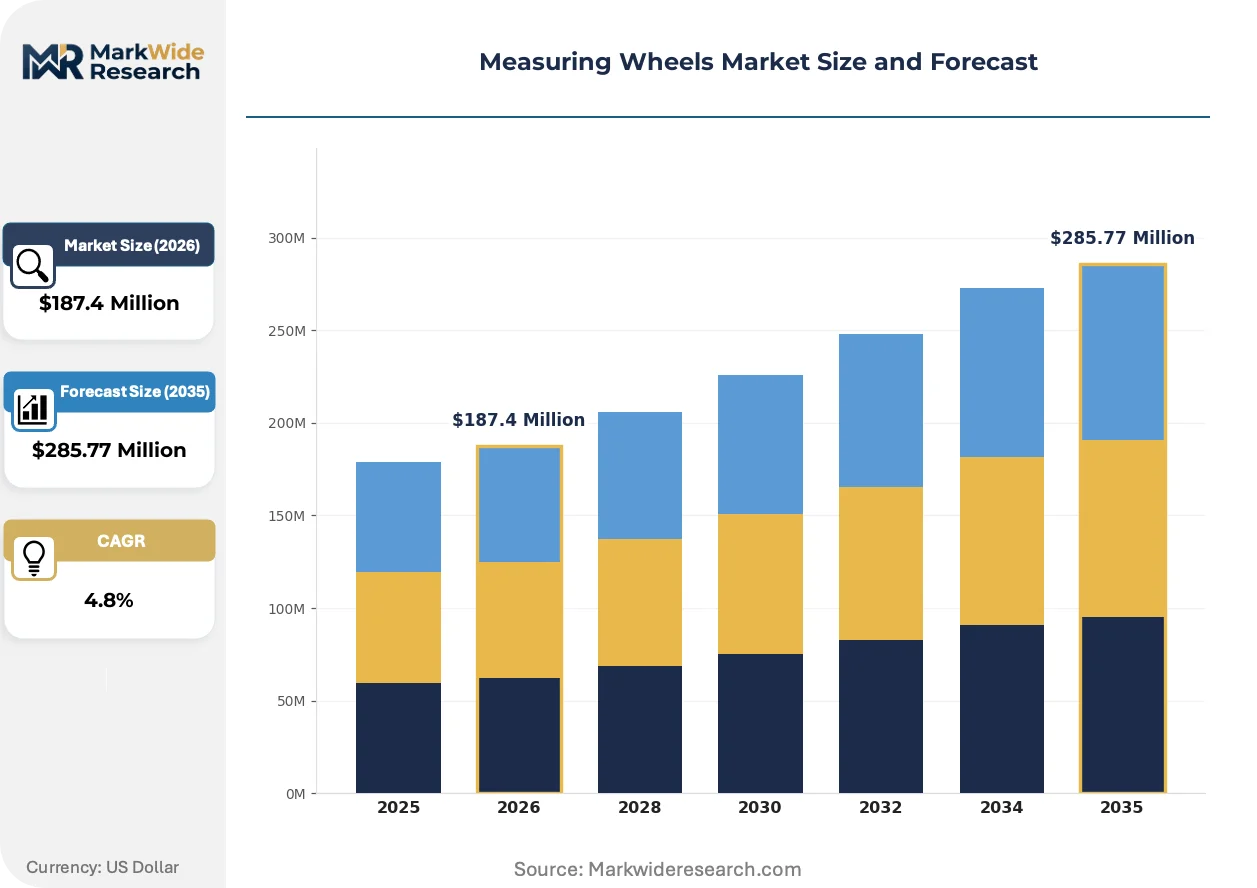
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Wheels, Digital Wheels, Mechanical Wheels, Heavy-Duty Wheels End User: Construction Professionals, Surveyors, Landscape Architects, Recreational Users Measurement Range: Up to 1000 Feet, 1000-3000 Feet, 3000-5000 Feet, Over 5000 Feet Terrain Type: Flat Surfaces, Uneven Terrain, Paved Roads, Grass and Dirt |
| Companies Covered | Trumbull Manufacturing, Condtrol GmbH, Nedo GmbH & Co. KG, Trison Global Company Ltd., Keson Industries, Shinwa Rules Co., Ltd., Line Seiki Co., Ltd., Komelon, CST/Berger, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Measuring Wheels Market Emerging Trajectories
Sensor miniaturization and wireless protocol standardization are converging to transform measuring wheels from passive mechanical tools into active data-collection nodes within construction technology stacks.
MEMS-based inertial measurement units integrated into wheel hubs now capture grade slope and surface texture alongside linear distance, rendering obsolete single-axis mechanical counters that cannot document terrain conditions. European survey firms are adopting these hybrid units for railway and pipeline surveys where elevation change documentation is mandatory. The added sensor payload is compressing price premiums for integrated versus basic wheels from 400% to 150% over three product generations.
Japan's METI has issued technical guidance requiring traceable calibration certificates for all measurement tools used in publicly funded civil engineering, tightening qualification thresholds that favor suppliers with in-house metrology labs. Domestic contractors must now maintain audit-ready documentation chains for boundary verification work. This regulatory friction is accelerating consolidation among smaller Japanese wheel distributors unable to fund certification infrastructure.
Rental platforms including United Rentals and Sunbelt have unbundled measuring wheels from general contractor tool packages, creating standalone subscription tiers with monthly calibration guarantees. Small residential builders in the United States are shifting from capital purchase to operating lease models for precision layout equipment. This channel transformation is eroding traditional distributor margins while expanding addressable volume among price-sensitive customer segments previously served by consumer-grade alternatives.
Measuring Wheels Market Segmentation
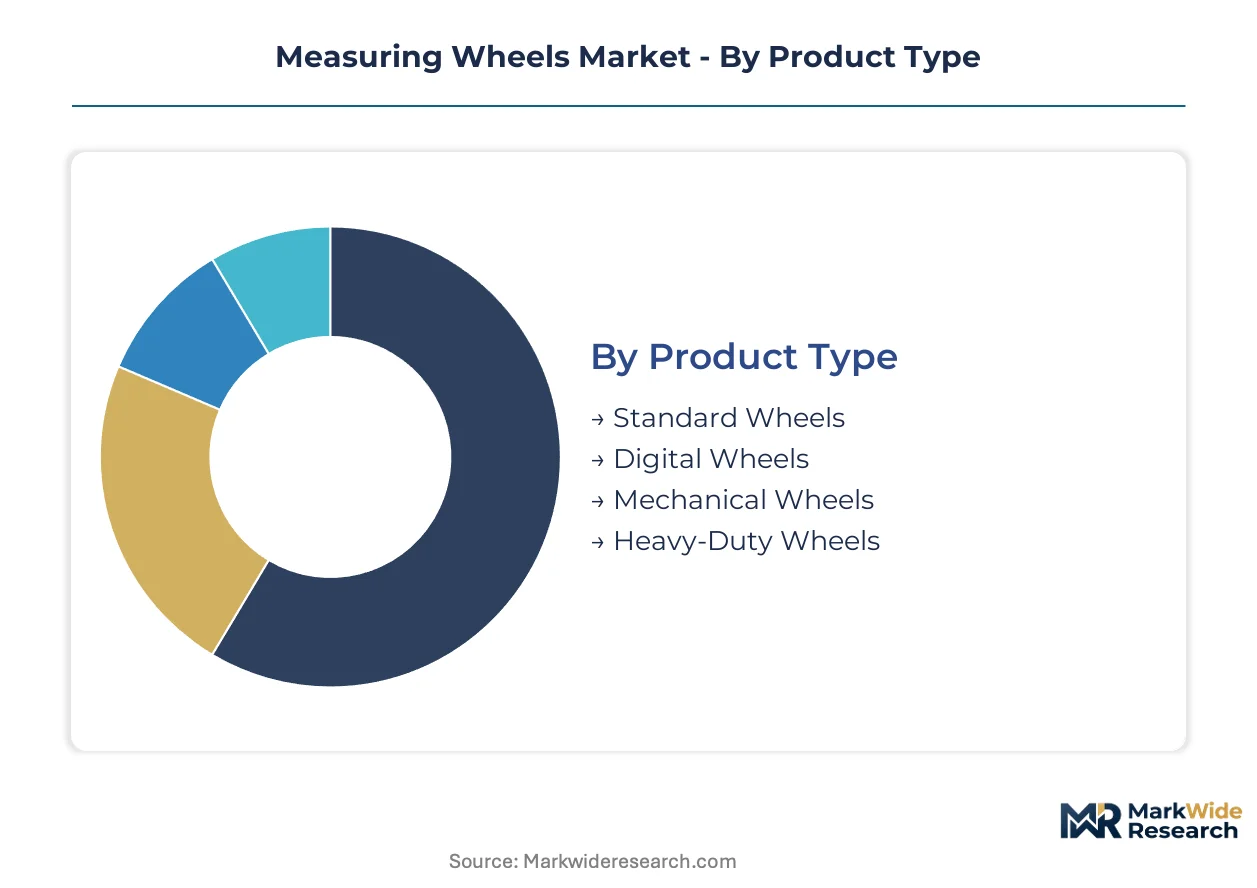
Measuring wheels serve distinct operational profiles across construction, surveying, and recreational applications, with product specifications and durability requirements varying sharply by end-use intensity. Segmentation reveals how calibration service dependencies and replacement cycle economics concentrate margin capture among specific customer categories.
Product Type:
After-sales service intensity varies dramatically across wheel categories, with digital units requiring firmware updates and ISO 17025 recalibration while mechanical designs need only bearing replacement.
- Standard Wheels:Molded polymer tires paired with mechanical click-counters deliver baseline distance measurement for residential construction layout. Demand concentrates among United States independent contractors performing foundation staking and fence line verification, driven by OSHA trenching documentation mandates that displace uncalibrated pacing methods.
- Digital Wheels:LCD displays with Bluetooth connectivity and cloud-synced memory functions capture premium positioning among surveyors requiring audit-ready measurement logs. German building automation contractors drive replacement demand as CE-marked precision standards tighten qualification thresholds for connected tool ecosystems.
- Mechanical Wheels:Precision-machined rotation counters without electronic components serve cost-sensitive municipal departments in Japan where METI calibration certificates remain voluntary for non-public funding.
- Heavy-Duty Wheels:Forged steel rims with sealed bearings withstand abrasive wear across railway maintenance and utility corridor surveys.
Standard wheels hold the largest share; momentum sits with digital wheels.
End User:
Cost tier stratification separates professional-grade procurement from consumer alternatives, with certification requirements and tool-rental access shaping purchasing authority.
- Construction Professionals:General contractors and excavation crews require traceable measurement documentation for regulatory compliance.
- Surveyors:Licensed practitioners demand sub-centimeter accuracy with temperature-compensated calibration chains for boundary disputes.
- Landscape Architects:Hardscape designers prioritize lightweight portability for garden layout and irrigation planning across residential projects.
- Recreational Users:Amateur mappers and hiking enthusiasts substitute smartphone LiDAR for dedicated wheels, compressing addressable volume.
Construction professionals dominate current procurement; surveyors command the steepest expansion trajectory as digital integration penetrates cadastral services.
Measurement Range:
Volume concentration aligns with municipal infrastructure scale, with mid-range specifications serving the majority of road maintenance and utility corridor applications.
- Up to 1000 Feet:Compact wheels for interior commercial layout and residential boundary marking.
- 1000-3000 Feet:Balanced capacity for municipal sidewalk replacement and parking lot resurfacing across German transport budgets.
- 3000-5000 Feet:Extended-range units for pipeline right-of-way verification and railway alignment surveys.
- Over 5000 Feet:Specialized drums for highway resurfacing contracts and airport runway measurement where cumulative error tolerance tightens.
1000-3000 Feet specifications anchor replacement demand; over 5000 Feet configurations gain share fastest among infrastructure megaprojects.
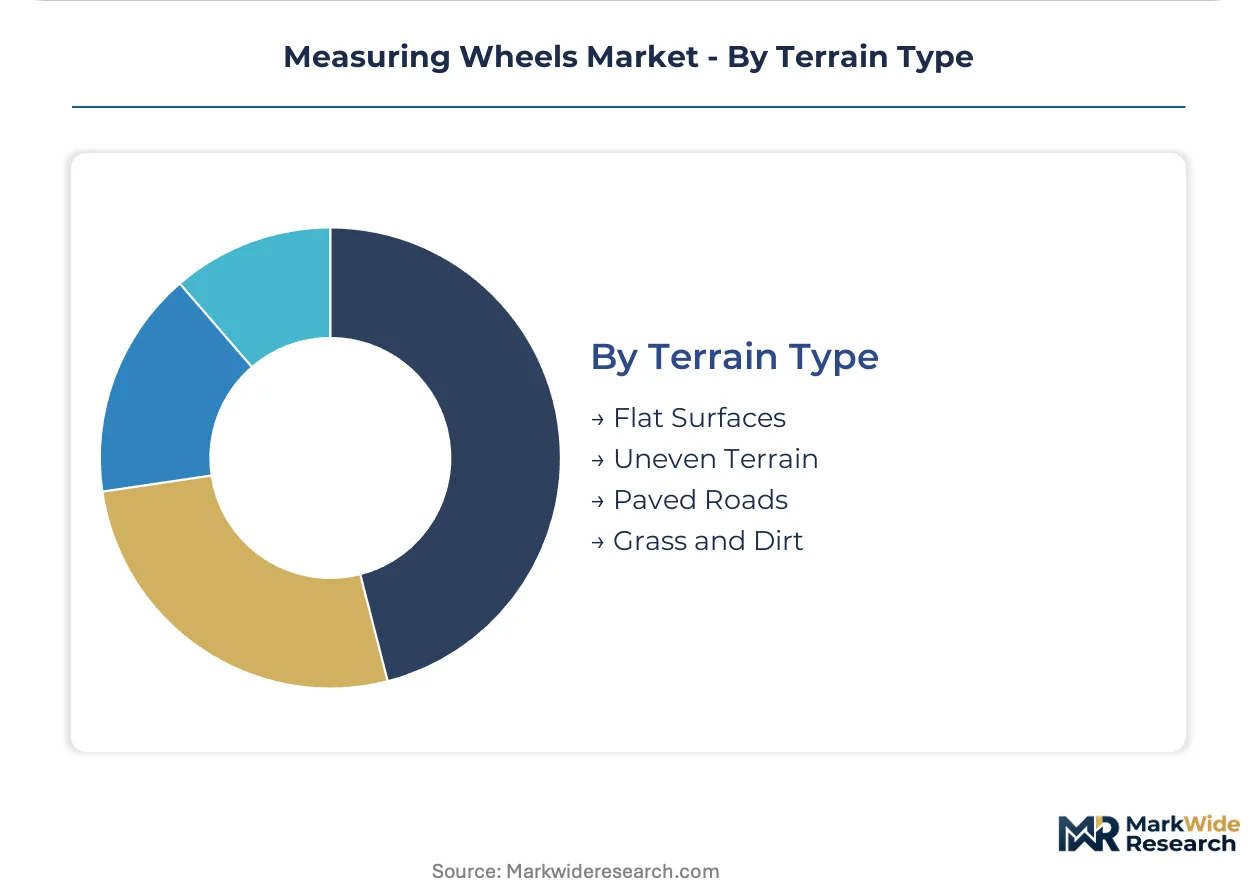
Terrain Type:
Application durability requirements dictate material selection, with wheel compounds and bearing seals engineered for specific surface abrasion profiles.
- Flat Surfaces:Polymer-tire designs for warehouse flooring and interior commercial measurement.
- Uneven Terrain:Articulated frames with pneumatic tires maintain ground contact across quarry access roads and construction sites.
- Paved Roads:Glass-filled nylon compounds resist thermal deformation and aggregate abrasion on asphalt surfaces.
- Grass and Dirt:Knurled steel rims penetrate vegetative cover for agricultural field mapping and golf course layout.
Paved roads applications hold the largest share; uneven terrain specifications are expanding most quickly as utility work intensifies in rural networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal infrastructure maintenance allocations across multiple jurisdictions are sustaining replacement demand for certified measurement tools. Municipal procurement standards increasingly mandate traceable calibration documentation for public works contracts. Equipment leasing platforms are expanding access to professional-grade wheels among small contractors previously priced out of capital purchase.
United States
OSHA trenching mandates compel excavation crews to abandon uncalibrated pacing methods for certified instruments. Federal highway resurfacing budgets under the Infrastructure Investment and Jobs Act sustain municipal fleet replacement cycles. Texas and Florida transportation departments anchor heavy-duty wheel procurement for road maintenance networks.
Germany
CE marking requirements under the EU Machinery Directive enforce precision standards that favor established suppliers with in-house certification capabilities. Federal transport maintenance allocations sustain demand for steel-rim wheels across municipal utility networks. Bavarian building automation contractors drive digital wheel adoption for connected tool ecosystems.
Japan
METI technical guidance mandates traceable calibration certificates for publicly funded civil engineering projects. Domestic contractors must maintain audit-ready documentation chains for boundary verification work. Osaka-based survey firms accelerate consolidation among distributors unable to fund certification infrastructure.
India
Smart Cities Mission urban infrastructure digitization programs create first-time demand for certified measurement tools among municipal engineering departments. Central Public Works Department procurement guidelines increasingly require ISO 17025 traceability for surveying equipment. Maharashtra and Karnataka state road development corporations anchor mid-range wheel deployment for highway expansion projects.
United Kingdom
Building Safety Regulator documentation requirements for high-rise construction impose measurement traceability standards on site layout work. NHS infrastructure maintenance budgets sustain replacement demand for precision instruments in hospital campus development. Greater London Authority procurement rules favor repairable modular designs over sealed disposable units.
Measuring Wheels Market Vendor Landscape
On the supply side, the industry is structured around three distinct capability tiers. Established European and Japanese manufacturers with metrology heritage occupy the premium digital segment. North American specialists with distribution scale dominate the contractor-facing standard wheel category. Asian fabricators with manufacturing cost advantages supply volume mechanical units for price-sensitive municipal procurement. Competitive positioning hinges on backward integration into precision encoder supply and captive calibration laboratory accreditation.
Within the premium digital tier, Condtrol GmbH exemplifies European integration expertise targeting building automation standards. Keson Industries anchors North American distribution visibility among independent contractors. Shinwa Rules Co., Ltd. occupies a position representing Japanese precision-machined manufacturing scale for domestic surveyors. These three archetypes illustrate how geographic specialization and certification infrastructure separate sustainable margin capture from commodity pressure.
| Leading Market Players |
|---|
| Trumbull Manufacturing |
| Condtrol GmbH |
| Nedo GmbH & Co. KG |
| Trison Global Company Ltd. |
| Keson Industries |
| Shinwa Rules Co., Ltd. |
| Line Seiki Co., Ltd. |
| Komelon |
| CST/Berger |
| Others |
Supply Flow & Price Mechanics
Single-source encoder concentration among Taiwanese component houses compresses pricing power for digital wheel assemblers while simultaneously dictating supply chain geography. This chokepoint widens spreads between premium digital units and mechanical alternatives as manufacturers pass through component scarcity premiums or absorb margins to defend market position.
Pricing Analysis
Certification level creates the primary spread across the measuring wheels market, with ISO 17025-accredited digital units commanding substantial premiums over non-certified mechanical designs. Three-tier pricing structure separates CE-marked precision instruments for European building automation from OSHA-compliant standard wheels for United States contractors and uncalibrated economy units for casual users. Pricing pressure stems from smartphone LiDAR substitution eroding recreational demand and forcing mid-tier suppliers toward bundled calibration service models. Construction professionals exhibit lowest price sensitivity due to regulatory documentation mandates, while municipal departments in cost-constrained jurisdictions drive hardest bargain negotiations.
Supply Chain Analysis
Tariff exposure between United States and Chinese steel inputs dominates supply chain risk calculations for forged-rim manufacturers serving road maintenance segments. Component sourcing concentrates in Taiwan for precision optical encoders, Germany for sealed bearing assemblies, and China for glass-filled nylon tire compounds. Raw material dependencies rest on scrap steel pricing volatility, polymer resin availability, and semiconductor wafer supply for MEMS sensor integration. Distribution runs through North American equipment rental platforms, European specialized distributor networks, and Japanese direct-to-surveyor channels anchored by domestic precision manufacturing heritage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bluetooth connectivity standardization and cloud-synced measurement logs are transforming measuring wheels from isolated tools into nodes within connected construction platforms, creating winner-take-most dynamics around ecosystem integration.
For Market Incumbents: Pre-empt smartphone LiDAR encroachment by embedding wheels within Autodesk Revit-compatible workflows and securing exclusive calibration service contracts with municipal procurement departments. Accelerate backward integration into encoder supply through strategic partnerships with Taiwanese component houses to neutralize single-source vulnerability. Lock in distributor loyalty via firmware update subscription models that strand competitor mechanical inventory. For New Entrants and Emerging Players: Build out calibration-as-a-service infrastructure targeting Indian Smart Cities Mission municipal engineering departments lacking ISO 17025 accreditation capabilities. Exploit white space in repairable modular designs favored by EU Green Deal procurement rules, positioning against sealed disposable units from established suppliers. Pursue direct digital-native go-to-market through equipment rental platform partnerships rather than traditional distributor channels. For Investors and Strategic Acquirers: Japan METI calibration mandate reshapes the acquisition landscape by rendering uncertified distributors unviable and consolidating value into metrology-lab-equipped manufacturers. Long-term viability hinges on captive certification infrastructure rather than assembly scale alone. Target acquisition archetype: mid-cap specialists with in-house ISO 17025 labs and existing relationships with public works procurement officers. Signal to monitor: backlog duration at accredited calibration facilities as indicator of pricing power inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Encoder Supply | Captive sourcing from Taiwanese optical sensor manufacturers neutralizes single-source vulnerability for digital wheel assemblers. |
| Calibration Service Subscription Launch | Recurring revenue models lock municipal customers through ISO 17025 documentation compliance requirements. |
| Building Information Modeling Integration | Native Autodesk Revit compatibility bypasses manual data entry for commercial contractors and displaces smartphone LiDAR alternatives. |
| Modular Repairable Design Transition | Spare parts networks satisfy EU Green Deal procurement preferences and extend replacement cycle capture. |
| Equipment Rental Platform Partnership | United Rentals and Sunbelt channel access erodes traditional distributor margins while expanding addressable volume among price-sensitive builders. |
Methodological Framework
A spread of perspectives from construction site supervisors, municipal procurement officers, calibration laboratory technicians, and equipment rental platform managers converged on the working assumptions underlying this analysis. Primary field engagement combined structured interviews with aftermarket service heads and OEM procurement teams at wheel manufacturers across Germany, Japan, and the United States. Secondary validation drew from OSHA regulatory filings, EU Machinery Directive implementation guidance, METI technical standards documentation, and customs trade data for polymer and steel inputs. Bottom-up unit economics triangulated against top-down infrastructure budget allocations across federal transport departments.
Demand-supply balance modeling anchored projections across the analysis window, with segmentation by product type, end user intensity, measurement range specification, and terrain application driving volume disaggregation. CAGRs derived from replacement cycle analysis calibrated to polymer tire abrasion testing data and steel-rim wear rates in road maintenance deployments. Forecast inputs incorporated federal highway resurfacing budget trajectories, Smart Cities Mission implementation pace, and rental platform penetration rates among residential builders.
Stress conditions across scrap steel price volatility, encoder supply disruption scenarios, and smartphone LiDAR accuracy improvements were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and infrastructure maintenance budget continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Nail Gun Market
Tools
Pruning Saw Market
Tools
Level Floats Market
Tools
Stationary Wood Planer Market
Tools
Allen Key Market
Tools
Floor Pads Market
Tools
Stand Tile Saw Market
Tools
Industrial Ladder Market
Tools
End Milling Machine Market
Tools
Bottle Jack Market
Tools
Power Tool Gears Market
Tools
Global Vertical Grinding Machine Market
Tools
Quick Release Pins Market
Tools
Land Survey Equipment Market
Tools
Cutting Equipment, Accessories and Consumables Market
Tools
Woodworking Power Tools Market