
 Allen Key Market | 2026-2036
Allen Key Market Size, Share, and Industry Trends Forecast 2026-2036
Allen Key Market Outlook
Precision torque calibration is tilting assembly protocols toward tighter hex-drive tolerances in automotive and electronics sectors. DeWalt leverages its cordless power tool ecosystem to bundle calibrated Allen key sets for professional installers. Wera sustains premium positioning through laser-etched size markings and ergonomic handle designs that reduce repetitive strain injuries. Bondhus anchors the North American market with domestic manufacturing of long-life hex keys using proprietary ProGuard corrosion-resistant finishes.
An Allen key is a handheld L-shaped or T-shaped tool with a hexagonal cross-section tip designed to drive bolts and screws with hexagonal sockets, typically manufactured from chrome vanadium steel hardened to 52-58 HRC for durability under torque load. Ball end variants permit angled insertion up to 25 degrees from perpendicular, enabling access in confined machinery compartments where straight-shaft tools cannot engage. Chrome vanadium material commands the widest industrial adoption due to its strength-to-cost ratio, while stainless steel variants capture medical equipment and food processing maintenance segments where corrosion resistance overrides raw material expense. T-handle configurations dominate automotive workshop environments where technicians apply sustained torque for suspension and powertrain fasteners.
FDA equipment validation requirements for medical device assembly influence stainless steel tool specifications in regulated manufacturing environments. OSHA ergonomic standards in the United States and REACH chemical restrictions in Europe jointly pressure suppliers to eliminate hexavalent chromium plating processes and redesign handles for reduced musculoskeletal stress. ISO 6789 torque tool calibration standards create compliance barriers for unaccredited manufacturers seeking entry into aerospace and precision assembly supply chains. Stakeholders must monitor evolving dual carbon goals in China and the EU Green Deal's embodied carbon tracking, as these frameworks will eventually extend to the steel forging and surface treatment stages of hand tool production.
Market Dynamics
Electric vehicle battery pack assembly lines in Germany are expanding procurement of precision torque tools, tightening hex-drive tolerances across automotive and electronics supply chains while REACH chemical compliance reshapes material specifications for chrome vanadium coatings.
Growth Catalysts
- EV battery manufacturing scale-up:Precision torque calibration requirements in automotive assembly are pulling hex key specifications toward tighter dimensional tolerances and certified calibration protocols.
- REACH chemical compliance:Tightening restrictions on hexavalent chromium plating across European supply chains are forcing material specification upgrades that favor premium chrome vanadium grades with alternative surface treatments.
- Guangdong electronics automation:Contract manufacturers in China's Guangdong province are scaling automated assembly operations that demand calibrated tool sets with traceable dimensional certification.
Market Restraints
- Chrome vanadium price volatility:Alloy steel input costs fluctuate with ferrovanadium and chromium ore supply disruptions from South African and Kazakh mining concentration.
- Ball end manufacturing concentration:Precision grinding capacity for 25-degree angled ball ends concentrates in Japanese and German specialized tool shops, creating supply bottlenecks during demand surges.
- Hexalobular drive substitution:Torx and other star-drive fastener systems are displacing hex socket designs in high-vibration applications across aerospace and heavy machinery.
Strategic Opportunities
- Medical device stainless steel penetration:FDA equipment validation requirements for surgical instrument assembly are opening specification windows for corrosion-resistant stainless steel variants in regulated cleanroom environments.
- Ergonomic handle redesign:OSHA musculoskeletal stress guidelines are creating procurement preference for T-handle and cushioned-grip configurations that reduce repetitive strain injuries in high-volume assembly.
- Carbon tracking integration:EU Green Deal embodied carbon frameworks will eventually extend to steel forging and surface treatment stages, rewarding suppliers with verified low-carbon production documentation.
Industry Challenges
- ISO 6789 calibration accreditation:Torque tool calibration standards create compliance barriers for unaccredited manufacturers seeking entry into aerospace and precision assembly supply chains.
- Dual carbon goal alignment:China's national carbon intensity targets are pressuring domestic forging operations to reconfigure energy-intensive heat treatment processes without compromising 52-58 HRC hardness specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Allen Key Market |
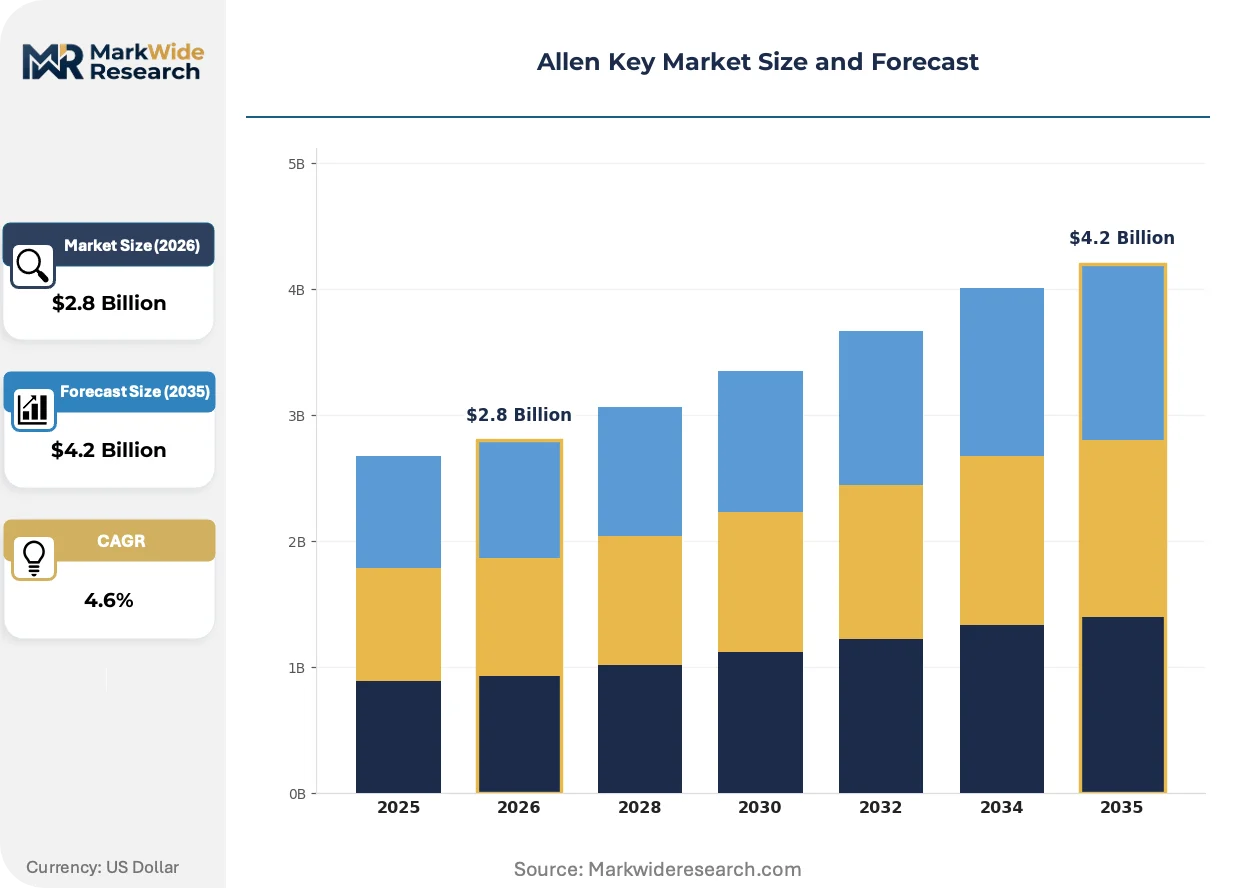
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Allen Keys, Ball End Allen Keys, T-Handle Allen Keys, Torque Allen Keys Material: Steel, Stainless Steel, Chrome Vanadium, Plastic End User: Automotive, Furniture Manufacturing, Electronics Assembly, General Maintenance Distribution Channel: Online Retail, Hardware Stores, Wholesale, Direct Sales |
| Companies Covered | Sunex Tools, DeWalt, Wera, Wiha, Stahlwille, Stanley, Powerbuilt, Snap-on, Bondhus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Allen Key Market Strategic Shifts
Tool specification convergence is compressing the gap between manual hand tools and digitally traceable assembly systems, with calibration protocols and ergonomic mandates reshaping product development priorities across industrial buyer segments.
Smart torque measurement is hybridizing traditional hex key functionality with embedded strain gauge sensors and Bluetooth connectivity. Automotive OEMs in Germany and battery manufacturers in South Korea are piloting these connected tools for real-time assembly data capture. This convergence is hybridizing quality assurance workflows, compressing the distinction between hand tools and precision measurement instruments while generating digital thread documentation for warranty traceability.
REACH chemical restrictions are eliminating hexavalent chromium plating processes across European supply chains, forcing suppliers to adopt trivalent chromium or ProGuard-style organic corrosion-resistant finishes. The industrial consequence is a material cost uplift of 15-25% for compliant surface treatments. Medical device and food processing maintenance segments are responding fastest, specifying stainless steel variants that bypass plating requirements entirely.
Certification-driven procurement is consolidating buyer preference around ISO 6789-accredited suppliers with documented calibration traceability. Industrial distributors in North America are unbundling traditional kit sales into calibrated tool-as-a-service programs with periodic recertification. This pattern is most visible in aerospace MRO operations and medical device contract manufacturing, where FDA and EMA validation requirements mandate documented tool calibration histories.
Allen Key Market Segmentation
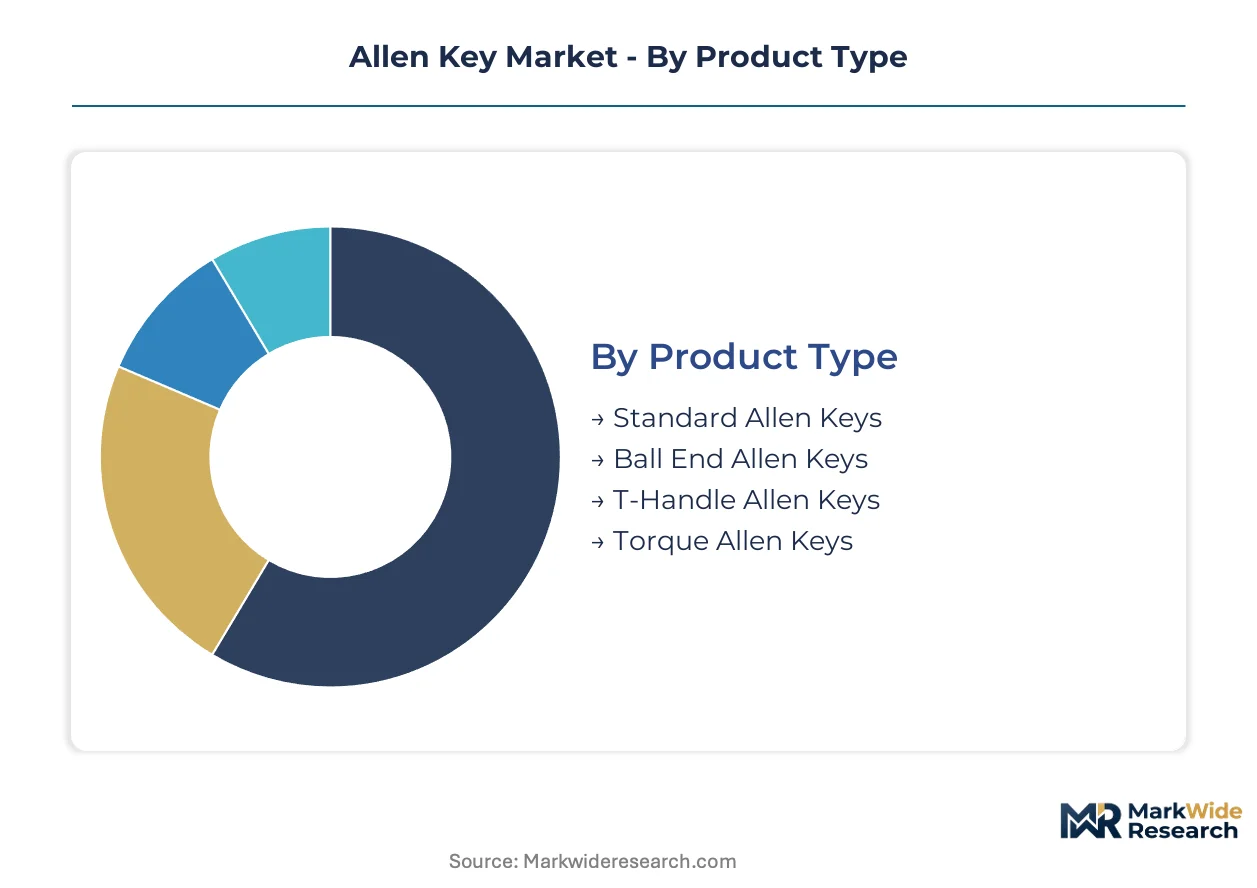
Segmentation in the Allen Key Market reveals how tool specification, material grade, and procurement channel determine margin capture and service intensity. Each dimension carries distinct aftermarket requirements that reshape supplier economics.
Product Type:
After-sales service intensity varies sharply across product configurations, with calibrated torque variants demanding recertification programs while standard hex keys operate as disposable consumables.
- Standard Allen Keys:L-shaped hexagonal tools with straight shafts dominate volume procurement in general maintenance and construction. Demand concentrates in China's Guangdong province electronics clusters where contract manufacturers treat these as high-turnover consumables in automated assembly lines.
- Ball End Allen Keys:Precision-ground spherical tips permit 25-degree angled insertion for confined machinery access. German automotive OEMs and South Korean battery manufacturers drive specification tightening as EV battery pack assembly lines expand procurement of tools accessing obstructed fasteners.
- T-Handle Allen Keys:Transverse grip configurations enable sustained torque application in automotive workshop environments. OSHA ergonomic standards in the United States elevate procurement preference for cushioned-grip variants reducing repetitive strain injuries.
- Torque Allen Keys:Factory-calibrated instruments with preset torque limiting for critical fastener applications. ISO 6789 accreditation requirements create compliance barriers for unaccredited suppliers seeking entry into aerospace and medical device supply chains.
Standard Allen Keys hold the largest share; momentum sits with Torque Allen Keys as traceable calibration becomes mandatory in regulated manufacturing.
Material:
Raw material selection determines corrosion resistance, hardness retention, and regulatory compliance cost across end-use environments.
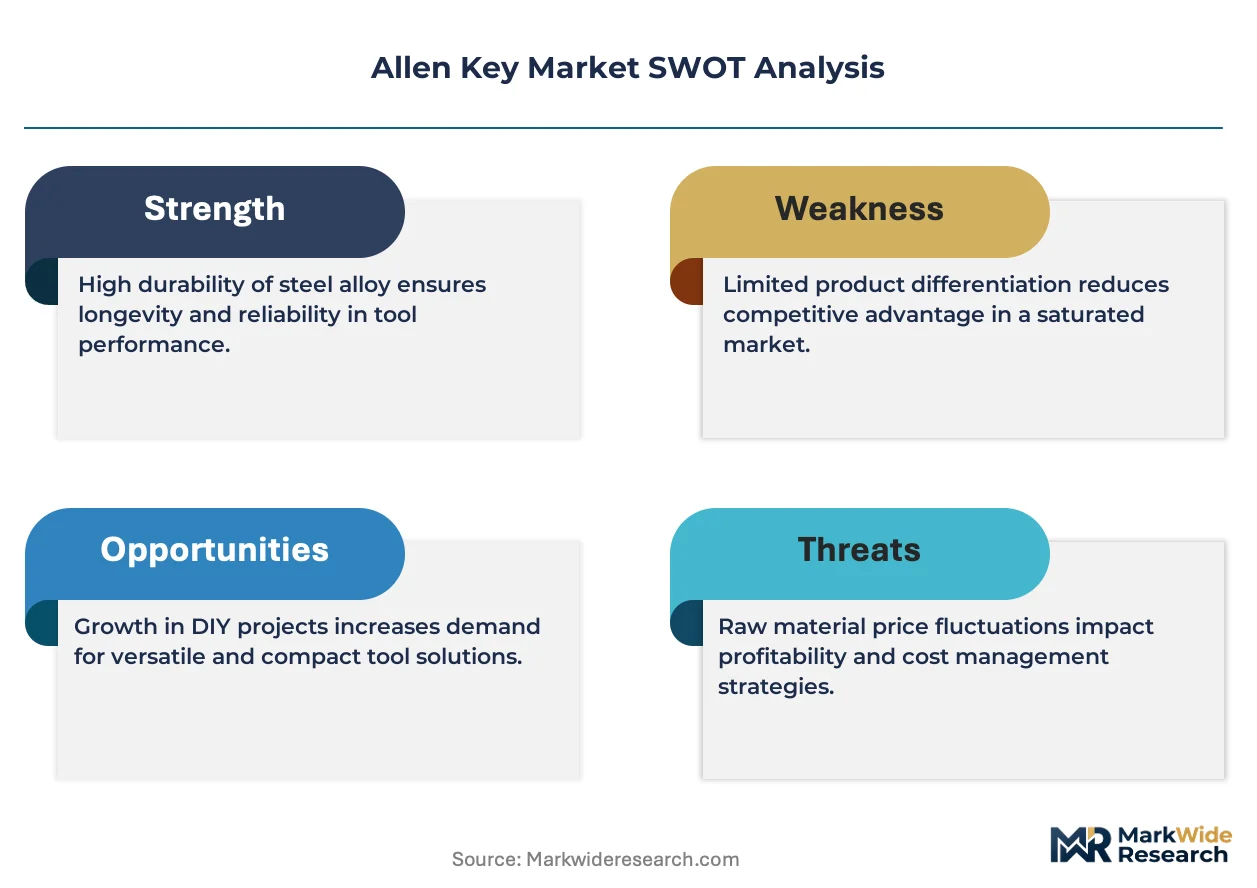
- Steel:Carbon steel variants serve price-sensitive general maintenance segments with basic hardness specifications. REACH chemical compliance in Europe is eliminating hexavalent chromium plating, forcing suppliers toward alternative surface treatments with 15-25% cost uplift.
- Stainless Steel:Austenitic grades deliver corrosion resistance for medical equipment and food processing maintenance where FDA equipment validation requirements override raw material expense. Surgical instrument assembly in regulated cleanrooms specifies these variants exclusively.
- Chrome Vanadium:Alloy steel combining chromium and vanadium achieves 52-58 HRC hardness with optimal strength-to-cost ratio. Ferrovanadium and chromium ore supply disruptions from South African and Kazakh mining concentration generate input cost volatility.
- Plastic:Glass-reinforced polymer tools serve electrical insulation applications and controlled-torque consumer assembly where metal conductivity poses hazard.
Chrome Vanadium holds the largest share; Stainless Steel is climbing the fastest as medical device manufacturing scales in regulated environments.
End User:
Application-specific torque calibration and dimensional tolerance requirements fragment procurement specifications across industrial buyer segments.
- Automotive:EV battery manufacturing scale-up in Germany pulls hex key specifications toward tighter tolerances and certified calibration protocols. T-handle configurations dominate suspension and powertrain fastener applications.
- Furniture Manufacturing:Flat-pack assembly operations in Southeast Asia drive high-volume procurement of standard L-key sets with minimal specification overhead.
- Electronics Assembly:Guangdong contract manufacturers scaling automated operations demand calibrated tool sets with traceable dimensional certification. Ball end variants access densely packed PCB enclosures.
- General Maintenance:Distributed repair and facility management operations prioritize availability and price over precision specifications.
Automotive holds the largest share; Electronics Assembly is gaining share fastest as automation density increases in Asian contract manufacturing.
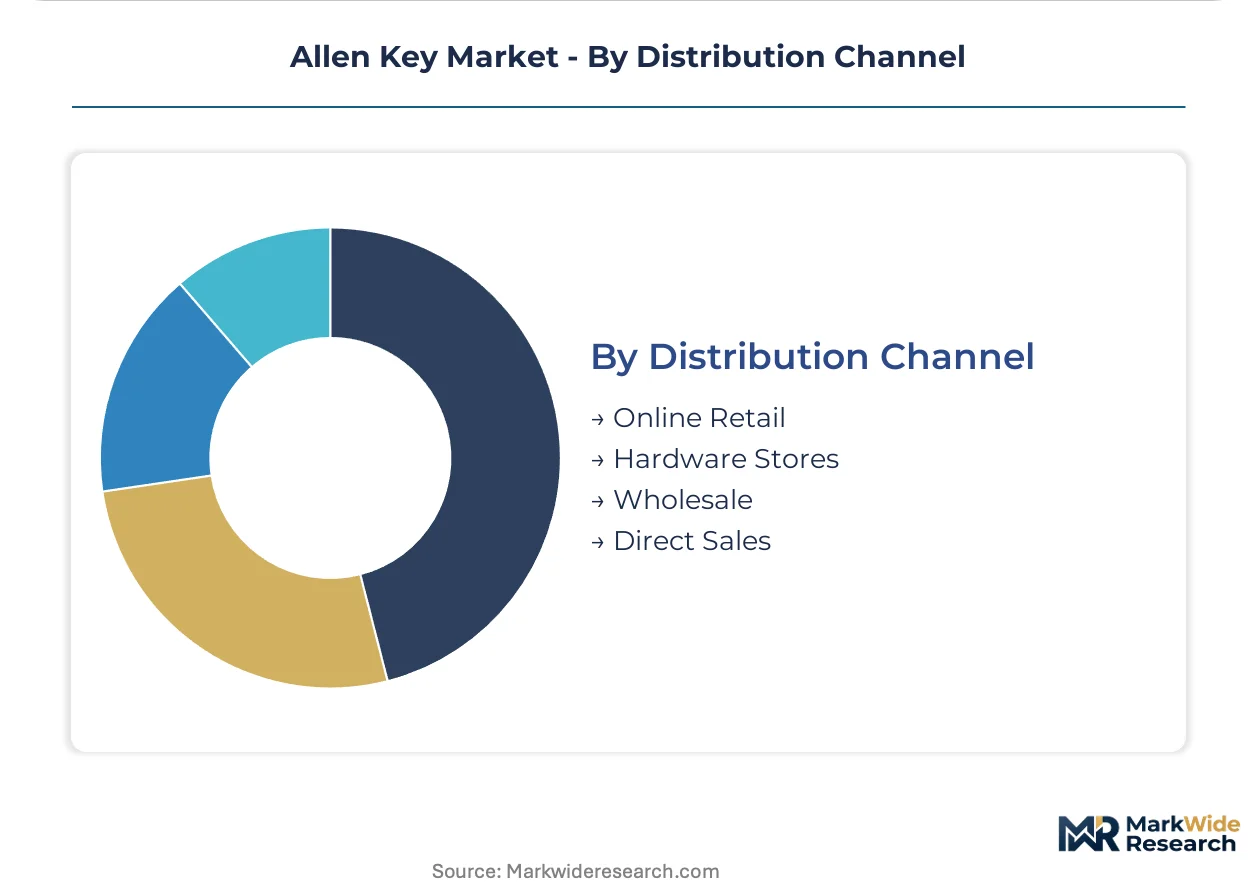
Distribution Channel:
Channel selection determines customer touchpoint economics and calibration service attachment rates.
- Online Retail:E-commerce platforms capture consumer and light industrial procurement with minimal service overlay. Product content focuses on size range and material claims rather than calibration documentation.
- Hardware Stores:Brick-and-mortar networks provide immediate availability for maintenance technicians and small contractors. Staff expertise varies in torque tool specification guidance.
- Wholesale:Industrial distributors unbundle traditional kit sales into calibrated tool-as-a-service programs with periodic recertification. This pattern concentrates in aerospace MRO and medical device contract manufacturing.
- Direct Sales:Manufacturer field engineers engage automotive OEMs and battery producers for specification development and calibration protocol integration.
Hardware Stores hold the largest share; Wholesale is expanding most quickly as industrial distributors build service-attachment revenue models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision tool exports supply automotive assembly lines across South Korea and China, while raw chrome vanadium feedstock flows from Kazakh mining operations into European forging facilities.
United States
OSHA ergonomic standards elevate procurement preference for cushioned-grip T-handle configurations in automotive workshops. FDA equipment validation requirements drive stainless steel specifications for surgical instrument assembly. Industrial distributors in the Midwest unbundle kit sales into calibrated tool-as-a-service programs.
Germany
EV battery manufacturing scale-up tightens hex-drive tolerances across automotive supply chains. REACH chemical restrictions eliminate hexavalent chromium plating, forcing 15-25% cost uplift for compliant surface treatments. Stuttgart and Wolfsburg clusters anchor precision torque tool specification development.
China
Dual carbon goals pressure domestic forging operations to reconfigure heat treatment processes without compromising 52-58 HRC hardness. MIIT industrial standards accelerate automation density in Guangdong electronics contract manufacturing. Shenzhen and Dongguan clusters demand calibrated tool sets with traceable dimensional certification.
South Korea
Battery manufacturers pilot smart torque measurement tools with embedded strain gauge sensors for real-time assembly data capture. MFDS medical device regulations align with FDA validation requirements for cleanroom tool specifications. Gyeonggi-do province concentrates precision grinding capacity for automotive OEM supply.
Japan
METI industrial policy supports precision grinding capacity for 25-degree ball end manufacturing that concentrates in specialized tool shops. JIS standards create technical barriers for unaccredited foreign suppliers. Nagoya and Osaka industrial zones maintain captive supply relationships with domestic forging operations.
Allen Key Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base organizes around three strategic archetypes: premium European precision specialists, North American ergonomic-focused manufacturers, and Asian volume producers serving contract manufacturing. Dominant competitive moves include ISO 6789 calibration accreditation investments and REACH-compliant surface treatment upgrades.
Among premium-tier specialists, Wera and Wiha exemplify European precision positioning through laser-etched markings and ergonomic handle engineering. DeWalt anchors the cordless power tool ecosystem bundling strategy, leveraging battery platform compatibility to attach calibrated Allen key sets for professional installers. Bondhus occupies a position within North American domestic manufacturing, representing the long-life hex key archetype with proprietary corrosion-resistant finishes.
| Leading Market Players |
|---|
| Sunex Tools |
| DeWalt |
| Wera |
| Wiha |
| Stahlwille |
| Stanley |
| Powerbuilt |
| Snap-on |
| Bondhus |
| Others |
Value Chain & Pricing Dynamics
Ferrovanadium and chromium ore mining concentration in South Africa and Kazakhstan feeds directly into margin capture at the precision grinding tier, where Japanese and German specialized tool shops command premium positioning for ball end manufacturing. This upstream chokepoint forces downstream buyers into long-term offtake arrangements or captive sourcing investments to secure dimensional certification capacity.
Pricing Analysis
Current-generation ISO 6789-accredited torque tools command substantial premiums over prior-generation standard hex keys, while next-generation smart torque measurement tools with embedded strain gauge sensors are piloting at experimental price points. Three-tier pricing structure across premium, standard, and economy levels separates calibration-certified instruments from basic maintenance-grade tools and disposable consumables for high-turnover assembly lines. Price differentiation rests on certification grade and after-sales service bundling, with wholesale distributors unbundling kit sales into recertification programs. Cost compression in the standard L-key segment is intensifying because Guangdong contract manufacturers treat these as consumables in automated operations. General maintenance technicians exhibit highest price sensitivity, while aerospace MRO and medical device contract manufacturing show lowest sensitivity due to FDA and EMA validation mandates.
Supply Chain Analysis
Precision grinding capacity for 25-degree ball ends concentrates in Japanese and German specialized tool shops, with secondary forging operations anchored in China and Taiwan. Raw material flows draw from South African ferrovanadium, Kazakh chromium ore, and domestic alloy steel feedstock in manufacturing hubs. Single-source vulnerability permeates the ball end grinding tier, where capacity constraints during demand surges create procurement bottlenecks for automotive and battery manufacturers. Distribution runs through industrial distributors building service-attachment revenue models, hardware store networks for immediate availability, and direct sales channels for OEM specification development.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
DeWalt's cordless power tool ecosystem bundling strategy illustrates platform economics at work, where battery platform interoperability creates switching costs that attach calibrated Allen key sets to professional installer workflows. This interoperability inflection rewards suppliers who integrate with dominant tool platforms while penalizing standalone specialists.
For Market Incumbents: Insulate calibration accreditation moats by accelerating ISO 6789 investment ahead of unaccredited competitors seeking aerospace and medical device entry. Secure captive supply of precision grinding capacity through backward integration into Japanese or German ball end manufacturing, or through exclusive offtake agreements with specialized tool shops. Hexalobular drive substitution in high-vibration aerospace applications represents the priority threat requiring defensive R&D into hybrid drive compatibility. For New Entrants and Emerging Players: Build out stainless steel variant production for medical device and food processing maintenance segments where FDA equipment validation requirements override raw material expense and create specification windows for new suppliers. Target the South Korean battery manufacturer ecosystem, where MFDS alignment with FDA standards and pilot demand for smart torque measurement tools creates white-space for connected instrument entrants. Pursue direct sales engagement with Gyeonggi-do province precision grinding clusters for specification co-development. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across smart torque measurement and embedded sensor integration, favoring scaled players with R&D absorption capacity over fragmented manual tool specialists. Long-term viability over the coming decade hinges on digital thread documentation capabilities and calibration-as-a-service revenue models. Acquisition targets should display ISO 6789 accreditation, REACH-compliant surface treatment infrastructure, and established automotive OEM relationships. The signal to watch is wholesale distributor consolidation around tool-as-a-service programs, which will concentrate procurement gatekeeper power and reshape supplier economics.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 6789 Calibration Accreditation Investment | Creates compliance barriers for unaccredited suppliers seeking aerospace and medical device supply chain entry. |
| REACH-Compliant Surface Treatment Upgrade | Eliminates hexavalent chromium plating costs while capturing European automotive and electronics procurement preference. |
| Smart Torque Measurement Platform Development | Hybridizes traditional hex keys with Bluetooth connectivity for real-time assembly data capture in German automotive OEMs. |
| Stainless Steel Medical Grade Capacity Expansion | Captures FDA-validated surgical instrument assembly demand in regulated cleanroom environments. |
| Wholesale Distribution Service Integration | Attaches recertification revenue to calibrated tool sales through industrial distributor partnerships. |
Study Parameters
Cross-validation between primary field engagement and secondary source triangulation anchors the qualitative findings in this analysis. Plant engineers at German automotive OEMs, procurement leads at Guangdong electronics contract manufacturers, aftermarket service heads at North American industrial distributors, and calibration laboratory directors provided operational perspective. These interviews were validated against customs and trade data for ferrovanadium and chromium ore flows, SEC filings from listed tool manufacturers, ISO accreditation registries, and REACH compliance documentation from ECHA. Bottom-up segment sizing and top-down macroeconomic calibration were reconciled through iterative refinement.
Calibration against historical volume trajectories and elasticity-adjusted demand curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product configuration, material grade, end-use industry, and distribution channel complexity. CAGRs were derived from regression-adjusted growth rate convergence across these segments. Industry-specific forecast inputs incorporated EV battery manufacturing capacity buildout schedules and MIIT automation density targets for Guangdong electronics clusters.
Stress conditions across ferrovanadium supply disruptions, REACH regulatory tightening timelines, and hexalobular drive substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding calibration mandate expansion and carbon intensity regulation progression. Quarterly review of ISO 6789 accreditation expansion rates and wholesale distributor service-attachment revenue ratios is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Key Cutting Machine Market
Tools
Tooling Market
Tools
Woodworking Tools Market
Tools
Global Vertical Grinding Machine Market
Tools
Electric Power Tools Market
Tools
Sander Market
Tools
Cordless Multi Rotary Tools Market
Tools
Garden Digging Tools Market
Tools
Global Tool Holder Adapters Market
Tools
Woodpecker Tools Market
Tools
Hand Tools and Woodworking Tools Market
Tools
Drill Bit Market
Tools
Diamond Hole Saw Market
Tools
Grinding Machines Market
Tools
Cordless Blind Rivet Gun Market
Tools
Turning Centers Market