
 Global Vertical Grinding Machine Market | 2026-2036
Global Vertical Grinding Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vertical Grinding Machine Market Outlook
Ceramic abrasive wheels are shifting product economics as engineered grain structures replace conventional aluminum oxide in high-stock-removal applications. Okuma Corporation leverages in-house spindle production to sustain precision margins across its vertical grinder portfolio. WaldrichSiegen anchors heavy-duty gantry-style installations for wind turbine bearing rings. DMG MORI competes through integrated automation cells that combine vertical grinding with in-process measurement.
A vertical grinding machine positions a rotating abrasive wheel perpendicular to a stationary worktable, achieving surface finishes below 0.4 micrometers Ra on hardened steels and ceramics through plunge or traverse feed motions. CNC Vertical Grinders dominate value capture as multi-axis interpolation and adaptive dressing cycles reduce setup times for complex aerospace contours. Manual Vertical Grinders occupy a shrinking but defensible niche in tool-room prototype work where programming overhead exceeds part volume. Dedicated Vertical Grinders lead throughput in automotive camshaft and crankshaft lines where single-purpose architecture minimizes changeover.
ISO 230-2 geometric accuracy testing and the EU Machinery Directive's CE marking requirements enforce spindle vibration limits and guarding protocols that elevate R&D budgets for European-bound equipment. Japan's METI industrial standards and JIS B 6190 positioning tolerances shape export competitiveness for Yamazaki Mazak and Makino Milling Machine. China's SAMR certification and GB/T 17421 machine tool test codes add compliance layers for foreign suppliers. Stakeholders must monitor how dual-carbon policy trajectories in Beijing and Brussels redirect capital toward energy-efficient electric spindle architectures over legacy hydraulic systems.
Market Dynamics
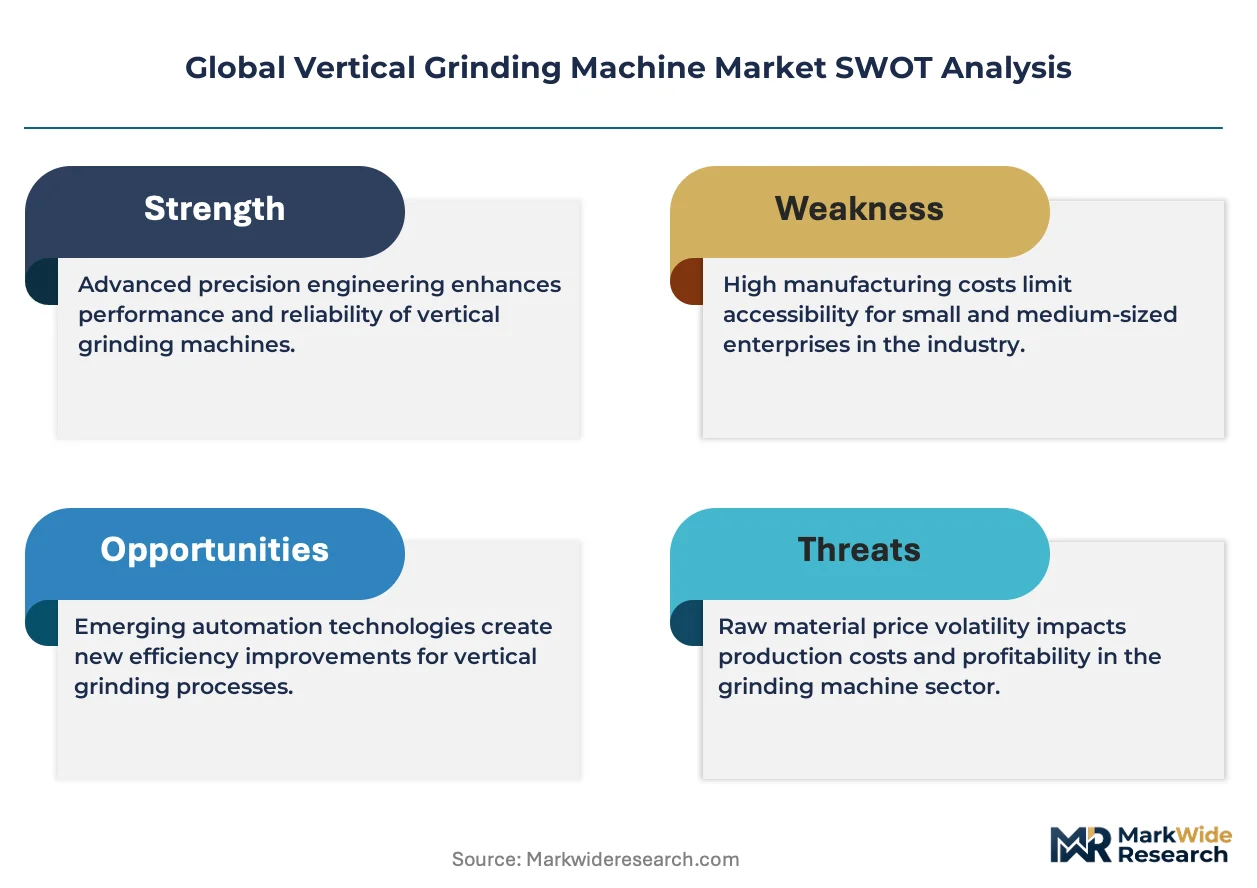
Ceramic abrasive wheel technology and ISO 230 geometric accuracy mandates are compressing setup cycles while elevating compliance costs across export-bound equipment portfolios.
Growth Catalysts
- Aerospace tolerance requirements:Turbine blade finishing below 0.4 micrometers Ra on hardened alloys pulls multi-axis CNC installations into engine manufacturing clusters.
- EU Machinery Directive CE marking:Spindle vibration limits and guarding protocols enforce R&D investment that differentiates compliant European-bound suppliers.
- China's dual carbon policy trajectory:Beijing's energy-efficiency mandates redirect capital toward electric spindle architectures and away from legacy hydraulic grinding systems.
Market Restraints
- Precision spindle supply concentration:High-frequency motorized spindle production concentrates among German and Japanese specialists, creating procurement bottlenecks for mid-tier grinder builders.
- Rare earth magnet cost volatility:Neodymium-iron-boron permanent magnets in direct-drive spindles expose margins to Chinese export quota fluctuations.
- GB/T 17421 compliance layering:China's SAMR certification adds testing documentation that extends delivery timelines for foreign suppliers without in-country technical service.
Strategic Opportunities
- India's PLI scheme for machine tools:Production-linked incentives for capital goods manufacturing create localized assembly pathways for European and Japanese brands.
- Wind turbine bearing ring processing:Gantry-style vertical grinders for 8-meter-diameter slewing bearings represent untapped capacity demand as offshore wind scales.
- Digital twin convergence with in-process measurement:Real-time adaptive dressing cycles combined with laser interferometry feedback enable unmanned aerospace finishing cells.
Industry Challenges
- CNC grinding programmer scarcity:Multi-axis interpolation and adaptive dressing cycle expertise concentrates among aging specialists in Stuttgart and Nagoya industrial corridors.
- ISO 230-2 geometric accuracy certification timelines:Third-party testing for positioning repeatability extends product launch schedules by 4-6 months for new spindle architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vertical Grinding Machine Market |
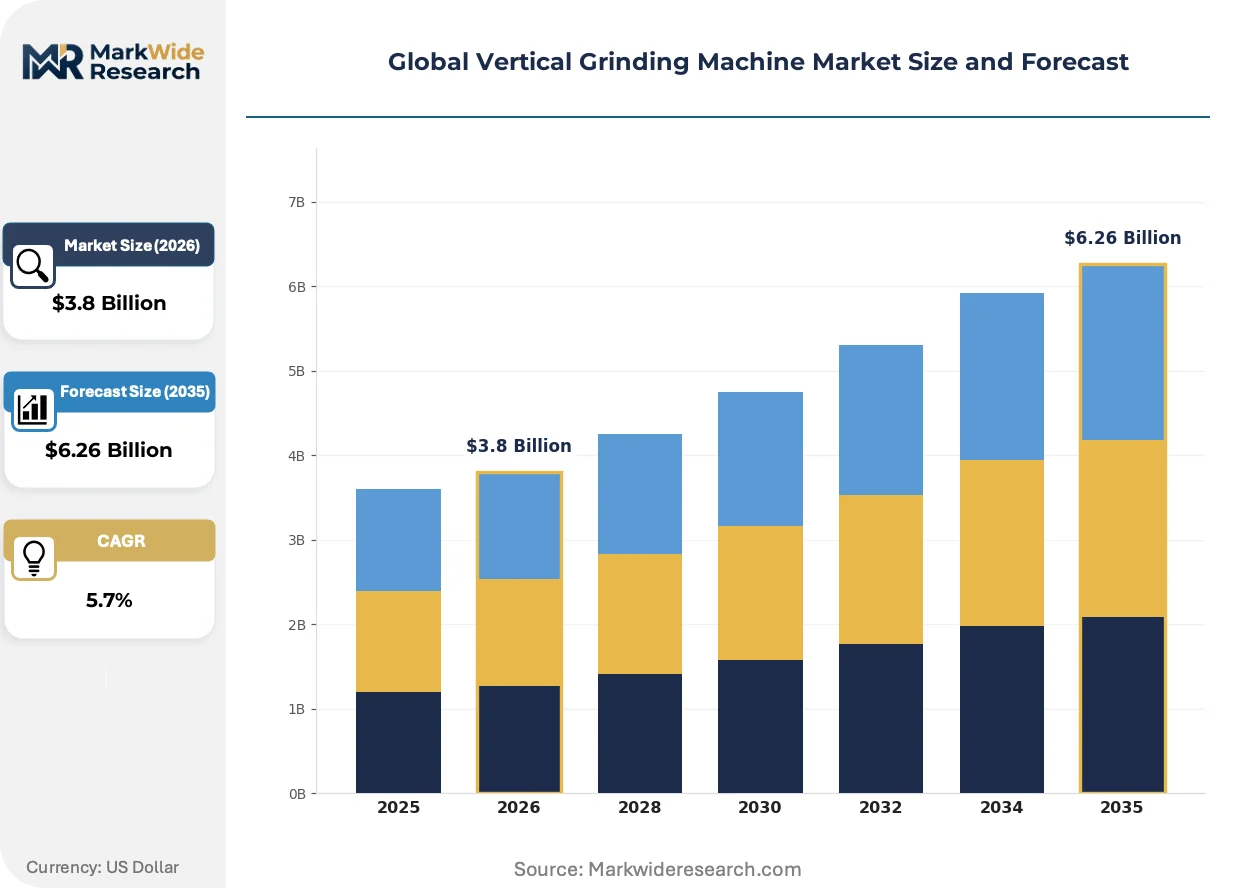
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CNC Vertical Grinders, Manual Vertical Grinders, Dedicated Vertical Grinders, Specialty Vertical Grinders Application: Aerospace, Automotive, Electronics, Tool & Die, Energy End User: Manufacturers, Repair Shops, Research Institutions, OEMs Technology: Hydraulic, Electric, Pneumatic, Hybrid |
| Companies Covered | Okuma Corporation, WaldrichSiegen, DMG MORI, Danobat Group, Peter Wolters, Yamazaki Mazak, Makino Milling Machine, Koyo Machinery, Haas Automation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vertical Grinding Machine Market Strategic Shifts
Machine architecture is fragmenting into configurable subsystems as buyers demand application-specific grinding cells rather than universal platforms. Three developments dominate this transition.
Adaptive dressing systems with embedded acoustic emission sensors are modularizing wheel conditioning workflows. Aerospace tier-one suppliers in Germany and Japan deploy these units to eliminate offline truing stations. The technology is modularizing floor layouts and compressing capital deployment per square meter of manufacturing space.
REACH regulation restrictions on chromium(VI) plating are forcing hard chrome replacement in spindle bearing surfaces. European grinder builders accelerate tungsten carbide coating adoption or ceramic hybrid bearing migration. This regulatory pressure most affects high-speed spindles above 12,000 RPM destined for EU aerospace subcontractors.
Tool-room prototype shops are fragmenting equipment acquisition patterns. Small-batch manufacturers in the United States and Italy now lease manual vertical grinders through distributor-managed service contracts rather than capital purchase. This consumption-pattern shift concentrates revenue risk with regional distributors while compressing OEM direct sales cycles.
Global Vertical Grinding Machine Market Segmentation
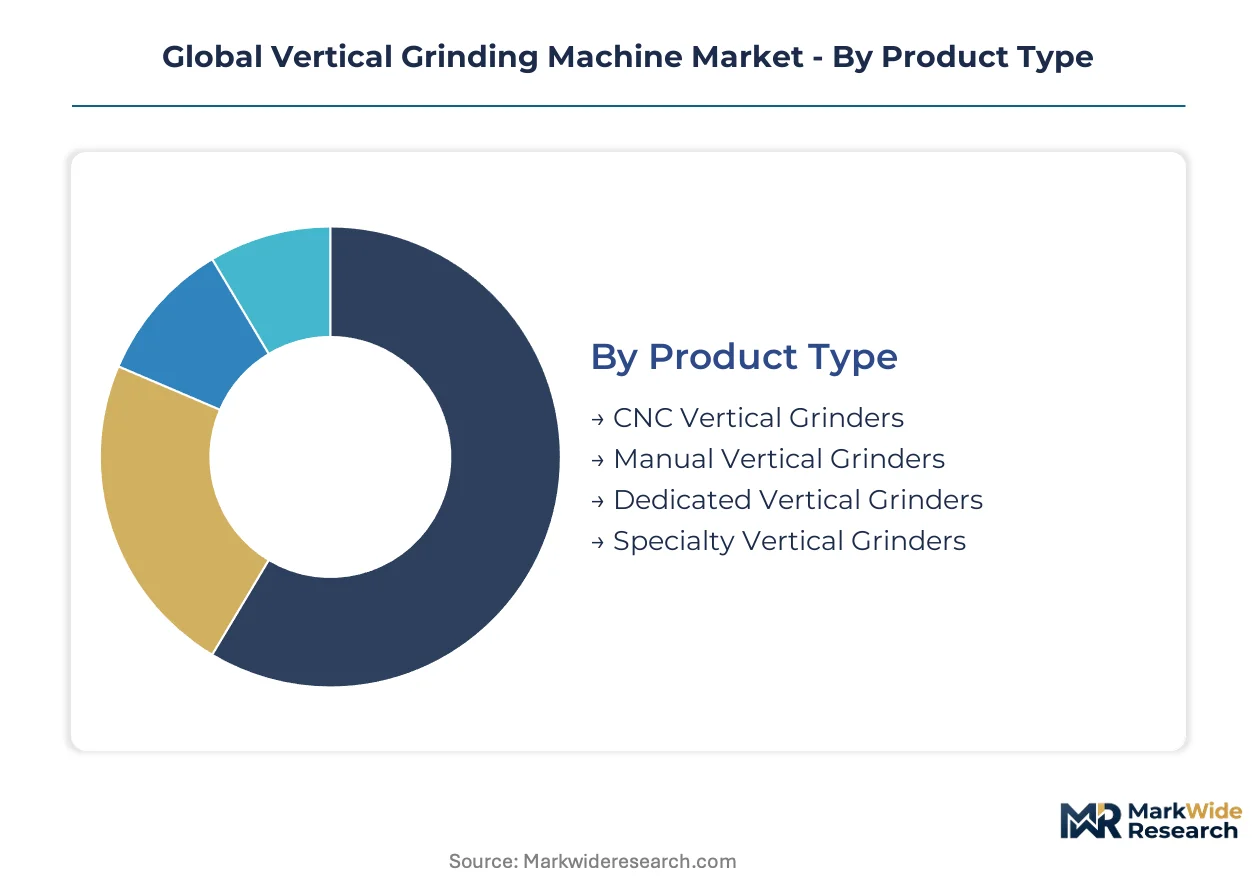
Vertical grinding machine procurement patterns diverge sharply between high-volume automotive lines demanding dedicated architectures and aerospace job shops requiring multi-axis CNC flexibility. Segmentation reveals how spindle technology, control systems, and application specificity determine margin structures across supplier portfolios.
Product Type:
Customization intensity varies from mass-configured dedicated platforms to fully programmable CNC systems, creating distinct service and software revenue attachment rates.
- CNC Vertical Grinders:Multi-axis interpolation enables complex contour grinding on turbine blades and medical implants. Aerospace manufacturers in Germany and Japan drive specifications below 0.4 micrometers Ra surface finish, pulling adaptive dressing cycles and in-process measurement into standard configurations.
- Dedicated Vertical Grinders:Single-purpose architecture minimizes changeover in automotive camshaft and crankshaft production lines. Fixed-axis designs sacrifice flexibility for throughput, capturing volume leadership in powertrain manufacturing clusters around Stuttgart and Detroit.
- Manual Vertical Grinders:Tool-room prototype work where programming overhead exceeds part volume. Leasing through distributor-managed service contracts now dominates acquisition in Italy and the United States.
- Specialty Vertical Grinders:Gantry-scale installations for wind turbine bearing rings exceeding 6-meter diameters. WaldrichSiegen anchors this niche with heavy-duty platforms for offshore wind fabrication yards.
Leading the category by volume: Dedicated Vertical Grinders. Expanding most quickly: CNC Vertical Grinders.
Application:
End-use requirements fragment along tolerance thresholds and batch size economics, with aerospace and automotive occupying opposite poles of the precision-volume spectrum.
- Aerospace:Turbine blade finishing demands multi-axis interpolation and thermal stability compensation. Engine manufacturing clusters in Germany, Japan, and the United States specify ISO 230-2 geometric accuracy certification as a baseline procurement filter.
- Automotive:Powertrain component grinding prioritizes throughput over contour complexity. Dedicated vertical grinders dominate crankshaft and camshaft lines where changeover minimization justifies single-purpose capital deployment.
- Electronics:Ceramic substrate and semiconductor wafer grinding requires sub-micron positioning repeatability. Cleanroom-compatible spindle sealing and vibration isolation differentiate supplier offerings.
- Tool & Die:Prototype and short-run mold finishing sustains manual grinder demand. Job shops in Italy and the United States favor lease arrangements over capital purchase.
- Energy:Wind turbine bearing rings and nuclear component finishing drive gantry-scale installations. Offshore wind scaling in Northern Europe pulls 8-meter-diameter capacity requirements.
Dominant by installed base: Automotive. Steepest expansion trajectory: Aerospace.
End User:
Procurement authority concentrates with manufacturers while service revenue pools with repair networks, fragmenting supplier go-to-market strategies.
- Manufacturers:In-house grinding capacity for production lines and component finishing. Direct OEM relationships dominate with multi-year service contracts and spindle rebuild programs.
- Repair Shops:Independent remanufacturing of worn shafts, rolls, and industrial components. Price-sensitive procurement favors refurbished hydraulic systems over electric spindle upgrades.
- Research Institutions:Materials science laboratories and university machine shops. Grant-funded acquisitions prioritize measurement integration and publication-grade surface characterization.
- OEMs:Grinding machine builders sourcing subsystems and spindle modules. Vertical integration by Okuma and DMG MORI compresses third-party component demand.
Highest volume concentration: Manufacturers. Fastest-growing service attachment: Repair Shops.
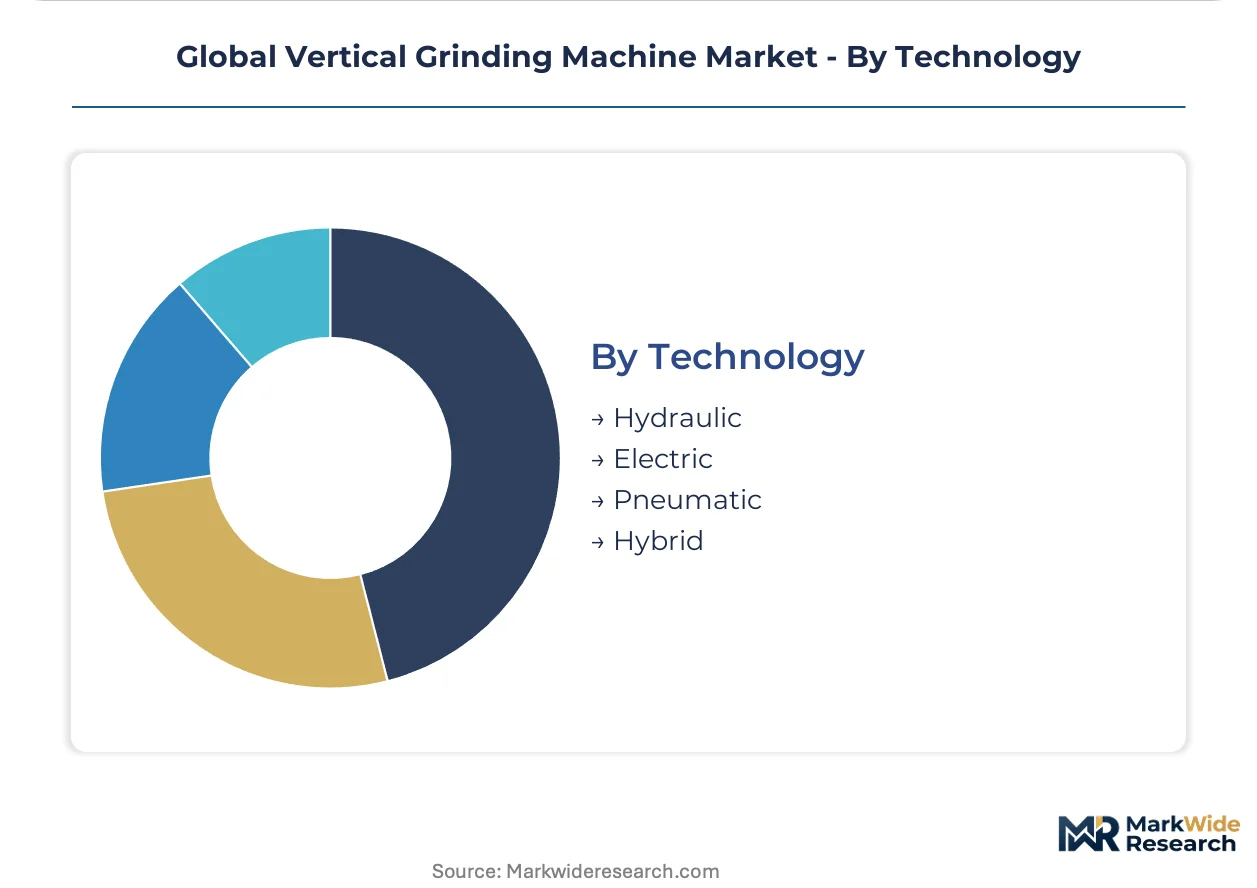
Technology:
Energy efficiency mandates and precision requirements are displacing hydraulic architectures in favor of electric spindle systems, though hybrid designs persist in heavy-stock-removal applications.
- Electric:High-frequency motorized spindles with direct-drive permanent magnet motors. China's dual carbon policy and EU Machinery Directive efficiency standards accelerate adoption across export-bound equipment.
- Hydraulic:Legacy systems in heavy-duty surface and cylindrical grinding. Maintenance intensity and energy consumption drive replacement cycles in European automotive plants.
- Pneumatic:Limited to specialized applications requiring explosion-proof operation or ultra-clean environments. Niche presence in chemical processing equipment remanufacturing.
- Hybrid:Electric spindle precision combined with hydraulic ram force for high-stock-removal. Wind turbine bearing ring grinding and large-diameter surface applications sustain demand.
Technology leader by new installations: Electric. Fastest displacement rate: Hydraulic.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's 21 Free Trade Zones and Germany's Industrie 4.0 tax credits concentrate precision machinery investment in designated industrial corridors. These fiscal instruments pull grinding machine procurement toward certified manufacturing clusters. Export compliance costs now vary sharply by destination market.
Germany
Aerospace engine manufacturing in Baden-Württemberg drives multi-axis CNC grinder specifications below 0.4 micrometers Ra. The EU Machinery Directive's CE marking mandates spindle vibration limits and guarding protocols that elevate R&D budgets for equipment bound for European subcontractors. Stuttgart's industrial corridor anchors turbine blade finishing clusters for Rolls-Royce and MTU Aero Engines.
China
Wind turbine bearing fabrication in Jiangsu Province pulls gantry-scale vertical grinder demand for 6-meter-diameter slewing rings. SAMR certification and GB/T 17421 machine tool test codes add compliance documentation layers that extend delivery timelines for foreign suppliers. The Yangtze River Delta concentrates offshore wind component manufacturing with state-backed capacity expansion.
United States
Defense aerospace programs in Connecticut and Ohio sustain dedicated grinding lines for turbine disk production. FAA airworthiness standards and DOD acquisition regulations enforce traceability protocols that favor domestic spindle rebuild networks. The Hartford-Springfield corridor hosts Pratt & Whitney and GE Aviation finishing operations with long-term service contracts.
Japan
Semiconductor equipment component grinding in Aichi Prefecture demands sub-micron positioning repeatability for ceramic substrate processing. METI industrial standards and JIS B 6190 positioning tolerances shape export competitiveness for precision machinery. Nagoya's Chubu region concentrates Makino and Yamazaki Mazak manufacturing with integrated automation cell development.
India
Automotive powertrain expansion in Tamil Nadu and Maharashtra creates localized assembly demand for dedicated camshaft grinding lines. The PLI scheme for machine tools offers production-linked incentives that attract European and Japanese brands to establish captive capacity. The Chennai-Bengaluru industrial corridor hosts Hyundai and Tata Motors component finishing operations.
Global Vertical Grinding Machine Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated OEMs capturing premium aerospace installations while regional fabricators serve price-sensitive repair shops. Market structure consolidates around three strategic tiers: full-system builders with captive spindle production, subsystem specialists supplying gantry architectures, and distributor-assemblers leasing manual platforms. M&A activity targets electric spindle technology acquisitions, while geographic expansion focuses on India's PLI-compliant assembly pathways.
Among Japanese precision machinery builders, Okuma Corporation and Yamazaki Mazak occupy positions emphasizing in-house spindle production and multi-axis control integration. WaldrichSiegen represents the heavy-duty gantry specialist archetype serving wind energy and large-diameter bearing applications. These three entities exemplify divergent competitive vectors: vertical integration into core components, scale-driven offshore wind capacity, and automation-centric aerospace cells.
| Leading Market Players |
|---|
| Okuma Corporation |
| WaldrichSiegen |
| DMG MORI |
| Danobat Group |
| Peter Wolters |
| Yamazaki Mazak |
| Makino Milling Machine |
| Koyo Machinery |
| Haas Automation |
| Others |
Value Chain & Pricing Dynamics
Neodymium-iron-boron magnet price indices cascade through electric spindle production costs into three-tier pricing structure across premium, standard, and economy levels for vertical grinding machine portfolios. Aerospace manufacturers in Germany and Japan absorb premium tier positioning for sub-0.4 micrometer Ra certification, while automotive powertrain buyers in Detroit and Stuttgart negotiate volume-driven standard tier arrangements.
Pricing Analysis
Short lead-time premiums of 15-25 percent apply to CNC vertical grinders with ISO 230-2 pre-certification, while spot inventory of manual platforms trades at distressed levels in Italian and U.S. distributor networks. Price differentiation rests on spindle origin certification and adaptive dressing module inclusion. Pricing pressure stems from rare earth magnet cost volatility compressing electric spindle margins. Repair shops exhibit highest price sensitivity, deferring electric upgrades for refurbished hydraulic systems.
Supply Chain Analysis
India's PLI scheme domestic-content thresholds are redirecting final assembly localization for European and Japanese brands previously exporting complete machines from Germany and Japan. High-frequency motorized spindle production concentrates in Germany, Japan, and Taiwan, drawing from rare earth magnet feedstock subject to Chinese export quota fluctuations. Single-source vulnerability concentrates in precision bearing supply from Schaeffler and NSK. Distribution runs through OEM-direct channels for aerospace tier-ones and distributor-managed lease networks for tool-room prototype shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around electric spindle architecture mastery as ISO 230-2 compliance timelines and rare earth cost volatility force mid-tier hydraulic specialists toward exit or acquisition. Surviving players will command captive spindle production or gantry-scale specialization.
For Market Incumbents: Deepen backward integration into ceramic abrasive wheel formulation and permanent magnet sourcing to insulate margins from Chinese export quota volatility. Prioritize ISO 230-2 third-party certification pre-positioning to capture aerospace procurement filters before competitor launch cycles complete. Defend Stuttgart and Nagoya corridor relationships against emerging Indian assembly competition through embedded service engineer placement. For New Entrants and Emerging Players: Digital aftermarket platforms for spindle rebuild and adaptive dressing module retrofit offer lowest barrier entry into installed base monetization. Target repair shop price sensitivity in Italy and the United States with lease-to-own manual grinder arrangements. Pursue PLI-compliant assembly partnerships in Tamil Nadu to access automotive powertrain expansion without full greenfield capital deployment. For Investors and Strategic Acquirers: Distressed-cycle entries favor electric spindle technology specialists in Taiwan and South Korea facing rare earth cost squeeze but holding precision positioning IP. Five-to-ten year viability hinges on dual-carbon policy alignment and aerospace certification backlog depth. Monitor SAMR certification queue lengths as inflection signal for foreign supplier delivery competitiveness erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Spindle Technology Acquisition | Captive high-frequency motor production insulates margins from rare earth volatility and ISO 230-2 compliance delays. |
| PLI-Compliant Assembly Localization | India's production-linked incentives enable tariff-advantaged supply to automotive powertrain expansion in Tamil Nadu. |
| Adaptive Dressing System Integration | Acoustic emission sensor modules eliminate offline truing stations and compress aerospace cell capital per square meter. |
| Gantry-Scale Capacity Expansion | 8-meter-diameter bearing ring platforms capture offshore wind scaling in Northern Europe and Jiangsu Province. |
| Digital Twin Convergence Development | Real-time laser interferometry feedback enables unmanned aerospace finishing cells and service contract attachment. |
Study Parameters
Document review covered customs trade databases, ISO 230 machine tool accuracy standards, and SAMR certification filings, complemented by interviews with plant engineers at aerospace tier-one suppliers, aftermarket service heads at European OEMs, and procurement leads at automotive powertrain manufacturers. Primary fieldwork with spindle rebuild specialists in Stuttgart and Nagoya industrial corridors validated secondary data on CNC programmer scarcity. Bottom-up unit economics triangulated against top-down industrial machinery investment flows.
Cross-referencing historical grinder shipment patterns against expert panel input on dual-carbon policy implementation timelines established the projection framework. Segmentation modeling spanned product type, application specificity, technology architecture, and regional regulatory cluster. CAGRs derived from interpolating aerospace tolerance tightening rates and automotive powertrain capacity expansion schedules across the analysis window. Forecast inputs incorporated wind turbine bearing ring diameter scaling and REACH regulation chromium(VI) replacement timelines.
The model holds under stable rare earth magnet supply and continued EU Machinery Directive enforcement; deviation in Chinese export quota severity or SAMR certification reciprocity agreements would shift competitive positioning. Forecasts reflect documented assumptions on ISO 230-2 adoption velocity and PLI scheme renewal probability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Fastening Power Tools Market
Tools
Stationary Wood Planer Market
Tools
Adoption of Benelux Power Tools Market
Tools
Mallets and Sledgehammers Market
Tools
Chainsaw Market
Tools
Machine Bench Vices Market
Tools
Circular Saw Blades Market
Tools
China Power Tools Market
Tools
Asia Pacific Power Tools Market
Tools
Global Table Saws Market
Tools
Foam Engraving Machines Market
Tools
2D Laser Cutting Machine Market
Tools
Riveting Tools Market
Tools
Press Machine Market
Tools
CNC Leather Cutting Machine Market
Tools
Spray Gun Market