
 End Milling Machine Market | 2026-2036
End Milling Machine Market Size, Share, and Industry Trends Forecast 2026-2036
End Milling Machine Market Foresight
The EU Green Deal's carbon-border adjustment mechanism is shifting procurement criteria for European metalworking equipment buyers. DMG MORI leverages its integrated spindle manufacturing to control quality across high-speed milling lines. Kennametal anchors its position through advanced carbide insert R&D for extended tool life in demanding cuts. Yamazaki Mazak dominates the Japanese domestic market with localized service networks and application-specific machine configurations.
An end milling machine employs a rotating cutter with cutting teeth on its end and periphery to remove material from a workpiece surface, typically achieving tolerances of 0.01 mm in precision configurations. The machine generates flat surfaces, slots, and complex profiles through controlled feed rates and spindle speeds ranging from 8,000 to 30,000 RPM in advanced systems. CNC milling machines command the highest value per unit as shops replace manual equipment for lights-out production runs. Five-axis milling grows fastest among technology segments because aerospace and medical device makers require simultaneous multi-face machining without repositioning errors. Conventional milling retains volume share in emerging manufacturing economies where capital constraints limit automation investment.
The EU Machinery Directive and CE marking requirements shape product design for any manufacturer seeking European market access, mandating safety interlocks and electromagnetic compatibility testing. China's SAMR enforces GB standards for precision machine tools that foreign suppliers must meet through local certification partners. ISO 230 standards for machine tool testing provide a common evaluation framework that reduces buyer uncertainty in cross-border procurement. Stakeholders must monitor how dual carbon goals in major manufacturing economies redirect subsidy flows toward energy-efficient machining centers versus legacy platform upgrades.
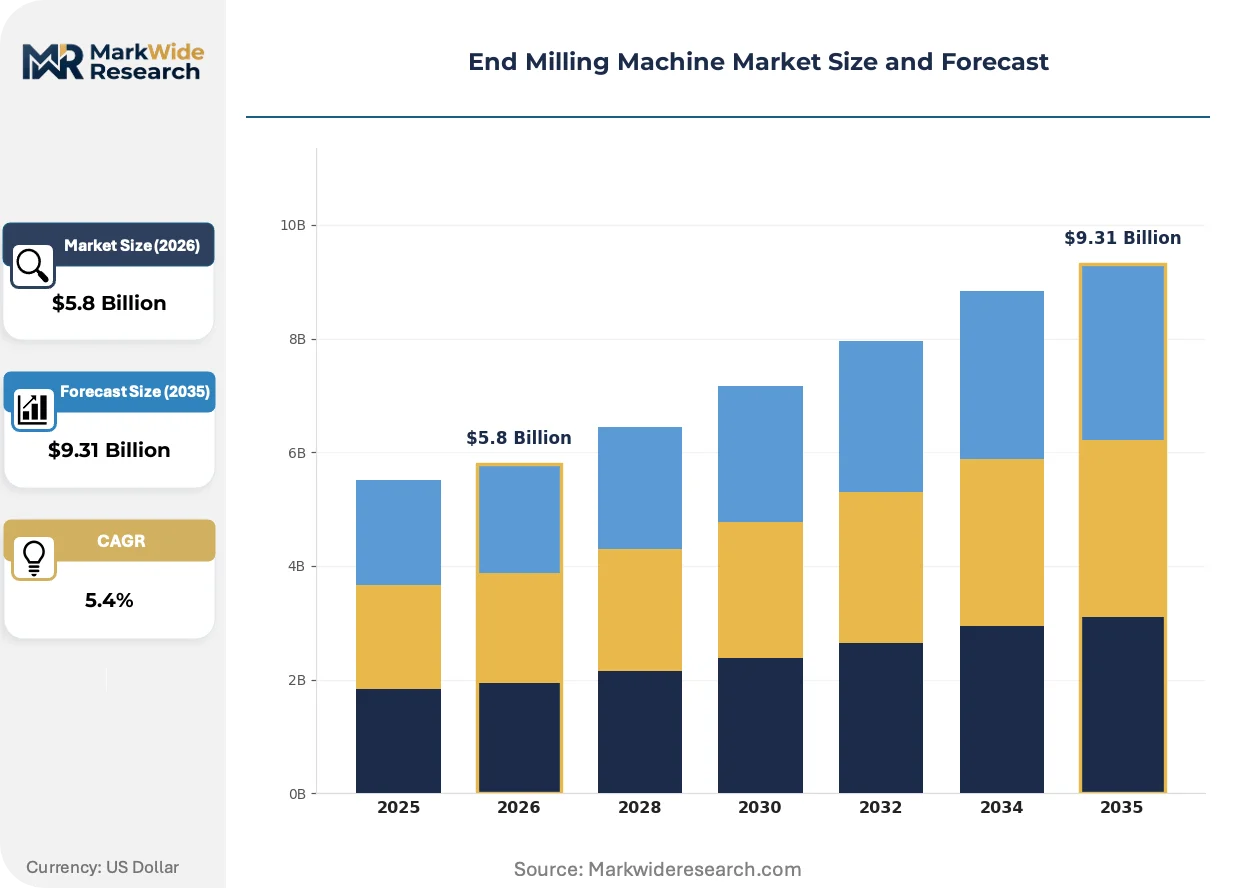
Market Dynamics
Five-axis simultaneous machining is compressing setup times and eliminating repositioning errors, forcing tool shops to replace three-axis platforms despite intact functional life. Aerospace and medical device tolerances now demand sub-ten-micron repeatability that legacy equipment cannot deliver.
Growth Catalysts
- EU Green Deal carbon-border adjustments:European metalworking buyers now embed lifecycle emissions into equipment procurement criteria, favoring energy-efficient machining centers with regenerative drives.
- Titanium-aluminide turbine blades:Aerospace engine programs in Germany and Japan require five-axis platforms capable of interrupted cuts in gamma titanium aluminide without thermal damage.
- Yangtze River Delta cluster upgrades:Chinese tool shops are retiring conventional knee mills for CNC platforms to serve export-oriented mold and die contracts.
Market Restraints
- High-purity cast iron bed castings:Foundry capacity constraints in Germany and Japan extend lead times for machine base components by four to six months.
- CE marking electromagnetic compatibility testing:The EU Machinery Directive mandates third-party certification that adds twelve to eighteen weeks to European market entry for non-EU builders.
- Used equipment arbitrage:Depreciated three-axis CNC mills from Japanese automotive supplier liquidations displace new equipment sales in Southeast Asian contract shops.
Strategic Opportunities
- India's PLI scheme for machine tools:Domestic component sourcing mandates create openings for local assembly partnerships serving automotive and defense verticals.
- Hybrid manufacturing convergence:Directed energy deposition heads integrated onto five-axis milling platforms enable near-net-shape repair of aerospace blisks and impellers.
- Performance-based service contracts:Tool life guarantees and spindle uptime commitments replace traditional maintenance agreements in North American job shops.
Industry Challenges
- ISO 230 machine tool testing certification:Third-party verification of volumetric accuracy and thermal drift consumes six to nine months for new platform introductions.
- Five-axis post-processor integration:CAM software vendors and machine builders must synchronize kinematic models for each installation, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | End Milling Machine Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $9.31 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Milling Machines, Horizontal Milling Machines, Universal Milling Machines, CNC Milling Machines Technology: Conventional Milling, Advanced Milling, High-Speed Milling, 5-Axis Milling End User: Aerospace, Automotive, Metal Fabrication, Electronics Application: Precision Cutting, Tool Manufacturing, Die Making, Prototyping |
| Companies Covered | Yamazaki Mazak, Hurco, DMG MORI, Haas Automation, Makino Milling Machine, Elumatec, WEGOMA, Okuma Corporation, Kennametal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
End Milling Machine Market Shifts & Advancements
Direct-drive spindle technology and real-time thermal compensation are collapsing the performance gap between mid-range and premium platform tiers. Machine builders now compete on software-enabled productivity rather than mechanical specifications alone.
Magnetic bearing spindles operating above 30,000 RPM are electrifying high-speed machining economics in aluminum aerospace structural components. Tier-one suppliers in Germany and Japan are specifying these systems for wing rib and floor beam programs. The technology is eliminating gearbox maintenance intervals and enabling continuous duty cycles that mechanical bearings cannot sustain.
China's SAMR enforcement of updated GB standards for precision machine tools is tightening electromagnetic compatibility and safety interlock requirements for imported equipment. Foreign suppliers must now submit to local testing protocols that extend certification timelines. European and Japanese builders with established Shanghai or Beijing technical centers are adapting firmware and documentation faster than entrants relying on headquarters engineering.
After-sales service unbundling is fragmenting traditional distributor relationships in North American metalworking markets. End users now procure spare spindles, ball screws, and control retrofits through specialized industrial parts platforms rather than authorized dealer networks. This pattern concentrates in high-mix, low-volume job shops where minimizing downtime overrides brand loyalty.
End Milling Machine Market Segmentation
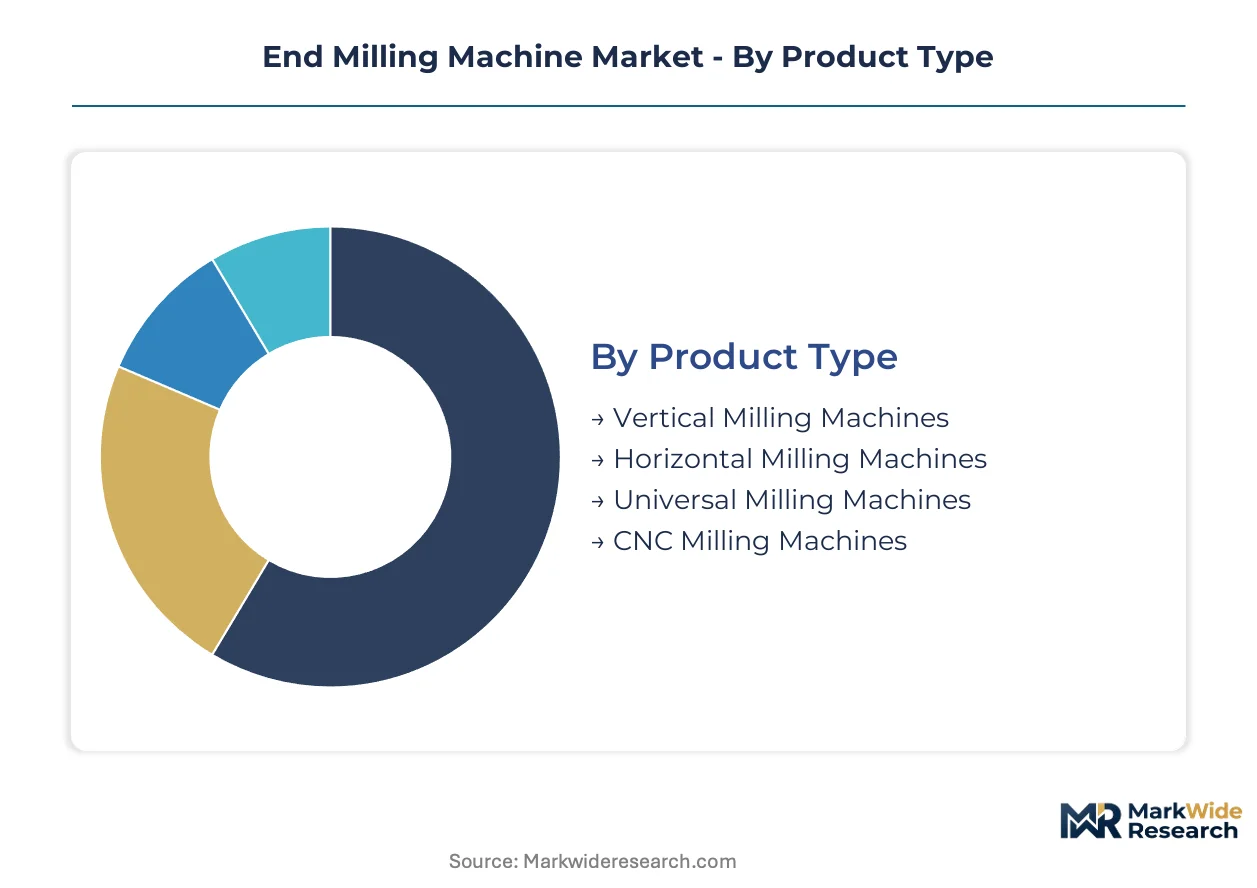
End milling machine purchasing patterns diverge sharply across product architectures and control systems. Each segment commands distinct specification requirements, aftermarket service intensities, and replacement cycles that reshape vendor priorities.
Product Type:
Supply concentration tilts toward integrated spindle and control system manufacturers who bundle hardware with proprietary software ecosystems.
- CNC Milling Machines:These systems integrate computerized numerical control with servo-driven axes achieving positioning repeatability below five microns. Aerospace manufacturers in Germany and Japan specify these platforms for titanium-aluminide turbine blade programs where thermal compensation algorithms prevent workpiece damage. DMG MORI and Yamazaki Mazak dominate this tier through captive spindle production and localized application engineering.
- Universal Milling Machines:Configurable for both vertical and horizontal spindle orientations, these machines serve job shops requiring setup flexibility without dedicated platform investment. Metal fabrication contractors in India's automotive supply chain favor these systems for mixed-batch production where changeover speed determines contract profitability.
- Vertical Milling Machines:The knee-mill architecture persists in emerging manufacturing economies where capital constraints limit automation investment.
- Horizontal Milling Machines:Pallet-based configurations dominate high-volume automotive powertrain machining where chip evacuation and tool magazine capacity drive throughput.
Today's leader: CNC Milling Machines. Tomorrow's challenger: Universal Milling Machines.
Technology:
Cost tier stratification separates premium platforms with real-time thermal compensation from baseline equipment lacking adaptive control.
- 5-Axis Milling:Simultaneous multi-face machining eliminates repositioning errors that accumulate in sequential three-axis operations. Medical device manufacturers in Switzerland and Germany require sub-ten-micron repeatability for orthopedic implant surfaces that three-axis platforms cannot deliver. The technology commands premium pricing but collapses setup times by seventy percent in complex aerospace structural components.
- High-Speed Milling:Magnetic bearing spindles operating above thirty thousand RPM enable continuous duty cycles in aluminum aerospace ribs and floor beams. Tier-one suppliers specify these systems where mechanical bearing maintenance intervals would interrupt just-in-time delivery commitments.
- Advanced Milling:Direct-drive spindles and integrated probing systems bridge the performance gap between conventional and high-speed tiers.
- Conventional Milling:Manual feed mechanisms and fixed spindle speeds retain volume in China's Yangtze River Delta tool shops upgrading from knee mills in phased automation programs.
Five-axis platforms expand most quickly among technology tiers. Conventional milling retains defensive positions in cost-sensitive procurement.
End User:
Application-specific tolerances and batch sizes create divergent equipment specification patterns across verticals.
- Aerospace:Gamma titanium aluminide and carbon fiber reinforced polymer machining demands thermal stability and vibration damping that only polymer-concrete or high-purity cast iron bed structures provide. Engine OEMs in Germany and Japan specify five-axis platforms with through-spindle coolant for interrupted cuts in heat-resistant superalloys.
- Automotive:Powertrain machining centers prioritize pallet-based horizontal configurations with automatic tool changers exceeding one hundred stations. Electric vehicle motor housing programs are redirecting capital toward dedicated aluminum high-speed lines separate from legacy cast iron engine block equipment.
- Metal Fabrication:Job shops serving construction and agricultural equipment favor universal machines with manual conversational programming for prototype and short-run work.
- Electronics:Miniaturization trends in connector and heat sink production drive demand for compact vertical machining centers with high spindle speed and rapid traverse rates.
Aerospace commands specification leadership. Automotive provides volume concentration.
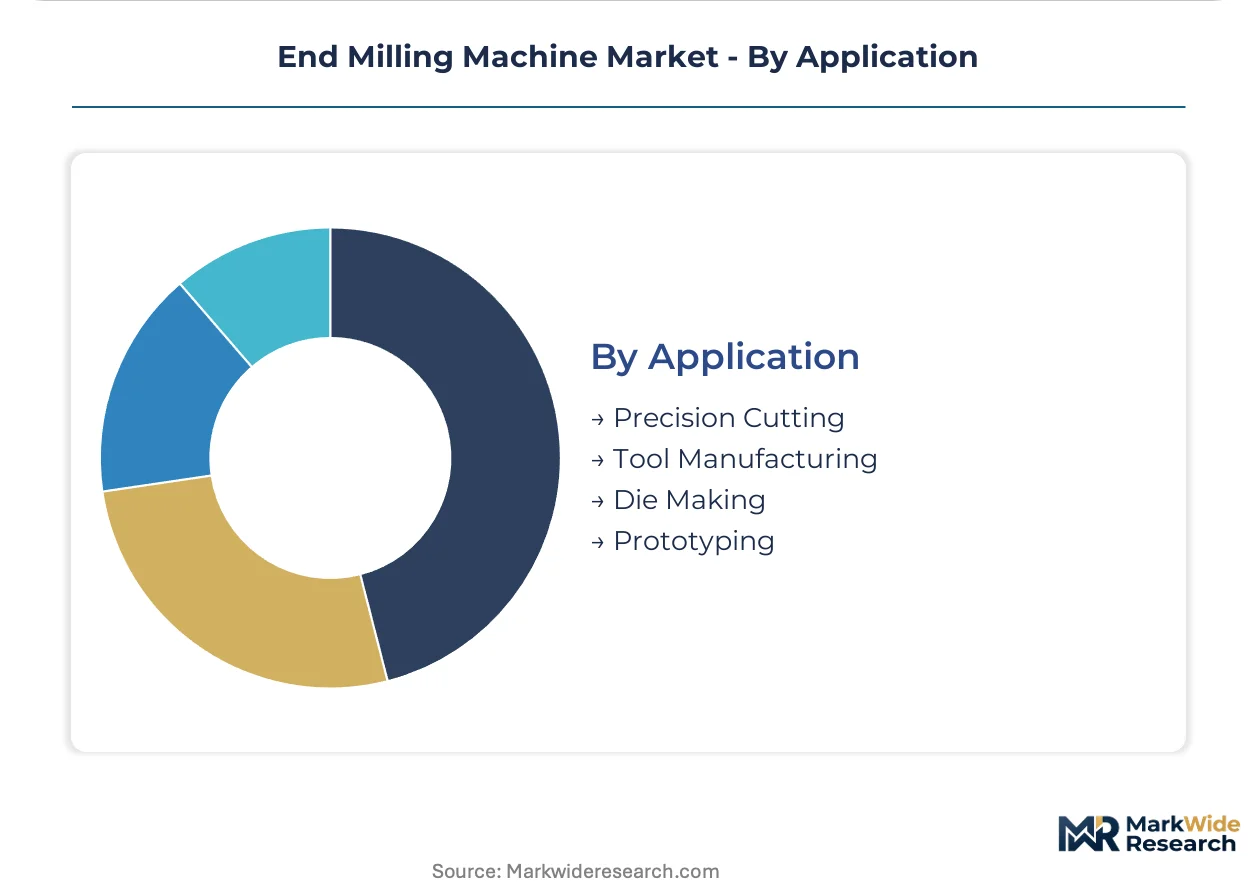
Application:
Customer type segmentation separates captive manufacturers with dedicated process engineering from contract shops purchasing generic capability.
- Precision Cutting:Sub-micron surface finish requirements in medical and optical applications demand hydrostatic bearing spindles and active vibration isolation. Swiss and German manufacturers specify these configurations for orthopedic implant and lens mold production where surface integrity determines biocompatibility certification.
- Tool Manufacturing:Carbide insert and solid round tool grinding requires specialized five-axis platforms with direct-drive rotary tables and laser measurement feedback. Kennametal and Sandvik Coromant operate captive equipment for proprietary geometries.
- Die Making:Mold and die shops in China's export-oriented manufacturing clusters are retiring conventional equipment for CNC platforms capable of hard milling hardened tool steel.
- Prototyping:Rapid design iteration requirements favor machines with quick-change fixturing and conversational programming interfaces accessible to operators without G-code expertise.
Precision Cutting anchors premium pricing. Die Making drives volume replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered modern machine tool manufacturing in the 19th century, establishing the precision engineering traditions that now define end milling machine specifications worldwide. Japanese builders later refined five-axis kinematics for aerospace applications. Contemporary demand patterns reflect these historical legacies while incorporating new regulatory pressures from major manufacturing economies.
Germany
Aerospace engine OEMs in Bavaria and Baden-Württemberg specify five-axis platforms with through-spindle coolant for gamma titanium aluminide machining. The EU Machinery Directive and CE marking requirements mandate electromagnetic compatibility testing that extends certification timelines for non-EU equipment. Stuttgart's manufacturing cluster concentrates precision machining capacity serving Airbus and MTU Aero Engines programs.
Japan
Domestic medical device manufacturers in the Kansai region demand sub-ten-micron repeatability for orthopedic implant production. METI oversees JIS standards for machine tool precision that foreign suppliers must meet through local certification partners. Nagoya's Chubu industrial corridor hosts concentrated five-axis machining capacity for automotive and aerospace component suppliers.
China
Tool shops in the Yangtze River Delta upgrade from conventional knee mills to CNC platforms for export-oriented mold and die contracts. SAMR enforces updated GB standards for precision machine tools that tighten electromagnetic compatibility requirements for imported systems. Shanghai's manufacturing cluster absorbs the majority of foreign builder technical center investments.
United States
North American job shops adopt performance-based service contracts with spindle uptime commitments replacing traditional maintenance agreements. OSHA workplace safety regulations intersect with state-level manufacturing incentives in Michigan and Ohio. The Midwest automotive corridor retains concentrated horizontal machining center demand for powertrain component production.
India
Automotive suppliers in Maharashtra and Tamil Nadu expand machining capacity under the PLI scheme's domestic component sourcing mandates. BIS certification requirements for imported precision equipment create procedural barriers for non-established builders. Pune's automotive manufacturing cluster drives universal milling machine demand for mixed-batch production flexibility.
End Milling Machine Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across tiered market positions. Integrated machine builders with captive spindle manufacturing control quality across high-speed lines, while component specialists supply standardized platforms to regional assemblers. Three archetypes dominate: full-system integrators with proprietary control ecosystems, spindle and cutting tool specialists supplying multiple OEMs, and regional fabricators serving price-sensitive procurement in emerging economies. Competitive moves concentrate on geographic expansion through local assembly partnerships and technology licensing arrangements that bypass capital-intensive greenfield investments.
Among Japanese builders, Yamazaki Mazak and Makino Milling Machine occupy positions emphasizing localized service networks and application-specific configurations. DMG MORI represents the European-Japanese hybrid model with integrated spindle manufacturing and control system development. Haas Automation anchors the mid-market tier with standardized platform architectures serving North American job shops. Hurco exemplifies the conversational programming specialist segment targeting operators without G-code expertise. Kennametal sits within the cutting tool and workholding supplier archetype rather than machine building proper. Okuma Corporation represents the comprehensive system integrator model with proprietary CNC and drive technology.
| Leading Market Players |
|---|
| Yamazaki Mazak |
| Hurco |
| DMG MORI |
| Haas Automation |
| Makino Milling Machine |
| Elumatec |
| WEGOMA |
| Okuma Corporation |
| Kennametal |
| Others |
Supply & Pricing Matrix
Magnetic bearing spindle adoption above 30,000 RPM is simultaneously collapsing maintenance cost economics and concentrating procurement leverage among tier-one aerospace suppliers in Germany and Japan who specify these systems for wing rib programs. This technology shift feeds back into supply chain restructuring as captive spindle manufacturers capture margin that previously flowed to independent bearing suppliers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates equipment procurement. Price differentiation hinges on ISO 230 certification grade and after-sales service bundling intensity. Cost compression in the economy tier is intensifying because used three-axis CNC mills from Japanese automotive liquidations displace new equipment in Southeast Asian contract shops. Job shops serving mixed-batch production exhibit highest price sensitivity, while aerospace engine OEMs demonstrate lowest sensitivity due to tolerance-driven specification requirements.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese foundries producing high-purity cast iron bed castings. Machine base production draws from concentrated foundry capacity in Germany, Japan, and select Italian suppliers. Supply chain risk centers on four-to-six month lead time extensions for critical bed components. Distribution runs through authorized dealer networks in developed markets while specialized industrial parts platforms fragment aftermarket relationships in North American job shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in five-axis platform tiers where thermal compensation algorithms command premium positioning against commoditized three-axis alternatives. Software-enabled productivity guarantees increasingly separate profitable installations from price-pressured legacy replacements.
For Market Incumbents: Extend application engineering presence in China's Yangtze River Delta manufacturing cluster to capture CNC upgrade cycles from conventional knee mill retirements. Deepen captive spindle manufacturing control to defend margin position against component specialists supplying standardized platforms to regional assemblers. Prioritize firmware localization investments that accelerate SAMR GB standards compliance timelines versus headquarters-dependent engineering.
For New Entrants and Emerging Players: Contract machining shops in India's Maharashtra and Tamil Nadu automotive corridors represent underserved buyer archetype with PLI scheme-driven capacity expansion requirements. Performance-based service contracts with spindle uptime commitments offer differentiated entry angle against established maintenance agreement structures. Target mixed-batch production flexibility needs with universal milling configurations before competing in five-axis aerospace specification tiers.
For Investors and Strategic Acquirers: Roll-up economics work for regional service specialists with localized spare spindle and ball screw inventories because after-sales unbundling fragments traditional distributor relationships. Mid-cap platform integrators with proprietary CNC ecosystems present viable acquisition targets over five-year horizon. Monitor hybrid manufacturing convergence signals as directed energy deposition integration onto milling platforms indicates inflection toward repair-service revenue models.
| Strategic Initiative | Industry Significance |
|---|---|
| Local Assembly Partnership | India's PLI domestic sourcing mandates require local component integration for automotive and defense vertical access. |
| Spindle Technology Licensing | Magnetic bearing systems above 30,000 RPM enable continuous duty cycles that mechanical bearings cannot sustain. |
| Performance-Based Service Contract | Tool life guarantees replace traditional maintenance agreements in North American high-mix job shop environments. |
| Hybrid Manufacturing Integration | Directed energy deposition heads on five-axis platforms enable near-net-shape repair of aerospace blisks and impellers. |
| Certification Acceleration Investment | Shanghai and Beijing technical centers adapt firmware faster for SAMR GB standards compliance than headquarters engineering. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads across Germany, Japan, China, and the United States inform demand-side validation. Secondary sources include customs and trade data for machine tool imports, SEC 10-K filings from publicly traded builders, production databases from automotive and aerospace OEMs, and national machine tool association statistics. Triangulation between these sources ensures volume and value estimates reflect actual procurement patterns rather than shipment data alone.
Historical trendline analysis across the analysis window establishes baseline growth trajectories segmented by product architecture, control system technology, end-use vertical, and regional manufacturing cluster. Modeled dimensions include CNC versus conventional platforms, five-axis versus three-axis kinematics, aerospace versus automotive versus metal fabrication end-use, and precision certification tier. CAGRs derive from regression analysis against macroeconomic manufacturing indicators and capital expenditure survey data. Industry-specific forecast inputs incorporate SAMR enforcement timelines for GB standards updates and EU Green Deal carbon-border adjustment implementation progress.
Underlying measurement precision varies by segment; five-axis CNC platforms in aerospace applications carry tighter precision than conventional milling in emerging economy tool shops. Forecasts reflect documented assumptions regarding regulatory enforcement consistency, foundry capacity expansion, and technology substitution rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Friction Washer Market
Tools
Technical Drawing Tools Market
Tools
Global Cordless Power Tools Market
Tools
Woodworking CNC Tools Market
Tools
US Chalk Reel and Line Market
Tools
Sander Market
Tools
Handheld Engraving Machine Market
Tools
Coil Fed Punching and Cutting Machines Market
Tools
Pipe Alignment Clamps Market
Tools
Drill Presses Market
Tools
Mortiser Market
Tools
Thread Milling Machine Market
Tools
Global Punch and Die Storage Cabinet Market
Tools
Parting-Off Blades Market
Tools
Engraver Machine Market
Tools
Tool Hammer Market