
 Power Tool Gears Market | 2026-2036
Power Tool Gears Market Size, Share, and Industry Trends Forecast 2026-2036
Power Tool Gears Market Analysis
Premium-grade alloy steel specifications is rotating demand toward hardened gear sets capable of withstanding higher torque loads in brushless cordless platforms. Bosch Power Tools leverages in-house metallurgy capabilities to control heat-treatment consistency across its gear supply chain. Makita Corporation anchors its competitive stance through vertical integration into powder metallurgy operations in Japan and China. Stanley Black & Decker differentiates via multi-brand portfolio architecture spanning professional and consumer torque categories.
Power tool gears are precision-machined or sintered mechanical components that transmit rotational force from motor spindles to output shafts, typically manufactured from case-hardened steel alloys with tolerances measured in micrometers to ensure meshing efficiency and noise reduction under cyclical load conditions. Gear motors and speed reducers command the largest share of product-type revenue due to their integration complexity and replacement-part dependency, while composite-material gears represent the fastest-expanding material segment as manufacturers seek weight reduction for extended-reach cordless tools. Construction and automotive applications generate the highest absolute demand volumes, though woodworking segments sustain premium pricing for low-backlash precision gear sets.
FCC equipment authorization rules in the United States govern electromagnetic compatibility for cordless power tool electronics, indirectly shaping gear-design requirements through motor-control specifications, while REACH substance restrictions in Europe constrain certain alloy additives and surface-treatment chemistries used in gear manufacturing. China's GB standards and MIIT energy-efficiency directives influence domestic gear producers serving both local and export markets. Stakeholders must monitor how battery-platform voltage escalation toward higher cell configurations alters gear-tooth loading profiles and material-selection criteria across cordless product lines.
Market Dynamics
Battery-platform voltage escalation toward 20V+ cell configurations is forcing gear-tooth loading recalibrations across cordless product lines, while brushless motor torque density improvements compress traditional gear-set design margins.
Growth Catalysts
- MIIT Energy-Efficiency Directives:China's domestic gear producers serving export markets must optimize transmission efficiency to meet MIIT benchmarks, accelerating hardened alloy adoption in Ningbo and Suzhou manufacturing clusters.
- Professional Contractor Cordless Migration:Construction crews in residential and commercial building segments now specify brushless platforms exclusively, creating replacement-part dependency for precision-machined gear sets.
- Lithium-Ion Cell Chemistry Advances:Higher discharge rates from improved cathode formulations enable sustained torque delivery that legacy gear specifications cannot accommodate.
Market Restraints
- Alloy Steel Input Volatility:Case-hardening grade steel prices fluctuate with nickel and molybdenum commodity markets, compressing margin structures for mid-tier gear suppliers.
- REACH Substance Restrictions:ECHA constraints on certain surface-treatment chemistries limit European gear manufacturers' hardening process options, forcing process revalidation.
- Powder Metallurgy Concentration:Sintered gear production capacity clusters in Japan and China, creating supply vulnerability for brands without captive metallurgy operations.
Strategic Opportunities
- Composite Gear Materials:Glass-fiber reinforced polymer gears enable weight reduction for extended-reach cordless tools targeting overhead installation work.
- Woodworking Precision Segment:Low-backlash gear specifications command premium positioning in cabinet-making and furniture production applications.
- India BIS Certification Pathway:Formal adoption of Indian Standards for power tool safety creates first-mover advantage for gear suppliers achieving BIS mark compliance ahead of enforcement deadlines.
Industry Challenges
- Heat-Treatment Skill Scarcity:Case-hardening process control requires metallurgical expertise that vocational pipelines in Germany and Japan no longer replenish at replacement rates.
- FCC Equipment Authorization Timelines:Electromagnetic compatibility certification for cordless tool electronics delays gear-motor integration testing, compressing product launch windows.
- Legacy Platform Compatibility:Gear suppliers must maintain tooling for obsolete battery voltages while retooling for 18V-20V platforms, straining capital allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Tool Gears Market |
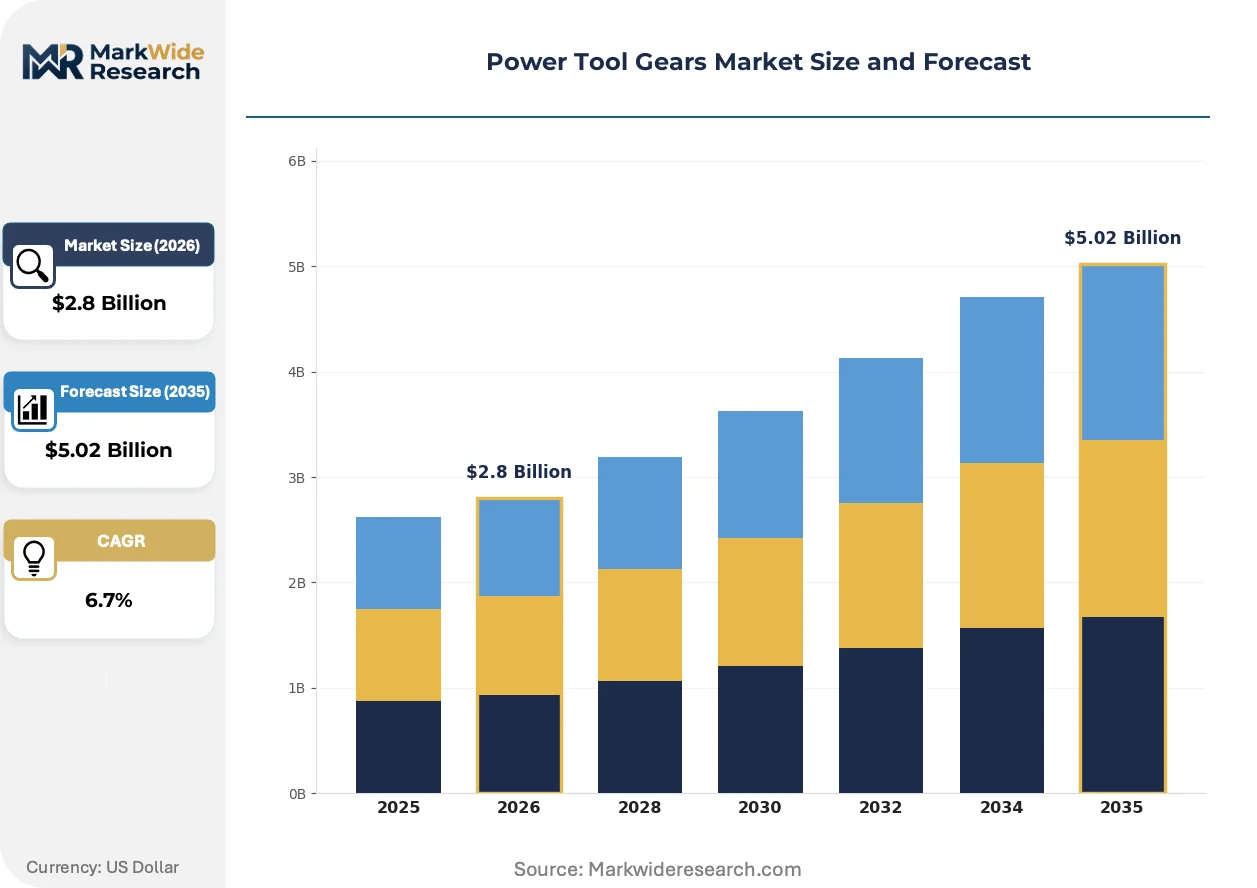
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drives, Gear Sets, Gear Motors, Speed Reducers Material: Steel, Plastic, Aluminum, Composite Application: Construction, Woodworking, Manufacturing, Automotive End User: Contractors, DIY Enthusiasts, Manufacturers, Retailers |
| Companies Covered | Stanley Black & Decker, Bosch Power Tools, Makita Corporation, Hilti Group, Techtronic Industries, Apex Tool Group, Atlas Copco, Emerson Electric, Festool Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Tool Gears Market Emerging Trajectories
Brushless motor architectures and composite material advances are fragmenting traditional gear-set specifications, while regulatory pressure on substance use and energy efficiency compresses design iteration cycles.
Additive manufacturing for gear prototyping is fragmenting traditional tool-and-die development timelines. Tier-one power tool brands now iterate tooth profiles in weeks rather than months. The structural consequence is compressing supplier qualification periods and enabling rapid torque-transmission optimization for platform-specific loads.
REACH substance restrictions on hexavalent chromium surface treatments are forcing European gear manufacturers toward alternative hardening chemistries. ECHA compliance deadlines accelerate process revalidation investments. German and Italian gear producers face compressed certification timelines for automotive-adjacent power tool applications.
Professional contractors now specify gear-set replacement intervals as part of fleet maintenance contracts rather than reactive failure-based purchasing. Tool rental channels and direct-to-crew service models displace traditional distributor parts counters. North American construction management firms drive this behavioral shift through total-cost-of-ownership procurement frameworks.
Power Tool Gears Market Segmentation
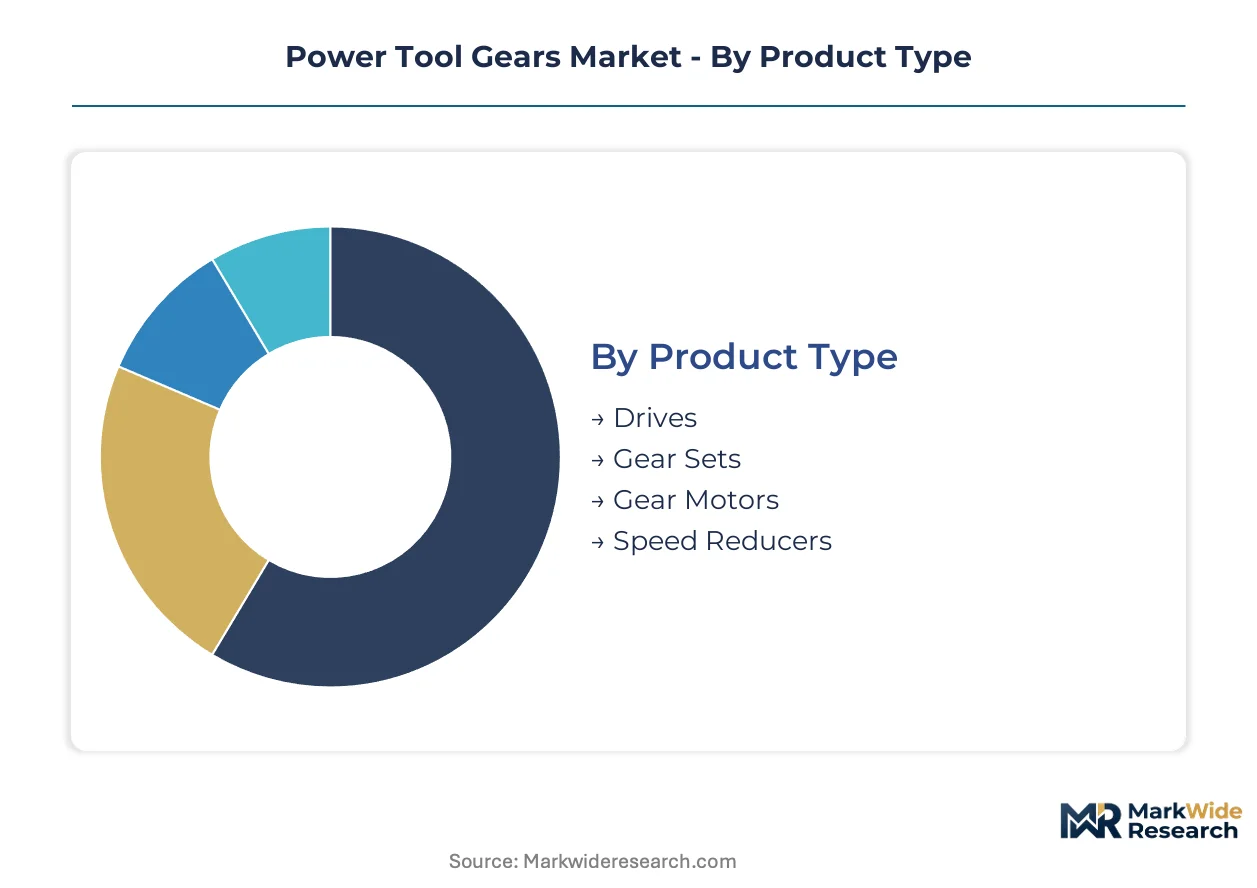
Power tool gear segmentation reveals how torque transmission requirements fragment across voltage platforms, material specifications, and professional versus consumer duty cycles. Each dimension carries distinct margin structures tied to metallurgy complexity, certification overhead, and replacement-part dependency.
Product Type:
Margin pools concentrate in integrated motor-gear assemblies where precision tolerances and thermal management create defensible supplier positions.
- Gear Motors:Combine brushless motor spindles with planetary reduction stages in single housings. Demand concentrates in cordless impact drivers for North American residential construction crews, where battery-platform standardization accelerates replacement-part turnover.
- Speed Reducers:Multi-stage epicyclic or helical configurations manage torque multiplication for high-load rotary hammers. German automotive supplier parks and Japanese metalworking facilities specify these for production-line fastening tools.
- Drives:Compact worm and bevel arrangements transmit power in right-angle configurations for compact drill designs.
- Gear Sets:Modular replacement components service legacy corded platforms and repair channels.
The dominant share belongs to Gear Motors, while Speed Reducers is closing the gap fastest.
Material:
Cost tiers separate commodity-grade suppliers from specialty alloy houses serving brushless motor torque density requirements.
- Steel:Case-hardened alloy grades dominate professional-grade cordless tools. Ningbo and Suzhou manufacturing clusters in China process these for export markets bound by MIIT energy-efficiency directives.
- Composite:Glass-fiber reinforced polymers reduce mass for extended-reach overhead installation tools. Woodworking segments in Italy and Germany specify these for low-vibration finishing applications.
- Aluminum:Die-cast housings and carriers serve mid-tier consumer platforms where weight reduction outweighs wear resistance needs.
- Plastic:Injection-molded gears occupy entry-level drill drivers with intermittent duty cycles.
Steel maintains volume leadership, though Composite materials are gaining share fastest in cordless platform development.
Application:
Customer type determines specification stringency, with professional construction commanding premium hardened grades versus consumer woodworking tolerance bands.
- Construction:Rotary hammers and impact drivers require shock-resistant gearing for masonry and steel fastening. Chinese domestic infrastructure spending and US residential building permits drive specification intensity.
- Automotive:Assembly-line fastening tools demand traceable heat-treatment records and lot-controlled metallurgy for torque audit compliance.
- Woodworking:Cabinet-making and furniture production prioritize low-backlash precision for finish-quality hole placement.
- Manufacturing:General industrial maintenance tools balance cost against mean-time-between-failure targets.
Construction commands the dominant application share, while Automotive specifications are expanding most quickly through EV assembly plant investments.
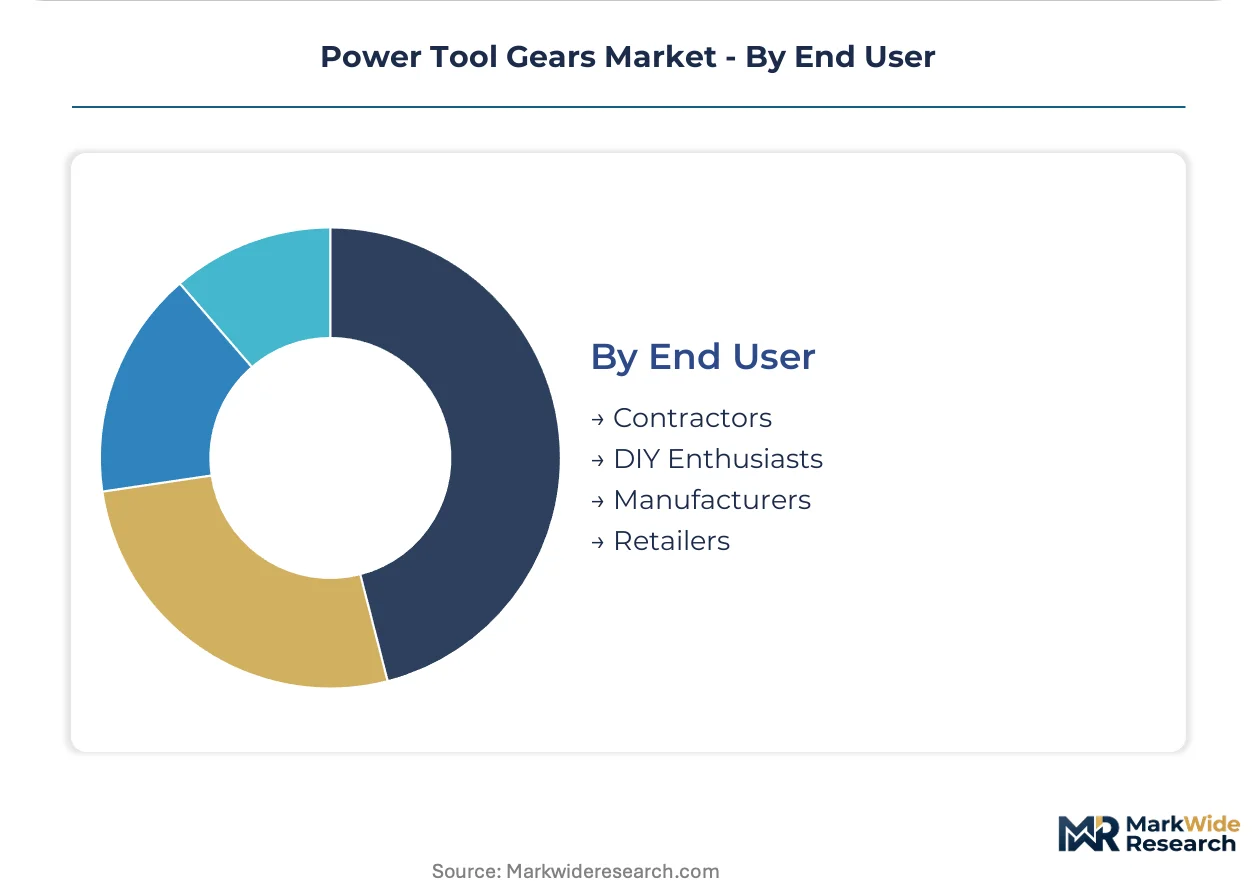
End User:
Procurement patterns bifurcate between fleet-contract professional buyers and price-sensitive retail consumers.
- Contractors:North American construction management firms specify brushless platforms with scheduled gear-set replacement intervals under total-cost-of-ownership frameworks.
- Manufacturers:Industrial tool buyers integrate gear suppliers into preventive maintenance contracts with direct-to-crew service models.
- DIY Enthusiasts:Home improvement retail channels drive volume for entry-level cordless platforms with standardized battery interfaces.
- Retailers:Big-box and e-commerce channels stock replacement gear sets for warranty and post-warranty repair demand.
Contractors generate the dominant revenue concentration, while Manufacturers are shifting procurement fastest toward outcome-based service agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented gear production clusters in China supply cordless platform manufacturers across North America and Europe, while import dependency for case-hardened alloy steins shapes regional cost structures in Germany and the United States. Trade flows concentrate precision-machined components through Ningbo and Suzhou for re-export to Milwaukee and Stuttgart assembly plants.
China
Domestic infrastructure spending and EV assembly plant construction drive brushless motor gear demand across MIIT-regulated manufacturing clusters. GB standards and MIIT energy-efficiency directives constrain transmission efficiency benchmarks for export-bound producers. Ningbo and Suzhou house captive powder metallurgy operations serving Bosch Power Tools and Makita Corporation regional supply requirements.
United States
Residential construction permits and professional contractor fleet standardization on 20V+ platforms accelerate replacement-part turnover for precision gear sets. FCC equipment authorization rules govern electromagnetic compatibility for cordless electronics, indirectly shaping gear-motor integration specifications. Milwaukee and Chicago anchor midwestern distribution hubs for construction-grade tool assembly.
Germany
Automotive assembly-line fastening tools and woodworking precision applications sustain premium-grade hardened gear demand. ECHA REACH substance restrictions constrain hexavalent chromium surface treatments, forcing alternative hardening chemistry revalidation. Stuttgart and Nuremberg supplier parks integrate heat-treatment traceability for torque audit compliance in industrial fastening systems.
Japan
Metalworking facilities and automotive supplier parks specify multi-stage speed reducers for production-line torque multiplication. METI industrial efficiency guidelines influence gear transmission specifications for domestic brushless motor platforms. Nagoya and Osaka host vertically integrated powder metallurgy operations with captive sintered gear capacity.
India
Infrastructure investment and formal manufacturing sector expansion create specification demand for professional-grade cordless platforms. BIS certification pathways for power tool safety standards create compliance requirements for gear suppliers targeting domestic assembly. Maharashtra and Gujarat industrial corridors concentrate import-substitution efforts for case-hardened alloy components.
Power Tool Gears Market Vendor Landscape
Concentration sits with vertically integrated power tool OEMs controlling captive gear production, while mid-tier suppliers face margin compression from alloy steel input volatility. The vendor base stratifies across three tiers: integrated OEM metallurgy operations, independent precision-machining houses, and commodity sintered component suppliers. Dominant competitive moves include backward integration into powder metallurgy capacity and multi-brand portfolio architecture spanning professional and consumer torque categories.
Within the integrated OEM tier, Bosch Power Tools, Makita Corporation, and Stanley Black & Decker exemplify divergent strategic postures. Bosch leverages in-house metallurgy capabilities for heat-treatment consistency. Makita anchors regional supply through captive powder metallurgy in Japan and China. Stanley Black & Decker differentiates via portfolio breadth across professional and consumer segments. These three represent how scale and integration depth separate competitive positions.
| Leading Market Players |
|---|
| Stanley Black & Decker |
| Bosch Power Tools |
| Makita Corporation |
| Hilti Group |
| Techtronic Industries |
| Apex Tool Group |
| Atlas Copco |
| Emerson Electric |
| Festool Group |
| Others |
Supply Flow & Price Mechanics
Ninety-day case-hardened alloy steel inventory cycles in Ningbo and Suzhou manufacturing clusters concentrate pricing leverage among vertically integrated OEMs while exposing mid-tier suppliers to nickel and molybdenum commodity volatility.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across professional-grade cordless platforms. Three-tier pricing structure across premium, standard, and economy levels separates traceable heat-treatment certification grades from commodity sintered alternatives. Cost compression in mid-tier steel alloys is intensifying because REACH substance restrictions force European producers toward alternative hardening chemistry revalidation. DIY retail channels exhibit highest price sensitivity, while automotive assembly-line buyers absorb premium positioning for lot-controlled metallurgy compliance.
Supply Chain Analysis
Ninety-day inventory cycles reflect just-in-time coordination between Chinese powder metallurgy clusters and Milwaukee assembly plants. Supply concentrates in China, Japan, and Germany for case-hardened alloy processing and captive sintered gear capacity. Raw material dependencies include nickel-molybdenum alloy steels, lithium-ion cell cathode materials, and glass-fiber reinforced polymer feedstocks. Single-source vulnerability sits with Japanese powder metallurgy operations serving Makita Corporation regional requirements. Distribution runs through midwestern US hubs and Stuttgart supplier parks for construction-grade and automotive-adjacent applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brushless motor torque density improvements and 20V+ battery-platform standardization are disrupting traditional gear-set specifications faster than legacy suppliers can retool, creating asymmetric opportunity for metallurgy-capable entrants.
For Market Incumbents: Fortify backward integration into powder metallurgy capacity in Ningbo and Suzhou to offset Japanese supply concentration risk. Deepen heat-treatment traceability systems for automotive torque audit compliance. Lock in multi-year alloy steel offtake contracts before nickel volatility escalates. For New Entrants and Emerging Players: Aftermarket service-layer gaps in direct-to-crew replacement part logistics offer white-space entry points. Target Indian BIS certification pathways ahead of enforcement deadlines. Penetrate composite gear segments for extended-reach cordless tools through woodworking precision specifications. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because vertical integration advantages compound as battery-platform voltages escalate. Acquire mid-tier precision-machining houses with dormant heat-treatment capabilities. Monitor MIIT energy-efficiency directive enforcement as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Powder Metallurgy | Captive sintered gear capacity insulates Bosch and Makita from Japanese supply concentration. |
| Composite Material R&D Partnership | Glass-fiber polymer development targets weight reduction for overhead installation cordless tools. |
| BIS Certification Pre-Positioning | Early compliance creates first-mover advantage in Indian power tool safety standard enforcement. |
| Heat-Treatment Traceability Investment | Lot-controlled metallurgy records satisfy automotive assembly-line torque audit requirements. |
| Direct-to-Crew Service Model Launch | Fleet maintenance contracts displace traditional distributor parts counters for contractor segments. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, customs trade databases, and MIIT energy-efficiency directive publications across the analysis window. Interviews with power tool OEM procurement directors, powder metallurgy plant managers, and automotive assembly-line fastening engineers informed transmission efficiency benchmarks. Secondary validation drew from FCC equipment authorization records, ECHA REACH substance restriction updates, and BIS certification pathway documentation. Bottom-up gear shipment data triangulated against top-down cordless platform production estimates.
Segmentation dimensions modeled include product type, material specification, application intensity, and end-user procurement pattern across the projection horizon. CAGRs derive from voltage-platform migration curves and brushless motor adoption rates applied to replacement-part dependency ratios. Forecast inputs incorporate alloy steel price elasticity coefficients and professional contractor fleet standardization timelines.
Forecasts assume regulatory continuity in FCC equipment authorization rules, ECHA REACH restrictions, and MIIT energy-efficiency directives; material policy shifts would require re-modeling transmission efficiency benchmarks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Foam Cutting Machine Market
Tools
Rocket Wrench Market
Tools
Spindle Shaper Market
Tools
Global Swaging Machine Market
Tools
Rebar Cutter Market
Tools
Portable Grinders Market
Tools
Foldable Ladder Market
Tools
Global Cordless Power Tools Market
Tools
Telescopic Tool Boxes Market
Tools
Construction Anchors Market
Tools
Digital Laser Levels Market
Tools
Drilling Tools Market
Tools
Cordless Impact Wrench Market
Tools
Edge Banders Market
Tools
Europe Paint Spray Guns Market
Tools
Multi Wire Cutting Machine Market