
 Floor Pads Market | 2026-2036
Floor Pads Market Size, Share, and Industry Trends Forecast 2026-2036
Floor Pads Market Analytics
North American nonwoven producers is expanding bonded abrasive capacity to serve institutional buyers with shorter lead times. 3M Co. leverages its materials science portfolio across multiple pad grades for healthcare and education end users. Americo Manufacturing Co. anchors its position through captive fiber processing and regional distribution density. Diversey Holdings Ltd. competes by bundling pads with chemical dispensing systems in janitorial supply contracts.
Floor pads are engineered nonwoven or woven abrasive substrates, typically 12–21 inches in diameter with thickness ranging from 3/4 inch to 1 inch, designed to strip, scrub, buff, polish, or burnish resilient and non-resilient floor surfaces through rotational friction. Polyester-based pads dominate volume due to uniform fiber distribution and chemical resistance in alkaline cleaning environments, while natural fiber variants retain niche positions in facilities pursuing green procurement certifications. Scrubbing pads command the largest revenue pool across industrial cleaning applications where aggressive soil removal justifies premium unit pricing, whereas burnishing pads represent the fastest-expanding category as high-speed propane and battery-powered equipment penetrates retail and hospitality maintenance programs.
OSHA slip-resistance standards for commercial walking surfaces and EPA guidelines on volatile organic compound emissions from floor care chemicals constrain product formulation and pad-chemical pairing requirements. The EU Ecodesign framework and California Air Resources Board protocols on equipment emissions indirectly shape pad specifications through machine compatibility mandates. Stakeholders must monitor evolving state-level chemical disclosure rules and third-party sustainability certifications that determine qualification for municipal and federal procurement contracts.
Market Dynamics
Facility managers across commercial cleaning operations are consolidating pad procurement into fewer SKUs that satisfy multiple surface protocols, compressing supplier margins while elevating performance certification requirements as the primary selection filter.
Growth Catalysts
- EU REACH chemical disclosure mandates:Manufacturers reformulating synthetic fiber binders toward bio-based alternatives unlock premium positioning in institutional procurement channels.
- Propane burnisher equipment penetration:High-speed propane systems in retail and hospitality maintenance programs accelerate replacement cycles for specialized burnishing pads.
- Automotive surface protocols:German automotive and aerospace facilities enforce stringent floor cleanliness standards that drive systematic pad replacement schedules.
Market Restraints
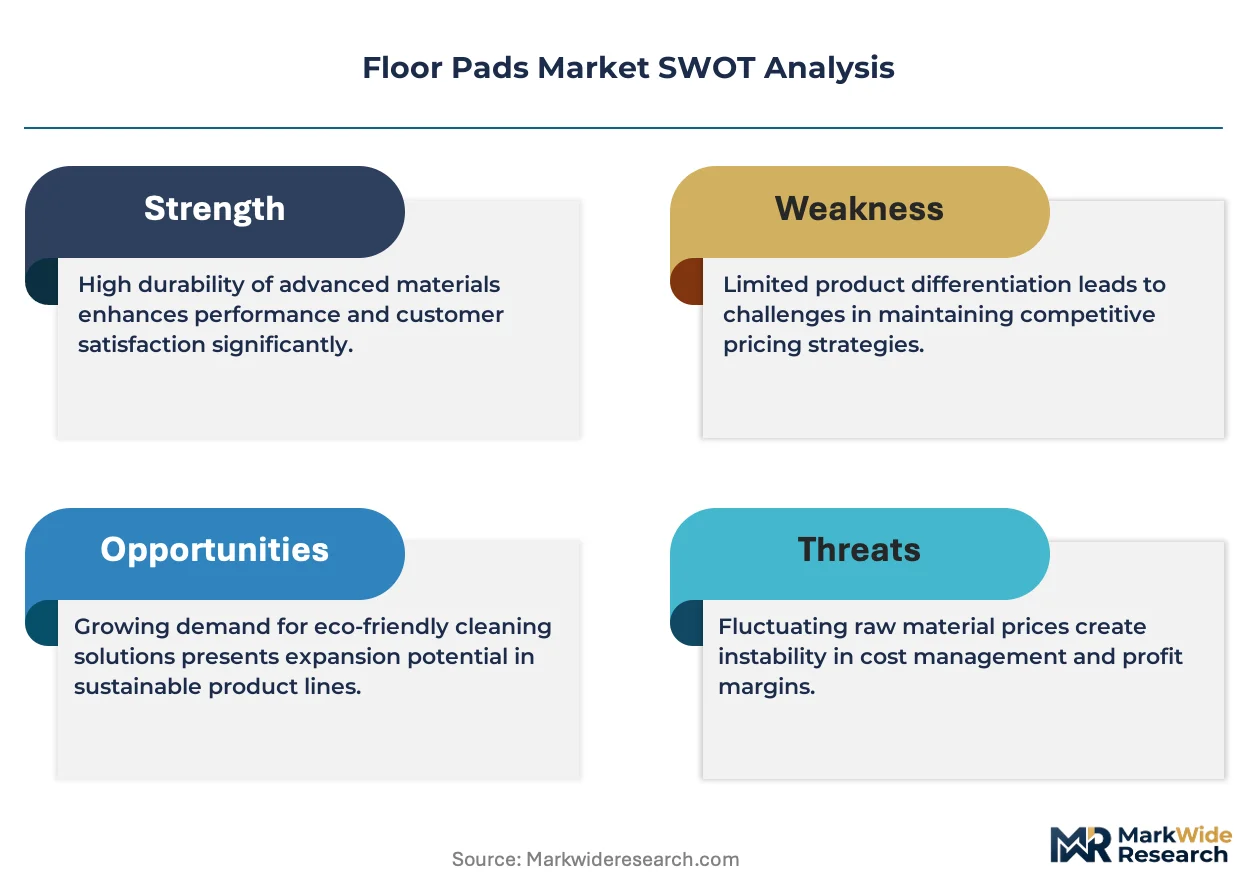
- Petrochemical feedstock volatility:Polyester resin prices fluctuate with crude oil benchmarks, compressing gross margins for nonwoven pad producers.
- Captive fiber processing concentration:Regional producers with backward-integrated fiber operations control cost structures that independent converters cannot replicate.
- Alkaline chemical compatibility limits:Natural fiber variants degrade in high-pH cleaning environments, restricting their addressable market share.
Strategic Opportunities
- California Safer Consumer Products compliance:Early alignment with chemical disclosure rules secures qualification for municipal and state procurement contracts.
- Battery-powered equipment convergence:Integration of lithium-ion battery systems with pad diagnostics creates predictive replacement service models.
- Green procurement certification tailwinds:LEED and BREEAM building standards elevate demand for recyclable and bio-based pad substrates.
Industry Challenges
- OSHA slip-resistance testing protocols:Facilities must validate pad-chemical combinations against walking-surface friction standards, extending sales cycles.
- Legacy equipment retrofit complexity:Older rotary machines lack standardized pad attachment mechanisms, forcing distributors to maintain obsolete inventory.
- Fiber engineering talent scarcity:Specialized knowledge in abrasive nonwoven construction concentrates at a handful of regional manufacturing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Floor Pads Market |
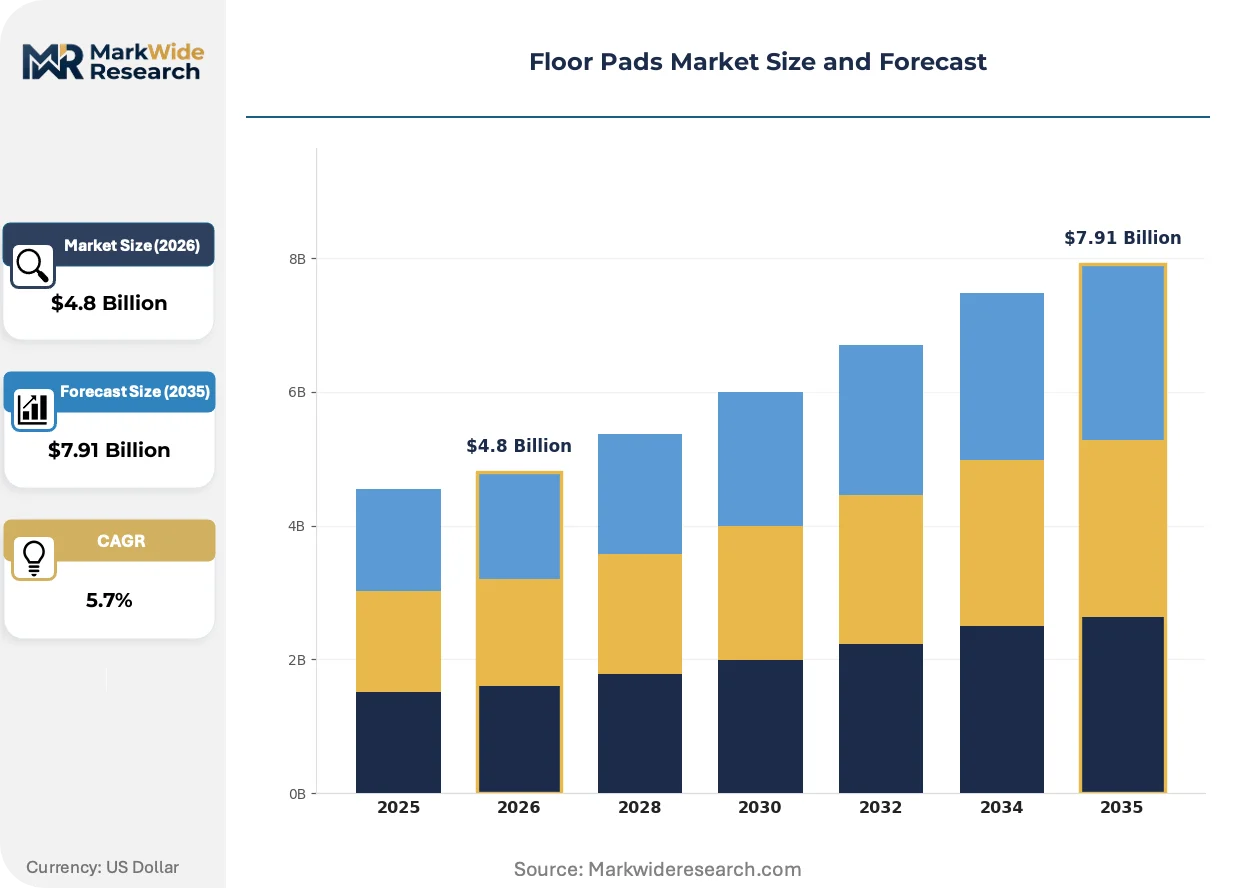
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scrubbing Pads, Buffing Pads, Polishing Pads, Burnishing Pads Material: Polyester, Natural Fiber, Nylon, Foam Application: Industrial Cleaning, Household Use, Commercial Cleaning, Maintenance Distribution Channel: Wholesale, Retail, Online, Direct Sales |
| Companies Covered | 3M Co., Americo Manufacturing Co., Jon Don LLC, ETC of Henderson Inc., Janex Inc., Bona AB, Diversey Holdings Ltd., Electrolux AB, Saint Gobain, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Floor Pads Market Evolving Landscape
Material science advances and regulatory disclosure requirements are converging to reshape how floor pads are specified, procured, and replaced across institutional cleaning operations.
Embedded RFID tagging in pad substrates is modularizing inventory tracking and usage monitoring for large facility networks. Healthcare systems and university campuses with distributed building footprints deploy these smart pads to automate reorder triggers and validate warranty claims. This technology is modularizing the traditional distributor relationship from product supply into integrated facility data services.
California Air Resources Board protocols on equipment emissions indirectly constrain pad specifications through machine compatibility mandates. Propane burnisher manufacturers must demonstrate emission compliance, which filters down to pad diameter, density, and friction coefficients that optimize engine load profiles. Premium pad grades certified for high-speed propane equipment capture disproportionate margin in California and states adopting similar emission frameworks.
Janitorial supply contracts are unbundling pad procurement from bundled chemical-dispensing system agreements. Large commercial cleaning contractors now negotiate pad volumes separately from chemical pricing, enabling direct relationships with specialized nonwoven producers. This pattern concentrates in the United States where facility management outsourcing has matured and procurement functions have centralized at national account levels.
Floor Pads Market Segmentation
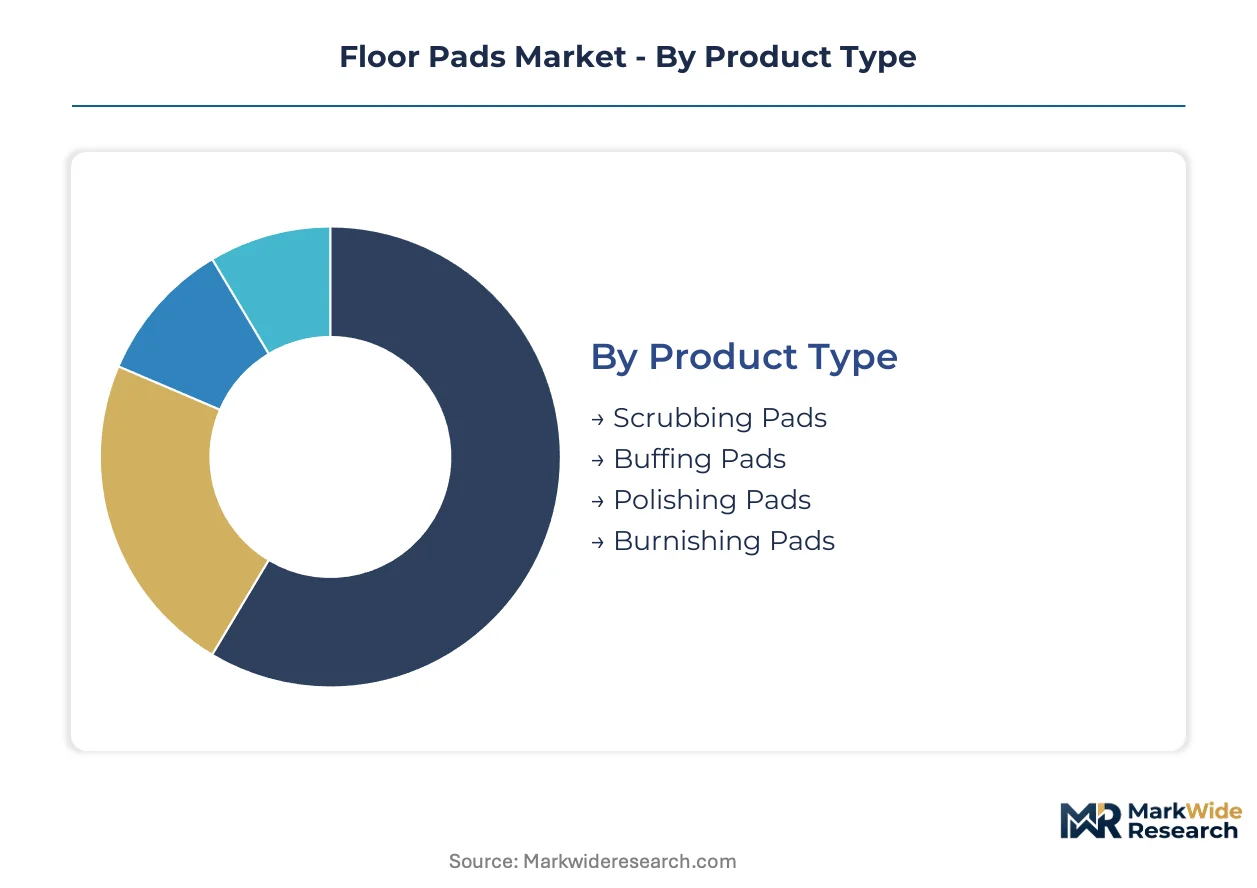
Floor pad procurement patterns diverge sharply across end-use environments, with industrial buyers prioritizing abrasive longevity while retail channels emphasize SKU consolidation. Material selection and distribution access determine supplier margins more than brand recognition in this specification-driven category.
Product Type:
Capital intensity concentrates in burnishing and scrubbing pad lines, where specialized fiber bonding equipment and density calibration systems require seven-figure upfront investment.
- Scrubbing Pads:Aggressive abrasive substrates engineered for soil removal on resilient surfaces like vinyl composition tile and sealed concrete. Demand clusters in automotive manufacturing facilities across Germany's industrial corridor, where contamination protocols mandate systematic replacement cycles.
- Burnishing Pads:High-density nonwoven constructions optimized for propane and battery-powered equipment operating at 1500+ RPM. Retail and hospitality maintenance programs in California drive the steepest expansion trajectory as CARB-compliant equipment penetration accelerates.
- Buffing Pads:Medium-abrasion grades for routine maintenance between deep-clean cycles.
- Polishing Pads:Fine-fiber finishes for final surface gloss restoration in healthcare and education settings.
Most installed capacity flows through scrubbing pads. Expansion is steepest in burnishing pads.
Material:
Raw material cost tiers separate polyester commodity production from specialty fiber alternatives that command specification premiums.
- Polyester:Dominant volume substrate formed from polyethylene terephthalate fibers with uniform denier distribution and resistance to alkaline cleaning chemistry. Commercial cleaning contractors in the United States specify polyester for standard maintenance programs where chemical compatibility outweighs sustainability credentials.
- Natural Fiber:Cellulose and bast fiber constructions targeting LEED and BREEAM procurement channels. EU REACH compliance costs constrain European production scale, limiting addressable market despite green certification tailwinds.
- Nylon:Polyamide variants offering superior abrasion resistance for high-traffic airport and transit facility applications.
- Foam:Reticulated polyurethane structures for delicate surface restoration in museum and heritage building contexts.
Polyester absorbs the majority of production volume. Natural fiber is gaining share fastest in municipal procurement channels.
Application:
Customer scale and contract structure determine which application segments support dedicated salesforce coverage versus distributor intermediation.
- Industrial Cleaning:High-volume pad consumption in manufacturing, warehousing, and logistics facilities with centralized procurement functions. German automotive OEMs enforce surface cleanliness standards that drive systematic replacement schedules and premium grade specification.
- Commercial Cleaning:Third-party janitorial contractors managing multi-site facility portfolios. National account consolidation in the United States compresses supplier margins while elevating performance certification requirements as primary selection filters.
- Household Use:Consumer retail channels with price-sensitive demand and minimal technical specification.
- Maintenance:In-house facility management operations with hybrid procurement of pads and associated floor care chemicals.
Industrial cleaning channels generate the highest revenue per account. Commercial cleaning is expanding most quickly as facility management outsourcing matures.
Distribution Channel:
Channel economics favor wholesale and direct models where volume concentration justifies inventory carrying costs and technical sales support.
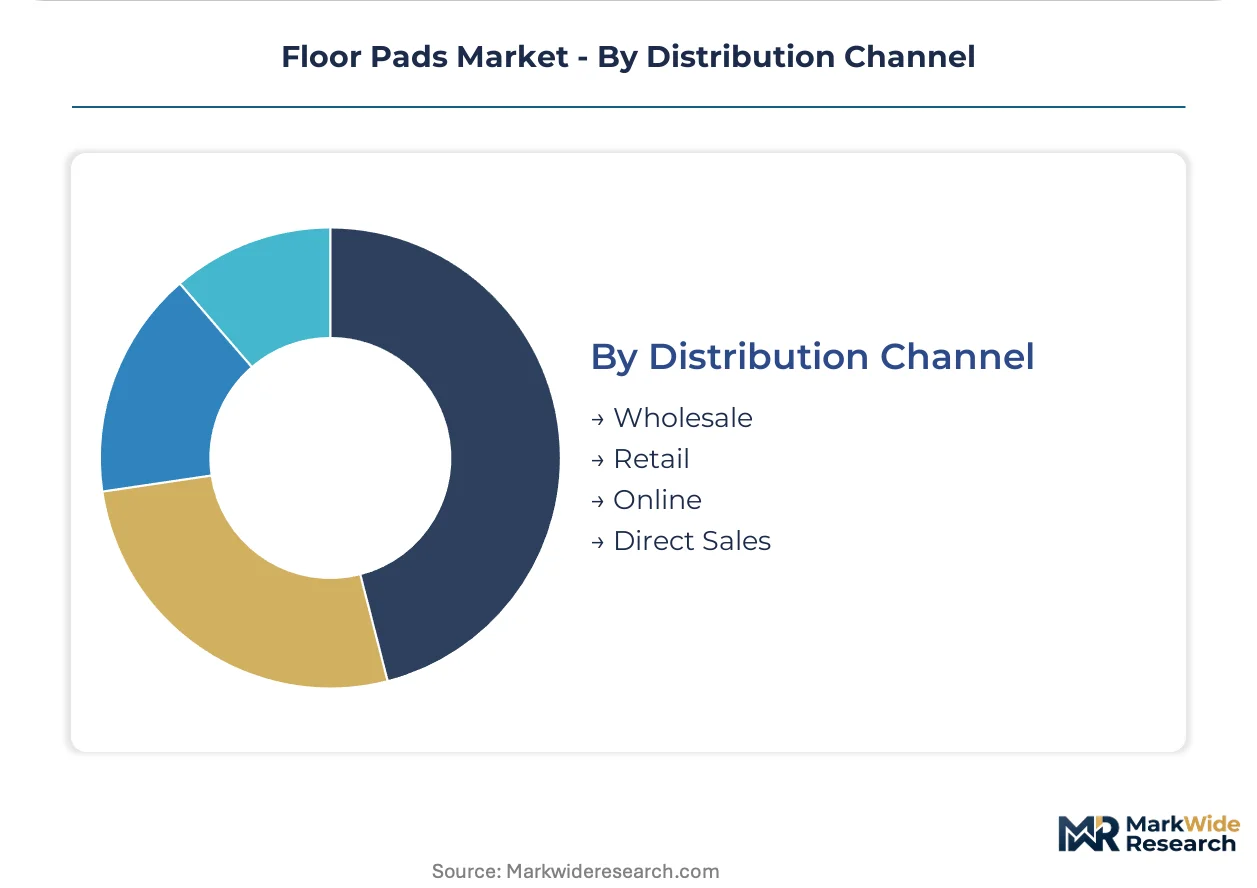
- Wholesale:Janitorial supply distributors serving regional contractor networks with consolidated chemical and pad procurement. Diversey Holdings and comparable bundling strategies concentrate volume through this channel.
- Direct Sales:National account relationships with healthcare systems, university campuses, and retail chains requiring embedded RFID inventory tracking and predictive replenishment services.
- Retail:Big-box and specialty store placements for household and light commercial segments.
- Online:E-commerce penetration remains limited by the specification complexity and equipment compatibility validation requirements that favor technical sales consultation.
Wholesale channels handle the majority of institutional volume. Direct sales is climbing the fastest as large facility networks consolidate procurement functions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping where floor pad production concentrates, with manufacturers migrating toward jurisdictions offering lower compliance costs for synthetic fiber processing while maintaining proximity to end-use clusters.
United States
Commercial cleaning contractors in California and the industrial Midwest drive replacement pad demand through systematic facility management programs. EPA guidelines on volatile organic compound emissions from floor care chemicals constrain product formulation requirements. The Los Angeles Basin hosts concentrated distribution networks serving retail and hospitality maintenance programs with CARB-compliant propane burnisher equipment.
Germany
Automotive OEMs and aerospace facilities in the industrial corridor enforce contamination protocols that mandate premium pad replacement cycles. EU REACH chemical disclosure mandates on synthetic fiber binders elevate compliance costs for domestic producers. Stuttgart and Wolfsburg anchor specialized procurement relationships with pad suppliers certified for cleanroom-grade surface protocols.
China
Rapid facility modernization across manufacturing zones generates volume demand for standard-grade polyester pads in warehousing and logistics applications. The country's national environmental regulator imposes emission controls on nonwoven production facilities that favor larger integrated producers. The Yangtze River Delta concentrates bonded abrasive capacity serving both domestic institutional buyers and export markets.
India
Facility management outsourcing in commercial real estate creates emerging demand for SKU-consolidated pad procurement. Bureau of Indian Standards certification requirements for imported synthetic fiber products shape supplier qualification processes. Maharashtra and Karnataka host early procurement centralization among IT park operators and hospital networks.
United Kingdom
Healthcare systems and university campuses deploy embedded RFID inventory tracking for distributed building portfolios. The Health and Safety Executive enforces slip-resistance testing protocols for commercial walking surfaces that validate pad-chemical combinations. The Southeast and Midlands concentrate national account procurement functions that negotiate direct relationships with specialized nonwoven producers.
Floor Pads Market Competitive Landscape
United States producers anchor the premium tier through materials science integration and captive fiber processing; European specialists hold specification-driven positions in automotive and aerospace channels. The vendor base stratifies across three tiers: multinational conglomerates with diversified materials portfolios, regional converters with backward-integrated fiber operations, and specialized distributors bundling pads with chemical systems. Dominant competitive moves include strategic partnerships with propane burnisher equipment manufacturers and geographic expansion through janitorial supply distributor networks.
Among Minnesota-based materials conglomerates, 3M Co. exemplifies the science-driven archetype that leverages cross-divisional technology portfolios. Americo Manufacturing Co. and Diversey Holdings Ltd. represent contrasting strategic positions—the former through regional distribution density and fiber processing integration, the latter through bundled chemical dispensing contracts with institutional buyers. These three anchors illustrate how competitive advantage in floor pads derives from control over either upstream material inputs or downstream procurement relationships rather than brand recognition alone.
| Leading Market Players |
|---|
| 3M Co. |
| Americo Manufacturing Co. |
| Jon Don LLC |
| ETC of Henderson Inc. |
| Janex Inc. |
| Bona AB |
| Diversey Holdings Ltd. |
| Electrolux AB |
| Saint Gobain |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between CARB-compliant burnishing pads and standard polyester grades manifests in both margin capture and upstream fiber sourcing strategies. Premium pad specifications tethered to California Air Resources Board equipment mandates command material premiums through specialized density calibration, while commodity scrubbing pads compete on petrochemical feedstock efficiency and regional distribution density.
Pricing Analysis
Distributor margin layering separates janitorial supply bundlers from direct-to-facility national accounts. Three-tier pricing structure across premium, standard, and economy levels reflects certification investment differential and equipment compatibility validation. Cost compression in commodity polyester grades intensifies because independent converters lack backward-integrated fiber operations. National commercial cleaning contractors exhibit lowest price sensitivity due to consolidated procurement functions, while regional retail channels remain most exposed to spot resin fluctuations.
Supply Chain Analysis
Polyester resin supply rests on integrated petrochemical complexes in China, the United States, and Germany. Synthetic fiber production draws from purified terephthalic acid and monoethylene glycol feedstocks, with specialized binder chemistry concentrated among European specialty chemical producers. Single-source vulnerability concentrates in high-denier fiber bonding equipment manufacturing. Distribution runs through janitorial supply wholesalers serving regional contractor networks with consolidated chemical and pad procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunity concentrates in predictive replacement service models and bio-based fiber certification premiums. SKU consolidation by facility managers compresses commodity tier returns while elevating performance-validated grade positioning.
For Market Incumbents: Anticipate battery-powered equipment convergence by embedding RFID diagnostics into pad substrates for automated inventory triggers. Deepen captive fiber processing control to defend margin position against resin price volatility. Prioritize California Safer Consumer Products pre-certification to secure municipal procurement lock-in before disclosure rules harden.
For New Entrants and Emerging Players: Janitorial supply distributors with fragmented regional coverage represent the most accessible channel partnership archetype. Target India's emerging facility management outsourcing clusters in Maharashtra and Karnataka where procurement centralization lags established markets. Lead with LEED-compliant natural fiber positioning to capture green certification tailwinds in European municipal channels.
For Investors and Strategic Acquirers: Consolidation pressure builds where backward-integrated fiber operations face generational ownership transition without succession planning. Long-term viability favors regional converters with captive resin processing and established automotive OEM certification relationships. Watch battery-powered burnisher equipment penetration rates as the inflection signal for predictive service model valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Processing | Captive resin operations insulate margin from petrochemical volatility in polyester pad production. |
| RFID-Enabled Predictive Replacement Service | Embedded tagging transforms distributor relationships into integrated facility data contracts with healthcare systems. |
| California SCP Pre-Certification Investment | Early alignment secures qualification for state and municipal procurement contracts before compliance deadlines. |
| Natural Fiber Green Certification Pivot | Cellulose and bast fiber constructions unlock LEED and BREEAM procurement channels in European institutional buyers. |
| Direct National Account Relationship Development | Bypassing janitorial supply bundlers captures margin from centralized procurement functions at retail chains and university campuses. |
Research Methodology
Direct dialogue with facility managers, commercial cleaning contractors, janitorial supply distributors, nonwoven manufacturing engineers, and automotive OEM surface protocol specialists grounded qualitative findings. Secondary validation drew from EPA emission guideline documents, California Air Resources Board equipment compliance filings, EU REACH chemical disclosure registers, and trade association production surveys. Bottom-up volume estimates triangulated against top-down facility square footage and replacement cycle assumptions.
Top-down market sizing assessed total addressable floor surface area across institutional segments applied to equipment penetration and pad replacement frequency norms. Segmentation modeling tracked product type, material substrate, application environment, and distribution channel across the projection horizon. CAGR derivation incorporated historical resin price elasticity, regulatory compliance cost trajectories, and equipment technology substitution patterns.
Revisions become necessary when propane burnisher emission standards tighten beyond current CARB baselines or when bio-based binder chemistry achieves cost parity with synthetic alternatives. Forecasts reflect documented assumptions on equipment replacement cycles and fiber processing capacity expansion timelines. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Handheld Engraving Machine Market
Tools
Global Construction Camera Market
Tools
Portable Grinders Market
Tools
China Power Tools and Hand Tools Market
Tools
Rebar Cutter Market
Tools
Cold and Hot Tool Steel Market
Tools
Painting Tools Market
Tools
Indexable Tool Inserts Market
Tools
Tool Storage Market
Tools
Edge Banders Market
Tools
US Power Tools Market
Tools
China Power Tools Market
Tools
Level Floats Market
Tools
Woodworking Circular Saw Blades Market
Tools
Flooring Tools Market
Tools
Pliers Market