
 India Extreme Ultraviolet Lithography (EUVL) Systems Market | 2026-2036
India Extreme Ultraviolet Lithography (EUVL) Systems Market Size, Share, and Industry Trends Forecast 2026-2036
India Extreme Ultraviolet Lithography (EUVL) Systems Market Insights
Multi-source procurement for critical EUVL subsystems is decoupling from the single-vendor dependencies that historically constrained Indian fab projects. ASML anchors the lithography stack through its scanner monopoly, while ZEISS Group sustains the optical supply chain with its specialized mirror and lens systems. Samsung Electronics competes indirectly by driving foundry process roadmaps that dictate EUVL specification requirements for equipment vendors serving India.
Extreme Ultraviolet Lithography Systems deploy thirteen-point-five-nanometer wavelength light generated by laser-produced plasma sources to pattern sub-seven-nanometer semiconductor features with single-exposure resolution. The technology serves the primary commercial purpose of enabling transistor scaling at nodes where traditional deep-ultraviolet lithography reaches physical resolution limits. Light sources command the highest capital intensity within the product type split due to their plasma generation complexity and source power requirements. Semiconductor foundries represent the dominant end user category, absorbing the bulk of system shipments as India builds out indigenous logic and memory fabrication capacity.
BIS standards alignment and CDSCO-equivalent equipment safety certifications shape import clearance timelines for EUVL tools entering Indian facilities. The PLI scheme administered by MeitY and the Ministry of Electronics and Information Technology directly subsidizes capital expenditure for domestic semiconductor manufacturing, altering project economics for EUVL procurement decisions. Stakeholders must track how India's Semiconductor Mission revises eligibility thresholds for advanced node incentives against actual tool delivery schedules.
Market Dynamics
The PLI scheme administered by MeitY is restructuring capital allocation timelines for domestic semiconductor fabrication, compressing the interval between equipment procurement decisions and actual tool commissioning at greenfield sites in Gujarat and Karnataka.
Growth Catalysts
- Semiconductor Mission incentives:The PLI scheme subsidizes capital expenditure for advanced node manufacturing, directly improving project returns for EUVL-equipped fabs.
- Sub-seven-nanometer process roadmaps:Logic and memory foundries require EUVL resolution capabilities that deep-ultraviolet lithography cannot deliver at single-exposure throughput.
- Gujarat Dholera cluster development:Dedicated semiconductor infrastructure zones aggregate power, water, and logistics capacity that EUVL tools require for stable operation.
Market Restraints
- Single-source lithography scanner dependency:EUVL scanner production concentrates with one Netherlands-based equipment supplier, creating delivery queue risk for Indian projects.
- Zeolite-based hydrogen purifier input costs:Laser-produced plasma sources require ultra-high-purity hydrogen that fluctuates with rare earth processing capacity.
- BIS technical standards misalignment:Indian equipment safety certifications for vacuum and laser systems diverge from SEMI S2 international benchmarks, extending import clearance timelines.
Strategic Opportunities
- Karnataka Mysuru corridor underutilization:Existing precision manufacturing clusters can absorb EUVL subsystem assembly and testing operations with targeted skill development.
- Photomask repair service localization:EUVL mask defect inspection and repair capabilities represent a gap that domestic engineering services can fill.
- CDSCO-adjacent equipment qualification pathways:Streamlined safety certification routes for semiconductor process tools can accelerate subsequent EUVL tool import cycles.
Industry Challenges
- Plasma physics specialist scarcity:Laser-produced plasma source operation and maintenance require expertise that Indian technical institutes have not yet scaled.
- Cleanroom capex sequencing:EUVL tools require Class 1 wafer environment completion before installation, forcing capital lock-up during construction delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Extreme Ultraviolet Lithography (EUVL) Systems Market |
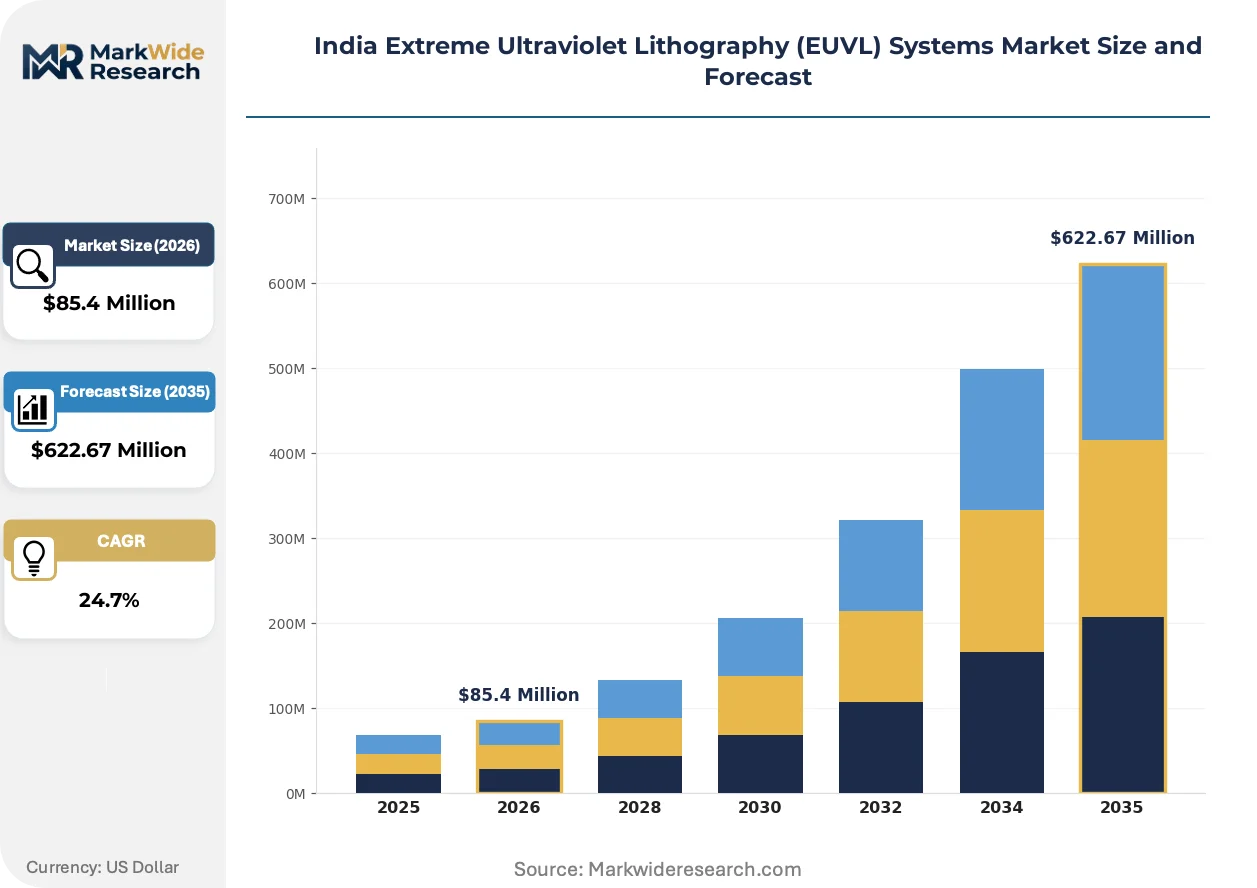
| Market Size in 2026 | $85.4 Million |
| Market Size in 2035 | $622.67 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mask/Etch Equipment, Wafer Handling, Light Sources, Measurement Systems Technology: Digital Lithography, Optical Lithography, Nanoimprint, Extreme Ultraviolet End User: Semiconductor Foundries, Research Institutions, Specialty Component Manufacturers, Electronics Manufacturers Application: Integrated Circuits, MEMS Devices, Photonics, Sensors |
| Companies Covered | Samsung Electronics, Micron Technology, ASML, GlobalFoundries, Taiwan Semiconductor Manufacturing Company, Nikon, Intel, ZEISS Group, Canon, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Extreme Ultraviolet Lithography (EUVL) Systems Market Trends and Innovations
Plasma source power scaling and optical system thermal management are compressing cost-per-wafer metrics for EUVL patterning, while policy frameworks restructure how Indian fabs finance and source these tools.
High-NA EUVL optics is consolidating next-generation lithography roadmaps for sub-three-nanometer transistor geometries. Semiconductor foundries in India are positioning for this transition by specifying scanner compatibility with 0.55 numerical aperture configurations in current procurement. The technology is consolidating supplier relationships around integrated optical-mechanical-electrical subsystems rather than discrete component sourcing.
India's Semiconductor Mission is revising PLI eligibility thresholds to link incentive disbursement with actual wafer start dates rather than equipment import milestones. This policy shift forces project developers to accelerate construction and commissioning timelines. Foundry operators in Gujarat and Karnataka are responding by pre-qualifying contractors and pre-ordering long-lead mechanical and electrical infrastructure.
After-sales service unbundling is fragmenting traditional equipment vendor relationships in the Indian market. Foundry operators are negotiating separate contracts for EUVL scanner maintenance, light source refurbishment, and optical component cleaning. This pattern is most visible at greenfield sites where operators seek to localize tier-two and tier-three support functions to reduce total cost of ownership.
India Extreme Ultraviolet Lithography (EUVL) Systems Market Segmentation
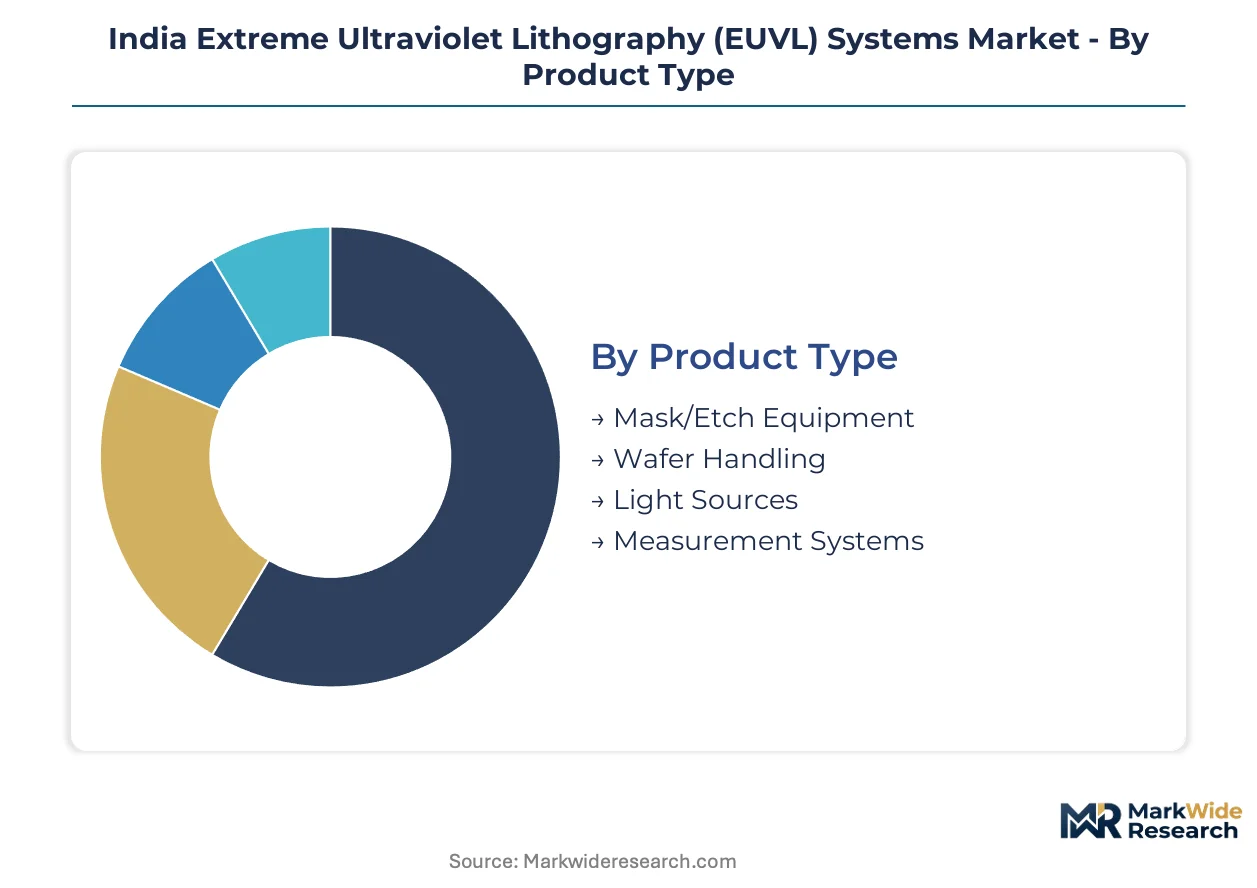
EUVL procurement in India follows distinct technical and economic logics across product categories, technology generations, and end-user capabilities. Understanding these segment boundaries clarifies where capital concentrates and where supply constraints bite hardest.
Product Type:
Capital allocation intensity drives purchasing priority, with subsystems commanding the largest share of fab equipment budgets receiving earliest procurement authorization.
- Light Sources:Laser-produced plasma systems generate thirteen-point-five-nanometer wavelength radiation through tin droplet excitation, requiring source power above six hundred watts for commercial throughput. Demand concentrates at Gujarat Dholera and Karnataka Mysuru greenfield sites where foundry operators prioritize source power stability over cost minimization to meet process roadmaps.
- Mask/Etch Equipment:EUV-specific photomask patterning and plasma etching tools process multilayer reflective blanks with sub-nanometer defect tolerance. Karnataka precision manufacturing clusters absorb the bulk of mask equipment demand as domestic engineering services expand into EUVL blank inspection and repair.
- Wafer Handling:Vacuum-compatible robotic systems transport wafers between scanner, source, and metrology stations under Class 1 environmental conditions.
- Measurement Systems:Scatterometry and electron-beam inspection tools verify pattern fidelity at resolutions below seven nanometers.
Light sources lead on scale; mask equipment leads on momentum as domestic service capabilities mature.
Technology:
Process node requirements determine technology selection, with single-exposure resolution limits forcing migration decisions at specific transistor geometry thresholds.
- Extreme Ultraviolet:Thirteen-point-five-nanometer wavelength patterning enables sub-seven-nanometer features without multiple patterning overlays. Semiconductor foundries in Gujarat specify EUVL exclusively for logic nodes at five nanometers and below, driven by PLI scheme incentives tied to advanced process technology.
- Optical Lithography:One-ninety-three-nanometer deep-ultraviolet systems with immersion extensions serve mature node production where resolution requirements permit. Specialty component manufacturers in India retain optical lithography for analog and power semiconductor fabrication where transistor density constraints relax.
- Digital Lithography:Maskless direct-write systems pattern low-volume prototypes and research wafers without photomask fabrication lead times.
- Nanoimprint:Mechanical pattern replication serves photonics and MEMS applications where feature sizes exceed EUVL resolution advantages.
Extreme ultraviolet dominates capital deployment; optical lithography retains the broadest installed base across process nodes.
End User:
Technical sophistication and capital access separate end-user categories, with fabrication scale determining EUVL procurement feasibility.
- Semiconductor Foundries:Merchant and captive logic or memory manufacturers operate at wafer volumes justifying EUVL capital intensity. Gujarat Dholera cluster developers represent the primary demand concentration as India's Semiconductor Mission prioritizes indigenous foundry capacity.
- Research Institutions:IIT Bombay and IISc Bangalore maintain EUVL access through consortium arrangements and shared facilities rather than dedicated tool ownership.
- Specialty Component Manufacturers:Analog, discrete, and power semiconductor producers lack process roadmaps requiring EUVL resolution.
- Electronics Manufacturers:System-level assemblers and packaging houses operate downstream of EUVL patterning stages.
Semiconductor foundries lead on scale; research institutions lead on technology access experimentation.
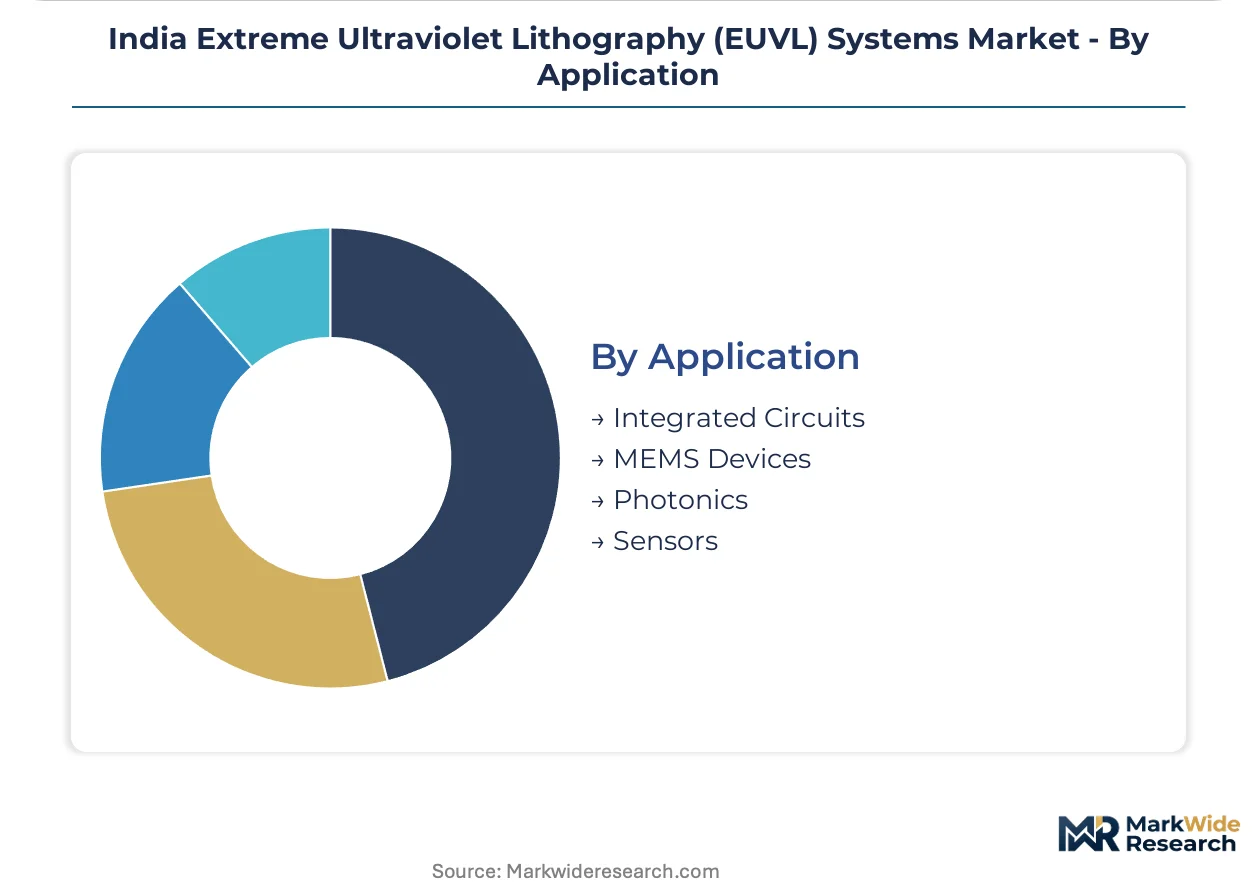
Application:
Device physics and economic value per wafer shape application prioritization, with highest-margin products commanding earliest EUVL allocation.
- Integrated Circuits:Logic processors and memory arrays at five-nanometer nodes and below generate revenue premiums sufficient to amortize EUVL equipment costs. Foundry operators in Karnataka target integrated circuit production for export markets where advanced node premiums persist.
- Photonics:Silicon photonics and optical interconnect devices leverage EUVL precision for waveguide and coupler geometries. Research demand from IISc photonics programs drives limited EUVL access for photonics prototyping.
- MEMS Devices:Micro-electromechanical systems typically exceed EUVL resolution requirements; deep-ultraviolet patterning suffices.
- Sensors:Image sensors and environmental detectors at mature nodes do not justify EUVL capital deployment.
Integrated circuits lead on scale; photonics leads on emerging application expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dholera Special Investment Region anchors India's EUVL demand concentration through its dedicated semiconductor fabrication zone. The Gujarat cluster aggregates power infrastructure and logistics capacity that EUVL tools require for stable plasma source operation. Karnataka and Telangana compete for secondary concentration through precision manufacturing corridors.
Gujarat
Dholera SIR hosts the country's first indigenous EUVL-equipped fab with dedicated hydrogen supply infrastructure for laser-produced plasma sources. MeitY's PLI scheme disburses capital subsidies contingent on wafer start milestones rather than equipment import dates. Ahmedabad-based engineering contractors pre-qualify for cleanroom construction sequencing that EUVL tools demand.
Karnataka
Mysuru precision manufacturing clusters absorb mask equipment demand as domestic blank inspection capabilities expand. CDSCO-equivalent safety certification pathways for vacuum systems accelerate import clearance timelines at Bengaluru International Airport cargo terminals. IISc Bangalore maintains EUVL research access through consortium arrangements with merchant foundries.
Telangana
Hyderabad's electronics manufacturing zone attracts EUVL subsystem assembly operations targeting reduced total cost of ownership. The state's semiconductor policy offers additional capital incentives atop central PLI scheme benefits. Fab City infrastructure reserves utility capacity for future EUVL-equipped logic fabrication.
Tamil Nadu
Sriperumbudur electronics corridor specializes in mature node equipment where EUVL resolution advantages do not justify capital deployment. BIS standards alignment for deep-ultraviolet lithography tools creates certification precedent that EUVL importers reference. Chennai port infrastructure handles non-EUVL semiconductor equipment at scale.
Maharashtra
Mumbai-Pune industrial belt concentrates on photonics and MEMS applications where nanoimprint lithography competes with EUVL for patterning precision. The state's technical universities develop plasma physics curricula addressing specialist scarcity for laser-produced source maintenance. Thane precision component suppliers feed into Karnataka and Gujarat fab construction.
India Extreme Ultraviolet Lithography (EUVL) Systems Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue subsystem localization partnerships with Indian project developers. The market structure concentrates around lithography scanner supply, with optical component and light source specialists occupying adjacent positions. Three archetypes dominate: integrated scanner-lithography platforms, precision optical subsystem suppliers, and foundry operators dictating specification requirements. Competitive moves center on pre-qualification contracting for greenfield sites and after-sales service unbundling to reduce operator total cost of ownership.
Within the integrated platform tier, ASML and Nikon represent the scanner supply concentration that Indian fabs navigate through delivery queue management. ZEISS Group exemplifies the optical subsystem archetype, supplying specialized mirror and lens systems that EUVL resolution demands. Samsung Electronics occupies a foundry-operator position, driving process roadmaps that shape equipment specifications for vendors serving Indian projects. Each entity represents a distinct competitive vector rather than direct substitution rivalry.
| Leading Market Players |
|---|
| Samsung Electronics |
| Micron Technology |
| ASML |
| GlobalFoundries |
| Taiwan Semiconductor Manufacturing Company |
| Nikon |
| Intel |
| ZEISS Group |
| Canon |
| Others |
Pricing and Supply Chain Analysis
High-NA EUVL optics adoption simultaneously compresses cost-per-wafer economics and concentrates supplier relationships around integrated optical-mechanical-electrical subsystems, reshaping how Indian foundries negotiate procurement terms and manage long-lead dependencies.
Pricing Analysis
Input-cost pass-through from laser-produced plasma source components dominates EUVL scanner pricing, with source power scaling requirements and zeolite-based hydrogen purifier volatility feeding into capital expenditure quotes. Three-tier pricing structure across premium, standard, and economy levels separates foundry operators with advanced node commitments from research consortiums and specialty component manufacturers. Pricing pressure stems from single-source lithography scanner dependency and extended delivery queues. Semiconductor foundries in Gujarat demonstrate lowest price sensitivity due to PLI scheme capital subsidies, while research institutions face tightest budget constraints.
Supply Chain Analysis
Domestic-content mandates under India's Semiconductor Mission are reshaping sourcing patterns for EUVL subsystem assembly and after-sales service localization. Supply concentrates in the Netherlands for lithography scanners, Germany for precision optical components, and South Korea for process roadmap specifications. Raw material dependencies include high-purity hydrogen, tin droplet feedstock, and specialized mirror substrates. Single-source vulnerability for scanner procurement creates delivery risk exposure. Distribution runs through direct vendor-to-fab contracting with separate maintenance service unbundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's EUVL systems market functions as a stable compounder, with Semiconductor Mission incentives providing durable capital formation that underpins sustained equipment demand across the analysis window.
For Market Incumbents: Deploy after-sales service unbundling to capture recurring revenue streams from light source refurbishment and optical component cleaning contracts. Foundry operators in Gujarat and Karnataka are negotiating separate maintenance agreements to reduce total cost of ownership, threatening traditional bundled service margins. Backward integration into mask blank inspection capabilities defends against domestic engineering services expansion.
For New Entrants and Emerging Players: Precision manufacturing contractors in Karnataka's Mysuru corridor offer the most penetrable entry point for EUVL subsystem assembly partnerships. Photomask repair service localization represents unmet demand that domestic engineering firms can capture. Go-to-market positioning should emphasize CDSCO-adjacent equipment qualification expertise to accelerate import clearance timelines for subsequent tool cycles.
For Investors and Strategic Acquirers: Roll-up economics work for precision optical component suppliers because EUVL resolution requirements consolidate vendor relationships around integrated subsystems rather than discrete sourcing. The five-to-ten-year viability window favors acquisition targets with established cleanroom construction sequencing capabilities and pre-qualified contractor relationships. Monitor Semiconductor Mission PLI threshold revisions linking incentive disbursement to actual wafer start dates as the key inflection signal for project financing risk.
| Strategic Initiative | Industry Significance |
|---|---|
| After-Sales Service Unbundling | Separate maintenance contracts for EUVL scanners reduce operator total cost of ownership in Gujarat. |
| Mask Equipment Localization | Karnataka precision clusters absorb EUVL blank inspection demand as domestic capabilities expand. |
| High-NA Optics Pre-Qualification | Foundry operators specify 0.55 numerical aperture compatibility for sub-three-nanometer roadmap positioning. |
| Cleanroom Construction Pre-Qualification | Ahmedabad contractors accelerate EUVL tool commissioning timelines through pre-qualified sequencing protocols. |
| Plasma Physics Curriculum Development | Maharashtra technical universities address specialist scarcity for laser-produced source maintenance operations. |
Research Methodology
Coverage spans India, the Netherlands, Germany, and South Korea, with primary inputs from each market cluster combining interviews with foundry project developers, lithography equipment procurement officers, precision optical component suppliers, and cleanroom construction contractors. Secondary validation draws from BIS standards documentation, Semiconductor Mission policy circulars, customs import records for lithography equipment, and SEC filings from listed semiconductor capital equipment vendors. Bottom-up project pipeline assessment triangulates against top-down incentive allocation modeling.
Granularity-level framing models EUVL system demand at the subsystem component level, technology generation tier, and end-user capability segment across the projection horizon. Analytical framework incorporates process node migration timelines, PLI scheme disbursement schedules, and foundry construction sequencing constraints. CAGRs derive from equipment procurement authorization patterns and wafer start milestone trajectories. Industry-specific forecast inputs include laser-produced plasma source power scaling roadmaps and high-NA optics adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Semiconductor Mission policy revisions, BIS technical standards alignment timelines, and single-source scanner delivery queue fluctuations. Forecasts reflect documented assumptions regarding PLI eligibility thresholds, cleanroom construction completion rates, and plasma physics specialist pipeline development. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Photolithography Market
Semiconductor Equipment
Semiconductor Laser Equipment Market
Semiconductor Equipment
Underfill Dispenser Market
Semiconductor Equipment
Vacuum Soldering System Market
Semiconductor Equipment
Nanoimprint Lithography System Market
Semiconductor Equipment
China Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Global Semiconductor Stepper Systems Market
Semiconductor Equipment
Automatic Dicing Saw Market
Semiconductor Equipment
Semiconductor Dielectric Etching Equipment Market
Semiconductor Equipment
I-Line Lithography Market
Semiconductor Equipment
Global Semiconductor Thermal Evaporators Market
Semiconductor Equipment
Asia-Pacific Aligner Sheet Market
Semiconductor Equipment
Middle East and Africa Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
Photolithography Equipment Market
Semiconductor Equipment
Plasma Etch System Market
Semiconductor Equipment
Temperature Calibration Equipment Market