
 Marine Heat Exchanger Market | 2026-2036
Marine Heat Exchanger Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Heat Exchanger Market Analytics
Corrosion-resistant alloy welding is reshaping how marine heat exchangers withstand seawater exposure and thermal cycling in high-salinity environments. Alfa Laval leverages its Scandinavian engineering heritage to dominate plate heat exchanger design for cruise liners and chemical tankers. GEA Group anchors its position through backward integration into precision tube rolling for shell-and-tube configurations serving offshore platforms. Wuxi Yushun Heat Exchanger competes on manufacturing scale from its Jiangsu production base, supplying cost-optimized copper-nickel units to Chinese fishing boat retrofit programs.
A marine heat exchanger is a thermal transfer device constructed from titanium, stainless steel, or copper-nickel alloys that regulates fluid temperatures in propulsion systems, auxiliary machinery, and HVAC circuits aboard vessels; units typically operate at pressures between 6 and 16 bar with seawater flow rates calibrated to engine load profiles. Shell and tube designs retain primacy in engine cooling applications where high-pressure tolerance and mechanical robustness outweigh compactness constraints. Plate configurations capture margin pools in waste heat recovery systems where thermal efficiency gains of fifteen to twenty percentage points justify premium alloy costs. Titanium material grades are displacing copper-nickel in naval specifications where fifty-year service life requirements override initial procurement budgets.
The International Maritime Organization enforces MARPOL Annex VI energy efficiency standards that mandate heat recovery integration in newbuild vessels above four hundred gross tons. The EPA regulates ballast water treatment system thermal management in US-flagged commercial fleets, while the EU Green Deal's FuelEU Maritime initiative tightens carbon intensity thresholds that reward waste heat recovery investments. Classification societies including DNV and Lloyd's Register certify alloy selection protocols that gate market access for unapproved suppliers. Stakeholders must monitor how ammonia fuel propulsion architectures alter cooling loop specifications and thermal load distributions across dual-fuel engine rooms.
Market Dynamics
Naval procurement programs across NATO member states are forcing a material transition from copper-nickel alloys to titanium grades in plate heat exchanger specifications, compressing supplier qualification timelines and rewiring alloy supply chains toward corrosion-resistant metallurgy.
Growth Catalysts
- IMO MARPOL Annex VI:Revised efficiency standards mandate waste heat recovery integration in newbuild vessels above four hundred gross tons, directly expanding addressable equipment volume in commercial shipping.
- Titanium alloy welding advances:Automated orbital welding of thin-gauge titanium plates reduces fabrication costs for naval heat exchangers while extending service life in high-salinity environments.
- South Korea's Ulsan cluster:Hyundai Heavy Industries and Samsung Heavy Industries anchor concentrated newbuild demand for LNG carrier thermal management systems, creating procurement gravity for specialized suppliers.
Market Restraints
- Titanium sponge supply concentration:Primary titanium sponge production clusters in China and Russia expose Western fabricators to geopolitical supply disruption and alloy price volatility.
- Copper-nickel legacy fleet lock-in:Existing commercial vessel cooling circuits use copper-nickel metallurgy incompatible with ammonia fuel propulsion chemistries, forcing premature replacement cycles.
- DNV and Lloyd's Register certification timelines:Extended alloy qualification protocols for novel corrosion-resistant grades delay supplier market entry by eighteen to thirty-six months.
Strategic Opportunities
- Ammonia dual-fuel architectures:Toxicity and corrosion properties of ammonia propulsion systems require redesigned cooling loop specifications, opening specification windows for qualified heat exchanger suppliers.
- Ballast water treatment thermal management:EPA regulations for US-flagged fleets mandate temperature-controlled treatment systems, creating aftermarket retrofit demand distinct from newbuild cycles.
- Additive manufacturing of titanium manifolds:Convergence of powder-bed fusion with topological optimization enables complex internal channel geometries previously impossible through conventional machining.
Industry Challenges
- Orbital welding technician scarcity:Qualified titanium welders for thin-plate heat exchanger fabrication command premium wages, constraining production scaling for qualified suppliers.
- Legacy shell-and-tube integration:Engine room spatial constraints in retrofitted vessels complicate physical installation of compact plate configurations alongside existing auxiliary machinery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Heat Exchanger Market |
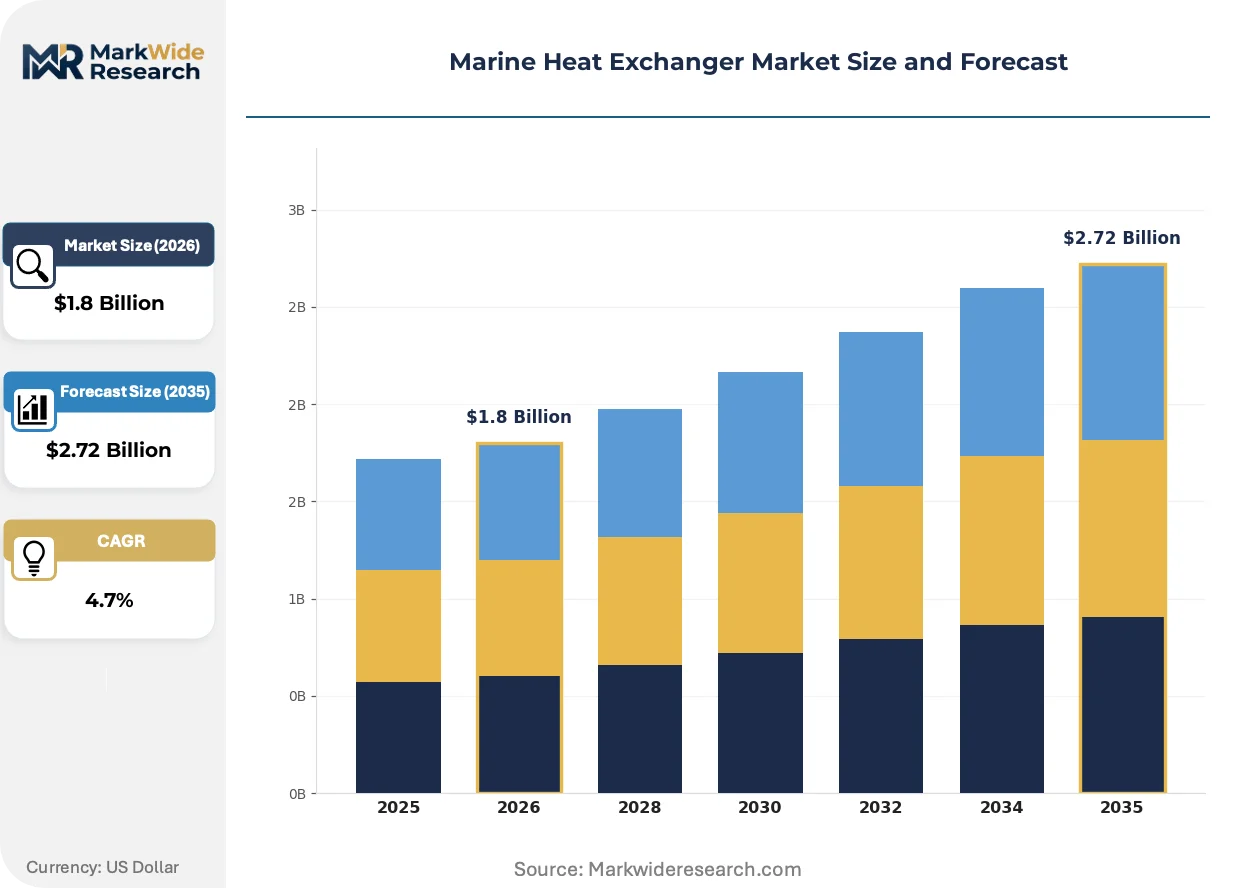
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shell & Tube, Plate, Spiral, Air-Cooled Application: Cooling System, Heating System, Waste Heat Recovery, Engine Cooling Material: Stainless Steel, Titanium, Copper-Nickel, Alloy End User: Commercial Vessels, Naval Ships, Offshore Platforms, Fishing Boats |
| Companies Covered | Xylem, Inc., Crusader, Alfa Laval, Orca Marine Cooling Systems, Seakamp Engineering, GEA Group, Thermex, Wuxi Yushun Heat Exchanger, SPX FLOW, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Heat Exchanger Market Evolving Landscape
Material science advances and regulatory chemistry requirements are converging to rewrite heat exchanger specification sheets, with alloy selection now preceding thermal design in procurement workflows.
Corrosion-resistant alloy construction is migrating from naval exclusivity into commercial chemical tanker specifications. DNV-certified titanium plate packs now appear in methanol carrier cargo heating circuits where copper-nickel pitting previously limited service intervals. This metallurgical upgrade path compresses the supplier base to fabricators with qualified titanium welding capabilities.
EU Green Deal's FuelEU Maritime initiative tightens carbon intensity thresholds on voyages calling at European ports. Vessel operators respond by prioritizing waste heat recovery investments that improve effective fuel efficiency without engine replacement. Chemical tankers and refrigerated cargo vessels face the steepest compliance gradients under the phased implementation timeline.
Shipyard procurement departments now unbundle heat exchanger supply from engine maker package deals. Korean and Japanese yards increasingly source thermal management equipment through standalone tender processes, enabling specialized fabricators to bypass incumbent engine OEM channels. This pattern concentrates in LNG carrier newbuild programs where custom cargo conditioning requirements exceed standard engine maker catalog offerings.
Marine Heat Exchanger Market Segmentation
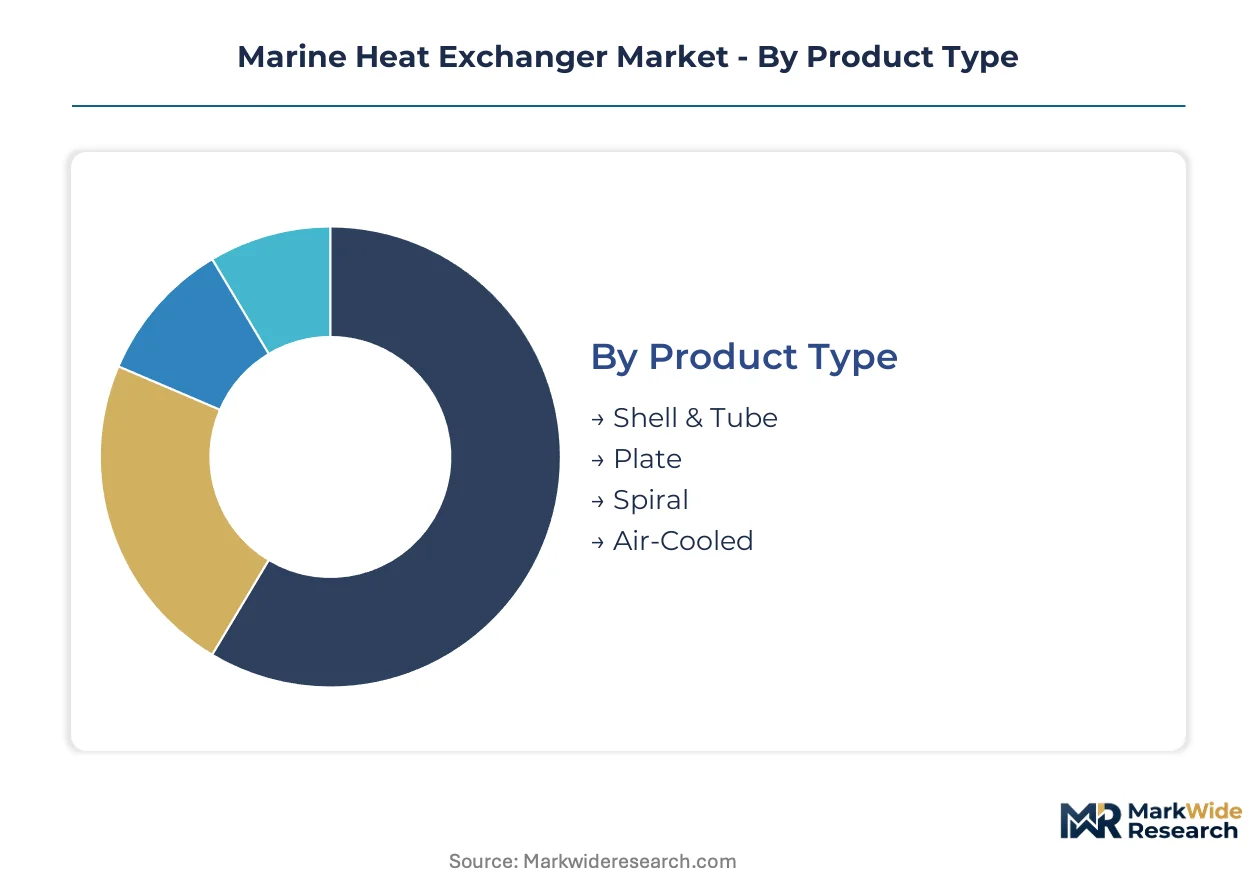
Segmentation in marine heat exchangers tracks how thermal management requirements diverge across vessel architectures, metallurgical specifications, and operational duty cycles. Procurement patterns vary sharply between naval programs with fifty-year service horizons and commercial fleets optimizing for fuel efficiency compliance.
Product Type:
Configurations span the pressure-tolerance spectrum from high-strength engine cooling circuits to compact auxiliary heat recovery loops.
- Shell & Tube:Cylindrical pressure vessels with tube bundles handle engine jacket water and lube oil cooling at 10-16 bar operating pressures. Hyundai Heavy Industries specifies these for LNG carrier propulsion systems where mechanical robustness outweighs footprint constraints.
- Plate:Stacked corrugated plates deliver thermal efficiency gains of fifteen to twenty percentage points over shell designs. DNV-certified titanium plate packs now penetrate methanol carrier cargo heating circuits where copper-nickel pitting previously limited maintenance intervals.
- Spiral:Coiled channel geometry handles viscous fluids and slurries in chemical tanker cargo temperature control with self-cleaning flow patterns.
- Air-Cooled:Finned tube arrays serve auxiliary machinery in coastal vessels with limited raw water access or high-sediment harbors.
The dominant share belongs to Shell & Tube configurations, while Plate designs are closing the gap fastest as FuelEU Maritime carbon intensity rules reward waste heat recovery investments.
Application:
Functional deployment tracks thermal load distribution across propulsion, auxiliary, and environmental control systems.
- Cooling System:Seawater circuits regulate temperatures in main engines, generators, and steering gear. Samsung Heavy Industries sources specialized units for Ulsan-built container ships with dual-circuit redundancy.
- Heating System:Thermal oil and steam exchangers maintain fuel viscosity and accommodation climate control in Arctic-route vessels.
- Waste Heat Recovery:Exhaust gas economizers and organic Rankine cycle preheaters capture thermal energy for power generation. IMO MARPOL Annex VI mandates integration in newbuild vessels above four hundred gross tons.
- Engine Cooling:Dedicated circuits for cylinder jackets, pistons, and charge air maintain thermal equilibrium across variable load profiles.
Cooling System applications command the largest equipment volume, though Waste Heat Recovery is expanding most quickly under regulatory pressure.
Material:
Alloy selection now precedes thermal design in procurement workflows as corrosion chemistry reshapes specification sheets.
- Titanium:Grade 2 and Grade 5 titanium plates withstand fifty-year naval service lives in high-salinity environments. Automated orbital welding of thin-gauge sheets reduces fabrication costs while NATO procurement programs accelerate adoption.
- Copper-Nickel:90-10 and 70-30 alloys retain cost advantages in commercial fishing fleets and legacy fleet retrofits despite incompatibility with ammonia fuel chemistries.
- Stainless Steel:316L and duplex grades balance corrosion resistance with formability in coastal patrol craft and harbor service vessels.
- Alloy:Nickel-aluminum-bronze and other specialized formulations address galvanic compatibility in mixed-metallurgy systems.
Copper-Nickel retains the largest installed base, yet Titanium is gaining share fastest as naval specifications override initial procurement budgets.
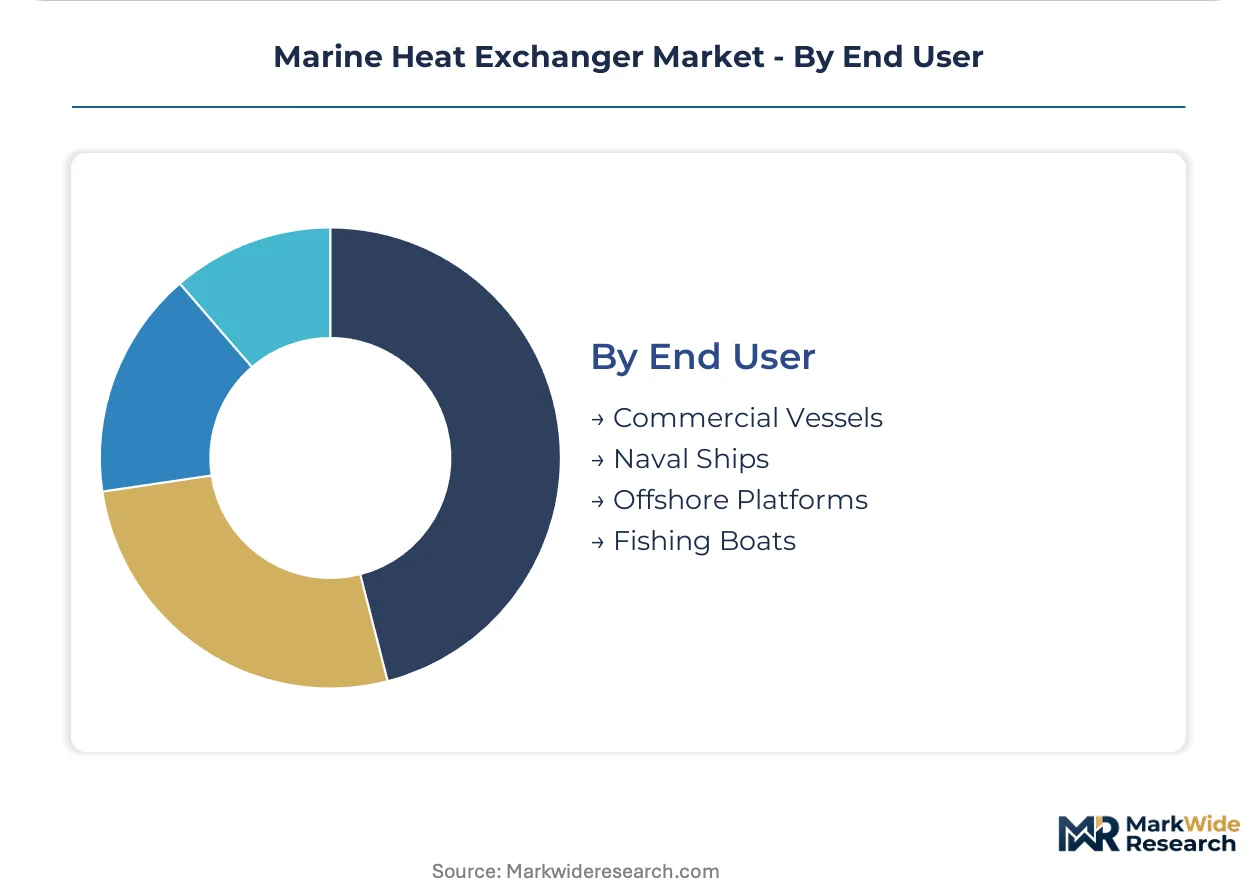
End User:
Customer categories separate capital-intensive newbuild programs from lifecycle-driven aftermarket demand.
- Commercial Vessels:Container ships, tankers, and bulk carriers drive standardized high-volume procurement. Korean and Japanese yards increasingly unbundle thermal equipment from engine maker package deals.
- Naval Ships:Destroyers, frigates, and submarines demand qualified titanium fabrication with extended qualification timelines. Lloyd's Register and DNV certification protocols gate supplier access.
- Offshore Platforms:Floating production units and drilling rigs require explosion-rated shell-and-tube configurations with API compliance.
- Fishing Boats:Cost-optimized copper-nickel units dominate retrofit programs in Chinese and Southeast Asian fleets with shorter replacement cycles.
Commercial Vessels generate the highest equipment volume, while Naval Ships are climbing the fastest as NATO procurement programs expand titanium specification adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean shipyards export titanium heat exchanger specifications to NATO naval procurement programs across the Atlantic, while Chinese fabricators supply cost-optimized copper-nickel units to Southeast Asian fishing fleet retrofits.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries drive concentrated demand for LNG carrier thermal management systems through the Ulsan shipbuilding cluster. The Korean Register of Shipping enforces alloy qualification protocols that gate supplier access to naval newbuild programs. Busan-Ulsan corridor fabricators specialize in automated orbital welding of thin-gauge titanium plates for fifty-year service life specifications.
United States
EPA ballast water treatment regulations for US-flagged commercial fleets create aftermarket retrofit demand distinct from newbuild cycles. The US Coast Guard enforces thermal management standards for temperature-controlled treatment systems in coastal and deep-water vessels. Gulf Coast shipyards in Louisiana and Texas concentrate on offshore platform shell-and-tube configurations with API compliance requirements.
China
Wuxi Yushun Heat Exchanger anchors cost-optimized copper-nickel production from its Jiangsu manufacturing base for domestic fishing boat retrofit programs. The Ministry of Ecology and Environment implements dual carbon goals that accelerate waste heat recovery investments in newbuild vessels above four hundred gross tons. Yangtze River Delta fabricators dominate titanium sponge processing despite Western supply chain diversification efforts.
Germany
KBA maritime certification requirements for ammonia dual-fuel propulsion systems open specification windows for redesigned cooling loop suppliers. The EU Green Deal's FuelEU Maritime initiative tightens carbon intensity thresholds on voyages calling at Hamburg and Bremerhaven. Northern German shipyards specialize in chemical tanker cargo heating circuits requiring DNV-certified titanium plate packs.
Japan
METI efficiency standards drive waste heat recovery integration in domestic newbuild programs for refrigerated cargo vessels facing steep compliance gradients. Japanese classification society Nippon Kaiji Kyokai certifies alloy selection protocols for methanol carrier thermal management systems. Nagoya-Chubu region fabricators maintain precision tube rolling capabilities for shell-and-tube configurations serving offshore platforms.
Marine Heat Exchanger Market Competitive Landscape
On the supply side, the industry is consolidating around qualified titanium welding capabilities as naval procurement programs compress supplier qualification timelines. Scandinavian and German engineering heritage anchors premium-tier positioning in plate heat exchanger design for cruise liners and chemical tankers. Three archetypes dominate: full-line thermal equipment suppliers with backward integration into precision manufacturing, regional scale fabricators competing on cost-optimized copper-nickel production, and specialized naval contractors with captive titanium alloy supply chains. Competitive moves concentrate on geographic expansion into Korean and Japanese shipyard procurement channels and technology licensing for automated orbital welding processes.
Among European heritage suppliers, Alfa Laval and GEA Group exemplify the premium-tier archetype through Scandinavian engineering positioning and upstream control over precision tube rolling. Wuxi Yushun Heat Exchanger represents the scale-driven Chinese fabricator model supplying Jiangsu-based production to cost-sensitive retrofit programs. These three occupy positions across the pricing spectrum from naval specification premiums to commercial fleet economy tiers.
| Leading Market Players |
|---|
| Xylem, Inc. |
| Crusader |
| Alfa Laval |
| Orca Marine Cooling Systems |
| Seakamp Engineering |
| GEA Group |
| Thermex |
| Wuxi Yushun Heat Exchanger |
| SPX FLOW |
| Others |
Value Network & Pricing Analysis
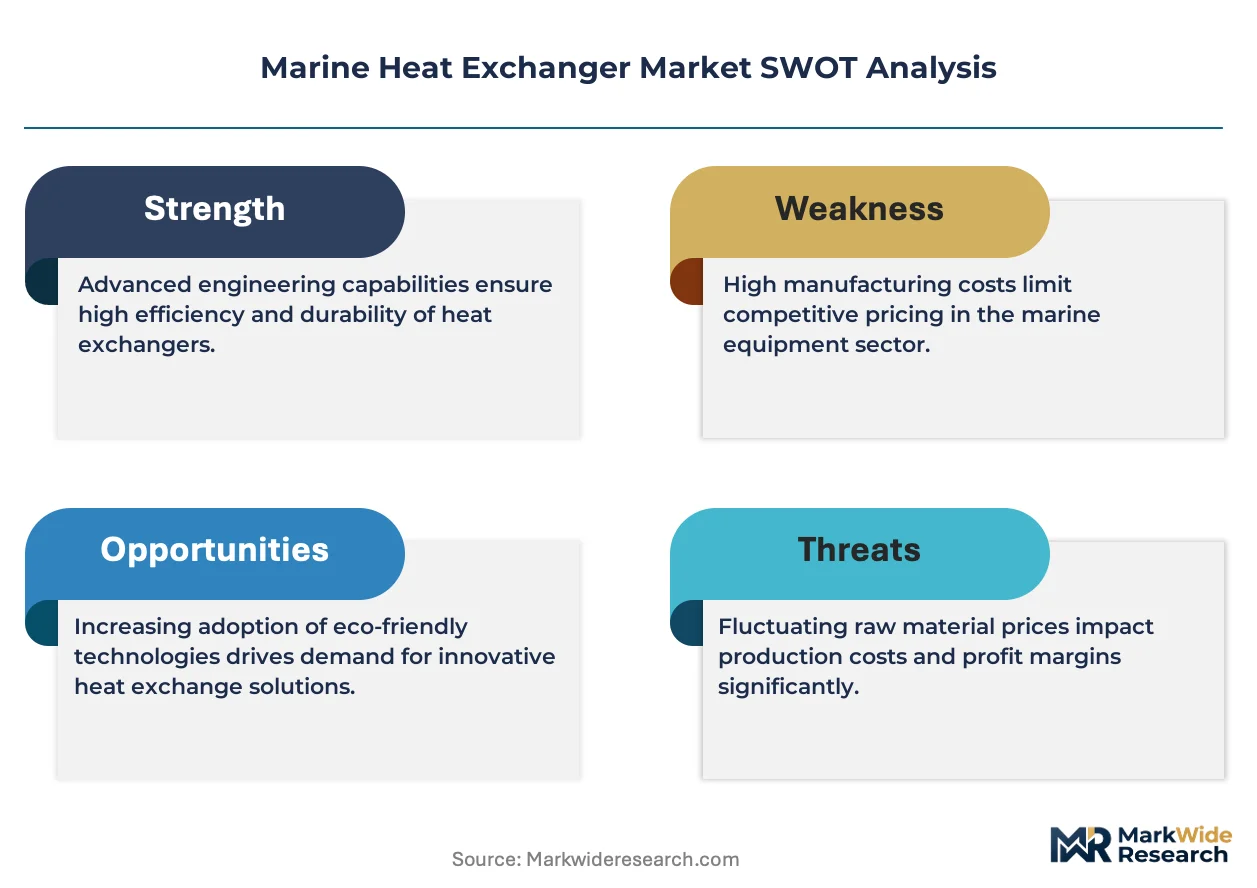
Titanium sponge supply concentration in China and Russia exposes Western fabricators to geopolitical disruption that widens pricing spreads between naval-grade titanium units and commercial copper-nickel alternatives while compressing margins across all tiers.
Pricing Analysis
Current-generation titanium plate heat exchangers command substantial premiums over prior-generation copper-nickel configurations, while next-generation additive-manufactured titanium manifolds remain pre-commercial. Pricing stratifies across premium, standard, and economy tiers based on alloy grade certification and volume scale. Cost compression in the commercial fishing fleet segment is intensifying because Chinese fabricators exploit manufacturing scale advantages. Naval procurement programs exhibit the lowest price sensitivity due to fifty-year service life specifications.
Supply Chain Analysis
Contract manufacturing for precision tube rolling concentrates among German and Japanese specialists with captive metallurgical capabilities. Titanium sponge processing draws from Chinese and Russian primary production clusters, while precision fabrication rests on South Korean and Scandinavian engineering bases. Single-source vulnerability in titanium sponge exposes Western supply chains to export restriction risk. Distribution runs through Korean and Japanese shipyard procurement channels with increasing unbundling from engine OEM package deals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where DNV and Lloyd's Register certification protocols create switching costs that protect qualified incumbents from unapproved competitors.
For Market Incumbents: Insulate market position by deepening backward integration into titanium alloy supply chains and expanding automated orbital welding capacity in the Busan-Ulsan corridor. Certification investment represents the critical defensive lever against emerging Chinese fabricators seeking Western naval qualification. For New Entrants and Emerging Players: Build out specialized capabilities in ammonia dual-fuel cooling loop specifications where incumbent engine OEMs lack established thermal management partnerships. The ballast water treatment retrofit segment for US-flagged fleets offers the most penetrable entry point through EPA compliance specialization. For Investors and Strategic Acquirers: FuelEU Maritime implementation reshapes the acquisition landscape toward waste heat recovery specialists with DNV-certified titanium fabrication capabilities. Long-term viability centers on suppliers positioned for ammonia and methanol propulsion thermal architectures. Monitor Korean shipyard unbundling trends as the signal for standalone heat exchanger procurement inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Titanium Welding Qualification Investment | DNV certification unlocks NATO naval procurement programs with fifty-year service specifications. |
| Ammonia Dual-Fuel Cooling Loop Development | KBA maritime requirements open specification windows for corrosion-resistant alloy suppliers. |
| Automated Orbital Welding Scale-Up | Hyundai Heavy Industries and Samsung Heavy Industries prioritize qualified fabrication partners. |
| Ballast Water Treatment Thermal Integration | EPA regulations create aftermarket retrofit demand distinct from newbuild cycles. |
| Additive Manufacturing Capability Buildout | Powder-bed fusion enables complex titanium manifold geometries for next-generation naval specifications. |
Research Methodology
Initial hypotheses were tested against primary input from shipyard procurement directors, naval engineering program managers, classification society surveyors, and titanium alloy fabricators and refined through secondary validation against Lloyd's Register certification databases, Korean Register of Shipping technical bulletins, IMO MARPOL Annex VI regulatory filings, and customs trade data for titanium sponge and heat exchanger equipment. Bottom-up vessel newbuild forecasts were triangulated with top-down thermal equipment spend estimates.
Demand-supply balance modeling across the analysis window incorporated segmentation by product configuration, alloy specification, vessel type, and end-user category. CAGRs were derived from regression analysis of historical procurement patterns and projected regulatory compliance requirements. Industry-specific forecast inputs included NATO naval procurement timelines, FuelEU Maritime carbon intensity phase-in schedules, and ammonia dual-fuel propulsion adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese titanium fabricators or accelerated NATO qualification of alternative suppliers would shift outcomes. Quarterly review of Korean shipyard tender unbundling rates and DNV certification queue lengths is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine and Coastal Engineering
Cable Laying Vessel Market
Marine and Coastal Engineering
Crane Barge Market
Marine and Coastal Engineering
Submersible Dredge Pump Market
Marine and Coastal Engineering
Subsea Trencher Market
Marine and Coastal Engineering
Global Marine and Dock Gangways Market
Marine and Coastal Engineering
Mooring Compensators Market
Marine and Coastal Engineering
Offshore Pipeline Market
Marine and Coastal Engineering
Marine Cranes Market
Marine and Coastal Engineering
Asia-Pacific Offshore Crane Market
Marine and Coastal Engineering
Marine Watertight Door Market
Marine and Coastal Engineering
Saudi Arabia Mobile Sea Water Reverse Osmosis (SWRO) Treatment Plants Market
Marine and Coastal Engineering
Wind Turbine Installation Vessel Market
Marine and Coastal Engineering
Underwater Concrete Market
Marine and Coastal Engineering
Offshore Inspection, Repair, and Maintenance Market
Marine and Coastal Engineering
Work Barges Market
Marine and Coastal Engineering
Flood Control Sandbags Market