
 Ship Gangways Market | 2026-2036
Ship Gangways Market Size, Share, and Industry Trends Forecast 2026-2036
Ship Gangways Market Analytics
Defense and offshore energy buyers are unwinding their historical dominance as cruise line procurement accelerates. SafeBoarding Systems leverages its aluminum fabrication expertise to anchor European newbuild contracts. MacGregor sustains integrated deck machinery portfolios that compete across cargo and passenger segments. Palfinger Marine differentiates through telescoping systems designed for harsh North Sea environments.
Ship gangways are articulated or fixed bridge structures, typically fabricated from marine-grade aluminum or coated steel with anti-slip surfaces and integrated handrails, engineered to enable safe personnel and cargo transfer between vessels and shore facilities or between ships at sea. Telescoping gangways lead product type demand due to operational flexibility in variable tidal conditions, while aluminum dominates material selection for its strength-to-weight ratio and corrosion resistance in saltwater exposure. Passenger transfer applications command premium specification tiers, whereas cargo loading segments prioritize load-bearing capacity and rapid deployment cycles.
IMO SOLAS conventions, the EU Marine Equipment Directive, and ISO 7061 standards collectively govern gangway design loads, safety factors, and testing protocols for international maritime deployment. These frameworks compel manufacturers to maintain type-approved certification portfolios, creating barriers for unqualified suppliers and favoring incumbents with established notified body relationships. Stakeholders must monitor evolving polar code amendments and autonomous vessel interface standards that will reshape gangway specification requirements for next-generation ship designs.
Market Dynamics
Cruise fleet renewal programs are compressing specification cycles as SOLAS amendments and EU Marine Equipment Directive certification requirements force simultaneous safety upgrades across newbuild and retrofit contracts.
Growth Catalysts
- EU Marine Equipment Directive:Tighter gangway certification standards are mandating type-approved equipment on all EU-flagged vessels, creating replacement demand across existing fleets.
- Aluminum fabrication advances:Marine-grade aluminum alloys with improved strength-to-weight ratios are enabling longer span designs without structural compromise.
- Passenger transfer applications:Cruise lines are elevating gangway specifications to match premium vessel interiors, driving specification upgrades.
Market Restraints
- Marine-grade aluminum price volatility:Primary aluminum input costs fluctuate with energy prices, compressing fabrication margins on fixed-price contracts.
- Notified body concentration:Type approval certification depends on a limited pool of EU-recognized testing bodies, creating approval bottlenecks.
- Fixed gangway substitution:Simple ramp systems retain cost advantage on short-haul ferry routes with minimal tidal variation.
Strategic Opportunities
- Polar Code amendments:Ice-class gangway specifications for Arctic cruise routes are opening specialized design contracts.
- Autonomous vessel interfaces:Self-docking systems require sensor-integrated gangways with automated alignment capabilities.
- Aftermarket service unbundling:Maintenance and inspection contracts are separating from initial equipment sales, creating recurring revenue streams.
Industry Challenges
- Welding certification scarcity:Marine aluminum welding requires specialized ASME and EN 1090 qualifications that outpace training program output.
- Legacy system integration:Retrofit installations must interface with existing deck machinery control architectures without full replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ship Gangways Market |
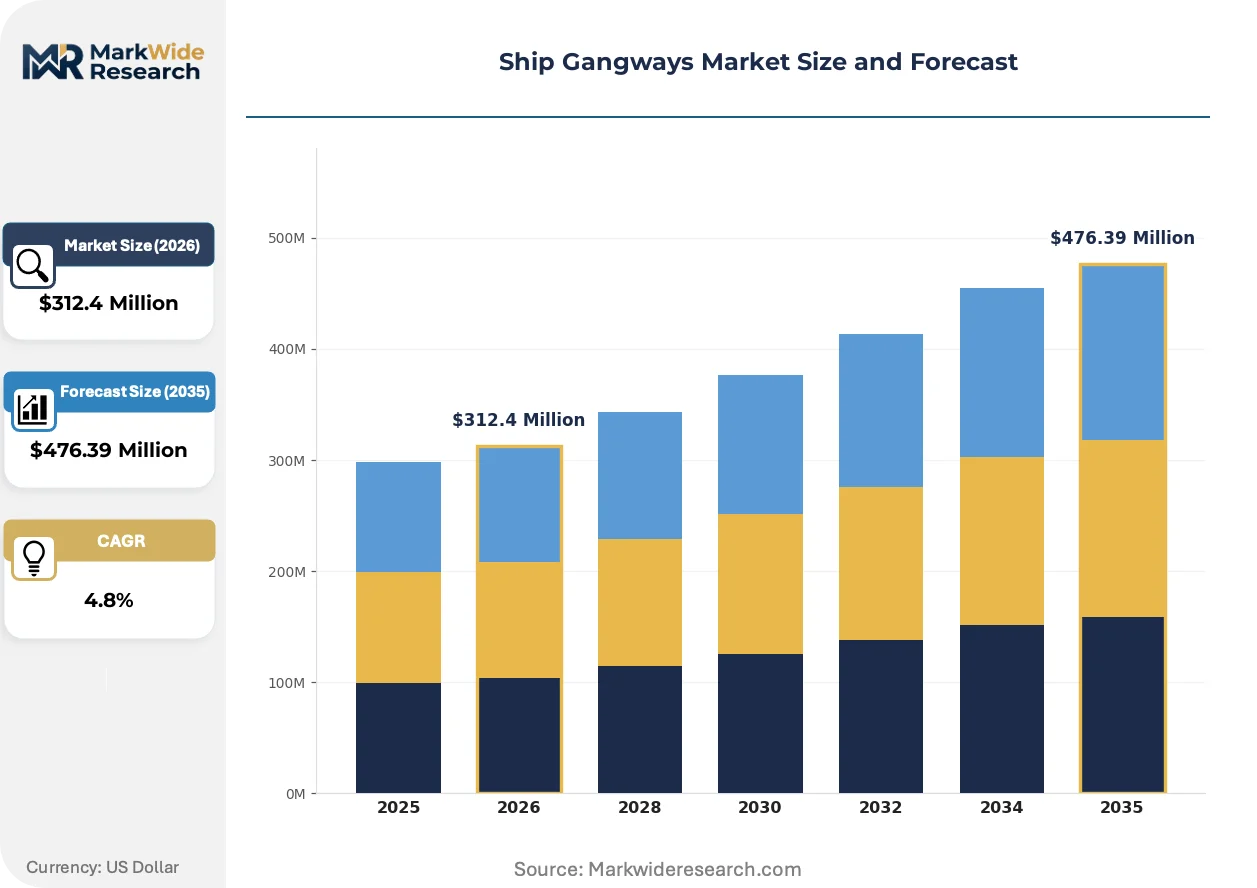
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $476.39 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Folding Gangway, Telescoping Gangway, Fixed Gangway, Inflatable Gangway Material: Aluminum, Steel, Fiberglass, Plastic End User: Cruise Lines, Cargo Shipping, Yacht Manufacturers, Marine Construction Application: Passenger Transfer, Cargo Loading, Emergency Evacuation, Pilot Boarding |
| Companies Covered | SafeBoarding Systems, MacGregor (Cargotec Corporation), Palfinger Marine, TTS Group ASA, Brunvoll AS, DSB Marine, SafeRack LLC, JIEHU Ship Gangway, Cavotec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ship Gangways Market Evolving Landscape
Digitalization of gangway control systems is converging with predictive maintenance platforms, while regulatory pressure on passenger safety is accelerating specification tier compression across vessel categories.
Modular aluminum truss systems are decomposing traditional welded fabrication approaches. Cruise operators in the Mediterranean and Baltic routes are specifying bolt-together sections for rapid reconfiguration. This modularity is decomposing the historical advantage of integrated shipyard supply chains by enabling third-party installation.
EU Marine Equipment Directive 2014/90/EU amendments are tightening emergency release and load-testing protocols. Manufacturers must now submit finite element analysis documentation alongside physical testing. German and Norwegian notified bodies are experiencing approval queue extensions of six to nine months as certification demand outpaces assessor capacity.
Long-term service agreements are displacing spot procurement for gangway maintenance. Major cruise operators are consolidating vendor relationships into five-year performance contracts covering inspection, repair, and component replacement. This consolidation is most visible in Miami and Barcelona, where fleet management headquarters are centralizing technical procurement decisions across multiple vessel classes.
Ship Gangways Market Segmentation
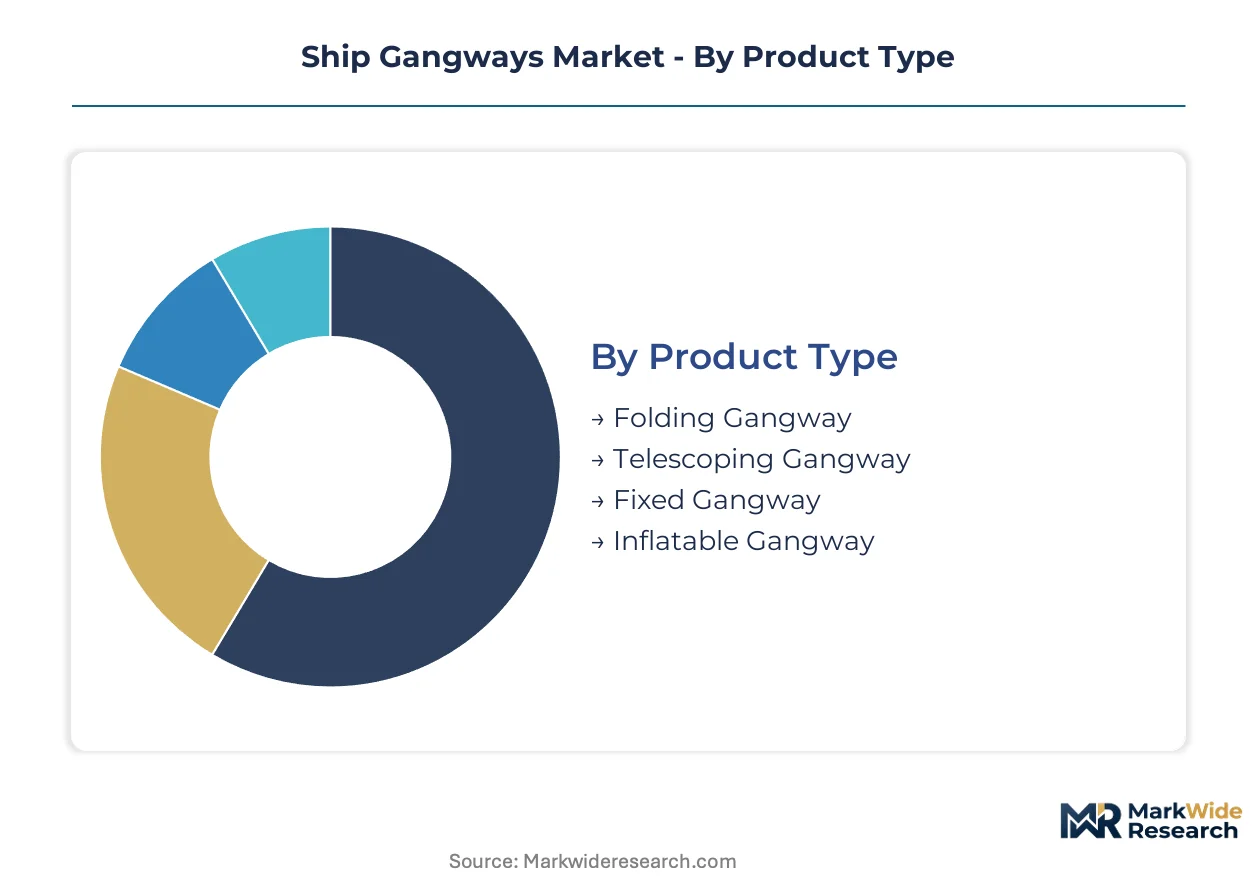
Ship gangway procurement splits across structural configurations, material specifications, and operational use cases. Regulatory frameworks from IMO SOLAS and the EU Marine Equipment Directive create tiered compliance requirements that reshape segment economics and manufacturer positioning.
Product Type:
EU Marine Equipment Directive certification intensity varies sharply across structural formats, with telescoping and folding systems facing stricter dynamic load testing protocols than fixed installations.
- Telescoping Gangway:Articulated multi-section aluminum assemblies extend and retract to accommodate tidal variation and vessel freeboard changes. Mediterranean cruise operators in Barcelona and Miami fleet headquarters specify these for premium passenger transfer applications where operational flexibility commands specification premiums.
- Folding Gangway:Hinged aluminum or steel platforms collapse for stowage against vessel superstructures. Norwegian and German shipyards favor these for offshore supply vessels and ice-class retrofits where deck space constraints intersect with SOLAS emergency release requirements.
- Fixed Gangway:Rigid steel or aluminum structures permanently mounted at shore facilities. Short-haul ferry routes with minimal tidal variation retain these for cost efficiency.
- Inflatable Gangway:Deployable pneumatic structures for emergency and military applications. Special operations and rescue vessel operators in South Korea specify these for rapid deployment scenarios.
Telescoping gangways handle the majority of throughput; folding configurations are expanding most quickly on share as ice-class retrofits accelerate.
Material:
Cost tier stratification separates premium aluminum specifications from steel alternatives, with fiberglass and plastic occupying niche positions where weight reduction or chemical resistance outweighs structural load requirements.
- Aluminum:Marine-grade alloys with enhanced strength-to-weight ratios dominate newbuild contracts. German notified bodies and Norwegian certification queues prioritize aluminum finite element analysis documentation under amended EU Marine Equipment Directive protocols.
- Steel:Coated carbon and stainless grades persist in heavy cargo applications. South Korean shipbuilding clusters specify these for load-bearing gangways on bulk carriers where corrosion protection coatings add lifecycle cost.
- Fiberglass:Glass-reinforced polymer composites resist galvanic corrosion in specialized chemical tanker environments. Limited adoption reflects brittleness concerns under impact loading.
- Plastic:High-density polyethylene and composite polymers serve small craft and recreational marina installations. Cost positioning restricts these to non-certified applications below SOLAS threshold requirements.
Aluminum commands the dominant specification tier; fiberglass is climbing the fastest as chemical tanker fleet renewal accelerates.
End User:
Customer type determines procurement cycle length and service bundling intensity, with cruise lines separating from cargo operators through multi-year performance contracts covering inspection and component replacement.
- Cruise Lines:Fleet renewal programs in Miami and Barcelona headquarters compress specification cycles. Premium interior matching drives gangway aesthetic upgrades alongside safety compliance.
- Cargo Shipping:Bulk and container operators prioritize rapid deployment cycles and load-bearing capacity over passenger comfort specifications. German and Norwegian shipyards dominate this procurement segment.
- Yacht Manufacturers:Custom superyacht builders in the Netherlands and Italy specify bespoke gangway dimensions. Low volume per project contrasts with high margin capture.
- Marine Construction:Offshore platform and port infrastructure contractors procure heavy-duty fixed systems. South Korean fabrication yards anchor regional demand concentration.
Cruise lines drive the premium tier expansion; marine construction is gaining share fastest as offshore wind installation vessel demand climbs.
Application:
Functional use case shapes safety factor requirements and testing protocols, with passenger transfer facing the most stringent EU Marine Equipment Directive amendments.
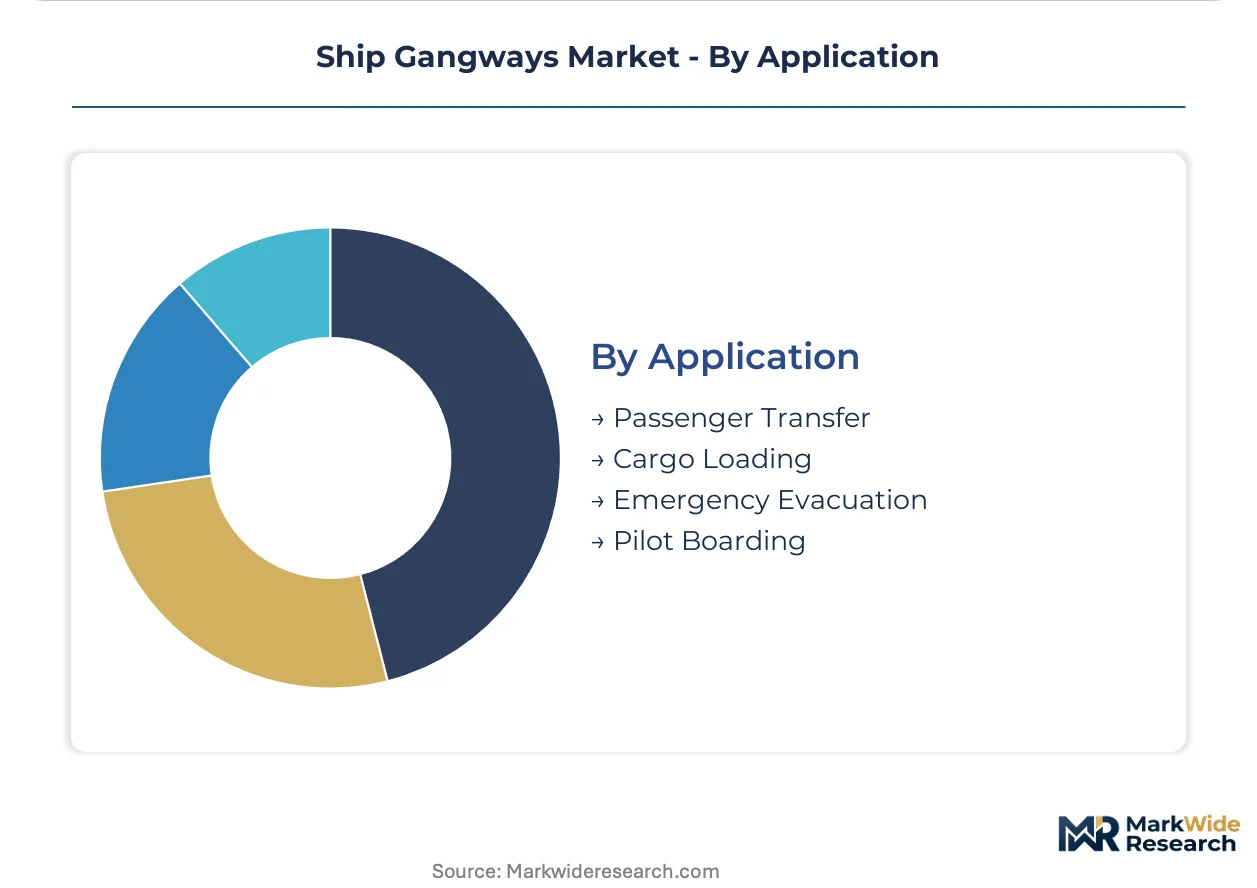
- Passenger Transfer:Cruise and ferry operations require anti-slip surfaces, integrated lighting, and handrail continuity. SOLAS amendments mandate emergency release mechanisms for this application tier.
- Cargo Loading:Stevedoring and offshore supply operations prioritize structural load ratings. German certification bodies emphasize dynamic testing for cargo gangway approval.
- Emergency Evacuation:Muster station gangways require rapid deployment and marine evacuation system integration. Norwegian flagged vessels lead specification adoption here.
- Pilot Boarding:Pilot ladder and gangway combinations face specialized ISO 799 and SOLAS Chapter V requirements. Port authorities in Barcelona and Miami enforce local pilot transfer safety standards.
Passenger transfer absorbs the dominant compliance investment; emergency evacuation is expanding fastest as Polar Code amendments drive Arctic cruise route preparation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ship gangway procurement concentrates where cruise fleet management headquarters intersect with shipbuilding clusters and notified body certification capacity. Buyer archetypes split between Miami and Barcelona-based cruise operators demanding premium passenger transfer systems and German, Norwegian, and South Korean shipyards executing newbuild contracts.
Germany
Cruise line fleet renewal programs and offshore wind installation vessel demand drive specification intensity. The EU Marine Equipment Directive mandates type-approved equipment through German notified bodies experiencing six-to-nine-month certification queues. Hamburg and Bremerhaven anchor shipbuilding clusters where aluminum fabrication expertise concentrates for telescoping gangway production.
Norway
Ice-class retrofit acceleration and Arctic cruise route preparation expand folding gangway adoption. SOLAS amendments and Polar Code implementation require specialized emergency release mechanisms on Norwegian-flagged vessels. Bergen and Stavanger house engineering clusters developing harsh-environment telescoping systems for North Sea offshore supply operations.
South Korea
DSME and Hyundai Heavy Industries anchor global newbuild contract execution for bulk carriers and container vessels. The country's national maritime safety regulator enforces SOLAS-aligned gangway certification for export vessels. Busan and Ulsan fabrication yards concentrate steel gangway production for cargo loading applications with heavy load-bearing requirements.
United States
Miami-based cruise headquarters compress specification cycles across premium passenger transfer applications. The Coast Guard enforces SOLAS Chapter V pilot boarding standards at Florida and California port authorities. Seattle and Gulf Coast marine fabrication clusters serve retrofit demand from domestic ferry operators and offshore energy contractors.
Italy
Superyacht builders in the Netherlands and northern Italy specify bespoke gangway dimensions for custom vessel projects. CE marking requirements under the EU Marine Equipment Directive govern equipment approval for Mediterranean cruise routes. Genoa and Monfalcone shipyards integrate gangway systems into premium passenger vessel interiors.
Ship Gangways Market Competitive Landscape
Player mix skews toward integrated deck machinery specialists and aluminum fabrication specialists with notified body relationships. The competitive terrain splits between European incumbents holding EU Marine Equipment Directive certification portfolios and Asian fabricators competing on steel gangway production scale. Two strategic archetypes dominate: integrated marine equipment conglomerates bundling gangways with broader deck machinery offerings, and specialized aluminum fabricators leveraging welding certification scarcity to defend premium positioning. Competitive moves concentrate on capacity expansion in South Korean fabrication yards and strategic partnerships between European specialists and cruise line fleet management headquarters.
Among European specialists, SafeBoarding Systems represents the aluminum fabrication archetype with established notified body relationships, while MacGregor exemplifies the integrated deck machinery conglomerate model. Palfinger Marine occupies a position bridging both archetypes through telescoping system specialization. These three anchors illustrate how certification capacity and fabrication expertise concentrate competitive advantage in distinct geographic and capability clusters.
| Leading Market Players |
|---|
| SafeBoarding Systems |
| MacGregor (Cargotec Corporation) |
| Palfinger Marine |
| TTS Group ASA |
| Brunvoll AS |
| DSB Marine |
| SafeRack LLC |
| JIEHU Ship Gangway |
| Cavotec |
| Others |
Value Network & Pricing Analysis
Aluminum substitution for steel in telescoping gangway fabrication simultaneously concentrates supply geography in German and Norwegian fabrication clusters and compresses pricing economics through marine-grade alloy certification premiums. This material shift rewards notified body relationships while penalizing fabricators without ASME welding qualifications.
Pricing Analysis
Generation-gap pricing separates legacy fixed gangways from sensor-integrated telescoping systems and emerging autonomous-interface designs. Three-tier pricing structure across premium passenger transfer, standard cargo loading, and economy fixed-ramp tiers reflects certification intensity under EU Marine Equipment Directive amendments. Price differentiation hinges on notified body queue position and aluminum alloy grade specification. Pricing pressure stems from energy-linked aluminum input volatility compressing fabrication margins. Cargo shipping operators exhibit highest price sensitivity; cruise lines accept specification premiums for interior-matching aesthetics.
Supply Chain Analysis
Strategic stockpiling of marine-grade aluminum plate prevails over just-in-time preferences given six-to-nine-month notified body certification queues and alloy grade availability constraints. Supply concentrates in Germany, Norway, and South Korea where shipbuilding clusters anchor fabrication capacity. Raw material dependencies center on primary aluminum from smelters, marine-grade extrusions, and anti-slip surface coatings. Single-source vulnerability runs through concentrated EU notified body capacity for type approval. Distribution runs through shipyard-integrated supply chains and direct fleet management procurement at Miami and Barcelona headquarters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket service unbundling generates recurring revenue streams expanding faster than initial equipment sales as cruise operators consolidate five-year performance contracts covering inspection, repair, and component replacement.
For Market Incumbents: Compound certification portfolio depth by securing additional notified body relationships ahead of EU Marine Equipment Directive queue extensions. Add captive aluminum welding training capacity to defend against ASME qualification scarcity threatening production scaling. Vertical integration into marine-grade alloy sourcing mitigates energy-price-linked input volatility eroding fixed-contract margins. For New Entrants and Emerging Players: Differentiate on Polar Code-compliant ice-class gangway specifications where Arctic cruise route preparation outpaces incumbent design cycle capacity. Target South Korean fabrication yards serving offshore wind installation vessel demand as the most penetrable geography. Pursue strategic partnerships with established notified bodies to bypass six-to-nine-month approval bottlenecks blocking market entry. For Investors and Strategic Acquirers: The market sits at a fleet-renewal acceleration phase that favors aluminum fabrication specialists with notified body relationships over integrated deck machinery conglomerates. Long-term viability favors targets with aftermarket service contract portfolios and ASME welding certification infrastructure. Watch for aluminum price volatility crossing thresholds that trigger fixed-contract margin distress among under-hedged fabricators.| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Partnership Expansion | Secures type approval capacity ahead of EU Marine Equipment Directive queue extensions affecting German and Norwegian assessors. |
| Aftermarket Service Unbundling | Captures recurring revenue from cruise line five-year performance contracts consolidating inspection and component replacement. |
| Polar Code Design Investment | Opens specialized contracts for Arctic cruise routes requiring ice-class emergency release mechanisms. |
| Aluminum Welding Training Expansion | Addresses ASME and EN 1090 qualification scarcity constraining fabrication scaling across European clusters. |
| Autonomous Interface Development | Positions for self-docking vessel sensor integration requirements reshaping next-generation gangway specifications. |
Research Methodology
A standing panel of shipyard procurement directors, cruise line fleet managers, notified body certification engineers, and marine aluminum fabricators provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from IMO SOLAS convention updates, EU Marine Equipment Directive amendment filings, shipbuilding order databases, and classification society technical bulletins. Bottom-up vessel fleet analysis and top-down shipbuilding market sizing were triangulated for consistency.
Consistency checks validated volume and value outputs against shipbuilding order backlogs, cruise fleet renewal program announcements, and aluminum fabrication capacity utilization across the projection horizon. Segmentation modeling covered product type, material specification, end user category, and application use case alongside regional regulatory cluster differentiation. CAGRs were derived from fleet expansion trajectories and retrofit cycle compression. Forecast inputs incorporated Polar Code implementation timelines and autonomous vessel interface development roadmaps.
Forecasts assume regulatory continuity in EU Marine Equipment Directive enforcement and SOLAS amendment adoption; material policy shifts would require re-modeling. Aluminum price volatility, notified body capacity constraints, and welding certification pipeline bottlenecks represent specific risk factors. Revision becomes warranted when aluminum alloy input costs or certification queue durations cross thresholds disrupting fabrication economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine and Coastal Engineering
Offshore Inspection, Repair, and Maintenance Market
Marine and Coastal Engineering
Mooring Compensators Market
Marine and Coastal Engineering
Marine Heat Exchanger Market
Marine and Coastal Engineering
Marine Hawser Market
Marine and Coastal Engineering
Mooring Bollards Market
Marine and Coastal Engineering
Offshore Pipeline Market
Marine and Coastal Engineering
Work Barges Market
Marine and Coastal Engineering
Underwater Concrete Market
Marine and Coastal Engineering
Global Marine and Dock Gangways Market
Marine and Coastal Engineering
Global Seismic Vessels Market
Marine and Coastal Engineering
Flood Control Sandbags Market
Marine and Coastal Engineering
Global Marine Ventilation Systems Market
Marine and Coastal Engineering
Marine Manifolds and Risers Market
Marine and Coastal Engineering
Global Pipe Laying Vessel Market
Marine and Coastal Engineering
Middle East Offshore Crane Market
Marine and Coastal Engineering
Dredging Market