
 Marine Hawser Market | 2026-2036
Marine Hawser Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Hawser Market Analytics
Synthetic HMPE fiber is pivoting away from traditional wire rope in deepwater mooring configurations, cutting installed weight by half while maintaining break-strength parity. Samson Rope Technologies leverages proprietary braiding platforms to dominate the high-performance synthetic segment. Cortland Limited anchors its position through captive plasma rope manufacturing for subsea tension-leg applications. Offspring International competes on integrated mooring system design, bundling hawser supply with installation engineering.
A marine hawser is a large-diameter flexible line, typically braided or twisted from synthetic polymer yarns or natural fibers, engineered to transmit tensile loads between vessels, platforms, or shore fixtures under dynamic marine conditions; break strengths commonly range from 100 to 2,000 metric tons depending on construction and diameter. The product serves as critical load-bearing infrastructure for vessel mooring, offshore station-keeping, and emergency towing operations where cyclic loading and saltwater exposure demand fatigue-resistant, UV-stabilized constructions. Polyester hawsers command the largest volume share due to proven creep resistance and cost efficiency in permanent moorings. Nylon segments attract premium positioning for energy-absorbing applications where elastic elongation protects hardware from snap loads. Extra-large diameter categories concentrate margin pools as certification complexity and custom engineering requirements limit supplier participation.
DNV classification rules for offshore mooring systems, API RP 2SK guidelines for station-keeping design, and IMO's Polar Code for Arctic shipping operations collectively dictate minimum performance thresholds, inspection intervals, and material traceability requirements that shape procurement specifications across the value chain. Brazil's national petroleum regulator enforces ANP-mandated mooring integrity protocols that favor certified suppliers with local content commitments. Stakeholders must monitor evolving certification scopes for bio-based fiber alternatives as lifecycle carbon accounting penetrates contract terms.
Market Dynamics
Deepwater floating production systems are multiplying across Brazil's pre-salt basins, forcing mooring procurement toward high-modulus polyethylene fiber configurations that halve topside weight while maintaining break-strength parity with traditional wire rope.
Growth Catalysts
- FPSO Installation Surge:Floating production storage and offloading units in Brazil's deepwater pre-salt fields require certified high-performance hawsers for permanent station-keeping, creating sustained demand pull for synthetic fiber constructions.
- EU Green Deal Maritime Mandates:The European Union's decarbonization framework accelerates fiber-transition timelines for mooring systems, favoring lifecycle carbon accounting in contract specifications across North Sea offshore wind and port infrastructure.
- HMPE Fiber Maturation:High-modulus polyethylene braiding platforms now achieve creep resistance parity with polyester in permanent mooring applications, unlocking substitution in tension-leg platform tendons and deepwater anchor systems.
Market Restraints
- Petrochemical Input Volatility:Ultra-high molecular weight polyethylene resin prices track ethylene feedstock costs, compressing margin predictability for synthetic hawser manufacturers during energy price spikes.
- Brazilian Content Requirements:ANP-mandated local content thresholds for mooring integrity protocols limit supplier participation to firms with established Brazilian manufacturing or partnership structures.
- Wire Rope Incumbency:Traditional steel wire rope retains cost advantages in shallow-water temporary moorings and emergency towing, delaying full synthetic penetration in price-sensitive segments.
Strategic Opportunities
- Arctic Shipping Expansion:IMO's Polar Code mandates specialized cold-weather mooring equipment for vessels operating above 60 degrees north, creating certification-gated demand for low-temperature-flexible synthetic constructions.
- Offshore Wind Farm Mooring:Floating offshore wind platforms in the Celtic Sea and Gulf of Maine require dynamic station-keeping systems sized for turbine-scale loads, opening a new application vertical for extra-large diameter hawsers.
- Bio-Based Fiber Development:Lifecycle carbon accounting in EU procurement tenders creates early-mover advantage for suppliers developing certified bio-based alternatives to petroleum-derived HMPE and polyester.
Industry Challenges
- DNV Certification Bottlenecks:Extended type-approval timelines for novel fiber constructions and braiding geometries delay product commercialization, particularly for plasma rope variants targeting subsea tension-leg applications.
- Specialized Braiding Technician Shortage:Captive manufacturing of large-diameter synthetic hawsers requires skilled operators for multi-layer braiding platforms, constraining capacity expansion for mid-tier suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Hawser Market |
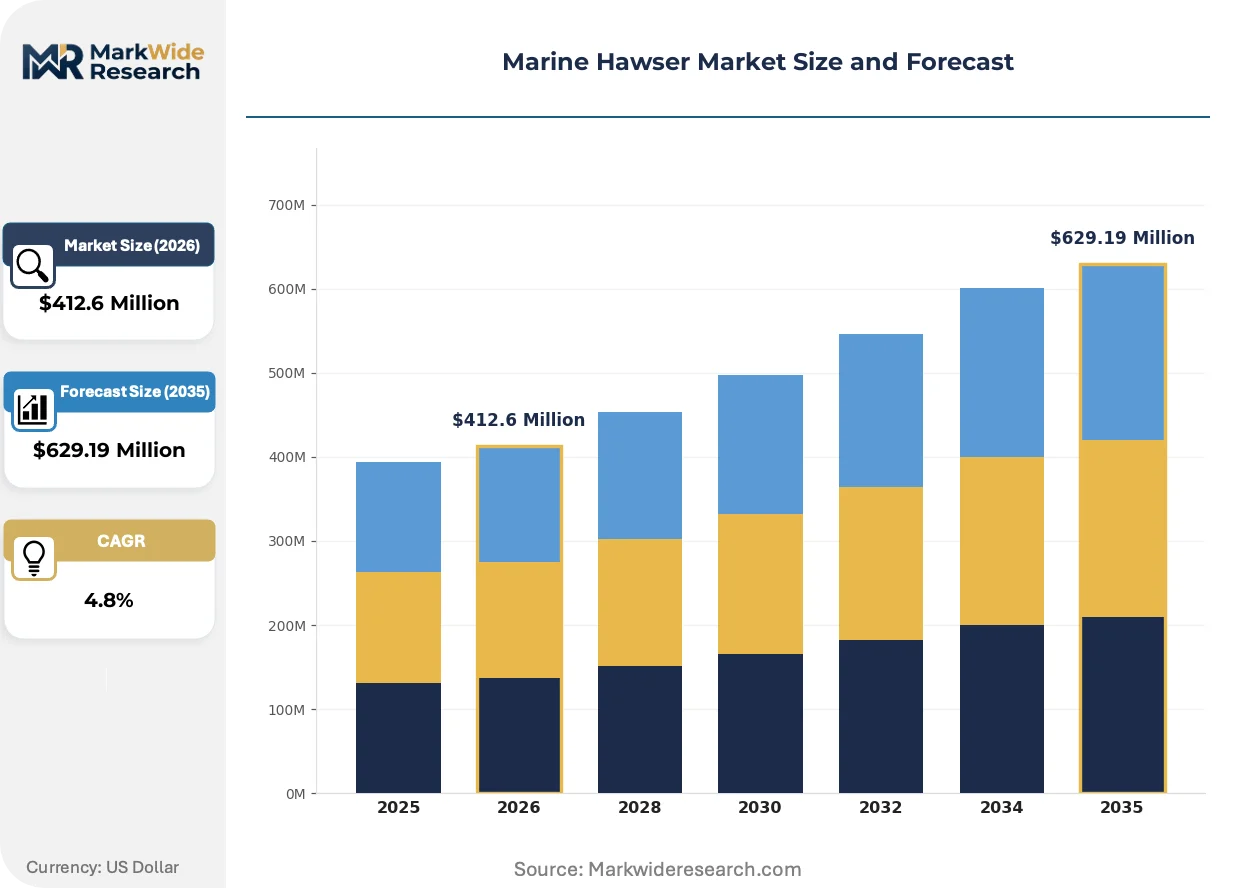
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $629.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polyester, Nylon, Natural Fiber Application: Shipping, Fishing, Offshore Construction, Salvage Operations End User: Shipping Companies, Fishing Operators, Maritime Services, Port Authorities Diameter: Small, Medium, Large, Extra Large |
| Companies Covered | Samson Rope Technologies, Cortland Limited, Offspring International, SBM Offshore, MODEC Inc., BW Offshore, Delmar Systems, Trelleborg, Entrion Wind, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Hawser Market Evolving Landscape
Active fiber substitution is compressing traditional material hierarchies across marine mooring, with regulatory carbon accounting and weight-reduction engineering converging to accelerate synthetic platform adoption.
Plasma rope manufacturing for subsea tension-leg platforms is electrifying competitive positioning in the ultra-deepwater segment. Offshore operators in Brazil and the Gulf of Mexico are specifying plasma-derived constructions for permanent moorings below 1,500 meters. This technology is electrifying margin capture for suppliers with captive braiding capabilities, compressing participation to firms with in-house plasma processing.
API RP 2SK guideline revisions for station-keeping design now incorporate synthetic fiber-specific fatigue modeling, shifting engineering practice across the US Gulf Coast and West African deepwater developments. The updated framework mandates extended cyclic loading test protocols for permanent mooring hawsers. Polyester and HMPE constructions in Brazil's pre-salt fields face accelerated re-qualification timelines under the new standard.
Integrated mooring system contracting is displacing component-only procurement in major floating production projects. EPC contractors now bundle hawser supply with installation engineering and integrity monitoring, compressing the supplier base to firms with subsea service capabilities. This pattern concentrates most visibly in Brazil, where Petrobras-led FPSO tenders favor single-source mooring responsibility.
Marine Hawser Market Segmentation
Marine hawser procurement varies sharply by operational intensity and regulatory exposure. Buyers prioritize creep resistance for permanent moorings, energy absorption for dynamic loads, and weight reduction for deepwater deployments.
Product Type:
Cost tier separates commodity buyers from performance-specification purchasers across fiber chemistry choices.
- Polyester:High-tenacity polyethylene terephthalate yarns deliver proven creep resistance under sustained static loads. Permanent FPSO moorings in Brazil's pre-salt basins specify polyester cores for 25-year service life requirements.
- HMPE (High-Modulus Polyethylene):Ultra-high molecular weight polyethylene braiding achieves strength-to-weight ratios double that of polyester. Deepwater tension-leg platforms in the Gulf of Mexico specify HMPE tendons to reduce topside payload.
- Polypropylene:Lightweight olefin fiber resists chemical degradation and floats in seawater. Fishing fleets and temporary mooring applications favor polypropylene for cost efficiency and handling ease.
- Nylon:Polyamide construction provides 15-25% elastic elongation under load. Emergency towing and ship-to-ship transfer operations specify nylon hawsers for energy absorption during shock loading.
- Natural Fiber:Manila and sisal constructions serve heritage vessel restoration and specific flag-state regulatory exemptions. Niche demand concentrates in traditional sailing vessel operations and museum fleet maintenance.
Polyester leads volumes today; HMPE is gaining share fastest.
Application:
Operational environment dictates fiber selection, inspection protocols, and replacement cycles.
- Offshore Construction:Permanent floating production systems require DNV-certified synthetic moorings with fatigue-tested splice configurations. Brazil's ANP-mandated integrity protocols enforce continuous monitoring for station-keeping hawsers.
- Shipping:Container vessels and tankers deploy high-diameter polyester lines for single-point mooring at liquid bulk terminals. EU Green Deal carbon accounting is accelerating fiber-transition timelines for European-flag fleets.
- Salvage Operations:Dynamic load cycling demands energy-absorbing nylon constructions with chafe protection. North Sea salvage contractors specify hybrid rope-wire configurations for wreck recovery.
- Fishing:Trawl and purse-seine operations favor polypropylene for buoyancy and abrasion resistance. Alaskan and North Atlantic fleets prioritize UV-stabilized treatments for extended seasonal deployment.
Shipping dominates current procurement volumes; offshore construction shows the steepest expansion trajectory.
End User:
Procurement sophistication ranges from spot-market purchasing to integrated long-term contracting.
- Shipping Companies:Fleet operators with 50+ vessels negotiate multi-year supply agreements with certified manufacturers. Major container lines specify type-approved hawsers for automated mooring systems at Rotterdam and Singapore.
- Maritime Services:Towage and salvage contractors maintain rapid-deployment inventories across multiple fiber grades. UK and Norwegian North Sea operators stock HMPE emergency sets for ultra-deepwater response.
- Port Authorities:Public terminal operators issue tender-based procurement with lifecycle cost evaluation. Brazilian port complexes enforce local content requirements under ANP guidelines.
- Fishing Operators:Artisanal and industrial fleets purchase through regional distributors with seasonal credit terms. Alaskan crab and groundfish sectors specify US-manufactured lines for Jones Act compliance.
Shipping companies command the largest contract values; maritime services are expanding procurement most quickly.
Diameter:
Manufacturing complexity and certification burden escalate non-linearly with rope dimension.
- Extra Large:Diameters exceeding 120mm require specialized braiding platforms and individual break-test certification. Floating offshore wind platforms in the Celtic Sea specify extra-large HMPE for turbine-scale mooring loads.
- Large:80-120mm constructions serve deepwater FPSO permanent mooring and heavy-lift offshore towing. Petrobras pre-salt contracts concentrate demand for large-diameter plasma rope.
- Medium:40-80mm hawsers balance handling characteristics with load capacity. General cargo shipping and coastal construction represent core demand.
- Small:Under 40mm diameters serve auxiliary lines, tender mooring, and recreational marine. Commodity pricing and distributor inventory cycles shape procurement patterns.
Medium diameters anchor current production volumes; extra large is climbing the fastest as floating wind scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's pre-salt basin developments concentrate deepwater mooring demand for synthetic hawser procurement. Floating production installations across the Santos and Campos basins drive specifications for high-modulus polyethylene fiber constructions. National content mandates reshape supplier qualification requirements.
Brazil
Petrobras-operated FPSO deployments in the Búzios and Mero fields anchor regional procurement volumes. ANP-mandated local content thresholds for mooring integrity protocols restrict contract participation to suppliers with established Brazilian manufacturing partnerships. Rio de Janeiro's offshore services cluster hosts certification facilities and splice testing laboratories serving pre-salt developments.
United States
Gulf of Mexico tension-leg platforms and planned floating offshore wind arrays in the Gulf of Maine generate dual demand vectors. API RP 2SK guideline revisions enforce synthetic fiber-specific fatigue modeling for permanent mooring designs. Houston's subsea engineering corridor concentrates procurement decision-making for deepwater developments.
Norway
North Sea offshore wind expansion and Arctic shipping routes under IMO Polar Code jurisdiction drive cold-weather mooring specifications. DNV classification rules for offshore mooring systems originate from Oslo headquarters and propagate globally. Stavanger's subsea technology cluster anchors engineering specifications for synthetic station-keeping systems.
United Kingdom
Celtic Sea floating wind lease rounds and North Sea salvage operations sustain diversified demand. EU Green Deal maritime decarbonization mandates accelerate fiber-transition timelines for British-flag fleets and port infrastructure. Aberdeen's offshore engineering base transitions expertise from oil and gas toward renewable mooring applications.
China
Domestic shipbuilding output and port infrastructure modernization expand medium-diameter hawser consumption. GB standards for marine mooring equipment and dual carbon goals influence procurement specifications at state-owned terminal operators. Shanghai's maritime equipment manufacturing hub scales synthetic rope production for domestic and export markets.
Marine Hawser Market Competitive Landscape
Global majors compete with regional champions across certification-gated deepwater segments and price-sensitive coastal applications. Market structure tiers between DNV-certified synthetic specialists serving FPSO operators and commodity-grade suppliers filling fishing and temporary mooring demand. Three archetypes dominate: captive plasma rope manufacturers, integrated mooring system designers, and regional distributors with braiding capabilities. Capacity expansion and strategic partnerships represent the primary competitive vectors as floating wind applications scale.
Within the high-performance synthetic tier, Samson Rope Technologies and Cortland Limited exemplify divergent strategic positions. Samson anchors the premium segment through proprietary braiding platforms targeting deepwater permanent moorings. Cortland occupies a position tied to captive plasma rope manufacturing for subsea tension-leg applications. Offspring International represents the integrated-systems archetype, bundling hawser supply with installation engineering to capture single-source contracting preferences in Brazilian FPSO tenders.
| Leading Market Players |
|---|
| Samson Rope Technologies |
| Cortland Limited |
| Offspring International |
| SBM Offshore |
| MODEC Inc. |
| BW Offshore |
| Delmar Systems |
| Trelleborg |
| Entrion Wind |
| Others |
Value Network & Pricing Analysis
Ethylene feedstock price volatility cascades through ultra-high molecular weight polyethylene resin markets into three-tier hawser pricing structures, compressing margin predictability for synthetic fiber manufacturers while amplifying cost premiums for certified deepwater constructions.
Pricing Analysis
Input-cost pass-through from petrochemical feedstocks dominates synthetic hawser pricing, with HMPE grades absorbing resin fluctuations more acutely than polyester alternatives. Three-tier pricing structure across premium, standard, and economy levels separates DNV-certified plasma rope for Brazilian FPSO tenders from commodity polyester lines for coastal shipping. Price differentiation hinges on certification grade and captive braiding capability, with integrated mooring system bundling commanding substantial premiums over component-only supply. Cost compression in standard-grade polyester is intensifying because of Asian capacity expansion, while emergency towing contractors prove most price-sensitive versus deepwater operators prioritizing break-strength parity.
Supply Chain Analysis
Single-source vulnerability sits with ultra-high molecular weight polyethylene resin production concentrated in the United States, the Netherlands, and Japan, where specialty polymer manufacturing requires dedicated reactor infrastructure. Raw material flows draw from ethylene feedstock, high-tenacity polyester yarn, and plasma-processed fiber, with each tier tethered to distinct petrochemical value chains. Tariff exposure on finished rope imports into Brazil threatens non-localized suppliers competing for ANP-mandated content thresholds. Distribution runs through direct EPC contracting for offshore projects and regional distributor networks for shipping and fishing fleet replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The marine hawser market functions as a regulatory compounder, where EU Green Deal maritime decarbonization mandates and Brazil's ANP local content protocols continuously reshape procurement specifications and supplier qualification barriers.
For Market Incumbents: Hedge against HMPE fiber commoditization by deepening backward integration into captive plasma processing and securing Brazilian manufacturing partnerships before ANP content thresholds tighten further. Reinforce certification moats through accelerated DNV type-approval for bio-based fiber alternatives as lifecycle carbon accounting penetrates European tenders. Capacity addition in Rio de Janeiro's offshore services cluster offers defensive positioning against emerging Asian competitors. For New Entrants and Emerging Players: The price-point gap between premium plasma rope and economy-grade polypropylene hawsers creates entry space for mid-tier HMPE specialists targeting North Sea offshore wind and Arctic shipping applications. Floating wind mooring in the Celtic Sea and Gulf of Maine represents the most penetrable vertical, with turbine-scale loads demanding extra-large diameters where certification complexity limits incumbent participation. A go-to-market angle bundling installation engineering with hawser supply mirrors Petrobras-preferred contracting structures. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier braiding operations lack captive plasma capability yet possess established DNV certification pipelines. Long-term viability favors suppliers with demonstrated synthetic fiber fatigue modeling under API RP 2SK revisions and proven Brazilian local content compliance. Target acquisition archetypes include regional distributors with braiding platforms in Atlantic-facing markets. The signal to watch is floating offshore wind lease round announcements in North Atlantic jurisdictions, which trigger step-function demand for extra-large diameter HMPE constructions.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Plasma Rope Manufacturing | In-house plasma processing locks in margin capture for Brazilian ultra-deepwater tenders. |
| Bio-Based Fiber Certification | DNV type-approval for bio-HMPE unlocks EU Green Deal procurement preferences. |
| Brazilian Manufacturing Partnership | Local content compliance secures ANP-mandated FPSO mooring contracts. |
| Integrated Mooring System Contracting | Installation engineering bundling mirrors Petrobras single-source preferences. |
| Arctic Cold-Weather Qualification | IMO Polar Code certification gates access to high-margin northern shipping routes. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with offshore construction procurement directors, DNV certification engineers, synthetic fiber R&D leads, and Brazilian port authority technical officers with secondary validation. Trade data from customs authorities, API RP 2SK guideline documentation, ANP regulatory filings, and offshore project development databases anchored supply-side sizing. Bottom-up installation counts for FPSO and floating wind units triangulated against top-down synthetic fiber consumption estimates from petrochemical industry associations.
Segment-weighting approaches modeled fiber chemistry, diameter class, application vertical, and end-user procurement sophistication across the projection horizon. CAGRs derived from elasticity-adjusted demand functions incorporating regulatory mandate timelines and project pipeline visibility. Industry-specific forecast inputs included Petrobras pre-salt development schedules, EU offshore wind auction calendars, and IMO Polar Code enforcement phases for Arctic shipping corridors.
Caveats apply where ethylene feedstock price spikes, extended DNV type-approval timelines, or Brazilian local content threshold revisions could materially shift the outlook. Forecasts reflect documented assumptions about synthetic fiber substitution rates and floating wind deployment velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine and Coastal Engineering
Floating Docks Market
Marine and Coastal Engineering
Submersible Dredge Pump Market
Marine and Coastal Engineering
Global Marine Ventilation Systems Market
Marine and Coastal Engineering
Mooring Bollards Market
Marine and Coastal Engineering
Marine Heat Exchanger Market
Marine and Coastal Engineering
Cable Laying Vessel Market
Marine and Coastal Engineering
Work Barges Market
Marine and Coastal Engineering
STS (Ship-To-Shore) Cranes Market
Marine and Coastal Engineering
Marine Cranes Market
Marine and Coastal Engineering
Flood Control Sandbags Market
Marine and Coastal Engineering
Crane Barge Market
Marine and Coastal Engineering
Marine Watertight Door Market
Marine and Coastal Engineering
Global Pipe Laying Vessel Market
Marine and Coastal Engineering
Asia-Pacific Offshore Crane Market
Marine and Coastal Engineering
Mooring Compensators Market
Marine and Coastal Engineering
Subsea Trencher Market