
 Hydrolyzed Oat Protein Market | 2026-2036
Hydrolyzed Oat Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrolyzed Oat Protein Market Foresight
Market Context
Sweden is tilting toward expanded oat protein fractionation capacity as Lantmännen leverages its cooperative farmer network to secure raw oat supply. Cargill Inc. anchors North American distribution through its existing plant protein infrastructure. Croda International PLC specializes in cosmetic-grade hydrolyzed oat protein for premium skin care brands.
Technical Definition and Segment Structure
Hydrolyzed oat protein refers to enzymatically or acid-cleaved protein fractions derived from Avena sativa, typically yielding peptides with molecular weights below 10 kDa that function as film-forming agents and moisture binders. Powdered hydrolyzed oat protein dominates formulation flexibility in dry-blend nutritional supplements, while liquid hydrolyzed oat protein leads in cosmetic serum applications where solubility and sensory profile determine adoption. Food and beverages represents the most mature application segment, whereas cosmetics and personal care captures the fastest margin expansion as brands reformulate around plant-derived alternatives.
Regulatory Frame and Outlook
REACH in Europe and FDA GRAS self-determination in the United States create divergent compliance burdens that shape ingredient documentation costs and market access timelines. EFSA novel food consultations and EPA agricultural processing permits add layered oversight for new extraction facilities. Stakeholders must monitor evolving cosmetic ingredient disclosure mandates in California and the EU to anticipate reformulation timelines and certification investments.
Market Dynamics
Cosmetic formulators are accelerating hydrolyzed oat protein adoption as REACH disclosure mandates and clean-label certification requirements force ingredient transparency upgrades across European and North American supply chains.
Growth Catalysts
- REACH ingredient transparency:ECHA registration requirements for cosmetic-grade hydrolyzed proteins are compelling brands to document peptide molecular weight profiles and enzymatic hydrolysis pathways, elevating documented suppliers above commodity alternatives.
- Film-forming functional demands:Skin care serum manufacturers are specifying hydrolyzed oat protein for moisture-binding applications where peptides below 10 kDa demonstrate superior barrier repair versus synthetic polyquaternium compounds.
- German processing cluster concentration:Overlapping oat fractionation facilities and natural cosmetics manufacturing in Bavaria and Baden-Württemberg are compressing raw material-to-formulation lead times for regional beauty brands.
Market Restraints
- Avena sativa supply volatility:Nordic oat harvest fluctuations and grain price arbitrage with feed markets create input cost instability for hydrolyzed protein processors dependent on food-grade oat groats.
- EFSA novel food consultation timelines:Extended safety assessment periods for new hydrolyzed protein extraction methods delay market entry for innovative enzymatic processes, freezing capacity expansion decisions.
- Plant protein substitution breadth:Rice, pea, and wheat hydrolysates offer comparable film-forming functionality at lower certification burdens, constraining oat protein pricing power in mass-market cosmetic tiers.
Strategic Opportunities
- Scandinavian cooperative supply models:Swedish farmer-owned processing networks demonstrate captive raw material access that multinational ingredient suppliers cannot replicate without multi-year contract cultivation investments.
- Biotechnology-enzyme convergence:Precision protease engineering and membrane filtration integration are enabling targeted peptide fractionation for pharmaceutical-grade applications beyond cosmetic use cases.
- California cosmetic ingredient disclosure mandates:The state's Fragrance and Flavor Ingredient Right to Know Act is accelerating demand for fully documented hydrolyzed protein supply chains that preempt regulatory scrutiny.
Industry Challenges
- Cosmetic chemist specialization scarcity:Formulation expertise bridging plant protein chemistry and skin microbiome science commands premium compensation, constraining R&D team scaling for mid-tier ingredient suppliers.
- GRAS self-determination documentation burden:FDA's lack of pre-market approval for hydrolyzed oat protein in food applications forces manufacturers to maintain extensive safety dossiers without standardized submission pathways, elevating legal compliance costs.
- Multi-certification synchronization:Simultaneous pursuit of COSMOS organic, ECOCERT, and NSF/ANSI 305 certifications creates overlapping audit requirements that fragment quality management resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrolyzed Oat Protein Market |
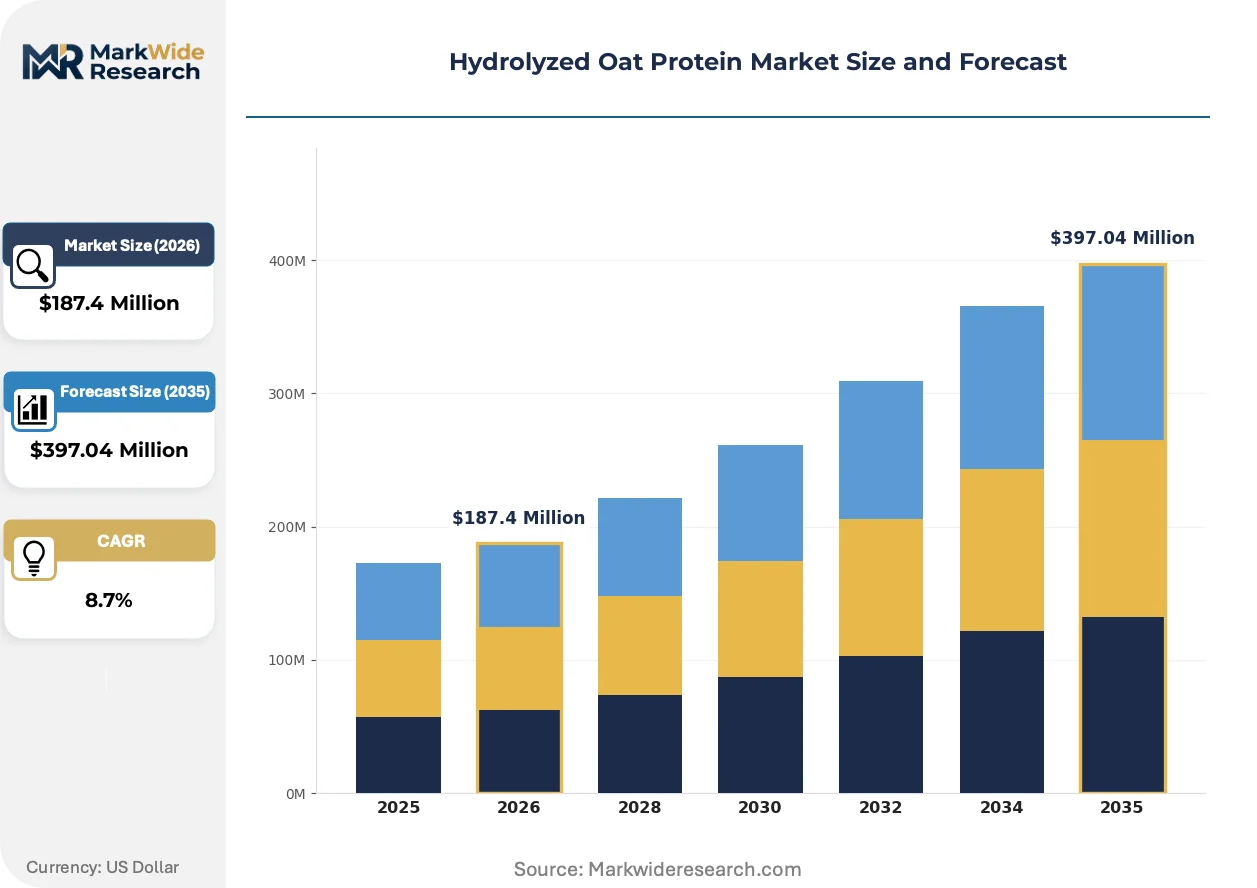
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Hydrolyzed Oat Protein, Powdered Hydrolyzed Oat Protein, Concentrated Hydrolyzed Oat Protein, Isolated Hydrolyzed Oat Protein Application: Food & Beverages, Nutritional Supplements, Cosmetics & Personal Care, Animal Feed End User: Food Manufacturers, Cosmetic Brands, Nutraceutical Companies, Animal Feed Producers Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Cargill Inc., Archer Daniels Midland, Tate & Lyle PLC, Givaudan SA, Croda International PLC, Kerry Group PLC, Lantmännen, Roquette Frères, Avena Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrolyzed Oat Protein Market Shifts & Advancements
Enzymatic hydrolysis precision and peptide characterization analytics are transforming hydrolyzed oat protein from a commodity botanical extract into a specification-critical functional ingredient for premium cosmetic formulations.
Membrane filtration-coupled enzymatic hydrolysis is rendering obsolete traditional acid-hydrolysis methods that produce broader molecular weight distributions and inconsistent sensory profiles. Premium skin care brands in Germany and France are specifying narrow-cut peptide fractions for anti-aging serums, compressing margins for undifferentiated commodity suppliers.
REACH Annex XVII restrictions on allergen labeling and the EU Green Deal's sustainable chemistry incentives are accelerating investment in enzymatic processing facilities with closed-loop water systems. Cosmetic ingredient distributors are prioritizing suppliers with documented carbon footprint reductions, disadvantaging acid-hydrolysis operations with higher effluent treatment burdens.
Beauty brand technical buyers are consolidating supplier relationships around full-chain documentation capabilities, displacing spot-market purchasing for hydrolyzed proteins. Direct partnerships between Scandinavian oat processors and North American clean beauty brands are bypassing traditional ingredient distribution layers, most visibly in California's indie skin care segment where founders prioritize traceable farm-to-face narratives.
Hydrolyzed Oat Protein Market Segmentation
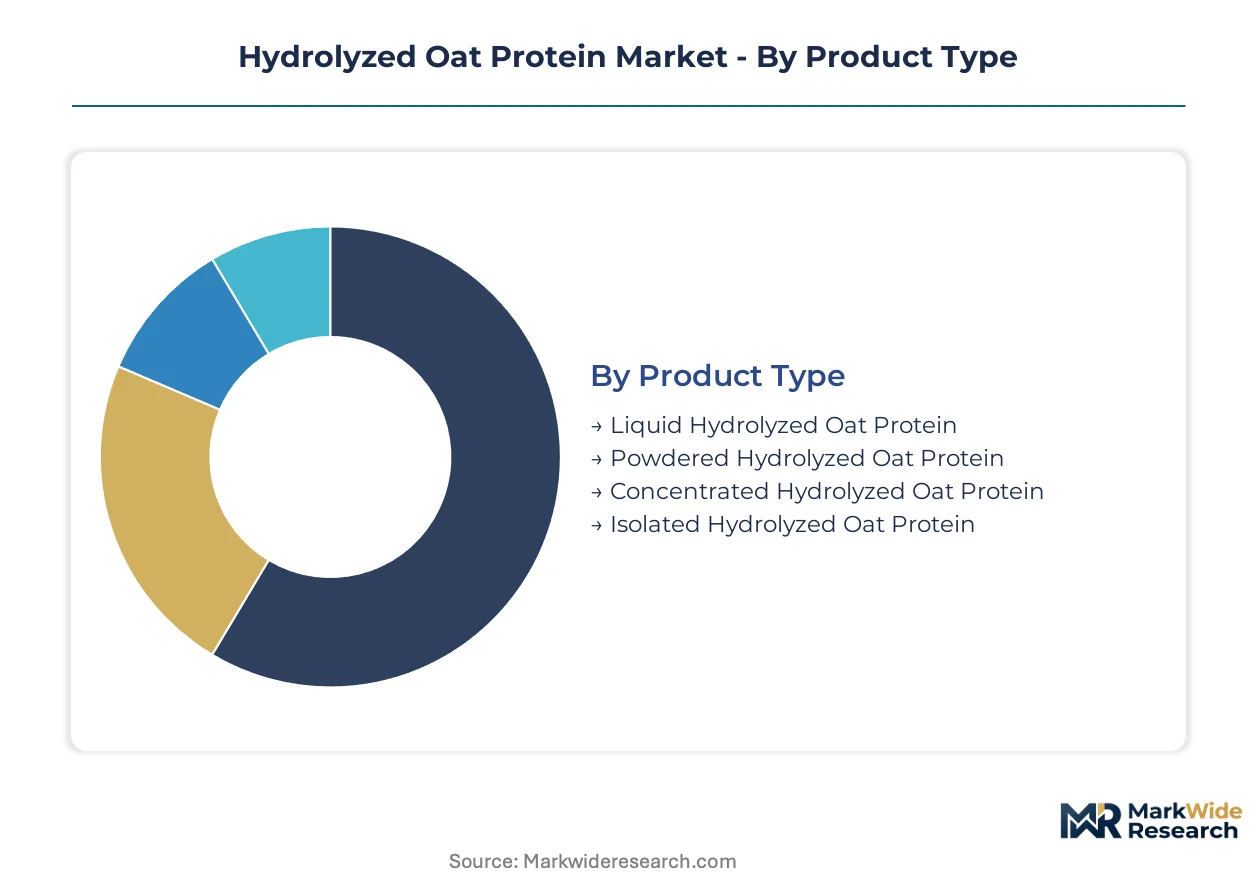
Segmentation in hydrolyzed oat protein markets exposes how formulation requirements diverge sharply between cosmetic serum manufacturers seeking sensory precision and food processors prioritizing cost-efficient bulk incorporation. Technical specifications around molecular weight distribution and solubility profiles create non-substitutable demand pockets that resist commoditization.
Product Type:
After-sales technical support intensity varies dramatically across product formats, with liquid formulations demanding ongoing formulation troubleshooting while powders require minimal post-sale intervention.
- Liquid Hydrolyzed Oat Protein:Pre-dissolved aqueous solutions with standardized peptide concentrations between 15-25% enable direct incorporation into cosmetic emulsions without hydration protocols. Demand concentrates in German and French premium skin care manufacturing where serum viscosity control and transparent finished-product aesthetics override raw material cost considerations.
- Powdered Hydrolyzed Oat Protein:Spray-dried particulates with moisture content below 5% maximize shelf stability and freight efficiency for dry-blend nutritional applications. Sports nutrition contract manufacturers in the United States specify powder formats for protein bar and shake powder formulations where dissolution kinetics and flavor masking determine supplier selection.
- Concentrated Hydrolyzed Oat Protein:Intermediate protein content grades serving regional food processors with intermediate technical capabilities and budget constraints.
- Isolated Hydrolyzed Oat Protein:Highest purity fractions targeting pharmaceutical and medical nutrition applications with stringent contaminant thresholds.
By volume, powdered formats lead. By growth pace, liquid hydrolyzed oat protein is expanding most quickly.
Application:
Margin structures across applications separate mature food-grade commodity supply from emerging cosmetic-grade premium positioning.
- Cosmetics & Personal Care:Film-forming peptides below 10 kDa molecular weight deliver barrier repair functionality in anti-aging serums and sensitive-skin moisturizers. Clean beauty brands in California and Scandinavian markets specify documented enzymatic hydrolysis pathways to satisfy REACH disclosure mandates and state-level ingredient transparency laws.
- Food & Beverages:Plant-based dairy alternatives and gluten-free bakery applications leverage oat protein for emulsion stability and nutritional fortification. European oat milk manufacturers in Sweden and Finland integrate hydrolyzed fractions to improve foam stability in barista-grade formulations.
- Nutritional Supplements:Hypoallergenic protein positioning targets consumers with soy and dairy sensitivities in North American and European sports nutrition segments.
- Animal Feed:Functional protein ingredients for premium pet food formulations emphasizing digestibility and palatability in wet food applications.
Food and beverages commands volume leadership. Cosmetics and personal care captures the steepest expansion trajectory.
End User:
Procurement sophistication tiers separate multinational ingredient buyers with dedicated technical audit teams from mid-tier formulators relying on distributor certifications.
- Cosmetic Brands:Premium positioning demands full-chain documentation from Scandinavian oat cultivators through enzymatic processing facilities. Technical buyers conduct on-site supplier audits verifying peptide characterization capabilities and closed-loop water treatment systems.
- Food Manufacturers:Scale-driven procurement prioritizes volume pricing and supply security over traceability narratives. Oat milk and plant-based yogurt producers negotiate multi-year contracts with Swedish cooperative processors.
- Nutraceutical Companies:Regulatory compliance burden around novel food consultations and GRAS documentation shapes supplier selection for functional food positioning.
- Animal Feed Producers:Cost-sensitive procurement with limited formulation technical support requirements.
Food manufacturers dominate volume absorption. Cosmetic brands are gaining share fastest.
Distribution Channel:
Channel selection reflects customer technical confidence and order scale thresholds.
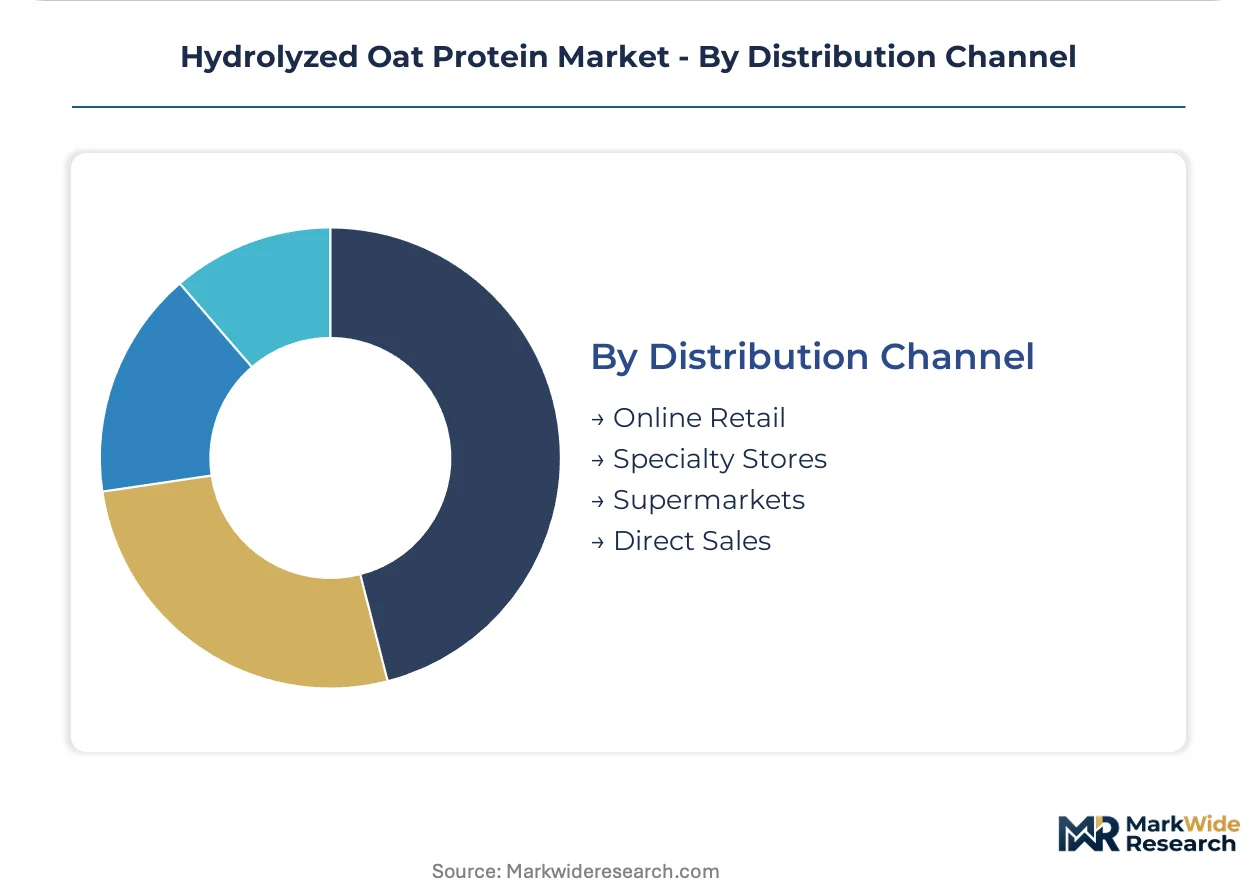
- Direct Sales:Technical ingredient specialists maintain direct relationships with cosmetic brand R&D teams, providing peptide characterization data and co-formulation support. Croda International and comparable suppliers bypass distribution layers for premium accounts.
- Specialty Stores:Regional ingredient distributors serving mid-tier cosmetic and food manufacturers with consolidated botanical and protein portfolios.
- Online Retail:E-procurement platforms capture small-batch cosmetic startup demand and artisan food producer orders below minimum direct-sale thresholds.
- Supermarkets:Limited penetration for industrial-grade hydrolyzed proteins; primarily serves hobbyist and small-scale cosmetic formulators.
Direct sales leads by value contribution. Online retail climbs fastest among emerging channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oat fractionation capacity clusters in Northern Europe where cooperative supply networks intersect with enzymatic processing infrastructure. Bavarian and Baden-Württemberg cosmetic manufacturing hubs draw raw material from these Scandinavian supply bases, compressing formulation lead times for regional beauty brands.
Germany
REACH Annex XVII disclosure mandates propel cosmetic-grade hydrolyzed oat protein specification as Bavarian and Baden-Württemberg natural cosmetics manufacturers demand documented peptide molecular weight profiles. ECHA registration requirements elevate certified suppliers above commodity alternatives. The Munich-Stuttgart corridor concentrates enzymatic processing facilities serving premium skin care brands.
United States
FDA GRAS self-determination frameworks shape food-grade hydrolyzed oat protein market entry without pre-market approval pathways. California's Fragrance and Flavor Ingredient Right to Know Act accelerates demand for fully documented supply chains among indie skin care founders prioritizing traceable farm-to-face narratives. Minneapolis-based Cargill anchors North American distribution through existing plant protein infrastructure.
Sweden
Lantmännen leverages its cooperative farmer network to secure captive raw oat supply for expanded fractionation capacity. EFSA novel food consultation timelines for innovative extraction methods delay capacity expansion decisions for new entrants. Skåne County oat processing clusters overlap with natural cosmetics manufacturing in the Stockholm-Uppsala corridor.
France
EU Green Deal sustainable chemistry incentives accelerate investment in enzymatic processing facilities with closed-loop water systems. ANSM cosmetic ingredient disclosure mandates tighten documentation requirements for peptide characterization. The Lyon-Grenoble axis concentrates premium skin care formulation expertise specifying narrow-cut peptide fractions for anti-aging serums.
United Kingdom
Post-Brexit divergence from REACH creates dual compliance burdens for hydrolyzed protein suppliers serving both UK and EU markets. The MHRA retains cosmetic safety assessment frameworks that mirror ECHA standards in practice. Greater Manchester and Yorkshire house contract manufacturing organizations integrating oat-derived ingredients for clean beauty brands.
Hydrolyzed Oat Protein Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying enzymatic fractions and peptide characterization services. The vendor base separates into three functional tiers: multinational agribusiness conglomerates with captive oat supply, mid-scale Scandinavian cooperatives leveraging farmer-owned processing networks, and cosmetic-grade specialists focused on premium skin care documentation. Consolidation pressures concentrate around REACH-compliant suppliers with verified carbon footprint reductions. Dominant competitive moves include backward integration into oat cultivation contracts and technology licensing for precision protease engineering.
Among agribusiness conglomerates, Cargill Inc. and Archer Daniels Midland occupy positions spanning commodity supply through formulated ingredient distribution. Croda International PLC exemplifies the cosmetic-grade specialist archetype, anchoring premium-tier positioning through documented enzymatic hydrolysis pathways. Lantmännen represents the cooperative model with captive Scandinavian raw material access that multinational competitors cannot replicate without multi-year contract cultivation investments.
| Leading Market Players |
|---|
| Cargill Inc. |
| Archer Daniels Midland |
| Tate & Lyle PLC |
| Givaudan SA |
| Croda International PLC |
| Kerry Group PLC |
| Lantmännen |
| Roquette Frères |
| Avena Foods |
| Others |
Supply & Pricing Matrix
Undercapacity in Scandinavian enzymatic processing facilities is compressing lead times for cosmetic-grade hydrolyzed oat protein and elevating pricing leverage for certified suppliers serving German and French premium skin care brands. REACH registration requirements and EFSA novel food consultation backlogs are amplifying this dynamic by freezing capacity expansion timelines for new market entrants.
Pricing Analysis
REACH Annex XVII dictates the pricing tier structure across the hydrolyzed oat protein market, separating documented enzymatic processors from acid-hydrolysis commodity suppliers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and peptide characterization depth. Cost compression in economy tiers is intensifying because rice and pea hydrolysates offer comparable film-forming functionality at lower compliance burdens. Mass-market cosmetic manufacturers exhibit highest price sensitivity, while German premium serum brands prioritize molecular weight documentation over unit economics.
Supply Chain Analysis
Extended payment terms from Scandinavian cooperative processors to German cosmetic manufacturers are stabilizing working capital flows across the enzymatic supply chain. Raw material sourcing concentrates in Sweden, Germany, and France, drawing from Nordic oat cultivators and Bavarian fractionation clusters. Processing infrastructure rests on food-grade oat groat supply, precision protease enzymes, and membrane filtration systems. Single-source vulnerability around Swedish farmer-owned networks creates concentration risk. Distribution runs through direct technical sales for premium cosmetic accounts and specialty ingredient distributors for mid-tier food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as beauty brands consolidate supplier relationships around full-chain documentation capabilities that preempt California and EU regulatory scrutiny. Interoperability between peptide characterization analytics and cosmetic formulation software is accelerating this consolidation.
For Market Incumbents: Harden defensible positioning by deepening captive oat supply through multi-year Scandinavian cultivation contracts and accelerating COSMOS organic certification investments. Rice and pea protein substitution threats in mass-market tiers demand premium-tier margin protection through narrow-cut peptide fractionation capabilities that commodity suppliers cannot replicate. For New Entrants and Emerging Players: North American contract manufacturing white-space offers the most penetrable entry corridor, particularly among California indie skin care startups prioritizing traceable farm-to-face narratives over established supplier relationships. Biotechnology-enzyme convergence for pharmaceutical-grade applications represents a second white-space target with higher margin potential than cosmetic commodity supply. Go-to-market execution should anchor on direct technical partnerships with brand R&D teams rather than distributor channel builds. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cosmetic-grade specialists with documented enzymatic hydrolysis pathways and multi-year supply agreements with premium beauty brands. Long-term viability over the next decade hinges on backward integration into oat cultivation and precision protease engineering capabilities. Watch for EFSA novel food consultation resolution timelines as the inflection signal for capacity expansion decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oat Cultivation | Scandinavian cooperative networks secure captive raw material access that multinational competitors cannot replicate without multi-year contract investments. |
| Precision Protease Engineering Licensing | Targeted peptide fractionation capabilities unlock pharmaceutical-grade applications beyond cosmetic use cases. |
| COSMOS Organic Certification Investment | Preemptive compliance with overlapping EU and California disclosure mandates compresses competitor response windows. |
| Direct Technical Sales Channel Build | Bypassing distributor layers captures premium cosmetic accounts requiring peptide characterization data and co-formulation support. |
| Closed-Loop Water System Installation | EU Green Deal sustainable chemistry incentives reward enzymatic processors with verified carbon footprint reductions. |
Research Methodology
The analysis maps enzymatic hydrolysis processors, cosmetic formulation houses, and food-grade fractionation facilities, each validated through cosmetic chemists, oat processing plant managers, and regulatory affairs specialists. Primary interviews with technical buyers at premium skin care brands, procurement leads at Swedish cooperatives, and peptide characterization laboratory directors combined with secondary validation against EFSA consultation databases, REACH registration filings, and EU trade statistics. Bottom-up capacity modeling and top-down demand estimation triangulate market sizing across the projection horizon.
Assumptions held fixed include prevailing REACH disclosure mandates, EFSA novel food consultation timelines, and FDA GRAS self-determination frameworks; variables tested include oat harvest volatility, enzymatic processing technology diffusion rates, and California cosmetic ingredient disclosure enforcement intensity. The analytical framework segments by product format, application end-use, and procurement sophistication tier. CAGRs derive from segment-level demand elasticity modeling and capacity utilization trajectories. Industry-specific forecast inputs incorporate peptide molecular weight specification trends and clean beauty brand consolidation patterns.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by agribusiness conglomerates or rapid EFSA consultation streamlining would shift outcomes. Macroeconomic deviation in Nordic oat markets, regulatory acceleration in California or the EU, or breakthrough enzymatic processing technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
North America Soy Protein Market
Ingredients
GCC Bakery Ingredients Market
Ingredients
North America Fats and Oils Market
Ingredients
Centella Asiatica Extract Market
Ingredients
Pea Starch Market
Ingredients
Agar Agar Flakes Market
Ingredients
Colombia Food Ingredients Market
Ingredients
Low Fat Cooking Oil Market
Ingredients
APAC Savoury Ingredients Market
Ingredients
Fats and Oils Market
Ingredients
Meat Starter Culture Market
Ingredients
Cocoa Derivatives Market
Ingredients
Homecare Ingredients Market
Ingredients
Oak Extract Market
Ingredients
Algae Omega-3 Ingredients Market
Ingredients
Asia-Pacific Lipids Market