
 Cheese Ingredients Market | 2026-2036
Cheese Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Cheese Ingredients Market Analysis
Asset-light leasing models for industrial fermentation capacity are rewriting competitive entry barriers in enzyme and starter culture supply. Chr. Hansen Holding A/S leverages its microbial strain libraries to dominate specialized culture development for premium cheese varieties. DSM-Firmenich anchors its position through integrated biotechnology platforms that span enzyme engineering to nutritional lipid formulations. Kerry Group plc extends its reach by controlling flavor systems that bind cheese ingredients into finished food applications for manufacturers.
Cheese ingredients encompass milk proteins, enzymes, cultures, salts, and functional additives that undergo controlled fermentation, coagulation, and aging to develop texture, flavor, and shelf stability in dairy products. Rennet and microbial coagulants operate at precise temperature-pH windows to achieve protein cleavage and curd formation. Natural cheese ingredients command sustained volume leadership due to their centrality in aged and fresh cheese production across European and North American manufacturing bases. Processed cheese ingredients occupy expanding share in foodservice channels where meltability and standardized performance offset premium positioning. Cheese powders concentrate margin pools through their role in seasoning blends for snacks and convenience foods.
The European Food Safety Authority enforces strict evaluation thresholds for novel enzymes and processing aids entering cheese manufacturing workflows. The FDA in the United States governs GRAS determinations for cultures and coagulants, directly shaping which ingredient technologies achieve commercial scale in American dairy plants. ISO standards for dairy processing hygiene create baseline compliance costs that favor suppliers with established quality management systems. Stakeholders must track how evolving clean-label definitions in regulatory guidance documents will redraw permissible ingredient declarations across major dairy-producing jurisdictions.
Market Dynamics
Asset-light fermentation leasing is collapsing capital barriers for enzyme and starter culture entrants, enabling specialized suppliers to challenge incumbents without building captive biomanufacturing infrastructure.
Growth Catalysts
- Clean-label reformulation:Ready-to-eat meal manufacturers are stripping artificial preservatives from cheese-containing products, pulling demand for natural cultures and minimally processed milk proteins.
- REACH chemical tightening:Europe's evolving framework for processing aids is forcing ingredient suppliers to requalify enzymatic inputs, advantaging those with established EFSA dossiers.
- Cluster procurement scale:Large-scale dairy processing concentrations in Wisconsin and California generate bulk purchasing power that sustains continuous fermentation runs and lowers unit economics for culture suppliers.
Market Restraints
- Milk protein cost volatility:Whey and casein concentrate prices fluctuate with global dairy commodity cycles, compressing margin visibility for ingredient formulators dependent on spot procurement.
- Starter culture supply concentration:Proprietary microbial strain libraries remain concentrated among a handful of European biotechnology houses, creating single-source vulnerabilities for regional cheese manufacturers.
- Coagulant temperature-pH windows:Precision requirements for rennet and microbial coagulant activity limit substitution flexibility when supply disruptions force rapid input changes.
Strategic Opportunities
- Plant-based cheese analog expansion:Fermentation-derived casein mimics and precision-cultured dairy proteins open formulation pathways for vegan cheese applications previously inaccessible to traditional suppliers.
- India FSSAI enzyme approvals:India's food safety regulator is expanding its approved substances list for cheese manufacturing, creating first-mover advantage for suppliers with pre-filed technical dossiers.
- Direct-to-manufacturer digital channels:Specialty culture suppliers are bypassing traditional distribution layers through e-procurement platforms that connect strain libraries directly to mid-size dairy plant technical buyers.
Industry Challenges
- Strain banking expertise scarcity:Qualified microbiologists capable of maintaining cryopreserved culture collections and executing controlled phenotype expression are concentrated in legacy European biotechnology clusters.
- GRAS determination timelines:FDA review cycles for novel enzyme submissions extend commercialization windows, forcing suppliers to sustain R&D burn without near-term revenue offset.
- Legacy plant integration:Retrofitting continuous fermentation monitoring into batch-oriented cheese manufacturing infrastructure demands capital allocation that mid-size processors resist.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cheese Ingredients Market |
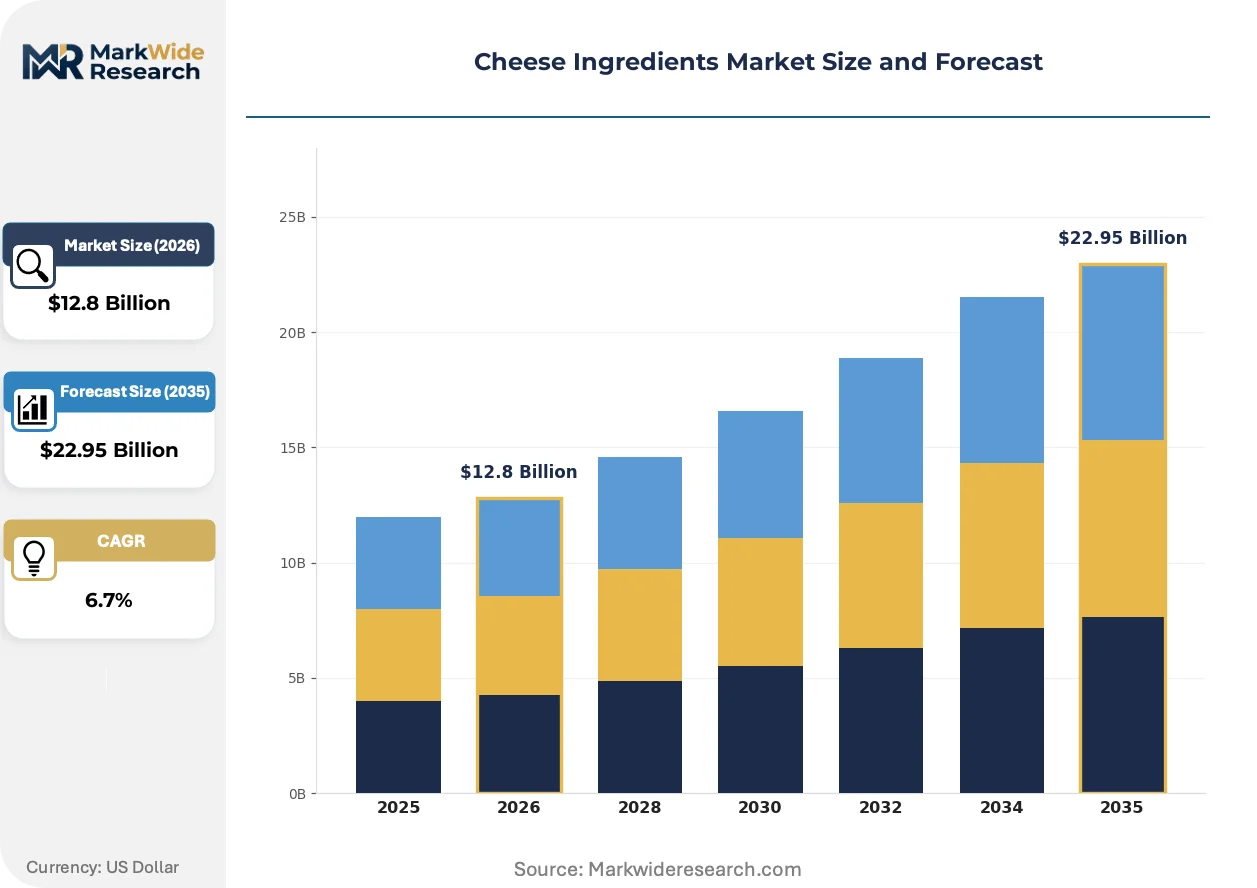
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Cheese, Processed Cheese, Cheese Powders, Cheese Sauces Application: Snacks, Dips, Baking, Sauces End User: Food Manufacturers, Retailers, Foodservice, Households Packaging Type: Bags, Boxes, Tubs, Pouches |
| Companies Covered | Arla Foods Ingredients Group P/S, Fonterra Co-operative Group Ltd, Chr. Hansen Holding A/S, DSM-Firmenich, Kerry Group plc, Lactalis, FrieslandCampina, Saputo, Bel Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cheese Ingredients Market Emerging Trajectories
Digital strain characterization and precision fermentation controls are compressing development cycles for specialized cheese cultures, while regulatory chemistry frameworks and shifting procurement behaviors redistribute competitive advantage across the supplier base.
Precision fermentation is virtualizing traditional culture development by enabling computer-guided strain optimization that predicts metabolic pathway outputs before pilot-scale validation. Mid-size cheese manufacturers in the United States are adopting these platforms to reduce reliance on external culture houses. The technology is virtualizing the economics of specialty variety production, allowing regional dairies to develop proprietary cultures without multi-million-dollar R&D infrastructure.
Europe's F-Gas Regulation is phasing down hydrofluorocarbon use in dairy processing cooling systems, indirectly constraining temperature-dependent enzymatic processing windows. Cheese ingredient suppliers must reformulate culture activity profiles to perform at elevated or less stable temperature bands. Aged cheese producers in France and Italy are investing in alternative refrigeration chemistries to preserve traditional aging protocols while maintaining EFSA-compliant manufacturing environments.
Consolidated foodservice distributors are unbundling after-sales technical support from ingredient supply contracts, forcing culture suppliers to compete on standalone advisory value. Large contract manufacturers in the United States are bringing sensory profiling and application testing in-house, displacing traditional supplier-provided formulation services. This behavioral shift concentrates purchasing leverage among buyers with captive technical capabilities while marginalizing suppliers dependent on bundled service relationships.
Cheese Ingredients Market Segmentation
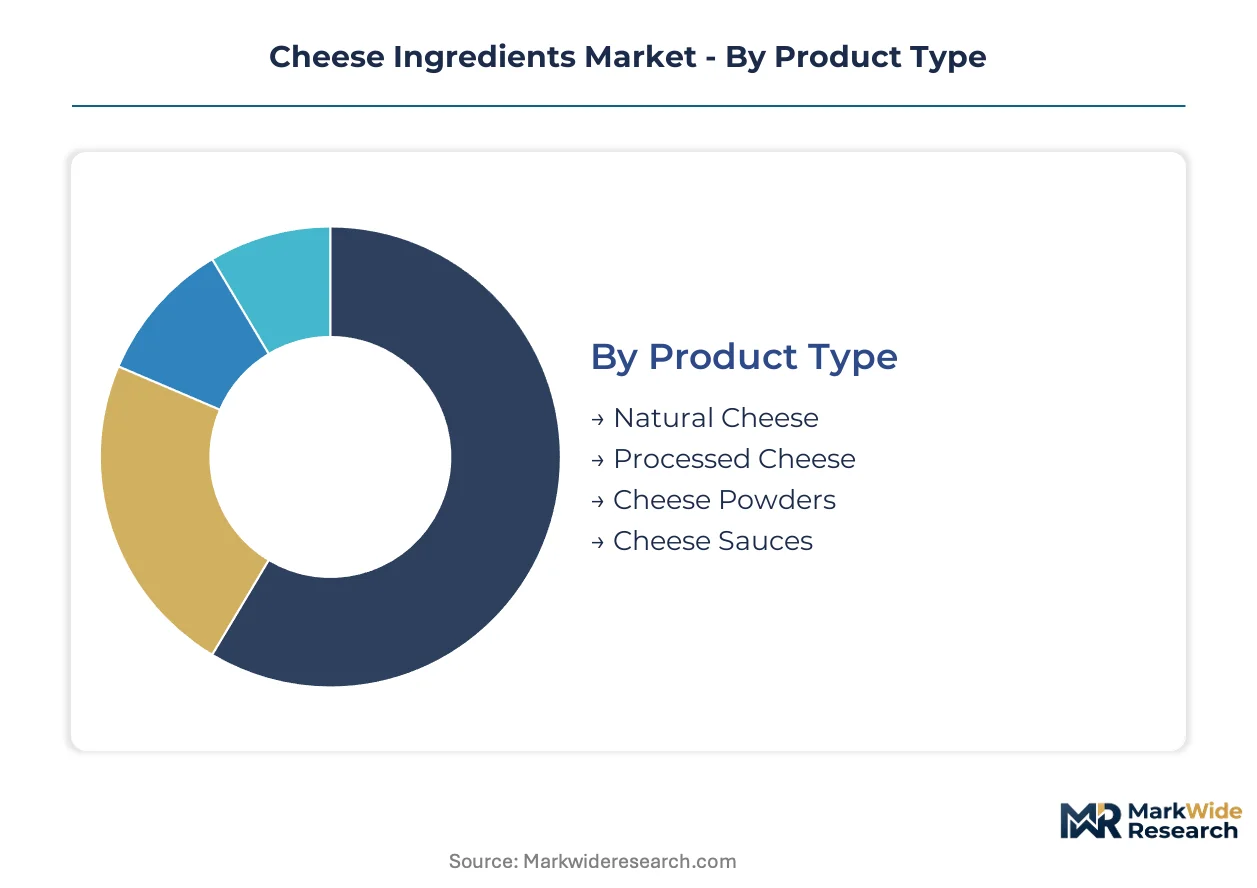
Cheese ingredient suppliers configure technical support intensity around segment-specific formulation complexity. Natural cheese varieties demand strain-specific troubleshooting that processed alternatives rarely require. Powder and sauce formats concentrate margin in seasoning blend partnerships where application testing replaces commodity supply relationships.
Product Type:
After-sales technical service intensity varies sharply across cheese ingredient categories, with natural and processed formats requiring divergent support architectures.
- Natural Cheese:Milk proteins, enzymes, and starter cultures undergo controlled fermentation and aging to develop authentic texture and flavor profiles. Wisconsin and California dairy clusters sustain bulk procurement of rennet and microbial coagulants for aged cheddar and fresh mozzarella production, though EFSA dossier requirements for novel enzymes constrain supplier flexibility.
- Processed Cheese:Emulsifying salts and functional additives create standardized meltability for foodservice channels. Clean-label reformulation by ready-to-eat meal manufacturers is stripping artificial preservatives from this segment, pulling demand toward minimally processed milk protein inputs.
- Cheese Powders:Concentrated flavor systems for snack seasoning blends.
- Cheese Sauces:Fluid formulations targeting foodservice dispensing systems.
Natural cheese holds the largest share; momentum sits with cheese powders.
Application:
Volume concentration patterns distinguish commodity-driven snack applications from precision-dependent baking formulations.
- Snacks:Cheese powders and seasonings dominate extruded and puffed product coatings where flavor intensity and adhesion properties determine procurement specifications. United States contract manufacturers are bringing sensory profiling in-house, displacing traditional supplier-provided application testing services.
- Baking:Processed cheese ingredients provide standardized performance in frozen dough and pastry applications where moisture control and fat stability are critical. REACH chemical tightening in Europe is forcing requalification of enzymatic processing aids used in these heat-stable formulations.
- Dips:Cream cheese bases and cultured dairy blends for refrigerated spreads.
- Sauces:Melt-stable cheese preparations for hot-hold foodservice environments.
Snacks command volume leadership; baking exhibits the steepest expansion trajectory.
End User:
Procurement scale and technical capability distribution fragment the customer base across divergent purchasing behaviors.
- Food Manufacturers:Large-scale processors leverage bulk fermentation runs and continuous culture supply contracts. Asset-light leasing models for industrial fermentation capacity are enabling mid-size manufacturers to challenge incumbent suppliers without captive biomanufacturing infrastructure.
- Foodservice:Distributors are unbundling after-sales technical support from ingredient supply contracts, forcing culture suppliers to compete on standalone advisory value.
- Retailers:Private-label cheese ingredient sourcing for store-brand dairy products.
- Households:Direct-to-consumer cheese making kits and specialty culture collections.
Food manufacturers absorb the dominant procurement volume; foodservice is climbing the fastest.
Packaging Type:
Packaging format selection tracks moisture sensitivity, oxygen barrier requirements, and foodservice dispensing compatibility.
- Pouches:Flexible films for cheese powder and sauce concentrates with extended shelf stability requirements.
- Tubs:Rigid containers for cultured dairy and fresh cheese ingredients requiring refrigeration.
- Bags:Bulk dry ingredient handling for industrial-scale manufacturing inputs.
- Boxes:Secondary containment for multi-unit foodservice distribution.
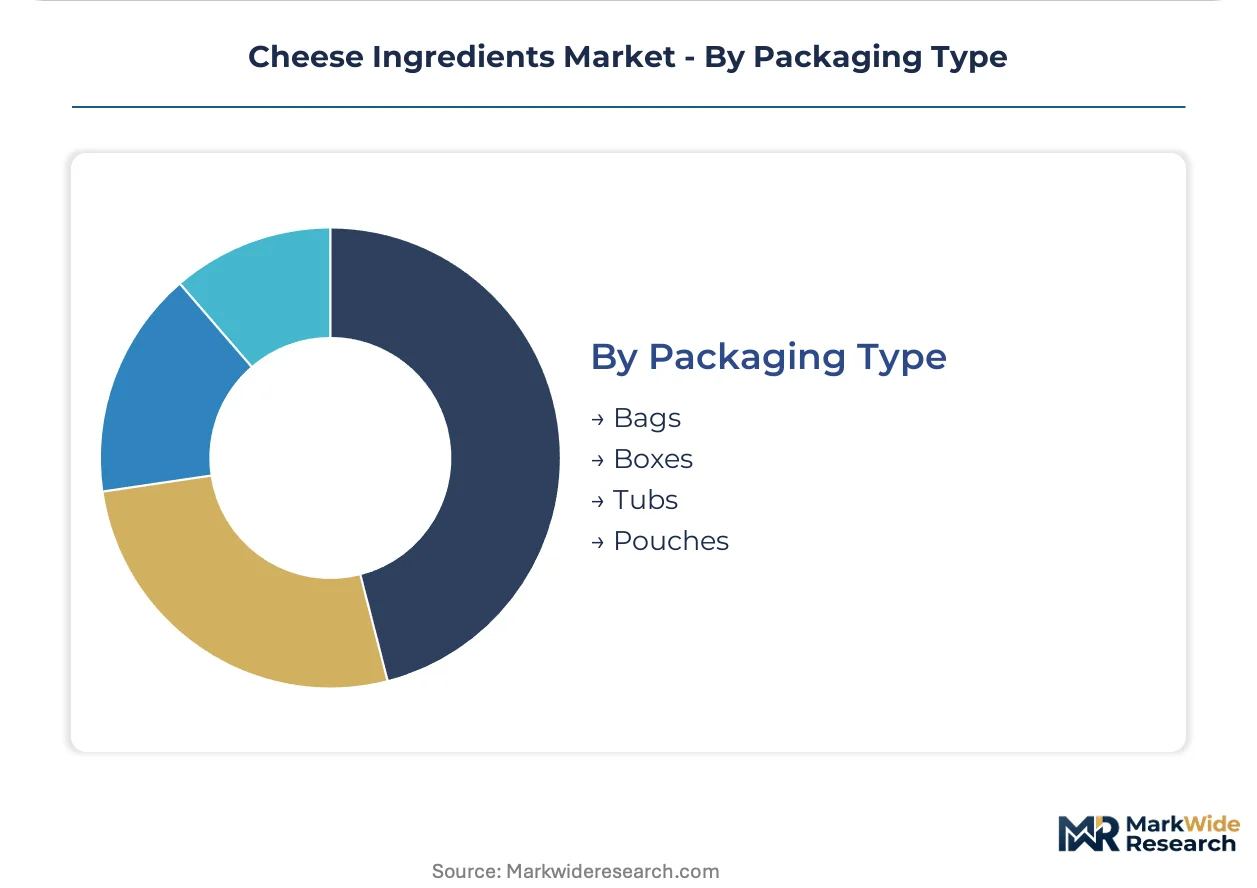
Pouches lead flexible packaging adoption; tubs retain dominance in refrigerated supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clean-label reformulation mandates and dairy cluster concentration are redrawing procurement geography for cheese ingredient suppliers. Regulatory chemistry frameworks in major producing jurisdictions now directly shape where fermentation capacity and culture development investments flow.
United States
Wisconsin and California dairy processing clusters sustain bulk fermentation runs for rennet and microbial coagulants. FDA GRAS determinations for novel enzymes govern which culture technologies achieve commercial scale in American plants. Mid-size manufacturers in the Upper Midwest are adopting asset-light fermentation leasing to reduce dependence on external culture houses.
Germany
REACH chemical tightening forces ingredient suppliers to requalify enzymatic processing aids for cheese manufacturing workflows. ECHA dossier requirements advantage established biotechnology houses with pre-filed technical documentation. Industrial dairy concentrations in Bavaria and Lower Saxony drive continuous procurement of starter cultures for processed cheese applications.
France
Aged cheese producers in Auvergne-Rhône-Alpes invest in alternative refrigeration chemistries to preserve traditional aging protocols under evolving F-Gas Regulation constraints. EFSA evaluation thresholds for novel processing aids constrain supplier flexibility for premium variety development. The country's national food safety authority maintains strict enforcement of ISO dairy processing hygiene standards.
India
FSSAI enzyme approval expansion creates first-mover positioning for suppliers with pre-filed technical dossiers. Maharashtra and Gujarat dairy cooperatives drive concentrated demand for standardized culture inputs in paneer and processed cheese production. The country's food safety regulator is accelerating its approved substances list modernization for commercial cheese manufacturing.
Netherlands
Integrated biotechnology platforms in the Randstad region span enzyme engineering to nutritional lipid formulations for cheese ingredient applications. EFSA-compliant manufacturing environments dominate export-oriented production serving European and Asian markets. FrieslandCampina's domestic presence anchors specialized culture development for continental cheese varieties.
Cheese Ingredients Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where scale advantages in fermentation capacity clash with proprietary strain library depth. The vendor base separates into consolidated biotechnology houses with integrated platforms, dairy cooperative-aligned ingredient divisions, and independent culture specialists leasing asset-light manufacturing. Dominant competitive moves include M&A to secure microbial strain collections and strategic partnerships to access regional distribution networks.
Within the integrated biotechnology tier, DSM-Firmenich and Chr. Hansen Holding A/S exemplify platform-scale competitors anchoring specialized culture development. Among dairy cooperative-aligned suppliers, Fonterra Co-operative Group Ltd and Arla Foods Ingredients Group P/S represent processor-integrated archetypes with captive milk protein supply chains. Kerry Group plc occupies a position bridging flavor system integration with cheese ingredient formulation services.
| Leading Market Players |
|---|
| Arla Foods Ingredients Group P/S |
| Fonterra Co-operative Group Ltd |
| Chr. Hansen Holding A/S |
| DSM-Firmenich |
| Kerry Group plc |
| Lactalis |
| FrieslandCampina |
| Saputo |
| Bel Group |
| Others |
Supply Flow & Price Mechanics
Rotterdam-Antwerp corridor freight costs compress margin pools for enzyme and culture suppliers serving European dairy clusters, while simultaneously amplifying price spreads between EFSA-certified premium tiers and standard-grade alternatives. This logistics chokepoint concentrates procurement leverage among buyers with multi-site manufacturing footprints that can optimize load consolidation.
Pricing Analysis
Certification level (ISO/EFSA/FDA-grade) creates the primary spread between premium culture formulations and commodity alternatives. Three-tier pricing structure across premium, standard, and economy levels tracks directly to dossier completeness and strain provenance documentation. Cost compression in standard-grade rennet intensifies as spot whey protein volatility feeds through to coagulant input costs. Mid-size cheese manufacturers exhibit acute price sensitivity due to limited volume leverage, while multinational food manufacturers absorb premium tier premiums for supply security.
Supply Chain Analysis
Upstream milk protein concentrates draw from New Zealand, Germany, and United States dairy processing clusters where whey and casein fractionation capacity concentrates. Starter culture development rests on cryopreserved microbial strain collections concentrated in Denmark and Netherlands biotechnology hubs. Single-source vulnerability persists for proprietary coagulant formulations where patent-protected production strains lack qualified second sources. Distribution runs through consolidated foodservice distributors and direct-to-manufacturer digital procurement platforms serving divergent buyer archetypes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cheese ingredient demand follows dairy commodity cycles, with current recovery momentum anchored in clean-label reformulation capex commitments from ready-to-eat meal manufacturers.
For Market Incumbents: Pre-empt asset-light fermentation leasing competitors by securing exclusive strain licensing agreements with regional dairy cooperatives. Accelerate backward integration into captive milk protein fractionation to offset whey concentrate spot price volatility. Lock in multi-year culture supply contracts with Wisconsin and California processing clusters before digital procurement platforms disintermediate traditional distribution relationships. For New Entrants and Emerging Players: India's FSSAI enzyme approval expansion offers first-mover positioning for suppliers with pre-filed technical dossiers and localized fermentation partnerships. Target mid-size paneer and processed cheese manufacturers in Maharashtra and Gujarat dairy cooperatives underserved by established European culture houses. Deploy direct-to-manufacturer e-procurement platforms that bypass layered distributor markups and embed application technical support as customer acquisition cost. For Investors and Strategic Acquirers: Carve-out targets emerge from dairy cooperative-aligned ingredient divisions seeking capital for biomanufacturing infrastructure modernization. Long-term viability hinges on regulatory chemistry expertise depth and strain library defensibility rather than commodity scale alone. Watch FDA GRAS determination timelines for novel precision-fermented dairy proteins as inflection signal for platform technology valuation resets.| Strategic Initiative | Industry Significance |
|---|---|
| Strain Library Acquisition | DSM-Firmenich and Chr. Hansen consolidation demonstrates that proprietary microbial collections anchor premium positioning in specialty culture supply. |
| Precision Fermentation Scale-Up | Computer-guided strain optimization platforms enable regional dairies to develop proprietary cultures without multi-million-dollar R&D infrastructure. |
| Regulatory Dossier Pre-Filing | Early EFSA and FSSAI technical submissions create approval timeline advantages that translate to exclusive supply windows in expanding markets. |
| Direct Digital Procurement Launch | E-procurement platforms connecting strain libraries to mid-size dairy technical buyers displace traditional distributor relationships and capture margin. |
| Alternative Refrigeration Chemistry Investment | F-Gas Regulation compliance in French and Italian aged cheese production preserves traditional aging protocols while maintaining EFSA manufacturing standards. |
Methodological Framework
Cross-validation between primary interviews with cheese plant technical directors, culture house R&D leads, dairy cooperative procurement officers, and foodservice distributor category managers anchors the qualitative findings. Secondary validation draws from EFSA novel food dossiers, FDA GRAS determination notifications, customs trade data for whey and casein concentrates, and SEC filings of publicly traded biotechnology suppliers. Bottom-up fermentation capacity modeling and top-down dairy processing cluster demand aggregation triangulate volume estimates.
Calibration against historical culture pricing indices and milk protein commodity cycles ensures forecast consistency across the projection horizon. Segmentation dimensions span natural versus processed cheese formats, snack versus baking versus foodservice applications, and food manufacturer versus foodservice end-user procurement behaviors. CAGRs derive from fitted growth curves applied to enzyme and culture penetration rates within each segment, with inputs including ECHA REACH compliance cost trajectories and FSSAI regulatory modernization pace.
The forecast holds incumbent behavior within observed patterns; aggressive moves by precision-fermented dairy protein startups would shift outcomes beyond modeled ranges. Material shifts in FDA novel enzyme review timelines or EFSA processing aid requalification thresholds would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Global Bioactive Ingredients Market
Ingredients
Fluid Lecithin Market
Ingredients
North America Phytosterols Market
Ingredients
Buckwheat–Mediterranean Grain Blend Ingredients Market
Ingredients
Almond Flour Market
Ingredients
Europe Algae Omega-3 Ingredients Market
Ingredients
South Africa Sodium Reduction Ingredients Market
Ingredients
Tannin Market
Ingredients
Europe Agar Market
Ingredients
Ingredients Market
Ingredients
Macleaya Cordata Extract Market
Ingredients
Global Alpha-Lactalbumin Market
Ingredients
Hydrolyzed Corn Protein Market
Ingredients
Protein Trends and Technologies Market
Ingredients
Phytogenic Market
Ingredients
Spain Sodium Reduction Ingredient Market