
 Europe Potato Protein Market | 2026-2036
Europe Potato Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Potato Protein Market Foresight
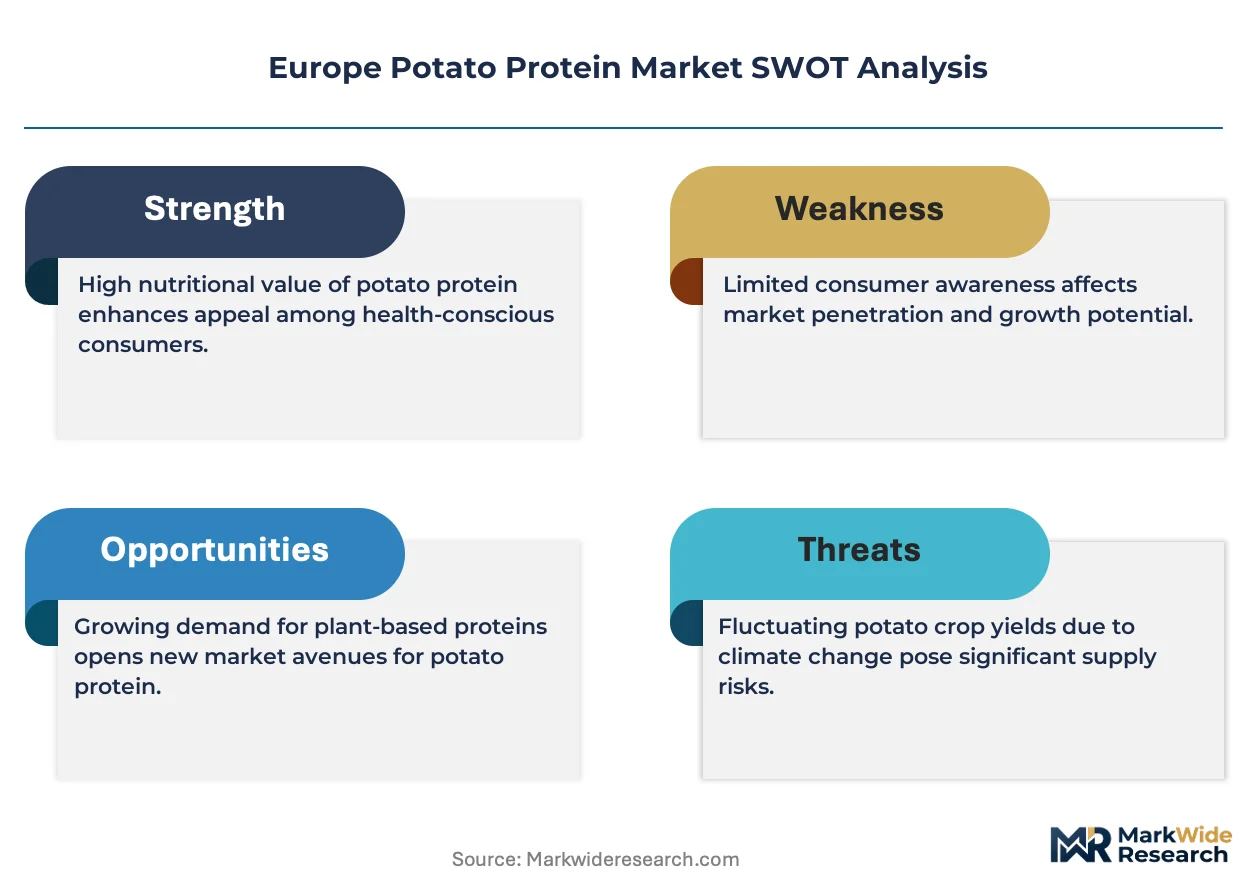
The EU Green Deal is decoupling protein demand from conventional animal agriculture across European food systems. Avebe leverages its Dutch starch-protein co-location to sustain cost-advantaged isolate output for plant-based meat customers. Roquette Freres anchors its position through deep R&D intensity in pea-potato protein blends, while Emsland Group dominates Central European supply with integrated potato processing infrastructure.
Potato protein comprises the albumin and globulin fractions extracted from potato juice, a byproduct of starch manufacture, typically yielding concentrates with protein content ranging from 60% to 90% depending on isolation method. Its primary commercial purpose centers on functional protein enrichment in foods where emulsification, gelation, or foaming properties are required. Isolates command the deepest margin pools due to purity thresholds demanded by meat alternatives manufacturers, while textured protein formats are gaining fastest traction in bakery products and snack foods as formulators seek clean-label binding solutions.
EMA food-contact guidelines, EFSA novel food authorization pathways, and EU Green Deal sustainability benchmarks collectively shape product standards and market access for potato protein suppliers. REACH compliance on processing aids and the F-Gas Regulation's indirect pressure on cold-chain energy intensity further filter which processors can scale cost-effectively. Stakeholders must monitor how EFSA's evolving protein quality scoring methodologies will recalibrate formulation premiums across meat alternatives and protein fortification channels.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is actively decoupling protein demand from intensive livestock systems across European food manufacturing, redirecting procurement toward plant-based isolates and concentrates sourced from starch processing byproducts.
Growth Catalysts
- EU Green Deal protein diversification mandates:The Farm to Fork strategy sets binding sustainability targets that force food manufacturers to reduce reliance on animal-derived inputs. Potato protein isolates qualify as compliant alternatives in meat alternative formulations.
- Textured protein adoption in bakery:Clean-label binding solutions from potato concentrates are displacing synthetic emulsifiers in European baked goods and snack applications where consumer scrutiny of ingredient decks intensifies.
- Dutch-German processing cluster concentration:Integrated starch-protein co-location in the Netherlands and Germany yields cost-advantaged isolate output with captive feedstock access and reduced logistics exposure.
Market Restraints
- Potato crop yield volatility:Input cost instability from weather-driven starch potato harvest fluctuations compresses margin predictability for protein processors dependent on seasonal tuber supply.
- EFSA novel food authorization timelines:Extended safety assessment pathways for new protein formats delay product launch windows and tie up regulatory capital for eighteen to thirty-six months.
- Pea and fava protein substitution:Established supply chains for legume isolates offer formulators comparable functionality with greater volume scalability and lower certification friction.
Strategic Opportunities
- Polish and Romanian market underpenetration:Central and Eastern European meat alternative manufacturing capacity is expanding faster than localized protein supply, creating first-mover positioning for isolate distributors.
- EFSA protein quality scoring evolution:Upcoming methodology revisions for digestible indispensable amino acid scores may recalibrate formulation premiums toward potato protein's favorable leucine and lysine profiles.
- Hybrid pea-potato protein blends:Converging fractionation technologies enable synergistic functional combinations that outperform single-source isolates in extruded meat analog texture and mouthfeel.
Industry Challenges
- Specialized protein extraction engineering talent scarcity:European universities produce insufficient graduates with integrated starch processing and food protein chemistry expertise to staff expanding isolate facilities.
- REACH compliance on enzymatic processing aids:Registration requirements for novel extraction enzymes create documentation burdens and supplier qualification delays that extend pilot-to-production timelines.
- Cold-chain energy intensity under F-Gas Regulation:Refrigeration system retrofits required for hydrocolloid and protein concentrate storage inflate capex loads for processors scaling isolate output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Potato Protein Market |
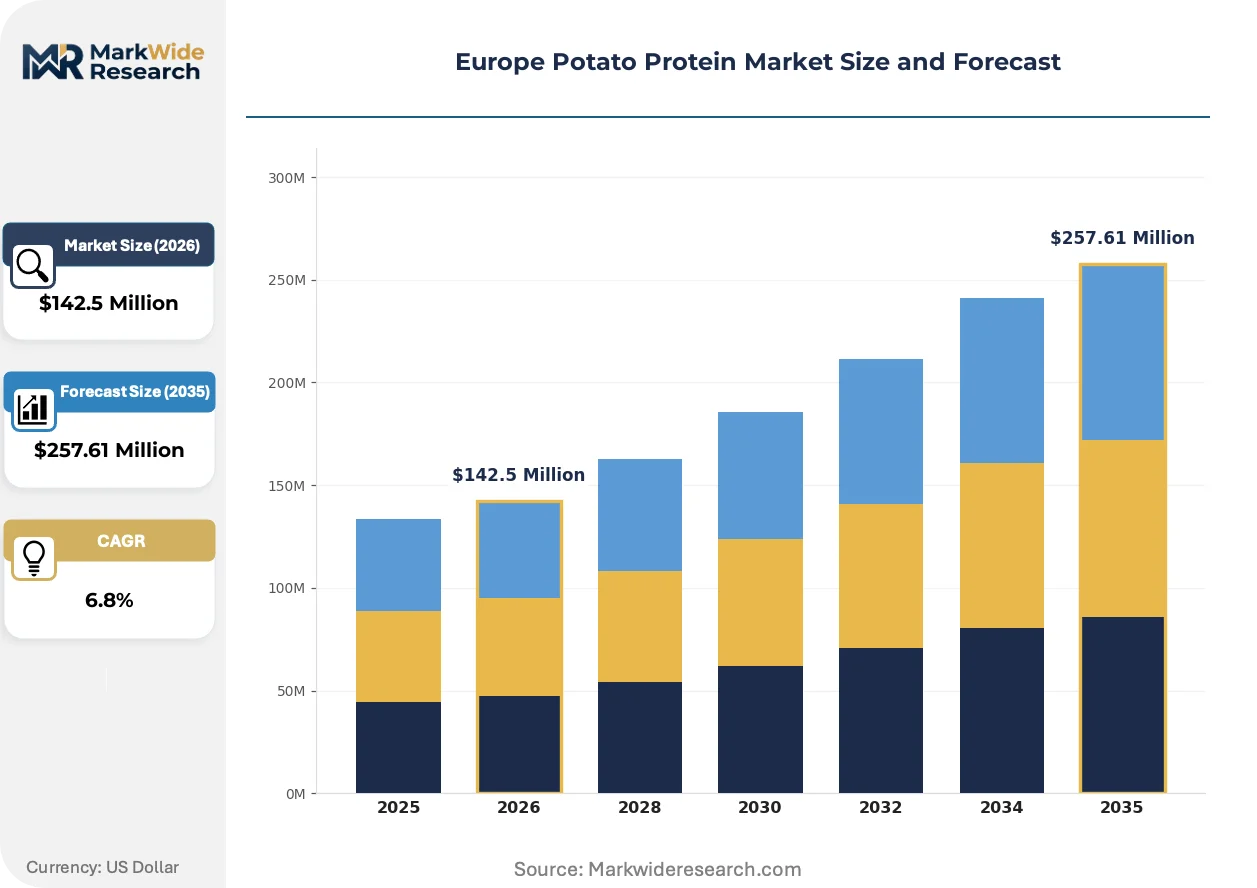
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $257.61 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Textured Protein, Isolates, Concentrates, Hydrolyzed Protein End User: Food and Beverages, Nutraceuticals, Feed Industry, Personal Care Application: Meat Alternatives, Protein Fortification, Bakery Products, Snack Foods Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Avebe, Roquette Freres, Tereos Group, KMC Ingredients, Emsland Group, AGRANA Beteiligungs-AG, AKV Langholt, Pepees Group, Solanic, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Potato Protein Market Shifts & Advancements
Electrification of protein extraction processes and precision fermentation adjacent technologies are compressing energy footprints while novel enzymatic fractionation methods unlock higher-purity isolates from potato juice streams previously relegated to animal feed.
Membrane filtration cascades with ceramic microfiltration and ultrafiltration stages are electrifying isolate recovery yields from potato fruit juice. Plant-based meat manufacturers in Germany and the Netherlands are retrofitting extraction lines to capture these efficiency gains. The technology is electrifying competitive positioning by collapsing unit economics for 90% protein isolates previously requiring prohibitively energy-intensive precipitation steps.
REACH registration requirements for enzymatic processing aids are tightening scrutiny on extraction catalysts used in isolate manufacture. ECHA's 2024 updated guidance on food-contact substances is forcing processors to resubmit safety dossiers for legacy protease formulations. Central European suppliers with pre-registered enzyme portfolios are accelerating qualification timelines while competitors face twelve-to-eighteen month reauthorization gaps.
Formulator procurement patterns are consolidating around single-source textured protein contracts with integrated sustainability certification. Meat alternative manufacturers are displacing spot-market concentrate purchases with multi-year offtake agreements tied to Scope 3 emissions reporting. This concentration is most visible in Dutch plant-based meat clusters where buyers demand batch-level carbon footprint documentation from Avebe and Emsland Group supply chains.
Europe Potato Protein Market Segmentation
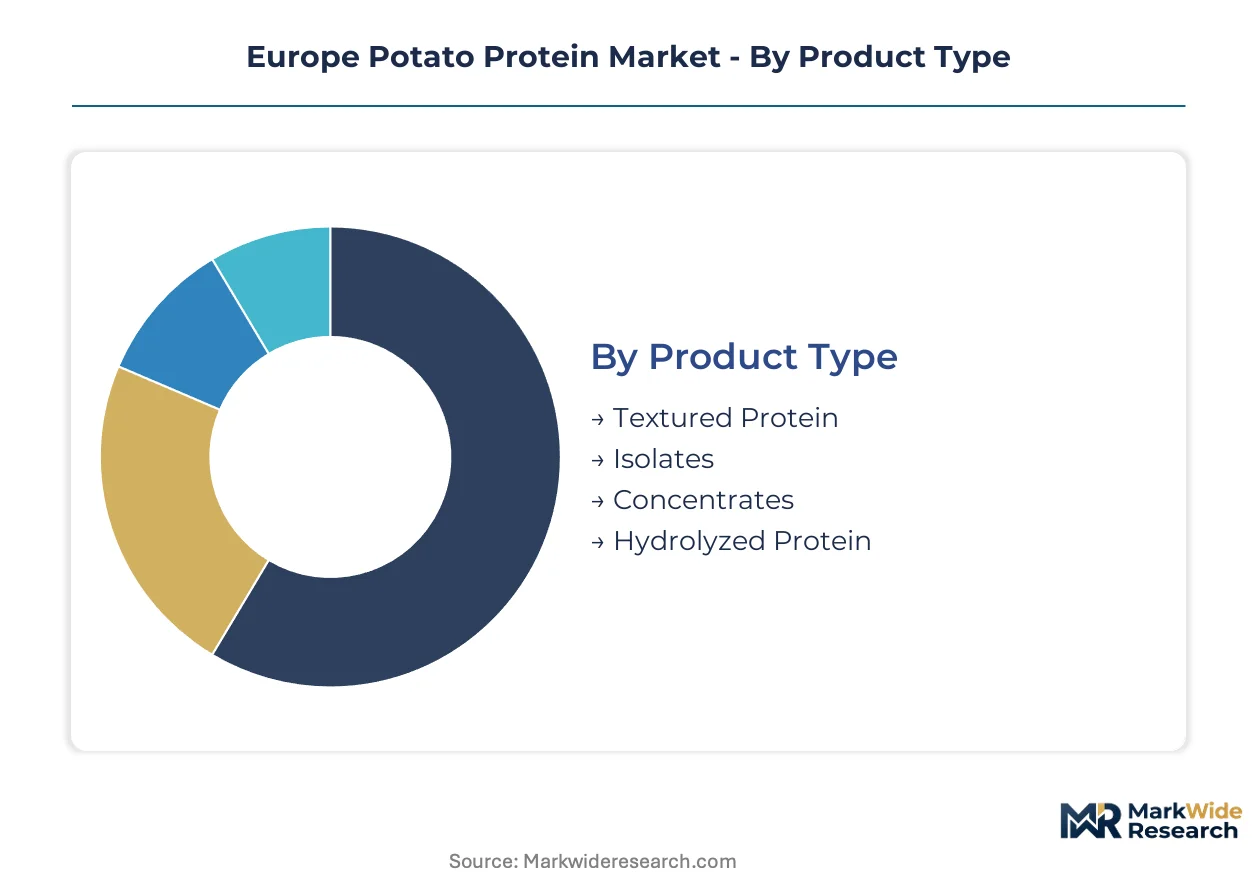
Potato protein procurement in Europe follows distinct technical and commercial logics across product grades, end-use requirements, and channel structures. Formulators select isolates for functional purity, concentrates for cost efficiency, and textured formats for structural performance in finished goods.
Product Type:
Price-performance tradeoffs drive buyer selection between purity grades and processing intensities.
- Isolates:Protein content exceeding 85% enables clean-label emulsification and gelation in premium meat alternatives. Dutch and German plant-based meat manufacturers specify isolates for extruded analogs where mouthfeel replication of animal muscle tissue is critical.
- Textured Protein:Fibrous structures formed through thermomechanical processing provide bite and chew in restructured meat applications. Bakery formulators across France and Belgium are adopting textured potato protein to displace methylcellulose binders in clean-label positioning.
- Concentrates:Mid-range protein content delivers cost-advantaged enrichment for processed foods where functional thresholds are less stringent.
- Hydrolyzed Protein:Pre-digested amino acid profiles target specialized nutraceutical applications with rapid absorption requirements.
Isolates lead on scale; textured protein leads on momentum.
End User:
Regulatory complexity and margin structures segment demand across consumer-facing and industrial buyers.
- Food and Beverages:Meat alternative manufacturers in the Netherlands, Germany, and Belgium account for the dominant volume pull, driven by EU Green Deal procurement mandates and Farm to Fork sustainability scoring.
- Nutraceuticals:Sports nutrition and senior nutrition formulators leverage potato protein's allergen-free status and favorable leucine content for muscle protein synthesis applications.
- Feed Industry:Pet food manufacturers specify potato protein for hypoallergenic formulations, particularly in premium dry and wet pet food segments across Germany and the United Kingdom.
- Personal Care:Cosmetic formulators utilize hydrolyzed fractions for film-forming and conditioning properties in hair and skin care products.
Food and beverages dominates absolute volume; nutraceuticals climbs the fastest.
Application:
Functional requirements and processing conditions dictate protein format selection across finished goods categories.
- Meat Alternatives:Extruded and formed products demand isolates with precise gelling temperatures and water-holding capacity. German plant-based sausage and burger manufacturers specify batch-level carbon documentation under Scope 3 reporting requirements.
- Protein Fortification:Beverage and dairy alternative applications require soluble, non-gritty protein with neutral flavor profiles.
- Bakery Products:Clean-label bread and pastry formulators substitute potato concentrates for DATEM and SSL emulsifiers to meet consumer scrutiny of ingredient decks.
- Snack Foods:Extruded puffs and crisps utilize textured protein for structural integrity and protein content claims.
Meat alternatives commands the deepest margin pools; bakery products gains share fastest.
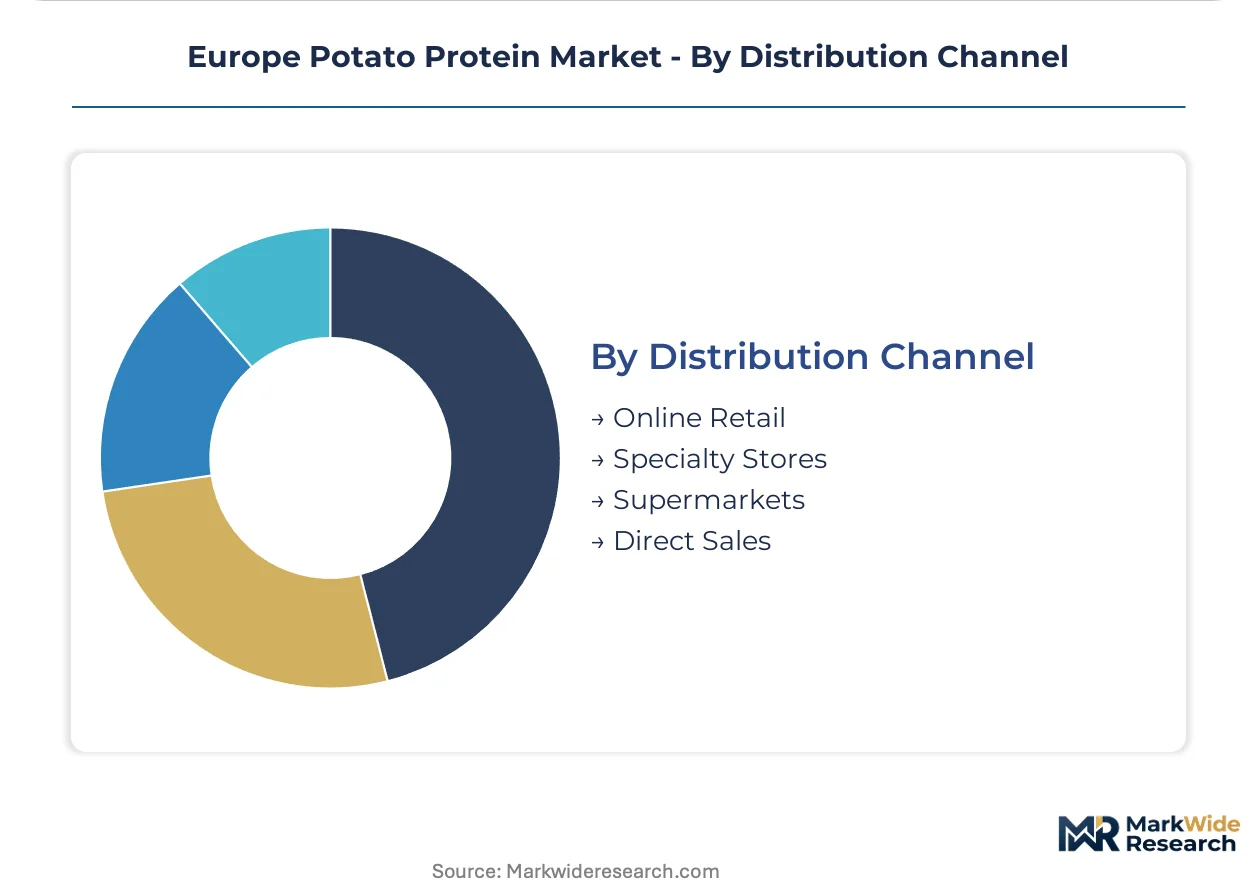
Distribution Channel:
Volume scale and technical service requirements shape channel selection for different buyer segments.
- Direct Sales:Large meat alternative manufacturers negotiate multi-year offtake agreements with Avebe and Emsland Group for captive supply security and integrated sustainability certification.
- Specialty Stores:Nutraceutical and personal care formulators source through distributors offering technical support and small-batch flexibility.
- Online Retail:E-commerce platforms serve artisanal food producers and research institutions requiring rapid sample access and low minimum order quantities.
- Supermarkets:Limited penetration for industrial-grade protein; primarily serves small-scale food service and institutional buyers.
Direct sales anchors volume concentration; online retail expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dutch and German food protein engineers anchor Europe's potato protein processing workforce, with specialized starch-fractionation talent concentrated in Groningen and Lower Saxony industrial corridors.
Germany
Plant-based meat manufacturers in Berlin and Hamburg drive isolate procurement for extruded sausage and burger analogs. The country's national food regulator enforces strict novel food authorization timelines that compress product launch windows. Bavarian and North Rhine-Westphalian processing clusters retrofit extraction lines to capture membrane filtration efficiency gains for 90% protein isolates.
Netherlands
Dutch plant-based meat clusters specify batch-level carbon documentation under Scope 3 emissions reporting requirements. EU Green Deal Farm to Fork sustainability scoring mandates redirect procurement toward potato protein isolates as compliant alternatives. Groningen-based starch-protein co-location facilities yield cost-advantaged output with captive feedstock access and reduced logistics exposure.
France
Bakery formulators across Paris and Lyon adopt textured potato protein to displace methylcellulose binders in clean-label positioning. EFSA novel food authorization pathways shape product standards and market access for protein suppliers. Auvergne-Rhône-Alpes and Hauts-de-France industrial zones expand fractionation capacity to serve meat alternative manufacturers seeking hybrid pea-potato blends.
Belgium
Snack food producers in Brussels and Antwerp utilize textured protein for structural integrity and protein content claims in extruded puffs and crisps. REACH compliance on enzymatic processing aids tightens scrutiny on extraction catalysts used in isolate manufacture. Flemish processing infrastructure integrates sustainability certification into multi-year offtake agreements with meat alternative buyers.
Poland
Central European meat alternative manufacturing capacity expands faster than localized protein supply, creating first-mover positioning for isolate distributors. The country's alignment with EU Green Deal protein diversification mandates accelerates procurement shifts away from animal-derived inputs. Warsaw and Łódź industrial corridors attract Dutch and German processors seeking lower-cost fractionation sites with proximity to expanding Baltic markets.
Europe Potato Protein Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across Europe's potato protein landscape. Integrated starch processors with captive tuber supply dominate isolate output, while specialized fractionation houses focus on premium textured formats. The market structures around three archetypes: Dutch-German integrated processors, French-Belgian specialty blenders, and Central European volume suppliers. Dominant competitive moves include backward integration into starch potato cultivation and multi-year offtake agreements tied to Scope 3 emissions documentation.
Among Dutch-German integrated processors, Avebe and Emsland Group occupy positions exemplifying cost-advantaged isolate output through starch-protein co-location. Roquette Freres represents the French specialty blender archetype, anchoring competitive positioning through deep R&D intensity in protein blend development. These three enterprises collectively illustrate how geographic clustering around tuber supply and regulatory alignment with EU Green Deal mandates shapes sustainable competitive advantage in European plant protein markets.
| Leading Market Players |
|---|
| Avebe |
| Roquette Freres |
| Tereos Group |
| KMC Ingredients |
| Emsland Group |
| AGRANA Beteiligungs-AG |
| AKV Langholt |
| Pepees Group |
| Solanic |
| Others |
Supply & Pricing Matrix
Starch potato procurement costs in the Netherlands and Germany cascade through three distinct pricing tiers, with isolate premiums widening against concentrate benchmarks as Dutch plant-based meat manufacturers demand batch-level carbon documentation under Scope 3 reporting requirements.
Pricing Analysis
Bundled sustainability certification and multi-year offtake agreements command premium positioning over unbundled spot-market concentrate purchases. Pricing stratifies across premium isolates with full traceability documentation, standard concentrates for processed foods, and economy-grade feed applications. Cost compression in the concentrate tier is intensifying because Polish and Romanian processors are expanding fractionation capacity with lower labor and energy overhead. Small-scale nutraceutical formulators exhibit the highest price sensitivity, while Dutch-German meat alternative manufacturers prioritize supply security over unit cost.
Supply Chain Analysis
Starch potato supply rests on Dutch, German, and Polish agricultural output, with processing capacity concentrated in Groningen, Lower Saxony, and Warsaw industrial corridors. Protein extraction draws from enzymatic processing aids, membrane filtration systems, and cold-chain refrigeration infrastructure. Single-source vulnerability runs through the seasonal tuber harvest, where weather-driven yield fluctuations in any one country propagate across European isolate availability. Distribution runs through direct sales contracts for large meat alternative manufacturers, specialty distributors for nutraceutical buyers, and online platforms for research-scale purchasers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe potato protein market reads as a late-cycle quality story, with Dutch and German plant-based meat manufacturers redirecting procurement toward premium isolates that satisfy EU Green Deal Farm to Fork sustainability scoring mandates.
For Market Incumbents: Anchor cost-advantaged positioning through backward integration into starch potato cultivation in the Netherlands and Germany, securing captive feedstock access that buffers against Polish and Romanian price competition. Deepen R&D investment in hybrid pea-potato protein blends to defend against legume isolate substitution threats from established supply chains. For New Entrants and Emerging Players: Artisanal bakery formulators across France and Belgium represent an underserved buyer archetype seeking clean-label binding solutions without the technical service overhead demanded by meat alternative manufacturers. Polish meat alternative producers expanding faster than localized protein supply offer the most penetrable geography, with a technical partnership angle leveraging membrane filtration efficiency gains from Dutch engineering consultants. For Investors and Strategic Acquirers: Consolidation pressure builds where specialized protein extraction engineering talent scarcity constrains capacity expansion timelines for mid-cap processors. The market supports viable returns across a multi-year horizon for targets with pre-registered enzymatic processing aid portfolios under REACH. Watch EFSA protein quality scoring methodology revisions as the inflection signal that could recalibrate formulation premiums toward potato protein's amino acid advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Starch Potato Cultivation | Dutch and German processors secure captive feedstock access against seasonal yield volatility. |
| Hybrid Protein Blend R&D Investment | Roquette Freres anchors positioning through synergistic pea-potato combinations for extruded meat analogs. |
| Multi-year Offtake Agreement Structuring | Avebe locks in Scope 3 emissions documentation requirements from Dutch plant-based meat clusters. |
| Membrane Filtration Capacity Expansion | Central European suppliers capture 90% isolate yield improvements from electrified extraction lines. |
| REACH Pre-registration of Enzymatic Processing Aids | Emsland Group accelerates qualification timelines while competitors face reauthorization gaps. |
Research Methodology
Direct dialogue with starch processing plant managers, protein procurement leads at Dutch and German meat alternative manufacturers, EFSA regulatory affairs specialists, and membrane filtration equipment engineers grounded qualitative insights. Secondary validation drew from EU Green Deal policy documents, EFSA novel food authorization filings, ECHA REACH registration databases, and Cefic chemical industry statistics. Bottom-up isolate volume estimates from named processing facilities triangulated against top-down protein demand projections from food and beverage end-use segments.
Segment-level value outputs across isolates, concentrates, textured protein, and hydrolyzed formats were derived through price-performance tradeoff analysis over the projection horizon. The analytical framework modeled protein content tiers, end-use industry requirements, application functional specifications, and distribution channel structures. CAGRs were computed from year-over-year growth rate convergence across historical trade data and forward procurement contract visibility, with potato crop yield volatility and EFSA authorization timelines as key uncertainty inputs.
Underlying measurement precision varies by segment; isolate volumes for meat alternative applications carry tighter precision than nutraceutical or personal care channels due to concentrated buyer concentration. Forecasts reflect documented assumptions about EU Green Deal implementation pace and membrane filtration technology adoption curves. Regulatory authorization delays, legume protein substitution acceleration, and cold-chain energy cost spikes constitute the trigger set warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Global Fresh Compressed Yeast Market
Ingredients
Seaweed Extracts Market
Ingredients
North America Cheese Powder Market
Ingredients
Cocoa Solids Market
Ingredients
Mung Bean Starch Market
Ingredients
Lupin Flour Market
Ingredients
North America Sodium Reduction Ingredients Market
Ingredients
White Mulberry Leaves Extract Market
Ingredients
North America Soy Protein Concentrate Market
Ingredients
Interesterified Fats Market
Ingredients
Hydrolysed Vegetable Protein (HVP) Market
Ingredients
Asia-Pacific Agar Market
Ingredients
Curcuma Longa (Turmeric) Root Extract Market
Ingredients
Cognitive Ingredients Market
Ingredients
Starches/Glucose Market
Ingredients
Lime Seed Oils Market