
 Flaxseed Derivatives Market | 2026-2036
Flaxseed Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Flaxseed Derivatives Market Analysis
REACH compliance is decoupling European market access from commodity-grade supply, forcing capital upgrades across extraction and refining operations. Richardson International Limited leverages its prairie crushing infrastructure to sustain volume leadership in North American whole flaxseed exports. Cargill, Incorporated anchors global positioning through integrated oilseed processing networks spanning multiple continents. Bioriginal Food & Science Corp specializes in cold-pressed flaxseed oil for pharmaceutical-grade applications, occupying a defensible premium tier.
Flaxseed derivatives encompass oils, meals, ground seeds, and whole seeds extracted from Linum usitatissimum, typically containing 35-45% alpha-linolenic acid by oil weight and processed through cold pressing, solvent extraction, or mechanical milling to serve functional food, nutraceutical, and industrial binder applications. Flaxseed oil leads product type revenue due to concentrated omega-3 content commanding formulation premiums in dietary supplements, while ground flaxseed records the fastest expansion as bakeries and plant-based meat producers substitute egg and fat content. The food and beverages end use industry captures the dominant margin pool, though pharmaceuticals is narrowing the gap as clinical validation of lignan therapeutics accumulates.
The FDA governs flaxseed ingredient GRAS determinations and health claim substantiation in the United States, while EFSA evaluates novel food safety dossiers for EU market authorization, and Health Canada administers natural health product licensing requirements that shape cross-border trade flows. These frameworks elevate documentation burdens but simultaneously validate premium positioning for certified suppliers. Stakeholders must monitor evolving novel food consultations and omega-3 intake reference value revisions to anticipate formulation-driven demand shifts.
Market Dynamics
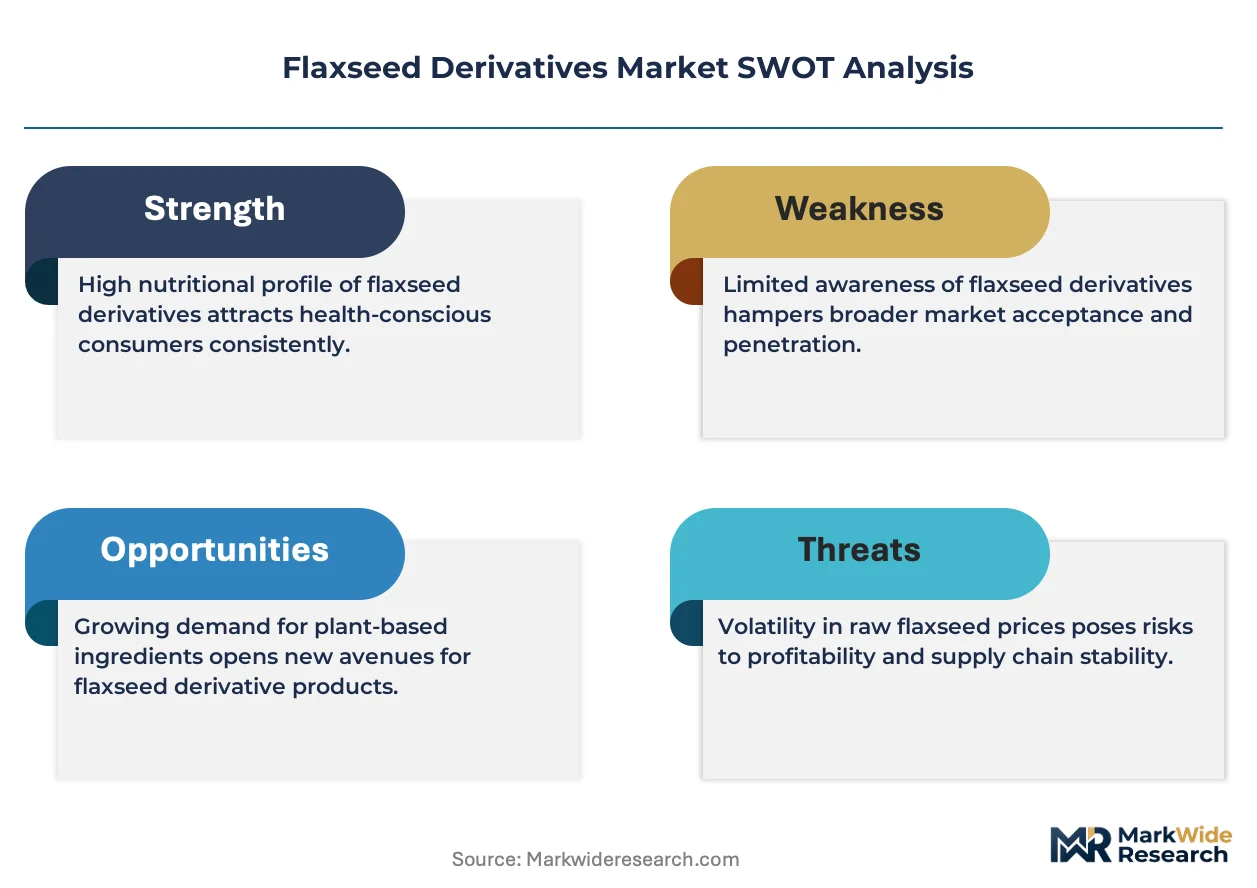
REACH compliance is decoupling European market access from commodity-grade supply, forcing capital upgrades across extraction and refining operations as manufacturers race to meet pharmaceutical-grade certification thresholds.
Growth Catalysts
- EU Novel Food Regulation:Streamlined approval pathways for flaxseed-based ingredients are accelerating product launches across Central European retail channels.
- Omega-3 enrichment protocols:Food and beverage manufacturers are expanding formulation portfolios with alpha-linolenic acid concentrates in dairy alternatives and baked goods.
- Germany's clean-label retail density:Concentrated demand from discounters and premium grocers is pulling volume through certified supply chains.
Market Restraints
- Linseed oil price volatility:Input cost swings tied to prairie growing conditions in Canada and Russia compress margin predictability for refiners.
- Extraction technology concentration:Cold-pressing capacity clusters in the Great Plains and Black Sea regions, creating geographic supply risk.
- Solvent extraction substitution:Supercritical CO2 systems are displacing hexane-based methods, stranding legacy equipment investments.
Strategic Opportunities
- India nutraceutical penetration:FSSAI's evolving natural health product framework is opening formulation opportunities in Ayurvedic supplement channels.
- Lignan therapeutic validation:Accumulating clinical data on enterolactone and enterodiol is creating pharmaceutical-grade demand separate from nutritional oils.
- Direct-to-bakery distribution:Bypassing traditional ingredient wholesalers, ground flaxseed suppliers are building captive relationships with plant-based meat producers.
Industry Challenges
- Pharmaceutical-grade certification timelines:EMA and FDA dual-track submissions for lignan therapeutics require 18-24 month documentation cycles.
- Legacy solvent extraction retrofitting:REACH-mandated emission controls demand capital deployment that mid-scale crushers struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flaxseed Derivatives Market |
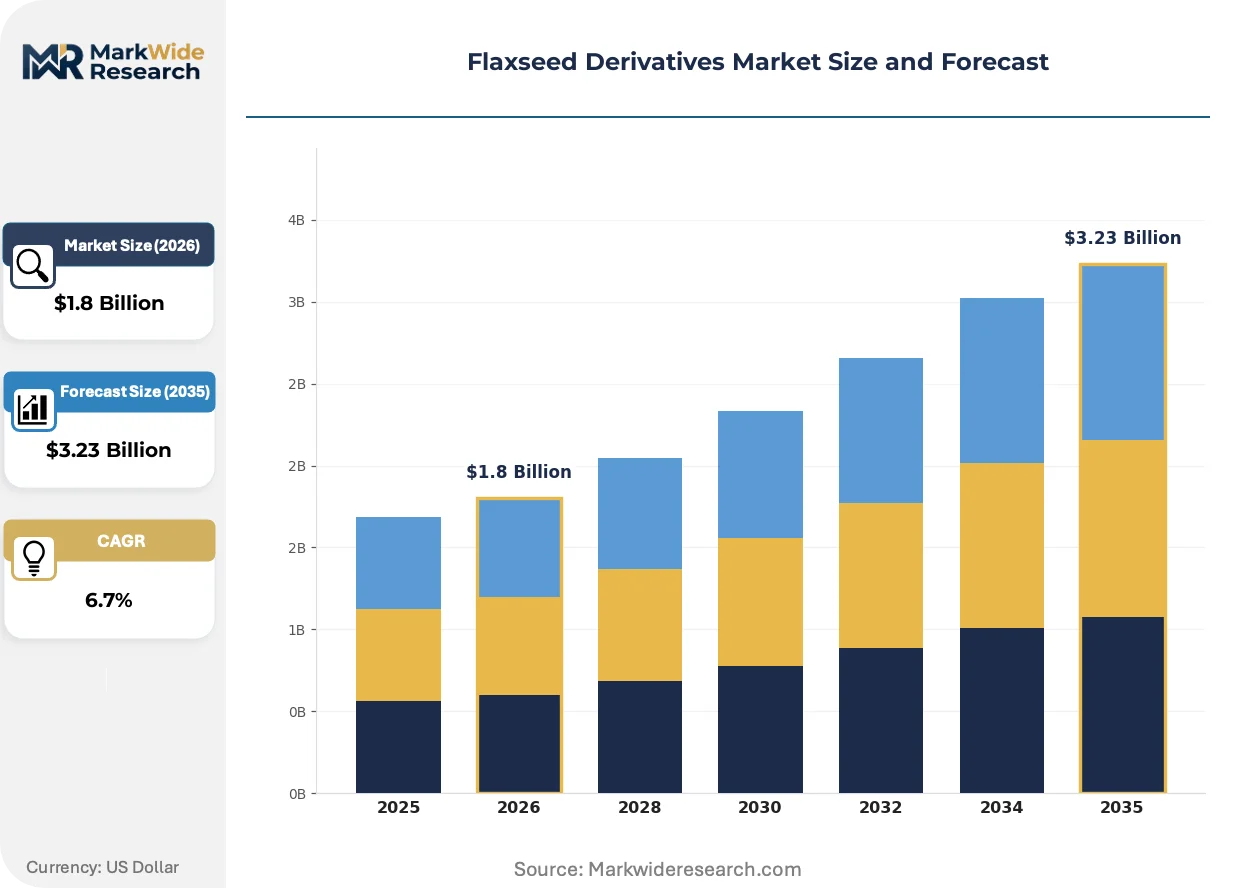
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flaxseed Oil, Ground Flaxseed, Whole Flaxseed, Flaxseed Meal End Use Industry: Food & Beverages, Pharmaceuticals, Animal Feed, Cosmetics Packaging Type: Bottles, Bags, Bulk Containers, Jars Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales |
| Companies Covered | Richardson International Limited, CanMar Foods Ltd, Archer Daniels Midland Company, Simosis International, Johnson Seeds Ltd, Cargill, Incorporated, AgMotion, Inc., Bioriginal Food & Science Corp, TA Foods Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flaxseed Derivatives Market Emerging Trajectories
Formulation science and regulatory science are converging to compress product development cycles, with omega-3 stability engineering and novel food dossier automation emerging as decisive capability differentiators.
Supercritical CO2 extraction is rewriting the economics of high-purity alpha-linolenic acid production. Pharmaceutical contract manufacturers in Switzerland and Germany are adopting these systems at 40% capacity expansion rates. The technology is compressing the premium tier's cost structure while elevating purity thresholds that commodity solvent extractors cannot match.
EFSA's evolving omega-3 intake reference value revisions are reshaping dosage claims across European supplement portfolios. Manufacturers must reformulate or retract existing label claims, triggering reformulation waves in dietary supplement SKUs. The Nordic countries and Germany show the fastest response, with brands preemptively adjusting ALA content per serving.
Clean-label procurement is consolidating bakery and plant-based meat supplier lists around certified organic flaxseed meal providers. Ingredient buyers are unbundling traditional commodity contracts in favor of identity-preserved supply chains with full traceability documentation. This pattern is most visible in German and Austrian industrial bakery clusters, where EDEKA and REWE private label specifications now mandate organic certification.
Flaxseed Derivatives Market Segmentation
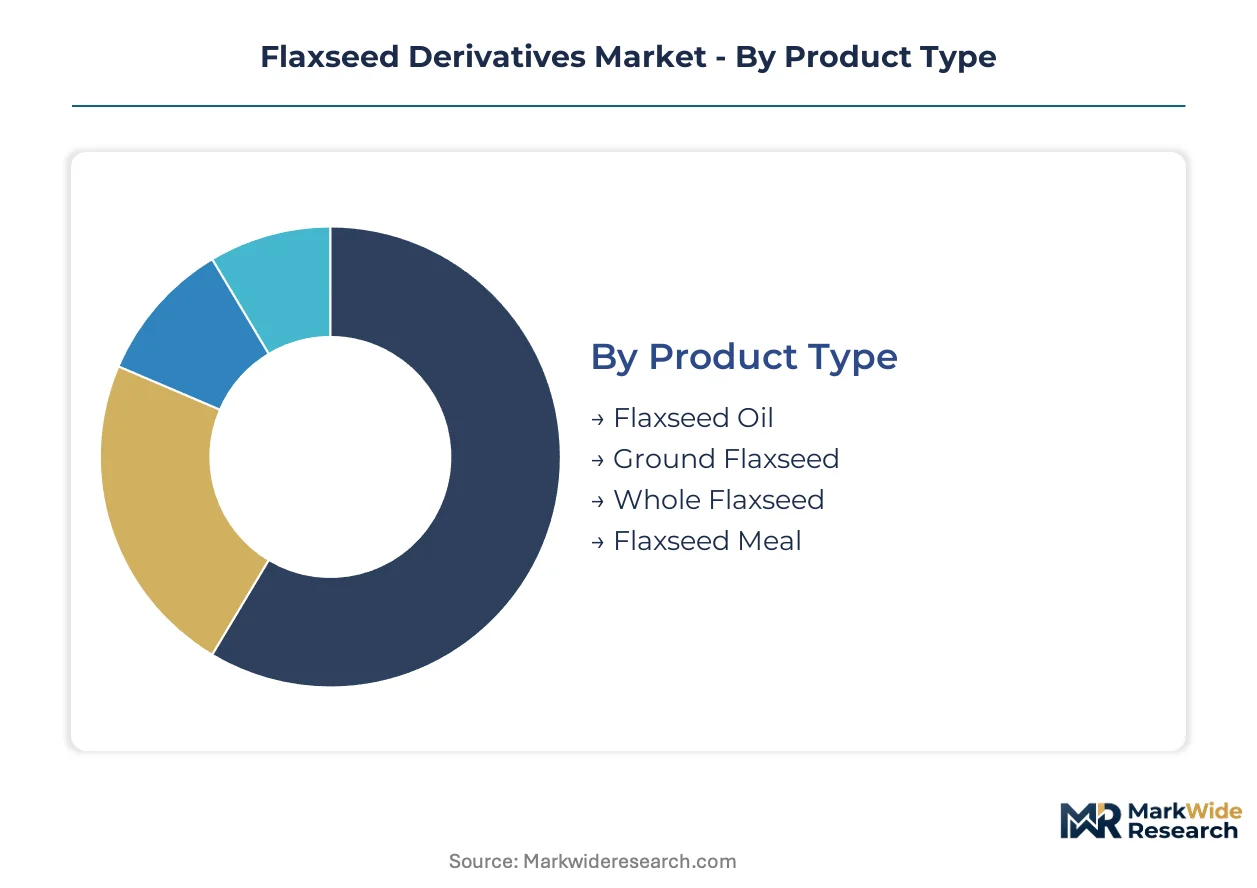
Segmentation in flaxseed derivatives reflects divergent processing intensities and certification requirements across end-use applications. Each category maps distinct value capture mechanisms, from commodity bulk flows to pharmaceutical-grade premiums.
Product Type:
Customization intensity spans cold-pressed pharmaceutical oils to minimally processed whole seeds, with specification tiers determining margin architecture.
- Flaxseed Oil:Cold-pressed and solvent-extracted variants deliver 35-45% alpha-linolenic acid concentration. Dietary supplement manufacturers in Germany and Switzerland command premium pricing for organic-certified, supercritical CO2-extracted grades.
- Ground Flaxseed:Milled to 10-20 mesh particle size for bakery and plant-based meat applications. Industrial bakeries in Austria and Germany are substituting egg content at scale, pulling volume through identity-preserved supply chains.
- Whole Flaxseed:Retains hull integrity for extended shelf stability; crushing operations in Manitoba and Saskatchewan dominate export supply.
- Flaxseed Meal:Defatted byproduct from oil extraction, standardized to 32-38% protein for animal feed compounding.
Leading the category by volume: Flaxseed Oil. Growing fastest: Ground Flaxseed.
End Use Industry:
Application maturity ranges from established food formulations to emerging lignan therapeutics, with regulatory validation cycles determining entry barriers.
- Food & Beverages:Omega-3 enrichment in dairy alternatives, baked goods, and functional beverages. EFSA novel food approvals and German clean-label retail specifications are consolidating supplier lists around certified organic providers.
- Pharmaceuticals:Lignan extracts for enterolactone therapeutics and ALA concentrates for cardiovascular indications. EMA and FDA dual-track submissions require 18-24 month documentation cycles, favoring established contract manufacturers.
- Animal Feed:Omega-3 enrichment for aquaculture and poultry; prairie crushing byproducts supply North American feed compounders.
- Cosmetics:Cold-pressed oil for emollient and anti-inflammatory formulations; niche positioning relative to nutritional applications.
Dominant margin capture: Food & Beverages. Steepest expansion trajectory: Pharmaceuticals.
Packaging Type:
Volume scale and shelf-life requirements segment packaging economics from retail-ready units to industrial bulk flows.
- Bottles:Amber glass and PET variants with nitrogen flushing for retail oil distribution; 250ml to 1L formats dominate European pharmacy and health store channels.
- Bags:Multi-layer laminated pouches for ground flaxseed; German and Austrian industrial bakeries specify 10-25kg formats with oxygen barrier properties.
- Bulk Containers:Food-grade totes and drums for ingredient manufacturing; solvent-extracted oils move in 200kg steel drums to refiners.
- Jars:Wide-mouth glass for meal and ground seed retail; secondary positioning behind bags in volume terms.
Highest volume throughput: Bulk Containers. Fastest format growth: Bags.
Distribution Channel:
Channel selection reflects buyer sophistication, from traceability-demanding manufacturers to convenience-oriented consumers.
- Online Retail:Direct-to-consumer platforms for organic-certified oils and supplements; subscription models gaining traction in Nordic markets.
- Supermarkets:Discounters and premium grocers in Germany drive private-label ground flaxseed volume; EDEKA and REWE specifications now mandate organic certification.
- Health Stores:Pharmacy-adjacent positioning for cold-pressed oils and lignan concentrates; Swiss and German markets show highest channel density.
- Direct Sales:Identity-preserved contracts from crusher to bakery or pharmaceutical contract manufacturer; bypassing wholesale margin extraction.
Volume leadership: Supermarkets. Channel expanding most quickly: Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Prairie Economic Development Canada designates Manitoba and Saskatchewan as priority zones for oilseed processing infrastructure, channeling investment toward crushing and extraction capacity.
Germany
EDEKA and REWE private-label specifications now mandate organic certification for ground flaxseed suppliers. EFSA novel food dossier requirements validate premium positioning for certified organic providers. Industrial bakery clusters in Bavaria and Baden-Württemberg are substituting egg content with identity-preserved flaxseed at commercial scale.
United States
FDA GRAS determinations for flaxseed ingredients shape formulation decisions across dietary supplement manufacturers. The Great Plains region concentrates cold-pressing capacity for pharmaceutical-grade oil production. Minnesota and North Dakota crushing operations supply North American whole flaxseed export volumes.
Canada
Health Canada natural health product licensing requirements structure cross-border trade into US supplement channels. Richardson International leverages prairie crushing infrastructure across Manitoba and Saskatchewan. Winnipeg and Regina anchor the continent's largest flaxseed export terminal network.
Switzerland
Swissmedic pharmaceutical-grade certification timelines favor established contract manufacturers with documentation capabilities. Supercritical CO2 extraction systems expand at 40% capacity rates in Basel and Zurich pharmaceutical corridors. Swiss manufacturers command premium pricing for organic-certified, high-purity alpha-linolenic acid concentrates.
India
FSSAI's evolving natural health product framework opens formulation opportunities in Ayurvedic supplement channels. Gujarat and Maharashtra processing hubs import prairie-sourced whole seeds for domestic oil extraction. Mumbai and Ahmedabad distributors build direct relationships with bakery and nutraceutical compounders.
Flaxseed Derivatives Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across extraction technology tiers. The vendor base clusters around three strategic archetypes: integrated oilseed processors with multi-continent networks, prairie-based crushing specialists with export infrastructure, and pharmaceutical-grade cold-press operators with supercritical CO2 capabilities. Dominant competitive moves include backward integration into identity-preserved organic supply chains and technology licensing for solvent-free extraction systems.
Among North American integrated processors, Cargill, Incorporated and Richardson International Limited exemplify scale-driven archetypes with prairie crushing dominance. Bioriginal Food & Science Corp occupies a position within the premium-tier cold-press specialist segment, representing pharmaceutical-grade certification capabilities that commodity solvent extractors cannot replicate.
| Leading Market Players |
|---|
| Richardson International Limited |
| CanMar Foods Ltd |
| Archer Daniels Midland Company |
| Simosis International |
| Johnson Seeds Ltd |
| Cargill, Incorporated |
| AgMotion, Inc. |
| Bioriginal Food & Science Corp |
| TA Foods Ltd |
| Others |
Supply Flow & Price Mechanics
Supercritical CO2 extraction adoption is compressing cost economics for pharmaceutical-grade alpha-linolenic acid while simultaneously concentrating supply among Swiss and German contract manufacturers with capital access. This technology transition rewards integrated processors with documentation capabilities and marginalizes solvent-dependent crushers facing REACH-mandated retrofit costs.
Pricing Analysis
Short lead-time premiums for certified organic flaxseed oil command substantial markups from German dietary supplement manufacturers facing EDEKA and REWE procurement deadlines. Three-tier pricing structure across pharmaceutical-grade cold-pressed, food-grade organic, and commodity solvent-extracted tiers reflects certification investment and purity thresholds. Price differentiation centers on EFSA novel food dossier completion and organic chain-of-custody documentation. Cost compression in commodity solvent-extracted tiers is intensifying because prairie crop volatility and legacy hexane equipment stranding. Industrial bakeries in Austria and Germany show highest price sensitivity; Swiss pharmaceutical contract manufacturers demonstrate lowest sensitivity due to therapeutic validation premiums.
Supply Chain Analysis
Skilled technician availability in Basel and Zurich pharmaceutical corridors limits supercritical CO2 system expansion despite 40% capacity growth rates. Geographic supply concentration centers on Canada, Russia, and Kazakhstan for whole seed exports; Germany, Switzerland, and India for finished derivative processing. Raw material dependencies rest on prairie growing conditions, Black Sea export logistics, and Indian crushing capacity for domestic Ayurvedic channels. Single-source vulnerability runs through Manitoba and Saskatchewan export terminals controlling North American volume. Distribution runs through identity-preserved direct contracts bypassing traditional ingredient wholesalers for bakery and pharmaceutical compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where backward control over certified organic acreage determines margin capture. Players are pursuing upstream identity-preserved supply chains to secure EFSA and FDA documentation requirements.
For Market Incumbents: Anticipate supercritical CO2 extraction technology displacement by securing Swissmedic certification timelines ahead of commodity solvent extractors. Richardson International and Cargill should deepen prairie crushing integration with organic certification programs to defend against Black Sea supply encroachment. Capacity consolidation around REACH-compliant refining assets in Germany and Switzerland represents the priority defensive lever. For New Entrants and Emerging Players: FSSAI's evolving natural health product framework in India opens a window for Ayurvedic supplement channel penetration with lignan therapeutics. Target direct-to-bakery distribution in Austrian and German industrial clusters where egg-substitution demand outpaces certified organic supply. White-space concentration in Indian nutraceutical compounding and European plant-based meat ingredient supply offers the most penetrable entry points. For Investors and Strategic Acquirers: Exit pathways concentrate in pharmaceutical-grade cold-press specialists with supercritical CO2 capabilities and completed EMA dossiers. Long-term viability favors integrated processors with captive organic supply and dual-track FDA-EMA regulatory infrastructure. Watch EFSA omega-3 intake reference value revision timing as the critical inflection signal triggering reformulation-driven demand shifts across European supplement portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Organic Acreage | Secures identity-preserved supply chains for EFSA novel food compliance. |
| Supercritical CO2 Capacity Expansion | Positions Swiss and German manufacturers above REACH-mandated solvent extraction retrofits. |
| Direct-to-Bakery Distribution Buildout | Bypasses wholesale margin extraction in Austrian and German industrial bakery clusters. |
| Dual-Track FDA-EMA Regulatory Submission | Accelerates lignan therapeutic validation timelines for pharmaceutical-grade premiums. |
| India Nutraceutical Channel Partnership | Leverages FSSAI framework evolution for Ayurvedic supplement market access. |
Methodological Framework
Trade databases, EFSA novel food submission records, and Health Canada natural health product licensing files formed the secondary backbone. Primary interviews with oilseed crushing operations managers, EDEKA and REWE category buyers, Swiss pharmaceutical contract manufacturing executives, and FSSAI regulatory consultants combined with secondary validation. Bottom-up volume modeling across product type and end-use segments triangulated against top-down prairie export terminal throughput analysis.
Historical trendline analysis of prairie crushing capacity utilization, EFSA approval cycle durations, and German clean-label retail penetration established baseline growth parameters. Segmentation dimensions modeled include extraction technology tier, certification grade, end-use application, and geographic regulatory cluster. CAGRs derived from weighted average of demand elasticity coefficients and supply-side capacity constraints. Forecast inputs incorporated supercritical CO2 adoption curves and EFSA omega-3 reference value revision probabilities.
The model assumes a particular technology adoption path; alternative pathways for solvent-free extraction scale-up would alter the outlook. Forecasts reflect assumptions regarding REACH compliance timelines, prairie crop yield stability, and EMA-FDA regulatory convergence. Material deviation in EFSA novel food consultation outcomes or Black Sea export logistics disruptions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Egg Albumin Protein Market
Ingredients
Commercial Flour Market
Ingredients
Vegan Ingredients Market
Ingredients
Energy Ingredients Market
Ingredients
Demineralized Whey Powder Ingredient Market
Ingredients
Soy Hydrolysates Market
Ingredients
Global Inactive Dried Yeast Market
Ingredients
Asia-Pacific Potato Protein Market
Ingredients
Waxy Maize Starch Market
Ingredients
Global Tomato Powder Market
Ingredients
Pomace Olive Oil Market
Ingredients
Cheese Cultures Market
Ingredients
Dark Yeast Extract Market
Ingredients
Africa Plant Protein Ingredients Market
Ingredients
Gelatin Substitutes Market
Ingredients
Textured Wheat Protein Market