
 Diastatic Malt Market | 2026-2036
Diastatic Malt Market Size, Share, and Industry Trends Forecast 2026-2036
Diastatic Malt Market Outlook
Ingredient-as-a-service contracting is shifting how diastatic malt moves from commodity to tailored input. Cargill, Incorporated leverages its grain origination network to secure premium barley streams for enzymatic malt production. Muntons plc anchors British supply through vertical control over malting and roasting stages. Briess Malt & Ingredients Co. differentiates via specialized roasted malt portfolios for craft brewing accounts.
Diastatic malt comprises germinated cereal grains, typically barley, whose enzymatic activity—measured in degrees Lintner or Windisch-Kolbach units—converts starches to fermentable sugars during mashing or dough conditioning. The germination process halts at precise moisture and temperature thresholds to preserve alpha-amylase and beta-amylase activity for industrial baking and brewing applications. Dry malt extract holds mature volume positions in large-scale brewing operations where consistency and shelf stability command priority. Liquid malt extract captures faster expansion among craft breweries seeking flavor complexity and batch customization. Malted grains retain strong positions in artisanal baking channels where visual and textural whole-grain credentials support premium positioning.
The FDA enforces food-grade enzyme labeling and Good Manufacturing Practice standards for malt-derived ingredients sold into U.S. interstate commerce. EFSA and EMA frameworks govern novel enzyme applications and food contact substance approvals across European member states, while REACH registration requirements affect chemical additives used in malt processing aids. Stakeholders must monitor evolving enzyme activity measurement standards and carbon intensity disclosure rules that could reshape supplier qualification criteria and procurement specifications.
Market Dynamics
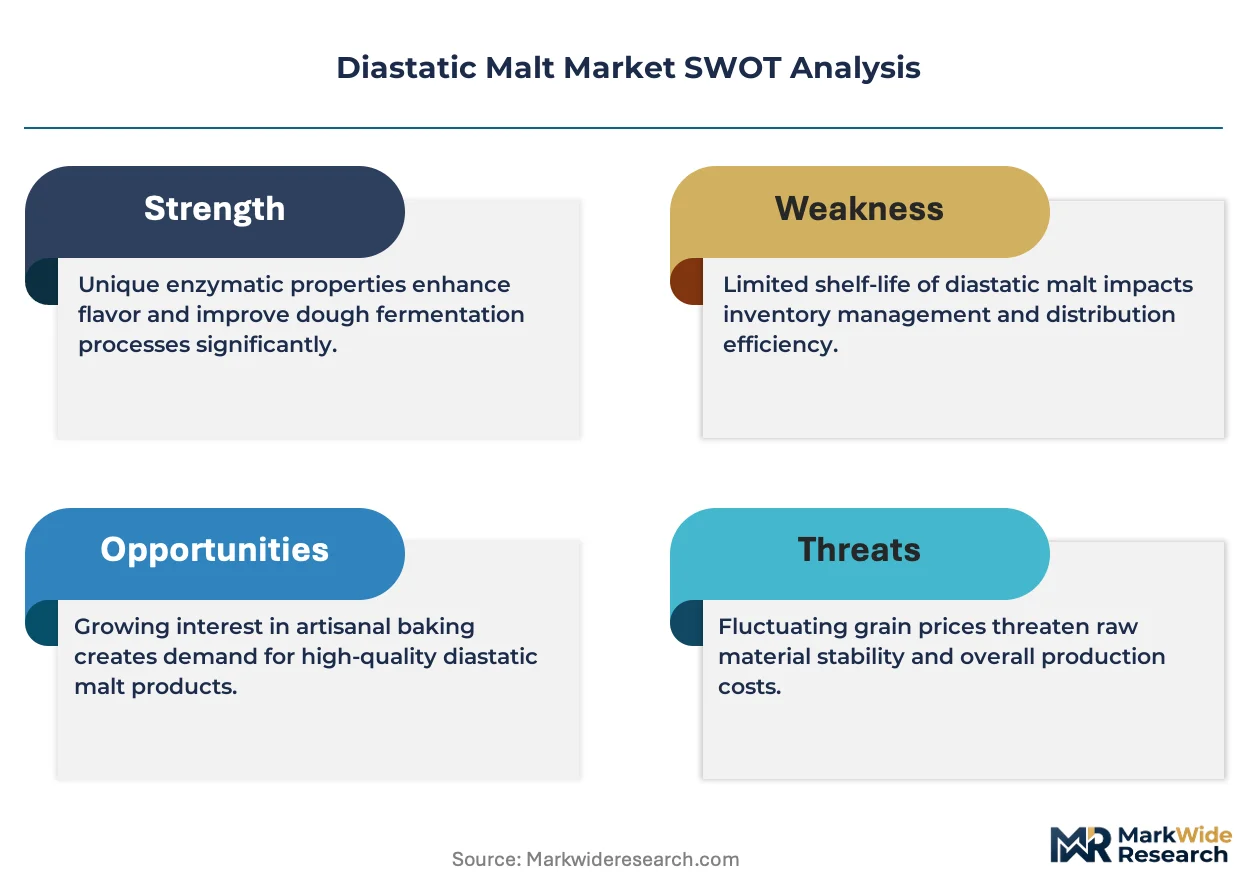
Specialty malt procurement is consolidating around enzymatic performance specifications rather than commodity grades, forcing suppliers to certify alpha-amylase and beta-amylase activity under stricter food-grade protocols.
Growth Catalysts
- Craft Brewing Differentiation:Small-batch breweries in Colorado and Oregon now specify diastatic malt extracts by Lintner units to achieve repeatable fermentation profiles. This precision demand pulls premium volumes from specialty malting houses.
- EU F-Gas Regulation:Updated purity requirements for processing inputs are disqualifying conventional malt suppliers across Bavaria's brewing corridor, creating qualified-supplier premiums for compliant enzymatic malt producers.
- Clean-Label Baking:Artisanal bakeries in Germany are substituting chemical dough conditioners with malted barley powders, driving whole-grain positioning that commands shelf-space premiums in European retail channels.
Market Restraints
- Barley Input Volatility:Premium malting barley concentrates in specific growing regions, exposing processors to weather-driven supply interruptions and quality downgrades that cascade into enzymatic activity shortfalls.
- REACH Registration Burden:Chemical additives used in malt processing aids face escalating compliance costs and timeline uncertainty, compressing margins for mid-tier processors without captive chemical registration teams.
- Enzyme Substitution:Industrial bakeries increasingly specify fungal amylase concentrates for cost reasons, displacing diastatic malt in high-volume applications where flavor contribution is secondary.
Strategic Opportunities
- Carbon Intensity Disclosure:Early alignment with emerging EU carbon accounting rules for agricultural inputs positions malt suppliers for preferential procurement from sustainability-focused brewing conglomerates.
- Liquid Extract Customization:Craft breweries seek batch-specific gravity and color profiles, opening service-contracting models where malt houses co-develop proprietary extract formulations under exclusive supply terms.
- India Food Processing:FSSAI modernization of food additive standards creates first-mover advantage for enzymatic malt suppliers achieving novel food ingredient approvals in an underpenetrated commercial baking market.
Industry Challenges
- Enzymology Talent Scarcity:Malting operations lack sufficient brewing chemists capable of optimizing germination protocols for specific Lintner targets, slowing product development cycles.
- Legacy Equipment Retrofit Costs:Transitioning kilning operations to precision moisture-control systems for enzymatic preservation demands capital outlays that strain family-owned malt house balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diastatic Malt Market |
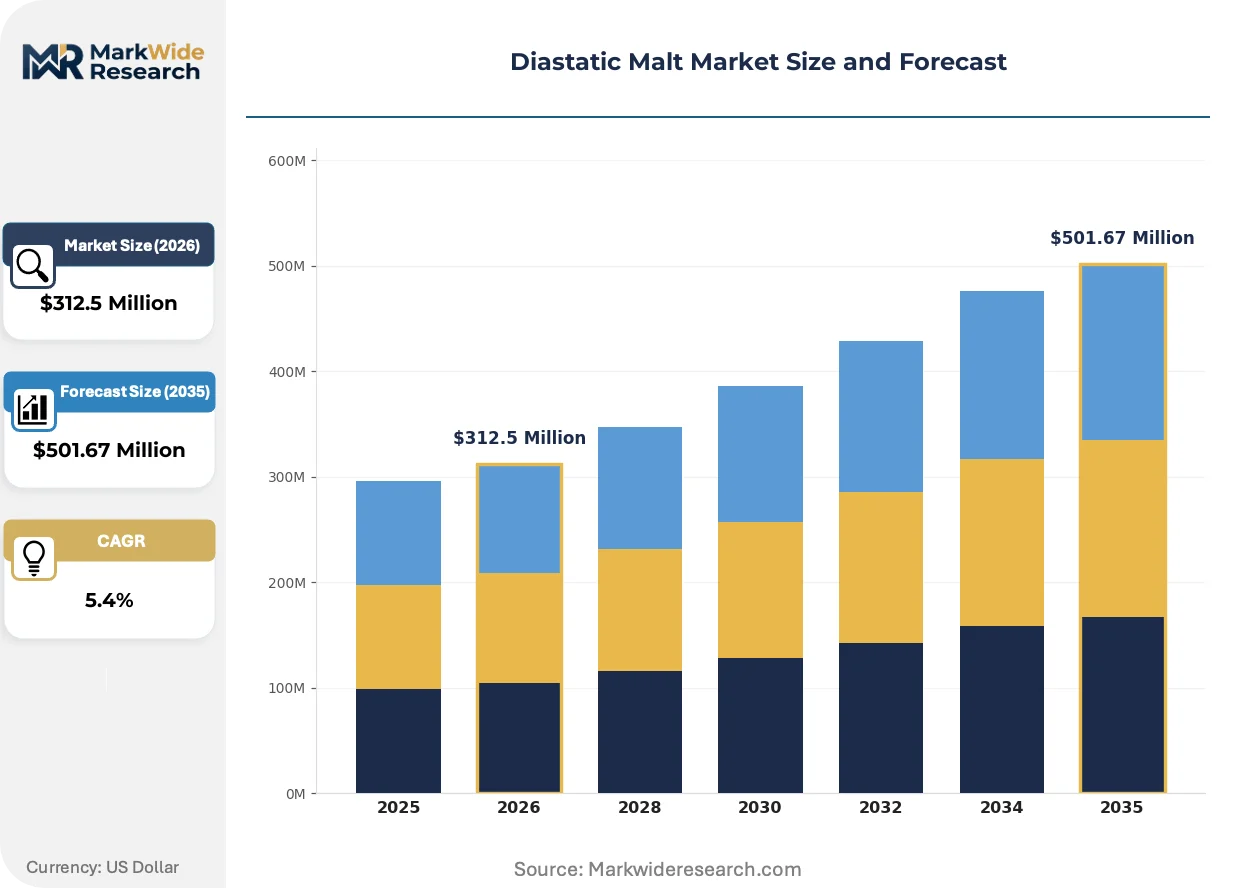
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $501.67 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Malt Extract, Dry Malt Extract, Powdered Malt, Malted Grains Application: Baking, Brewing, Confectionery, Nutritional Supplements Customer Type: Commercial Bakers, Craft Breweries, Food Manufacturers, Health Stores Distribution Channel: Online Retail, Direct Sales, Wholesale Distribution, Specialty Stores |
| Companies Covered | Cargill, Incorporated, Malteurop Group, Muntons plc, Briess Malt & Ingredients Co., GrainCorp Malt, Viking Malt, Simpsons Malt Limited, Boortmalt Group, Rahr Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diastatic Malt Market Strategic Shifts
Enzymatic malt production is fragmenting into specialized service tiers, with technology investments concentrating on precision germination control and regulatory-compliant processing rather than scale expansion.
Controlled-atmosphere germination technology is modularizing how malt houses configure production lines. Craft breweries in Oregon now contract for small-lot malting with specified enzyme retention curves. This modularization compresses minimum viable batch sizes from industrial tonnages to craft-scale volumes without sacrificing enzymatic consistency.
REACH registration requirements for processing aids are tightening substance documentation obligations across EU malting operations. German suppliers face extended approval timelines for novel enzyme stabilizers. Bavarian processors are responding by qualifying existing food-grade additives rather than innovating with new chemical inputs.
Ingredient-as-a-service contracting is displacing spot commodity purchasing among mid-sized craft breweries. Briess Malt and regional competitors now embed technical consultation into supply agreements. This shift concentrates procurement relationships with suppliers offering formulation support, visible most clearly across Colorado's Front Range brewing cluster.
Diastatic Malt Market Segmentation
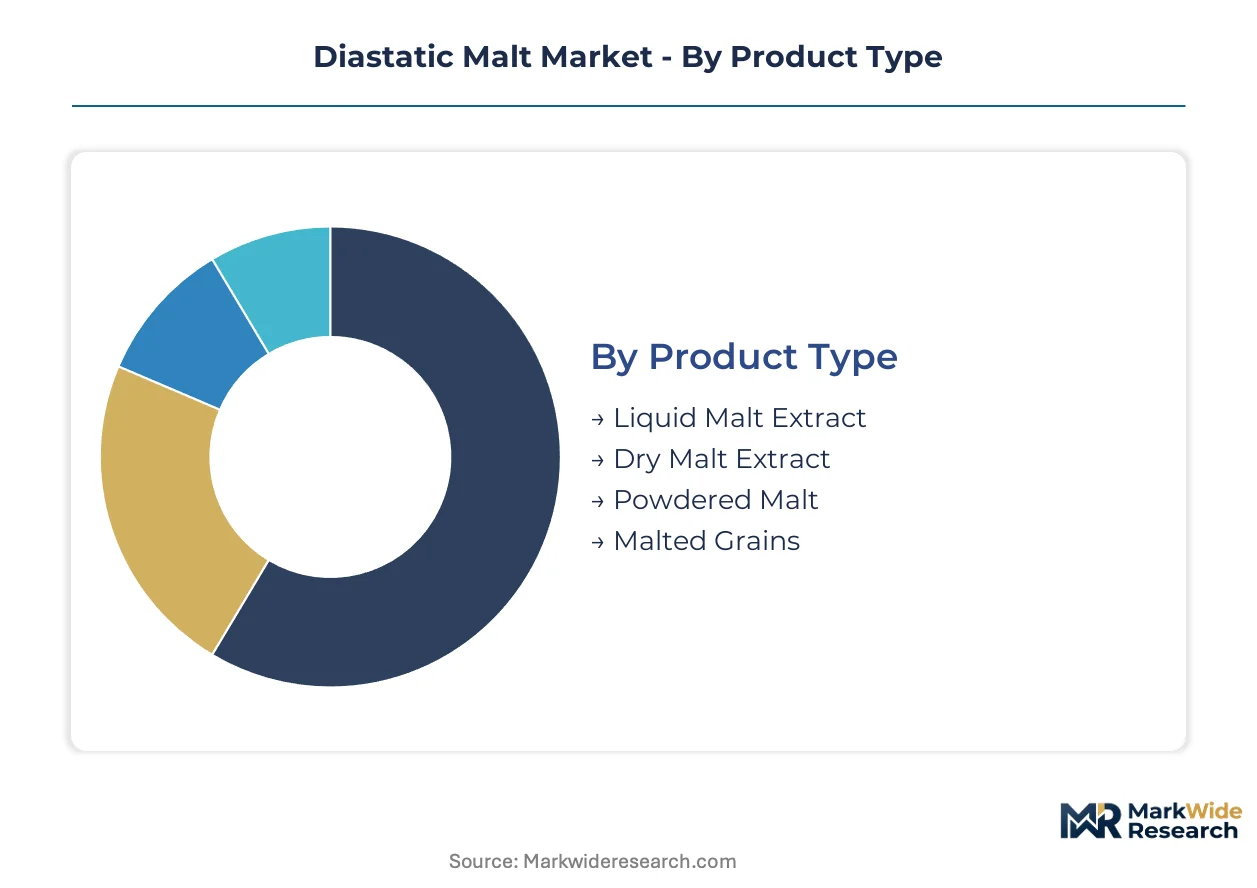
Diastatic malt procurement increasingly hinges on enzymatic performance metrics rather than commodity specifications. Suppliers must align product formats with precise end-use requirements across brewing, baking, and emerging nutritional applications.
Product Type:
Enzymatic activity retention and moisture content define how each format performs in industrial versus artisanal settings.
- Liquid Malt Extract:Higher moisture content preserves volatile aromatic compounds that dry processing strips away. Craft breweries in Oregon and Colorado specify gravity and color profiles batch-by-batch, driving service-contracting models with regional malting houses.
- Dry Malt Extract:Spray-dried or drum-dried formats achieve shelf stability measured in years rather than months. Large-scale brewing operations in Germany's Bavarian corridor prioritize this format for fermentation consistency across multi-site production networks.
- Powdered Malt:Fine-milled diastatic powders integrate into dry dough mixes without hydration delays. Artisanal bakeries substitute these for chemical conditioners to achieve clean-label positioning.
- Malted Grains:Whole or cracked kernels retain visual whole-grain credentials for premium bakery displays. European retail channels command shelf-space premiums for visible grain integrity.
Mature deployment sits with Dry Malt Extract. Newer deployment is concentrated in Liquid Malt Extract.
Application:
End-use specifications diverge sharply between enzyme-driven process requirements and flavor-contribution priorities.
- Brewing:Mashing protocols demand precise alpha-amylase and beta-amylase activity measured in degrees Lintner. Craft breweries now contract for specified enzyme retention curves rather than accepting commodity grades.
- Baking:Dough conditioning applications exploit diastatic malt's natural amylase to soften crumb structure without chemical additives. German artisanal bakeries lead substitution away from azodicarbonamide and DATEM emulsifiers.
- Confectionery:Caramelization and Maillard reaction control in malt-based syrups requires lower enzymatic activity to prevent uncontrolled sugar breakdown during high-heat processing.
- Nutritional Supplements:Malt-derived enzymes and B-vitamin complexes target digestive health positioning in functional food formulations.
Volume concentration remains in Brewing. Application expansion is climbing the fastest in Nutritional Supplements.
Customer Type:
Procurement sophistication varies from specification-heavy technical buying to ingredient-as-a-service relationships.
- Commercial Bakers:High-volume operations prioritize cost stability and supply security over enzymatic customization. Fungal amylase displacement threatens diastatic malt share where flavor contribution is minimal.
- Craft Breweries:Small-batch producers specify Lintner units and protein content with precision once reserved for industrial accounts. Briess Malt and regional competitors embed technical consultation into supply agreements.
- Food Manufacturers:Processed food applications require standardized enzyme activity for consistent texture across production runs. REACH registration burdens for processing aids compress margins for mid-tier suppliers.
- Health Stores:Natural products positioning drives demand for organic-certified and non-GMO malt ingredients with traceable supply chains.
Established relationships dominate Commercial Bakers. Relationship deepening is accelerating most quickly among Craft Breweries.
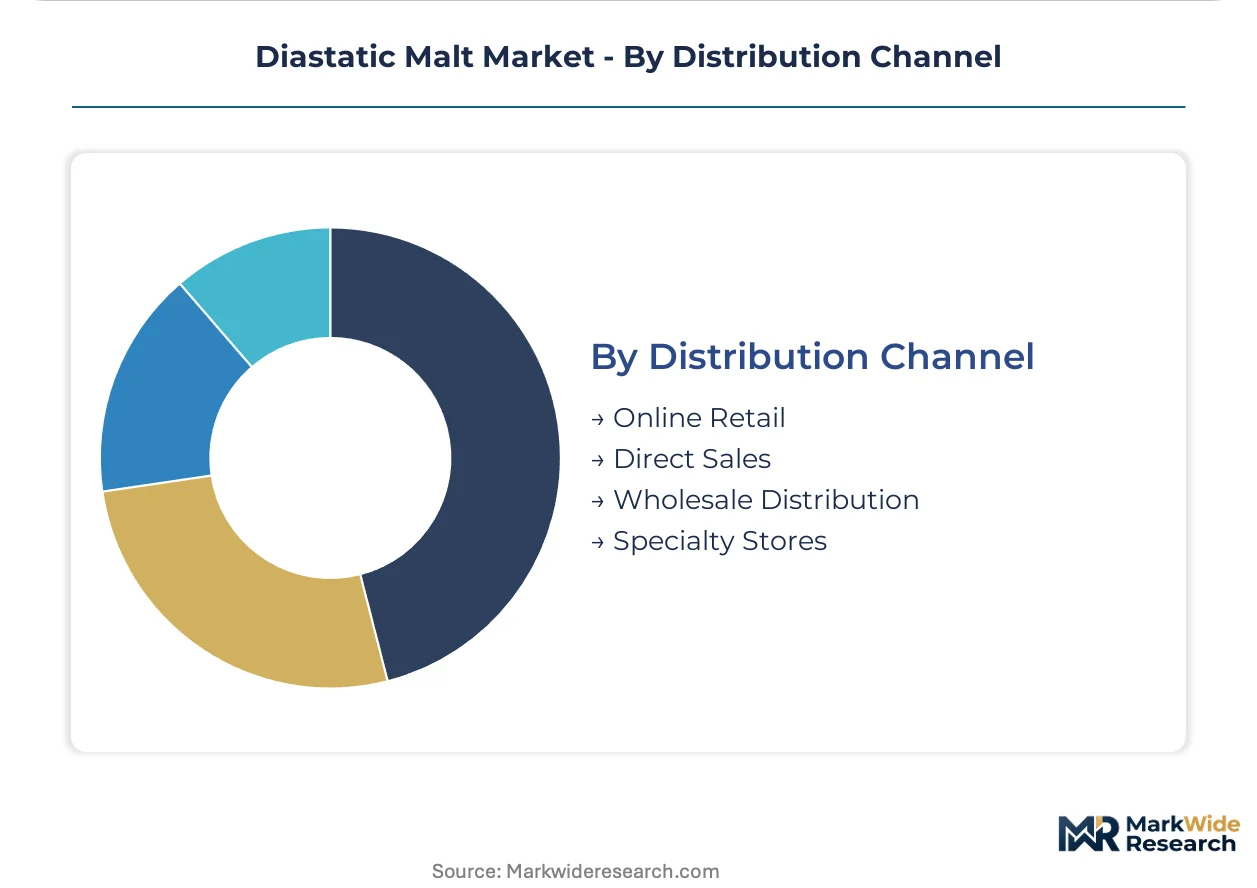
Distribution Channel:
Channel selection reflects order scale, technical support requirements, and geographic concentration of demand.
- Online Retail:E-commerce platforms serve dispersed artisanal producers and home brewing enthusiasts with smaller lot sizes. Digital specification tools now allow Lintner unit selection at point of purchase.
- Direct Sales:Technical consultation and formulation support travel through direct relationships with large brewing and baking operations. Cargill's grain origination network leverages direct channels for premium barley stream allocation.
- Wholesale Distribution:Regional distributors aggregate demand from mid-tier food manufacturers requiring consistent supply without direct supplier relationships.
- Specialty Stores:Homebrew supply shops and artisanal baking equipment retailers carry curated malt portfolios with educational staff support.
Volume flows through Wholesale Distribution. Channel innovation is gaining share fastest in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in malting barley belts while consumption clusters in brewing and baking corridors. Germany and the United States anchor processing capacity. Demand fragmentation pulls specialty volumes toward craft-scale operations in secondary markets.
United States
Colorado and Oregon craft breweries specify diastatic malt extracts by Lintner units for fermentation precision. FDA food-grade enzyme labeling and Good Manufacturing Practice standards govern interstate commerce. The Front Range brewing corridor from Denver to Fort Collins drives ingredient-as-a-service contracting with regional malting houses.
Germany
Bavarian brewing operations demand enzymatic malt with certified alpha-amylase and beta-amylase activity for Reinheitsgebot-compliant production. EFSA frameworks and REACH registration requirements tighten purity protocols for processing inputs. Munich and the broader Bavarian malting corridor concentrate procurement relationships with qualified specialty suppliers.
United Kingdom
Artisanal bakeries in England and Scotland substitute malted barley powders for chemical dough conditioners to achieve clean-label positioning. EMA and EFSA oversight governs novel enzyme applications in food contact substances. Yorkshire and East Anglia malting districts anchor supply for domestic baking and export brewing accounts.
India
Commercial baking expansion in Mumbai and Delhi creates demand for enzymatic malt as FSSAI modernizes food additive standards. CDSCO and FSSAI frameworks create approval pathways for novel food ingredients. Maharashtra and Gujarat food processing corridors attract first-mover malt suppliers seeking ingredient approvals in underpenetrated markets.
Australia
Premium malting barley production in South Australia and Victoria supplies export markets across Asia-Pacific. The country's national food standards regulator enforces labeling requirements for enzyme-modified ingredients. Adelaide and Melbourne malting facilities concentrate processing for brewing conglomerates and craft export accounts.
Diastatic Malt Market Competitive Environment
Capital-heavy malting operations compete with asset-light ingredient formulators across distinct service tiers. The vendor base stratifies between integrated grain processors, specialized malt houses, and regional roasting specialists. Three archetypes dominate: origination-backed multinationals with captive barley supply, vertically controlled regional malters, and craft-focused extract specialists. Competitive moves concentrate on strategic partnerships for enzyme certification and geographic expansion into underpenetrated brewing markets.
Within the integrated processing tier, Cargill, Incorporated anchors North American supply through grain origination networks. Muntons plc exemplifies British vertical control over malting and roasting stages. Briess Malt & Ingredients Co. occupies the specialty extract position for craft brewing accounts. These three represent distinct competitive vectors rather than direct substitutes, with each archetype commanding different procurement relationships based on scale, technical consultation depth, and geographic proximity to demand clusters.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Malteurop Group |
| Muntons plc |
| Briess Malt & Ingredients Co. |
| GrainCorp Malt |
| Viking Malt |
| Simpsons Malt Limited |
| Boortmalt Group |
| Rahr Corporation |
| Others |
Value Chain & Pricing Dynamics
Malting barley futures on the Intercontinental Exchange anchor cost structures across enzymatic malt tiers, transmitting weather-driven volatility from South Australian growing regions into Bavarian processor margins and Colorado craft brewery procurement budgets.
Pricing Analysis
Margin tightening in standard-grade extracts reflects REACH registration cost absorption by mid-tier European processors without captive chemical teams. Pricing stratifies across certified food-grade, industrial-grade, and feed-grade tiers based on enzymatic activity certification and organic credentialing. Cost-down pressure on economy-grade dry malt accelerates because fungal amylase substitution in industrial baking strips volume leverage from commodity malt suppliers. Commercial bakers exhibit highest price sensitivity, while craft breweries in Oregon and Colorado prioritize Lintner precision over per-kilogram cost.
Supply Chain Analysis
Premium malting barley supply rests on concentrated growing regions in South Australia, Victoria, and the North American northern plains. Germination equipment, kilning infrastructure, and enzyme testing laboratories constitute critical input dependencies. Single-source vulnerability concentrates in Bavarian specialty malting houses serving Reinheitsgebot-compliant breweries. Distribution runs through direct technical-sales relationships with large brewing conglomerates, supplemented by regional wholesale aggregators serving mid-tier food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The diastatic malt market functions as a cost-of-compliance story where EU F-Gas Regulation and REACH protocols erect qualification barriers that favor incumbent processors with dedicated regulatory affairs infrastructure.
For Market Incumbents: Hedge against enzyme substitution threats by embedding formulation consultation into supply agreements with Colorado and Oregon craft breweries. Secure backward integration into premium barley origination through long-term contracts with South Australian growers. Prioritize carbon intensity disclosure alignment ahead of emerging EU agricultural input accounting rules to capture preferential procurement from sustainability-focused brewing conglomerates.
For New Entrants and Emerging Players: Begin with FSSAI novel food ingredient approval pathways in Maharashtra and Gujarat food processing corridors, where commercial baking expansion outpaces domestic enzymatic malt supply. Target liquid malt extract customization services for craft-scale breweries seeking batch-specific gravity profiles. Deploy ingredient-as-a-service contracting models that bundle technical consultation with supply agreements.
For Investors and Strategic Acquirers: Distressed-cycle entries favor family-owned malt houses in Yorkshire and East Anglia facing legacy equipment retrofit costs for precision moisture-control systems. Five-to-ten year viability hinges on enzymology talent acquisition and modular germination technology deployment. Watch craft brewery consolidation patterns across the American Front Range as an inflection indicator for specialty extract demand concentration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barley Origination | Cargill's grain network secures premium South Australian streams for enzymatic malt production. |
| REACH-Compliant Processing Aid Qualification | Bavarian processors adopting existing food-grade additives avoid extended ECHA approval timelines. |
| Liquid Extract Customization Services | Briess Malt embeds technical consultation into Colorado Front Range supply agreements. |
| Carbon Intensity Disclosure Alignment | Early EU compliance positions suppliers for preferential procurement from sustainability-focused brewers. |
| FSSAI Novel Ingredient Approval | First-mover malt suppliers capture underpenetrated commercial baking demand in Mumbai and Delhi corridors. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with malting operations managers, craft brewery procurement leads, artisanal bakery owners, and food manufacturing R&D directors combined with ECHA substance registration databases, FSSAI additive approval records, and brewing industry production statistics. Bottom-up volume modeling across product formats and top-down demand validation through end-use consumption patterns enabled triangulation.
Granularity-level modeling operated at product-type, application, and customer-segment dimensions across the projection horizon. CAGRs derived from historical volume trajectories adjusted for regulatory phase-in schedules and substitution elasticity parameters. Enzymatic activity measurement standard evolution and carbon accounting rule implementation served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; liquid malt extract and craft brewery customer data carry tighter precision than powdered malt and commercial baker estimates. Forecasts incorporate assumptions regarding F-Gas Regulation enforcement intensity and fungal amylase displacement rates. REACH registration timeline delays, barley crop quality volatility, and craft brewery consolidation patterns warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Lentils Flour Market
Ingredients
Virgin Coconut Oil Market
Ingredients
Buckwheat–Mediterranean Grain Blend Ingredients Market
Ingredients
Jojoba Oil Market
Ingredients
Bran Market
Ingredients
Ice Cream Bases Market
Ingredients
Egg White Powder Market
Ingredients
Sunflower Lecithin Market
Ingredients
Asia-Pacific Bakery Ingredients Market
Ingredients
India Sodium Reduction Ingredients Market
Ingredients
Grape Seed Extracts Market
Ingredients
Asia-Pacific Agar Market
Ingredients
Global Malt Extracts and Ingredients Market
Ingredients
Rendered Products Market
Ingredients
North America Collagen Ingredients Market
Ingredients
Europe Agar Market