
 Global Oral Proteins and Peptides Market | 2026-2036
Global Oral Proteins and Peptides Market Size, Share, and Industry Trends Forecast 2026-2036
Global Oral Proteins and Peptides Market Foresight
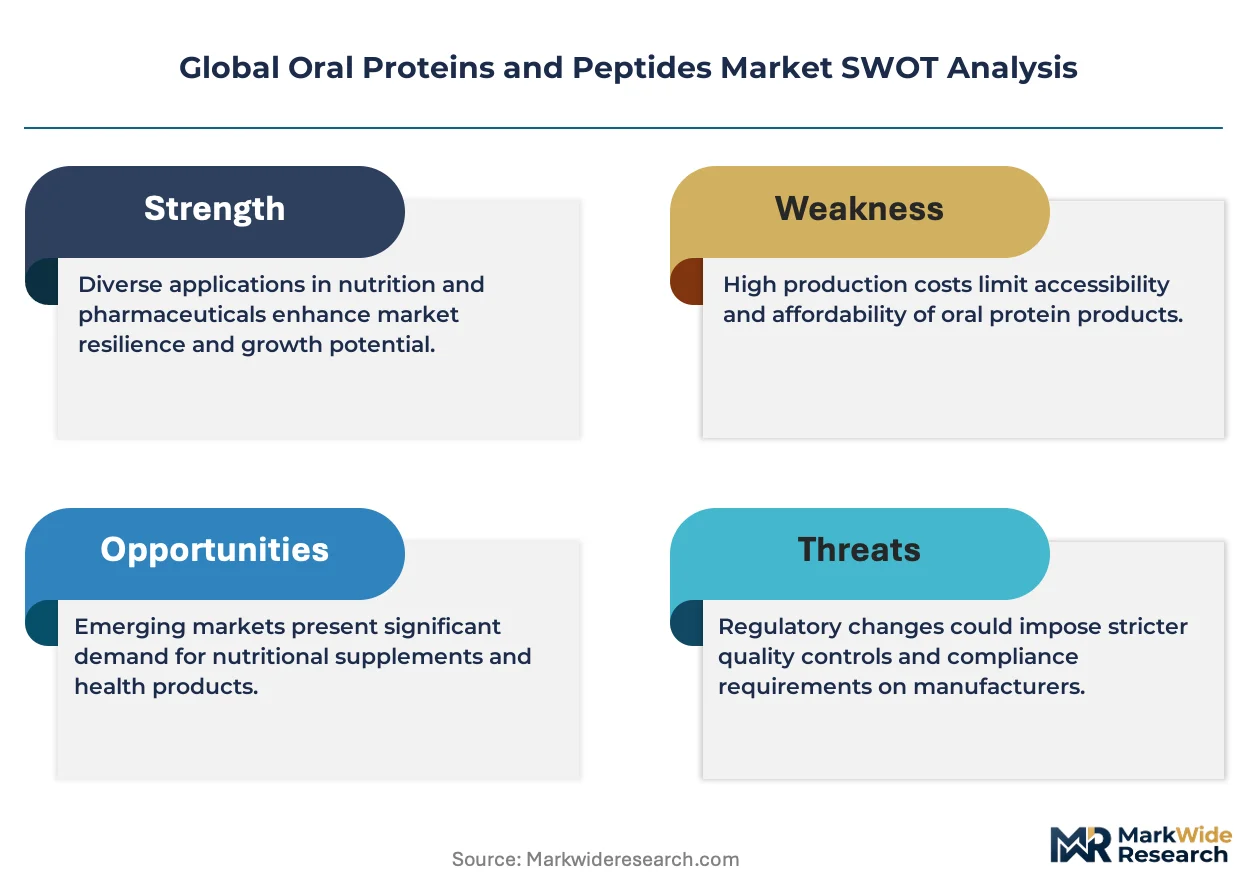
The EU Green Deal is consolidating sustainability requirements across pharmaceutical supply chains, pushing manufacturers toward cleaner production protocols. Novo Nordisk A/S leverages its insulin peptide heritage to dominate metabolic therapy development. Biocon Limited anchors biosimilar manufacturing scale across emerging markets. Pfizer Inc. competes through integrated R&D networks spanning oral delivery platforms.
Oral proteins and peptides comprise amino acid chains formulated for gastrointestinal absorption, typically requiring enteric coatings or permeation enhancers to survive enzymatic degradation and achieve therapeutic bioavailability. These molecules serve primarily as alternatives to injectable biologics in diabetes, osteoporosis, and malabsorption therapies. Whey Protein and Pea Protein segments lead product type revenue as sports nutrition brands prioritize rapid absorption and plant-based positioning. Protein Bars within the Application dimension capture margin concentration through convenience-driven repeat purchasing and premium shelf placement.
FDA peptide drug approval standards, EMA biosimilar guidelines, and WHO prequalification protocols collectively shape formulation investments and cross-border market access timelines. The FDA's emphasis on bioequivalence data for oral peptide generics raises barriers for new entrants while protecting innovator returns. Stakeholders must monitor permeation enhancer patent cliffs and regulatory harmonization progress between FDA and EMA to time capacity commitments and partnership structures.
Market Dynamics
Permeation enhancer patent cliffs are compressing formulation timelines as generic developers race to replicate bioequivalence profiles established by first-generation oral peptide platforms. This structural pressure is redistributing R&D investment toward novel absorption technologies and away from incremental coating improvements.
Growth Catalysts
- FDA Accelerated Approval Pathways:The FDA's streamlined biologics review timelines compress development cycles for oral peptide candidates targeting metabolic disorders. Developers gain earlier revenue recognition while building real-world efficacy datasets.
- Diabetes Patient Preference Shift:Type 2 diabetes populations in the United States demonstrate measurable adherence improvements when switching from injectable GLP-1 analogues to oral formulations. Endocrinology practices report reduced nursing burden and higher prescription renewal rates.
- Enteric Coating Innovation:pH-responsive polymer advances from Germany's specialty chemical suppliers enable precise ileal release timing. These materials protect peptide integrity through gastric transit while triggering absorption in the optimal intestinal segment.
Market Restraints
- Bioavailability Ceiling:Oral peptide absorption rates plateau below 2% for molecules exceeding 30 amino acids regardless of enhancer sophistication. This fundamental biophysical constraint limits therapeutic candidates to smaller peptide sequences.
- India API Concentration:Active pharmaceutical ingredient manufacturing for permeation enhancers clusters in Maharashtra and Gujarat states. Geopolitical disruptions or environmental compliance actions at these sites cascade through global formulation supply.
- Injectable Biologic Substitution:Subcutaneous peptide delivery devices from Denmark and Switzerland achieve 95%+ bioavailability with weekly dosing. These established alternatives erode the clinical urgency driving oral formulation investment.
Strategic Opportunities
- Brazil Biosimilar Prequalification:ANVISA's emerging pathway for oral peptide generics creates first-mover positioning in Latin America's largest metabolic therapy market. Local manufacturing partnerships satisfy domestic content requirements while accessing Mercosur distribution.
- Sports Nutrition Convergence:Collagen peptide fortification of ready-to-drink beverages targets gym-attached convenience retail in South Korea and Australia. Functional positioning beyond basic protein supplementation commands shelf placement premiums.
- EU Green Deal Manufacturing Incentives:The European Commission's pharmaceutical sustainability grants subsidize solvent-free peptide synthesis and biodegradable enteric coatings. Applicants demonstrating carbon footprint reductions gain accelerated EMA scientific advice access.
Industry Challenges
- Bioanalytical Talent Scarcity:LC-MS/MS method development for oral peptide pharmacokinetics requires specialized chromatography expertise concentrated in Boston, Basel, and Singapore. Contract research organizations report 8-month recruitment timelines for senior scientists.
- Stability Validation Burden:ICH Q1A guidelines mandate 24-month real-time stability data for novel oral peptide formulations. This timeline extends regulatory submission windows and compresses effective patent life.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Oral Proteins and Peptides Market |
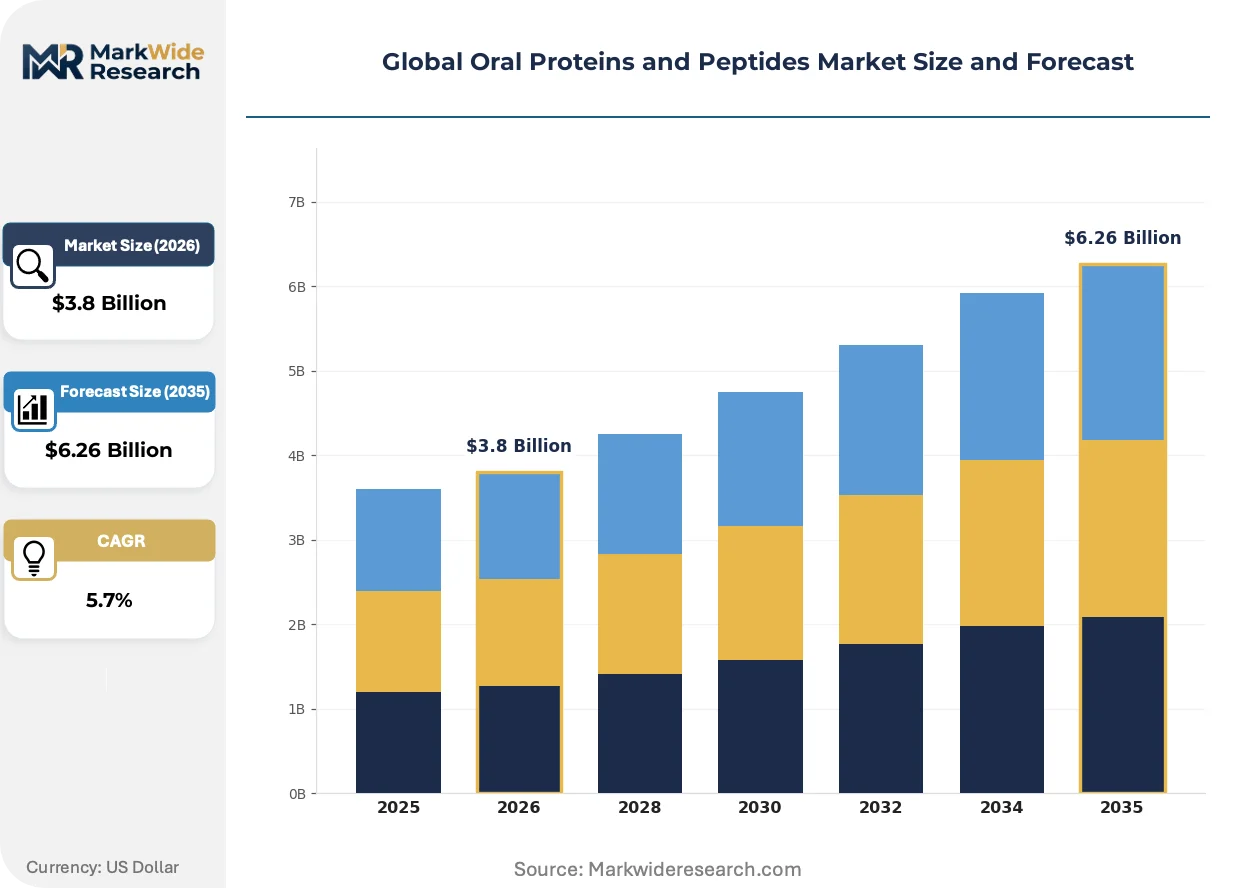
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein, Casein Protein, Soy Protein, Pea Protein End User: Healthcare, Sports Nutrition, Weight Management, Dietary Supplements Application: Protein Bars, Protein Shakes, Nutritional Supplements, Functional Foods Distribution Channel: Online Retail, Supermarkets, Health Stores, Specialty Stores |
| Companies Covered | Novo Nordisk A/S, Biocon Limited, AbbVie Inc., Pfizer Inc., Oramed Pharmaceuticals Inc., Entera Bio Ltd., Proxima Concepts Limited, AstraZeneca plc, Chiesi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Oral Proteins and Peptides Market Shifts & Advancements
Delivery technology convergence is fragmenting competitive advantage away from single-platform specialists toward integrated formulation-engineering capabilities spanning biophysics, materials science, and regulatory strategy.
Self-emulsifying drug delivery systems (SEDDS) are electrifying oral peptide bioavailability by creating lipid-rich intestinal environments that bypass efflux transporters. Mid-sized biotechnology firms in California and Massachusetts are licensing these platforms from academic spinouts at unprecedented velocity. The technology is compressing development timelines for once-discarded peptide candidates previously abandoned due to absorption failures.
REACH authorization requirements for novel chemical permeation enhancers are tightening toxicology disclosure standards across European manufacturing. The ECHA's expanded endocrine disruption screening protocols now capture peptide absorption adjuvants previously exempt from full substance evaluation. German and Swiss formulation houses are responding by accelerating investment in naturally derived enhancer alternatives to preempt regulatory rejection.
Direct-to-consumer subscription models for oral collagen and plant protein peptides are displacing traditional retail pharmacy distribution in urban United States markets. Wellness platforms bundle personalized dosing algorithms with recurring shipments, capturing customer lifetime value exceeding conventional prescription economics. This channel shift concentrates marketing spend on digital acquisition rather than clinician detailing.
Global Oral Proteins and Peptides Market Segmentation
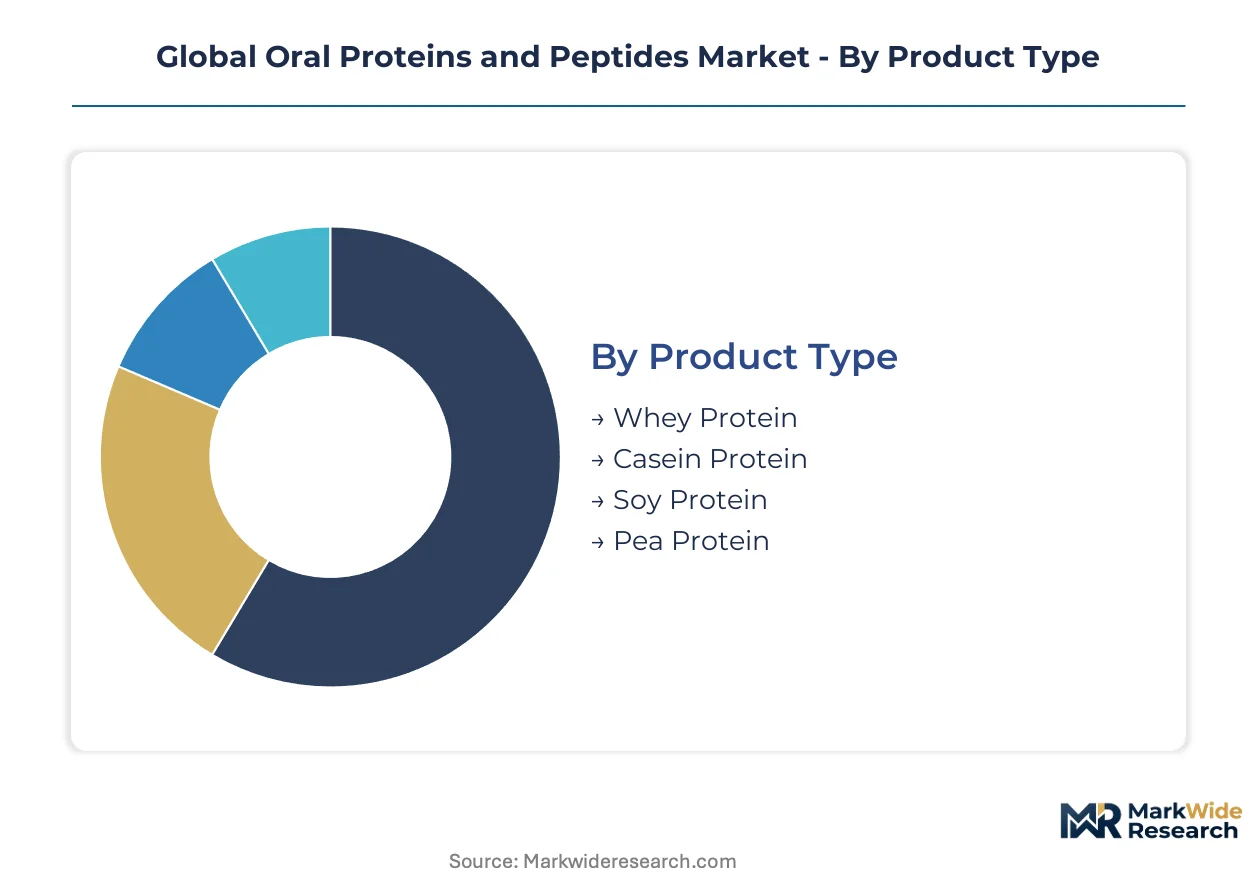
Oral protein and peptide segmentation reveals how formulation requirements diverge across therapeutic versus wellness applications. Each dimension—product chemistry, end-use environment, delivery format, and purchase channel—carries distinct margin structures and regulatory burdens that reshape investment priorities.
Product Type:
Upgrade cycles in protein sourcing accelerate as brands reformulate to capture clean-label premiums and digestive tolerance improvements.
- Whey Protein:Rapidly absorbed complete protein with high leucine content supports muscle protein synthesis. Sports nutrition brands in the United States concentrate procurement here, though lactose intolerance prevalence in East Asian populations limits addressable market expansion.
- Pea Protein:Hypoallergenic plant-based alternative with improving amino acid profiles through fractionation advances. German and Dutch ingredient suppliers scale extrusion capacity to serve European vegan positioning requirements.
- Casein Protein:Slow-digesting micellar structure enables overnight amino acid release for recovery applications.
- Soy Protein:Cost-efficient isoflavone-containing option dominates emerging market mass nutrition programs.
Volume placements concentrate in Whey Protein; the faster expansion belongs to Pea Protein.
End User:
Cost tier stratification separates clinical-grade peptide therapies from commodity protein nutrition.
- Sports Nutrition:Athletes and gym-attached consumers prioritize rapid absorption kinetics and leucine thresholds. Australian and South Korean markets show particular willingness to pay for hydrolyzed peptide formulations claiming accelerated recovery.
- Healthcare:Hospital and long-term care settings demand therapeutic-grade proteins for malabsorption and wound healing. FDA and EMA bioequivalence standards elevate sourcing costs above wellness-grade alternatives.
- Weight Management:Satiety-signaling peptide fortification targets meal replacement positioning.
- Dietary Supplements:General wellness consumers drive commoditization through price-sensitive bulk purchasing.
Margin capture peaks in Healthcare; Sports Nutrition gains share fastest through direct-to-consumer subscription penetration.
Application:
Format innovation reshapes consumption occasions and shelf stability requirements.
- Protein Bars:Convenience-driven repeat purchasing commands premium placement in airport and gym retail. German and Swiss manufacturers lead in clean-label binding technologies that extend shelf life without artificial preservatives.
- Protein Shakes:Ready-to-drink liquid formats require aseptic processing and cold chain logistics. Brazilian and Mexican markets expand manufacturing capacity for Latin American distribution.
- Nutritional Supplements:Powder and capsule formats retain cost advantage for home preparation.
- Functional Foods:Peptide fortification of mainstream grocery items broadens addressable base.
Protein Bars anchor revenue concentration; Functional Foods climb fastest as CPG brands cross-category.
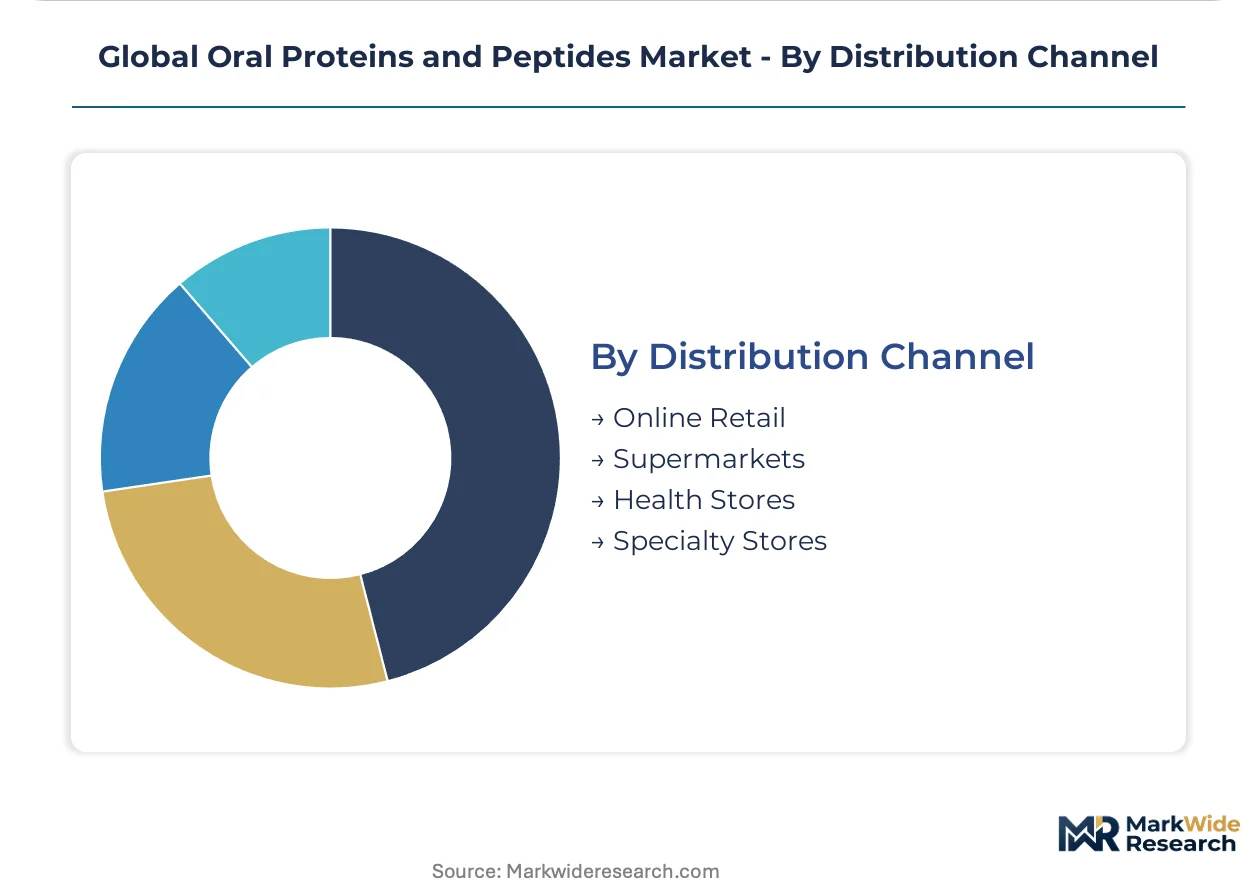
Distribution Channel:
Customer acquisition economics diverge sharply between digital-native and brick-and-mortar pathways.
- Online Retail:Subscription algorithms and personalized dosing recommendations capture lifetime value exceeding traditional pharmacy economics. United States wellness platforms dominate this channel through influencer-driven customer acquisition.
- Supermarkets:Mass-market penetration requires slotting fee negotiations and promotional calendar alignment. French and UK retailers particularly emphasize private-label protein positioning.
- Health Stores:Pharmacist and nutritionist consultation attachment sustains premium pricing.
- Specialty Stores:Gym-attached and sports-specific retail concentrates high-loyalty repeat purchasers.
Online Retail captures volume leadership; Specialty Stores expand most quickly through boutique fitness proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation capacity clusters in Germany and the United States while consumption tilts toward diabetes-prevalent populations in Brazil and South Korea. Regulatory divergence between FDA accelerated pathways and EMA sustainability mandates fragments investment geography.
United States
GLP-1 oral peptide demand concentrates among Type 2 diabetes patients seeking injection alternatives. FDA accelerated approval pathways compress development timelines for metabolic disorder candidates. Greater Boston hosts contract research organizations specializing in LC-MS/MS bioanalytical method development for peptide pharmacokinetics.
Germany
Enteric coating innovation drives specialty chemical procurement from pH-responsive polymer suppliers. EU Green Deal manufacturing incentives subsidize solvent-free peptide synthesis and biodegradable coating development. The Rhine-Ruhr industrial corridor anchors permeation enhancer production serving EMA-regulated formulations.
India
API manufacturing for permeation enhancers clusters in Maharashtra and Gujarat states serving global generic developers. CDSCO bioequivalence guidelines for oral peptide generics raise documentation burdens for domestic manufacturers. Hyderabad's biotech corridor expands biosimilar peptide capacity targeting emerging market access.
Brazil
ANVISA's emerging biosimilar prequalification pathway attracts first-mover investment in Latin America's largest metabolic therapy market. Domestic content requirements under Mercosur trade rules favor local manufacturing partnerships. São Paulo's pharmaceutical cluster concentrates oral peptide distribution infrastructure.
South Korea
Sports nutrition convergence drives collagen peptide fortification in ready-to-drink beverages targeting gym-attached retail. MFDS functional food regulations govern peptide health claims in consumer-facing products. Seoul's wellness platform ecosystem dominates direct-to-consumer subscription distribution.
Global Oral Proteins and Peptides Market Competitive Landscape
The competitive structure tilts toward integrated pharmaceutical conglomerates with heritage peptide platforms. Novo Nordisk and Biocon exemplify divergent archetypes: the former leveraging insulin peptide heritage for metabolic therapy dominance, the latter anchoring biosimilar manufacturing scale across price-sensitive markets. Mid-sized biotechnology specialists concentrate on novel absorption technologies including self-emulsifying drug delivery systems. Dominant competitive moves include strategic partnerships for permeation enhancer licensing and capacity expansion in India and Brazil to satisfy local content requirements.
Among heritage metabolic therapy developers, Novo Nordisk A/S occupies a position exemplifying vertical integration from peptide synthesis through commercial distribution. Biocon Limited represents the emerging market biosimilar archetype, anchoring cost-competitive manufacturing scale. Pfizer Inc. sits within the diversified pharmaceutical conglomerate tier, competing through integrated R&D networks spanning multiple oral delivery platforms. These three entities collectively illustrate the strategic divergence between innovation-driven and scale-driven market participation.
| Leading Market Players |
|---|
| Novo Nordisk A/S |
| Biocon Limited |
| AbbVie Inc. |
| Pfizer Inc. |
| Oramed Pharmaceuticals Inc. |
| Entera Bio Ltd. |
| Proxima Concepts Limited |
| AstraZeneca plc |
| Chiesi Group |
| Others |
Supply & Pricing Matrix
pH-responsive polymer costs from Germany's specialty chemical suppliers cascade through oral peptide formulation tiers, compressing margins at the generic end while sustaining premium pricing for novel absorption platforms protected by enhancer patents.
Pricing Analysis
Value-based pricing anchors on therapeutic bioequivalence outcomes, with FDA-approved oral peptide therapies commanding substantial premiums over injectable alternatives. Three-tier pricing structure across premium, standard, and economy levels separates innovator formulations with permeation enhancer exclusivity from bioequivalent generics and commodity protein nutrition. Pricing pressure stems from patent cliff compression as first-generation oral peptide platforms face generic replication. Hospital procurement committees exhibit highest price sensitivity; direct-to-consumer wellness subscribers demonstrate lowest elasticity.
Supply Chain Analysis
Regional distribution centers in São Paulo, Mumbai, and Rotterdam orchestrate hub-and-spoke patterns for temperature-sensitive peptide intermediates. API manufacturing for permeation enhancers clusters in India, China, and Germany, drawing from soy and pea protein isolates plus synthetic polymer feedstocks. Single-source vulnerability concentrates in Maharashtra and Gujarat states for critical absorption adjuvants. Distribution runs through pharmaceutical wholesale networks for clinical grades and direct-to-consumer platforms for wellness segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Permeation enhancer patent scarcity props pricing across oral peptide tiers, constraining supply expansion as generic developers race bioequivalence replication.
For Market Incumbents: To counter generic developer acceleration around patent cliffs, Novo Nordisk and heritage metabolic therapy leaders should deepen backward integration into pH-responsive polymer production and lock exclusive capacity at German specialty chemical suppliers. Channel control through direct-to-consumer subscription platforms offers defensive moats against retail pharmacy erosion. For New Entrants and Emerging Players: ANVISA's emerging biosimilar prequalification pathway in Brazil opens a window for first-mover positioning in Latin America's largest metabolic therapy market. White-space targets include collagen peptide fortification in South Korean ready-to-drink beverages and solvent-free synthesis capacity serving EU Green Deal manufacturing incentives. A go-to-market angle anchored in local manufacturing partnerships satisfies Mercosur domestic content requirements. For Investors and Strategic Acquirers: Permeation enhancer patent cliff announcements are the leading indicator that generic formulation capacity will flood select therapeutic segments. Long-term viability across the projection horizon favors acquisition targets with integrated absorption technology platforms spanning SEDDS, enteric coating, and permeation enhancement. Self-emulsifying drug delivery system licensing velocity from California and Massachusetts academic spinouts signals platform consolidation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Permeation Enhancer Patent Licensing | Platform access from German and Swiss formulation houses accelerates generic bioequivalence timelines. |
| Local Manufacturing Partnership | Brazilian and Indian capacity satisfies ANVISA and CDSCO domestic content requirements for market access. |
| Direct-to-Consumer Platform Launch | Subscription algorithms in United States urban markets capture customer lifetime value exceeding pharmacy economics. |
| Solvent-Free Synthesis Scale-Up | EU Green Deal subsidies accelerate EMA scientific advice access for sustainable peptide production. |
| LC-MS/MS Bioanalytical Capacity Expansion | Boston and Basel contract research organizations address 8-month recruitment timelines for pharmacokinetics expertise. |
Research Methodology
Independent corroboration across drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers underwrites the qualitative findings, cross-checked against FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up segmentation modeling triangulates with top-down market sizing from trade data and industry association reports.
Rate-of-change decomposition separates volume growth from pricing dynamics across the analysis window, with segmentation dimensions spanning product chemistry, end-use environment, delivery format, and distribution channel. CAGRs derive from modeled patient population expansion, prescription conversion rates from injectable to oral formulations, and wellness segment subscription penetration. Forecast inputs include permeation enhancer patent expiration schedules and regulatory harmonization progress between FDA and EMA.
The model assumes a particular technology adoption path; alternative pathways for self-emulsifying drug delivery systems would alter the outlook. Forecasts reflect assumptions around bioequivalence approval timelines, API supply continuity from Indian manufacturing clusters, and direct-to-consumer channel regulatory tolerance. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Japan Functional Drinks Market
Functional Food and Beverage
Functional Foods and Natural Health Products Market
Functional Food and Beverage
Health and Wellness Foods Market
Functional Food and Beverage
Low Fat Protein Market
Functional Food and Beverage
GCC Functional Food & Beverage Market
Functional Food and Beverage
Europe Functional Water Market
Functional Food and Beverage
Low-Fat and Low Cholesterol Diet Market
Functional Food and Beverage
Asia-Pacific Functional Mushroom Market
Functional Food and Beverage
Adaptogen Drink Market
Functional Food and Beverage
Galacto Oligosaccharides (GOS) Market
Functional Food and Beverage
Vitamin Functional Water Market
Functional Food and Beverage
Europe Medical Foods Market
Functional Food and Beverage
Functional Shots Market
Functional Food and Beverage
Low Carb and Low Fat Diet Market
Functional Food and Beverage
Natural Functional Food Market
Functional Food and Beverage
Asia-Pacific Functional Beverages Market