
 Marine Engines Market | 2026-2036
Marine Engines Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Engines Market Analysis
Capital-intensity divergence between integrated two-stroke specialists and modular four-stroke assemblers is reorganizing competitive tiers in marine propulsion. MAN Energy Solutions leverages in-house foundry capacity and electronic fuel-injection platforms to sustain dominance in low-speed cargo-vessel segments. Wärtsilä anchors its position through dual-fuel portfolio breadth, while Caterpillar competes across medium-speed auxiliary and tug applications with distributed service networks.
Marine engines are internal-combustion or electric propulsion systems engineered to deliver sustained torque at variable load profiles, typically operating at 500–1,200 rpm for two-stroke low-speed units and 600–1,800 rpm for four-stroke medium-speed designs, with bore diameters spanning 250–960 mm and specific fuel-oil consumption targets below 160 g/kWh for IMO Tier III compliance. Their primary purpose is converting thermal energy into rotational mechanical power for ship propulsion and onboard electrical generation. Diesel engine types occupy the dominant revenue share due to retrofit compatibility and bunker-fuel infrastructure maturity, while hybrid configurations represent the fastest-expanding margin pool as harbor craft and short-sea operators face port-emission mandates. Power ratings above 1000 HP concentrate value in deep-sea merchant vessels, whereas the 100–500 HP band serves coastal patrol and workboat fleets where lifecycle cost sensitivity shapes procurement.
IMO Tier III NOx limits, EU MRV monitoring rules, and EPA marine engine standards collectively restrict market access for non-compliant powertrain architectures and redirect R&D budgets toward aftertreatment and alternative fuels. Classification societies including DNV and Lloyd's Register now embed lifecycle carbon scoring into type-approval protocols, tightening certification pathways for conventional diesel-only offerings. Stakeholders must monitor methanol bunkering infrastructure buildout and ammonia combustion trials to align product roadmaps with fuel-agnostic regulatory trajectories.
Market Dynamics
IMO 2023 carbon intensity regulations are compressing engine replacement cycles and forcing shipowners toward dual-fuel architectures before residual-value collapse hits conventional diesel-only assets.
Growth Catalysts
- EU MRV monitoring rules:Data-verification mandates for vessels calling European ports are accelerating sensor retrofits and engine-control upgrades across container and tanker fleets.
- Methanol bunkering infrastructure:Port authorities in Rotterdam, Singapore, and Shanghai are installing storage and supply systems that enable methanol-ready engine orders.
- Offshore wind installation vessels:Jones Act compliance requirements and turbine-scale growth are driving demand for high-thrust, dynamic-positioning-capable propulsion packages.
Market Restraints
- Steel and nickel alloy input costs:Crankshaft forging and cylinder liner casting face margin compression from volatile commodity markets and energy-intensive foundry operations.
- Two-stroke engine supply concentration:Low-speed propulsion systems depend on a narrow base of licensed manufacturers with captive casting capacity in South Korea and Japan.
- Ammonia combustion toxicity:Unresolved NOx and N2O emission profiles, plus crew-safety protocols, delay type-approval timelines for ammonia-fueled architectures.
Strategic Opportunities
- Battery-hybrid harbor craft:Tug operators in Los Angeles, Long Beach, and Hamburg are piloting shore-charging infrastructure for zero-emission terminal assist.
- EU Green Deal maritime funding:Innovation grants and green-corridor subsidies are de-risking first-mover investments in hydrogen and methanol propulsion pathways.
- Digital twin integration:Real-time performance modeling combined with predictive maintenance contracts is creating recurring-revenue streams independent of hardware sales.
Industry Challenges
- Dual-fuel technician scarcity:High-pressure gas-injection and cryogenic fuel-system expertise remains concentrated among original-equipment service networks, constraining third-party maintenance scale.
- IMO Tier III certification timelines:Selective catalytic reduction and exhaust-gas recirculation validation protocols extend new-engine type-approval cycles by 12–18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Engines Market |
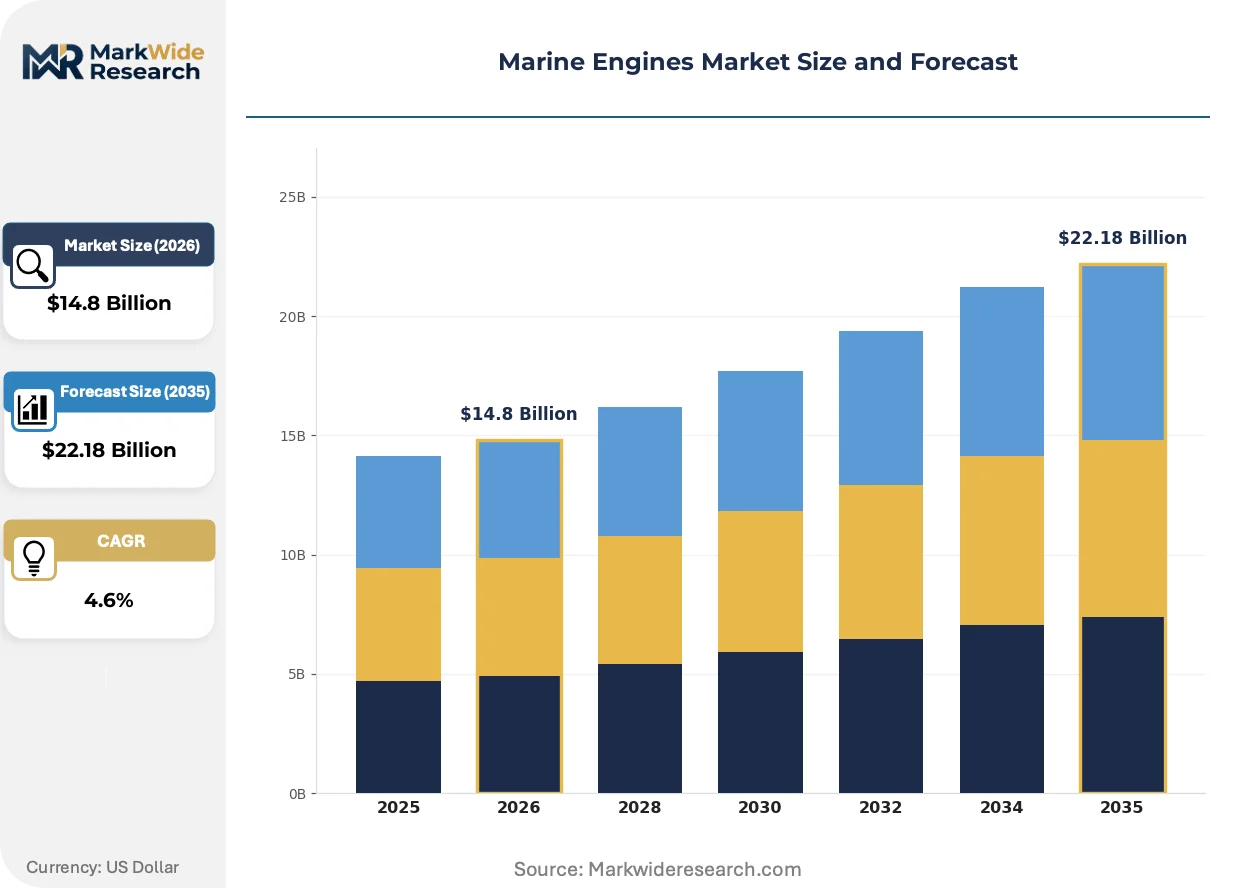
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Engine Type: Diesel, Gasoline, Electric, Hybrid Power Rating: Less than 100 HP, 100-500 HP, 501-1000 HP, Above 1000 HP Application: Commercial Vessels, Recreational Boats, Fishing Boats, Military Crafts Installation Type: Inboard, Outboard, Sterndrive, Auxiliary |
| Companies Covered | MAN Energy Solutions, Wärtsilä, Caterpillar, Rolls-Royce, Hyundai Heavy Industries, Mitsubishi Heavy Industries, Yanmar Holdings, Cummins, Volvo Penta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Engines Market Emerging Trajectories
Propulsion technology is bifurcating between deep-sea decarbonization pathways and coastal electrification, with software-defined engine management emerging as the common thread across both segments.
Electronic fuel-injection systems with real-time cylinder-pressure feedback are supplanting mechanically governed camshaft designs in medium-speed four-stroke engines. Coastal ferry operators in Scandinavia and the Baltic are adopting these architectures to enable multi-fuel switching without hardware swaps. The shift is compressing the aftermarket for mechanical spare parts while expanding software-licensing revenue pools.
EPA marine engine standards for Category 3 vessels are tightening NOx and particulate limits for US-flagged cargo operations. Engine makers must now integrate selective catalytic reduction or exhaust-gas recirculation into new builds, adding cost and footprint constraints. Great Lakes bulk carriers and Jones Act container feeders face the steepest compliance ramps, with retrofit deadlines accelerating fleet-renewal decisions.
Shipowners are unbundling propulsion-system procurement from lifecycle service contracts, splitting hardware purchase from maintenance and spare-part agreements. Charter-party operators with volatile route assignments favor this flexibility over traditional power-by-the-hour arrangements. The pattern is most pronounced in Singapore and Dubai, where third-party technical managers dominate vessel operations.
Marine Engines Market Segmentation
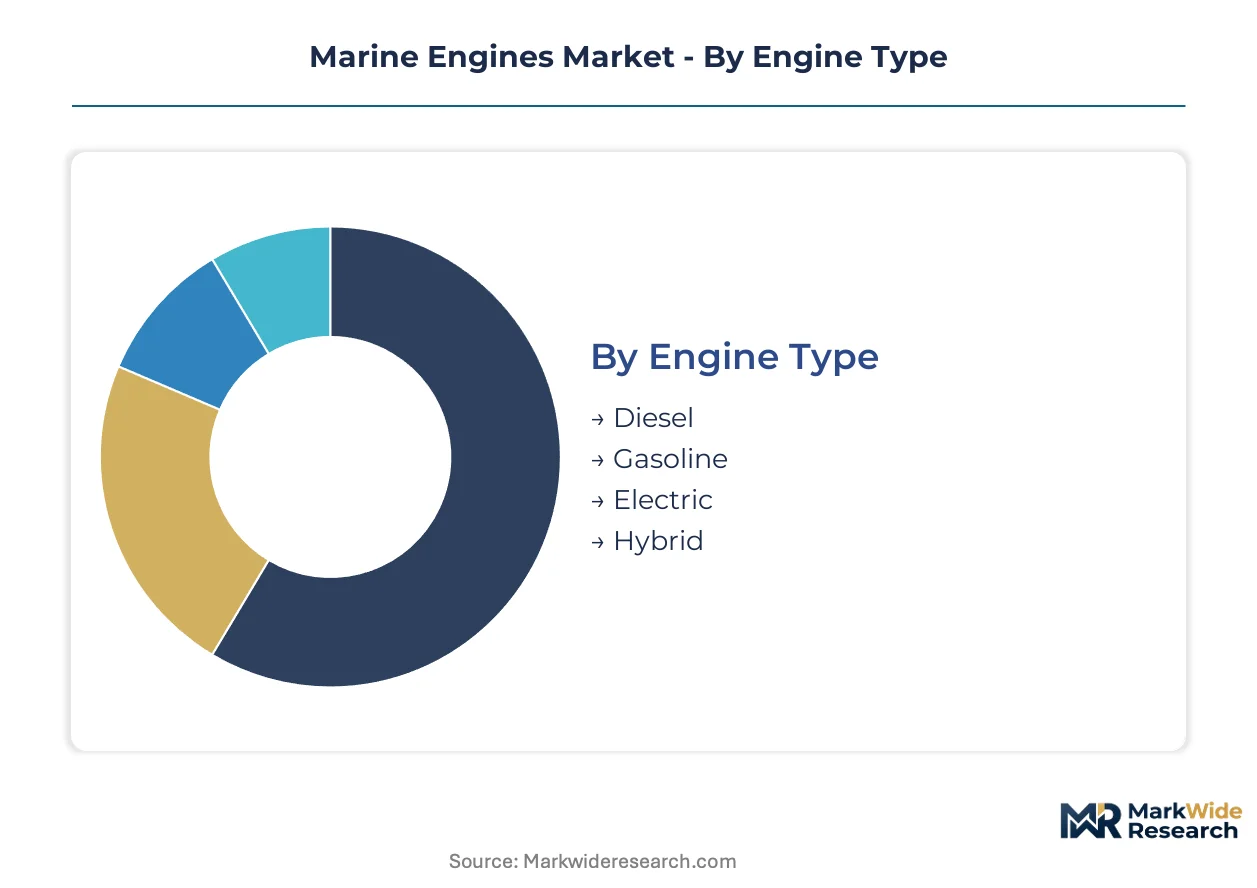
Marine engine procurement patterns diverge sharply across propulsion architectures and vessel duty cycles. Shipowners segment investments by regulatory exposure, fuel infrastructure maturity, and route-specific torque demands.
Engine Type:
Diesel architectures dominate export-heavy supply chains to deep-sea merchant fleets, while electric and hybrid configurations concentrate in domestic coastal operations with shore-power access.
- Diesel:Two-stroke low-speed and four-stroke medium-speed designs deliver sustained torque at 500–1,800 rpm for cargo vessels and tankers. Demand clusters in South Korea's Ulsan shipbuilding cluster where Hyundai Heavy Industries anchors procurement for IMO Tier III compliant architectures.
- Hybrid:Battery-diesel and battery-gas configurations enable zero-emission harbor operations and short-sea routes. Scandinavian ferry operators in Oslo Fjord and Danish Belt routes are retrofitting fleets to meet port-emission mandates ahead of EU Green Deal timelines.
- Electric:Pure battery propulsion serves inland waterways and terminal assist tugs with predictable duty cycles and shore-charging infrastructure.
- Gasoline:Spark-ignition outboards power recreational craft and small fishing vessels where first-cost sensitivity outweighs fuel efficiency priorities.
Diesel commands the established base. The steepest expansion runs through hybrid configurations.
Power Rating:
Cost tiers separate procurement behavior: capital-intensive ratings above 1000 HP require integrated foundry partnerships, while sub-500 HP bands favor modular assembly and distributed service networks.
- Above 1000 HP:Low-speed two-stroke engines with bore diameters of 600–960 mm propel container ships and bulk carriers across transoceanic routes. MAN Energy Solutions and licensed foundries in Japan and South Korea concentrate output for this segment where specific fuel-oil consumption targets below 160 g/kWh determine contract awards.
- 100-500 HP:Medium-speed four-stroke units serve coastal patrol, workboat, and tug fleets. Lifecycle cost sensitivity shapes procurement in Singapore and Dubai where third-party technical managers dominate vessel operations.
- Less than 100 HP:Compact outboards and small inboards power recreational and near-shore fishing craft.
- 501-1000 HP:Auxiliary generators and medium-duty propulsion for offshore supply vessels and short-sea feeders.
Ratings above 1000 HP concentrate value in deep-sea merchant fleets. The 100-500 HP band is climbing fastest as harbor craft electrification accelerates.
Application:
Customer type determines fuel pathway lock-in: commercial operators face charter-party carbon clauses, while military buyers prioritize supply security over emission metrics.
- Commercial Vessels:Container ships, tankers, and bulk carriers face IMO 2023 carbon intensity regulations compressing replacement cycles. Dual-fuel methanol-ready architectures are concentrating orders in Rotterdam and Singapore corridors where bunkering infrastructure is maturing.
- Military Crafts:Naval patrol vessels and amphibious platforms require fuel-agnostic architectures with strategic fuel reserve compatibility. Procurement prioritizes domestic foundry capacity and sovereign maintenance protocols over emission optimization.
- Fishing Boats:Diesel outboards and small inboards serve artisanal and industrial fleets with intermittent duty cycles and limited shore-power access.
- Recreational Boats:Pleasure craft and yacht segments favor gasoline outboards and sterndrives where noise and vibration suppression command price premiums.
Commercial vessels anchor volume demand. Military applications maintain the most stable procurement trajectory through defense budget cycles.
Installation Type:
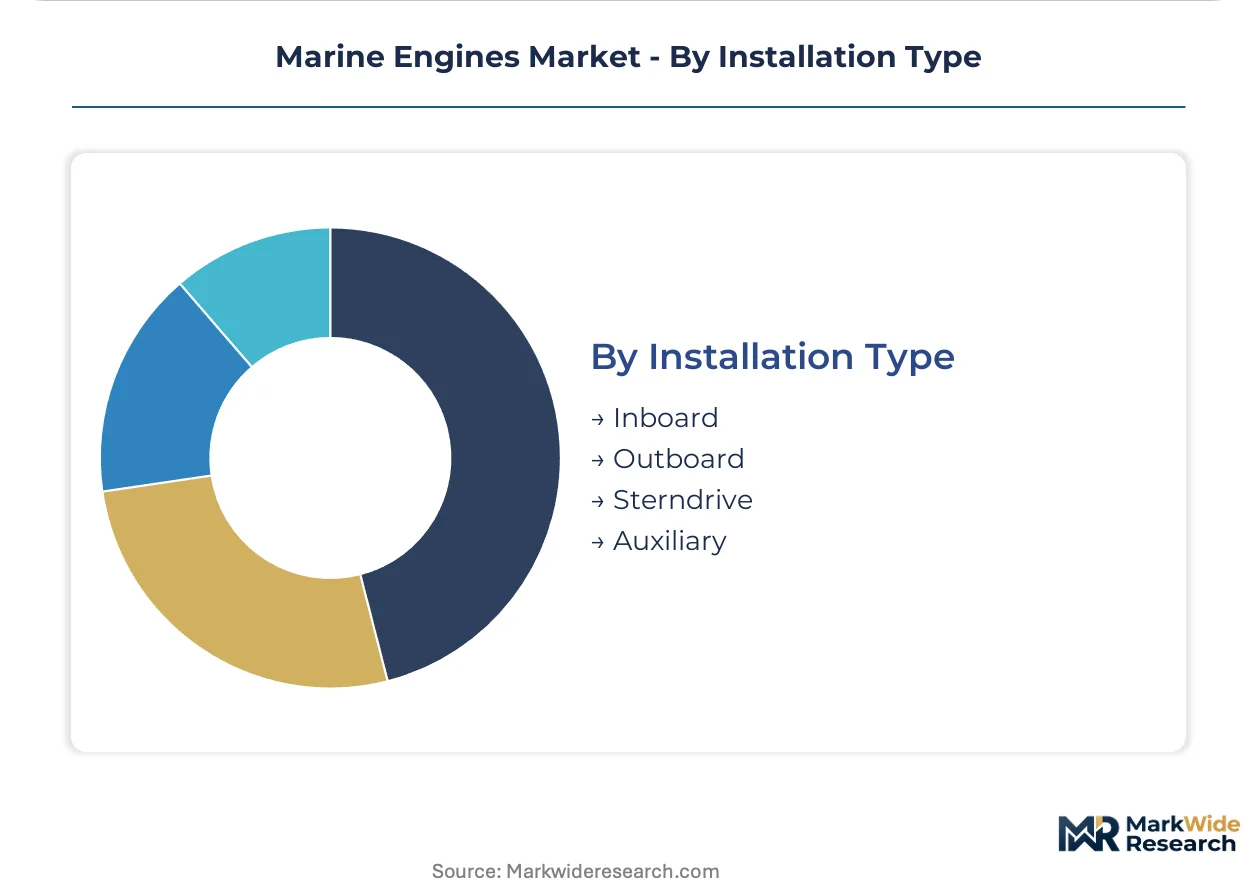
Volume distribution reflects vessel architecture constraints: inboard installations scale with hull displacement, while outboard modularity suits multi-mission craft.
- Inboard:Fixed-shaft propulsion systems integrate with deep hull forms for cargo vessels, tankers, and large yachts. MAN Energy Solutions and Wärtsilä dominate this segment through electronic fuel-injection platforms and dual-fuel portfolio breadth.
- Outboard:Transom-mounted engines enable rapid power scaling and shallow-water operations for patrol craft, rescue vessels, and recreational boats. Caterpillar competes across this segment with distributed service networks in coastal hubs.
- Sterndrive:Inboard-outboard hybrids merge maneuverability with interior hull space efficiency for mid-size recreational and commercial craft.
- Auxiliary:Generator sets and thruster engines provide electrical power and dynamic positioning independent of main propulsion.
Inboard systems command the established base. Outboard configurations are gaining share fastest in multi-mission and coastal patrol applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in South Korea and Japan exhibit low price elasticity for low-speed two-stroke engines due to captive foundry partnerships, while operators in Southeast Asia and the Middle East display acute cost sensitivity in the sub-500 HP auxiliary segment.
South Korea
Hyundai Heavy Industries anchors procurement for deep-sea merchant fleets through its Ulsan shipbuilding cluster, where dual-fuel methanol-ready architectures concentrate orders. The Ministry of Oceans and Fisheries enforces domestic content requirements for public vessel programs. Foundry capacity in Ulsan and Geoje supplies crankshaft forgings and cylinder liners to licensed engine manufacturers.
Japan
Mitsubishi Heavy Industries and licensed fabricators serve container ship and bulk carrier operators facing IMO 2023 carbon intensity deadlines. METI subsidizes ammonia combustion trials and alternative fuel R&D through its Green Innovation Fund. Nagasaki and Kobe house concentrated casting capacity for low-speed propulsion systems.
China
State-owned shipyards in Shanghai and Dalian drive demand for medium-speed four-stroke engines in short-sea feeder and offshore supply vessel applications. MEE implements domestic emission standards mirroring IMO Tier III NOx limits. The Yangtze River Delta cluster concentrates engine assembly and retrofit activity for coastal trade routes.
United States
Jones Act compliance requirements sustain demand for high-thrust propulsion in Great Lakes bulk carriers and offshore wind installation vessels. EPA marine engine standards for Category 3 vessels tighten NOx and particulate limits, accelerating fleet renewal. Gulf Coast shipyards in Louisiana and Texas specialize in dynamic-positioning packages for energy sector applications.
Germany
MAN Energy Solutions leverages in-house foundry capacity and electronic fuel-injection platforms from its Augsburg headquarters. The KBA enforces EU MRV monitoring compliance for vessels calling Hamburg and Bremerhaven. The country's inland waterway operators pilot methanol-ready medium-speed engines on Rhine cargo routes.
Marine Engines Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in marine propulsion. Two-stroke low-speed engine production concentrates among licensed manufacturers with captive casting capacity in East Asia, while four-stroke medium-speed assembly fragments across modular suppliers with distributed service networks. Strategic archetypes include foundry-integrated system integrators, dual-fuel technology specialists, and regional service-intensive assemblers. Dominant competitive moves center on backward integration into precision casting and electronic control platform licensing.
Among integrated European specialists, MAN Energy Solutions and Wärtsilä exemplify the foundry-integrated and dual-fuel archetypes respectively, while Caterpillar represents the service-network-intensive assembler model. These three anchors occupy positions across distinct power rating and application tiers without direct overlap in core propulsion segments.
| Leading Market Players |
|---|
| MAN Energy Solutions |
| Wärtsilä |
| Caterpillar |
| Rolls-Royce |
| Hyundai Heavy Industries |
| Mitsubishi Heavy Industries |
| Yanmar Holdings |
| Cummins |
| Volvo Penta |
| Others |
Supply Flow & Price Mechanics
Fourteen-month crankshaft forging lead times concentrate pricing power among licensed foundries in South Korea and Japan, while shipowners absorb premium markups for dual-fuel architectures that lock in residual value against IMO 2023 carbon intensity deadlines. This supply bottleneck feeds into tiered contract structures where electronic fuel-injection platforms command licensing royalties independent of hardware margins.
Pricing Analysis
After-sales service contracts and spare-part agreements now drive lifetime value beyond initial engine sales, with power-by-the-hour arrangements yielding recurring revenue streams that offset compressed hardware margins. Pricing stratifies across IMO Tier III certified architectures, dual-fuel methanol-ready configurations, and conventional diesel-only units, with certification level and after-sales bundling as primary differentiation drivers. Cost compression in conventional diesel segments is intensifying because shipowners accelerate fleet renewal ahead of residual-value collapse, while military buyers show lowest price sensitivity due to sovereign maintenance protocols and strategic fuel reserve requirements.
Supply Chain Analysis
Strategic stockpiling of nickel alloy ingots and cylinder liner castings prevails over just-in-time preferences as foundry capacity constraints in Ulsan and Nagasaki force engine makers to secure input positions six quarters ahead of delivery windows. Geographic supply concentration centers on South Korea, Japan, and China for crankshaft forgings, precision castings, and electronic control module assembly. Raw material dependencies rest on high-grade steel billets, nickel-chromium alloys, and rare-earth elements for permanent magnet alternators. Single-source vulnerability in low-speed two-stroke licensed manufacturing creates structural risk, while distribution runs through shipyard-integrated procurement channels and third-party technical managers in Singapore and Dubai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine propulsion sits in early-cycle expansion as methanol bunkering infrastructure buildout in Rotterdam, Singapore, and Shanghai de-risks first-mover engine orders ahead of regulatory enforcement curves.
For Market Incumbents: Secure captive foundry partnerships in South Korea's Ulsan cluster to defend against capacity constraints that threaten delivery commitments on dual-fuel orders. Deepen backward integration into electronic fuel-injection platform licensing to capture software recurring revenue as mechanical spare-part markets contract. MAN Energy Solutions and Wärtsilä already anchor this model through in-house casting and control-system architectures.
For New Entrants and Emerging Players: Anchor in the 100–500 HP hybrid harbor craft segment where battery-diesel configurations face technician scarcity among incumbent service networks. Scandinavian ferry operators in Oslo Fjord and Danish Belt routes present the most penetrable white-space as port-emission mandates accelerate retrofit demand. A go-to-market angle through shore-charging infrastructure partnerships with port authorities de-risks customer acquisition against established aftermarket networks.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with marine engine divisions that lack standalone scale to fund dual-fuel R&D and IMO certification timelines. Long-term viability over a five-to-ten year window favors foundry-integrated specialists with methanol-ready type approvals already in hand. The signal to watch is ammonia combustion trial results from METI-funded programs in Japan, which would reset competitive positioning if toxicity and NOx emission profiles resolve favorably.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Architecture Certification | IMO Tier III compliance with methanol-ready designs secures residual value in charter-party markets. |
| Foundry Capacity Expansion | Captive crankshaft forging in South Korea's Ulsan cluster insulates against fourteen-month lead time bottlenecks. |
| Electronic Control Platform Licensing | Software-defined engine management with real-time cylinder-pressure feedback displaces mechanical aftermarket revenue. |
| Shore-Charging Infrastructure Partnership | Port authority collaboration in Los Angeles and Hamburg enables zero-emission harbor craft pilot programs. |
| Ammonia Combustion R&D Investment | METI Green Innovation Fund trials in Japan address unresolved N2O emission profiles for next-generation fuel pathways. |
Methodological Framework
A spread of perspectives from shipyard procurement directors, engine maker product strategy leads, classification society surveyors, and third-party technical managers converged on the working assumptions that frame this analysis. Primary field engagement combined with secondary validation from Lloyd's Register type-approval databases, DNV vessel statistics, IMO regulatory filings, and customs trade records established demand and supply parameters. Bottom-up vessel orderbook analysis and top-down fleet composition modeling triangulated volume estimates across the projection horizon.
Segmentation dimensions modeled include engine architecture, power rating tier, vessel application, and installation type, with fuel pathway readiness as an industry-specific overlay. CAGRs were derived from regression analysis against historical replacement cycles, regulatory deadline impacts, and bunkering infrastructure deployment curves. Forecast inputs incorporated foundry capacity utilization rates, dual-fuel technician training pipeline data, and port authority emission mandate timelines.
Material uncertainties — commodity price volatility in steel and nickel alloys, ammonia combustion toxicity resolution, and methanol bunkering infrastructure delays — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement consistency and shipowner capital allocation priorities. Revision becomes warranted when IMO carbon intensity indicator thresholds trigger accelerated scrappage beyond baseline replacement rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Marine Communication Market
Marine
Marine Dynamic Positioning System Market
Marine
Marine Fender Systems Market
Marine
Ship Heat Exchanger Market
Marine
Ship Rudders Market
Marine
Marine Fasteners Market
Marine
Electric Boat and Ship Market
Marine
Controllable Pitch Marine Propeller Market
Marine
Commercial Hovercraft Market
Marine
Rescue Boats Market
Marine
Recreational Vessel Battery Market
Marine
Yacht Painting and Maintenance Market
Marine
Ballast Water Management Market
Marine
Asia-Pacific Electric Boat Market
Marine
Global Discount-Marine Trenchers Market
Marine
Integrated Bridge System for Ships Market