
 Integrated Bridge System for Ships Market | 2026-2036
Integrated Bridge System for Ships Market Size, Share, and Industry Trends Forecast 2026-2036
Integrated Bridge System for Ships Market Foresight
Aftermarket service revenue for integrated bridge systems is tilting toward predictive maintenance and remote diagnostics contracts. Wärtsilä leverages its extensive installed base across LNG carriers to anchor recurring service income. Kongsberg Gruppen competes through deep specialization in dynamic positioning integration within bridge suites. Raytheon Anschütz sustains its North Sea and Baltic presence with sensor calibration and software upgrade programs.
An integrated bridge system for ships consolidates navigation, communication, and vessel control functions into a unified workstation architecture, typically incorporating multiple redundant sensor inputs, electronic chart display and information systems, and autopilot interfaces to reduce operator workload and collision risk. Radar systems and sensor fusion technology command the largest current revenue pools, while cloud-based solutions and hybrid deployment models represent the fastest-expanding segments as fleet operators seek shore-side fleet management integration. Software algorithms for autonomous navigation assistance are emerging as a distinct margin concentration point within the technology stack.
The International Maritime Organization's performance standards for navigation equipment, the IEC 61924 series for integrated navigation systems, and flag-state requirements from Lloyd's Register and DNV shape product certification timelines and retrofit obligations across the installed base. The US Coast Guard and Japan's ClassNK enforce additional regional testing protocols for bridge system redundancy that lengthen vendor qualification cycles. Stakeholders must weigh capital allocation between next-generation sensor fusion development and service infrastructure buildout as regulatory compliance windows compress.
Market Dynamics
Sensor fusion architectures are compressing hardware footprints across commercial fleets, forcing bridge system vendors to recalibrate R&D allocation toward software-defined navigation stacks.
Growth Catalysts
- IMO Performance Standards:The International Maritime Organization's mandated navigation equipment upgrades are triggering retrofit waves across aging commercial fleets. Ship operators face compressed compliance windows.
- LNG Carrier Demand:Specialized gas carrier fleets require redundant bridge architectures for hazardous cargo routing. Korean and Japanese shipyards anchor newbuild orders.
- Autonomous Navigation Algorithms:Machine learning-based collision avoidance is displacing rule-based autopilot systems. Deepwater offshore operators pilot these integrations first.
Market Restraints
- Semiconductor Supply Concentration:Marine-grade radar processors depend on specialized foundry capacity concentrated in Taiwan. Geopolitical exposure constrains delivery schedules.
- Copper and Rare Earth Volatility:Magnetron assemblies and sensor housings face input cost swings. Procurement teams lock multiyear contracts to hedge exposure.
- Legacy System Interoperability:IEC 61924 certification requires backward compatibility with decades-old NMEA protocols. Engineering overhead inflates development cycles.
Strategic Opportunities
- Indian Coastal Fleet Modernization:The Sagarmala port development program mandates navigation upgrades for domestic shipping. Local system integrators capture retrofit contracts.
- Shore-Side Fleet Management Convergence:Cloud telemetry from bridge systems enables predictive maintenance. Satellite bandwidth costs are compressing adoption barriers.
- Dynamic Positioning Integration:Offshore wind installation vessels require precision station-keeping. Norwegian and UK North Sea operators specify these configurations.
Industry Challenges
- Marine Cybersecurity Certification:IACS Unified Requirements for cyber-resilience impose new testing protocols. Vendors rebuild software supply chains for traceability.
- Bridge Human Factors Engineering:Alarm fatigue and interface complexity drive regulatory scrutiny. Designers reconcile automation depth with operator situational awareness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Integrated Bridge System for Ships Market |
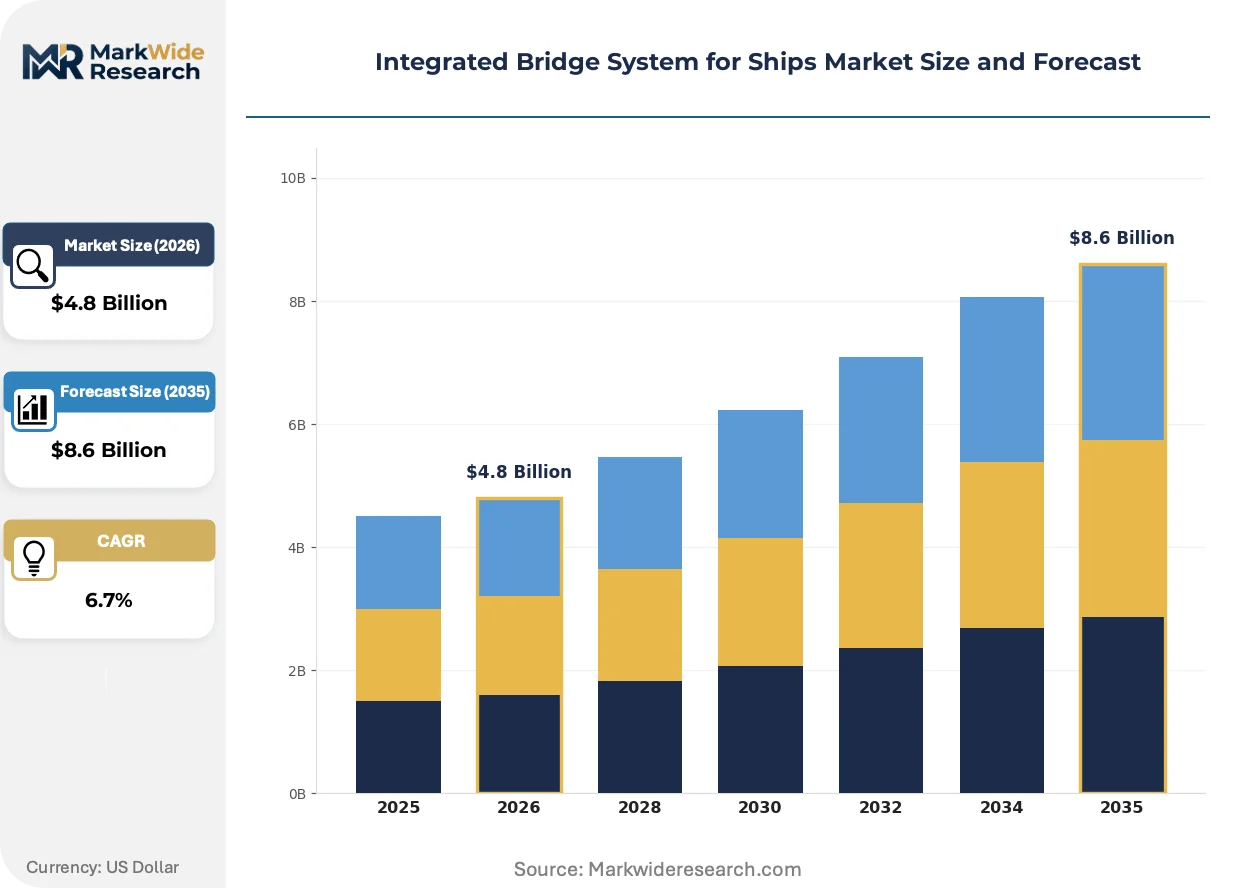
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autopilot Systems, Radar Systems, AIS, VTS End User: Commercial Shipping, Navy, Fishing Industry, Yacht Deployment: Onboard Systems, Cloud-Based Solutions, Hybrid Systems, Integrated Platforms Technology: Software Algorithms, Sensor Fusion, Electronic Chart Display, Connectivity Solutions |
| Companies Covered | Wärtsilä, Kongsberg Gruppen, Northrop Grumman, Raytheon Anschütz, Furuno Electric, Japan Radio Company, Tokyo Keiki, L3Harris Technologies, Alphatron Marine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Integrated Bridge System for Ships Market Shifts & Advancements
Bridge system architectures are pivoting from hardware-centric consoles toward software-defined platforms, compressing refresh cycles and opening service revenue streams.
Multi-function display technology is hybridizing radar, ECDIS, and conning information into single-glass interfaces. Container line operators pilot these configurations on newbuild ultra-large vessels. The consolidation is hybridizing supplier margins away from dedicated hardware boxes toward software licensing.
The IEC 61924-2 standard revision tightens redundancy requirements for integrated navigation systems. Certification timelines extend by six to nine months for non-compliant legacy architectures. European flag states and Lloyd's Register enforce these protocols most stringently, compressing vendor qualification windows.
Charterers now specify bridge system vintage in vessel selection criteria, displacing pure price-based fixture decisions. Major commodity traders audit navigation equipment age during pre-fixture inspections. This behavioral shift concentrates demand for certified modern architectures in the spot tanker and bulker markets.
Integrated Bridge System for Ships Market Segmentation
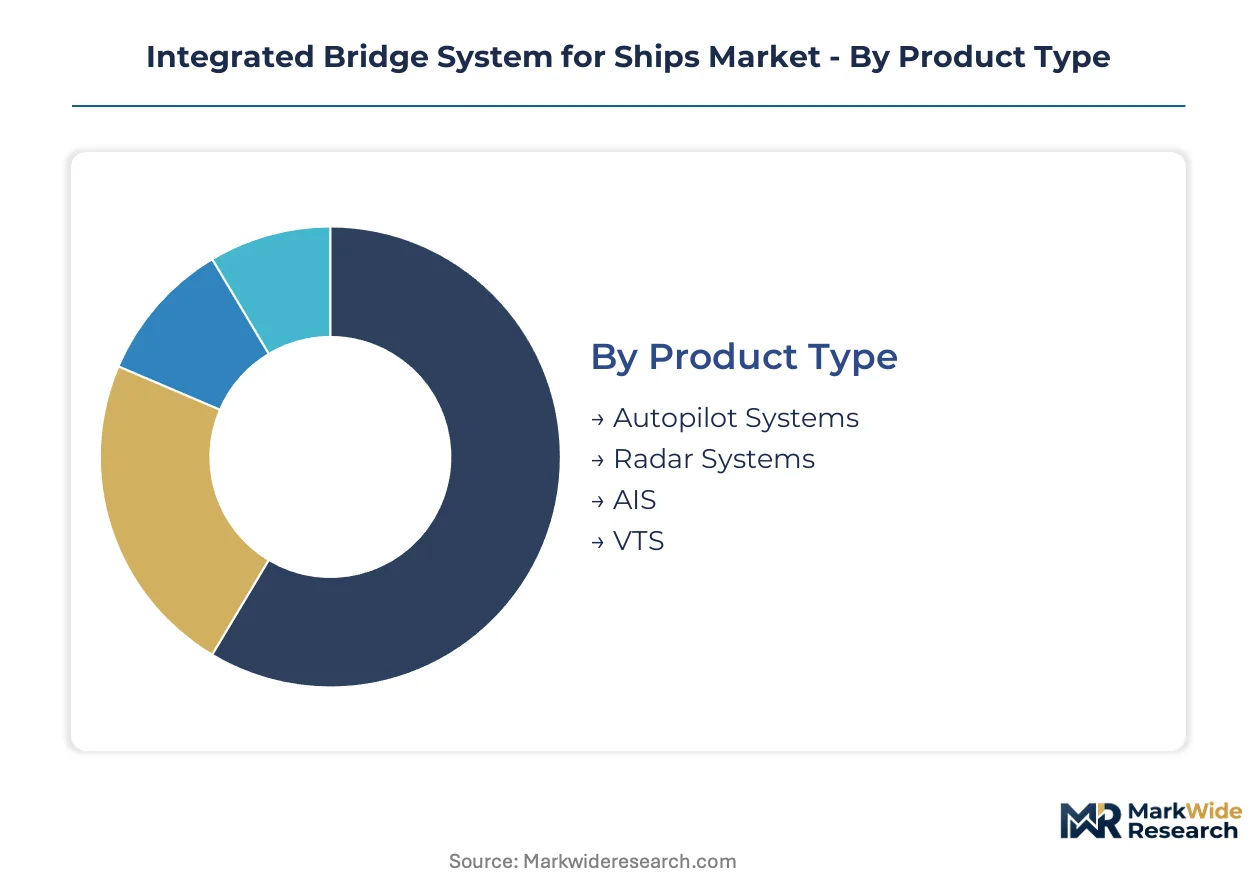
Bridge system vendors calibrate service infrastructure around segment-specific lifecycle patterns. Autopilot retrofits demand rapid-response technical support, while cloud deployments shift revenue toward recurring software maintenance contracts.
Product Type:
After-sales-service intensity varies sharply across hardware-software boundaries, with sensor-heavy categories requiring calibration-intensive maintenance programs.
- Radar Systems:Marine-grade radar processors integrate magnetron assemblies, waveguide networks, and ARPA tracking modules. Korean LNG carriers and Japanese bulk operators anchor replacement demand as IMO performance standards tighten sensor redundancy requirements.
- Autopilot Systems:Rule-based and machine-learning collision avoidance algorithms run on redundant processing architectures. Deepwater offshore fleets in the North Sea pilot autonomous navigation integrations first, compressing vendor qualification cycles.
- AIS:Automatic Identification Systems transmit vessel position, course, and cargo data via VHF transponders. Coastal regulatory mandates drive retrofit waves across aging commercial fleets.
- VTS:Vessel Traffic Services coordinate port approaches through shore-side radar and communication overlays. Harbor authorities in Rotterdam, Singapore, and Shanghai anchor system procurement.
Radar Systems holds the largest share; momentum sits with Autopilot Systems.
End User:
Cost tier differentiation separates capital-intensive newbuild specifications from retrofit-driven installed base monetization.
- Commercial Shipping:Container lines, tanker operators, and bulk carriers specify bridge architectures during newbuild programs at Korean and Japanese shipyards. Charterers now audit navigation equipment vintage during pre-fixture inspections, displacing pure price-based selection.
- Navy:Naval surface combatants require hardened bridge systems with electromagnetic interference shielding and combat system integration. Procurement cycles extend through multi-year defense budgeting processes.
- Fishing Industry:Trawler and longline fleets face compressed compliance windows for ECDIS and AIS mandates. Regional system integrators capture retrofit contracts in coastal clusters.
- Yacht:Superyacht builders specify single-glass bridge interfaces with integrated entertainment and communication systems. Customization depth elevates engineering overhead per hull.
Commercial Shipping dominates volume; steepest expansion trajectory belongs to Navy modernization programs.
Deployment:
Volume concentration tilts toward architectures that balance latency requirements against shore-side connectivity economics.
- Onboard Systems:Traditional bridge architectures process navigation data through local servers with redundant sensor inputs. Aging commercial fleets sustain retrofit demand as IEC 61924-2 compliance deadlines approach.
- Hybrid Systems:Split architectures process time-critical functions locally while routing analytics to shore-side fleet management platforms. Satellite bandwidth cost compression accelerates pilot programs among container line operators.
- Cloud-Based Solutions:Telemetry streams enable predictive maintenance and remote diagnostics across distributed fleets. Cyber-resilience certification under IACS Unified Requirements extends vendor qualification timelines.
- Integrated Platforms:Unified software stacks consolidate radar, ECDIS, conning, and communication into single-glass workstations. Ultra-large vessel newbuilds at Korean shipyards anchor early adoption.
Onboard Systems retains the largest installed base; Hybrid Systems are gaining share fastest.
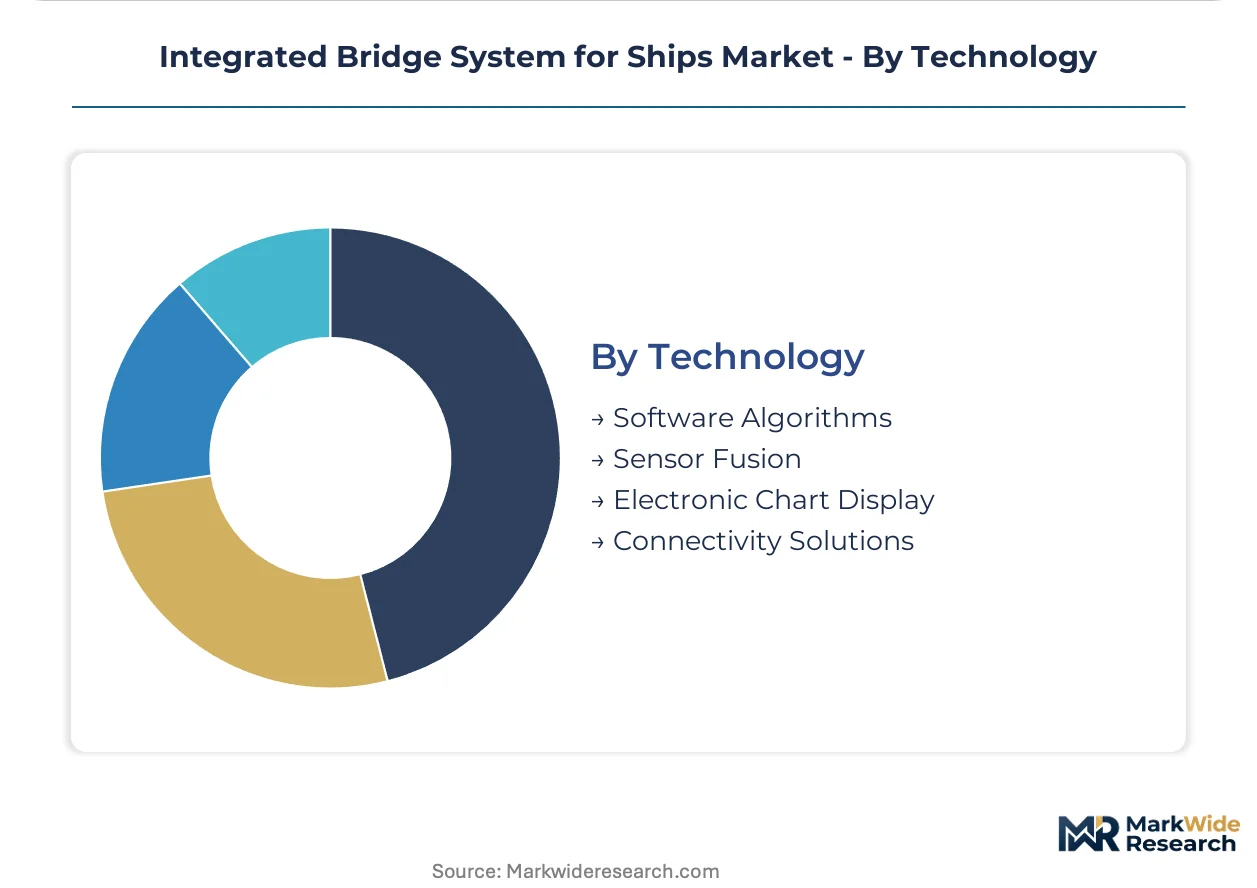
Technology:
Margin concentration tracks toward software layers as hardware commoditization compresses sensor and display pricing.
- Sensor Fusion:Multi-source data integration from radar, AIS, gyrocompass, and GNSS inputs reduces operator workload through unified track processing. Korean and German shipbuilding clusters specify these architectures for newbuild LNG carriers.
- Software Algorithms:Machine learning collision avoidance and route optimization modules license per-vessel or per-fleet. Deepwater offshore operators pilot autonomous navigation assistance first.
- Electronic Chart Display:ECDIS platforms render ENC data with overlay integration for radar and AIS tracks. IMO carriage requirements sustain replacement demand across commercial fleets.
- Connectivity Solutions:Satellite, cellular, and shore-based communication links bridge vessel and fleet operations center data flows. Bandwidth cost curves determine adoption pacing by trade route.
Sensor Fusion commands the largest revenue pool; Software Algorithms show the steepest margin expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in South Korea and Japan demonstrate low price elasticity for certified redundant architectures, while coastal fleet operators in India and fishing vessel owners across Southeast Asia prioritize retrofit economics over premium specifications.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries anchor newbuild LNG carrier orders with integrated bridge specifications. The country's flag administration enforces stringent redundancy protocols for hazardous cargo routing. Busan and Ulsan shipyards specify sensor fusion architectures that compress hardware footprints while satisfying IEC 61924-2 certification timelines.
Japan
ClassNK testing protocols for bridge system redundancy extend vendor qualification cycles for foreign suppliers. The Ministry of Land, Infrastructure, Transport and Tourism mandates ECDIS upgrades for coastal fleets operating in congested traffic separation schemes. Nagoya and Yokohama maritime clusters concentrate electronics manufacturing for radar processors and autopilot modules.
Germany
Lloyd's Register certification requirements for integrated navigation systems shape product development priorities for equipment serving North Sea and Baltic routes. The Federal Maritime and Hydrographic Agency enforces performance standards for vessel traffic services in Hamburg and Bremerhaven approaches. German shipyards in Lower Saxony specify single-glass bridge interfaces for container feeder vessels.
United States
The US Coast Guard imposes additional regional testing protocols for bridge system redundancy that lengthen vendor qualification cycles beyond IMO baselines. Jones Act fleet operators face compressed compliance windows for navigation equipment upgrades. Houston and New Orleans anchor demand for dynamic positioning integration in offshore supply vessels serving Gulf of Mexico energy installations.
India
The Sagarmala port development program mandates navigation upgrades for domestic coastal shipping fleets operating between major harbor complexes. The Directorate General of Shipping enforces AIS and ECDIS carriage requirements for vessels above specified tonnage thresholds. Mumbai and Chennai system integrators capture retrofit contracts as fleet operators seek cost-effective compliance pathways.
Integrated Bridge System for Ships Market Competitive Landscape
Full-stack system integrators and specialized sensor manufacturers split the market based on vessel complexity tiers and service infrastructure depth. The vendor base concentrates around three strategic archetypes: conglomerate marine divisions with captive shipyard relationships, dedicated navigation electronics specialists with deep software competencies, and defense contractors leveraging military technology transfer. Consolidation pressure intensifies as sensor fusion architectures commoditize hardware margins and compress refresh cycles. Geographic expansion through local system integrator partnerships and technology licensing for software-defined navigation stacks represent the dominant competitive moves.
Within the full-stack integrator tier, Wärtsilä and Kongsberg Gruppen occupy positions anchored by extensive installed bases across specialized vessel segments. Raytheon Anschütz exemplifies the regional specialist archetype with concentrated presence in North Sea and Baltic markets. Among defense-technology crossovers, Northrop Grumman and L3Harris Technologies represent entities leveraging military navigation and sensor fusion expertise for commercial marine applications. Japanese electronics manufacturers including Furuno Electric and Japan Radio Company sit within the dedicated navigation hardware tier, serving coastal and regional fleet operators with established distribution networks across Asia-Pacific markets.
| Leading Market Players |
|---|
| Wärtsilä |
| Kongsberg Gruppen |
| Northrop Grumman |
| Raytheon Anschütz |
| Furuno Electric |
| Japan Radio Company |
| Tokyo Keiki |
| L3Harris Technologies |
| Alphatron Marine |
| Others |
Supply & Pricing Matrix
Taiwanese foundry capacity for marine-grade radar processors constrains hardware delivery schedules and compresses margin structures for system integrators serving LNG carrier newbuild programs. Shipyards in South Korea and Japan leverage concentrated electronics manufacturing clusters to negotiate volume discounts on sensor fusion modules, while retrofit operators across India and Southeast Asia absorb freight premiums for fragmented component sourcing.
Pricing Analysis
After-sales service contracts for predictive maintenance and remote diagnostics anchor lifetime value capture for bridge system vendors. Pricing stratifies across premium certified-redundant architectures for hazardous cargo fleets, standard IEC 61924-2 compliant configurations for commercial shipping, and economy retrofit packages for coastal operators. Cost compression in hardware tiers stems from sensor commoditization, while software licensing for autonomous navigation modules sustains margin expansion. Charterers auditing equipment vintage during pre-fixture inspections elevate price insensitivity for certified modern systems, whereas fishing fleet operators and regional coastal carriers exhibit acute sensitivity to upfront capital outlay.
Supply Chain Analysis
Supplier-financing facilities extending payment terms to 180 days anchor working capital arrangements for Korean and Japanese shipyards procuring bridge system components. Manufacturing concentration rests on Taiwan for specialized radar processors, South Korea for display and conning module assembly, and Germany for precision sensor calibration equipment. Magnetron assemblies, waveguide networks, and rare-earth sensor housings draw from concentrated upstream suppliers. Single-source vulnerability in semiconductor foundry capacity exposes delivery schedules to geopolitical disruption. Distribution runs through captive shipyard partnerships for newbuild specifications and regional system integrator networks for retrofit installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity in marine cybersecurity certification capabilities and software-defined navigation engineering talent concentrates competitive advantage among vendors with established IACS compliance track records. Bridge system procurement increasingly filters for vendors demonstrating traceable software supply chains and redundant architecture validation.
For Market Incumbents: Harden defensive positions by deepening software algorithm development for autonomous navigation assistance and securing captive sensor fusion manufacturing partnerships in South Korea or Germany. Consolidate service infrastructure around predictive maintenance contracts to offset hardware margin compression from IEC 61924-2 certification delays. Threats from cloud-native entrants with shore-side fleet management platforms demand accelerated hybrid system deployment. For New Entrants and Emerging Players: India's Sagarmala-mandated coastal fleet modernization presents the most penetrable retrofit geography, with Mumbai and Chennai system integrators capturing compliance-driven demand for cost-effective ECDIS and AIS upgrades. Target fishing industry clusters across Southeast Asia with modular, calibration-light bridge configurations. A go-to-market angle anchored by satellite bandwidth cost compression enables predictive maintenance pilots without heavy onboard infrastructure investment. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because IMO-mandated navigation safety standards and flag-state retrofit obligations sustain replacement demand across aging commercial fleets. Acquisition targets should display concentrated installed bases in specialized vessel segments—LNG carriers, offshore wind installation vessels—with recurring service contract attach rates. The signal to watch is charterer adoption of bridge system vintage as a fixture selection criterion, which would accelerate spot market concentration toward certified modern architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Navigation Stack Development | Machine learning collision avoidance modules displace rule-based autopilot systems in North Sea offshore fleets. |
| Marine Cybersecurity Certification Investment | IACS Unified Requirements for cyber-resilience extend vendor qualification timelines and rebuild software supply chains. |
| Hybrid Deployment Model Pilot Programs | Satellite bandwidth cost compression enables shore-side fleet management integration for container line operators. |
| Regional System Integrator Partnership Expansion | Local retrofit capture in India and Southeast Asia accelerates compliance-driven demand absorption. |
| Dynamic Positioning Integration Specialization | Offshore wind installation vessels in Norwegian and UK North Sea markets specify precision station-keeping configurations. |
Research Methodology
Operator-level perspectives from bridge system engineering directors, fleet technical managers at container lines and tanker operators, shipyard procurement leads in South Korea and Japan, and maritime regulatory compliance officers anchored the qualitative base. Secondary validation drew from IMO performance standard documentation, IEC 61924 series certification records, Lloyd's Register and DNV type approval databases, and flag-state carriage requirement filings. Bottom-up vessel fleet analysis triangulated against top-down market sizing from equipment manufacturer revenue disclosures.
Scenario-bracketing around regulatory compliance deadline shifts and semiconductor supply disruption probabilities shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end user category, deployment architecture, and technology layer, with regional adoption patterns calibrated by shipbuilding cluster concentration. CAGRs derived from installed base replacement cycles, newbuild order pipelines, and retrofit obligation timelines. Forecast inputs incorporated satellite bandwidth cost curves and autonomous navigation algorithm maturity assessments.
Practitioners should monitor IEC 61924-2 revision implementation pace, Taiwan foundry capacity utilization, and charterer audit protocol adoption for early signals of demand inflection. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and shipyard delivery schedule realization. Macroeconomic deviation in commercial shipping freight rates, unanticipated cybersecurity certification delays, or breakthrough autonomous navigation regulatory approval would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Marine Trenchers Market
Marine
Autonomous Ships Market
Marine
Dynamic Positioning System Market
Marine
Global Maritime Information Market
Marine
Marine LED Lights Market
Marine
Marine Interiors Market
Marine
Marine Pipes Market
Marine
Marine Dynamic Positioning System Market
Marine
GCC ROV Market
Marine
Rescue Boats Market
Marine
Shipbuilding Market
Marine
Marine Propeller Market
Marine
Hydrofoil Market
Marine
Marine Suspension Seat Bases Market
Marine
Azimuth Thrusters Market
Marine
Marine Winch Motors Market