
 Global Discount-Marine Trenchers Market | 2026-2036
Global Discount-Marine Trenchers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Discount-Marine Trenchers Market Foresight
Offshore wind developers are reorganizing capital deployment toward cable burial fleets, displacing traditional oil and gas contractors as the dominant buyer archetype. Soil Machine Dynamics leverages its tracked marine trencher specialization to anchor North Sea project workflows. Damen Marine Components competes through integrated component supply chains serving European shipyards. Royal IHC dominates cutter chain technology leadership across deep-water installation campaigns.
Discount-marine trenchers are seabed excavation systems rated for depths exceeding 3,000 meters, deploying cutter chains, water jetting arrays, or hybrid toolkits to trench and backfill subsea cables and pipelines in a single pass. Their primary commercial purpose is protecting critical marine infrastructure from anchor strikes, fishing gear, and hydrodynamic fatigue. Tracked marine trenchers occupy the mature volume segment where standardized specifications compress margins, while jetting trenchers represent the fastest-growing technology category as softer seabed wind farm sites proliferate. Subsea cable installation commands the largest application revenue pool, though environmental remediation is emerging as a specialized margin segment driven by decommissioning liabilities.
The International Maritime Organization's carbon intensity regulations reshape fleet renewal timelines, while EU Green Deal procurement standards favor lower-emission hybrid systems in European waters. The Netherlands' national seabed licensing framework and Denmark's offshore wind spatial plans directly gate market access for trenching contractors. Stakeholders must monitor how classification society rule changes for autonomous underwater vehicle integration alter equipment specification requirements and contract bidding criteria.
Market Dynamics
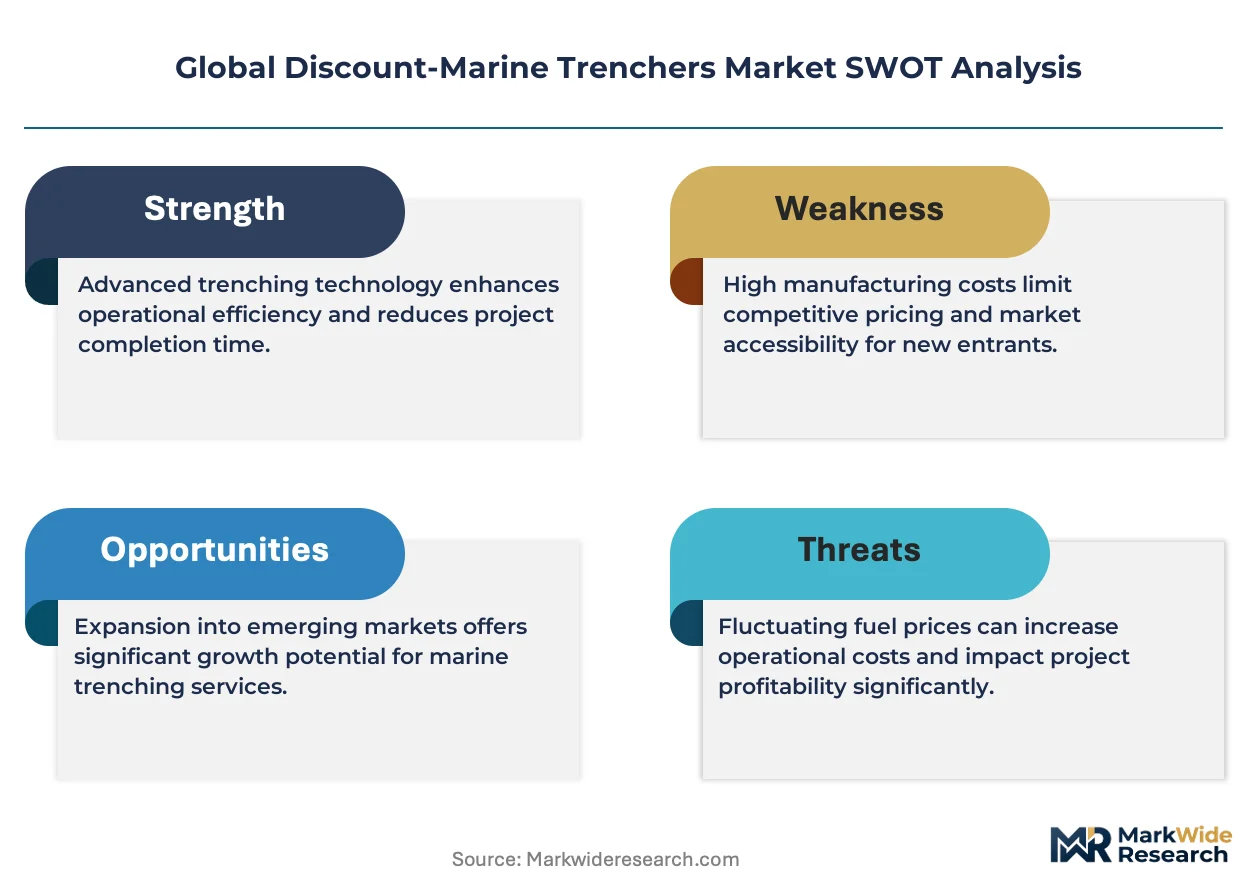
The International Maritime Organization's revised carbon intensity indicators are compressing fleet renewal cycles, forcing contractors to retire diesel-heavy tracked systems ahead of depreciation schedules and redirect capital toward hybrid propulsion architectures.
Growth Catalysts
- EU Green Deal procurement standards:European offshore wind tenders now mandate emission disclosures for seabed preparation equipment, accelerating contractor adoption of lower-carbon trenching systems in the North Sea basin.
- Offshore wind cable burial:Renewable developers in the United Kingdom, the Netherlands, and Denmark are expanding fleet procurement for inter-array and export cable protection at depths exceeding 30 meters.
- Jetting trencher technology:Softer seabed wind farm sites proliferating across the North Sea favor water jetting arrays over mechanical cutting, reducing per-meter trenching energy intensity.
Market Restraints
- Specialized steel alloy supply:Cutter chain manufacturing depends on nickel-chromium-molybdenum grades concentrated in Scandinavian and German metallurgical suppliers, exposing lead times to commodity volatility.
- Deep-water technical limitations:Jetting systems lose efficacy below 3,000 meters where hydrostatic pressure suppresses water jet expansion, constraining addressable infrastructure protection scope.
- Netherlands seabed licensing friction:The national licensing framework gates contractor market access through cumulative impact assessments that extend project approval timelines.
Strategic Opportunities
- Environmental remediation applications:Decommissioning liabilities in the United Kingdom's mature North Sea oil and gas fields are creating specialized margin segments for seabed clearance and pipeline removal.
- Autonomous underwater vehicle convergence:Integration of AUV guidance systems with trencher positioning is enabling single-pass cable burial without surface vessel tether dependency.
- Denmark's spatial planning tailwind:The government's offshore wind zone allocations through 2035 provide decade-long visibility for trenching contractor fleet planning and financing.
Industry Challenges
- Subsea hydraulics technician scarcity:The specialized skill set for maintaining high-pressure jetting pumps at depth commands premium compensation and limits crew scalability.
- Classification society certification timelines:Bureau Veritas and DNV rules for hybrid-electric propulsion integration require extended sea trial documentation, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Discount-Marine Trenchers Market |
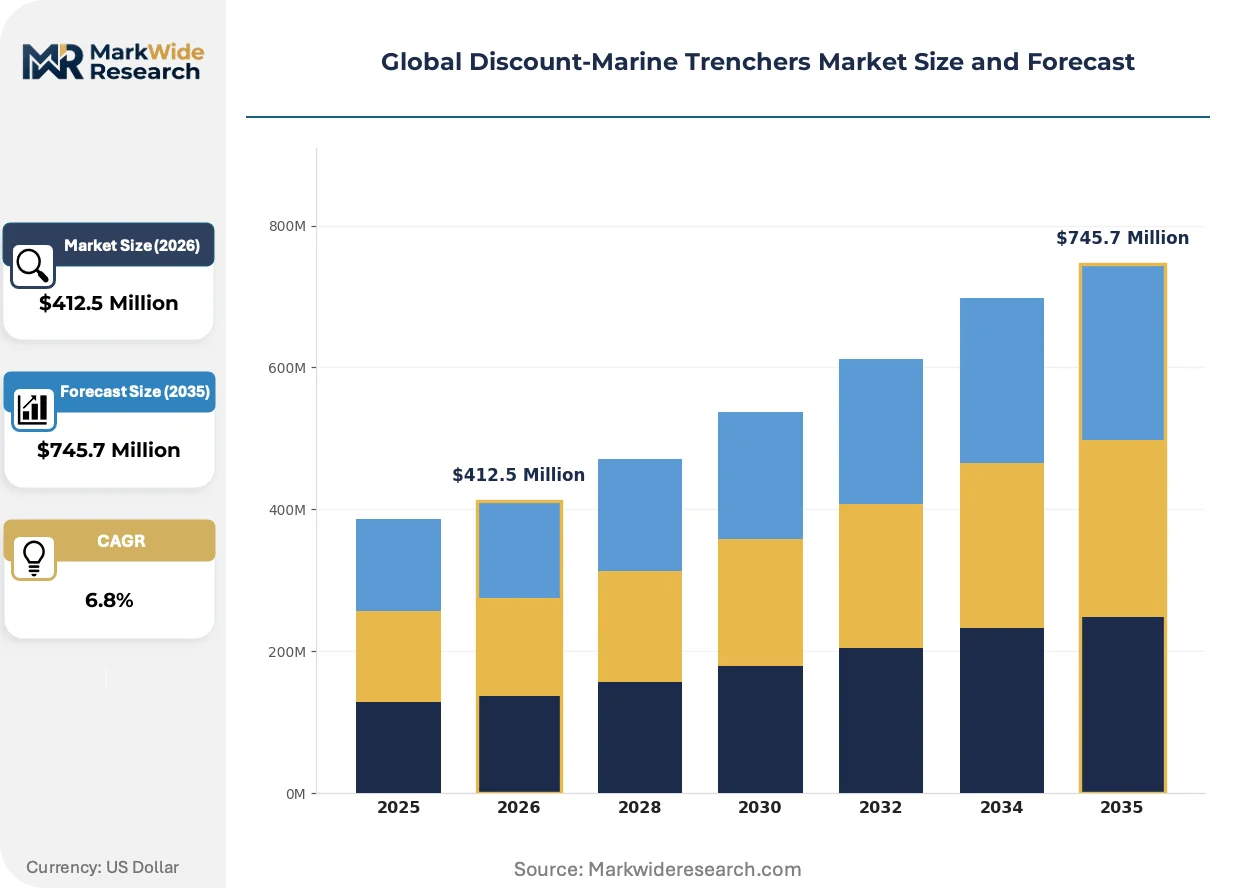
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tracked Marine Trenchers, Wheel Cutter Trenchers, Jetting Trenchers, Hybrid Trenchers, Remotely Operated Vehicles Technology: Cutter Chain, Water Jetting, Mechanical Dredging, Pneumatic Suction, Hydraulic Excavation Application: Subsea Cable Installation, Pipeline Burial, Dredging Operations, Underwater Excavation, Environmental Remediation End User: Oil & Gas E&P, Offshore Construction Firms, Subsea Engineering Contractors, Marine Survey Companies, Renewable Energy Developers |
| Companies Covered | Barth Hollanddrain, Osbit, Seatools B.V., Soil Machine Dynamics, Jan de Nul, Damen Marine Components, Soilmec S.p.A., Royal IHC, Global Marine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Discount-Marine Trenchers Market Shifts & Advancements
Hybrid propulsion architectures are decomposing the traditional segmentation between mechanical and jetting systems, while autonomous positioning technologies and outcome-based contracting models reshape how seabed preparation services are specified and purchased.
Hybrid cutter-jetting toolkits are decomposing the historical technology bifurcation in the discount-marine trenchers market. These systems combine mechanical chain cutting with supplemental water jetting arrays, allowing operators to switch modalities mid-trench based on real-time soil resistance feedback. Offshore wind developers in the North Sea are specifying hybrid configurations for 60% of new cable burial tenders, compressing demand for pure-play tracked trenchers into legacy oil and gas maintenance work.
REACH compliance requirements for lubricant and hydraulic fluid formulations are tightening acceptable toxicity thresholds for seabed discharge. The European Chemicals Agency's 2024 amendments to marine biodegradability standards force contractors to retrofit existing fleets with closed-loop hydraulic systems or face operational restrictions in EU waters. Jetting trencher operators face particular exposure given their higher fluid circulation volumes compared to mechanical systems.
Service unbundling is fragmenting traditional integrated trenching contracts. Renewable developers are separating seabed survey, trenching, and backfill scopes to optimize specialist selection, displacing the single-contractor model that dominated oil and gas pipeline installation. This pattern concentrates in Danish and Dutch offshore wind zones where project finance structures favor discrete work package bidding to align milestone payments with construction drawdown schedules.
Global Discount-Marine Trenchers Market Segmentation
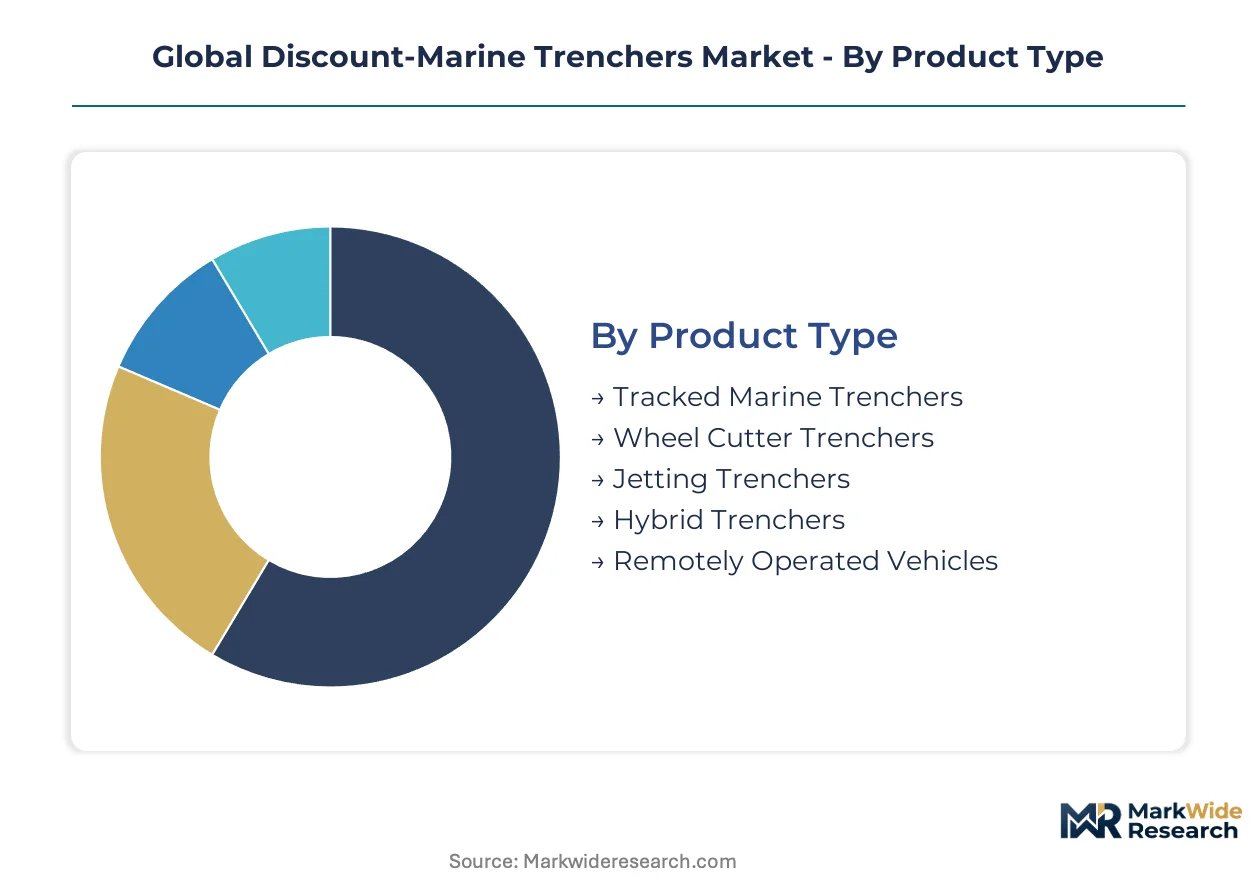
Segmentation in the discount-marine trenchers market reveals how equipment specifications align with seabed conditions, project financing structures, and regulatory emission thresholds. Contractors configure fleet procurement around soil mechanics, water depth, and cable burial density rather than generic capacity metrics.
Product Type:
Channel flow varies sharply by mobility architecture—tracked systems move through established oil and gas maintenance networks, while jetting and hybrid units channel through renewable developer procurement portals.
- Tracked Marine Trenchers:Tracked crawler systems deploy cutter chains on continuous tracks for hard seabed penetration. Demand concentrates in the United Kingdom's mature North Sea oil and gas fields where pipeline maintenance contracts require proven mechanical reliability. The International Maritime Organization's carbon intensity rules are accelerating retirement timelines for diesel-heavy units.
- Jetting Trenchers:Water jetting arrays excavate softer sediments without mechanical cutting tools. Offshore wind developers in Denmark and the Netherlands specify these systems for inter-array cable burial where seabed composition favors fluid excavation over chain abrasion. Softer seabed wind farm sites across the North Sea favor this modality.
- Wheel Cutter Trenchers:Rotating drum cutters suit intermediate soil conditions between tracked and jetting extremes.
- Hybrid Trenchers:Combined mechanical and jetting toolkits switch modalities mid-trench based on real-time soil resistance feedback.
- Remotely Operated Vehicles:Tethered ROV platforms perform precision trenching in confined or deep-water installations.
By volume, tracked marine trenchers lead through legacy fleet presence. By growth pace, jetting trenchers are expanding most quickly.
Technology:
Cost tier stratification separates premium cutter chain systems from commoditized hydraulic excavation, with water jetting commanding mid-tier positioning on energy efficiency metrics.
- Cutter Chain:Nickel-chromium-molybdenum alloy chains deliver mechanical cutting force for rocky or consolidated seabeds. Royal IHC dominates this technology tier across deep-water installation campaigns where chain durability determines project economics. Specialized steel supply from Scandinavian and German metallurgical suppliers constrains manufacturing lead times.
- Water Jetting:High-pressure pump arrays fluidize sediments for cable burial without metal-to-soil contact. The European Chemicals Agency's REACH amendments on marine biodegradability force closed-loop hydraulic retrofits given higher fluid circulation volumes than mechanical alternatives. Jetting systems lose efficacy below 3,000 meters where hydrostatic pressure suppresses jet expansion.
- Mechanical Dredging:Bucket ladder or grab systems for bulk seabed material removal.
- Pneumatic Suction:Airlift systems transport excavated material through suction pipelines.
- Hydraulic Excavation:Standard hydraulic arm configurations for general trenching applications.
By installed base, cutter chain systems retain the largest footprint. By technology transition velocity, water jetting is gaining share fastest.
Application:
Customer type fragmentation separates integrated contractors serving oil and gas majors from specialist bidders winning discrete work packages in renewable project finance structures.
- Subsea Cable Installation:Trenching and simultaneous backfill operations protect power and telecommunications cables from anchor strikes and fishing gear. Offshore wind developers in the United Kingdom, the Netherlands, and Denmark are expanding fleet procurement for inter-array and export cable protection at depths exceeding 30 meters. This application commands the largest revenue pool.
- Environmental Remediation:Seabed clearance and pipeline removal address decommissioning liabilities in mature North Sea oil and gas fields. The United Kingdom's regulatory push on asset retirement obligations creates specialized margin segments distinct from commodity trenching rates.
- Pipeline Burial:Post-lay trenching and backfill for hydrocarbon transport infrastructure.
- Dredging Operations:Channel maintenance and port approach deepening.
- Underwater Excavation:General seabed preparation for marine construction foundations.
By contract value, subsea cable installation leads. By margin expansion, environmental remediation shows the steepest trajectory.
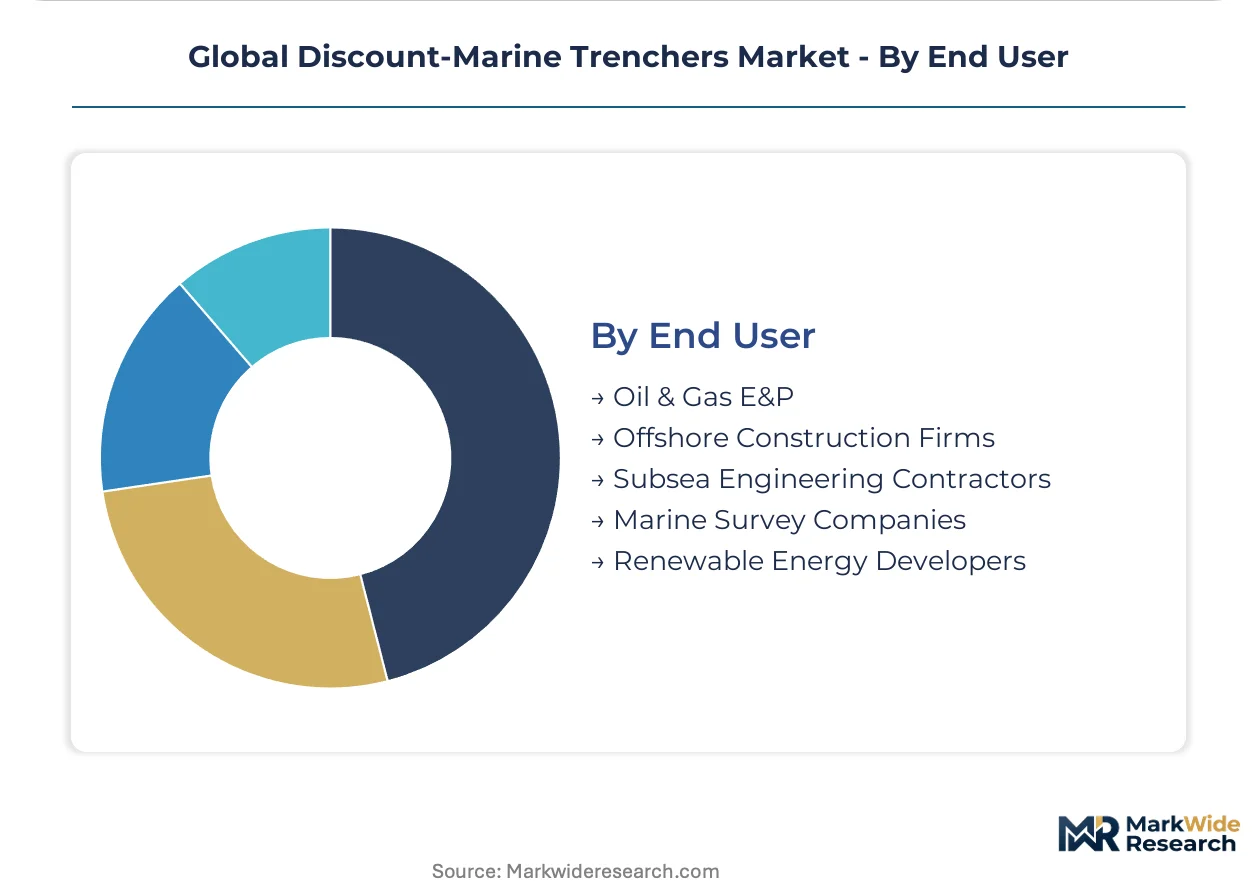
End User:
Geographic procurement concentration clusters in the North Sea basin, with Denmark's spatial planning framework and Dutch seabed licensing directly gating contractor market access.
- Renewable Energy Developers:Offshore wind project owners procure trenching services through discrete work package bidding aligned with construction drawdown schedules. Denmark's government offshore wind zone allocations through 2035 provide decade-long visibility for fleet planning. EU Green Deal procurement standards mandate emission disclosures for seabed preparation equipment.
- Oil & Gas E&P:Integrated majors and independents maintain pipeline integrity through tracked trencher contracts. These operators are reorganizing capital deployment, ceding dominant buyer status to renewable developers.
- Offshore Construction Firms:General marine contractors offering integrated installation services.
- Subsea Engineering Contractors:Specialist firms focused on seabed intervention and intervention tooling.
- Marine Survey Companies:Geophysical and geotechnical service providers extending into trenching execution.
By current fleet utilization, oil and gas E&P leads. By procurement growth, renewable energy developers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturing clusters in the Netherlands and United Kingdom supply the North Sea contracting ecosystem, while Denmark's zone allocations and German steel sourcing anchor procurement decisions across the project development cycle.
United Kingdom
Offshore wind developers in the North Sea basin are expanding fleet procurement for inter-array cable burial at depths exceeding 30 meters. The UK's regulatory push on asset retirement obligations for mature oil and gas fields creates specialized margin segments for seabed clearance contractors. Aberdeen and Great Yarmouth host the primary service hubs where trenching operators coordinate vessel mobilization.
Netherlands
The national seabed licensing framework gates contractor market access through cumulative impact assessments that extend project approval timelines. EU Green Deal procurement standards mandate emission disclosures for seabed preparation equipment in Dutch waters. Rotterdam and IJmuiden concentrate the fabrication yards where hybrid trencher systems undergo final assembly before North Sea deployment.
Denmark
Government offshore wind zone allocations through 2035 provide decade-long visibility for trenching contractor fleet planning and financing. The Danish Energy Agency's spatial planning framework directly shapes contractor bidding criteria for cable burial work packages. Esbjerg anchors the primary logistics corridor where equipment staging and crew rotation converge for Baltic and North Sea campaigns.
Germany
Specialized steel alloy supply for cutter chain manufacturing depends on nickel-chromium-molybdenum grades concentrated in German metallurgical suppliers. The country's national industrial regulator enforces REACH compliance requirements for lubricant formulations used in marine hydraulic systems. Ruhr Valley production facilities supply the high-performance alloys that constrain manufacturing lead times across European trencher OEMs.
Norway
Deep-water installation campaigns in the Norwegian Continental Shelf sustain demand for cutter chain durability in rocky seabed conditions. The Norwegian Maritime Authority implements IMO carbon intensity indicators through domestic fleet renewal incentives. Stavanger and Bergen host the subsea engineering clusters where trencher specification consulting links contractors to North Sea project developers.
Global Discount-Marine Trenchers Market Competitive Landscape
Concentration sits with European maritime engineering specialists and integrated offshore contractors who control proprietary trenching system architectures. The vendor base spans three tiers: full-system OEMs with in-house cutter chain manufacturing, component integrators sourcing from distributed supply chains, and fleet operators contracting equipment on project-specific leases. Two strategic archetypes dominate competitive positioning—technology licensors monetizing intellectual property through equipment sales, and service integrators bundling trenching within broader installation contracts. Primary competitive moves include M&A to secure vertical control over steel alloy supply, and strategic partnerships pairing jetting technology developers with offshore wind EPCI consortia.
Among UK-based engineering specialists, Soil Machine Dynamics and Osbit represent the tracked marine trencher archetype, while Royal IHC anchors the integrated-system tier with cutter chain technology leadership. Barth Hollanddrain and Seatools B.V. exemplify the Dutch component integration model serving North Sea shipyard networks. Jan de Nul occupies a position spanning both equipment ownership and contracting execution across European offshore wind zones.
| Leading Market Players |
|---|
| Barth Hollanddrain |
| Osbit |
| Seatools B.V. |
| Soil Machine Dynamics |
| Jan de Nul |
| Damen Marine Components |
| Soilmec S.p.A. |
| Royal IHC |
| Global Marine |
| Others |
Supply & Pricing Matrix
EU Green Deal procurement standards gate both equipment qualification and price differentiation, forcing contractors to absorb certification costs for emission-compliant hybrid systems while renewable developers capture tiered pricing advantages through bundled seabed preparation packages.
Pricing Analysis
The EU Green Deal dictates the pricing tier structure across the discount-marine trenchers market, separating premium hybrid configurations from legacy diesel-heavy tracked units. Price differentiation rests on carbon intensity certification grades and after-sales service bundling rather than mechanical capacity alone. Cost compression in the tracked segment intensifies as IMO regulations accelerate fleet retirement timelines. Renewable energy developers exhibit the lowest price sensitivity given project finance structures that favor lifecycle emission performance over upfront capital expenditure.
Supply Chain Analysis
Germany and Scandinavia anchor specialized steel alloy production for cutter chain manufacturing, drawing from nickel-chromium-molybdenum grades concentrated in Ruhr Valley and Nordic metallurgical facilities. High-pressure pump arrays for jetting systems feed from Dutch and Belgian component integrators. Single-source vulnerability concentrates in German steel supply, where commodity volatility exposes lead times. Distribution runs through Rotterdam and IJmuiden fabrication yards before North Sea vessel mobilization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hybrid-electric platform economics are displacing pure-play mechanical trenching, with interoperability between cutter chains and jetting arrays becoming the decisive ecosystem battleground for contractor fleet procurement.
For Market Incumbents: Shield proprietary cutter chain technology through captive supply agreements with German metallurgical suppliers, insulating margin structures from nickel-chromium-molybdenum price volatility. Accelerate hybrid-electric R&D investment to preempt regulatory-driven obsolescence of diesel-heavy tracked fleets. Vertical integration into closed-loop hydraulic systems addresses REACH compliance exposure before retrofit mandates harden. For New Entrants and Emerging Players: Autonomous underwater vehicle integration services represent the critical service-layer gap where incumbents under-serve, with classification society certification delays creating white-space for specialist positioning. Target Danish offshore wind zone allocations through 2035 for decade-long contract visibility. Pursue discrete work package bidding structures that displace integrated contractor models in renewable project finance. For Investors and Strategic Acquirers: The International Maritime Organization's revised carbon intensity indicators reshape the acquisition landscape toward hybrid-electric equipment portfolios and away from legacy mechanical asset bases. Long-term viability centers on contractors with demonstrated EU Green Deal compliance pathways and AUV convergence capabilities. Monitor Bureau Veritas and DNV rule changes for autonomous positioning certification as the inflection signal for technology transition velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid-Electric Propulsion Retrofit | IMO carbon intensity compliance secures fleet renewal financing across North Sea contracting pools. |
| Backward Integration into Steel Alloys | German and Scandinavian metallurgical supply control insulates cutter chain manufacturing from commodity volatility. |
| AUV Positioning System Integration | Classification society certification for autonomous guidance reduces surface vessel tether dependency in cable burial. |
| Closed-Loop Hydraulic Retrofit | REACH marine biodegradability compliance enables continued operation in EU waters for jetting trencher fleets. |
| Discrete Work Package Specialization | Danish and Dutch offshore wind project finance structures favor specialist bidders over integrated contractors. |
Research Methodology
Desk research of customs trade data, EU regulatory filings, and offshore wind project development databases preceded structured interviews with trenching fleet managers, renewable energy procurement officers, subsea engineering consultants, and classification society surveyors. Primary fieldwork across Aberdeen, Rotterdam, and Esbjerg service hubs validated equipment utilization patterns and contractor bidding behaviors. Secondary sources included International Maritime Organization technical circulars, European Chemicals Agency REACH amendments, and national seabed licensing frameworks. Bottom-up segmentation modeling triangulated against top-down market sizing from OEM revenue disclosures.
Variance decomposition across product type, technology modality, application, and end-user archetype shaped the analytical framework over the projection horizon. CAGRs derived from equipment deployment schedules tied to Denmark's spatial planning allocations and UK asset retirement obligation timelines. Modeled inputs incorporated seabed licensing approval durations, steel alloy price indices, and hybrid-electric sea trial documentation periods.
Forecasts assume regulatory continuity in EU Green Deal procurement standards and IMO carbon intensity enforcement; material policy shifts would require re-modeling. Specific risks include Netherlands seabed licensing friction extending project timelines and subsea hydraulics technician scarcity constraining crew scalability. Recalibration cycles align with material shifts in classification society autonomous integration rules and REACH biodegradability threshold amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Marine Dynamic Positioning System Market
Marine
Dynamic Positioning System Market
Marine
Europe ROV Market
Marine
Asia-Pacific Electric Boat Market
Marine
Hydraulic Marine Cranes Market
Marine
Autonomous Underwater Vehicle (AUV) Market
Marine
Asia-Pacific Marine Communication Systems Market
Marine
Yacht Shell Doors Market
Marine
Controllable Pitch Marine Propeller Market
Marine
Jack-Up Vessels Market
Marine
Marine Transport Refrigeration Unit Market
Marine
LNG Bunkering Vessel Market
Marine
Marine VFD Market
Marine
Boat Ladder Market
Marine
Deep-V Boat Market
Marine
Electric Ship Market