
 MAP Trays Market | 2026-2036
MAP Trays Market Size, Share, and Industry Trends Forecast 2026-2036
MAP Trays Market Analytics
Direct procurement between resin suppliers and food manufacturers is tilting away from traditional distributor networks. Sealed Air Corporation leverages its Cryovac vacuum and MAP systems to anchor integrated tray-film equipment relationships with protein processors. Amcor PLC sustains global film and tray supply through backward integration into resin compounding and recycling streams. Graphic Packaging International competes with fiber-based alternatives, positioning paperboard trays as a circular substitute where plastic bans advance.
Modified atmosphere packaging trays are thermoformed or injection-molded containers engineered to maintain controlled gas compositions—typically elevated carbon dioxide and reduced oxygen—to retard microbial growth and oxidative spoilage in perishable goods. Rigid trays dominate fresh meat and poultry applications due to dimensional stability under vacuum sealing and high-barrier lidding film adhesion; flexible trays are gaining share in portion-controlled seafood and prepared meal kits where lightweighting reduces freight cost. Polypropylene leads material selection for microwaveable and freezer-to-oven formats, while PET captures premium retail segments demanding clarity and post-consumer recycled content compliance.
The FDA governs food contact substance notifications and migration limits for tray polymers in the United States, while the EU's REACH and Packaging and Packaging Waste Regulation impose extended producer responsibility and recycled content thresholds that reshape material specifications. Germany's national packaging regulator, the Zentrale Stelle Verpackungsregister, enforces strict licensing and recycling quota compliance that elevates cost for non-compliant imports. Stakeholders must monitor evolving state-level plastic restrictions in the United States and the European Commission's anticipated mandatory recycled content rates, as these will determine which material platforms and tray formats retain commercial viability.
Market Dynamics
The EU's Packaging and Packaging Waste Regulation is forcing converters to abandon multi-material laminates in favor of mono-material PET and polypropylene tray designs that satisfy mechanical recycling requirements without sacrificing barrier performance.
Growth Catalysts
- Centralized meat processing in Germany:Retail consolidation favors high-volume MAP tray supply contracts with converters capable of just-in-time delivery to automated packaging lines.
- REACH compliance migration:Food contact substance notifications for recycled PET are streamlining approval pathways, accelerating post-consumer content adoption across European protein packaging.
- Microwaveable polypropylene formats:Freezer-to-oven convenience specifications from ready-meal manufacturers are displacing crystallized PET in premium prepared food segments.
Market Restraints
- Resin price volatility:Propylene feedstock exposure creates margin compression for thermoformers lacking backward integration into polymer production.
- Recycling infrastructure gaps:Mechanical sorting limitations for black CPET trays constrain circular economy claims in markets without near-infrared detection upgrades.
- Fiber-based substitution:Graphic Packaging International's paperboard barrier trays capture shelf space where municipal plastic bans restrict conventional polymer formats.
Strategic Opportunities
- Chemical recycling scale-up:Pyrolysis partnerships between resin suppliers and tray converters enable food-grade rPET supply independent of mechanical recycling yield losses.
- Seafood portion-control formats:Flexible MAP trays for meal-kit subscription services address lightweighting requirements that rigid designs cannot satisfy.
- Zentrale Stelle Verpackungsregister licensing:Compliance infrastructure investments create defensive moats against non-EU imports unable to navigate Germany's packaging registry obligations.
Industry Challenges
- Gas barrier engineering:EVOH coextrusion expertise for high-barrier lidding film adhesion remains concentrated among specialized compounders, creating talent scarcity for in-house development.
- Validation timelines:FDA food contact substance notifications for novel mono-material structures extend commercialization cycles beyond protein processor sourcing windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MAP Trays Market |
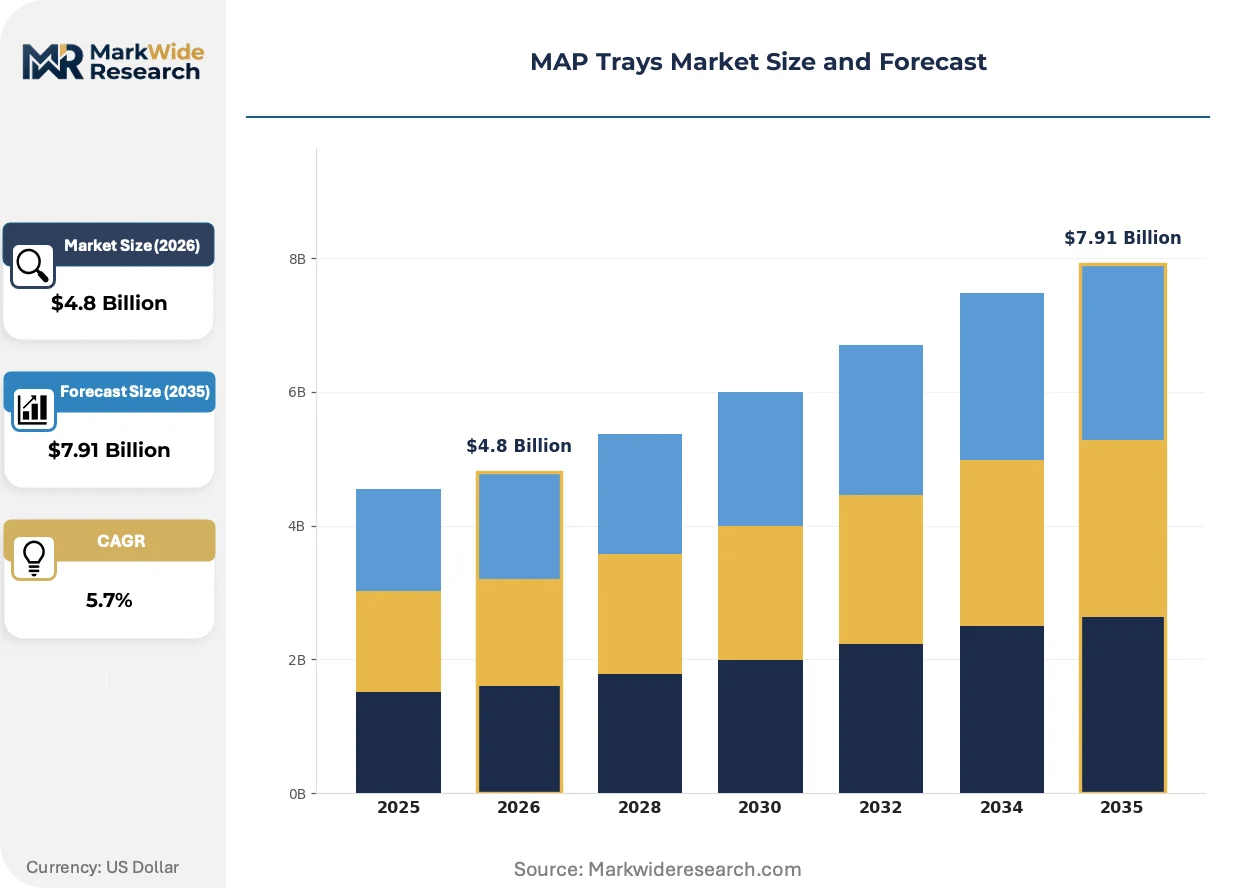
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Trays, Flexible Trays, Blister Packs, Clamshells Material: Polypropylene, Polystyrene, PVC, PET Application: Food Packaging, Medical Supplies, Electronics, Retail End User: Food Manufacturers, Pharmacies, Electronics Firms, Retailers |
| Companies Covered | Sealed Air Corporation, Amcor PLC, Graphic Packaging International, Pactiv LLC, Huhtamaki Oyj, Silgan Plastic Food Containers, Quinn Packaging, Papier-Mettler, ProAmpac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MAP Trays Market Evolving Landscape
Active and intelligent packaging integration is digitizing supply chain traceability while gas scavenging technologies extend shelf life without preservatives, reshaping how converters differentiate tray specifications for protein and prepared food channels.
Smart labels embedded with time-temperature indicators are digitizing cold chain verification for export seafood shipments. Major retailers in Germany and France now mandate electronic freshness monitoring for private-label Atlantic salmon and shellfish categories. This sensor convergence is compressing insurance premiums and reducing rejected-load disputes between processors and distributors.
The EU's anticipated mandatory recycled content thresholds are accelerating mono-material PET tray development ahead of mechanical recycling infrastructure deployment. Thermoformers in Italy and Spain are retooling extrusion lines to process 50% rPET feedstock despite optical sorting capacity constraints. Protein processors with pan-European distribution networks face material specification fragmentation as member states implement divergent interim compliance deadlines.
Direct resin procurement between polymer suppliers and food manufacturers is consolidating distributor intermediaries in high-volume tray markets. Large German meatpackers now negotiate annual propylene contracts with integrated petrochemical producers, bypassing compounder markups for standardized polypropylene specifications. This channel compression is most advanced in fresh poultry packaging, where tray volumes justify dedicated extrusion capacity commitments.
MAP Trays Market Segmentation
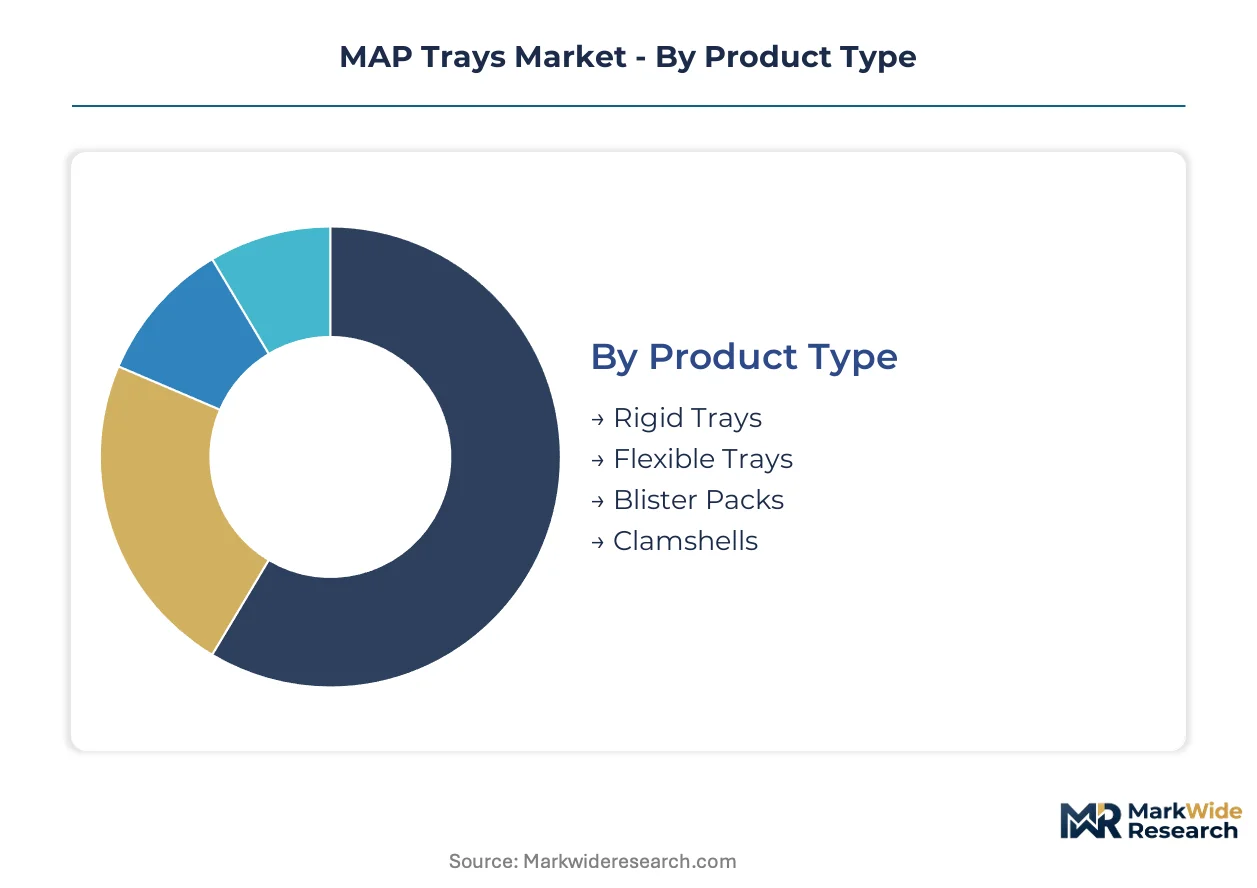
MAP tray specifications diverge sharply across end-use requirements, with protein packaging demanding oxygen barrier precision that medical and electronics applications do not. Material selection and structural format determine recyclability compliance, shelf-life extension, and sealing compatibility with automated packaging lines.
Product Type:
Cycle times vary dramatically: rigid trays for fresh meat turn weekly through retail channels, while medical blister packs sit in inventory for months before hospital consumption.
- Rigid Trays:Thermoformed or injection-molded structures with dimensional stability under vacuum sealing and high-barrier lidding film adhesion. Demand concentrates in German centralized meat processing facilities where automated lines require just-in-time tray supply contracts with precise dimensional tolerances.
- Flexible Trays:Lightweight thermoformed films gaining share in portion-controlled seafood and prepared meal kits where freight cost reduction outweighs structural rigidity needs. Meal-kit subscription services in France and the Netherlands specify these formats for temperature-controlled last-mile delivery optimization.
- Blister Packs:Medical and pharmaceutical applications requiring tamper-evident sealing and moisture barrier properties for tablet and device protection.
- Clamshells:Hinged designs for retail produce and electronics display packaging where consumer visibility and reclosability drive selection.
Rigid trays dominate installed base across European protein packaging. Flexible trays are where expansion concentrates as e-commerce grocery penetration accelerates portion-control specifications.
Material:
Cost tiers separate commodity resins from performance grades, with recycled content compliance premiums reshaping procurement decisions.
- Polypropylene:Microwaveable and freezer-to-oven formats displacing crystallized PET in premium prepared food segments. Ready-meal manufacturers in the United Kingdom specify PP for dual-oven compatibility that PET cannot match.
- PET:Clarity and post-consumer recycled content compliance capturing premium retail segments. Italian thermoformers retool extrusion lines to process 50% rPET feedstock ahead of EU mandatory recycled content thresholds.
- Polystyrene:Cost-sensitive applications in electronics cushioning and disposable food service where regulatory pressure on styrene monomer migration limits food contact growth.
- PVC:Medical blister packs and pharmaceutical applications leveraging established sterilization compatibility, though REACH restrictions constrain expansion in food contact.
PET captures premium positioning and regulatory compliance investment. Polypropylene is climbing the fastest as convenience specifications proliferate across frozen and chilled ready-meals.
Application:
Volume concentration and margin structure diverge: food packaging runs at massive scale with thin margins, while medical applications command price premiums for validation documentation.
- Food Packaging:Fresh proteins, prepared meals, and produce requiring controlled atmosphere maintenance. German retail consolidation favors high-volume supply contracts with converters capable of color-coded tray specifications for private-label differentiation.
- Medical Supplies:Sterile barrier systems for surgical instruments and pharmaceutical devices. FDA food contact substance notification pathways extend commercialization timelines beyond standard procurement cycles.
- Electronics:ESD-sensitive component protection with anti-static additive requirements.
- Retail:General merchandise display and theft-deterrent packaging with lower barrier specifications.
Food packaging dominates installed base. Medical supplies are where expansion concentrates as healthcare supply chain resilience investments accelerate domestic sourcing requirements.
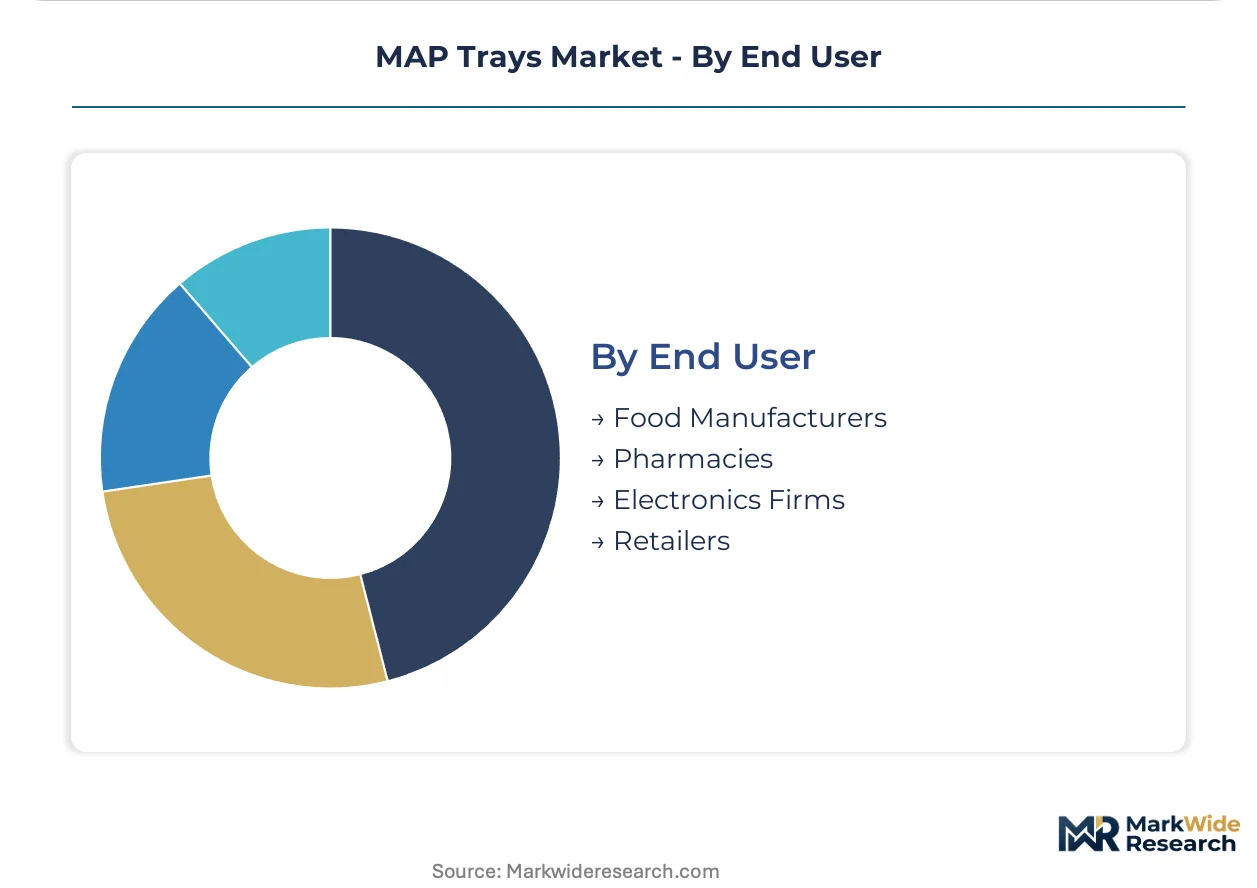
End User:
Procurement sophistication separates integrated manufacturers with direct resin contracts from distributors serving fragmented demand.
- Food Manufacturers:Large German meatpackers negotiate annual propylene contracts with integrated petrochemical producers, bypassing compounder markups. Zentrale Stelle Verpackungsregister licensing requirements elevate compliance costs for non-EU import alternatives.
- Pharmacies:Unit-dose and compliance packaging specifications driven by medication adherence programs.
- Electronics Firms:Cleanroom-compatible formats with ionic contamination controls for semiconductor component shipping.
- Retailers:Private-label packaging specifications consolidating toward mono-material designs for shelf-ready display and recycling stream compatibility.
Food manufacturers dominate installed base. Pharmacies are where expansion concentrates as unit-dose packaging mandates expand across European healthcare systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German converters extract premium pricing for Zentrale Stelle Verpackungsregister-compliant mono-material trays, while US thermoformers face margin compression from fragmented state-level plastic restrictions that lack unified federal standards.
Germany
Centralized meat processing in Lower Saxony and Bavaria drives high-volume MAP tray contracts with just-in-time delivery requirements. The Zentrale Stelle Verpackungsregister enforces strict licensing and recycling quota compliance that elevates costs for non-compliant imports. Thermoformers in the Ruhr industrial cluster retool extrusion lines to process elevated rPET feedstock ahead of EU mandatory recycled content thresholds.
United States
Fresh protein processors in the Midwest negotiate direct propylene contracts with integrated petrochemical producers, bypassing compounder markups. FDA food contact substance notifications for novel mono-material structures extend commercialization timelines beyond standard procurement cycles. Dallas-Fort Worth distribution hubs concentrate tray supply contracts for retail consolidation across the Southern states.
Italy
Thermoformers in Emilia-Romagna retool extrusion lines to process 50% rPET feedstock despite optical sorting capacity constraints. REACH compliance migration for recycled PET food contact notifications streamlines approval pathways. Bologna's packaging machinery cluster anchors mono-material tray development ahead of mechanical recycling infrastructure deployment.
France
Major retailers mandate electronic freshness monitoring for private-label Atlantic salmon and shellfish categories through smart label integration. ANSM and EFSA coordinate on active packaging substance approvals for gas scavenging technologies. Lyon-based converters develop flexible MAP trays for meal-kit subscription services targeting temperature-controlled last-mile delivery optimization.
Spain
Catalan thermoformers advance mono-material PET tray development to satisfy anticipated EU mandatory recycled content thresholds. Protein processors with pan-European distribution networks face material specification fragmentation as member states implement divergent interim compliance deadlines. Barcelona's packaging cluster concentrates microwaveable polypropylene format production for freezer-to-oven ready-meal specifications.
MAP Trays Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying resin, film, and equipment modules. The MAP trays market structures around three archetypes: integrated packaging systems providers bundling tray-film-sealing equipment, material-centric converters with backward integration into resin compounding, and fiber-based substitution specialists positioning paperboard alternatives. Dominant competitive moves include M&A to secure chemical recycling feedstock streams and capacity expansion into high-barrier mono-material extrusion lines.
Among North American packaging conglomerates, Sealed Air Corporation and Amcor PLC exemplify the integrated systems archetype, anchoring equipment-anchored relationships with protein processors. Graphic Packaging International occupies a distinct position within fiber-based substitution, representing paperboard barrier tray development where municipal plastic restrictions constrain conventional polymer formats. These three entities collectively illustrate the strategic divergence between polymer platform dominance and circular material alternatives.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Amcor PLC |
| Graphic Packaging International |
| Pactiv LLC |
| Huhtamaki Oyj |
| Silgan Plastic Food Containers |
| Quinn Packaging |
| Papier-Mettler |
| ProAmpac |
| Others |
Value Network & Pricing Analysis
German resin compounding concentration in the Ruhr industrial cluster anchors margin capture upstream, while downstream thermoformers face compression from just-in-time delivery obligations and rPET feedstock premiums. The Zentrale Stelle Verpackungsregister licensing costs create defensive pricing power for compliant domestic converters against non-EU import competition.
Pricing Analysis
The customization-premium spread separates configured-to-order mono-material tray specifications from standardized polypropylene formats. Three-tier pricing structure across premium, standard, and economy levels reflects barrier performance grades and post-consumer recycled content certification tiers. Pricing pressure stems from propylene feedstock volatility and black CPET tray sorting limitations that constrain circular economy claims. Large German meatpackers exhibit lowest price sensitivity due to direct annual resin contracts, while mid-sized ready-meal manufacturers face acute margin compression from compliance-driven material switches.
Supply Chain Analysis
Supplier-financing facilities from integrated petrochemical producers extend payment terms to large protein processors negotiating direct propylene contracts. Geographic supply concentration centers on Germany, Italy, and Spain for thermoformed tray production, with resin compounding anchored in Belgian and Dutch petrochemical clusters. Raw material dependencies rest on propylene feedstock, rPET flake supply, and EVOH barrier resin. Single-source vulnerability runs through specialized EVOH coextrusion compounders. Distribution runs through automated packaging line integrators serving centralized meat processing facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment-anchored service contracts for tray-film-sealing system maintenance represent a recurring-revenue layer expanding faster than standalone tray hardware sales. Gas scavenging technology integration and smart label subscriptions compound this service-attach opportunity.
For Market Incumbents: Entrench platform dominance by deepening backward integration into pyrolysis chemical recycling partnerships that secure food-grade rPET supply. Add high-barrier mono-material extrusion capacity in the Ruhr cluster to capture Zentrale Stelle Verpackungsregister compliance premiums. Fiber-based substitution from Graphic Packaging International threatens polymer tray shelf space where municipal bans advance. For New Entrants and Emerging Players: Build out flexible MAP tray production for meal-kit subscription services in France and the Netherlands, the most penetrable segment where lightweighting requirements outpace incumbent rigid tray capabilities. Target seafood portion-control formats with temperature-controlled last-mile delivery optimization as the entry wedge. Pursue co-development partnerships with Lyon-based converters lacking flexible format expertise. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed thermoformers in Italy and Spain retooling for 50% rPET feedstock ahead of EU mandatory recycled content thresholds. Five-to-ten year viability hinges on chemical recycling infrastructure deployment pace. Watch for pyrolysis partnership announcements between resin suppliers and tray converters as the inflection signal for food-grade circular feedstock scale.| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Partnership | Pyrolysis alliances between resin suppliers and converters unlock food-grade rPET independent of mechanical yield losses. |
| Mono-Material Extrusion Retooling | Italian and Spanish thermoformers upgrade lines to process 50% rPET ahead of EU compliance deadlines. |
| Smart Label Integration | German and French retailers mandate electronic freshness monitoring for private-label Atlantic salmon categories. |
| Direct Resin Procurement | Large German meatpackers negotiate annual propylene contracts bypassing compounder markups. |
| Fiber-Based Barrier Development | Graphic Packaging International advances paperboard trays where municipal plastic bans constrain polymer formats. |
Research Methodology
The analysis maps rigid tray, flexible tray, and blister pack sub-sectors, each validated through thermoformer operations directors, protein processor procurement leads, retail category buyers, and packaging machinery OEMs. Primary interviews combined with secondary validation from ECHA REACH filings, EU Packaging and Packaging Waste Regulation drafts, Zentrale Stelle Verpackungsregister compliance databases, and SEC 10-K disclosures from listed packaging conglomerates. Bottom-up capacity estimates and top-down demand triangulation cross-check volume assumptions.
Assumption sets held regulatory timeline phasing and resin price corridors fixed while varying e-commerce grocery penetration rates and chemical recycling capacity buildout speeds across the projection horizon. Segmentation dimensions modeled include product type, material platform, application vertical, and end-user procurement sophistication. CAGRs derived from installed base turnover rates and substitution elasticity estimates. Industry-specific inputs incorporated EVOH barrier resin supply constraints and optical sorting infrastructure deployment timelines.
Stress conditions across propylene feedstock volatility, rPET flake availability, and EU recycled content mandate enforcement were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions. Macroeconomic contraction, regulatory timeline acceleration, or breakthrough barrier coating technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Kraft Envelopes Market
Paper & Paperboard Packaging
Middle East Corrugated Packaging Market
Paper & Paperboard Packaging
Desiccant Paper Market
Paper & Paperboard Packaging
White Sack Kraft Paper Market
Paper & Paperboard Packaging
Global Window Cake Box Market
Paper & Paperboard Packaging
Composite Cardboard Tube Packaging Market
Paper & Paperboard Packaging
India Paper Packaging Market
Paper & Paperboard Packaging
Australia Corrugated Board Packaging Market
Paper & Paperboard Packaging
Super Calendered Kraft Papers Market
Paper & Paperboard Packaging
Global Fanfold Corrugated Market
Paper & Paperboard Packaging
Butchers Paper Market
Paper & Paperboard Packaging
Cold Seal Paper Market
Paper & Paperboard Packaging
Beverage Filter Paper Market
Paper & Paperboard Packaging
Indonesia Paper Packaging Market
Paper & Paperboard Packaging
North America Paper Cups Market
Paper & Paperboard Packaging
Paperboard Packaging Market