
 Butchers Paper Market | 2026-2036
Butchers Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Butchers Paper Market Outlook
North American kraft pulp producers is expanding coated and uncoated butchers paper capacity to serve protein packaging and foodservice channels. Georgia-Pacific leverages integrated pulp-to-paper operations across the southeastern United States to sustain cost-advantaged supply. International Paper competes through broad distribution networks and scale in virgin kraft production. WestRock differentiates via recycled-content formulations and food-safe certification depth.
Butchers paper denotes a durable, unbleached or minimally processed kraft paper, typically manufactured from sulfate pulp at basis weights of 30–50 lb/ream, engineered to absorb meat juices while maintaining wet strength during handling and storage. Its primary commercial purpose spans meat wrapping, smoking and aging applications, and foodservice presentation where breathability and moisture control protect product quality. Kraft paper anchors volume demand across food packaging and meat processing end uses, where heavyweight uncoated grades dominate procurement for primal cuts and subprimal breakdown. Greaseproof paper occupies faster-growing niches in artisan butcher and premium foodservice segments, where moisture and fat resistance command price premiums over standard kraft.
The United States FDA governs food-contact substance compliance under 21 CFR, while the EPA regulates pulp and paper effluent discharges through Cluster Rule permits that shape mill-level environmental compliance costs. The EU F-Gas Regulation and REACH framework constrain coating chemistries and fluorinated treatments used in certain greaseproof grades, redirecting formulation investment toward bio-based barriers. Stakeholders must monitor evolving state-level extended producer responsibility laws in California and New York, as these jurisdictions pilot paper packaging fees that would alter cost allocation across the value chain.
Market Dynamics
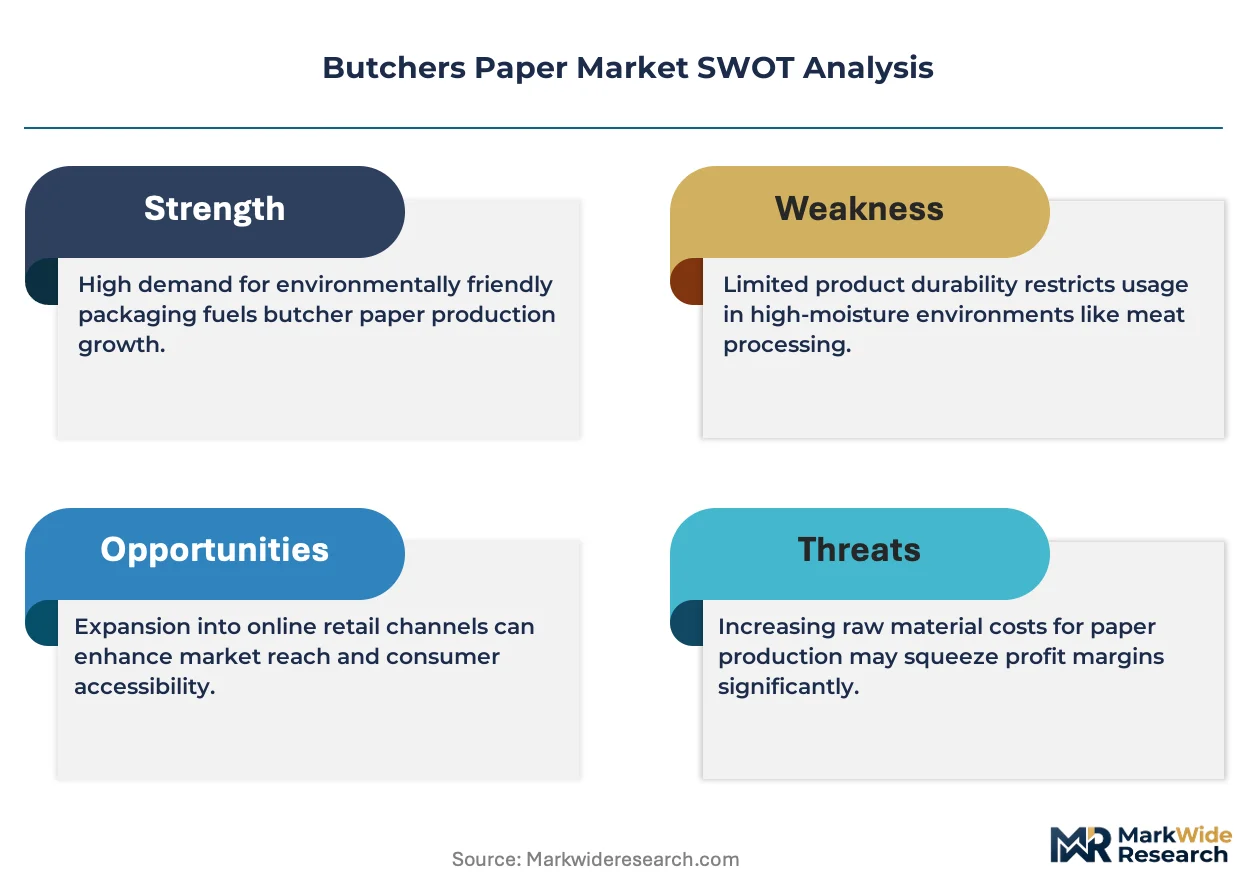
The EU Packaging and Packaging Waste Regulation is forcing mill-level reformulation investments across food-contact paper grades, compressing margins for non-compliant producers while advantaging certified suppliers.
Growth Catalysts
- REACH-compliant barrier coatings:Bio-based alternatives to fluorinated chemistries are unlocking premium positioning in artisan butcher channels across Germany and France.
- US craft barbecue culture:Regional meat processing clusters in Texas and the Carolinas sustain heavyweight uncoated kraft demand for smoking and aging applications.
- California extended producer responsibility pilots:State-level packaging fee structures are accelerating certified-recyclable grade procurement among national foodservice distributors.
Market Restraints
- Softwood pulp price volatility:Sulfate pulp input costs swing with Canadian lumber harvest cycles and energy pricing at Scandinavian mills.
- EU F-Gas Regulation constraints:Fluorinated greaseproof treatments face phase-down timelines, eliminating certain high-performance grades from formulation portfolios.
- Plastic film substitution threat:Vacuum-sealed barrier films retain cost advantages for long-haul protein distribution, limiting butchers paper penetration in export-oriented processing.
Strategic Opportunities
- India FSSAI food-contact compliance:Emerging organized retail and cold-chain expansion create first-mover openings for certified kraft suppliers.
- Direct-to-consumer butcher subscriptions:E-commerce meat delivery channels prize branded, presentation-grade wrapping for unboxing differentiation.
- EU Green Deal bio-economy incentives:Agricultural residue pulp sourcing qualifies for circular economy funding, offsetting capital intensity of non-wood fiber lines.
Industry Challenges
- FDA 21 CFR food-contact substance notification timelines:Novel barrier chemistries face 180-day review cycles that delay product launches and freeze R&D pipelines.
- Wet-strength resin supply concentration:Polyamide-epichlorohydrin additive production clusters in China and Germany create single-source vulnerability for North American mills.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Butchers Paper Market |
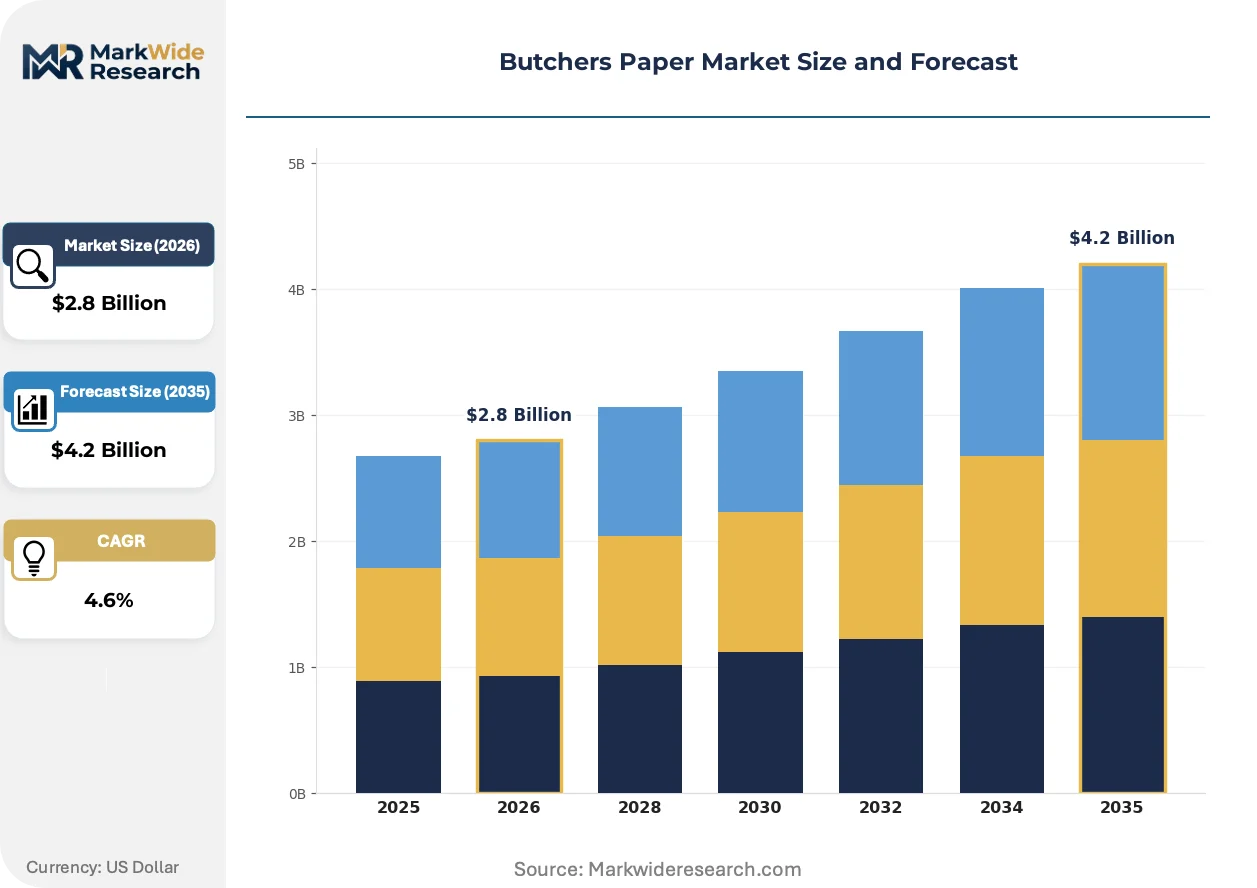
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Greaseproof Paper, Kraft Paper, Parchment Paper, Butcher Paper End Use: Food Packaging, Meat Processing, Artisan Butcher, Foodservice Thickness: Heavyweight, Mediumweight, Lightweight, Extra Heavyweight Coating Type: Uncoated, Wax Coated, Plastic Coated, Others |
| Companies Covered | Georgia-Pacific LLC, International Paper Company, WestRock Company, Mondi Group, Nordic Paper, NIPPON PAPER INDUSTRIES CO., LTD., Oji Paper Company, Canadian Kraft Paper Ltd., Smurfit Kappa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Butchers Paper Market Strategic Shifts
Active reformulation of barrier chemistries and shifting procurement authority from processors to retail compliance departments are compressing traditional specification cycles.
Cellulose nanofibril (CNF) reinforcement is integrating into uncoated kraft substrates to boost wet strength without synthetic additives. Artisan butcher shops in the Pacific Northwest and Nordic countries are piloting these grades for aging-room applications. The technology is integrating moisture management performance previously requiring plastic laminates, enabling premium positioning at standard kraft price points.
REACH authorization requirements for per- and polyfluoroalkyl substances (PFAS) are eliminating legacy greaseproof formulations from EU supply chains. Mill operators face capital decisions on aqueous barrier coating lines versus bio-wax alternatives. German and French protein processors are consolidating procurement around suppliers with ECHA-registered bio-barrier portfolios, squeezing mid-tier competitors.
Retail compliance departments are capturing specification authority from meat processing procurement teams. Grocery chain sustainability scorecards now weight packaging recyclability alongside shelf-life performance. This pattern concentrates most visibly in California and New York, where state-level packaging mandates have elevated certified-recyclable grades to bid-table requirements.
Butchers Paper Market Segmentation
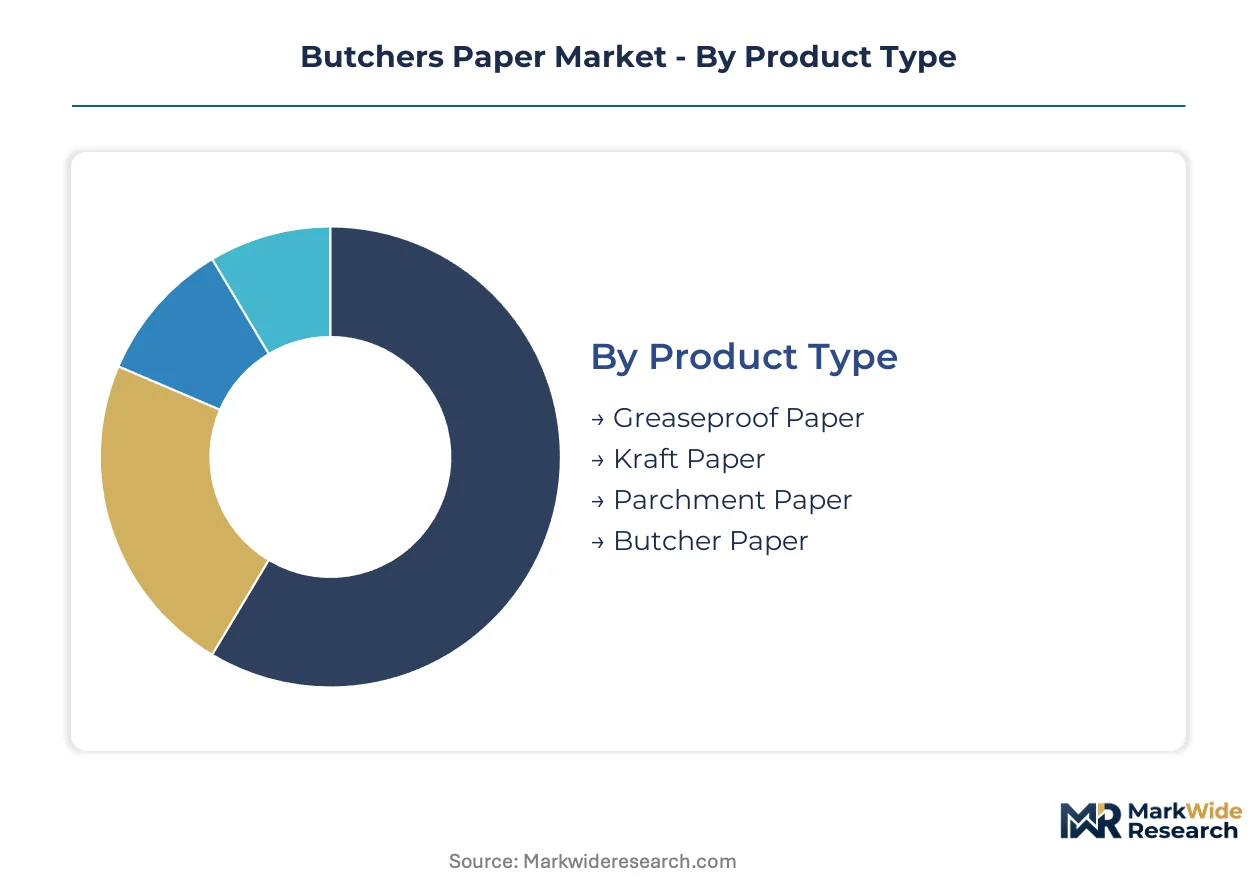
Butchers paper procurement cycles track protein processing equipment upgrades and retail compliance refreshes, creating predictable replacement windows for suppliers. Specification authority has migrated from meat processors to retail sustainability departments, reshaping how each segment competes on certification depth versus functional performance.
Product Type:
Upgrade cycles in artisan butcher equipment and smoking hardware drive replacement demand across paper grades, with coating compatibility and heat resistance dictating switching costs.
- Kraft Paper:Uncoated sulfate pulp at 30–50 lb/ream basis weights delivers breathability for primal cut aging and smoking applications. United States meat processing clusters in Texas and the Carolinas anchor volume procurement for barbecue and aging-room use, where wet-strength performance during extended handling cycles determines supplier selection.
- Greaseproof Paper:Densified pulp with proprietary barrier treatments resists fat penetration for premium charcuterie presentation. German and French artisan butchers are consolidating procurement around REACH-compliant bio-barrier formulations as ECHA phase-down timelines eliminate fluorinated alternatives.
- Parchment Paper:Silicone-treated cellulose provides non-stick surfaces for foodservice wrapping and baking applications.
- Butcher Paper:Branded presentation grades with custom printing serve direct-to-consumer subscription channels seeking unboxing differentiation.
Kraft Paper sits at the top of the volume ranking, with Greaseproof Paper climbing the fastest.
End Use:
Cost tier separation between commodity protein processors and premium foodservice channels creates distinct specification bands, with certification requirements widening the gap.
- Meat Processing:Industrial-scale operations demand high-volume uncoated kraft for primal and subprimal breakdown, where line speed compatibility and roll consistency override premium positioning. United States regional processing clusters sustain heavyweight grade consumption through integrated supply contracts with southeastern pulp producers.
- Artisan Butcher:Small-batch operators prioritize presentation-grade wrapping with moisture management for dry-aging rooms and counter display. Nordic countries and the Pacific Northwest are piloting cellulose nanofibril-reinforced substrates that boost wet strength without synthetic additives.
- Food Packaging:Retail-ready formats require food-safe certification depth for grocery chain sustainability scorecards.
- Foodservice:Restaurant and catering channels balance disposability compliance with branded presentation needs.
Meat Processing commands the largest volume position, while Artisan Butcher demonstrates the steepest expansion trajectory.
Thickness:
Application-driven thickness selection maps directly to handling intensity and moisture exposure duration across protein types.
- Heavyweight:40–50 lb/ream constructions absorb juices during extended smoking and aging cycles without structural failure. United States craft barbecue culture sustains demand for these grades in regional meat processing clusters where pitmasters require breathability combined with wet-strength durability.
- Extra Heavyweight:Above-50 lb/ream specifications serve industrial processors handling bone-in primals with puncture risk.
- Mediumweight:30–40 lb/ream balances cost and performance for standard retail wrapping applications.
- Lightweight:Sub-30 lb/ream grades serve deli counter and short-duration display uses where minimal handling reduces strength requirements.
Heavyweight dominates procurement volume, with Extra Heavyweight gaining share fastest in export-oriented processing.
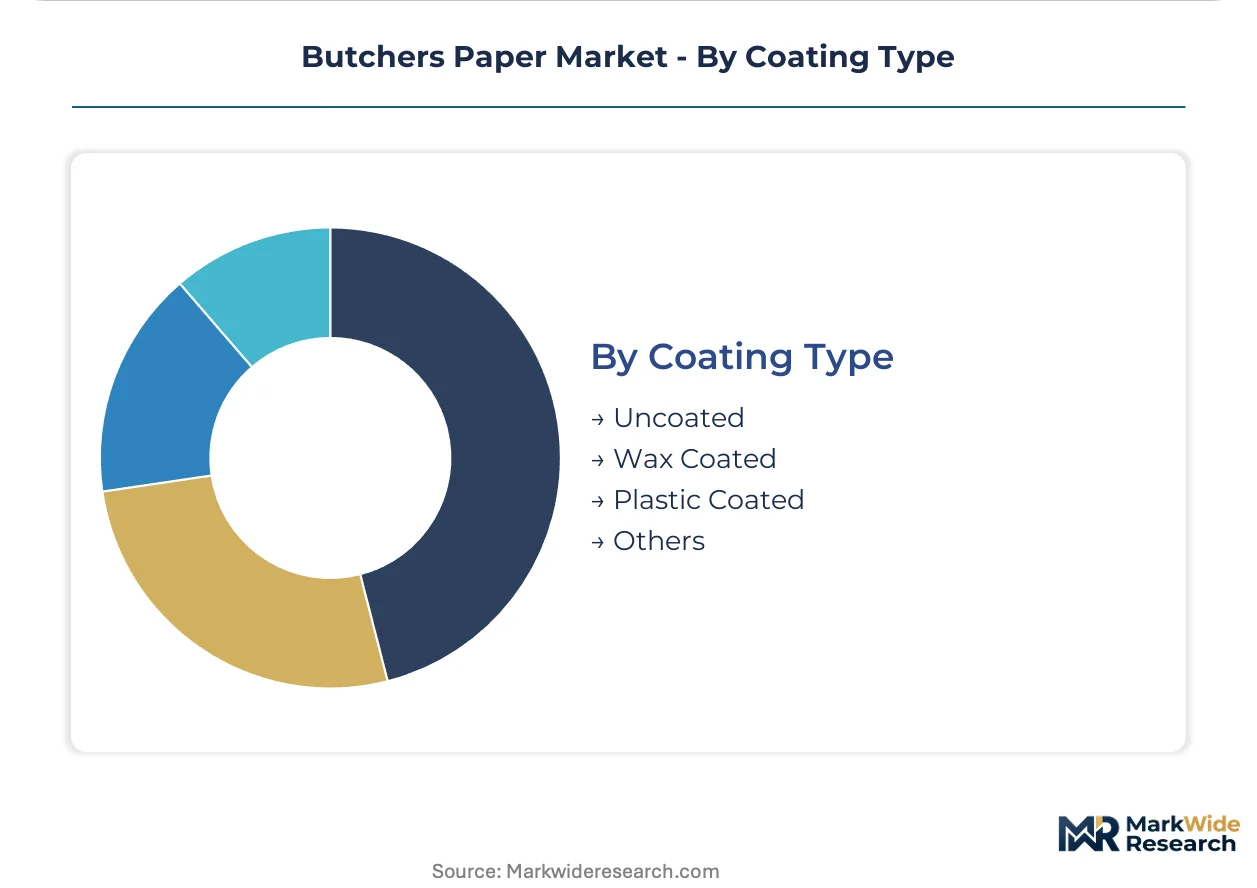
Coating Type:
Margin structures diverge sharply between commodity uncoated grades and barrier-coated premiums, with regulatory compliance costs compressing mid-tier positions.
- Uncoated:Virgin or recycled kraft without surface treatments retains cost advantages for high-volume meat processing and barbecue applications. California and New York state-level packaging mandates have elevated certified-recyclable uncoated grades to bid-table requirements among national foodservice distributors.
- Wax Coated:Bio-based paraffin or vegetable wax barriers provide moisture resistance for artisan presentation without fluorinated chemistries.
- Plastic Coated:Polyethylene laminates face regulatory pressure under EU Packaging and Packaging Waste Regulation recycling targets.
- Others:Aqueous barrier coatings and novel bio-polymers occupy emerging positions as mill operators reformulate for REACH compliance.
Uncoated leads volume rankings, with Wax Coated expanding most quickly as processors abandon fluorinated alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between jurisdictions is redirecting capital toward mills with pre-certified compliance infrastructure, compressing margins for producers caught in reformulation lag.
United States
Regional meat processing clusters in Texas and the Carolinas sustain heavyweight uncoated kraft consumption for craft barbecue and aging applications. FDA 21 CFR food-contact substance notifications govern barrier chemistry approvals, creating 180-day review bottlenecks for novel formulations. Georgia-Pacific leverages integrated pulp-to-paper operations across the southeastern United States to maintain cost-advantaged supply positions.
Germany
Artisan butcher channels in Bavaria and the Rhineland are consolidating procurement around REACH-compliant bio-barrier grades as ECHA phase-down timelines eliminate fluorinated alternatives. The EU F-Gas Regulation constrains coating chemistries, redirecting mill investment toward aqueous barrier lines. German protein processors now weight ECHA-registered bio-barrier portfolios as bid-table requirements, squeezing mid-tier competitors without compliant formulations.
France
Premium charcuterie presentation demand in the Île-de-France and Auvergne-Rhône-Alpes regions drives greaseproof paper consumption for counter display and dry-aging rooms. The EU Packaging and Packaging Waste Regulation tightens material compliance requirements, accelerating certified-recyclable grade procurement. French retail compliance departments have captured specification authority from meat processing procurement teams, reshaping supplier selection criteria.
India
Organized retail expansion and cold-chain infrastructure development in Maharashtra and Gujarat create first-mover openings for FSSAI-certified kraft suppliers. The FSSAI food-contact compliance framework remains less stringent than REACH or FDA equivalents, attracting investment from mills seeking regulatory arbitrage. Indian e-commerce meat delivery channels in Bangalore and Delhi-NCR are piloting branded presentation-grade wrapping for unboxing differentiation.
Japan
Traditional aging-room techniques in the Kansai region sustain demand for high wet-strength uncoated grades. METI industrial standards and JIS certification requirements shape food-contact paper specifications for domestic protein processors. Oji Paper and NIPPON PAPER INDUSTRIES anchor supply positions through integrated forestry-to-mill operations across Honshu island.
Butchers Paper Market Competitive Environment
United States producers anchor one tier through integrated pulp-to-paper operations and scale in virgin kraft production; European specialists hold another through REACH-compliant bio-barrier formulation depth. The vendor base fragments across regional certification requirements, with tier separation widening between certified premium suppliers and commodity-grade competitors. Three archetypes dominate: integrated forest products conglomerates with captive pulp supply, specialty paper converters with barrier-coating expertise, and regional kraft mills serving proximity-sensitive meat processing clusters. Capacity expansion and strategic partnerships represent the dominant competitive moves, as mills seek to lock in protein processor contracts ahead of regulatory compliance deadlines.
Within the integrated conglomerate tier, Georgia-Pacific LLC, International Paper Company, and WestRock Company exemplify scale-driven positioning through southeastern United States pulp integration. These entities represent archetypes of backward-controlled supply chains, where captive sulfate pulp production insulates margin positions from Canadian softwood price volatility. Mondi Group and Nordic Paper occupy comparable positions in European markets, though their regulatory exposure centers on ECHA compliance timelines rather than FDA notification cycles. The competitive dynamic concentrates on certification depth as the primary differentiation vector, with mills lacking pre-approved bio-barrier portfolios facing accelerated customer defection.
| Leading Market Players |
|---|
| Georgia-Pacific LLC |
| International Paper Company |
| WestRock Company |
| Mondi Group |
| Nordic Paper |
| NIPPON PAPER INDUSTRIES CO., LTD. |
| Oji Paper Company |
| Canadian Kraft Paper Ltd. |
| Smurfit Kappa |
| Others |
Value Chain & Pricing Dynamics
Pulp mill technical workforce concentration in the southeastern United States widens pricing-tier spreads between virgin kraft and recycled-content grades, as labor-cost differentials compound with sulfate pulp input volatility to separate premium-certified suppliers from commodity producers.
Pricing Analysis
Distributor margin layers absorb 12-18 points between mill gate and end-user pricing, creating three-tier pricing structure across premium, standard, and economy levels differentiated by FDA food-contact certification depth and wet-strength resin loading. Pricing pressure stems from softwood pulp cost swings tied to Canadian lumber harvest cycles, with national foodservice distributors in California and New York showing greatest price sensitivity due to state packaging fee exposure, while artisan butcher channels remain least sensitive given unboxing differentiation priorities.
Supply Chain Analysis
Single-source vulnerability sits with polyamide-epichlorohydrin wet-strength resin production clustered in China and Germany, exposing North American mills to additive supply disruption. Geographic supply concentration centers on the United States, Canada, and Sweden for sulfate pulp feedstock, with finished paper production drawing from integrated southeastern US operations and Nordic mill networks. Distribution runs through protein processor procurement departments and retail compliance gatekeepers, with tariff exposure on Canadian softwood pulp creating structural cost risk for non-integrated converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in butchers paper hinges on REACH-compliant bio-barrier premiumization offsetting fluorinated chemistry phase-down costs, with reformulation investment separating certified suppliers from margin-compressed commodity tiers.
For Market Incumbents: Hedge against PFAS regulatory elimination by accelerating aqueous barrier coating line deployment ahead of ECHA enforcement timelines. Lock in protein processor contracts through integrated pulp-to-paper supply guarantees that insulate customers from Canadian softwood price swings. Prioritize California and New York retail compliance relationships as specification authority migrates from processors to sustainability departments. For New Entrants and Emerging Players: Direct-to-consumer butcher subscription channels represent the most penetrable white-space target, as e-commerce meat delivery prioritizes branded presentation wrapping over commodity grade procurement. Enter through FSSAI-certified kraft supply to Indian organized retail cold-chain expansion, leveraging regulatory arbitrage against REACH and FDA stringency. Pursue co-development partnerships with Pacific Northwest artisan shops piloting cellulose nanofibril-reinforced substrates. For Investors and Strategic Acquirers: Integrated forest products conglomerates are the most active acquirer in this space, targeting specialty paper converters with ECHA-registered bio-barrier portfolios to close formulation gaps. Long-term viability favors mills with pre-certified compliance infrastructure and captive sulfate pulp supply. Watch for FDA 21 CFR notification backlog clearance as inflection signal for novel barrier chemistry launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Bio-Barrier Reformulation | ECHA-registered aqueous coatings unlock German and French artisan butcher procurement consolidation. |
| Integrated Pulp-to-Paper Capacity Expansion | Captive sulfate pulp production insulates Georgia-Pacific and International Paper from Canadian softwood volatility. |
| Cellulose Nanofibril Substrate Development | Nordic Paper and Pacific Northwest pilots eliminate synthetic wet-strength additives for aging-room applications. |
| Direct-to-Consumer Packaging Partnerships | Branded presentation grades capture unboxing differentiation premium in subscription meat delivery channels. |
| FSSAI Certification First-Mover Investment | Indian organized retail cold-chain expansion rewards early certified-kraft entrants with procurement lock-in. |
Study Parameters
Coverage spans the United States, Germany, France, India, and Japan, with primary inputs from each market combining interviews with pulp mill operations directors, protein processor procurement managers, retail sustainability compliance officers, and artisan butcher shop owners. Secondary validation draws from FDA 21 CFR food-contact substance notifications, ECHA REACH registration databases, FSSAI compliance filings, and EU Packaging and Packaging Waste Regulation implementation guidance. Bottom-up volume modeling triangulates against top-down pulp consumption estimates and trade flow analysis.
Rate-of-change decomposition across the analysis window segments volume and value by product type (kraft, greaseproof, parchment, presentation), end-use channel (meat processing, artisan butcher, foodservice, retail), coating configuration (uncoated, wax, aqueous barrier), and geographic regulatory cluster. CAGRs derive from equipment upgrade cycle timing, retail compliance refresh schedules, and protein processing capacity expansion pipelines. Forecast inputs incorporate cellulose nanofibril pilot adoption curves and ECHA PFAS phase-down enforcement probability.
Underlying measurement precision varies by segment; uncoated kraft volume estimates carry tighter precision than emerging bio-barrier grade projections given formulation portfolio opacity. Forecasts reflect assumptions on regulatory enforcement timing, pulp price mean-reversion, and substitution elasticity between paper and vacuum-sealed films. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
South East Asia Corrugated Packaging Market
Paper & Paperboard Packaging
Vegetable Parchment Paper Market
Paper & Paperboard Packaging
Middle East and Africa Paper Cone Market
Paper & Paperboard Packaging
India Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Europe Paper Cone Market
Paper & Paperboard Packaging
Paper Pleated Cups Market
Paper & Paperboard Packaging
Global Folding Boxboards Market
Paper & Paperboard Packaging
Coated Recycled Boxboard Market
Paper & Paperboard Packaging
UAE Corrugated Board Packaging Market
Paper & Paperboard Packaging
Paper Wrap Market
Paper & Paperboard Packaging
Desiccant Paper Market
Paper & Paperboard Packaging
Corrugated Shippers Market
Paper & Paperboard Packaging
Coated Paper Packaging Box Market
Paper & Paperboard Packaging
Italy Honeycomb Paper Market
Paper & Paperboard Packaging
Tissue and Hygiene Paper Packaging Market
Paper & Paperboard Packaging
Asia Pacific Paper Packaging Market