
 Kraft Envelopes Market | 2026-2036
Kraft Envelopes Market Size, Share, and Industry Trends Forecast 2026-2036
Kraft Envelopes Market Foresight
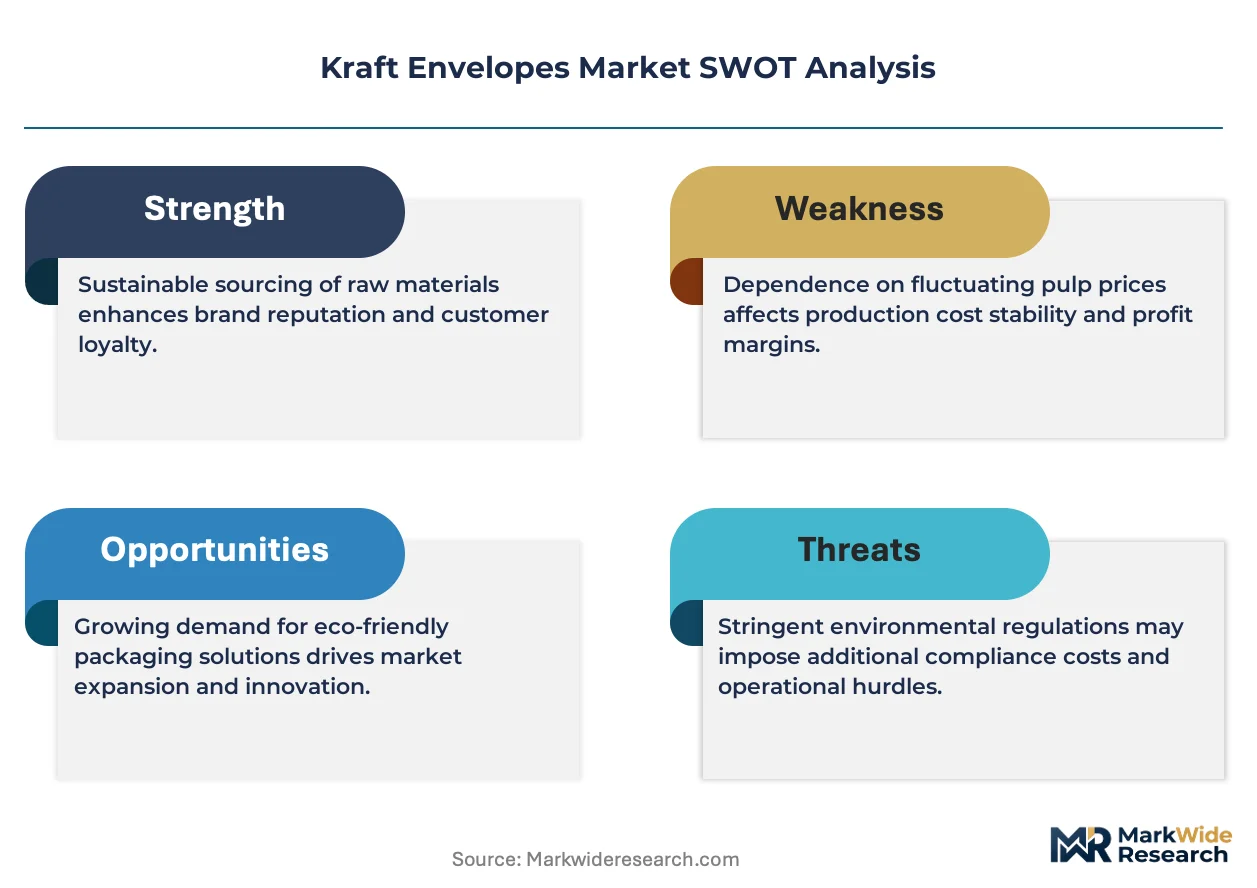
FSC chain-of-custody certification is reorganizing supplier eligibility across the Kraft Envelopes Market, filtering out uncertified mills from premium tender pools. International Paper leverages its captive pulp supply to sustain cost advantages in North American flat envelope production. WestRock anchors its position through integrated containerboard and converting assets along the US Gulf Coast. Mondi Group competes via specialized kraftliner grades engineered for high-speed e-commerce fulfillment lines.
Kraft envelopes are unbleached paper-based mailers, typically manufactured from sulfate pulp with basis weights ranging from 70 to 150 gsm, designed to protect documents and lightweight goods during transit. Their commercial purpose centers on providing tear-resistant, printable, and recyclable packaging for postal and courier distribution networks. Bubble envelopes lead volume among product types due to built-in cushioning that reduces secondary dunnage requirements in e-commerce parcels. Padded envelopes sustain premium positioning through quilted fiber lining that satisfies retailer sustainability scorecards. Window envelopes occupy a stable niche in corporate billing and statement mailing where address visibility eliminates separate labeling steps.
FDA indirect food contact rules, EPA recycled content guidelines, and FSC chain-of-custody standards collectively shape material sourcing and end-market access for kraft envelope manufacturers serving US retail and food-adjacent distribution. The EU Packaging and Packaging Waste Regulation extends these constraints across European supply chains, mandating design-for-recycling protocols that favor uncoated kraft substrates over polymer-laminated alternatives. Stakeholders must monitor evolving extended producer responsibility frameworks and certify substrate portfolios before tender windows close on major retail and postal contracts.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing rapid substrate redesign across kraft envelope supply chains, eliminating polymer-laminated variants from retail tender pools and privileging uncoated fiber grades that satisfy extended producer responsibility frameworks.
Growth Catalysts
- E-commerce fulfillment acceleration:Online retail parcel volumes in Germany and the Netherlands are pulling padded and bubble kraft variants into automated sorting lines designed for dimensional stability.
- FSC chain-of-custody mandates:Major European postal operators now require certified fiber sourcing as a contract precondition, filtering uncertified mills from premium segments.
- Recyclability engineering:Water-based barrier coatings are replacing polyethylene laminations, enabling single-stream paper recovery without contamination penalties.
Market Restraints
- Sulfate pulp cost volatility:Energy-intensive kraft pulping exposes producers to natural gas price swings in Nordic and Baltic supply basins.
- Converter concentration:Flat envelope capacity clusters along the US Gulf Coast and in Poland, creating freight cost penalties for inland distribution.
- Plastic mailer substitution:Polyethylene bubble mailers retain cost advantages in moisture-critical applications, limiting fiber penetration in humid climates.
Strategic Opportunities
- India e-commerce logistics:Underdeveloped cold-chain packaging creates demand for insulated kraft solutions in pharmaceutical and fresh-food last-mile delivery.
- Digital printing integration:Inline inkjet addressing on window envelopes eliminates separate label application, compressing production steps for billing services.
- EU Green Deal procurement:Public sector tendering now weights carbon footprint metrics, advantaging regional kraft suppliers with verified scope-three data.
Industry Challenges
- FSC certification timelines:Chain-of-custody audits require 12-18 month implementation windows, delaying contract eligibility for mid-tier converters.
- Automated line integration:High-speed e-commerce fulfillment systems demand precise dimensional tolerances that legacy converting equipment cannot achieve without capital retooling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kraft Envelopes Market |
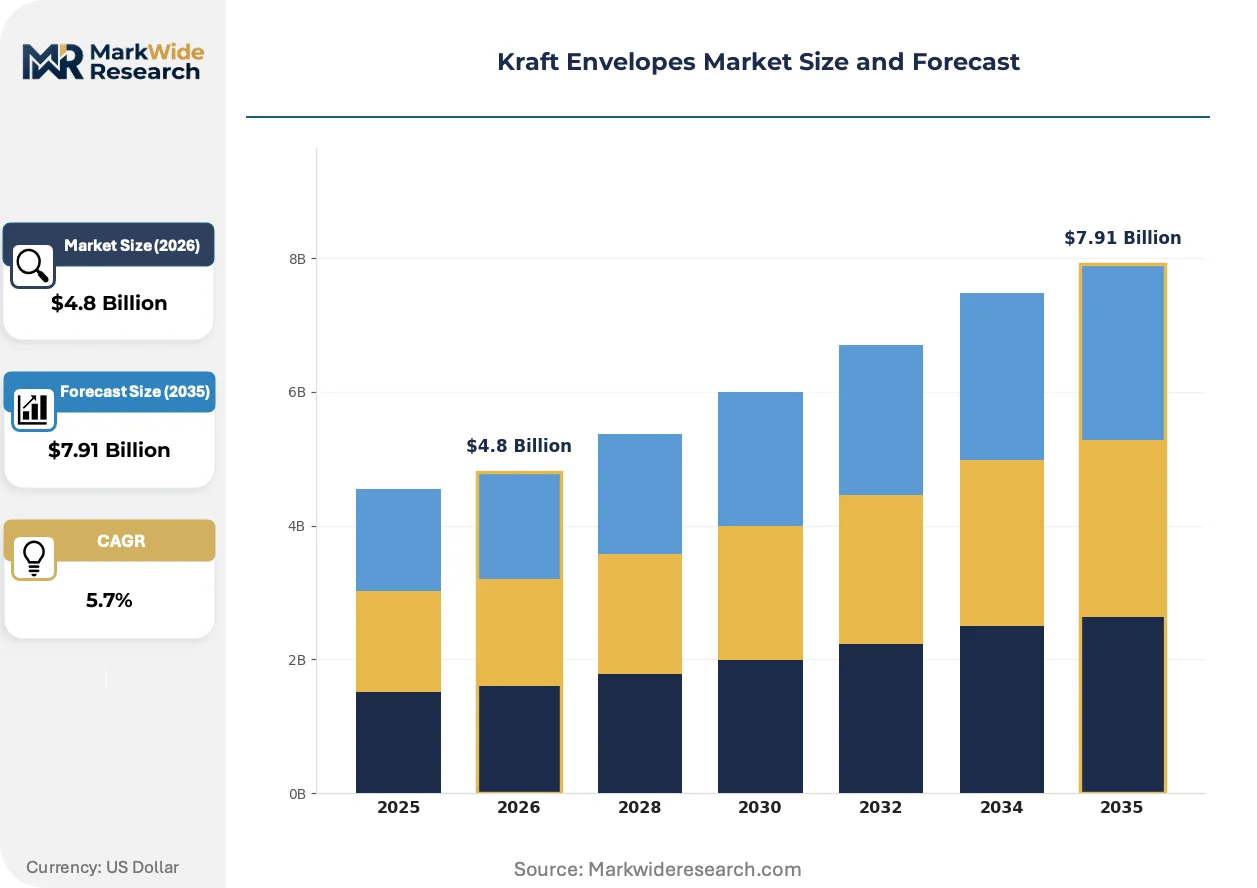
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Envelopes, Bubble Envelopes, Padded Envelopes, Window Envelopes End User: Retailers, E-commerce, Educational Institutions, Corporates Size: DL, C5, C4, C6 Closure Type: Self-Seal, Tape Seal, Gummed Seal, String & Button |
| Companies Covered | International Paper, WestRock, Georgia-Pacific, Mondi Group, Sealed Air, Smurfit Kappa Group, DS Smith, Stora Enso, Bong Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kraft Envelopes Market Shifts & Advancements
Active substrate engineering and regulatory compliance automation are reshaping competitive capabilities across kraft envelope manufacturing, compressing product development cycles while elevating certification requirements.
Water-based barrier coatings with oxygen and moisture resistance are supplanting polyethylene extrusion laminations in food-adjacent mailer applications. European pharmaceutical distributors are adopting these substrates at accelerating rates to satisfy EU Packaging and Packaging Waste Regulation recyclability mandates. The shift is compressing demand for multi-material laminated structures and redirecting R&D spending toward bio-based polymer research.
REACH chemical registration requirements are tightening disclosure obligations for paper additives and surface treatments used in kraft envelope production. Manufacturers must now document substance volumes and hazard classifications across complex multi-tier supply chains. Specialty envelope grades with antimicrobial or tracking functionalities face the steepest compliance burdens, driving consolidation among additive suppliers capable of regulatory dossier preparation.
Consolidated procurement by platform retailers is compressing supplier bases and elevating performance guarantees in contract terms. Third-party logistics providers in Germany and France are replacing fragmented envelope sourcing with single-vendor agreements covering multi-country distribution networks. Food and beverage subscription services represent the most visible end-use vertical where packaging specifications now bundle traceability, carbon accounting, and return-loop logistics into unified tender requirements.
Kraft Envelopes Market Segmentation
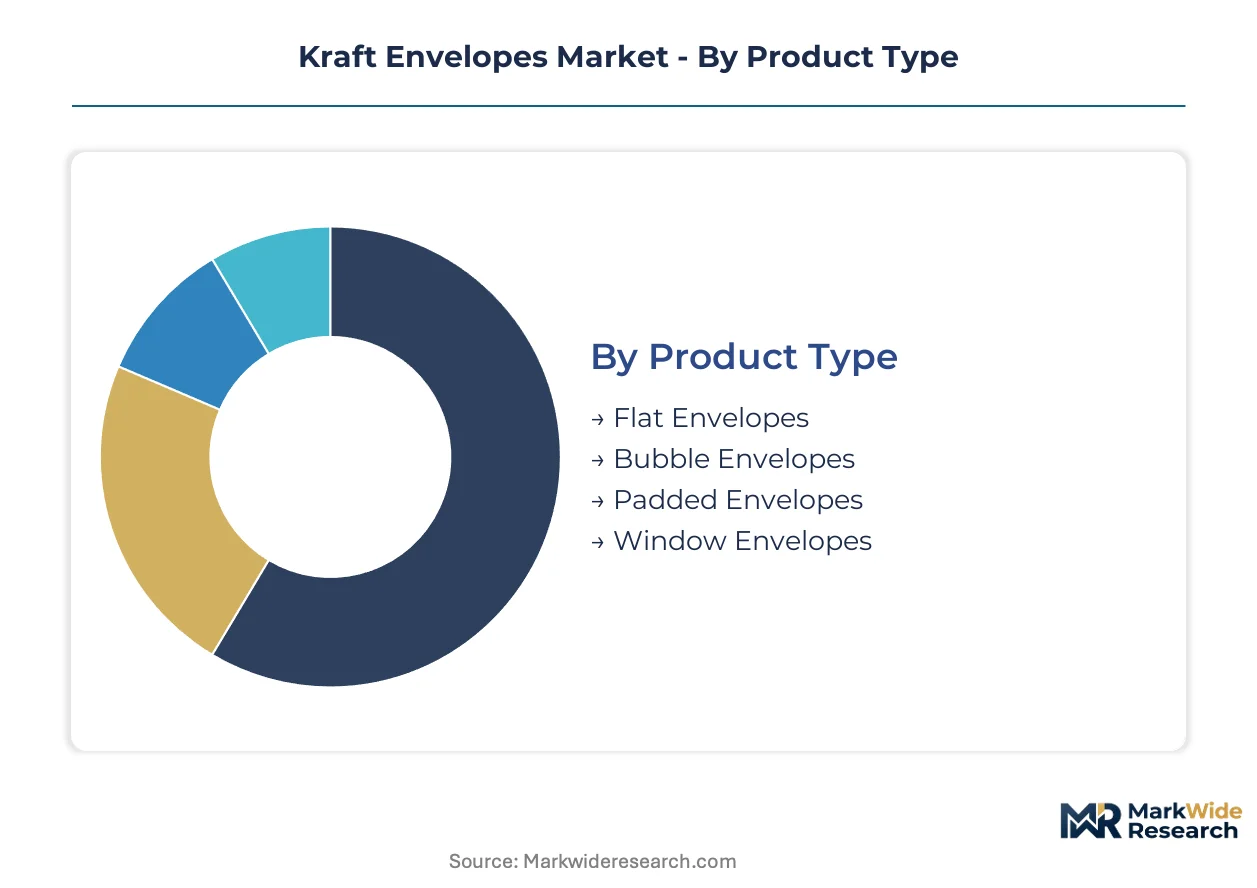
Kraft envelope manufacturers configure production assets around dimensional and functional specifications that align with postal automation standards and retailer sustainability mandates. Segmentation reveals where capital allocation concentrates and which specifications command tender premiums in contract negotiations.
Product Type:
Margin pools concentrate in padded and bubble variants where cushioning specifications justify 30-40% price premiums over flat alternatives in e-commerce fulfillment contracts.
- Bubble Envelopes:Built-in polyethylene air-cell lining provides impact protection without secondary dunnage, making these the default choice for German and Dutch automated sorting facilities handling electronics and accessories. Major platform retailers specify bubble variants for parcels under 500 grams to minimize damage claims and return logistics costs.
- Padded Envelopes:Quilted fiber lining from recycled pulp satisfies FSC chain-of-custody requirements while delivering comparable protection to plastic alternatives. Demand clusters in corporate sustainability programs and subscription box services where unboxing experience and recyclability scoring influence vendor selection.
- Flat Envelopes:Standard unbleached kraft construction dominates document mailing and statement distribution with basis weights from 70-120 gsm.
- Window Envelopes:Die-cut film windows enable address visibility for billing and invoice streams without separate labeling steps.
Flat envelopes hold installed capacity across North American Gulf Coast mills. Bubble variants are rotating up the share rankings as e-commerce parcel volumes displace paper correspondence.
End User:
Application requirements diverge sharply between high-volume automated fulfillment and low-frequency administrative mailing, reshaping converter customer service structures.
- E-commerce:Third-party logistics providers in Germany and France consolidate procurement across multi-country networks, bundling dimensional stability specifications with carbon accounting requirements. Platform retailers mandate FSC certification and water-based barrier coatings as baseline contract conditions.
- Retailers:Brick-and-mortar chains source kraft envelopes for in-store gift services and click-and-collect packaging, prioritizing printable surfaces for brand messaging over protective performance.
- Corporates:Financial services and utilities maintain steady demand for window envelopes in statement mailing programs.
- Educational Institutions:Universities and examination boards require tamper-evident closures for transcript and credential distribution.
E-commerce is expanding most quickly as a demand vertical. Retailers maintain the largest historical volume base though share is compressing.
Size:
Postal tariff structures and sorting equipment tolerances lock in dimensional standards that limit custom specification opportunities.
- C4:229 × 324 mm format accommodates A4 documents without folding, commanding premium positioning in legal and contract mailing where crease-free presentation matters.
- DL:220 × 110 mm standard for machine-inserted correspondence and direct mail campaigns with high-speed envelope inserter compatibility.
- C5:162 × 229 mm intermediate format for folded A4 correspondence and mid-weight e-commerce parcels.
- C6:114 × 162 mm compact format for greeting cards and small accessory shipping.
C4 holds installed capacity in European converting assets. DL is climbing the fastest as direct mail automation investments expand.
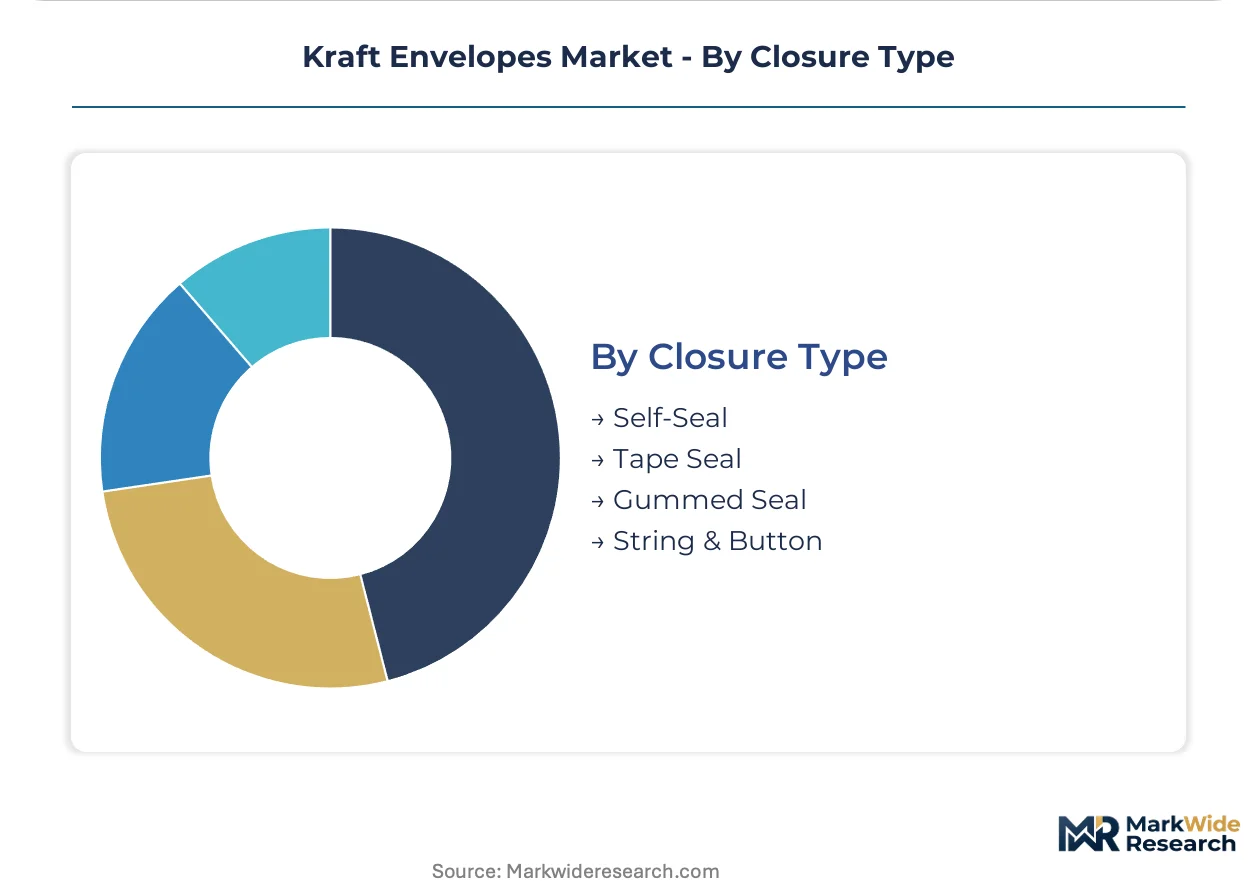
Closure Type:
Automation compatibility and security requirements create tiered pricing structures across sealing mechanisms.
- Self-Seal:Pressure-activated adhesive strips eliminate moisture application in high-speed packing operations, dominating e-commerce fulfillment lines where labor cost minimization drives specification.
- Gummed Seal:Moisture-activated adhesives provide tamper-evident properties valued in examination and credential distribution.
- Tape Seal:Peel-and-strip convenience for consumer gift packaging and low-security administrative use.
- String & Button:Reusable closure for interoffice circulation and archival document storage.
Self-seal holds installed capacity across automated fulfillment supply chains. Gummed seal is gaining share fastest in security-sensitive applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Third-party logistics providers in Germany and the Netherlands drive premium kraft envelope procurement, while North American pulp integration and Asian e-commerce expansion reshape supply priorities across distinct regulatory environments.
Germany
Automated fulfillment centers in Leipzig and Dortmund pull bubble and padded variants into high-speed sorting lines handling electronics and fashion accessories. The EU Packaging and Packaging Waste Regulation mandates design-for-recycling protocols that eliminate polymer-laminated alternatives from retail tender pools. North Rhine-Westphalia hosts concentrated converting capacity serving cross-border distribution networks into France and the Benelux.
United States
E-commerce platform retailers specify FSC-certified kraft mailers for parcels under 500 grams, compressing demand for plastic alternatives in California and Texas fulfillment corridors. EPA recycled content guidelines shape material sourcing for food-adjacent distribution, while FDA indirect food contact rules govern pharmaceutical mailer applications. The Gulf Coast pulp-to-converting cluster sustains cost advantages in flat envelope production through captive sulfate supply.
China
Cross-border e-commerce exporters in Guangdong and Zhejiang provinces source kraft mailers for AliExpress and Temu fulfillment into European markets. GB standards and dual carbon goals tighten energy efficiency requirements for paper converting operations. The Yangtze River Delta hosts integrated packaging districts where envelope converters co-locate with corrugated box manufacturers.
India
Underdeveloped cold-chain infrastructure creates demand for insulated kraft solutions in pharmaceutical and fresh-food last-mile delivery across Maharashtra and Karnataka. BIS certification requirements for paper-based packaging materials filter supplier eligibility in government procurement. Mumbai-Pune logistics corridors concentrate third-party logistics provider activity driving padded envelope adoption.
Netherlands
Rotterdam distribution hubs serve as entry points for pan-European retail networks, consolidating procurement specifications across multiple national markets. EU Green Deal procurement weights carbon footprint metrics in public sector tendering, advantaging regional suppliers with verified scope-three data. The Randstad logistics cluster integrates automated envelope insertion systems for direct mail and subscription box fulfillment.
Kraft Envelopes Market Competitive Landscape
Player mix skews toward integrated forest products groups with captive pulp supply and specialized packaging converters with e-commerce fulfillment expertise. Market structure concentrates around sulfate pulp integration in North America and kraftliner specialization in Europe, with mid-tier converters facing certification barriers to premium tender pools. Three archetypes dominate: vertically integrated pulp-to-converting conglomerates, specialized protective packaging engineers, and regional envelope converters with postal certification heritage. Competitive moves center on FSC chain-of-custody acquisition for contract eligibility and water-based barrier coating R&D to displace polyethylene laminations.
Among North American integrated producers, International Paper, WestRock, and Georgia-Pacific exemplify the pulp-captive archetype that sustains cost positioning in flat envelope grades. Mondi Group and Smurfit Kappa Group occupy positions within the European kraftliner specialization tier, engineering substrate grades for high-speed automated fulfillment lines. Sealed Air represents the protective packaging engineering archetype through bubble and padded variant development. These named entities anchor strategic commentary without constraining the full competitive set.
| Leading Market Players |
|---|
| International Paper |
| WestRock |
| Georgia-Pacific |
| Mondi Group |
| Sealed Air |
| Smurfit Kappa Group |
| DS Smith |
| Stora Enso |
| Bong Group |
| Others |
Supply & Pricing Matrix
Forty-five-day sulfate pulp inventory cycles in Nordic mills translate directly into contract pricing power for integrated producers, while inland converters absorb freight penalties that compress their margin capture against Gulf Coast and Polish manufacturing clusters. This lead-time asymmetry between captive pulp supply and merchant fiber sourcing stratifies competitive positioning across flat, padded, and bubble envelope grades.
Pricing Analysis
Cost-plus contracts with sulfate pulp indexation dominate long-term supply agreements between integrated producers and platform retailers, creating three-tier pricing structure across premium, standard, and economy levels. Price differentiation separates FSC-certified padded variants from uncertified flat grades and from polyethylene-laminated bubble alternatives facing regulatory displacement. Pricing pressure stems from energy-intensive kraft pulping exposure to natural gas volatility in Baltic supply basins. Third-party logistics providers exhibit highest price sensitivity in automated fulfillment contracts, while pharmaceutical distributors prioritize barrier performance over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies prevail among German and Dutch automated fulfillment centers, whereas North American integrated producers maintain strategic stockpiles of unbleached kraftliner to buffer sulfate pulp cost swings. Geographic supply concentration centers on the US Gulf Coast, Poland, and the Yangtze River Delta, with captive pulp integration in the first two and co-located corrugated manufacturing in the third. Raw material dependencies rest on sulfate pulp, water-based barrier coatings, and pressure-sensitive adhesives. Single-source vulnerability concentrates in Nordic pulp supply for European converters. Distribution runs through centralized third-party logistics hubs serving cross-border retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of FSC chain-of-custody certification capacity filters mid-tier converters from premium tender pools, creating asymmetric returns for early certifiers against stranded competitors facing 12-18 month audit timelines. This capability gap widens as EU Packaging and Packaging Waste Regulation compliance hardens into contract preconditions.
For Market Incumbents: Fortify pulp-captive positions through sulfate supply integration along the US Gulf Coast and Baltic regions, while accelerating water-based barrier coating R&D to displace polyethylene laminations before regulatory deadlines eliminate multi-material structures from retail tender pools. Certification investment represents the critical defensive lever against specialty converters capturing pharmaceutical and food-adjacent mailer premiums. For New Entrants and Emerging Players: Anchor in India's underdeveloped cold-chain packaging segment, where insulated kraft solutions for pharmaceutical and fresh-food last-mile delivery face limited domestic competition and BIS certification barriers filter incumbent eligibility. White-space targets include Maharashtra pharmaceutical distribution and Karnataka fresh-produce logistics. Digital printing integration for window envelopes offers a differentiated go-to-market angle against commodity flat envelope producers. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated forest products groups divesting non-core envelope converting assets to focus on containerboard and corrugated core operations. Long-term viability favors specialized protective packaging engineers with e-commerce fulfillment expertise over commodity flat envelope producers facing plastic mailer substitution pressure. Watch FSC certification timeline compression as the inflection signal—accelerating audit completion rates indicate tightening supply scarcity and expanding tender premiums for certified capacity.| Strategic Initiative | Industry Significance |
|---|---|
| FSC Chain-of-Custody Certification | EU Packaging and Packaging Waste Regulation mandates filter uncertified mills from premium retail and postal tender pools. |
| Water-Based Barrier Coating Development | REACH chemical registration requirements favor bio-based polymer research displacing polyethylene extrusion laminations. |
| Automated Line Integration Investment | High-speed e-commerce fulfillment systems in Leipzig and Dortmund demand precise dimensional tolerances legacy equipment cannot achieve. |
| India Cold-Chain Packaging Expansion | Underdeveloped pharmaceutical and fresh-food last-mile infrastructure in Maharashtra and Karnataka creates insulated kraft demand. |
| Digital Printing Integration | Inline inkjet addressing on window envelopes eliminates separate label application for billing services compression. |
Research Methodology
A standing panel of envelope converting plant managers, third-party logistics procurement leads, paper mill technical directors, and postal operator supply chain managers provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from customs trade data, FSC certification databases, SEC 10-K filings of integrated forest products groups, and EU regulatory implementation notices. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Consistency checks against external benchmarks validated projection outputs across the analysis window. The analytical framework modeled segmentation dimensions including product type, end-user vertical, closure mechanism, and regional regulatory cluster. CAGRs derived from envelope insertion equipment deployment rates, e-commerce parcel volume trajectories, and pulp cost pass-through elasticity estimates. Industry-specific forecast inputs incorporated FSC certification audit completion timelines and water-based coating adoption curves in pharmaceutical distribution.
Decision-makers should treat outputs as directional under stable natural gas pricing and sustained EU regulatory enforcement; material deviation would warrant model refresh. Forecasts reflect assumptions about sulfate pulp supply continuity and automated fulfillment capital expenditure patterns. Revision becomes warranted when FSC certification backlog durations or barrier coating performance metrics cross thresholds that alter competitive supply availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Envelope Market
Paper & Paperboard Packaging
Disposable Paper Plates Market
Paper & Paperboard Packaging
Food Contact Paper and Board Market
Paper & Paperboard Packaging
Packing Paper Market
Paper & Paperboard Packaging
India Paper Packaging Market
Paper & Paperboard Packaging
Composite Cardboard Tube Packaging Market
Paper & Paperboard Packaging
Tissue and Hygiene Paper Packaging Market
Paper & Paperboard Packaging
Schrenz Paper Market
Paper & Paperboard Packaging
Saudi Arabia Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Super Calendered Kraft Papers Market
Paper & Paperboard Packaging
Natural Sack Kraft Papers Market
Paper & Paperboard Packaging
Waxed Paper Packaging Market
Paper & Paperboard Packaging
Countertop Paper Napkin Dispenser Market
Paper & Paperboard Packaging
Sublimation Paper Market
Paper & Paperboard Packaging
Envelope Paper Market
Paper & Paperboard Packaging
Paperboard Protectors Market