
 India Paper Packaging Market | 2026-2036
India Paper Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
India Paper Packaging Market Foresight
Buyer concentration among quick-commerce platforms and organized retail chains is restructuring procurement volumes across the India paper packaging landscape. TCPL Packaging Ltd leverages its integrated carton and printing infrastructure to serve pharmaceutical and FMCG majors with specialized folding box solutions. Smurfit WestRock sustains corrugated containerboard leadership through scale advantages in recycled fiber sourcing and box plant automation. JK Paper Ltd anchors kraft paper supply for industrial wrapping and sack segments, competing on fiber self-sufficiency from its integrated pulp mills.
India paper packaging encompasses fiber-based protective and presentation systems manufactured from virgin or recycled cellulose pulp, typically ranging from 150 to 400 gsm in board grades and fluted in corrugated constructions to achieve specified burst strength and edge crush test values. Corrugated boxes dominate volume throughput across food and beverage distribution networks, where stacking strength and moisture resistance parameters govern specification. Kraft paper occupies margin-intensive niches in cement and chemical sack applications, where tensile energy absorption and porosity standards differentiate supplier tiers. Sustainable packaging formats are gaining specification share among export-oriented electronics and consumer goods brands responding to EPR compliance thresholds.
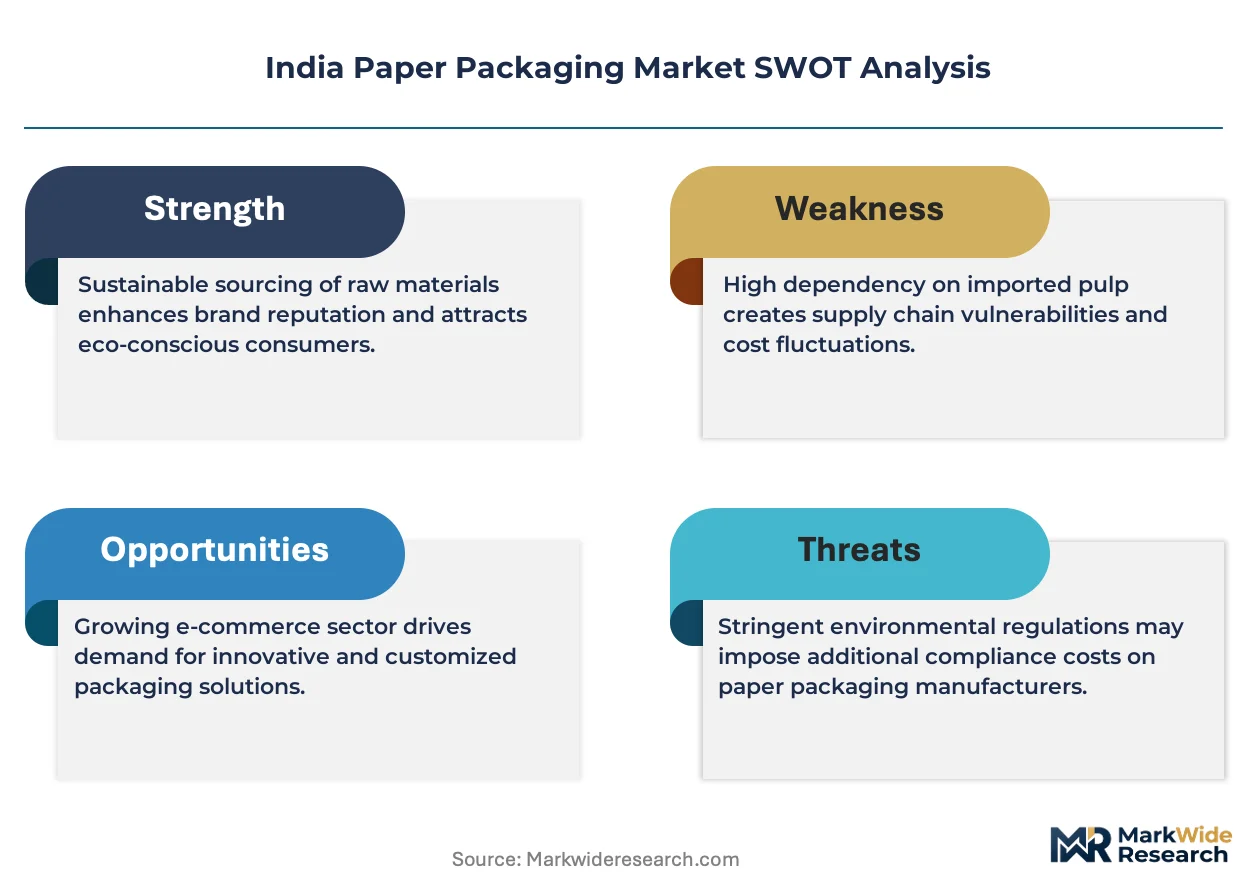
BIS certification requirements for food-contact paper materials and the Plastic Waste Management Rules from the Ministry of Environment, Forest and Climate Change are elevating fiber-based packaging specifications across regulated end uses. The Bureau of Indian Standards and Central Pollution Control Board jointly shape market access through mandatory testing protocols and EPR target enforcement. Stakeholders must monitor evolving EPR liability allocations and state-level implementation variance to anticipate compliance cost trajectories and capacity planning requirements.
Market Dynamics
Extended producer responsibility mandates under the Plastic Waste Management Rules are redirecting procurement volumes toward fiber-based alternatives across pharmaceutical, FMCG, and quick-commerce supply chains. The Ministry of Environment, Forest and Climate Change enforcement timelines are compressing specification cycles for brand owners.
Growth Catalysts
- EPR Compliance Thresholds:The Plastic Waste Management Rules mandate phased plastic reduction targets, forcing brand owners to specify corrugated and folding carton formats for food and electronics distribution.
- Quick-Commerce Procurement Concentration:Food delivery aggregators in Mumbai, Delhi, and Bengaluru are consolidating packaging volumes through long-term supply agreements with integrated converters.
- Fiber Self-Sufficiency:Integrated pulp-to-board operations in Gujarat and Maharashtra are insulating domestic supply from imported waste paper volatility.
Market Restraints
- Imported Recovered Fiber Cost Volatility:Containerboard producers depend on OCC imports from North American and European sources, exposing margin structures to freight and currency fluctuations.
- BIS Certification Timelines:Food-contact paper testing protocols from the Bureau of Indian Standards extend product qualification cycles for new board grades entering F&B applications.
- Plastic Flexible Substitution in Moisture-Sensitive Categories:Laminated pouches retain specification share in spice and oil packaging where grease resistance requirements exceed uncoated kraft capabilities.
Strategic Opportunities
- Tier-Two City Quick-Commerce Expansion:Jaipur, Lucknow, and Indore present underpenetrated demand for insulated corrugated delivery formats as platform coverage extends beyond metro anchors.
- Pharmaceutical Serialization Integration:Track-and-trace mandates from CDSCO are creating specification pull for folding cartons with embedded authentication features and tamper-evident closures.
- PLI Scheme for Paper Sector:Production-linked incentive allocations for specialty paper and packaging board are subsidizing capital deployment for recycled fiber processing upgrades.
Industry Challenges
- Skilled Converter Technician Scarcity:Die-cutting and folder-gluer operation expertise concentrates in legacy packaging clusters around Mumbai and Ahmedabad, constraining greenfield plant staffing.
- Legacy ERP Integration with EPR Reporting:Mid-tier converters face system reconfiguration costs to automate extended producer responsibility documentation for brand owner compliance submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Paper Packaging Market |
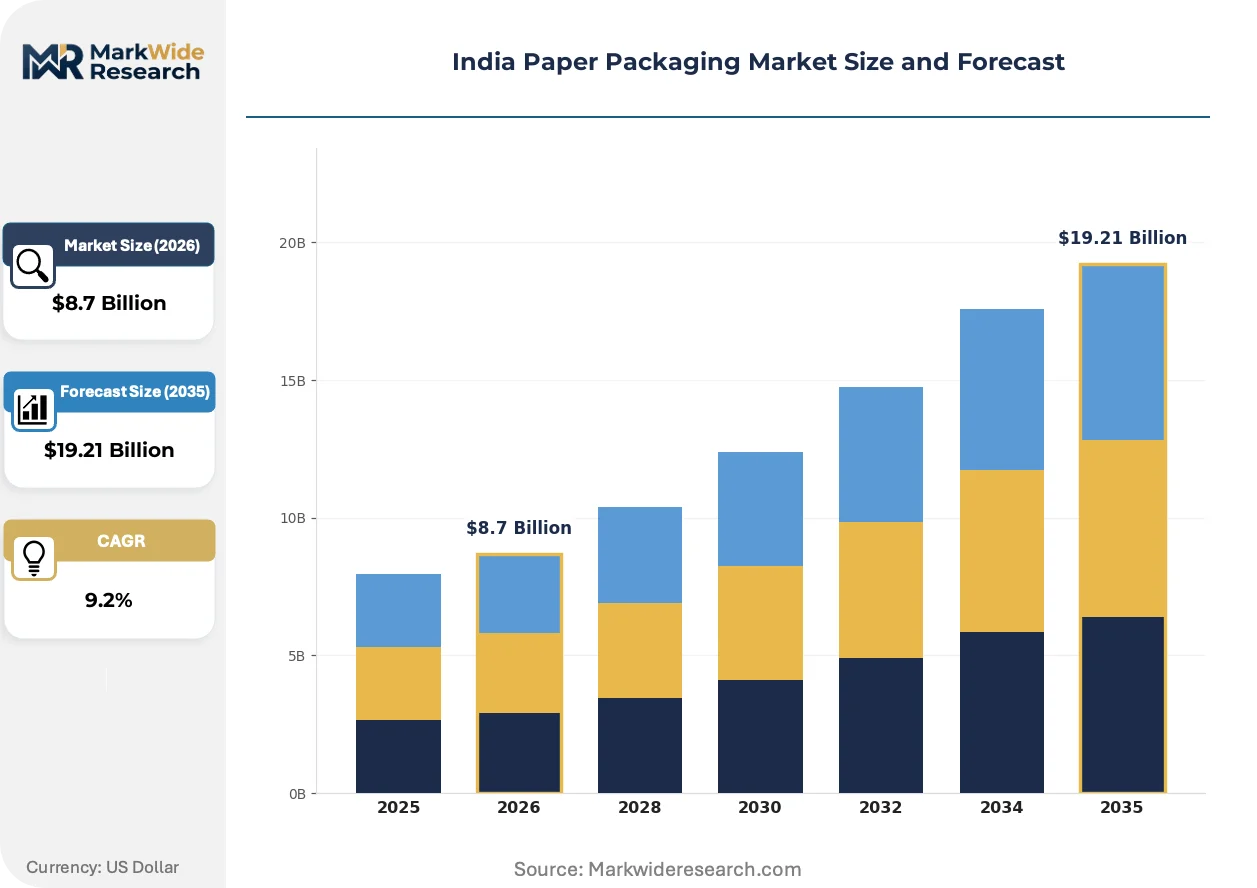
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.21 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cardboard, Kraft Paper, Corrugated Boxes, Paper Bags End User: Food & Beverage, Consumer Goods, Electronics, Healthcare Packaging Type: Rigid Packaging, Flexible Packaging, Sustainable Packaging, Custom Packaging Distribution Channel: Online Retail, Offline Retail, Direct Sales, Wholesale |
| Companies Covered | TCPL Packaging Ltd, Smurfit WestRock, Astron Packaging Ltd, TGI Packaging Pvt Ltd, Chaitanya Packaging Pvt Ltd, Kapco Packaging, JK Paper Ltd, Horizon Packs Pvt Ltd, Parksons Packaging Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Paper Packaging Market Shifts & Advancements
Digital printing and inline finishing systems are compressing minimum order quantities while enabling mass customization for seasonal promotional cycles. Regulatory enforcement of single-use plastic bans is accelerating material substitution roadmaps.
High-speed flexographic and digital inkjet systems are automating short-run carton production for pharmaceutical and cosmetics segments. Mid-size converters in Hyderabad and Pune are deploying these platforms to capture just-in-time replenishment contracts from FMCG brand owners. The technology is automating makeready reduction and enabling versioned packaging without plate inventory overhead.
The Plastic Waste Management Rules amendment tightening EPR targets is mandating audited recycling certificates for fiber-based alternatives. Brand owners in processed foods and personal care must now document end-of-life recovery rates through registered producer responsibility organizations. Maharashtra and Gujarat implementation cells are conducting the most aggressive compliance verification, accelerating supplier qualification audits.
Quick-commerce platforms are consolidating packaging specification authority into centralized procurement teams, displacing fragmented restaurant-level purchasing. Swiggy and Zomato are mandating standardized box sizes and moisture-resistant coatings across their delivery partner networks. This concentration is most visible in Bengaluru and Delhi NCR, where platform density supports direct converter relationships bypassing traditional distribution tiers.
India Paper Packaging Market Segmentation
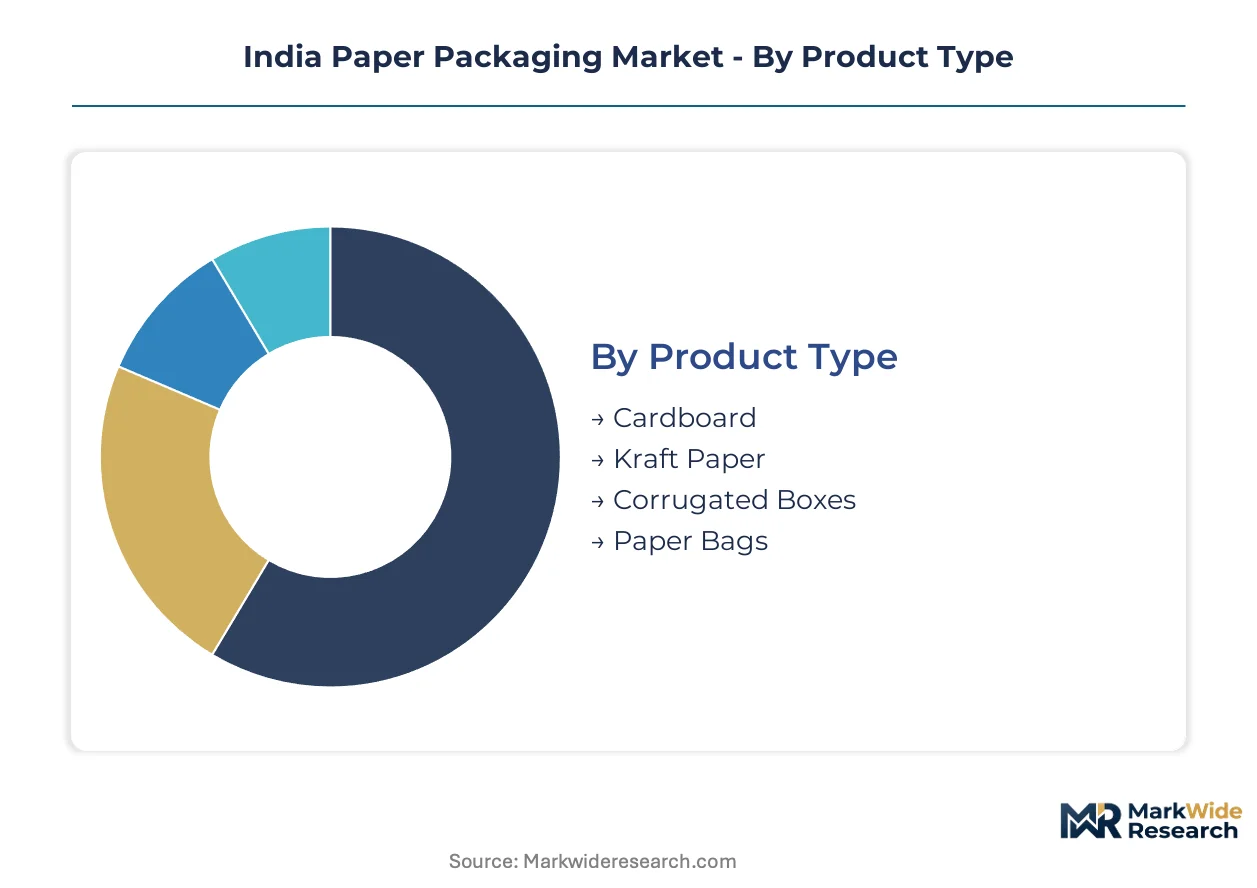
India paper packaging segmentation reveals distinct specification pathways where product-grade decisions cascade through end-use procurement cycles. Each dimension captures different pressure points in converter-customer relationships.
Product Type:
Material upgrade cycles accelerate as brand owners replace legacy plastic formats with fiber-based alternatives meeting BIS food-contact protocols.
- Corrugated Boxes:Fluted board constructions ranging from 150 to 400 gsm achieve specified burst strength and edge crush test values for stacked distribution. Demand concentrates in Maharashtra and Gujarat pharmaceutical clusters where moisture-resistant coatings meet CDSCO serialization requirements.
- Kraft Paper:Unbleached virgin or recycled fiber delivers tensile energy absorption for industrial sack applications. Cement and chemical processors in Rajasthan and Madhya Pradesh specify porosity-calibrated grades for pneumatic filling operations.
- Cardboard:Folding carton substrates serve FMCG presentation requirements with clay-coated surfaces enabling high-definition printing.
- Paper Bags:Twisted-handle and flat-bottom formats displace plastic carry bags in quick-commerce last-mile delivery across Bengaluru and Delhi NCR.
Volume placements concentrate in Corrugated Boxes; the faster expansion belongs to Paper Bags.
End User:
Customer procurement maturity varies sharply, with regulated sectors imposing qualification barriers that filter supplier tiers.
- Food & Beverage:Processed food majors and quick-commerce platforms specify grease-resistant board for ready-meal distribution. FSSAI compliance mandates and Plastic Waste Management Rule targets are redirecting volumes from laminated flexible formats.
- Healthcare:Pharmaceutical folding cartons integrate tamper-evident closures and track-and-trace serialization for CDSCO mandates. Demand clusters around Ahmedabad and Hyderabad formulation facilities.
- Consumer Goods:Personal care and cosmetics brands specify premium carton finishes with embossing and foil stamping for shelf differentiation.
- Electronics:Export-oriented brands specify molded pulp and corrugated cushioning for EPR-compliant end-of-life recovery documentation.
Procurement scale tilts toward Food & Beverage; Healthcare claims the steepest specification upgrade trajectory.
Packaging Type:
Format selection tracks regulatory enforcement intensity and brand sustainability positioning across customer portfolios.
- Sustainable Packaging:Recycled-content and FSC-certified board formats with audited recycling certificates meet Plastic Waste Management Rule EPR documentation requirements. Maharashtra implementation cells verify compliance most aggressively.
- Rigid Packaging:Structural carton and corrugated formats maintain dimensional integrity through distribution stress. Quick-commerce insulated delivery boxes in Mumbai and Pune specify this category for thermal protection.
- Flexible Packaging:Lightweight paper-based wraps and pouches compete with plastic laminates in moisture-tolerant applications.
- Custom Packaging:Short-run digital printing enables versioned promotional cartons without plate inventory overhead.
Shipment value aggregates in Rigid Packaging; Sustainable Packaging is climbing the fastest on compliance-driven substitution.
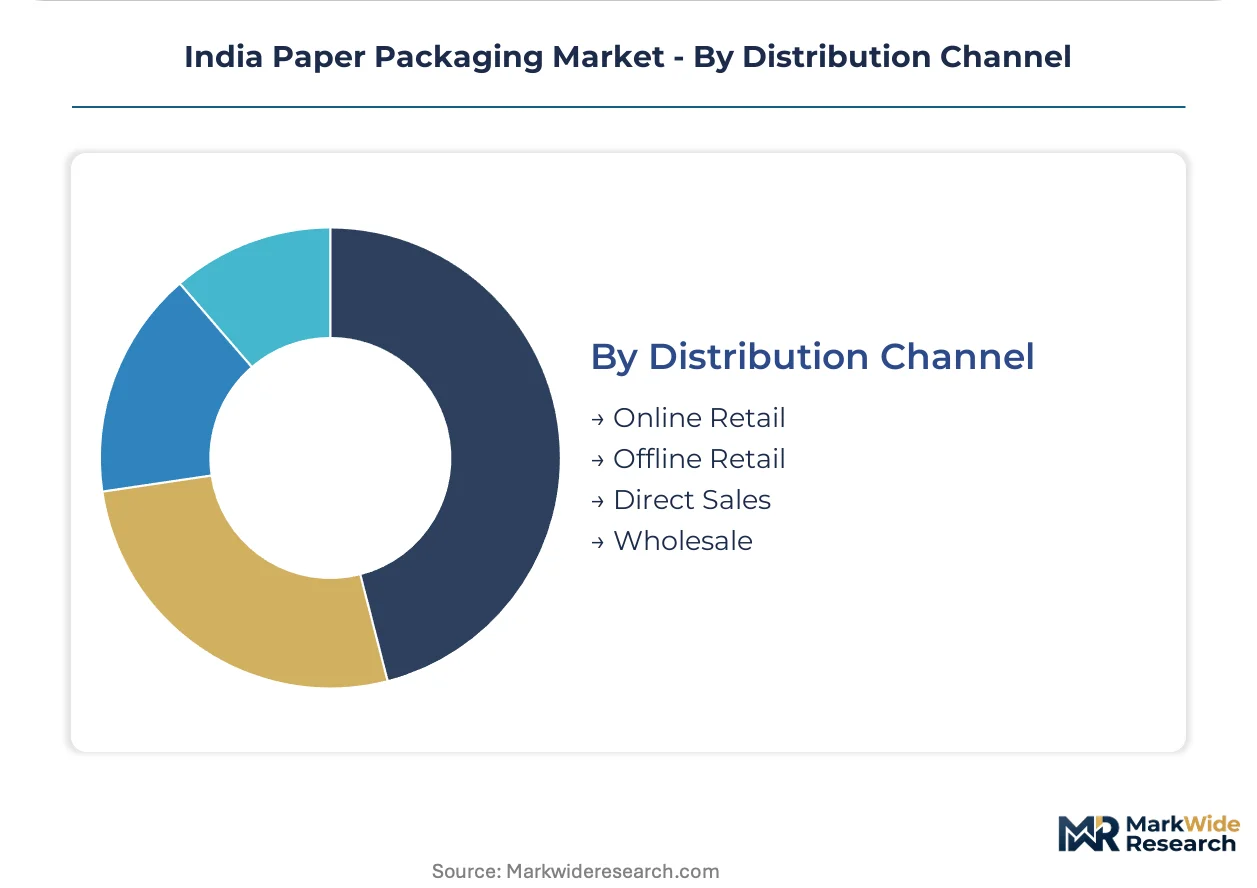
Distribution Channel:
Channel configuration determines converter margin capture and customer relationship depth.
- Direct Sales:Integrated converters maintain dedicated account teams for pharmaceutical and FMCG majors with just-in-time replenishment contracts. Long-term agreements with Swiggy and Zomato consolidate volumes through centralized procurement.
- Wholesale:Regional distributors aggregate fragmented restaurant and retail demand across tier-two cities including Jaipur and Lucknow.
- Online Retail:E-commerce platforms enable mid-tier converters to reach SME brand owners with standardized catalog specifications.
- Offline Retail:Traditional paper merchants stock commodity grades for immediate availability to small print shops and local processors.
Revenue concentration sits with Direct Sales; Wholesale is gaining share fastest on tier-two quick-commerce expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Recovered fiber collection networks in Maharashtra and Gujarat anchor India's containerboard supply base. These western states host integrated pulp-to-board operations that insulate domestic converters from imported OCC volatility. State-level Plastic Waste Management Rule enforcement cells in these regions are accelerating fiber-based substitution timelines.
Maharashtra
Pharmaceutical formulation clusters in Mumbai and Nashik drive folding carton demand with CDSCO serialization requirements. The Maharashtra Pollution Control Board enforces EPR compliance verification most aggressively among Indian states. Pune's quick-commerce hub concentrates insulated corrugated delivery box specifications for platform procurement teams.
Gujarat
Chemical and cement processors in Vadodara and Ahmedabad specify porosity-calibrated kraft sacks for pneumatic filling operations. The state's implementation of BIS food-contact certification protocols qualifies local board grades for F&B migration. Integrated recycled fiber processing plants in Vapi and Ankleshwar achieve scale advantages in containerboard production.
Karnataka
Bengaluru's food delivery aggregator density supports direct converter relationships bypassing traditional distribution tiers. The Karnataka State Pollution Control Board coordinates with Central Pollution Control Board on EPR target enforcement timelines. Electronics manufacturing clusters in the city's outskirts specify molded pulp cushioning for export compliance documentation.
Telangana
Hyderabad's pharmaceutical cartoning demand integrates tamper-evident closures for track-and-trace mandates. The Telangana State Industrial Infrastructure Corporation channels PLI scheme subsidies toward specialty paper capacity upgrades. Mid-size converters deploying digital printing platforms capture just-in-time replenishment contracts from FMCG brand owners.
Delhi-NCR
Quick-commerce platform procurement concentration in Delhi and Gurugram standardizes box sizes across delivery partner networks. The Delhi Pollution Control Committee enforces single-use plastic bans that redirect restaurant packaging volumes toward fiber formats. Noida-based folding carton specialists serve cosmetics and personal care brands with premium finish capabilities.
India Paper Packaging Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital printing and sustainable certification niches. The supplier base stratifies across integrated pulp-to-board operators, specialized folding carton converters, and regional corrugated box fabricators. Three archetypes dominate: fiber self-sufficient integrated mills, quick-commerce-focused insulated box specialists, and pharmaceutical serialization-compliant carton providers. Capacity expansion and backward integration into recovered fiber processing represent the prevailing competitive vectors.
Within the integrated mill tier, JK Paper Ltd exemplifies fiber self-sufficiency through captive pulp operations. Among specialized converters, TCPL Packaging Ltd occupies a position serving pharmaceutical and FMCG majors with folding box solutions. Smurfit WestRock anchors the corrugated containerboard segment through scale advantages in recycled fiber sourcing and box plant automation. These three represent distinct strategic postures across the value chain.
| Leading Market Players |
|---|
| TCPL Packaging Ltd |
| Smurfit WestRock |
| Astron Packaging Ltd |
| TGI Packaging Pvt Ltd |
| Chaitanya Packaging Pvt Ltd |
| Kapco Packaging |
| JK Paper Ltd |
| Horizon Packs Pvt Ltd |
| Parksons Packaging Ltd |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap converters in Maharashtra and Gujarat anchor supply discipline through long-term OCC offtake contracts, insulating board pricing from spot-market volatility while compressing margin capture for non-integrated competitors. This ownership structure concentrates bargaining power with recovered fiber aggregators, forcing smaller fabricators to absorb freight surcharges or cede volume to integrated rivals.
Pricing Analysis
Volume throughput concentrates in commodity corrugated grades where per-unit transactional pricing tracks imported OCC landed costs; premium folding cartons for pharmaceutical serialization command certification-driven markups. Price differentiation hinges on BIS food-contact compliance tier and volume scale, with quick-commerce platforms extracting lowest-unit-cost terms through consolidated procurement. Cost compression in standard-grade containerboard intensifies because integrated mills leverage captive pulp supply, while export-oriented electronics brands show least price sensitivity for EPR-documented sustainable formats.
Supply Chain Analysis
Direct-to-FMCG channels handle hyperscale buyer demand from Swiggy and Zomato procurement teams, bypassing traditional paper merchant tiers. Geographic supply concentrates in India, with secondary fiber processing clusters in Vapi and Ankleshwar drawing from domestic recovered paper networks and imported North American OCC. Raw material dependencies center on old corrugated containers, virgin pulp from JK Paper's integrated mills, and moisture-resistant coating chemicals. Single-source vulnerability runs through containerboard producers tethered to European waste paper exporters facing freight rate volatility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's paper packaging market reads as supply-constrained: skilled die-cutting technician scarcity in legacy Mumbai-Ahmedabad clusters props pricing for qualified converters while constraining greenfield capacity additions.
For Market Incumbents: Hedge against imported fiber cost volatility through backward integration into domestic recovered paper collection networks in Gujarat. Prioritize BIS certification investment for food-contact board grades to capture F&B migration from plastic laminates, defending share against emerging digital-printing specialists in Hyderabad and Pune. For New Entrants and Emerging Players: E-commerce platform partnerships offer the most penetrable route to SME brand owners in tier-two cities including Jaipur and Lucknow. Target insulated corrugated delivery formats for quick-commerce expansion beyond Delhi NCR and Bengaluru, leveraging standardized box specifications to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor pharmaceutical serialization-compliant carton converters in Telangana and Karnataka with embedded authentication capabilities. Long-term viability centers on EPR compliance infrastructure and fiber self-sufficiency; watch Maharashtra Pollution Control Board enforcement intensity as the inflection signal for accelerated fiber-based substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recovered Fiber Processing | Captive OCC supply from Vapi and Ankleshwar mills insulates margin structures from import volatility. |
| Digital Printing Platform Deployment | Inline finishing systems in Pune and Hyderabad capture just-in-time pharmaceutical and cosmetics contracts. |
| BIS Food-Contact Certification Investment | Qualification for FSSAI-mandated board grades opens processed food and quick-commerce procurement channels. |
| Quick-Commerce Direct Supply Agreements | Centralized Swiggy and Zomato procurement in Bengaluru and Delhi NCR displaces fragmented distributor tiers. |
| Pharmaceutical Serialization Integration | CDSCO track-and-trace mandates in Ahmedabad and Hyderabad pull tamper-evident folding carton specifications. |
Research Methodology
Independent corroboration across converter operations directors, brand owner procurement leads, and regulatory compliance officers underwrites the qualitative findings. Primary interviews with paper mill technical managers, quick-commerce supply chain heads, and BIS certification auditors combined with secondary validation from Central Pollution Control Board EPR enforcement circulars, DGFT import data for recovered paper, and state pollution control board implementation timelines. Bottom-up capacity assessments triangulate against top-down demand modeling from end-use sector consumption patterns.
Rate-of-change decomposition separates volume expansion in corrugated boxes from value migration toward sustainable-certified formats across the projection horizon. Segmentation dimensions modeled include product type, end-user industry, packaging format tier, and state-level regulatory enforcement intensity. CAGRs derive from trend extrapolation of fiber substitution rates, quick-commerce platform expansion trajectories, and EPR compliance cost pass-through assumptions. Industry-specific inputs incorporate BIS certification timeline delays and PLI scheme subsidy allocation impacts on specialty paper capacity.
The model holds under steady EPR enforcement trajectories and stable recovered fiber import flows; deviation in Maharashtra Pollution Control Board audit intensity or currency volatility affecting OCC landed costs would shift capacity utilization and pricing assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Germany Honeycomb Paper Market
Paper & Paperboard Packaging
North America Paper Cups Market
Paper & Paperboard Packaging
PE Coated Sack Kraft Paper Market
Paper & Paperboard Packaging
Italy Paper Packaging Market
Paper & Paperboard Packaging
Corrugated Shippers Market
Paper & Paperboard Packaging
Paper Band Market
Paper & Paperboard Packaging
Display Paper Box Market
Paper & Paperboard Packaging
Egypt Paperboard Packaging Market
Paper & Paperboard Packaging
Russia Paper Packaging Market
Paper & Paperboard Packaging
Paper Bubble Wrap Market
Paper & Paperboard Packaging
Bamboo Packaging Market
Paper & Paperboard Packaging
Kitchen Roll Market
Paper & Paperboard Packaging
Foam Cups Market
Paper & Paperboard Packaging
Tacky Transfer Paper Market
Paper & Paperboard Packaging
Canada Paper Packaging Market
Paper & Paperboard Packaging
United States Corrugated Packaging Market