
 Middle East Corrugated Packaging Market | 2026-2036
Middle East Corrugated Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Corrugated Packaging Market Insights
Skilled machine operator availability across Gulf converting plants is redrawing where capacity additions prove viable. Arabian Packaging Co LLC leverages its UAE base to sustain integrated linerboard-to-box operations along the Arabian Gulf coast. United Carton Industries Company (UCIC) anchors Saudi demand through large-format facilities serving dairy and date exporters. Napco National differentiates via food-contact certification depth that controls access to European-bound agri-product shippers.
Middle East corrugated packaging comprises paper-based containerboard products manufactured through flute-profile lamination between linerboard facings and corrugated medium, typically achieving burst strengths of 150–400 lb/in² and edge crush ratings of 23–55 lb/in for stacked-load performance. The primary commercial purpose is protective unitization of goods for distribution, with structural integrity calibrated to palletized shipping and retail-ready display. Kraft paper material grades dominate premium export applications where moisture resistance and printability command margin premiums, while recycled paper feeds price-sensitive domestic routes. E-Commerce end-user demand is accelerating fastest among structural segments, driven by last-mile fulfillment requirements for variable-dimension parcel protection.
Saudi Standards, Metrology and Quality Organization (SASO) and UAE's Emirates Authority for Standardization and Metrology (ESMA) enforce packaging material migration limits and recyclability labeling that shape product qualification for regional consumer goods. Gulf Cooperation Council technical regulations on single-use plastics are redirecting food-service and retail flow-wrap demand toward corrugated substitutes, tightening medium-paper furnish specifications. Stakeholders must monitor how Egypt and Morocco customs alignment with GCC packaging standards could reroute North African export carton sourcing toward Gulf mills.
Market Dynamics
E-commerce fulfillment networks across Saudi Arabia and the UAE are absorbing record containerboard volumes, forcing mills to recalibrate linerboard furnish toward shorter-fiber recycled content while maintaining burst strength specifications for palletized export loads.
Growth Catalysts
- GCC Single-Use Plastic Bans:Gulf Cooperation Council technical regulations redirect food-service packaging demand toward corrugated substitutes, tightening medium-paper specifications and expanding addressable market for food-contact certified converters.
- Jeddah Industrial Corridor Clustering:FMCG distributors concentrate near Red Sea port infrastructure, creating localized demand density that justifies dedicated corrugator investments and shortens finished-goods delivery loops.
- Die-Cut Automation:High-speed rotary die-cutters with servo-controlled registration enable variable-dimension box production for last-mile parcel protection, matching e-commerce SKU fragmentation without tooling changeover delays.
Market Restraints
- Recovered Paper Import Dependency:Domestic OCC collection infrastructure remains underdeveloped across Oman and Bahrain, forcing mills to source furnish from European and Asian export markets with freight cost volatility.
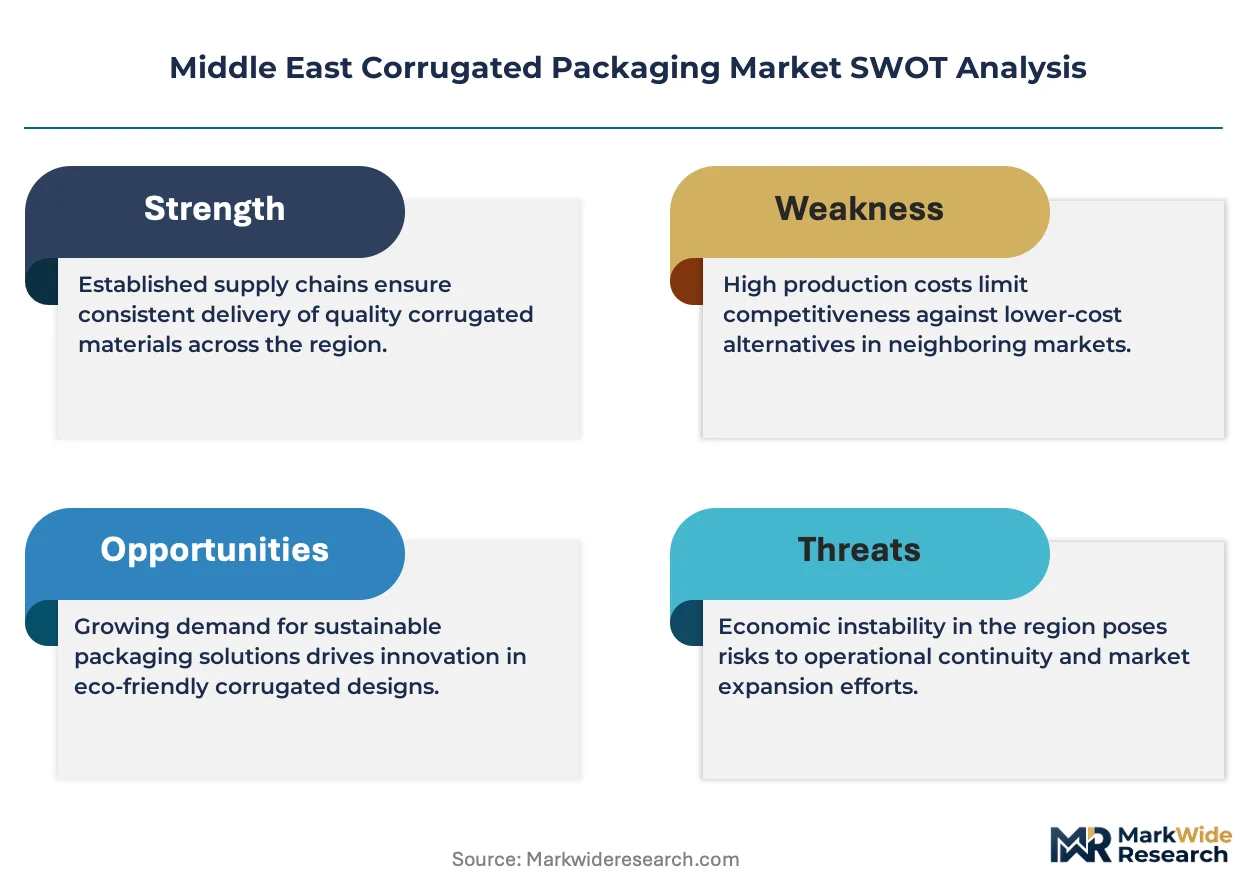
- Natural Gas Price Exposure:Steam generation for corrugator adhesive cooking and linerboard drying ties mill operating costs to regional LNG benchmark pricing, compressing margins during supply contract renegotiations.
- Skilled Operator Scarcity:Gulf converting plants face chronic shortfalls in flexo folder-gluer technicians and die-cut setup specialists, capping achievable machine speeds below rated capacity.
Strategic Opportunities
- Egypt Customs Alignment:Potential harmonization of Egyptian packaging standards with GCC technical regulations could reroute North African export carton sourcing toward Saudi and UAE mills with existing certification depth.
- Agri-Export Cold Chain Integration:European-bound date and dairy shippers demand moisture-resistant corrugated with integrated temperature-monitoring labels, opening premium specification tiers beyond standard RSC containers.
- Digital Print Convergence:Single-pass inkjet integration with existing corrugator lines enables lot-size-one customization for promotional retail-ready packaging, collapsing minimum order thresholds that previously favored offset preprint.
Industry Challenges
- Food-Contact Certification Timelines:SASO and ESMA migration testing protocols for recycled-content linerboard extend qualification cycles by 4-6 months, delaying new product launches for European-bound agricultural exporters.
- Legacy ERP Integration:Converter order-management systems lack native APIs for e-commerce platform connectivity, forcing manual order entry that elevates error rates on variable-dimension SKU configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Corrugated Packaging Market |
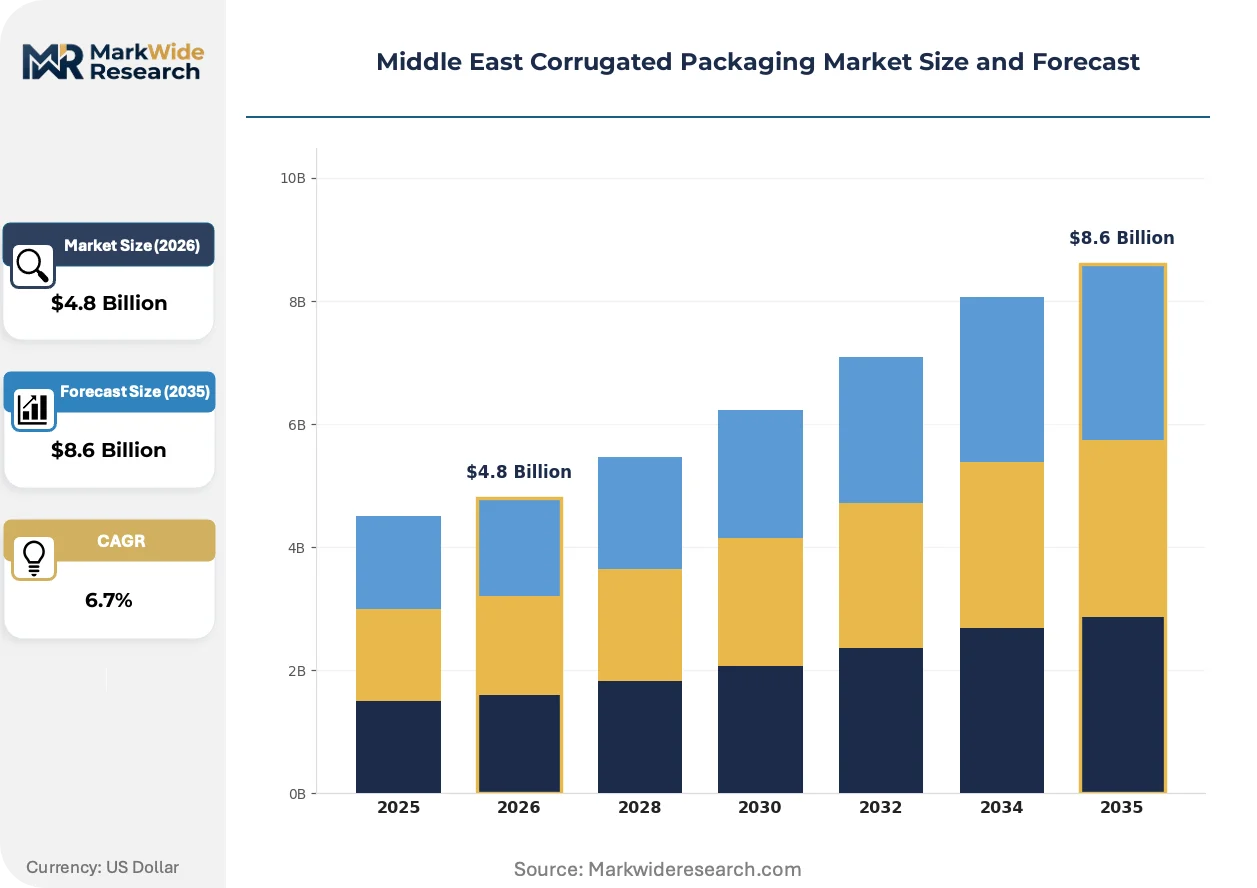
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular Slotted Container, Die-Cut Box, Full-Folding Box, Multi-Depth Box Material: Kraft Paper, Recycled Paper, Linerboard, Medium Paper End User: Food & Beverage, Electronics, Healthcare, E-Commerce Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | Arabian Packaging Co LLC, Queenex Corrugated Carton Factory, United Carton Industries Company (UCIC), Napco National, Falcon Pack, Cepack Group, World Pack Industries LLC, Universal Carton Industries Group, MEPCO (Middle East Paper Manufacturing Company), Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Corrugated Packaging Market Trends and Innovations
Containerboard production technology and regulatory compliance frameworks are diverging sharply between premium export-grade and domestic price-sensitive segments, creating distinct capability requirements that reshape capital allocation priorities.
High-performance linerboard formulations incorporating wet-strength resins and synthetic fiber blends are bifurcating the market between moisture-resistant export specifications and commodity domestic grades. Saudi dairy and date exporters adopt these enhanced boards for European cold-chain shipments, while price-sensitive FMCG distributors in Kuwait and Qatar retain recycled-content alternatives. This technical divergence is compressing mid-tier converter margins as they face simultaneous pressure to certify for export and compete on domestic tender pricing.
ESMA's extended producer responsibility framework for packaging recyclability labeling is tightening material traceability requirements across UAE manufacturing facilities. Industrial consequence includes mandatory batch-level testing for heavy metal content and fiber sourcing documentation. Food-contact certified converters serving European-bound agri-exporters face the most acute compliance burden, accelerating investment in in-house laboratory capabilities.
Direct-to-retailer procurement models are displacing traditional distributor intermediaries in Saudi Arabia's grocery and electronics channels. Hypermarket chains in Riyadh and Dammam now specify corrugated directly with converters, unbundling logistics services previously bundled with packaging supply. This disintermediation concentrates volume with integrated mills capable of JIT delivery, fragmenting residual demand among smaller regional converters.
Middle East Corrugated Packaging Market Segmentation
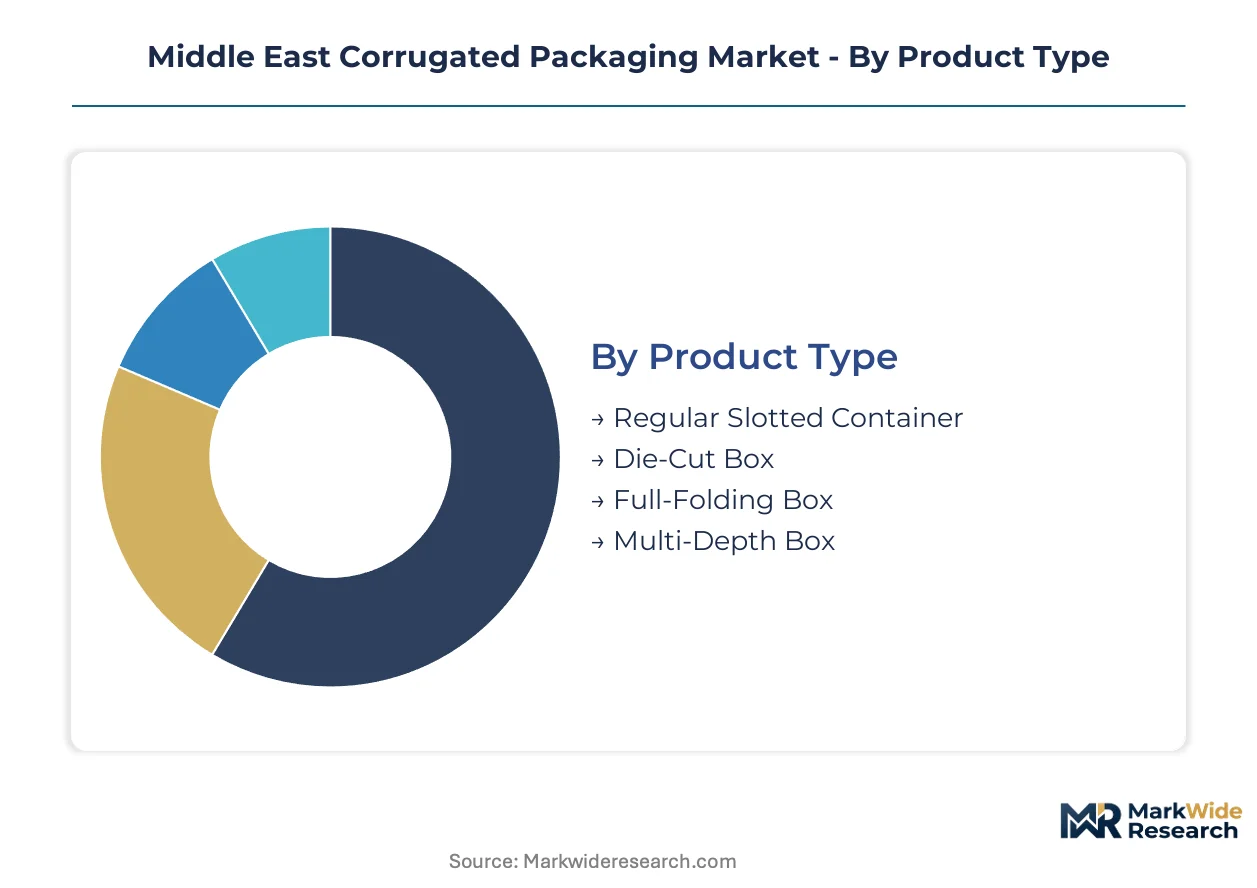
Structural design and material composition choices in Middle East corrugated packaging directly determine qualification for export-grade agricultural shipments versus domestic FMCG distribution. Segment boundaries increasingly reflect certification depth rather than simple functional performance, with SASO and ESMA compliance timelines creating tiered market access.
Product Type:
Regular slotted containers dominate Red Sea port corridors serving European-bound bulk exports, while die-cut formats concentrate in Dubai's e-commerce fulfillment zones handling variable-dimension parcel flows.
- Regular Slotted Container:Standard four-flap design with manufacturer's joint construction achieves burst strengths of 200–350 lb/in² for palletized stacking. Jeddah's dairy and date exporters specify RSC formats for European cold-chain shipments, with SASO migration testing extending qualification cycles. The established base commands volume concentration near industrial port infrastructure.
- Die-Cut Box:Rotary die-cut production with servo-controlled registration enables lot-size-one customization without tooling changeovers. Dubai and Riyadh e-commerce fulfillment networks absorb record volumes for last-mile parcel protection, matching SKU fragmentation with variable-dimension outputs. The steepest expansion runs through this segment.
- Full-Folding Box:Single-piece construction with integrated lid and base suits retail-ready display requirements for hypermarket chains in Riyadh and Dammam.
- Multi-Depth Box:Scored height adjustment reduces void fill requirements for mixed-SKU shipments, gaining traction among 3PL operators serving Saudi grocery distributors.
Regular slotted containers command the established base. The steepest expansion runs through die-cut formats.
Material:
Cost tier separation between premium export specifications and domestic commodity grades drives mill furnish decisions, with wet-strength resin formulations commanding margin premiums for agri-exporters.
- Kraft Paper:Virgin fiber construction delivers moisture resistance and superior printability for European-bound cold-chain shipments. Saudi dairy exporters specify kraft linerboard for temperature-monitored date and dairy distribution, with integrated labels tracking shipment integrity. Premium positioning reflects certification depth rather than fiber cost alone.
- Recycled Paper:Shorter-fiber furnish from OCC streams feeds price-sensitive domestic FMCG routes in Kuwait and Qatar. ESMA's extended producer responsibility framework mandates batch-level heavy metal testing and fiber sourcing documentation, compressing margins for uncertified converters. Domestic price competition intensifies qualification burdens.
- Linerboard:Outer facings determine burst strength and print surface quality, with mills reformulating recipes under GCC recycled-content mandates.
- Medium Paper:Corrugated inner fluting provides cushioning and stacking strength, with specifications tightening under food-contact certification protocols.
Kraft paper commands the established base. The steepest expansion runs through certified recycled-content grades.
End User:
Application-specific performance requirements create divergent certification pathways, with food-contact protocols consuming converter laboratory capacity and technical resources.
- Food & Beverage:Moisture-resistant corrugated with integrated temperature-monitoring labels serves European-bound date and dairy exporters. SASO migration testing for recycled-content linerboard extends qualification cycles, concentrating volume with integrated mills possessing in-house laboratory capabilities.
- E-Commerce:Variable-dimension parcel protection demands high-speed rotary die-cutters with servo-controlled registration. Last-mile fulfillment networks across Saudi Arabia and the UAE absorb record containerboard volumes, forcing mills to recalibrate furnish toward shorter-fiber recycled content while maintaining burst specifications. Digital print convergence enables lot-size-one promotional customization.
- Electronics:Anti-static coatings and precision-fit die-cut inserts protect high-value consumer devices distributed through Dubai's electronics channels.
- Healthcare:Sterile barrier compatibility and tamper-evident closure specifications govern pharmaceutical distribution packaging requirements.
Food and beverage commands the established base. The steepest expansion runs through e-commerce fulfillment.
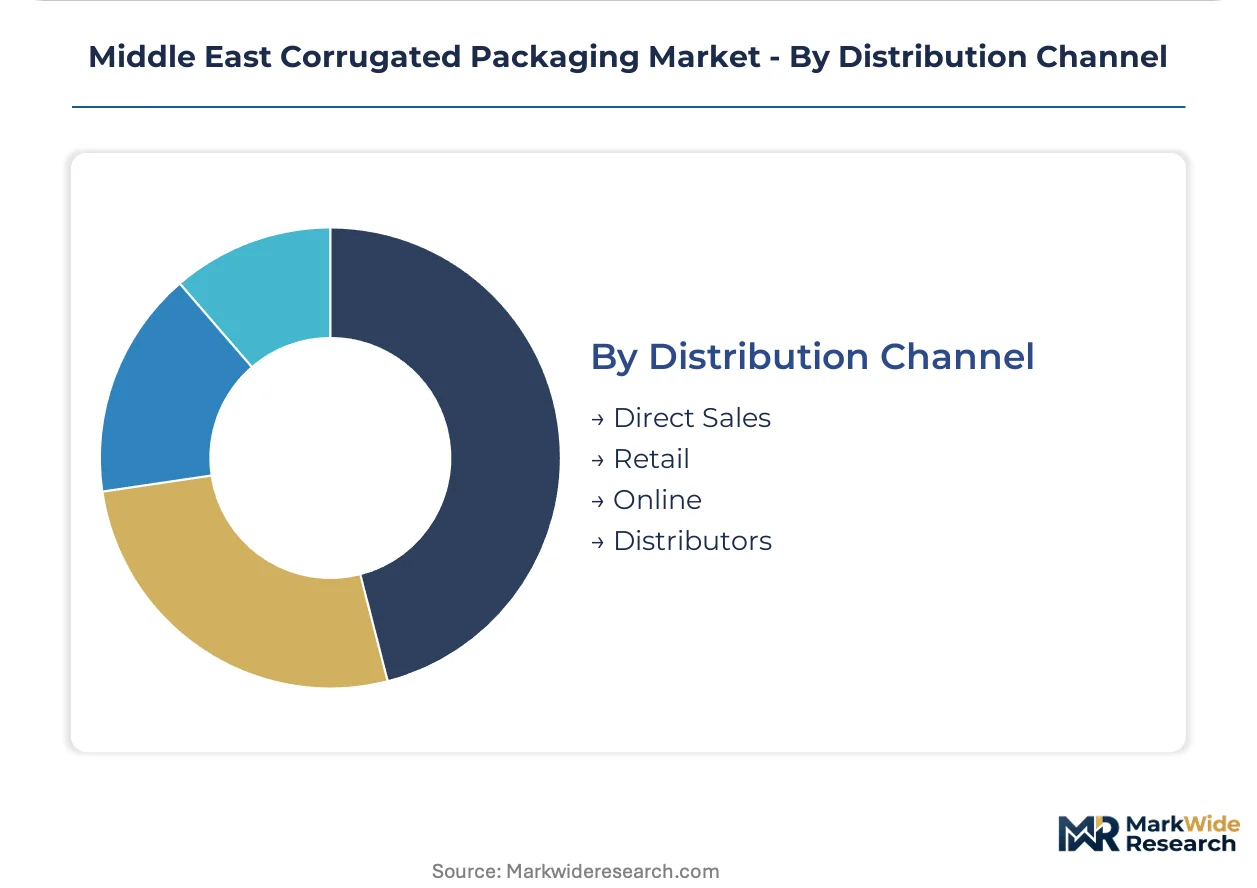
Distribution Channel:
Customer-type concentration determines order management complexity, with direct procurement models displacing traditional intermediaries and fragmenting residual demand.
- Direct Sales:Hypermarket chains in Riyadh and Dammam now specify corrugated directly with converters, unbundling logistics services previously bundled with packaging supply. JIT delivery requirements concentrate volume with integrated mills capable of short-lead production.
- Distributors:Traditional intermediaries retain relevance for smaller regional converters lacking ERP integration with e-commerce platforms, though manual order entry elevates error rates on variable-dimension configurations.
- Retail:Brick-and-mortar procurement flows through established trading relationships serving Kuwait and Qatar price-sensitive segments.
- Online:Digital platforms enable spot purchasing for emergency replenishment, though legacy converter systems lack native APIs for automated connectivity.
Direct sales commands the established base. The steepest expansion runs through disintermediated procurement models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across the Middle East corrugated packaging landscape. Saudi Arabia and the UAE absorb premium export-grade specifications for European-bound agricultural shipments, while Kuwait and Qatar sustain price-sensitive domestic FMCG routes on recycled-content alternatives.
Saudi Arabia
Jeddah's industrial corridor concentrates dairy and date exporter demand near Red Sea port infrastructure. SASO enforces packaging material migration limits and recyclability labeling that shape product qualification for regional consumer goods. Riyadh and Dammam hypermarket chains now specify corrugated directly with converters, unbundling logistics services previously bundled with packaging supply.
United Arab Emirates
Dubai's e-commerce fulfillment networks absorb record volumes of die-cut containers for last-mile parcel protection. ESMA's extended producer responsibility framework mandates batch-level heavy metal testing and fiber sourcing documentation across manufacturing facilities. Abu Dhabi-based integrated mills sustain captive linerboard-to-box operations along the Arabian Gulf coast.
Kuwait
Domestic FMCG distributors retain price-sensitive procurement patterns favoring recycled-content alternatives over virgin kraft specifications. The country's environmental authority aligns technical regulations with broader GCC single-use plastic bans redirecting food-service demand toward corrugated substitutes. Industrial activity clusters near Shuwaikh Port logistics corridors serving regional trade routes.
Qatar
Construction and retail distribution sustain steady containerboard absorption for commodity-grade applications. National standardization frameworks mirror GCC technical regulations on packaging recyclability and food-contact certification. Doha metropolitan warehousing zones concentrate converter capacity serving domestic grocery and electronics channels.
Egypt
North African agricultural exporters represent latent demand for Gulf-certified corrugated if customs alignment with GCC standards materializes. The country's national standards body maintains parallel technical requirements that could harmonize with Gulf regulations. Alexandria and Damietta port zones currently source carton requirements from domestic mills but remain exposed to sourcing redirection.
Middle East Corrugated Packaging Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Middle East corrugated packaging. Arabian Packaging Co LLC and United Carton Industries Company anchor the upper tier through captive linerboard supply and large-format converting capacity. The specialist tier comprises regional converters competing on food-contact certification depth and e-commerce fulfillment speed. Competitive moves concentrate on backward integration into medium-paper furnish and geographic expansion toward Egyptian export corridors.
Within the integrated tier, Arabian Packaging Co LLC exemplifies UAE-based coastal operations with captive supply chains. United Carton Industries Company occupies a position serving Saudi dairy and date export demand through scale-driven facilities. Napco National represents the certification-specialist archetype, anchoring food-contact depth that controls access to European-bound agricultural shippers.
| Leading Market Players |
|---|
| Arabian Packaging Co LLC |
| Queenex Corrugated Carton Factory |
| United Carton Industries Company (UCIC) |
| Napco National |
| Falcon Pack |
| Cepack Group |
| World Pack Industries LLC |
| Universal Carton Industries Group |
| MEPCO (Middle East Paper Manufacturing Company) |
| Others |
Pricing and Supply Chain Analysis
Sixty-day linerboard inventory cycles at Jeddah's integrated mills compress spot-market exposure for Saudi dairy exporters while amplifying price leverage over Kuwaiti distributors lacking captive furnish. This inventory asymmetry stratifies contract structures across the Red Sea corridor.
Pricing Analysis
Long-term offtake agreements dominate Saudi and UAE mill relationships with European-bound agri-exporters, locking in kraft linerboard premiums through SASO-certified migration testing. Price differentiation hinges on food-contact certification depth and volume scale, with integrated players commanding margin premiums over regional converters. Cost compression in recycled-content grades is intensifying because ESMA's batch-level heavy metal testing extends qualification timelines. Domestic FMCG distributors in Kuwait and Qatar exhibit highest price sensitivity, while cold-chain exporters absorb premium specifications.
Supply Chain Analysis
Red Sea port congestion and container availability fluctuations on Asia-Gulf trade lanes elevate inbound logistics costs for Omani and Bahraini mills sourcing OCC from European export markets. Supply concentration centers on Saudi Arabia, the UAE, and Egypt, with domestic collection infrastructure gaps forcing dependence on imported recovered paper. Raw material flows draw from European OCC streams, Asian kraft pulp shipments, and regional natural gas for adhesive cooking. Single-source vulnerability to LNG benchmark pricing compresses margins during contract renegotiations. Distribution runs through direct procurement channels displacing traditional intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East corrugated packaging market is recovering from cyclical lows as GCC single-use plastic bans redirect food-service demand toward corrugated substitutes, resetting baseline absorption rates.
For Market Incumbents: Fortify backward integration into medium-paper furnish to offset recovered paper import dependency volatility. Arabian Packaging Co LLC and United Carton Industries Company should expand in-house laboratory capabilities to compress SASO migration testing timelines. Certification depth remains the critical lever against emerging Egyptian competition should customs alignment with GCC standards materialize.
For New Entrants and Emerging Players: Lead with die-cut automation targeting Dubai's e-commerce fulfillment networks where SKU fragmentation outpaces incumbent capacity. Egypt represents the most penetrable geography pending regulatory harmonization. A digital-print convergence go-to-market angle collapses minimum order thresholds that previously favored offset preprint incumbents.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates holding non-core packaging assets lacking food-contact certification infrastructure. Long-term viability across the next decade rests on compliance depth rather than scale alone. The signal to watch is Egyptian customs alignment with GCC technical regulations, which would reroute North African export carton sourcing toward certified Gulf mills.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Medium-Paper Furnish | Captive supply from OCC streams insulates Saudi mills from European export market freight volatility. |
| Food-Contact Certification Investment | In-house SASO migration testing laboratories compress qualification cycles for European-bound date exporters. |
| Die-Cut Automation Deployment | Servo-controlled rotary die-cutters enable lot-size-one production for Dubai e-commerce fulfillment networks. |
| Digital Print Convergence | Single-pass inkjet integration collapses minimum order thresholds favoring offset preprint competitors. |
| Egyptian Market Entry Preparation | Regulatory harmonization with GCC standards would unlock North African agri-export carton demand redirection. |
Research Methodology
The analysis maps linerboard production tiers, converting capacity clusters, and certification-specialist segments, each validated through corrugator plant managers, FMCG procurement directors, and food-contact laboratory heads. Primary interviews with ESMA compliance officers and SASO technical committee members combined with secondary validation from GCC customs trade data, Saudi industrial production indices, and UAE manufacturing facility registrations. Bottom-up mill capacity modeling triangulates against top-down end-use consumption estimates across dairy, date, and e-commerce channels.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product type, material grade tier, end-use application, and distribution channel dimensions. CAGRs were derived from regression analysis of historical linerboard absorption rates and e-commerce parcel volume trajectories. Forecast inputs incorporated natural gas price sensitivity coefficients and recycled-content mandate compliance cost curves.
Forecasts assume regulatory continuity in SASO and ESMA frameworks; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Global Sack Kraft Paper Market
Paper & Paperboard Packaging
Desiccant Paper Market
Paper & Paperboard Packaging
Beverage Filter Paper Market
Paper & Paperboard Packaging
Paper Edge Protectors Market
Paper & Paperboard Packaging
Europe Mailer Packaging Market
Paper & Paperboard Packaging
Paper Coaster Market
Paper & Paperboard Packaging
Coated Duplex Board Market
Paper & Paperboard Packaging
Micro Flute Paper Market
Paper & Paperboard Packaging
Asia-Pacific Coated Paper Market
Paper & Paperboard Packaging
India Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Global Multi Depth Corrugated Boxes Market
Paper & Paperboard Packaging
Global Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Paperboard Packaging Market
Paper & Paperboard Packaging
Paper Cup Machine Market
Paper & Paperboard Packaging
Paper Bubble Wrap Market
Paper & Paperboard Packaging
Kitchen Roll Market