
 Desiccant Paper Market | 2026-2036
Desiccant Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Desiccant Paper Market Outlook
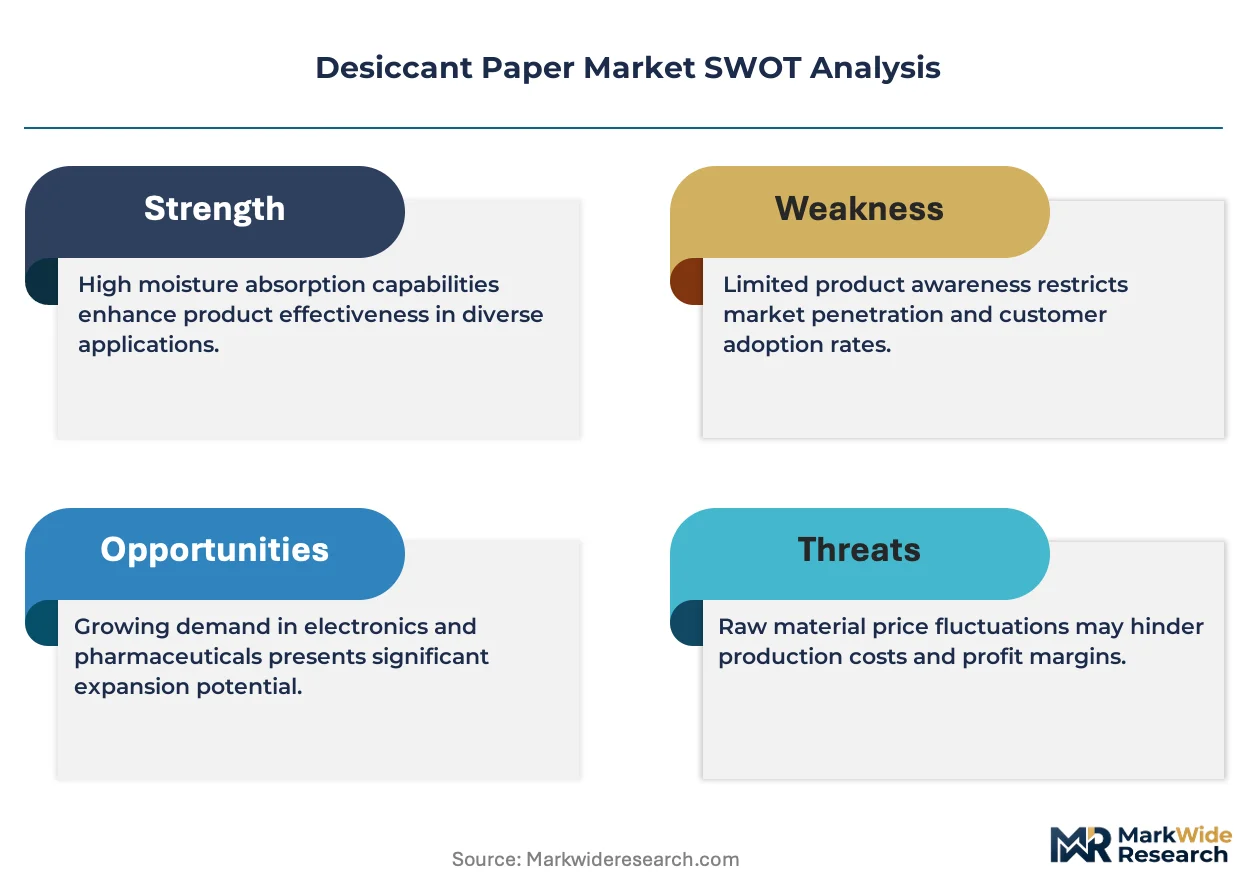
Multi-source procurement among desiccant paper buyers is consolidating toward fewer qualified suppliers with certified manufacturing capabilities. Clariant leverages its integrated silica gel production network to secure raw material continuity across European pharmaceutical accounts. Multisorb Technologies competes through specialized sachet assembly lines that serve electronics OEMs in Asia-Pacific. AGM Container Controls anchors military and aerospace demand with MIL-SPEC compliant desiccant solutions.
Desiccant paper comprises cellulose substrates impregnated with hygroscopic agents such as silica gel or clay, engineered to maintain equilibrium relative humidity below critical thresholds in sealed enclosures. The material typically achieves moisture adsorption capacities ranging from 15% to 35% by weight depending on active agent loading and substrate porosity. Silica gel-based formulations command premium positioning in pharmaceutical and electronics applications where ultra-low humidity maintenance is non-negotiable. Sachet packaging dominates unit volume through standardized dispensing compatibility with automated packaging lines, while bulk formats serve industrial drying operations with lower per-unit cost structures.
FDA compliance requirements for drug contact materials and EU REACH chemical registration obligations shape formulation choices and supplier qualification protocols in this market. EPA oversight of silica dust exposure limits additionally influences manufacturing facility design and worker safety investments in North American production sites. Stakeholders must monitor evolving pharmaceutical serialization mandates and food contact material migrations as these regulatory layers increasingly dictate specification sheets and procurement criteria.
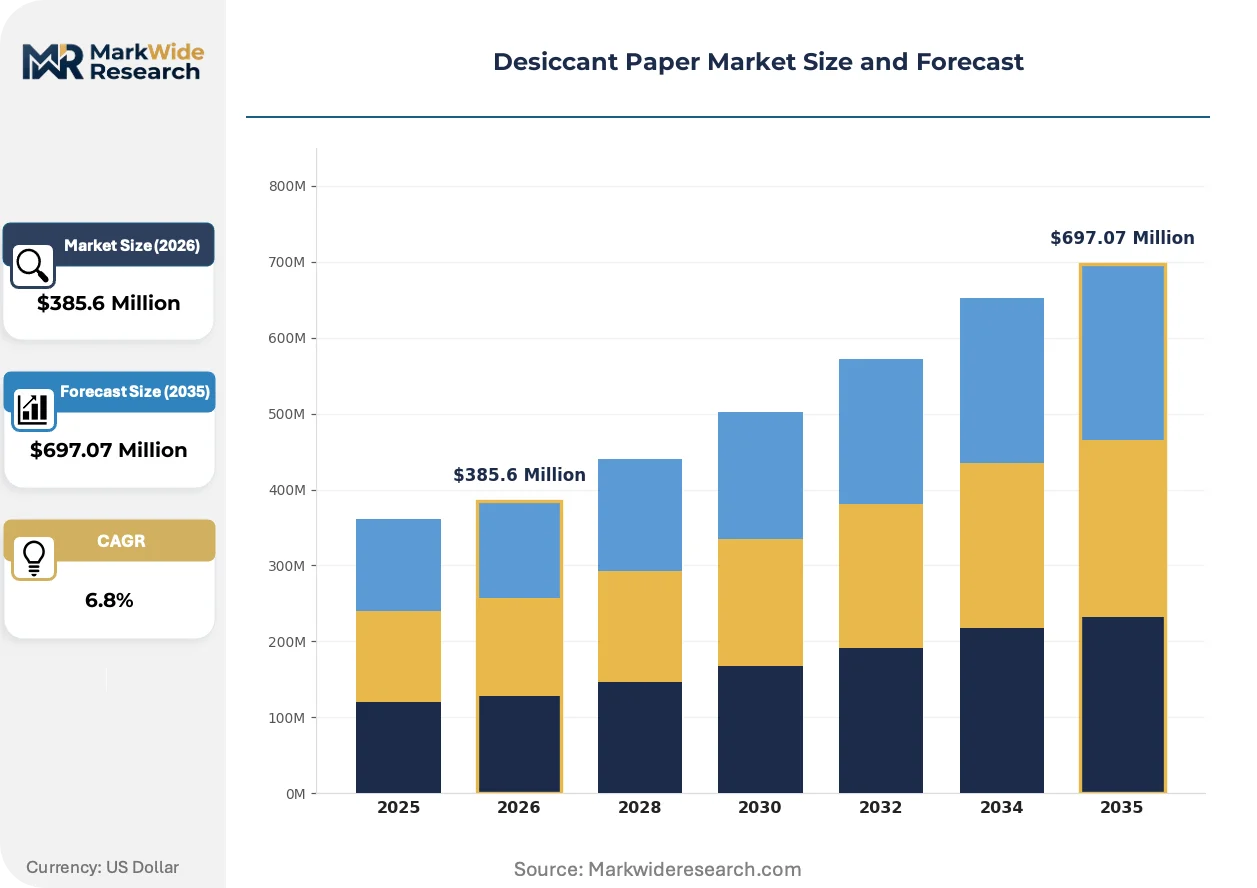
Market Dynamics
Pharmaceutical serialization mandates and EU F-Gas Regulation tightening are forcing desiccant paper suppliers to requalify formulations and manufacturing footprints simultaneously, compressing supplier bases while elevating certified capacity premiums.
Growth Catalysts
- EU F-Gas Regulation:Tightened absorbent material specifications across member states are disqualifying legacy clay-based formulations, pulling demand toward certified silica gel-impregnated substrates in Germany's industrial corridor.
- Pharmaceutical packaging automation:High-speed sachet dispensing lines at drug manufacturers require standardized desiccant paper roll formats, embedding volume commitments with qualified suppliers.
- Electronics OEM humidity control:Semiconductor and battery producers in Asia-Pacific are specifying ultra-low equilibrium relative humidity thresholds below 10% RH, filtering supplier pools to silica gel specialists.
Market Restraints
- Silica gel feedstock concentration:Synthetic amorphous silica production clusters in China's coastal provinces, exposing European and North American converters to shipping cost volatility and tariff exposure.
- Cellulose substrate energy intensity:Kraft pulp drying and calendering operations face natural gas price spikes, compressing margins for non-integrated converters without captive paper mills.
- Clay desiccant performance ceiling:Montmorillonite clay achieves maximum 25% by weight adsorption capacity versus 35% for silica gel, locking clay-based papers out of pharmaceutical stability applications.
Strategic Opportunities
- India pharmaceutical packaging:CDSCO serialization mandates and expanding domestic generic drug production are creating first-mover advantages for suppliers establishing BIS-certified converting capacity near Mumbai and Hyderabad.
- Biologics cold chain:Temperature-sensitive monoclonal antibody shipments require desiccant paper with validated performance across -20°C to +25°C ranges, a specification gap few competitors have filled.
- Reusable sachet formats:Industrial end-users in Japan are piloting regenerable desiccant paper cartridges for cleanroom applications, shifting procurement from disposable units toward service-based models.
Industry Challenges
- FDA drug master file timelines:Type III DMF submissions for desiccant paper as a drug contact material require 18-24 month review cycles, freezing supplier switching decisions during qualification.
- Multi-site audit coordination:Pharmaceutical buyers now mandate simultaneous ISO 15378 and EXCIPACT certification across all production facilities, complicating capacity expansion for regional converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Desiccant Paper Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $697.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silica Gel, Clay, Molecular Sieves, Activated Carbon Application: Pharmaceuticals, Food Packaging, Electronics, Textiles End User: Manufacturers, Distributors, Retailers, Consumers Packaging Type: Bulk, Sachets, Pouches, Tubs |
| Companies Covered | Clariant, Absortech, Desiccare, Valdamark Ltd, Grace Davison, AGM Container Controls, Multisorb Technologies, Solvay, IMPAK Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Desiccant Paper Market Strategic Shifts
Active agent loading precision and substrate engineering are converging to create application-specific desiccant paper grades, displacing generic multi-purpose formulations across regulated end-uses.
Silica gel microencapsulation within cellulose fiber matrices is overtaking surface-impregnation methods in pharmaceutical applications. This technology embeds hygroscopic particles within fiber walls rather than coating surfaces, eliminating dusting risks that trigger EPA silica exposure violations. European drug packagers are specifying microencapsulated grades exclusively, compressing demand for conventional impregnated papers in FDA-regulated applications.
EU REACH Annex XIV authorization requirements for cobalt dichloride indicator dyes are forcing reformulation of humidity-indicating desiccant papers. The ECHA sunset date for unrestricted cobalt use is compelling suppliers to validate alternative organic indicators that shift color across equivalent RH thresholds. Electronics OEMs in Germany are accelerating qualification of cobalt-free indicating papers ahead of regulatory deadlines, creating temporary dual-sourcing complexity.
Consolidated procurement desks at multinational pharmaceutical companies are compressing supplier panels from six to two qualified vendors per region. This concentration is displacing spot-market purchasing with multi-year master service agreements that bundle desiccant paper supply with sachet converting and logistics. The shift is most visible in North America, where three major generic drug manufacturers have consolidated humidity-control spend under single-source arrangements since 2023.
Desiccant Paper Market Segmentation
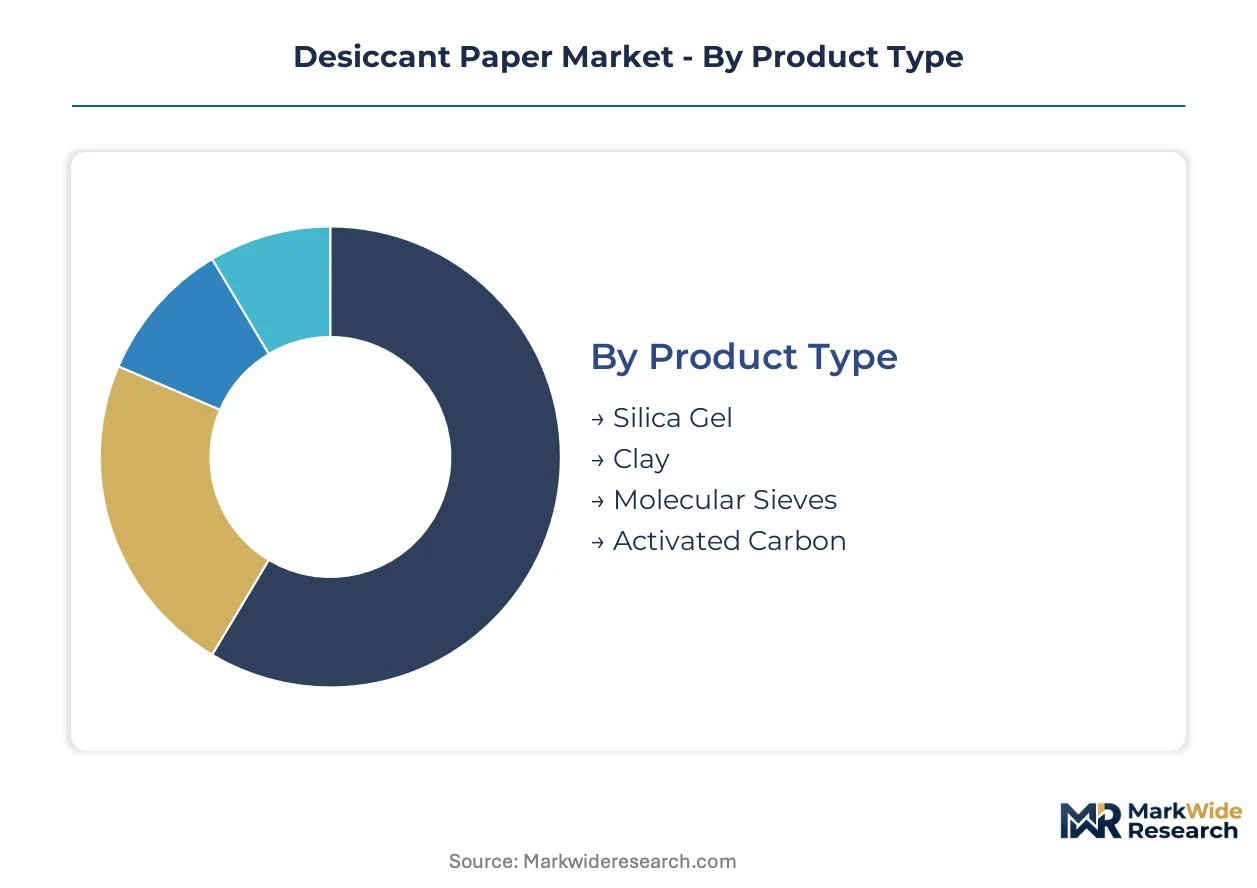
Desiccant paper specifications diverge sharply across end-use certifications, with pharmaceutical applications demanding FDA Type III drug master files while industrial buyers prioritize cost-per-adsorption metrics. Segmentation strategy must align active agent selection with regulatory burden and automation compatibility.
Product Type:
FDA drug master file requirements and EU REACH chemical registrations create tiered certification burdens that filter supplier pools differently across each active agent category.
- Silica Gel:Synthetic amorphous silica achieves 35% by weight moisture adsorption capacity through microporous structure engineering. Pharmaceutical packagers in Germany's industrial corridor specify microencapsulated silica gel grades exclusively to eliminate EPA silica dust exposure risks during high-speed sachet dispensing.
- Clay:Montmorillonite-based formulations derived from bentonite deposits cap at 25% adsorption capacity, locking clay papers out of ultra-low humidity applications. Food packaging converters in France leverage clay's natural mineral status to bypass EFSA novel food additive assessments, securing cost advantages in dried fruit and nut applications.
- Molecular Sieves:Zeolite crystalline structures with precisely engineered pore diameters target equilibrium relative humidity below 5% RH for lithium-ion battery cell packaging.
- Activated Carbon:Hybrid desiccant-odor control papers combine moisture adsorption with volatile organic compound scavenging for premium electronics and leather goods applications.
Silica gel sits at the top of the volume ranking, with molecular sieves climbing the fastest on battery supply chain demand.
Application:
End-use automation intensity and serialization mandates reshape procurement patterns across pharmaceutical, food, electronics, and textile verticals.
- Pharmaceuticals:CDSCO serialization mandates in India and FDA drug master file requirements in the US impose 18-24 month qualification timelines that freeze supplier switching decisions. High-speed blister packaging lines at generic drug manufacturers in Mumbai and Hyderabad specify standardized roll formats that embed multi-year volume commitments with qualified converters.
- Electronics:Semiconductor fabs in South Korea and battery producers in Japan specify equilibrium relative humidity thresholds below 10% RH, filtering supplier pools to silica gel and molecular sieve specialists with validated cleanroom compatibility.
- Food Packaging:Dried fruit, coffee, and spice applications prioritize clay-based papers for cost efficiency where moisture sensitivity permits higher equilibrium humidity levels.
- Textiles:Garment export logistics and leather goods storage use bulk-format desiccant paper for container desiccation with minimal per-unit cost structures.
Pharmaceuticals commands the largest revenue share, while electronics gains share fastest on humidity control specification tightening.
End User:
Procurement sophistication and technical specification authority concentrate differently across the value chain from raw material converters to final consumers.
- Manufacturers:Pharmaceutical and electronics OEMs deploy consolidated procurement desks that compress supplier panels from six to two qualified vendors per region, displacing spot-market purchasing with multi-year master service agreements bundling desiccant paper supply with sachet converting and logistics.
- Distributors:Industrial supply houses and packaging material distributors stock standardized sachet formats for mid-volume buyers lacking direct supplier qualification resources.
- Retailers:Private-label dried food brands and consumer electronics retailers specify desiccant paper indirectly through co-manufacturer agreements.
- Consumers:Direct-to-consumer regenerable desiccant cartridges for gun safes and storage applications represent a niche service-based model piloted in Japan.
Manufacturers dominate procurement volume, with distributors expanding fastest on small and mid-tier customer aggregation.
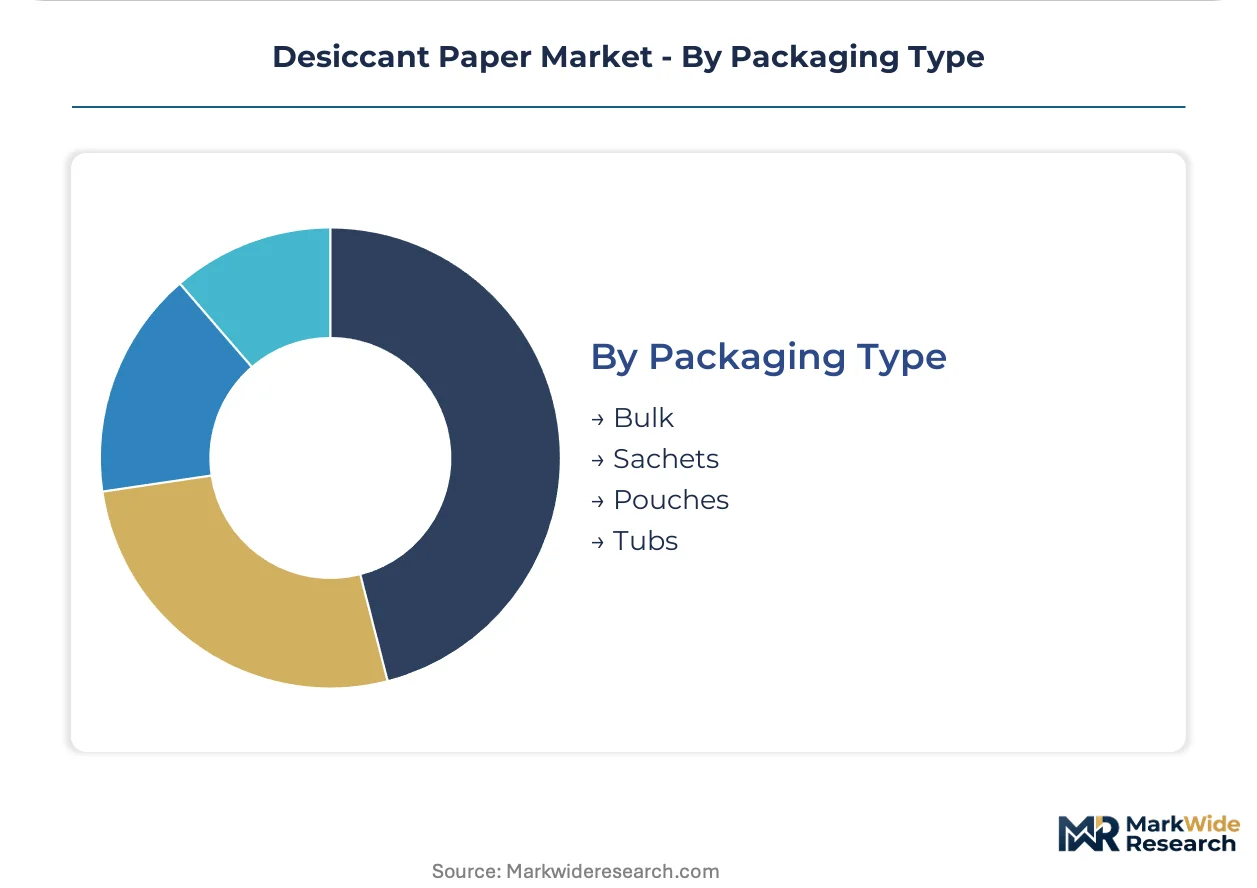
Packaging Type:
Automation compatibility and logistics economics drive format selection across bulk industrial, unitized sachet, flexible pouch, and rigid tub configurations.
- Sachets:Standardized paper sachets with heat-sealed edges dominate pharmaceutical and electronics unit volume through compatibility with automated dispensing systems running at 600+ units per minute. Roll-fed formats with precise width tolerances embed volume commitments with qualified suppliers.
- Bulk:Uncut roll stock and sheet formats serve industrial drying operations and container desiccation with lowest per-kilogram cost structures, though requiring manual handling incompatible with pharmaceutical automation.
- Pouches:Stand-up and flat pouch formats with integrated desiccant paper layers target premium food and consumer electronics applications requiring resealability.
- Tubs:Rigid plastic containers with desiccant paper inserts serve diagnostic test kit and medical device applications requiring repeated access with maintained humidity control.
Sachets leads absolute volume, with pouches expanding most quickly on premium food and electronics packaging convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial corridor anchors pharmaceutical and precision manufacturing demand for certified desiccant substrates. Regulatory tightening across multiple jurisdictions is reshaping supplier qualification requirements and procurement patterns.
United States
Pharmaceutical serialization mandates and FDA drug master file requirements drive specification rigor for moisture-control materials. EPA silica dust exposure limits influence manufacturing facility investments and worker safety protocols at converting sites. Generic drug manufacturers in New Jersey and North Carolina embed multi-year volume commitments with qualified suppliers.
Germany
EU F-Gas Regulation tightening pulls demand toward certified silica gel-impregnated substrates for high-precision humidity control. ECHA REACH chemical registration obligations shape formulation choices and supplier qualification protocols. Electronics OEMs in Bavaria and pharmaceutical packagers in Baden-Württemberg specify microencapsulated grades exclusively.
China
Synthetic amorphous silica production clusters in coastal provinces supply feedstock to converters serving domestic electronics and export pharmaceutical markets. NMPA pharmaceutical packaging regulations and dual carbon goals influence facility upgrade timelines. Semiconductor fabs in Shanghai and battery producers in Shenzhen specify ultra-low equilibrium relative humidity thresholds.
India
CDSCO serialization mandates and expanding domestic generic drug production create qualification opportunities for BIS-certified converters. Pharmaceutical packaging lines in Mumbai and Hyderabad require standardized roll formats compatible with high-speed automated dispensing. Dried fruit and spice exporters in Gujarat leverage clay-based papers for cost-efficient moisture control.
Japan
Industrial end-users pilot regenerable desiccant paper cartridges for cleanroom applications, shifting procurement toward service-based models. METI industrial standards and PMDA pharmaceutical regulations govern material specifications. Electronics manufacturers in the Kanto region and automotive suppliers in Aichi Prefecture drive humidity control specification tightening.
Desiccant Paper Market Competitive Environment
Global majors compete with regional champions across certification depth and manufacturing integration levels. The supplier base compresses toward fewer qualified vendors as pharmaceutical buyers consolidate procurement panels from six to two per region. Three archetypes dominate: integrated silica gel producers with captive paper converting, specialized sachet assemblers serving automated packaging lines, and military-aerospace specialists with MIL-SPEC compliance. Capacity expansion and strategic partnerships represent the dominant competitive vectors as players secure raw material continuity and regional certification coverage.
Within the integrated production tier, Clariant leverages its silica gel manufacturing network to anchor supply continuity across European pharmaceutical accounts. Multisorb Technologies occupies a position among specialized sachet converters serving high-volume automated dispensing requirements. AGM Container Controls exemplifies the compliance-intensive segment with military and aerospace certification focus.
| Leading Market Players |
|---|
| Clariant |
| Absortech |
| Desiccare |
| Valdamark Ltd |
| Grace Davison |
| AGM Container Controls |
| Multisorb Technologies |
| Solvay |
| IMPAK Corporation |
| Others |
Value Chain & Pricing Dynamics
Pharmaceutical procurement desk consolidation from six vendors to two per region is compressing supplier panels and embedding multi-year master service agreements that bundle desiccant paper with converting and logistics, forcing non-integrated converters to absorb cellulose substrate cost volatility or exit certified tiers.
Pricing Analysis
Input-cost pass-through from kraft pulp drying and synthetic amorphous silica feedstock dominates pricing dynamics, with natural gas price spikes at European paper mills compressing margins for converters lacking captive production. Three-tier pricing structure across FDA-certified pharmaceutical grades, industrial silica gel formulations, and economy clay-based papers reflects certification burden and automation compatibility. Cost compression in industrial tiers is intensifying because clay-based papers face performance ceilings that lock them out of pharmaceutical stability applications. Generic drug manufacturers in India exhibit highest price sensitivity, while semiconductor fabs in South Korea accept premiums for validated sub-10% RH equilibrium specifications.
Supply Chain Analysis
Freight cost exposure from China's coastal synthetic amorphous silica production clusters to European and North American converting sites is elevating landed costs and accelerating regional feedstock qualification efforts. The supply chain draws from China for silica gel feedstock, Germany for precision converting equipment, and India for expanding pharmaceutical packaging capacity. Single-source vulnerability concentrates in coastal Chinese silica production exposed to shipping cost volatility and tariff exposure. Distribution runs through pharmaceutical OEM direct procurement for high-volume accounts, with industrial supply houses aggregating mid-tier demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU F-Gas Regulation tightening against India's CDSCO serialization rollout creates a geographic-arbitrage window where certified capacity investments in South Asia capture cost advantages while maintaining European regulatory equivalence.
For Market Incumbents: Anticipate procurement desk consolidation by securing simultaneous ISO 15378 and EXCIPACT certification across all production facilities before buyer mandates freeze supplier switching decisions. Defend position by deepening backward integration into silica gel production to anchor raw material continuity when Chinese feedstock faces logistics disruption. Certification investment represents the critical lever as 18-24 month FDA drug master file timelines create switching friction. For New Entrants and Emerging Players: Launch via BIS-certified converting partnerships near Mumbai and Hyderabad to capture CDSCO-mandated pharmaceutical serialization demand before incumbent capacity expansion saturates the market. Target biologics cold chain applications where temperature-validated desiccant paper specifications remain unfilled by established suppliers. Direct-to-industrial-service models for regenerable cartridges in Japan offer a white-space entry angle. For Investors and Strategic Acquirers: Asymmetric upside sits with regional converters possessing BIS certification and pharmaceutical packaging automation compatibility in India. Long-term viability over the next decade hinges on regulatory certification depth rather than commodity scale. Watch for FDA Type III drug master file submission acceleration as the inflection signal indicating which regional players will secure locked-in procurement relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silica Gel Production | Captive feedstock supply secures continuity when Chinese coastal production faces logistics disruption. |
| BIS-Certified Converting Capacity Expansion | Domestic Indian certification captures CDSCO-mandated pharmaceutical serialization demand growth. |
| Microencapsulation Technology Investment | Eliminates EPA silica dust exposure risks that disqualify conventional impregnated papers. |
| Multi-Year Master Service Agreements | Bundled supply-converting-logistics contracts lock out spot-market competitors. |
| Cobalt-Free Indicator Validation | ECHA REACH Annex XIV compliance ahead of sunset dates secures European electronics OEM qualification. |
Study Parameters
Multiple input streams — primary interviews with pharmaceutical packaging engineers, desiccant material procurement leads, and regulatory affairs directors; secondary validation through FDA drug master file databases, ECHA REACH registrations, and customs trade data; plus SEC filings from integrated chemical producers — were reconciled through bottom-up and top-down triangulation to construct market estimates.
Data-stream reconciliation across active agent type, application vertical, packaging format, and regional certification cluster enabled segment-level modeling over the projection horizon. CAGRs were derived from growth driver elasticity analysis applied to base-year consumption patterns. Forecast inputs incorporated EU F-Gas Regulation implementation timelines and pharmaceutical serialization mandate rollouts across multiple jurisdictions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under raw material price volatility and regulatory enforcement intensity variations. Forecasts reflect documented assumptions about certification adoption rates and procurement consolidation trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Fast Food Wrapping Paper Market
Paper & Paperboard Packaging
SCK Paper Market
Paper & Paperboard Packaging
Recycled Paper Packaging Market
Paper & Paperboard Packaging
Stationery Films Packaging Market
Paper & Paperboard Packaging
Kraftliner Market
Paper & Paperboard Packaging
Paper Coaster Market
Paper & Paperboard Packaging
GCC Paper Bags Market
Paper & Paperboard Packaging
Compostable Paper Tray Market
Paper & Paperboard Packaging
MMA Film & Sheet Market
Paper & Paperboard Packaging
Japan Paper Packaging Market
Paper & Paperboard Packaging
Binder's Board Market
Paper & Paperboard Packaging
Decal Paper Market
Paper & Paperboard Packaging
Kraft Paper Mailer Market
Paper & Paperboard Packaging
Clear Envelopes and Mailing Supplies Market
Paper & Paperboard Packaging
North America Paper Cone Market
Paper & Paperboard Packaging
Kraft Paper SOS Bag Market