
 Australia Corrugated Board Packaging Market | 2026-2036
Australia Corrugated Board Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Corrugated Board Packaging Market Outlook
Aftermarket recovery and recycling services is reconfiguring margin pools across the Australia corrugated board packaging value chain. Visy Industries Holdings Pty Ltd leverages its integrated recycling and paper mill network to dominate fibre supply security across southeastern states. Oji Fibre Solutions (Australia) Pty Ltd anchors its position through specialized kraftliner production tailored to Australian agricultural export standards. Opal Fibre Packaging competes via extensive box plant coverage that positions the firm close to food processing clusters in regional Victoria and New South Wales.
Corrugated board packaging consists of fluted paperboard sheets laminated between flat linerboards, typically manufactured through a corrugator process running at 200-300 metres per minute to produce structures with burst strengths ranging from 150 to 1,000 kPa depending on wall configuration. Its primary purpose centres on protective containment, stacking strength, and print-ready branding surfaces for goods in transit and retail display. Single wall products occupy the highest volume share across Australian food and beverage distribution, while die-cut formats capture expanding margin pools from electronics and pharmaceutical end users seeking precision-fit protection with reduced void fill. Double wall and triple wall segments sustain demand from industrial machinery and bulk agricultural commodity exporters requiring enhanced compression resistance during extended supply chains.
TGA labelling requirements for pharmaceutical shipments and the Australian Packaging Covenant Organisation's 2025 recycled content targets are tightening material traceability and driving investment in domestic repulping capacity. Food Standards Australia New Zealand migration limits for packaging contaminants intersect with AS 1647 fibreboard hygiene standards to shape product qualification pathways for food-contact applications. Stakeholders must monitor how the National Plastics Plan's fibre substitution incentives redirect capital between virgin linerboard expansion and recycled medium upgrades.
Market Dynamics
Integrated recycling-to-boxplant networks are reconfiguring competitive advantage across Australian corrugated packaging, as fibre security displaces scale economies as the primary margin determinant. The Australian Packaging Covenant Organisation's recycled content mandates are accelerating capital reallocation toward domestic repulping infrastructure.
Growth Catalysts
- Export-oriented horticulture:Queensland and Victorian fresh produce exporters are expanding protective packaging specifications to meet Asian retail compliance standards, driving demand for moisture-resistant linerboard grades.
- APCO 2025 recycled content targets:The Australian Packaging Covenant Organisation's mandates are redirecting procurement toward post-consumer fibre streams, stimulating investment in domestic recovery infrastructure.
- Sydney industrial corridor concentration:Warehousing and distribution infrastructure clusters in western Sydney are generating dense demand pockets that reward proximity-based boxplant coverage.
Market Restraints
- Old corrugated container price volatility:Domestic OCC collection shortfalls expose mills to Asian export competition for recovered fibre, compressing medium production margins during supply tightness.
- Kraftliner import dependency:Limited domestic kraft pulp capacity forces reliance on Indonesian and Thai linerboard imports, creating exchange rate exposure and lead time uncertainty.
- Food Standards Australia New Zealand migration limits:Contaminant thresholds for food-contact fibreboard impose qualification barriers that extend new product development cycles.
Strategic Opportunities
- Pharmaceutical cold chain expansion:TGA temperature-controlled labelling requirements for biologic shipments are opening specifications for insulated corrugated solutions with integrated phase-change materials.
- National Plastics Plan substitution incentives:Federal fibre substitution programs are redirecting capital from polystyrene protective packaging toward molded pulp and corrugated alternatives in electronics fulfillment.
- Die-cut precision formats:Electronics and pharmaceutical end users are migrating from standard RSC boxes to precision-fit die-cut designs that eliminate void fill and reduce dimensional weight charges.
Industry Challenges
- Corrugator technician scarcity:Skilled operators capable of maintaining 250+ metre-per-minute production lines with automated knife and scorer calibration are concentrated among retiring cohorts, constraining capacity expansion.
- AS 1647 hygiene certification timelines:Third-party audit backlogs for food-contact fibreboard qualifications are extending customer onboarding periods beyond commercial planning horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Corrugated Board Packaging Market |
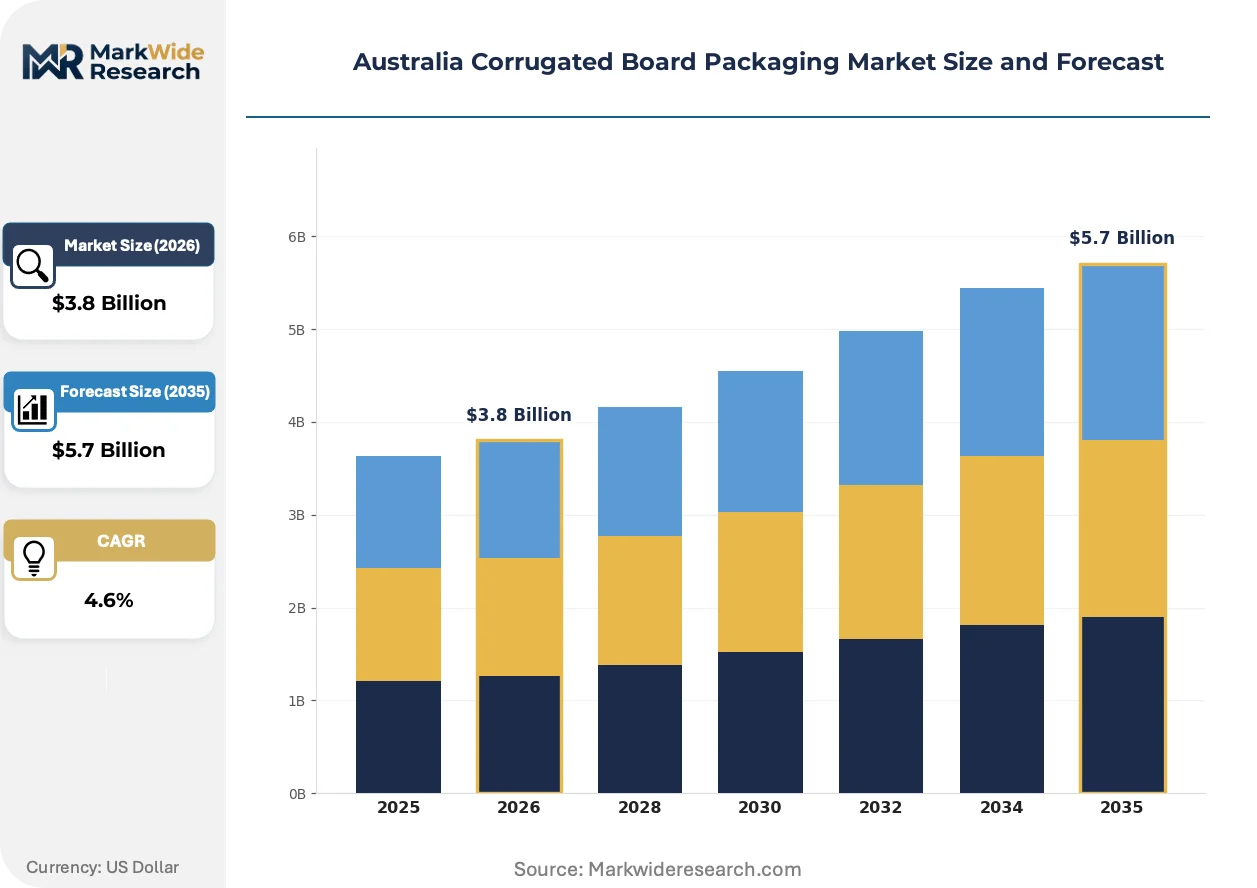
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Wall, Double Wall, Triple Wall, Die-Cut End User: Food & Beverages, Electronics, Pharmaceuticals, Consumer Goods Thickness: Lightweight, Medium Weight, Heavyweight, Super Heavyweight Style: Regular Slotted Container, Half-Slotted Container, Full Overlap, Pad |
| Companies Covered | Visy Industries Holdings Pty Ltd, Opal Fibre Packaging, Oji Fibre Solutions (Australia) Pty Ltd, Orora Ltd, Pratt Industries, DS Smith plc, WestRock Company, Abbe Corrugated Pty Ltd, Detmold Packaging, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Corrugated Board Packaging Market Strategic Shifts
Digital print integration and structural design software are compressing the traditional separation between commodity box production and specialized display packaging. These converging capabilities are eroding the historical volume-premium segmentation that organized the industry.
Water-based flexographic printing with expanded gamut ink sets is rendering obsolete the minimum order quantities that previously constrained short-run branded packaging. Fresh produce exporters in Victoria are adopting these systems for seasonal label variations without plate changeover costs. The technology is compressing the economic threshold between plain brown shipping containers and retail-ready printed boxes.
TGA serialization requirements for pharmaceutical distribution are mandating track-and-trace integration at the secondary packaging level. Australian corrugated converters are embedding variable data print stations and aggregation software into boxplant workflows. Cold chain pharmaceutical shipments face the most acute compliance pressure, with converters investing in vision systems and database connectivity to meet lot-level traceability mandates.
Consolidated procurement by national grocery chains is displacing the fragmented buyer landscape that historically sustained regional boxplant networks. Retailers are centralizing corrugated specifications through direct mill relationships, bypassing traditional distributor channels. This concentration is most visible in Sydney and Melbourne metropolitan zones, where national account structures are compressing supplier counts and extending contract durations.
Australia Corrugated Board Packaging Market Segmentation
Segmentation in Australian corrugated packaging reveals how fibre specifications, structural configurations, and end-use compliance requirements partition margin pools. Understanding these divides exposes where capital earns returns versus where commoditization compresses pricing power.
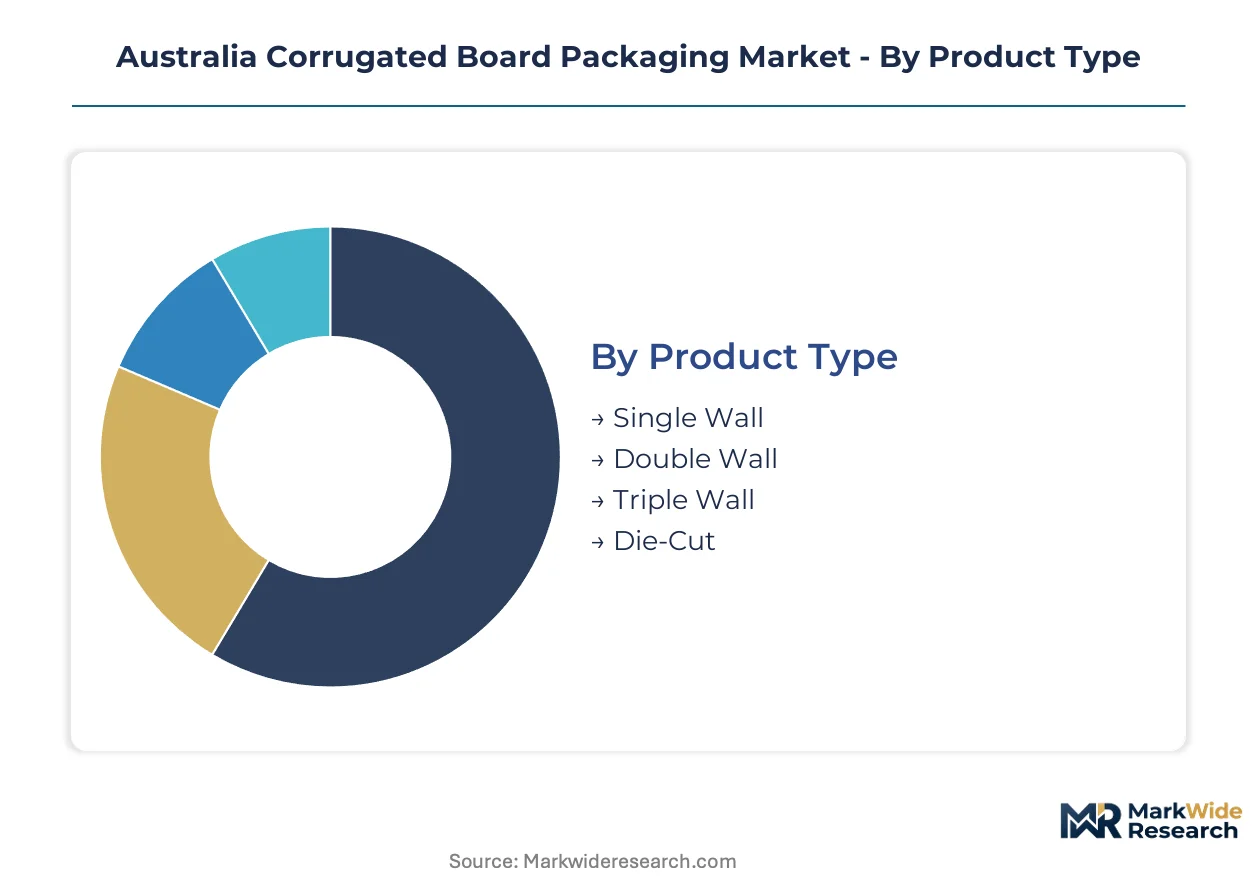
Product Type:
Mature formats dominate volume flows while precision-engineered variants capture expanding specification premiums from quality-sensitive exporters.
- Single Wall:One fluted medium sandwiched between two linerboards, typically specified at 150-275 kPa burst strength for routine distribution loads. Queensland and Victorian fresh produce exporters deploy moisture-resistant B-flute variants for Asian retail compliance, driving grade differentiation within this volume base.
- Die-Cut:Precision-cut formats engineered to exact product dimensions without void fill requirements. Electronics fulfillment centres in Sydney's industrial corridor are migrating from standard boxes to these designs to reduce dimensional weight charges and eliminate protective dunnage.
- Double Wall:Two fluted layers with three linerboard facings, delivering 350-700 kPa burst resistance for industrial machinery and bulk agricultural commodities.
- Triple Wall:Three fluted layers with four linerboards, specified for extreme compression resistance in heavy machinery export and bulk chemical transport.
Single Wall handles the majority of throughput; Die-Cut is expanding most quickly on specification premiums from e-commerce and pharmaceutical end users.
End User:
Application-specific compliance regimes create distinct qualification barriers that segment converter capabilities and customer switching costs.
- Food & Beverages:The largest demand pool, governed by Food Standards Australia New Zealand migration limits and AS 1647 fibreboard hygiene standards. Sydney and Melbourne metropolitan grocery distribution centres concentrate procurement through national account structures that reward integrated recycling-to-boxplant networks.
- Pharmaceuticals:TGA serialization mandates and cold chain labelling requirements for biologic shipments. Temperature-controlled specifications are opening demand for insulated corrugated with integrated phase-change materials, though qualification timelines extend commercial planning horizons.
- Electronics:Precision-fit protection requirements and National Plastics Plan substitution incentives redirecting capital from polystyrene toward molded pulp and corrugated alternatives.
- Consumer Goods:Seasonal volume volatility and retail-ready print specifications, with digital flexographic adoption compressing minimum order quantities for short-run branded packaging.
Food & Beverages anchors volume throughput; Pharmaceuticals shows the steepest expansion trajectory on compliance-driven specification upgrades.
Thickness:
Weight-class specifications align with load-bearing requirements and freight optimisation calculus across Australian supply chains.
- Lightweight:Sub-300 gsm combined board weight for parcel post and small consumer goods where dimensional weight pricing dominates logistics costs.
- Medium Weight:300-450 gsm specifications capturing the bulk of food and beverage distribution through Sydney's warehousing corridor.
- Heavyweight:450-600 gsm for industrial components and agricultural export requiring enhanced stacking strength through extended supply chains.
- Super Heavyweight:Exceeding 600 gsm for machinery export and bulk commodity transport where compression resistance justifies fibre cost premiums.
Medium Weight carries the dominant share of domestic consumption; Heavyweight is climbing fastest on agricultural export expansion.
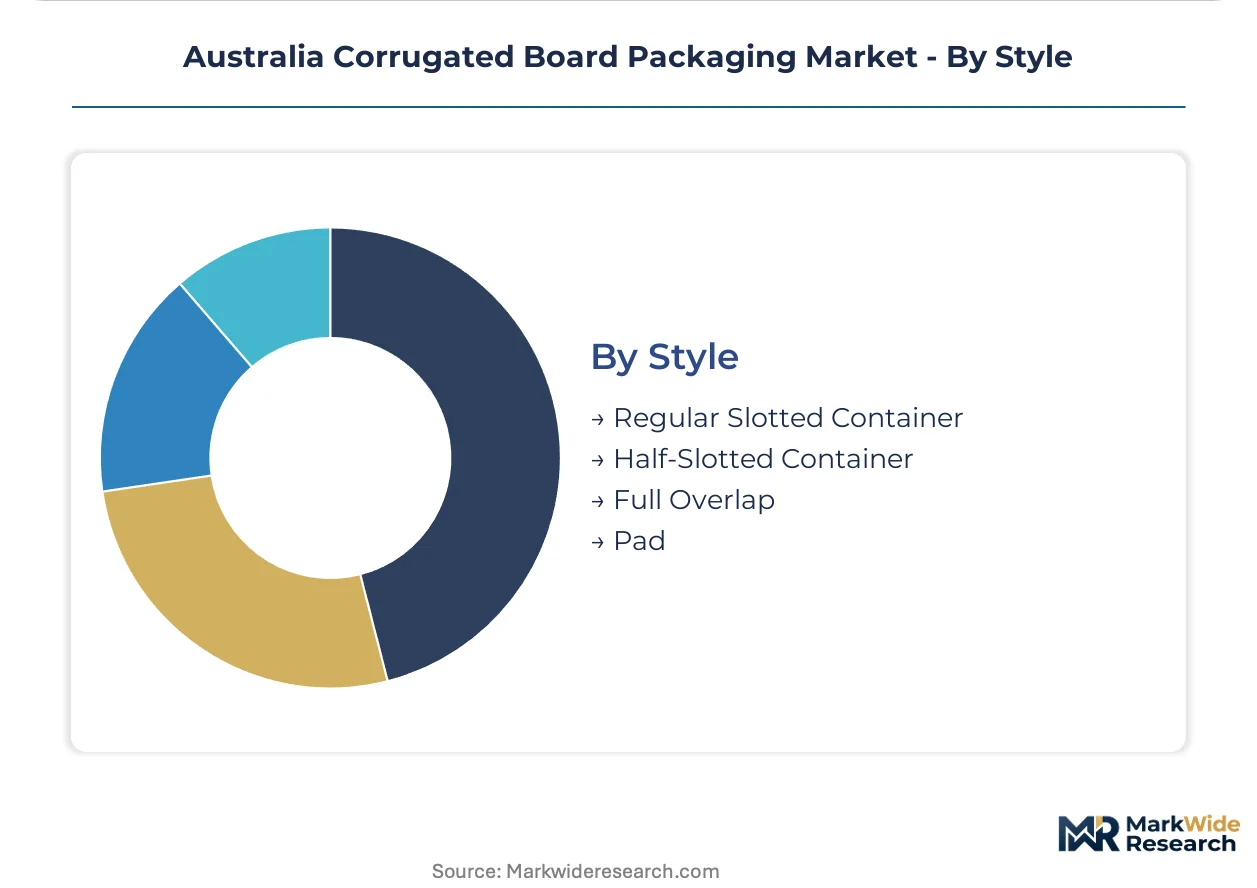
Style:
Box architecture determines manufacturing efficiency, palletisation economics, and end-use handling requirements across Australian distribution networks.
- Regular Slotted Container:Standard four-flap design with lengthwise flaps meeting at centre, optimised for automated case erection and high-speed filling lines. Dominates food processing clusters in regional Victoria and New South Wales where Opal Fibre Packaging maintains proximity coverage.
- Full Overlap:Outer flaps fully overlap across width, delivering superior stacking strength and protection for export shipments. Fresh produce exporters across Queensland specify this style for Asian retail compliance where pallet stability through multi-modal transit is critical.
- Half-Slotted Container:Similar to RSC but with one open end, used with separate lid for applications requiring top access or display presentation.
- Pad:Flat corrugated sheets for layer separation, pallet top protection, and interior dividing structures within master containers.
Regular Slotted Container moves the greatest volume through Australian boxplants; Full Overlap is gaining share fastest on export-oriented horticulture expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australian corrugated consumption patterns diverge sharply between eastern seaboard export corridors and southern manufacturing belts, with each geography driving distinct grade specifications and supply chain configurations.
New South Wales
Sydney's western industrial corridor concentrates warehousing and distribution infrastructure, generating dense demand pockets for medium-weight single wall formats. The Australian Packaging Covenant Organisation's recycled content mandates redirect procurement toward post-consumer fibre streams. National grocery chains centralize corrugated specifications through direct mill relationships, compressing supplier counts in the metropolitan zone.
Victoria
Regional food processing clusters around Shepparton and the Goulburn Valley sustain proximity-dependent boxplant coverage for fresh produce distribution. Food Standards Australia New Zealand migration limits intersect with AS 1647 fibreboard hygiene standards to shape qualification pathways. Melbourne metropolitan distribution centres are consolidating procurement through national account structures that reward integrated recycling networks.
Queensland
Asian export-oriented horticulture from the Lockyer Valley and Darling Downs drives moisture-resistant linerboard specifications for retail compliance standards. TGA labelling requirements for temperature-controlled pharmaceutical shipments open specifications for insulated corrugated solutions. Brisbane's logistics corridor anchors protective packaging demand for agricultural commodity exporters.
Western Australia
Perth's isolation from eastern manufacturing centres sustains distinct procurement patterns with longer lead time tolerances. Mining equipment and bulk chemical transport generate super heavyweight triple wall demand for extreme compression resistance. Domestic kraftliner import dependency exposes converters to exchange rate volatility from Indonesian and Thai supply sources.
South Australia
Adelaide's smaller industrial base relies on interstate supply chains for specialized die-cut formats serving electronics and pharmaceutical end users. Old corrugated container price volatility from domestic collection shortfalls compresses medium production margins during supply tightness. Wine industry export packaging sustains niche demand for print-ready branding surfaces.
Australia Corrugated Board Packaging Market Competitive Environment
Capability concentration sits with integrated recycling-to-boxplant networks; scale advantage sits with extensive mill and plant coverage across southeastern states. The market structures around three tiers: fibre-integrated conglomerates controlling pulp supply security, specialized kraftliner producers serving agricultural export standards, and regional boxplant operators competing on proximity to food processing clusters. Dominant competitive moves include backward integration into domestic repulping infrastructure and geographic expansion through boxplant acquisitions near Sydney and Melbourne industrial corridors.
Among fibre-integrated conglomerates, Visy Industries Holdings Pty Ltd exemplifies the recycling-to-boxplant archetype through its southeastern network control. Specialized kraftliner production is represented by Oji Fibre Solutions (Australia) Pty Ltd, which occupies a position tailored to export-grade specifications. Regional proximity coverage is anchored by Opal Fibre Packaging, sitting within the food processing cluster specialist tier across Victoria and New South Wales.
| Leading Market Players |
|---|
| Visy Industries Holdings Pty Ltd |
| Opal Fibre Packaging |
| Oji Fibre Solutions (Australia) Pty Ltd |
| Orora Ltd |
| Pratt Industries |
| DS Smith plc |
| WestRock Company |
| Abbe Corrugated Pty Ltd |
| Detmold Packaging |
| Others |
Value Chain & Pricing Dynamics
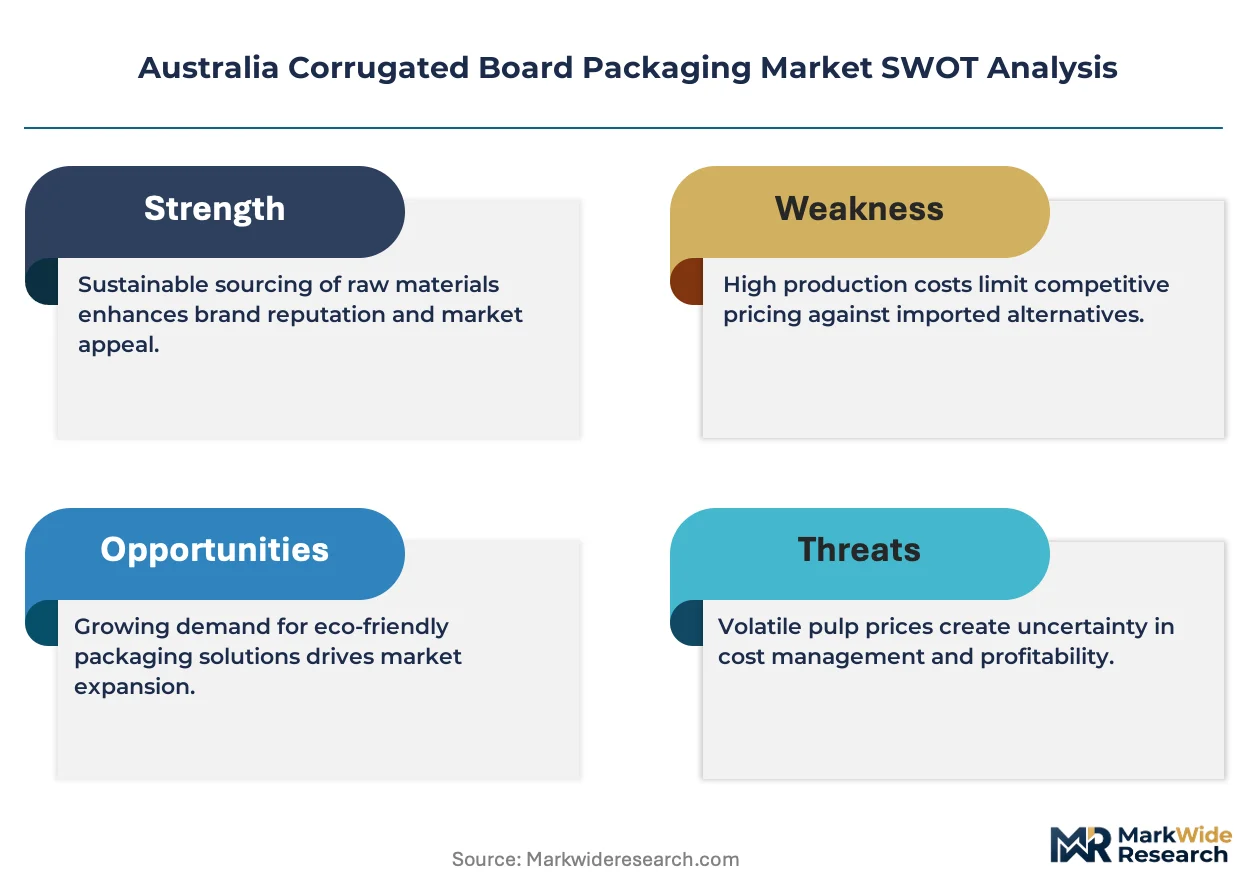
Indonesian and Thai kraftliner imports anchor linerboard supply security across Australian corrugated packaging, concentrating margin pools with converters who have locked in long-term offtake agreements with Southeast Asian pulp mills. This upstream dependency shapes downstream pricing power, as exchange rate exposure and lead time uncertainty compress margins for spot-market buyers while integrated players capture stability premiums.
Pricing Analysis
Long-term offtake contracts dominate kraftliner procurement for major Australian converters, insulating integrated players from spot volatility while regional boxplants absorb price swings. Price differentiation rests on fibre security certification and volume scale, with APCO 2025 recycled content compliance commanding premium positioning. Cost compression in medium-weight single wall grades is intensifying because domestic OCC collection shortfalls expose mills to Asian export competition. National grocery chains exhibit lowest price sensitivity due to consolidated procurement power, whereas regional food processors face acute margin pressure.
Supply Chain Analysis
Visy Industries and Opal Fibre Packaging hold dominant domestic repulping and boxplant capacity across Australia's southeastern manufacturing belt. Raw material flows draw from Indonesian kraft pulp, Thai linerboard imports, and domestic OCC recovery streams concentrated in Sydney and Melbourne metropolitan zones. Single-source vulnerability sits with kraftliner import dependency, as limited domestic pulp capacity creates exposure to exchange rate volatility and shipping disruption. Distribution runs through direct mill relationships with national grocery chains, bypassing traditional distributor channels in metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through national grocery chain procurement centralization, compressing supplier counts and extending contract durations across Sydney and Melbourne metropolitan zones.
For Market Incumbents: Pre-empt margin erosion in medium-weight single wall grades by accelerating backward integration into domestic repulping infrastructure ahead of APCO 2025 recycled content mandates. Lock in long-term OCC supply agreements with municipal recovery operators to defend fibre security against Asian export competition. Certification investment in AS 1647 hygiene standards and TGA serialization capabilities represents the critical lever for pharmaceutical and food-contact specification premiums.
For New Entrants and Emerging Players: Establish a beachhead in die-cut precision formats serving Sydney's electronics fulfillment corridor, where dimensional weight charge reduction drives rapid specification migration from standard RSC boxes. Target pharmaceutical cold chain expansion in Queensland, where TGA temperature-controlled labelling requirements for biologic shipments outpace incumbent converter qualification capacity. A go-to-market angle anchored to digital flexographic short-run capabilities captures seasonal fresh produce exporter demand without plate changeover cost penalties.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across domestic repulping infrastructure as APCO mandates redirect procurement toward post-consumer fibre streams. Acquisition targets should prioritize regional boxplant operators with proximity coverage to Victorian food processing clusters and latent AS 1647 certification pathways. The signal to watch is old corrugated container export price spreads to Asian markets, which indicate domestic supply tightness and margin compression timing for non-integrated players.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Repulping Capacity Expansion | APCO 2025 recycled content mandates redirect capital toward post-consumer fibre recovery infrastructure across southeastern states. |
| Die-Cut Precision Format Investment | Electronics fulfillment migration from standard RSC boxes captures specification premiums in Sydney's industrial corridor. |
| Pharmaceutical Cold Chain Qualification | TGA serialization and temperature-controlled labelling requirements open insulated corrugated specifications with phase-change material integration. |
| Digital Flexographic Print Integration | Water-based expanded gamut systems compress minimum order quantities for seasonal fresh produce exporter label variations. |
| Regional Boxplant Proximity Acquisition | Food processing cluster coverage in regional Victoria and New South Wales secures national grocery chain contract access. |
Study Parameters
Desk research of trade flow databases, customs records, and Australian Packaging Covenant Organisation regulatory filings preceded structured interviews with corrugated plant managers, grocery chain procurement directors, pharmaceutical supply chain managers, and recycling facility operators. Primary fieldwork captured operational metrics on corrugator line speeds, OCC collection economics, and boxplant capacity utilization. Secondary validation drew from AS 1647 hygiene standard audit reports, TGA pharmaceutical packaging guidelines, and Food Standards Australia New Zealand migration limit documentation. Bottom-up volume modeling triangulated against top-down macroeconomic consumption indicators.
Assumptions held fixed across the projection horizon include Australian Packaging Covenant Organisation 2025 recycled content target enforcement, TGA serialization mandate implementation timelines, and National Plastics Plan fibre substitution incentive continuity. Segmentation dimensions modeled encompass product type, end-use compliance regime, thickness specification, and box architecture style. CAGRs were derived from trend extrapolation of export-oriented horticulture packaging demand and pharmaceutical cold chain expansion, cross-referenced against corrugator technician availability constraints and domestic repulping capacity buildout schedules.
Stress conditions across old corrugated container export price volatility, kraftliner import exchange rate exposure, and AS 1647 certification timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these bounded assumptions, with specific revision triggers including regulatory enforcement delays, fibre substitution incentive cancellation, or abrupt Asian linerboard supply disruption. Quarterly review of OCC collection volumes, kraftliner import contract renegotiation activity, and pharmaceutical converter qualification backlogs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Paper Honeycomb Market
Paper & Paperboard Packaging
Air Fryer Paper Liners Market
Paper & Paperboard Packaging
Commercial Paper Bags Market
Paper & Paperboard Packaging
Push-Pull Slip Sheets Market
Paper & Paperboard Packaging
GCC Paper Cup Market
Paper & Paperboard Packaging
Food Wrapping Paper Market
Paper & Paperboard Packaging
Unbleached Kraft Paperboard Market
Paper & Paperboard Packaging
Ultraflute Paper Market
Paper & Paperboard Packaging
Paper Packaging Market
Paper & Paperboard Packaging
Paper Carrier Bags Market
Paper & Paperboard Packaging
Asia-Pacific Coated Paper Market
Paper & Paperboard Packaging
Greyboard Market
Paper & Paperboard Packaging
Kraft Paper Bags Market
Paper & Paperboard Packaging
Paperboard Mailer Market
Paper & Paperboard Packaging
Paperboard Container Market
Paper & Paperboard Packaging
Secondary Paper and Paperboard Luxury Packaging Market