
 Cold Seal Paper Market | 2026-2036
Cold Seal Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Seal Paper Market Outlook
Direct sales channels between paper converters and food packaging multinationals is narrowing as Mondi Group leverages its integrated pulp-to-package supply chain to bypass traditional distributor networks. Amcor plc sustains global reach through dedicated cold seal technical service teams embedded with Nestlé and Mars Wrigley. ProAmpac competes by specializing in short-run custom cold seal formulations for regional confectionery brands.
Cold seal paper consists of natural kraft or glassine substrates coated with water-based synthetic rubber latex adhesives that activate under pressure at ambient temperature, eliminating thermal sealing equipment and reducing energy consumption by eliminating heat bars. The material serves primarily as a sterile, grease-resistant barrier for temperature-sensitive products where heat would degrade contents. Multi-layer constructions lead the product type category due to their superior moisture and oxygen barrier properties required for extended shelf-life chocolate products. Flexible packaging applications dominate end-use volumes, though pharmaceutical blister lidding represents the fastest-growing segment as manufacturers replace PVC with fiber-based alternatives.
FDA food contact substance regulations govern latex coating chemistries permitted in US cold seal papers, while EU REACH restrictions on specific rubber accelerators are forcing reformulation of European-manufactured grades. The EU F-Gas Regulation indirectly supports cold seal adoption by penalizing heat-seal processes dependent on fluorinated refrigerants in forming equipment. Stakeholders must monitor emerging state-level extended producer responsibility laws in California and New York that will mandate fiber-based packaging recovery rates exceeding current infrastructure capacity.
Market Dynamics
Energy-intensive heat-seal packaging lines face mounting cost pressure as EU carbon border adjustments and industrial electricity tariffs reshape total cost of ownership calculations for chocolate and confectionery manufacturers.
Growth Catalysts
- EU F-Gas Regulation:Penalties on fluorinated refrigerants in heat-seal forming equipment accelerate cold seal adoption across German and French flexible packaging converters seeking compliance pathways.
- Chocolate shelf-life extension:Multi-layer cold seal constructions with enhanced oxygen barriers support premium confectionery brands expanding distribution into warmer climates without refrigeration.
- India PLI scheme:Domestic packaging material incentives attract cold seal substrate investments serving the subcontinent's rapidly modernizing confectionery sector.
Market Restraints
- Synthetic rubber latex price volatility:Water-based adhesive formulations depend on petrochemical feedstocks exposed to crude oil and natural gas fluctuations, compressing converter margins during energy price spikes.
- Substrate concentration risk:Natural kraft pulp supply concentrates in Nordic and North American forestry regions, exposing European cold seal manufacturers to transatlantic shipping cost swings and currency exposure.
- Heat-seal incumbent lock-in:Existing thermal sealing equipment represents sunk capital across major confectionery packaging facilities, slowing conversion timelines even where operating cost savings are demonstrable.
Strategic Opportunities
- Pharmaceutical blister lidding:PVC replacement mandates in EU medical packaging create fiber-based cold seal entry points previously dominated by plastic films, with Swissmedic and EMA guidance favoring recyclable alternatives.
- Direct-to-brand technical service:Embedded formulation chemists at regional confectionery houses bypass distributor markups and capture specification authority previously held by multinational flexible packaging suppliers.
- California EPR implementation:Extended producer responsibility laws mandating fiber recovery rates exceeding current infrastructure capacity position cold seal papers ahead of plastic-laminated competitors in compliance planning.
Industry Challenges
- Adhesive formulation expertise scarcity:Water-based synthetic rubber latex compounding requires specialized polymer chemistry capabilities concentrated among legacy tape and label manufacturers, creating recruitment friction for packaging converters expanding cold seal capacity.
- Food contact certification timelines:FDA food contact substance notifications and EU REACH rubber accelerator reformulations impose 12-18 month approval cycles that delay new product commercialization and tie up R&D resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Seal Paper Market |
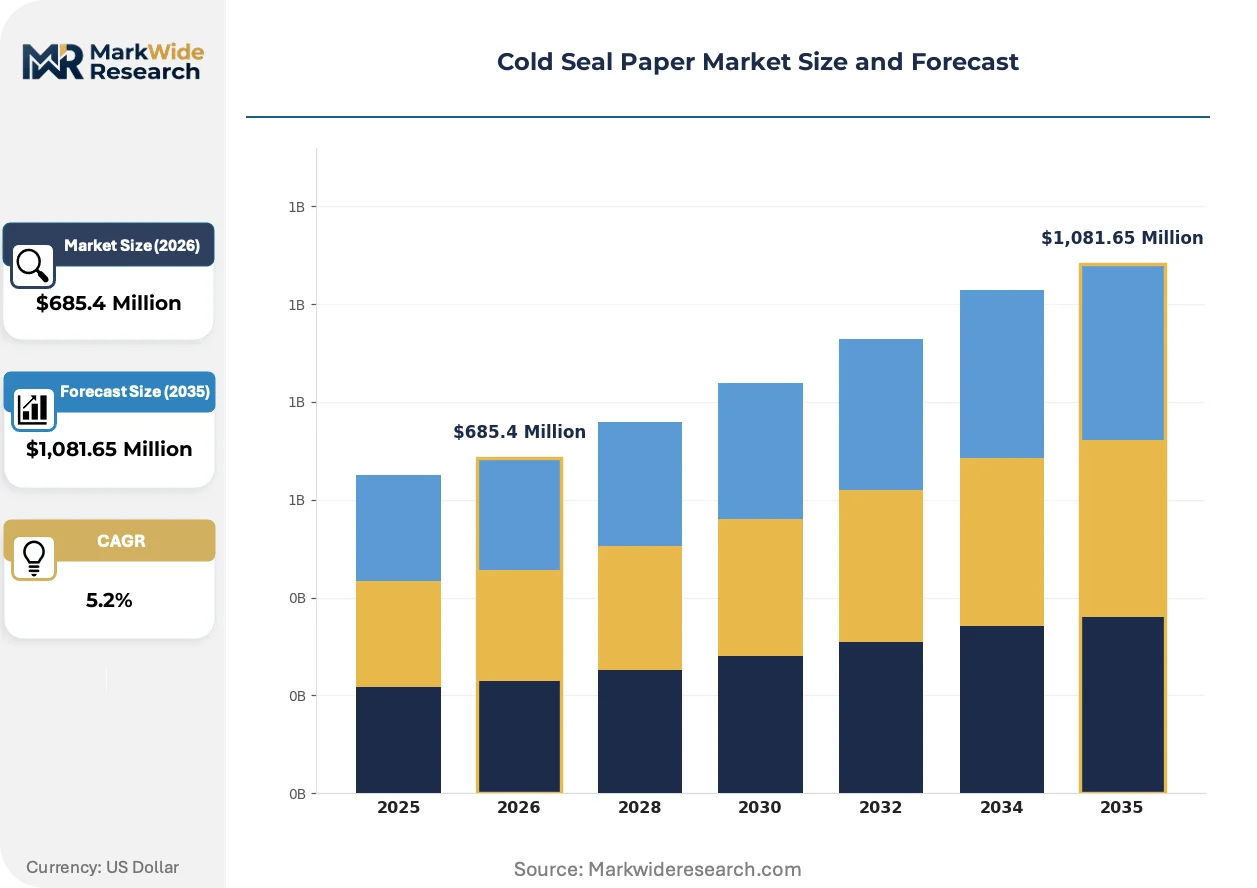
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,081.65 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Layer, Multi Layer, Coated, Uncoated End User: Food Packaging, Pharmaceutical, Personal Care, Electronics Application: Flexible Packaging, Labels, Wrapping, Sealing Distribution Channel: Online Retail, Offline Retail, Direct Sales, Distributors |
| Companies Covered | Mondi Group, Amcor plc, Berry Global Inc., Constantia Flexibles, Uflex Ltd, ProAmpac, Coveris Holdings S.A., Huhtamaki, Winpak Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Seal Paper Market Strategic Shifts
Pressure-activated adhesive systems are advancing beyond conventional synthetic rubber latex toward bio-based and recyclable formulations that align with circular packaging mandates while maintaining seal integrity under high-speed wrapping conditions.
High-speed cold seal coating lines equipped with precision gravure and slot-die application systems are rendering obsolete older flexo-coated substrates that required excessive adhesive mass to achieve reliable seal strength. Swiss and German packaging machinery OEMs have integrated these coating technologies into turnkey lines delivered to major chocolate manufacturers, compressing the performance gap between cold seal and thermal alternatives while eliminating heat bar maintenance and energy consumption.
EU REACH restrictions on specific rubber accelerators and the broader EU Packaging and Packaging Waste Regulation are forcing systematic reformulation of European-manufactured cold seal grades. ECHA substance evaluations have flagged thiazole and thiuram compounds historically prevalent in latex curing, compelling adhesive suppliers to validate alternative crosslinking chemistries. German and Austrian converters with in-house polymer laboratories have accelerated this transition, while smaller Southern European competitors face outsourcing dependencies that extend compliance timelines.
Specification authority is migrating from procurement departments to technical packaging engineers embedded within Nestlé, Mars Wrigley, and Ferrero innovation centers. These engineers now dictate adhesive chemistry, substrate construction, and seal performance parameters through direct collaboration with cold seal paper converters, displacing the traditional distributor-mediated model where intermediaries controlled technical communication. This shift concentrates volume with converters maintaining captive R&D facilities capable of rapid formulation iteration, most visible in Vevey and Halle-Neustadt where major confectionery R&D campuses cluster.
Cold Seal Paper Market Segmentation
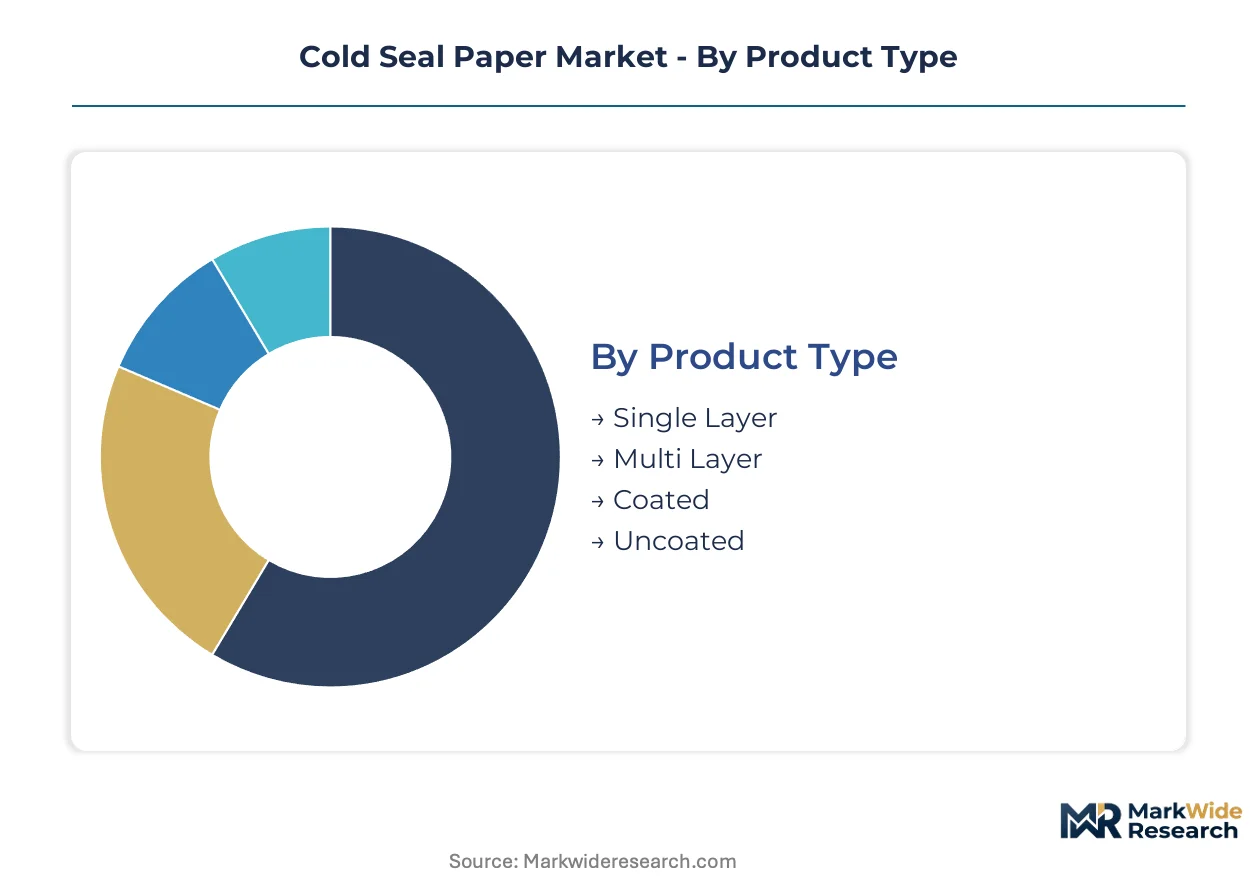
Cold seal paper specifications diverge sharply across end-use requirements, with chocolate confectionery demanding multi-layer oxygen barriers while pharmaceutical lidding prioritizes fiber-based sterility. Substrate construction and adhesive formulation choices cascade through distribution economics and customer procurement patterns.
Product Type:
Cost tier differentiation separates commodity-grade substrates from engineered constructions serving temperature-sensitive applications.
- Multi Layer:Laminated natural kraft and glassine substrates with synthetic rubber latex coatings provide superior moisture and oxygen barriers. German and Austrian converters with in-house polymer laboratories dominate supply for premium chocolate shelf-life extension into warmer climates.
- Single Layer:Unlaminated kraft or glassine constructions serve cost-sensitive wrapping applications where barrier demands are modest. Nordic pulp supply concentration exposes this tier to transatlantic shipping cost volatility.
- Coated:Precision gravure and slot-die application systems deposit water-based adhesives with controlled mass distribution for high-speed wrapping lines.
- Uncoated:Raw substrates for downstream converter coating or specialty applications requiring custom adhesive formulation.
Multi Layer holds installed capacity. Single Layer is rotating up the share rankings.
End User:
Application maturity varies dramatically across sectors, with food packaging representing established volume while pharmaceutical adoption accelerates under regulatory pressure.
- Food Packaging:Chocolate and confectionery wrapping consumes the majority of cold seal tonnage as manufacturers eliminate heat-seal energy costs. Nestlé and Mars Wrigley technical engineers now dictate adhesive specifications directly with converters.
- Pharmaceutical:PVC replacement mandates in EU medical packaging create fiber-based cold seal entry points for blister lidding. Swissmedic and EMA guidance favor recyclable alternatives, positioning this segment for steepest expansion trajectory.
- Personal Care:Sterile barrier applications for temperature-sensitive cosmetic products where heat degradation risks content integrity.
- Electronics:Anti-static wrapping for moisture-sensitive components requiring pressure-activated sealing without thermal exposure.
Food Packaging anchors volume throughput. Pharmaceutical is climbing the fastest in specification authority.
Application:
Volume concentration tracks flexible packaging infrastructure while adjacent applications capture margin through technical differentiation.
- Flexible Packaging:Roll-fed wrapping systems for high-speed chocolate production lines dominate end-use volumes. Swiss and German packaging machinery OEMs have integrated precision coating technologies into turnkey lines.
- Wrapping:Individual product enclosure for confectionery and baked goods where grease resistance and sterile barriers are essential.
- Labels:Pressure-sensitive adhesive applications leveraging cold seal coating equipment for specialty labelstock production.
- Sealing:Closure systems and pouch formats requiring ambient-temperature activation for temperature-sensitive contents.
Flexible Packaging commands production scale. Wrapping is gaining share fastest through direct-to-brand technical service models.
Distribution Channel:
Customer type fragmentation between multinational procurement and regional converter purchasing reshapes channel economics.
- Direct Sales:Integrated pulp-to-package supply chains bypass traditional distributor networks. Mondi Group leverages captive substrate production to serve Nestlé and Mars Wrigley through embedded technical teams.
- Distributors:Traditional intermediaries retain relevance for smaller Southern European converters lacking in-house polymer laboratories and facing extended EU REACH compliance timelines.
- Online Retail:Digital procurement platforms for standardized grades and spot purchasing by regional packaging operations.
- Offline Retail:Conventional trade counter and representative-based sales for custom formulation development and technical consultation.
Direct Sales captures specification authority. Distributors is rotating up the share rankings through outsourcing dependencies among smaller competitors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU F-Gas Regulation penalties on fluorinated refrigerants anchor European cold seal adoption, while Asia-Pacific confectionery modernization and North American extended producer responsibility laws reshape regional demand trajectories across the forecast window.
Germany
Chocolate manufacturers eliminate heat-seal energy costs through cold seal conversion. EU F-Gas Regulation compliance deadlines accelerate flexible packaging line retrofits. Halle-Neustadt hosts major confectionery R&D campuses where technical engineers dictate adhesive specifications directly with substrate converters.
United States
FDA food contact substance notifications govern latex coating chemistries for domestic cold seal grades. California and New York extended producer responsibility laws mandate fiber-based packaging recovery rates. Midwest flexible packaging corridors concentrate converter capacity serving Mars Wrigley and Nestlé technical service requirements.
India
Domestic confectionery sector modernization drives substrate demand for temperature-sensitive wrapping applications. PLI scheme incentives attract packaging material investments. Maharashtra and Gujarat house expanding flexible packaging facilities targeting regional chocolate brands.
Switzerland
Swissmedic guidance favors recyclable fiber-based alternatives for pharmaceutical blister lidding. EMA regulatory alignment supports PVC replacement mandates. Vevey anchors Nestlé's global packaging innovation center where specification authority concentrates with embedded converter technical teams.
China
Dual carbon goals pressure energy-intensive heat-seal processes across confectionery manufacturing bases. National standards for food contact materials govern adhesive formulations. Yangtze River Delta flexible packaging clusters integrate precision gravure coating systems for high-speed chocolate production lines.
Cold Seal Paper Market Competitive Environment
Integrated pulp-to-package conglomerates and specialized flexible packaging converters split the market through divergent supply chain configurations. Tier concentration reflects captive substrate production capabilities versus outsourced formulation expertise. Strategic archetypes encompass backward-integrated forestry owners, dedicated technical service specialists, and regional short-run custom formulators. Dominant competitive moves include embedded R&D facility establishment with major confectionery houses and precision coating line integration by packaging machinery OEMs.
Within the integrated supply chain tier, Mondi Group leverages captive pulp production to bypass traditional distribution networks. Amcor plc exemplifies the technical service archetype through dedicated cold seal teams embedded with multinational food packaging customers. ProAmpac occupies a position among specialized regional formulators, competing through short-run custom adhesive development for mid-sized confectionery brands. Constantia Flexibles and Huhtamaki represent European-based flexible packaging specialists with in-house polymer laboratories accelerating EU REACH compliance transitions.
| Leading Market Players |
|---|
| Mondi Group |
| Amcor plc |
| Berry Global Inc. |
| Constantia Flexibles |
| Uflex Ltd |
| ProAmpac |
| Coveris Holdings S.A. |
| Huhtamaki |
| Winpak Ltd |
| Others |
Value Chain & Pricing Dynamics
Nordic natural kraft pulp concentration in Sweden and Finland anchors upstream supply for European cold seal manufacturers, concentrating margin capture with integrated converters possessing captive substrate production while forcing merchant buyers into price-taker positions during transatlantic shipping volatility.
Pricing Analysis
Geographic price spreads widen between German integrated producers and Southern European merchant converters dependent on Nordic pulp imports. Three-tier pricing structure across premium multi-layer, standard single-layer, and economy uncoated grades tracks barrier performance and certification complexity. Pricing pressure stems from synthetic rubber latex feedstock volatility tied to petrochemical indices. Regional confectionery brands exhibit highest price sensitivity, while multinational chocolate houses prioritize technical service over unit cost.
Supply Chain Analysis
Contract manufacturing concentrates among German and Austrian converters with in-house polymer laboratories, including Constantia Flexibles and Huhtamaki facilities. Raw material dependencies center on Nordic bleached kraft pulp, water-based synthetic rubber latex, and precision coating equipment from Swiss and German machinery OEMs. Single-source vulnerability runs through thiazole and thiuram rubber accelerator supply chains facing EU REACH phaseouts. Distribution runs through direct technical service teams embedded with Nestlé and Mars Wrigley, bypassing traditional paper merchant networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cold seal paper market fragmentation creates entry niches as specification authority migrates from procurement departments to technical packaging engineers at major confectionery houses, rewarding specialized formulation capabilities over scale.
For Market Incumbents: Harden formulation expertise moats through captive polymer laboratory investments in Halle-Neustadt and Vevey R&D corridors. Deepen backward integration into natural kraft substrate production to offset Nordic pulp concentration risk. Prioritize EU REACH-compliant accelerator chemistry transitions ahead of Southern European competitors facing outsourcing delays. For New Entrants and Emerging Players: Build out pharmaceutical blister lidding capabilities targeting Swissmedic and EMA PVC replacement guidance, the fastest-specification-growth segment. Penetrate India's Maharashtra and Gujarat flexible packaging clusters under PLI scheme incentives. Lead with direct technical service models bypassing distributor markups to regional confectionery brands. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap European converters with in-house polymer laboratories and established FDA food contact substance notification pathways. Long-term viability favors participants capturing specification authority through embedded R&D relationships rather than commodity substrate scale. Watch for EU F-Gas Regulation enforcement intensity as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Natural Kraft Substrate Production | Mondi Group leverages captive Swedish pulp mills to bypass Nordic supply volatility and capture converter margins. |
| Embedded Technical Service Team Deployment | Amcor plc positions chemists directly within Nestlé Vevey innovation center to dictate adhesive specifications. |
| EU REACH-Compliant Accelerator Chemistry Transition | German and Austrian laboratories validate alternative crosslinking compounds ahead of thiazole phaseout deadlines. |
| Pharmaceutical Blister Lidding Capacity Addition | Swissmedic guidance on PVC replacement creates fiber-based entry points with premium margin structures. |
| Precision Gravure Coating Line Integration | Swiss and German packaging machinery OEMs deliver turnkey systems compressing cold seal performance gaps with thermal alternatives. |
Study Parameters
The analysis maps multi-layer substrate specifications, single-layer commodity grades, and pharmaceutical lidding constructions, each validated through primary interviews with flexible packaging plant managers, adhesive formulation chemists, confectionery technical service directors, and pharmaceutical regulatory affairs specialists. Secondary sources include FDA food contact substance notifications, ECHA substance evaluation databases, EU F-Gas Regulation implementation guidance, and trade flow data from Nordic pulp export statistics. Bottom-up volume modeling triangulates against top-down converter capacity assessments across the analysis window.
Assumptions hold EU Packaging and Packaging Waste Regulation recyclability mandates at current trajectory, India PLI scheme incentives at announced levels, and synthetic rubber latex feedstock pricing within historical volatility bands. Segmentation dimensions include product type tier, end-use application maturity, distribution channel structure, and regional regulatory cluster. CAGRs derive from installed capacity utilization trends, substitution elasticity estimates for heat-seal displacement, and pharmaceutical adoption curve modeling.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by Asian pulp conglomerates or accelerated EU REACH enforcement would shift volume and margin outcomes. Quarterly review of EMA pharmaceutical packaging guidance updates, Nordic pulp export pricing indices, and California EPR implementation timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Global Fanfold Corrugated Market
Paper & Paperboard Packaging
Germany Honeycomb Paper Market
Paper & Paperboard Packaging
Masking Paper Market
Paper & Paperboard Packaging
Commercial Paper Bags Market
Paper & Paperboard Packaging
India Paper Packaging Market
Paper & Paperboard Packaging
Paper Band Market
Paper & Paperboard Packaging
Italy Honeycomb Paper Market
Paper & Paperboard Packaging
Stationery Films Packaging Market
Paper & Paperboard Packaging
Italy Paper Packaging Market
Paper & Paperboard Packaging
Chipboard Box Market
Paper & Paperboard Packaging
Middle-East and Africa Corrugated Packaging Market
Paper & Paperboard Packaging
Paperboard Container Market
Paper & Paperboard Packaging
Decal Paper Market
Paper & Paperboard Packaging
Binder's Board Market
Paper & Paperboard Packaging
Push-Up Paperboard Tube Market
Paper & Paperboard Packaging
Dunnage Paper Bags Market