
 Managed IT Infrastructure Services Market | 2026-2036
Managed IT Infrastructure Services Market Size, Share, and Industry Trends Forecast 2026-2036
Managed IT Infrastructure Services Market Analysis
Mid-sized enterprises with limited in-house IT capabilities is redrawing demand patterns across the managed infrastructure landscape. IBM leverages its hybrid cloud platform to anchor multi-cloud deployments for regulated industries. Tata Consultancy Services competes on cost-engineered delivery networks spanning delivery centers in India and Eastern Europe. Microsoft extends its Azure Arc management layer to unify on-premises and cloud resource governance for distributed organizations.
Managed IT infrastructure services encompass the remote or co-located operation, monitoring, and optimization of enterprise compute, storage, networking, and security infrastructure under contractual service level agreements typically spanning 12 to 60 months. These services offload capital-intensive hardware refresh cycles and 24/7 operational burdens from client organizations, allowing internal teams to redirect capacity toward application development and business process digitization. Cloud services within the service type dimension now command the largest revenue share as enterprises accelerate workload migration away from owned data centers, while security services represents the fastest-expanding margin pool given the complexity of defending hybrid attack surfaces. Within the deployment category, hybrid architectures dominate current contract values by preserving legacy system connectivity, though multi-cloud configurations are gaining fastest as organizations seek to avoid single-vendor lock-in and satisfy geographic redundancy requirements.
FDA cybersecurity guidance for connected medical devices, SEC disclosure rules on material cyber incidents, and EU NIS2 directives on critical infrastructure operators collectively elevate compliance-driven demand for audited infrastructure management. HIPAA and GDPR data residency requirements further constrain where patient and consumer records may physically reside, directly shaping data center location strategy and cross-border service architecture. Stakeholders must monitor how sovereign AI compute initiatives in major economies reshape the geographic distribution of infrastructure assets and the vendor accreditation frameworks that govern access to sensitive workloads.
Market Dynamics
Zero-trust security architecture is forcing enterprises to rebuild network perimeters around identity verification rather than physical boundaries, reshaping how managed service providers design access controls and audit trails for hybrid cloud environments.
Growth Catalysts
- AI-driven automation:Machine learning platforms for predictive infrastructure maintenance reduce unplanned downtime for healthcare and financial services clients operating under strict SLA requirements.
- HIPAA and HITECH mandates:US healthcare providers face escalating penalties for data breaches, driving contracted infrastructure management with certified security operations centers.
- Sovereign cloud buildouts:India, Germany, and the United States are constructing domestic hyperscale facilities to retain sensitive data within national jurisdictions.
Market Restraints
- Specialized talent scarcity:Certified cloud security architects and SRE practitioners command premium compensation, compressing provider margins on fixed-price contracts.
- Input cost volatility:GPU and high-performance storage hardware prices fluctuate with semiconductor supply constraints, complicating multi-year infrastructure refresh planning.
- Regulatory fragmentation:Divergent data localization rules across the United States, Germany, and India force providers to maintain redundant operational capabilities.
Strategic Opportunities
- Edge computing integration:Manufacturing and logistics facilities require localized processing for IoT sensor networks, creating distributed infrastructure management contracts.
- EU NIS2 directive:Expanded critical infrastructure designations in Europe mandate audited security operations for energy, transport, and digital providers.
- FinOps tooling convergence:Cloud cost optimization platforms combined with infrastructure monitoring enable outcome-based pricing models for enterprise buyers.
Industry Challenges
- Multi-cloud orchestration complexity:Enterprises operating across AWS, Azure, and Google Cloud environments struggle with unified policy enforcement and cost attribution.
- Zero-trust implementation timelines:Microsegmentation projects for legacy mainframe-connected systems extend 18-36 months, delaying contracted value realization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Managed IT Infrastructure Services Market |
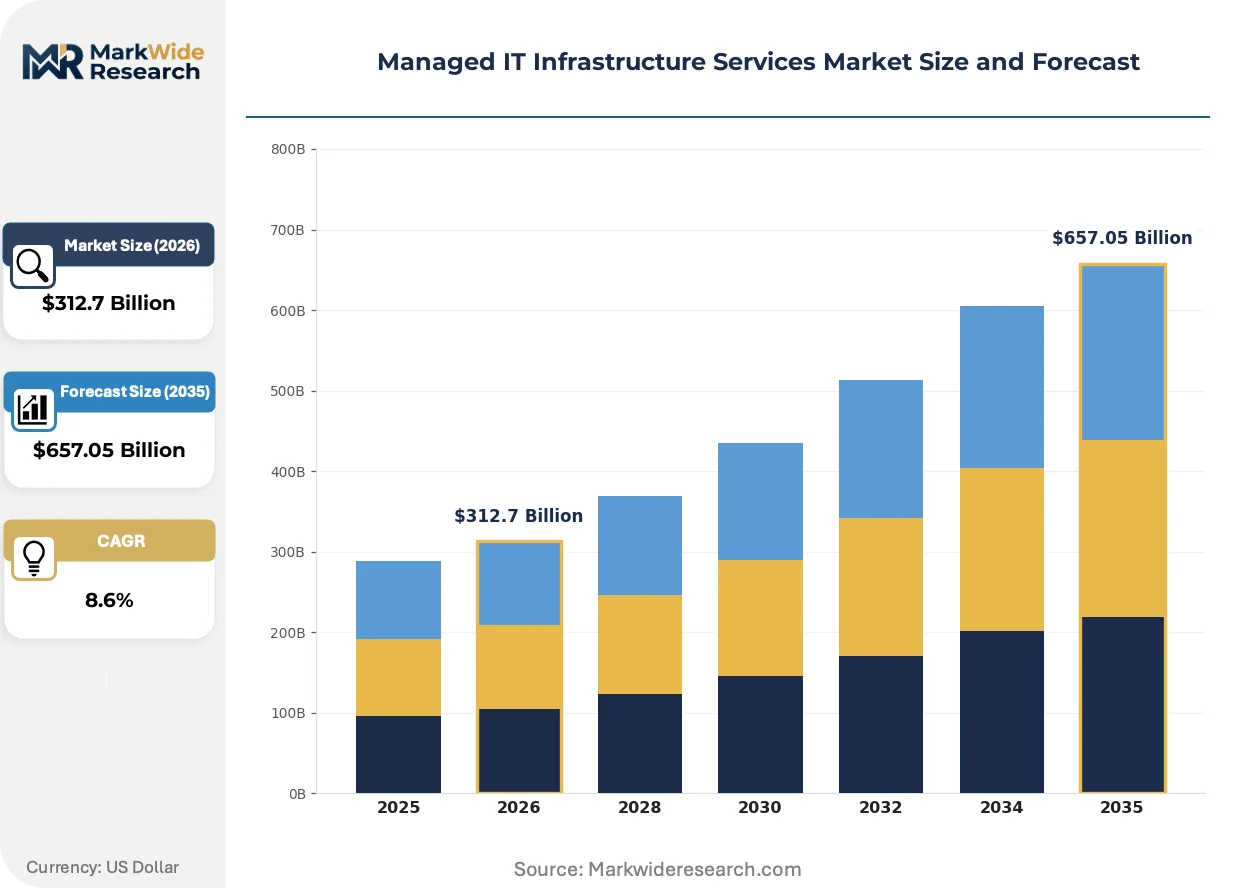
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $657.05 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cloud Services, Network Management, Data Center Management, Security Services End User: Small Enterprises, Medium Enterprises, Large Enterprises, Government Agencies Deployment: On-Premises, Off-Premises, Hybrid, Multi-Cloud Solution: Infrastructure Management, Disaster Recovery, Backup Solutions, Monitoring Tools |
| Companies Covered | IBM, Accenture, Microsoft, Cisco Systems, Fujitsu, Dell Technologies, Hewlett Packard Enterprise, Tata Consultancy Services, Verizon Communications, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Managed IT Infrastructure Services Market Emerging Trajectories
Automation platforms are compressing operational headcount requirements while elevating the strategic importance of infrastructure observability and FinOps governance across enterprise procurement criteria.
Agentic AI systems for autonomous incident remediation are displacing tier-1 support engineering roles in security operations centers. Large enterprises in regulated industries are piloting self-healing infrastructure platforms that execute patch management and capacity scaling without human intervention. This capability compression is reshaping provider staffing models toward higher-value architecture and compliance advisory functions.
The EU AI Act establishes risk-based classification for infrastructure automation systems handling critical service delivery. Providers deploying machine learning for predictive maintenance must now document algorithmic transparency and human oversight protocols. European financial services and healthcare buyers are prioritizing vendors with established conformity assessment procedures.
Consumption-based infrastructure contracts are replacing fixed-capacity agreements as enterprises seek to align spending with actual workload utilization. Managed service providers are unbundling reserved instance management and spot capacity optimization as distinct service lines. This behavioral shift is most pronounced among mid-sized technology and professional services firms in the United States and Germany.
Managed IT Infrastructure Services Market Segmentation
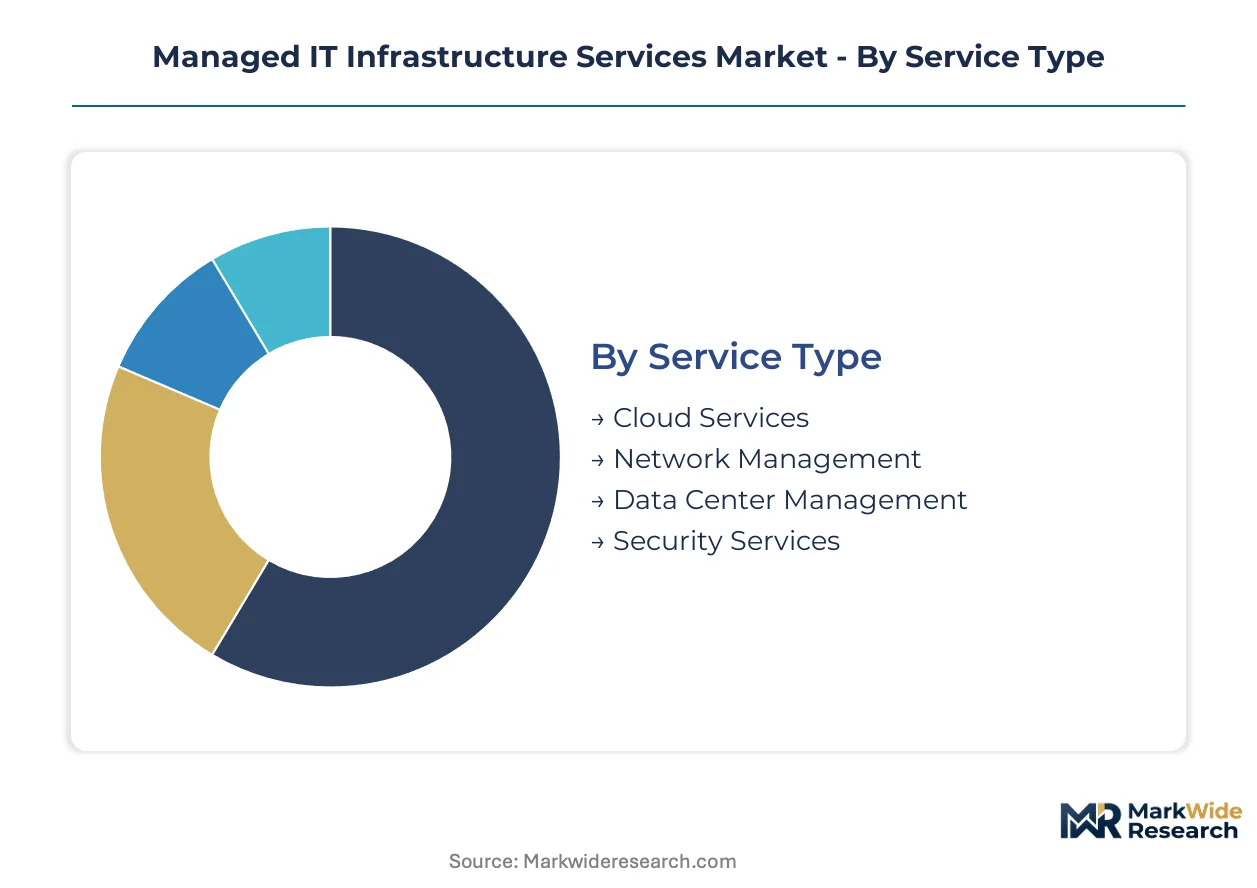
Segmentation in managed IT infrastructure services reveals how procurement criteria diverge across workload types, organizational scale, and compliance postures. Buyers prioritize different service bundles based on internal capabilities, regulatory exposure, and cloud maturity. Understanding these divides shapes vendor positioning and delivery network investments.
Service Type:
Margin pools concentrate in security operations and multi-cloud orchestration, where specialized talent scarcity supports premium pricing. Cloud migration services command volume but face compression from automation platforms.
- Cloud Services:Workload migration, container orchestration, and serverless architecture management now absorb the largest contract values. Healthcare systems in the United States and financial institutions in Germany are consolidating AWS, Azure, and Google Cloud environments under single managed service agreements to satisfy HIPAA and GDPR data residency requirements.
- Security Services:Managed detection and response, zero-trust architecture implementation, and compliance auditing generate the steepest margin expansion. The SEC disclosure rules on material cyber incidents and EU NIS2 directives are mandating 24/7 security operations center coverage that internal IT teams cannot staff economically.
- Network Management:SD-WAN deployment, bandwidth optimization, and latency-sensitive application routing for distributed workforces.
- Data Center Management:Colocation oversight, hardware lifecycle management, and legacy mainframe connectivity preservation for regulated industries.
Cloud Services holds installed capacity. Security Services is rotating up the share rankings.
End User:
Procurement sophistication varies sharply by organizational scale, with mid-sized enterprises representing the most contested acquisition target.
- Large Enterprises:Complex multi-cloud contracts spanning 36-60 month terms with outcome-based pricing clauses. These buyers demand FinOps integration, sovereign cloud options, and dedicated customer success teams. Manufacturing conglomerates in India and automotive suppliers in Germany are consolidating fragmented vendor relationships.
- Medium Enterprises:Standardized service bundles with modular add-ons for compliance and security. This segment exhibits the fastest vendor switching as buyers graduate from break-fix relationships to strategic partnerships. Professional services firms in the United States are prioritizing consumption-based contracts over reserved capacity.
- Small Enterprises:Fully managed IT-as-a-service with predictable monthly pricing and minimal customization.
- Government Agencies:FedRAMP, StateRAMP, and equivalent national accreditation requirements with mandatory domestic data center presence.
Large Enterprises anchor contract value. Medium Enterprises are gaining share fastest.
Deployment:
Architecture choices reflect risk tolerance, legacy system interdependence, and data sovereignty constraints.
- Hybrid:Integration of on-premises infrastructure with private and public cloud resources preserves connectivity to legacy ERP and manufacturing execution systems. This configuration dominates current contract values in healthcare and industrial sectors where downtime costs exceed migration benefits.
- Multi-Cloud:Deliberate distribution of workloads across AWS, Azure, and Google Cloud to avoid single-vendor lock-in and satisfy geographic redundancy requirements. Financial services firms in Germany and technology companies in India are mandating multi-cloud strategies as board-level risk management policy.
- On-Premises:Fully owned and operated infrastructure with managed service overlays for monitoring and maintenance.
- Off-Premises:Single-tenant or multi-tenant colocation with provider-managed hardware and virtualization layers.
Hybrid retains the largest installed base. Multi-Cloud is climbing the fastest.
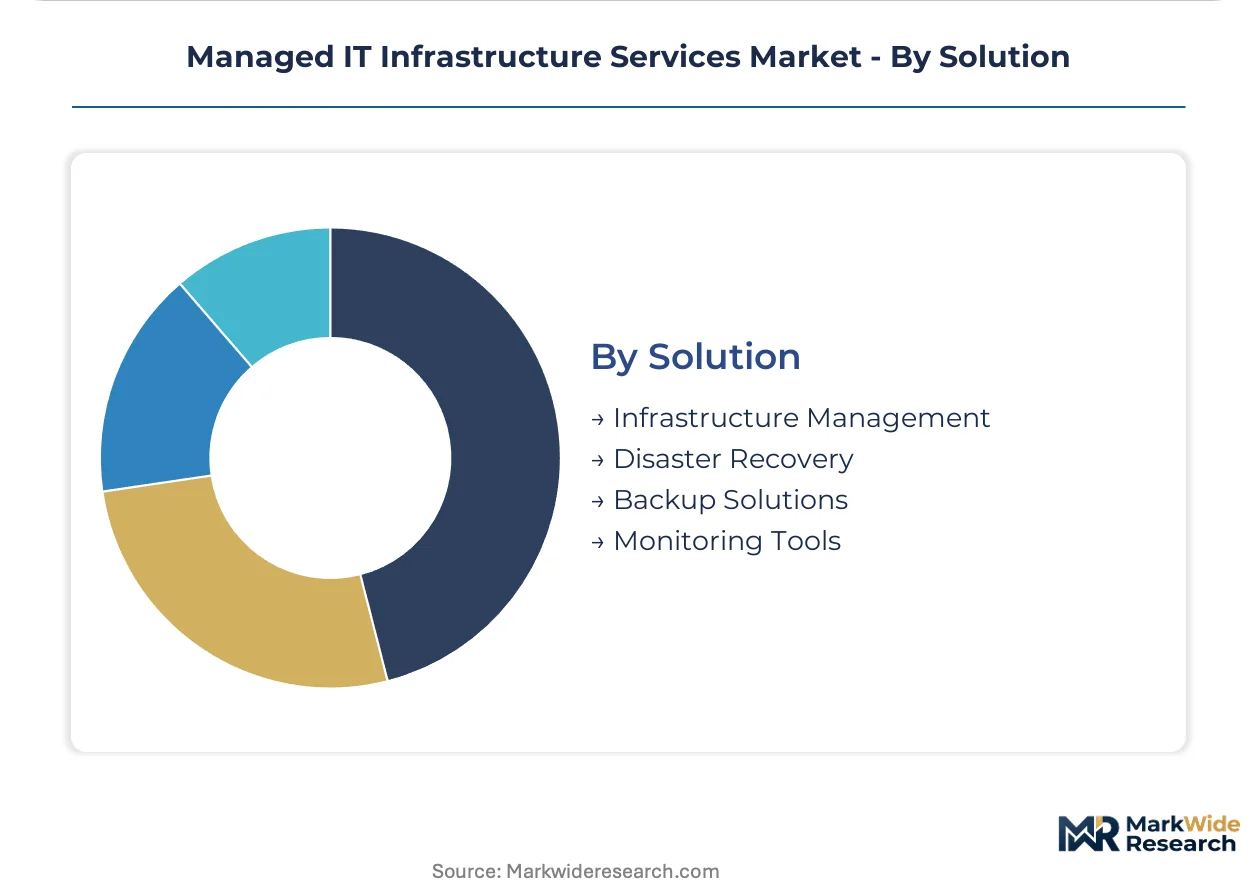
Solution:
Solution bundling determines contract stickiness and expansion revenue potential.
- Infrastructure Management:Comprehensive oversight of compute, storage, and networking resources with SLA-backed availability guarantees. This foundational layer generates recurring revenue stability but faces margin pressure from automation platforms displacing tier-1 engineering roles.
- Disaster Recovery:Business continuity planning, failover orchestration, and recovery time objective guarantees for mission-critical applications. Healthcare providers under HIPAA business associate agreements and financial institutions under SEC operational resilience guidance are expanding DR investments.
- Backup Solutions:Immutable backup architectures, ransomware recovery capabilities, and air-gapped storage configurations.
- Monitoring Tools:Infrastructure observability, AIOps platforms, and predictive analytics for capacity planning and incident prevention.
Infrastructure Management holds installed capacity. Disaster Recovery is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports managed infrastructure services to healthcare systems in the United States and automotive suppliers in Germany, creating a triangular trade corridor that concentrates delivery center investments across Bangalore, Hyderabad, and Pune.
United States
Healthcare providers and financial institutions drive contract volumes as HIPAA business associate agreements and SEC cyber incident disclosure rules mandate audited security operations centers. The FDA cybersecurity guidance for connected medical devices elevates infrastructure compliance requirements. Hospital systems in Texas and financial services clusters in New York Metro are consolidating multi-cloud contracts under single managed service agreements.
Germany
Automotive suppliers and industrial machinery manufacturers demand sovereign cloud capacity to satisfy GDPR data residency and EU NIS2 critical infrastructure designations. The country's national data protection regulator enforces strict cross-border transfer limitations. Manufacturing execution system integrations in Bavaria and Baden-Württemberg preserve hybrid architectures connecting legacy ERP to cloud resources.
India
Domestic hyperscale construction and PLI scheme incentives for semiconductor manufacturing attract global providers to build sovereign AI compute facilities. TRAI data localization consultations shape cross-border service architecture for multinational clients. Delivery centers in Bangalore and Hyderabad export remote infrastructure management to healthcare and financial services buyers in North America and Europe.
United Kingdom
Professional services firms and fintech startups prioritize consumption-based contracts with modular compliance add-ons. The Financial Conduct Authority operational resilience guidance mandates recovery time objectives for critical third-party infrastructure. London's financial district and Manchester's technology corridor exhibit fastest vendor switching as buyers graduate from break-fix relationships.
Japan
Automotive electronics and precision manufacturing sectors require edge computing integration for IoT sensor networks and predictive maintenance platforms. METI supply chain security guidelines influence vendor accreditation frameworks for sensitive workloads. Industrial clusters in Nagoya and Osaka are piloting self-healing infrastructure for autonomous capacity scaling.
Managed IT Infrastructure Services Market Vendor Landscape
Player mix skews toward diversified technology conglomerates with hybrid cloud platforms and cost-engineered delivery networks. Market structure concentrates around three tiers: global systems integrators with multi-cloud orchestration capabilities, hardware-centric providers pivoting toward managed service overlays, and telecommunications carriers leveraging network infrastructure for edge service delivery. Dominant competitive moves include strategic partnerships for sovereign cloud buildouts and portfolio diversification into AI-driven automation platforms.
Within the diversified technology tier, IBM anchors multi-cloud deployments for regulated industries through its hybrid cloud platform, while Microsoft extends Azure Arc management layers to unify distributed resource governance. Tata Consultancy Services occupies a position exemplifying cost-engineered delivery network optimization across India and Eastern European centers. These three entities represent distinct archetypes: platform-centric ecosystem orchestration, unified management layer standardization, and geographically distributed labor arbitrage.
| Leading Market Players |
|---|
| IBM |
| Accenture |
| Microsoft |
| Cisco Systems |
| Fujitsu |
| Dell Technologies |
| Hewlett Packard Enterprise |
| Tata Consultancy Services |
| Verizon Communications |
| Others |
Supply Flow & Price Mechanics
Ninety-day GPU procurement lead times for high-performance compute infrastructure concentrate pricing power with semiconductor distributors serving managed service providers across India and Taiwan. This inventory compression forces providers to pre-commit capital for multi-year refresh cycles while passing through hardware cost volatility via consumption-based contract renegotiation with enterprise buyers in Germany and the United States.
Pricing Analysis
Current-generation AI accelerator pricing commands 3-4x premiums over prior-generation CPU-based infrastructure, while next-generation sovereign cloud certifications introduce additional compliance-tier surcharges. Three-tier pricing structure across premium certified, standard enterprise, and economy self-service levels dominates contract architecture, with HIPAA business associate agreements and FedRAMP authorization driving differentiation. Cost compression in economy tiers intensifies because automation platforms displace tier-1 engineering roles. Mid-sized enterprises exhibit highest price sensitivity due to fixed IT budgets, while government agencies accept premium pricing for mandatory domestic data center presence.
Supply Chain Analysis
Inventory buffers for enterprise storage arrays and network security appliances have compressed to 45-60 days across distribution channels serving North American and European markets. Hardware supply concentrates in Taiwan, China, and South Korea for semiconductor components, with final assembly and integration distributed across Mexico, Poland, and India. Raw material dependencies span advanced lithography equipment, high-bandwidth memory modules, and specialized cooling substrates. Single-source vulnerability for GPU accelerators creates procurement risk during foundry allocation cycles. Distribution runs through authorized distributor networks and direct OEM relationships for hyperscale provider volume commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AI-driven automation platforms are disrupting staffing models and contract economics across managed infrastructure services, creating asymmetric opportunities for providers with established sovereign cloud accreditation and self-healing platform capabilities.
For Market Incumbents: Fortify hybrid cloud platform differentiation through backward integration into sovereign AI compute facilities in India and Germany, insulating against margin compression from emerging automation-native competitors. Invest in zero-trust architecture certification pipelines to capture compliance-driven procurement from healthcare systems under FDA cybersecurity guidance. Prioritize FinOps tooling convergence to enable outcome-based pricing that locks in multi-year enterprise relationships.
For New Entrants and Emerging Players: Edge computing integration for manufacturing IoT networks represents the most penetrable service layer where incumbents under-serve latency-sensitive workload requirements. Target mid-sized professional services firms in the United States and United Kingdom with consumption-based infrastructure contracts featuring modular security add-ons. Deploy agentic AI self-healing platforms as differentiated proof-of-concept offerings to bypass incumbent staffing scale advantages.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified technology conglomerates spinning off non-core managed infrastructure divisions lacking sovereign cloud accreditation. Long-term viability hinges on automation platform ownership rather than labor arbitrage scale. Monitor EU AI Act conformity assessment procedures as the inflection signal indicating which providers can sustain premium pricing for regulated European workloads.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Facility Buildout | Domestic hyperscale construction in India and Germany satisfies GDPR and data localization mandates from TRAI and national regulators. |
| Agentic AI Platform Integration | Autonomous incident remediation displaces tier-1 security operations center roles across healthcare and financial services clients. |
| Zero-Trust Architecture Certification | HIPAA and SEC compliance requirements mandate microsegmentation capabilities for healthcare providers and listed companies. |
| FinOps Tooling Convergence | Cloud cost optimization platforms enable consumption-based contracts aligning provider revenue with actual customer workload utilization. |
| Edge Computing Service Extension | Localized processing for manufacturing IoT sensor networks creates distributed infrastructure management contracts in Japan and Germany. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with chief technology officers, IT procurement officers, security operations center directors, and managed service provider delivery heads across healthcare, financial services, and manufacturing verticals. Secondary validation drew from SEC 10-K infrastructure disclosures, hyperscaler capex reports, HIPAA breach notification databases, and EU NIS2 implementation guidance documents. Bottom-up contract value analysis triangulated against top-down market sizing from IT services trade associations.
Across the projection horizon, the analytical framework modeled service type segmentation, deployment architecture choices, end-user organizational scale, and geographic regulatory cluster variations. CAGRs were derived from trend extrapolation of contract value migration from on-premises to hybrid and multi-cloud configurations. Forecast inputs incorporated sovereign cloud construction timelines, AI automation adoption curves, and zero-trust implementation velocity across regulated industries.
Material uncertainties — semiconductor supply allocation shifts, data localization rule amendments, and AI liability framework evolution — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding automation platform maturation and compliance mandate enforcement intensity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Global Cloud Computing Data Center IT Asset Disposition (ITAD) Market
Data Center Infrastructure
Hosting Infrastructure Services Market
Data Center Infrastructure
Philippines Data Center Server Market
Data Center Infrastructure
Sweden Data Center Power Market
Data Center Infrastructure
Ireland Data Center Power Market
Data Center Infrastructure
White Box Server Market
Data Center Infrastructure
Global Data Center Accelerator Market
Data Center Infrastructure
Global Data Center RFID Market
Data Center Infrastructure
Datacenter Infrastructure Services Market
Data Center Infrastructure
Nigeria Data Center Market
Data Center Infrastructure
Data Center Monitoring Systems Market
Data Center Infrastructure
Belgium Data Center Rack Market
Data Center Infrastructure
Data Center Virtualization Market
Data Center Infrastructure
Brazil Data Center Market
Data Center Infrastructure
Data Center Blocks Market
Data Center Infrastructure
Global Data Center Rack and Enclosure Market