
 IT Infrastructure Market | 2026-2036
IT Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
IT Infrastructure Market Analysis
Enterprise buyer concentration is shifting from fragmented SME procurement toward consolidated large-enterprise and government agency contracts. Amazon Web Services leverages its hyperscale footprint to dominate public cloud infrastructure commitments. Microsoft Corporation anchors hybrid deployments through Azure Stack integration with on-premises environments. Dell Technologies competes in enterprise server refresh cycles with direct sales to Fortune 500 accounts.
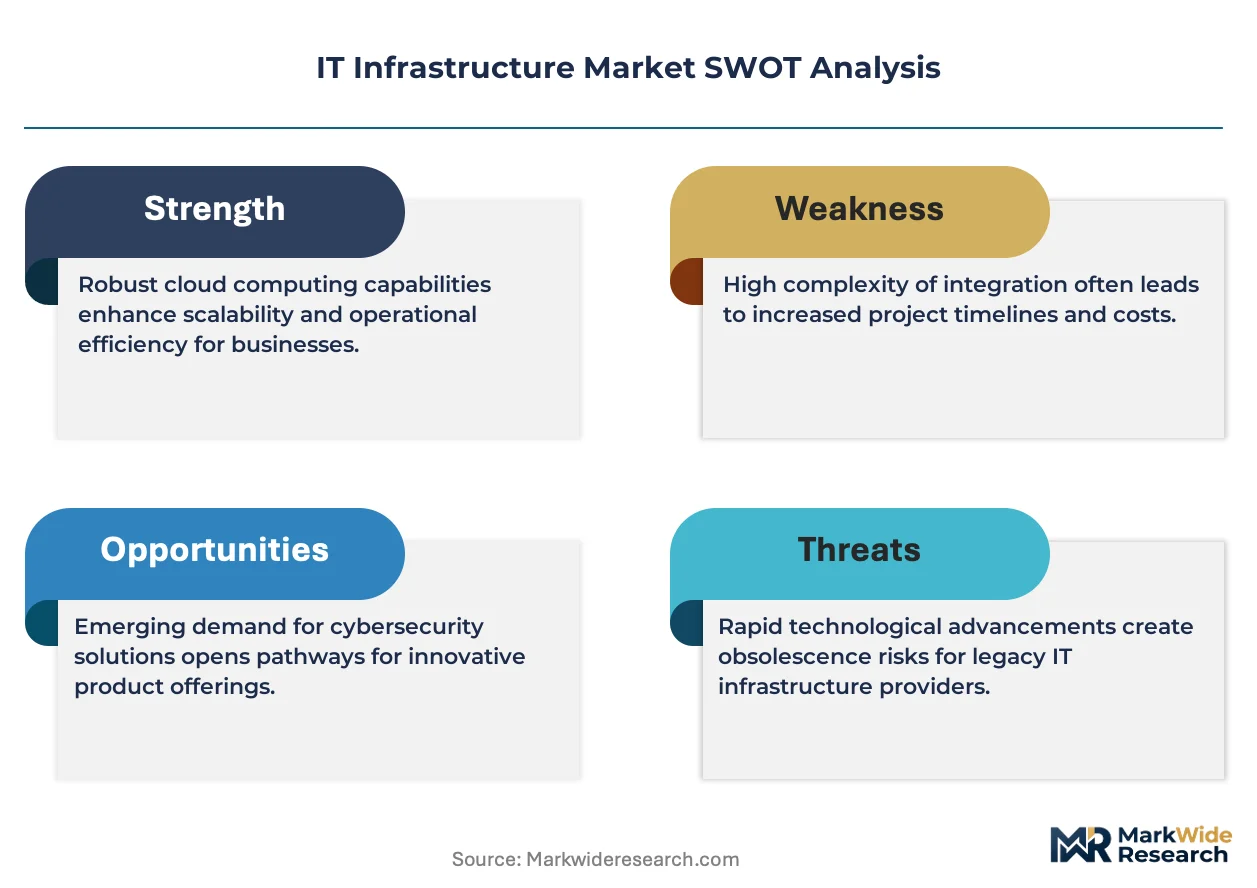
IT infrastructure comprises the physical and virtual resources enabling data processing, storage, and transmission across organizational networks, including server racks with Intel Xeon or AMD EPYC processors, NVMe storage arrays, and software-defined networking controllers operating at 100 Gbps throughput. Its primary purpose is delivering reliable, scalable compute services for business operations and digital service delivery. Software Solutions within the product type dimension captures expanding margin pools as vendors bundle management and orchestration layers. Hybrid Cloud deployment models lead absolute spending as enterprises retain sensitive workloads on-premises while bursting to public resources. Containerization technology is displacing traditional virtualization for cloud-native application deployment.
The EU AI Act imposes risk-based compliance tiers on automated decision-making systems, forcing infrastructure providers to certify transparency and auditability in their platforms. NIS2 Directive mandates cross-border incident reporting and supply chain security standards for essential and important entities across member states. ISO 27001 and IEC 62443 frameworks shape procurement requirements for critical infrastructure operators. Stakeholders must weigh sovereign cloud mandates against the cost economics of hyperscale concentration when architecting multi-region resilience strategies.
Market Dynamics
Containerization technology is compressing virtualization margins while EU operational resilience mandates force infrastructure refresh cycles across financial services and critical infrastructure operators.
Growth Catalysts
- EU AI Act compliance mandates:Risk-based tiers for automated systems require certified transparency and auditability in infrastructure platforms, driving replacement demand among European financial institutions and healthcare operators.
- Hybrid cloud workload orchestration:Enterprises retain sensitive data on-premises while bursting compute-intensive AI training to public resources, expanding multi-environment management software attach rates.
- Frankfurt data center cluster expansion:Continental European capacity concentration attracts hyperscale investment, anchoring cross-border latency-sensitive application deployment for DACH region enterprises.
Market Restraints
- NVMe storage array supply concentration:Controller chip fabrication depends on Taiwan-based foundry capacity, exposing procurement timelines to geopolitical friction and foundry allocation priorities.
- NIS2 Directive cross-border reporting:Incident notification timelines compress operational response windows, forcing smaller operators into managed security service relationships that erode direct infrastructure ownership economics.
- Copper and rare earth input volatility:Power distribution components and permanent magnet demand in cooling systems face commodity price swings that distort multi-year capex planning.
Strategic Opportunities
- Sovereign cloud mandates in Germany and France:Data localization requirements for public sector and defense contracts create protected procurement pools for EU-headquartered infrastructure providers.
- Edge computing convergence with 5G private networks:Manufacturing and logistics facilities deploy micro data centers for real-time inference, opening distributed hardware footprints outside traditional hyperscale concentration.
- Green Deal energy efficiency incentives:Power Usage Effectiveness certification tiers unlock public procurement preference and tax treatment for liquid-cooled and renewable-powered facility designs.
Industry Challenges
- ISO 27001 and IEC 62443 certification timelines:Multi-stage audit processes for critical infrastructure operators extend sales cycles and strain pre-sales engineering resources.
- Kubernetes and container orchestration skill scarcity:Enterprise IT organizations face recruitment friction for platform engineering roles, slowing cloud-native migration execution.
- Interoperability friction between on-premises and public cloud networking:Software-defined WAN integration with hyperscale virtual private clouds requires custom engineering that fragments vendor support accountability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IT Infrastructure Market |
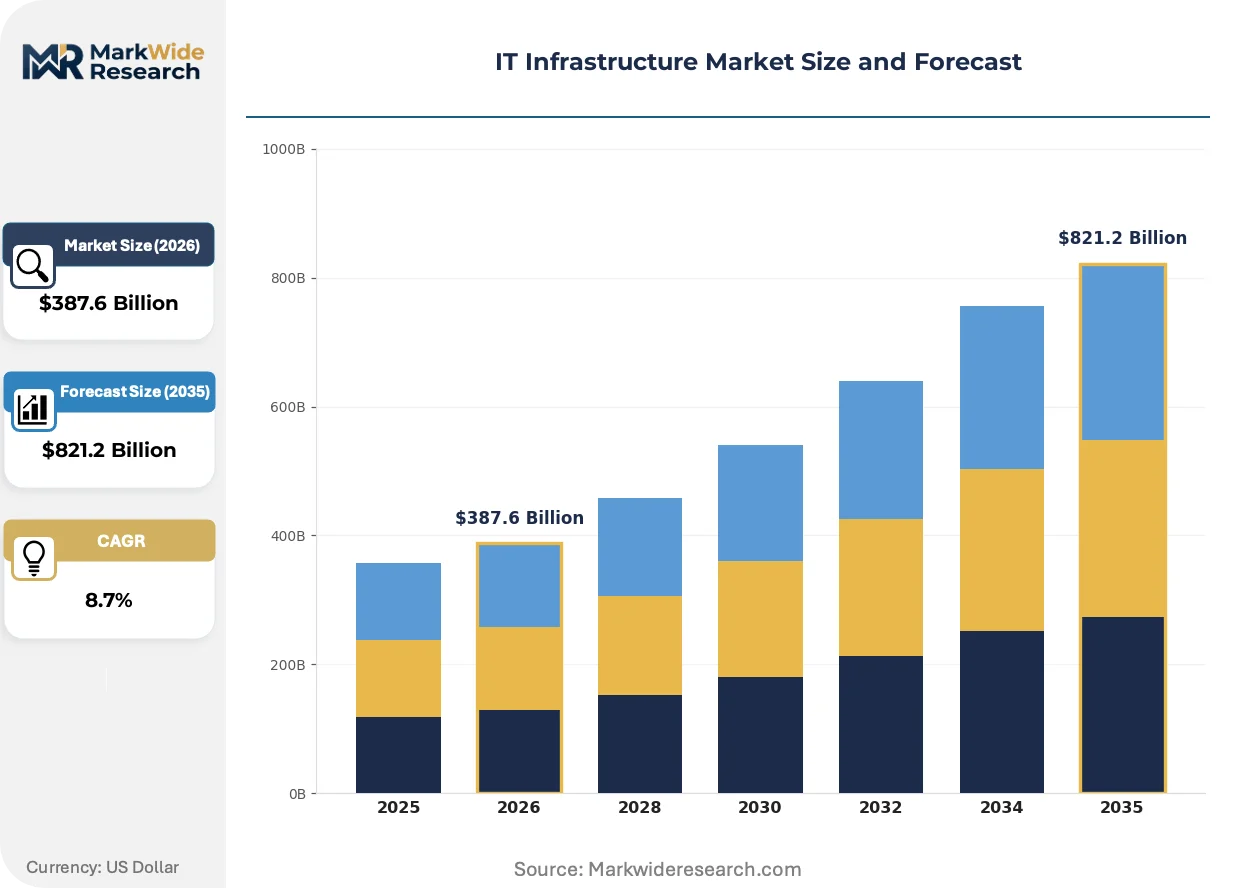
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $821.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Servers, Storage Systems, Network Equipment, Software Solutions Deployment Model: On-Premises, Hybrid Cloud, Public Cloud, Private Cloud End User: SMEs, Large Enterprises, Government Agencies, Educational Institutions Technology: Virtualization, Containerization, Networking, Cloud Computing |
| Companies Covered | Amazon Web Services, Microsoft Corporation, Google LLC, IBM Corporation, Cisco Systems, Dell Technologies, Hewlett Packard Enterprise, Fujitsu Limited, Oracle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IT Infrastructure Market Emerging Trajectories
Workload portability demands are collapsing traditional boundaries between compute environments, forcing infrastructure vendors to unify management planes across dissimilar deployment targets.
Container orchestration platforms are absorbing the function of legacy hypervisors in enterprise data centers. Financial services and SaaS providers deploy Kubernetes at production scale to standardize application packaging. This absorption is compressing VMware licensing footprints while expanding observability and service mesh software categories.
The EU AI Act's risk classification system imposes documentation and human oversight requirements on high-risk automated decision systems. Infrastructure providers must embed logging, explainability, and circuit-breaker capabilities into platform offerings. German automotive and French healthcare IT procurement now mandates these features as table stakes.
Capital deployment patterns among enterprise buyers are rotating from ownership toward subscription-based consumption models. Fortune 500 infrastructure teams favor managed rack-scale services with embedded refresh obligations over traditional depreciation cycles. This rotation is most pronounced in Netherlands and Nordic markets where sustainability reporting requirements amplify circular economy preferences.
IT Infrastructure Market Segmentation
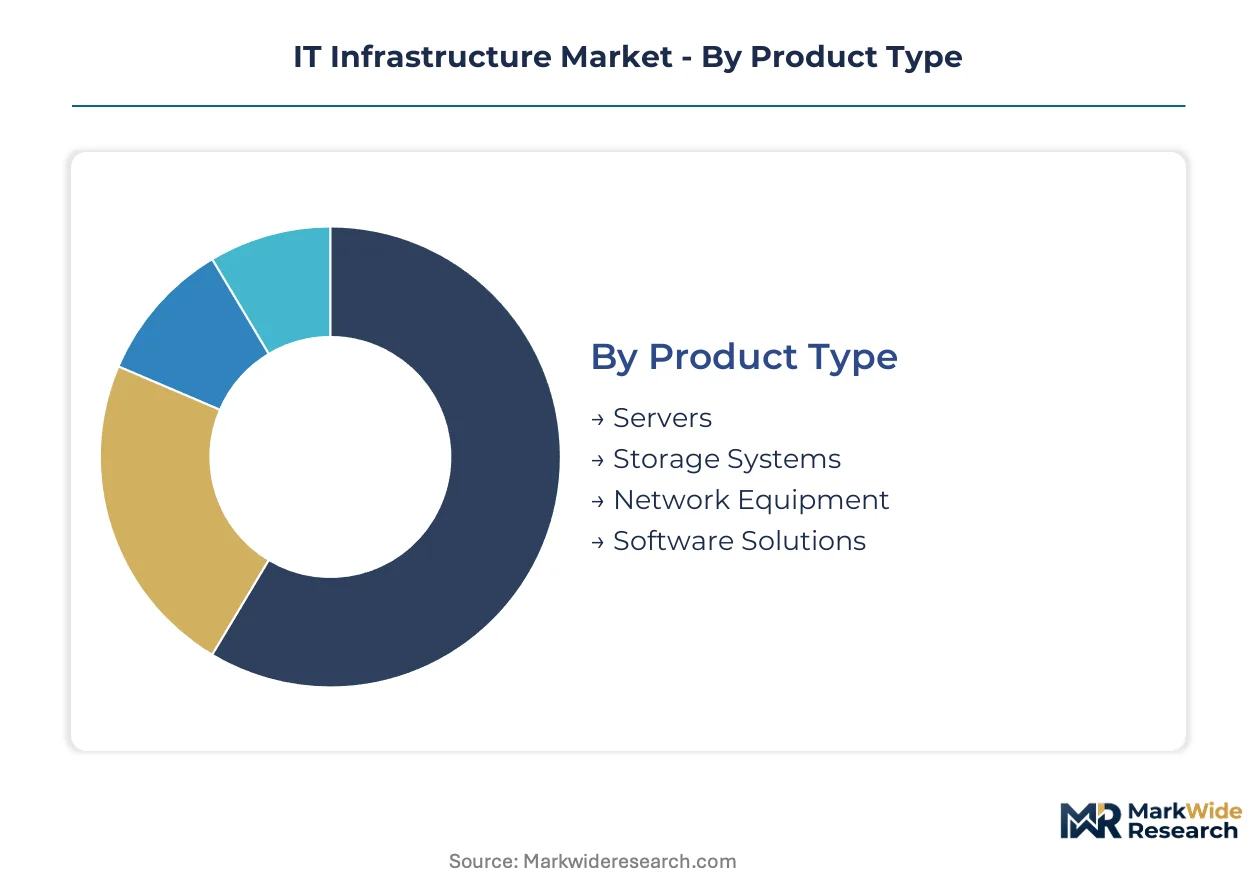
IT infrastructure procurement patterns diverge sharply across deployment models and buyer types, with compliance mandates and workload portability requirements reshaping how vendors architect product portfolios. Understanding these segment boundaries clarifies where margin pools concentrate and which technology transitions threaten incumbent positions.
Product Type:
Supply concentration in controller silicon and processor fabrication directly shapes which product categories capture investment priority and face procurement risk.
- Servers:Rack-scale systems built on Intel Xeon or AMD EPYC processors handle enterprise compute density requirements. Frankfurt's financial services cluster drives high-memory configurations for real-time risk analytics under EU AI Act auditability mandates.
- Storage Systems:NVMe all-flash arrays deliver sub-millisecond latency for transactional workloads. Taiwan-based controller foundry constraints expose German automotive manufacturers to allocation delays during capacity crunches.
- Network Equipment:100 Gbps switching fabrics with software-defined controllers interconnect distributed environments.
- Software Solutions:Management and orchestration layers bundle observability, automation, and security policy enforcement.
Today's leader: Servers. Tomorrow's challenger: Software Solutions.
Deployment Model:
Cost tier differentiation separates capital-intensive ownership models from consumption-based alternatives, with compliance complexity tilting the arithmetic for regulated industries.
- Hybrid Cloud:Workload portability between on-premises and public resources dominates enterprise architecture planning. German healthcare operators retain patient data locally while bursting imaging AI training to hyperscale resources under BfDI oversight.
- Public Cloud:Hyperscale rental of compute and storage eliminates depreciation cycles. Netherlands sustainability reporting requirements accelerate subscription preferences over owned infrastructure.
- On-Premises:Fully owned facilities persist where data sovereignty or latency constraints block externalization.
- Private Cloud:Single-tenant dedicated environments serve defense and intelligence community procurement pools.
Hybrid Cloud commands current spending share. Public Cloud shows the steepest expansion trajectory among regulated industries shedding ownership burdens.
End User:
Customer type determines contract scale, sales cycle length, and certification burden, with government and large-enterprise segments consolidating procurement influence.
- Large Enterprises:Fortune 500 infrastructure teams negotiate direct rack-scale refresh programs with embedded lifecycle management. French automotive OEMs mandate ISO 27001 certification as non-negotiable table stakes.
- Government Agencies:Sovereign cloud and data localization requirements create protected procurement pools. German federal contracts exclude non-EU headquartered providers under revised IT security framework guidelines.
- SMEs:Fragmented demand consolidates through managed service intermediaries with eroded direct vendor economics.
- Educational Institutions:Research computing grants drive intermittent high-performance cluster deployments.
Large Enterprises anchor vendor revenue concentration. Government Agencies represent the fastest-climbing contract value tier under resilience directive procurement.
Technology:
Maturity curves separate established virtualization from emerging container platforms, with skill scarcity and migration friction governing transition timelines.
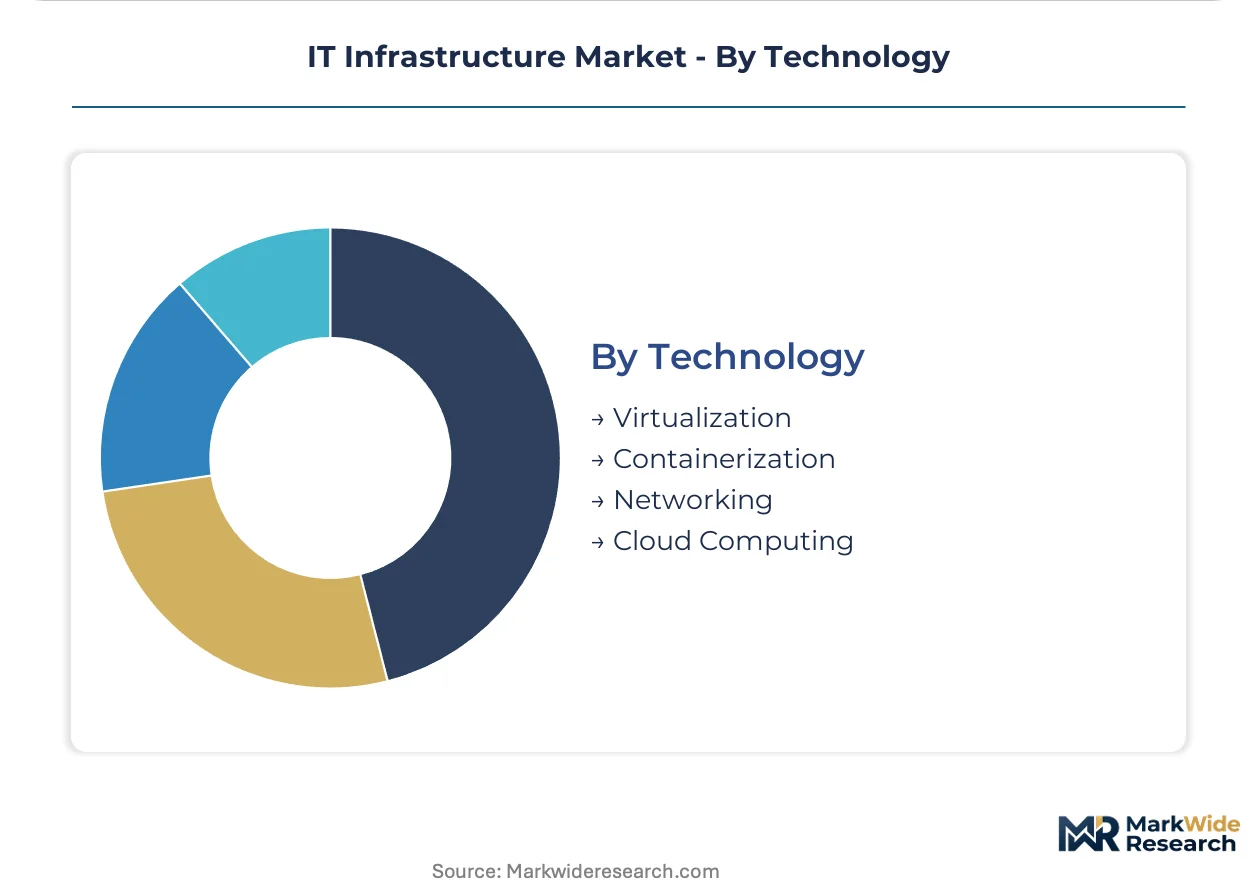
- Containerization:Kubernetes orchestration standardizes cloud-native application packaging across environments. SaaS providers in Ireland and Sweden deploy production-scale clusters, compressing VMware licensing footprints while expanding observability spend.
- Cloud Computing:Elastic resource pooling abstracts physical infrastructure management. NIS2 Directive incident reporting obligations force smaller operators toward managed service relationships.
- Virtualization:Legacy hypervisor estates persist in risk-averse financial services change windows.
- Networking:Software-defined WAN integration stitches dissimilar environments together.
Containerization is displacing incumbent virtualization. Cloud Computing captures the broadest adoption base across buyer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands continental European infrastructure investment while the United States drives hyperscale capacity expansion through cloud-native enterprise adoption.
United States
Fortune 500 financial services firms in New York and Chicago drive hybrid cloud refresh cycles under SEC cybersecurity disclosure rules. Virginia's Northern Virginia data center cluster anchors hyperscale concentration with over 70 percent of domestic cloud capacity.
Germany
Frankfurt's financial district generates dense demand for low-latency trading infrastructure under BaFin operational resilience mandates. The EU AI Act's risk-based compliance tiers force healthcare operators in Berlin and Munich toward certified audit platforms.
United Kingdom
London-based fintech clusters consume high-memory server configurations for real-time fraud detection under FCA operational resilience requirements. The Thames Valley corridor attracts Microsoft and Amazon hyperscale investments for cross-border latency optimization.
France
Parisian healthcare IT procurement now mandates EU AI Act explainability features for diagnostic imaging platforms. The Île-de-France region concentrates sovereign cloud demand as defense contracts exclude non-EU infrastructure providers.
Netherlands
Amsterdam's internet exchange anchors intercontinental traffic routing for European cloud workloads. Dutch sustainability reporting requirements under CSRD accelerate subscription-based infrastructure consumption over traditional capex ownership models.
IT Infrastructure Market Vendor Landscape
United States hyperscalers anchor the public cloud tier; European systems specialists hold sovereign deployment positions. The vendor structure concentrates around three strategic archetypes: hyperscale platform operators with embedded hardware partnerships, integrated systems vendors with direct enterprise sales forces, and managed service intermediaries consolidating SME demand. Dominant competitive moves include hyperscale capacity expansion into Frankfurt and Amsterdam clusters, plus vertical integration into custom silicon for AI training workloads.
Among United States-based platform operators, Amazon Web Services exemplifies the hyperscale archetype through its embedded refresh obligations in rack-scale service contracts. Microsoft Corporation occupies a hybrid integration position, leveraging Azure Stack for on-premises connectivity. Dell Technologies represents the integrated systems tier with direct Fortune 500 server refresh programs.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Corporation |
| Google LLC |
| IBM Corporation |
| Cisco Systems |
| Dell Technologies |
| Hewlett Packard Enterprise |
| Fujitsu Limited |
| Oracle Corporation |
| Others |
Supply Flow & Price Mechanics
Copper and rare earth price indices cascade through IT infrastructure manufacturing, compressing margins on power distribution components and cooling systems while forcing buyers into longer-term contract structures that lock in tiered pricing based on certification grade and volume commitments.
Pricing Analysis
Capacity additions in Taiwan and South Korea are reshaping price floors for NVMe storage controllers and processor silicon. Three-tier pricing structure across premium, standard, and economy levels separates ISO 27001-certified configurations from baseline offerings. Cost compression in mid-range server tiers is intensifying because hyperscale buyers negotiate embedded refresh obligations. SMEs exhibit highest price sensitivity, while German federal agencies accept premium tiers for sovereign cloud compliance.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore anchor hub-and-spoke patterns for European and Asia-Pacific fulfillment. Taiwan, South Korea, and the United States concentrate advanced semiconductor fabrication. Controller chip, processor wafer, and rare earth magnet inputs draw from geographically concentrated sources. Single-source vulnerability in Taiwan-based foundry capacity exposes procurement timelines to geopolitical friction. Distribution runs through authorized reseller networks and direct hyperscale procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Containerization adoption compresses legacy virtualization margins while expanding premium attach rates for observability and orchestration software, creating margin-expansion headroom for vendors that shift toward subscription-based consumption models.
For Market Incumbents: Lock in hybrid cloud integration positions through Azure Stack and equivalent on-premises connectivity offerings. Deepen backward integration into custom AI training silicon to defend against hyperscale captive supply advantages. Invest in ISO 27001 and IEC 62443 certification pipelines to extend sales cycle control.
For New Entrants and Emerging Players: The gap between premium sovereign-cloud configurations and economy-tier SME offerings creates entry space at the mid-market edge computing tier. Target manufacturing facilities deploying 5G private networks with micro data center solutions. Pursue managed service intermediary relationships to bypass direct Fortune 500 procurement barriers.
For Investors and Strategic Acquirers: Consolidation pressure builds where Kubernetes platform engineering capability scarcity fragments vendor accountability. Five-to-ten year viability favors managed infrastructure providers with embedded circular economy obligations under CSRD-aligned markets. Monitor sovereign cloud mandate enforcement in Germany and France as inflection signal for protected procurement pool expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Custom Silicon Development | In-house AI training chip production reduces dependency on Taiwan foundry allocation cycles. |
| Sovereign Cloud Certification | EU AI Act compliance tiers unlock German federal and French defense procurement pools. |
| Edge Computing Partnership | 5G private network integration captures manufacturing facility micro data center deployments. |
| Liquid Cooling Transition | Power Usage Effectiveness certification secures Green Deal tax treatment and public procurement preference. |
| Container Platform Acquisition | Kubernetes orchestration capability addresses enterprise skill scarcity and accelerates cloud-native migration. |
Methodological Framework
Direct dialogue with infrastructure procurement officers, platform engineering directors, hyperscale capacity planners, and managed service provider executives grounds qualitative findings. Secondary validation draws from SEC 10-K filings, hyperscaler capex disclosures, EU regulatory filings under NIS2 and AI Act frameworks, and customs trade data for semiconductor imports. Bottom-up and top-down triangulation cross-checks vendor shipment estimates against enterprise IT budget surveys.
Bottom-up modeling aggregates segment-level deployment data across product type, deployment model, end user, and technology dimensions. Top-down analysis benchmarks aggregate infrastructure spending against macroeconomic indicators and regulatory compliance cost estimates. CAGRs derive from fitted growth curves across the projection horizon, incorporating AI training workload expansion, containerization penetration rates, and sovereign cloud mandate enforcement timelines as industry-specific inputs.
Caveats apply where Taiwan foundry allocation disruptions, EU regulatory enforcement intensity shifts, or copper and rare earth commodity spikes could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
APAC Data Center Server Market
Data Center Infrastructure
Global Telecommunication Equipment Cabinet and Racks Market
Data Center Infrastructure
Nigeria Data Center Physical Security Market
Data Center Infrastructure
South America Data Center Market
Data Center Infrastructure
North America Green Data Center Market
Data Center Infrastructure
Denmark Data Center Rack Market
Data Center Infrastructure
Switzerland Data Center Server Market
Data Center Infrastructure
Next Generation Data Center Market
Data Center Infrastructure
Data Center Substation Market
Data Center Infrastructure
Japan Data Center Power Market
Data Center Infrastructure
Scientific Data Management System Market
Data Center Infrastructure
Europe Data Center Colocation Market
Data Center Infrastructure
Norway Data Center Networking Market
Data Center Infrastructure
Data Center Rack Solutions Market
Data Center Infrastructure
Belgium Data Center Power Market
Data Center Infrastructure
United Arab Emirates Data Center Physical Security Market